
 Flame-Retardant Polypropylene (PP) Market | 2026-2036
Flame-Retardant Polypropylene (PP) Market Size, Share, and Industry Trends Forecast 2026-2036
Flame-Retardant Polypropylene (PP) Market Foresight
The EU Green Deal is consolidating demand for low-smoke, halogen-free flame-retardant PP across European appliance and automotive supply chains. Albemarle Corporation leverages its bromine expertise to sustain positions in legacy halogenated segments while navigating regulatory transition. SABIC anchors Middle Eastern supply with integrated polypropylene feedstock and specialized compounding capabilities. LyondellBasell Industries dominates North American volume through broad resin portfolios and channel control with tier-1 automotive suppliers.
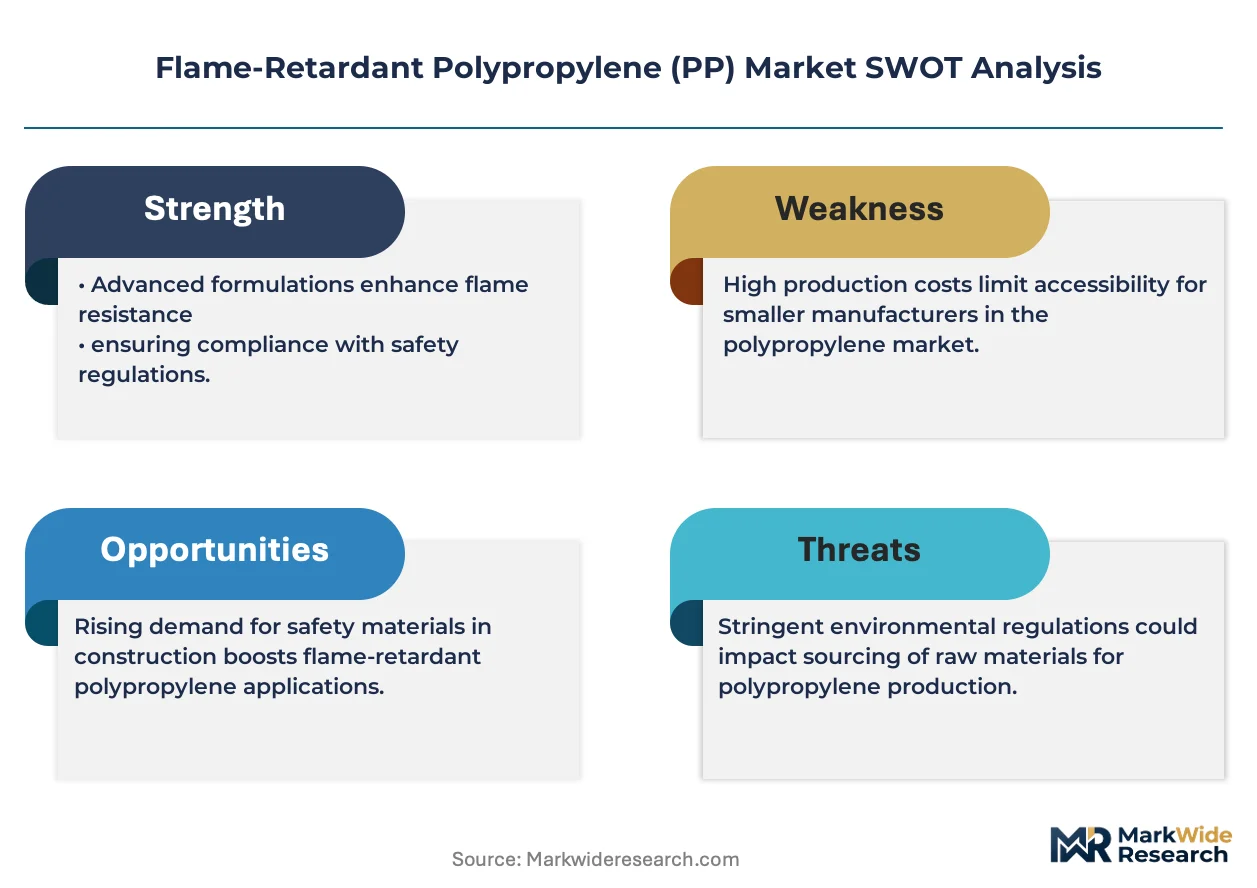
Flame-retardant polypropylene denotes polypropylene resin modified with halogenated, phosphorus-based, mineral, or intumescent additives to achieve defined UL 94 flammability ratings and reduced smoke density for injection-molded and extruded components. The material primarily serves electrical enclosures, appliance housings, building profiles, and under-hood automotive parts where ignition resistance and low toxic emission are mandated. Homopolymer PP leads volume due to cost efficiency and stiffness in electrical applications, while phosphorus-based flame retardant technology represents the fastest-expanding segment as OEMs phase out halogenated systems to meet REACH and RoHS thresholds. Intumescent systems command premium positioning in construction materials where extended fire resistance ratings justify higher formulation costs.
The EPA regulates volatile organic compound emissions from compounding operations, while REACH and RoHS in Europe restrict specific brominated flame retardants and mandate substance disclosure across supply chains. China's GB standards and MEE enforcement require flame-retardant compliance documentation for electronics exports, creating divergent certification burdens for multinational compounders. Stakeholders must monitor regulatory harmonization gaps between regional fire safety codes and chemical restriction lists when allocating R&D and capacity investments.
Market Dynamics
REACH restrictions on halogenated flame retardants and the EU Green Deal are forcing compounders to requalify entire resin portfolios while appliance OEMs demand simultaneous cost reduction and smoke-density compliance.
Growth Catalysts
- Appliance electrification:Heat-pump dryers and induction cooktops require UL 94 V-0 rated housings with low smoke emission, expanding specification volumes for halogen-free grades in German and Italian supply chains.
- REACH Annex XVII expansion:ECHA's progressive restriction of decaBDE and HBCDD pushes electrical enclosure manufacturers toward phosphorus-nitrogen intumescent systems.
- Building code harmonization:China's GB 8624 and updated MEE enforcement for electronics exports create certification pull-through for mineral-filled PP in construction profiles and cable management.
Market Restraints
- Phosphorus feedstock volatility:Red phosphorus and ammonium polyphosphate supply concentrates in Chinese and Moroccan extraction zones, exposing compounders to price swings and export licensing delays.
- Technical performance gaps:Halogen-free formulations struggle to match brominated systems in thin-wall electrical connectors below 0.8mm thickness, limiting substitution in high-density PCB applications.
- Competing engineering resins:Polycarbonate and PBT blends with inherent flame resistance capture premium appliance and automotive connector sockets where PP cannot meet glow-wire temperature thresholds.
Strategic Opportunities
- India appliance manufacturing:PLI scheme incentives for white goods production in Gujarat and Tamil Nadu create virgin demand for localized flame-retardant PP compounding near Haier and Whirlpool assembly plants.
- EV battery module housings:Thermal runaway containment specifications in UN ECE R100 and China's GB/T standards open specification windows for mineral-filled PP in pack enclosures and busbar covers.
- Recycled content mandates:EU CSRD disclosure requirements and France's AGEC law push OEMs toward post-industrial recycled PP with retained flame-retardant certification, rewarding compounders with mechanical recycling and recompounding capabilities.
Industry Challenges
- Multi-jurisdiction certification latency:UL 94, IEC 60695, and GB/T 2408 testing cycles run 14-26 weeks in parallel, delaying new formulation launches and locking working capital in qualification inventory.
- Compounder technical talent scarcity:Formulation chemists with simultaneous expertise in phosphorus chemistry, polypropylene rheology, and regulatory compliance command premium compensation and constrain R&D throughput at mid-tier suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flame-Retardant Polypropylene (PP) Market |
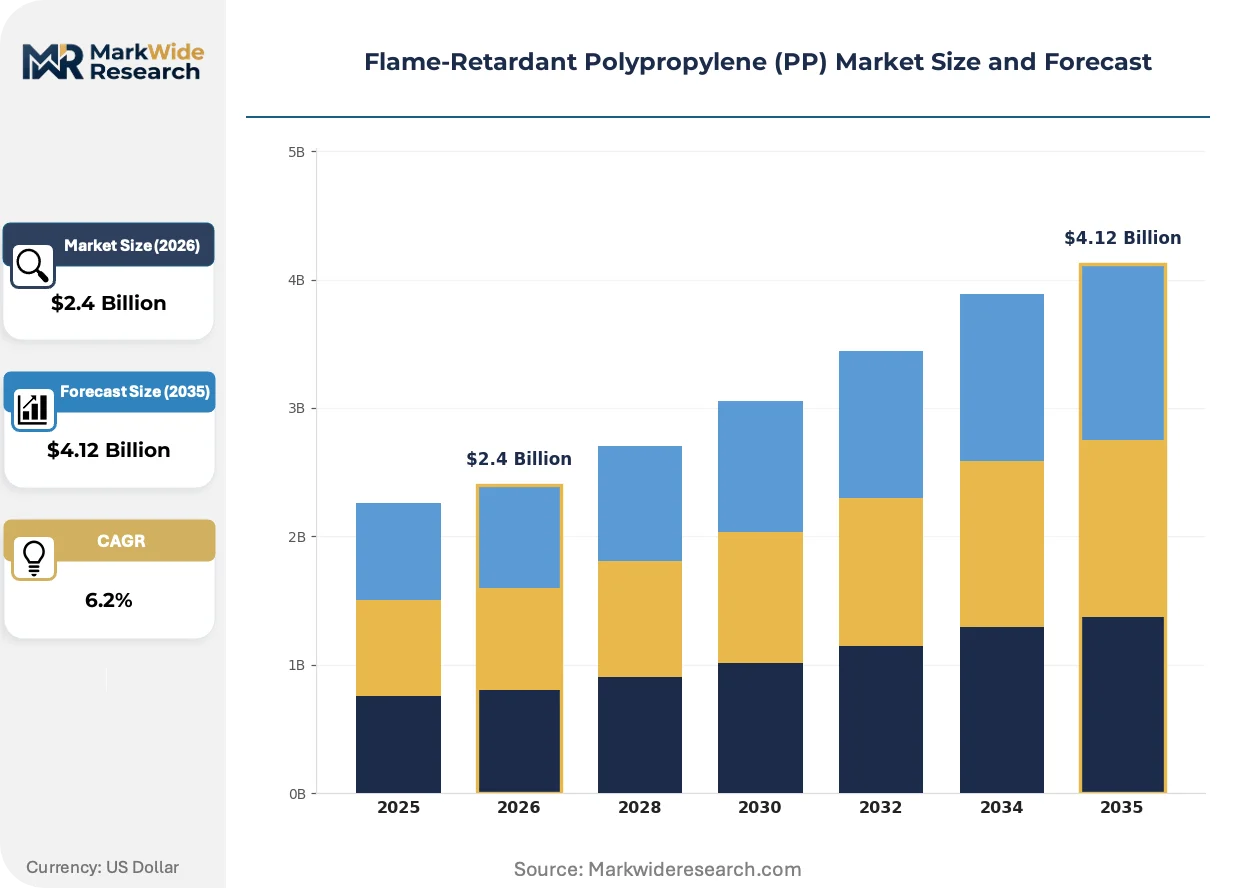
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.12 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Homopolymer PP, Random Copolymer PP, Block Copolymer PP, High Impact PP Application: Electrical & Electronics, Construction Materials, Consumer Goods, Packaging Films Flame Retardant Technology: Halogenated, Phosphorus-based, Mineral-based, Intumescent Systems End User: Electronics Manufacturers, Building Material Suppliers, Packaging Producers, Automotive Tier-1 Suppliers |
| Companies Covered | Avient Corporation, Albemarle Corporation, SABIC, Clariant, DuPont, LyondellBasell Industries, RTP Company, Lanxess, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flame-Retardant Polypropylene (PP) Market Shifts & Advancements
Formulation science is pivoting from legacy halogenated systems toward synergistic mineral-phosphorus hybrids as regulatory pressure and OEM sustainability targets converge on smoke-toxicity reduction.
Phosphorus-nitrogen intumescent systems are integrating nano-scale layered silicates to enhance char stability and reduce total additive loading. Appliance manufacturers in Germany and the Netherlands are specifying these grades for dishwasher and oven control panels. This integration is compressing the cost premium versus legacy brominated formulations from 40% to 15% at equivalent UL ratings.
China's GB standards evolution and MEE enforcement documentation requirements for electronics exports are tightening supply chain traceability. Compounders must now maintain substance-level disclosure across bromine, phosphorus, and mineral additive tiers. Japanese automotive wire harness suppliers are most affected, accelerating third-party certification investments to maintain China market access.
Appliance OEM procurement teams are consolidating qualified supplier lists from 12-15 compounders to 4-6 strategic partners with multi-continent compounding assets and pre-certified formulation libraries. This concentration displaces spot-buy relationships and rewards SABIC, LyondellBasell, and regional specialists with captive resin supply and technical service depth. The shift is most visible in North American refrigerator and HVAC component sourcing.
Flame-Retardant Polypropylene (PP) Market Segmentation
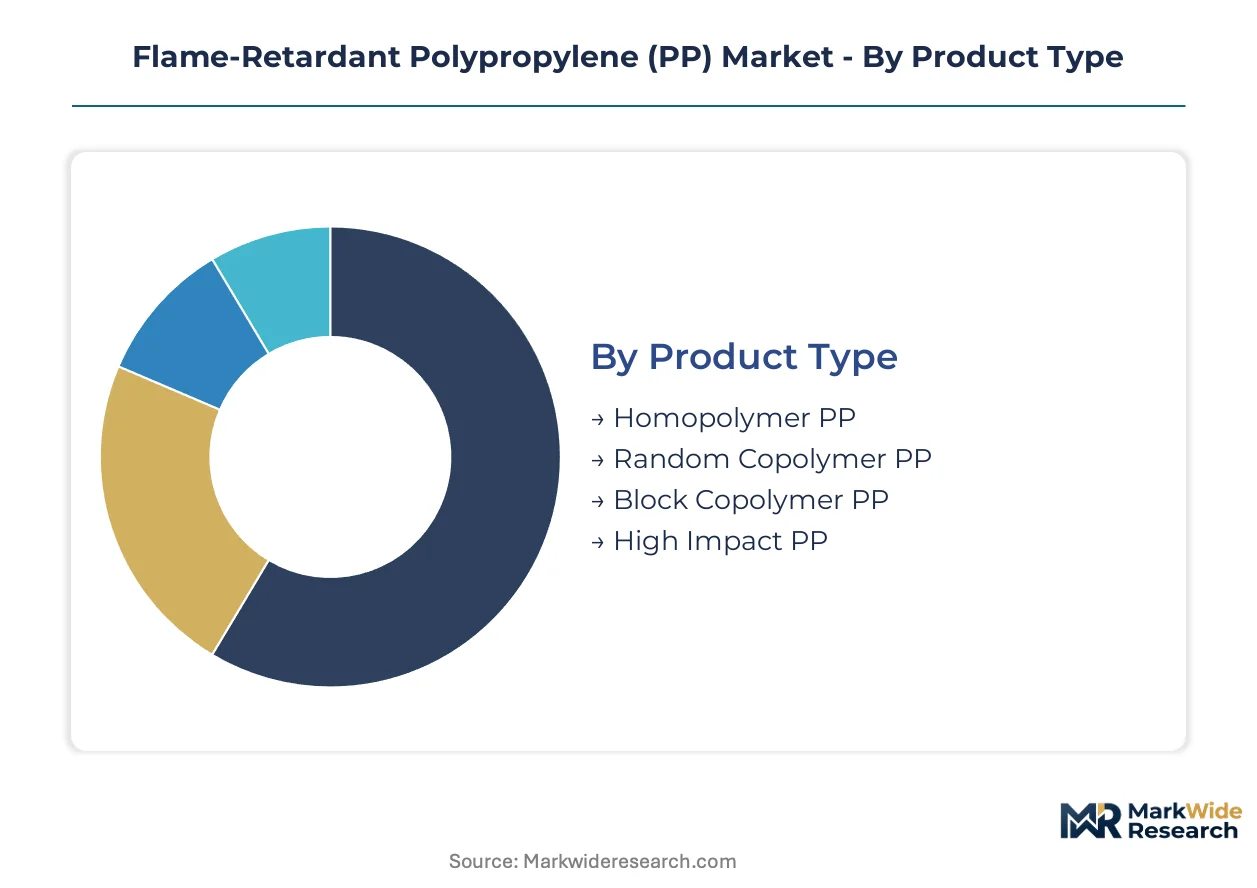
Segmentation in flame-retardant polypropylene reveals how formulation chemistry, resin architecture, and end-use certification requirements fragment demand across incompatible specification tiers. Procurement teams source from parallel supply chains that rarely intersect.
Product Type:
Resin selection hinges on stiffness-to-toughness tradeoffs and the thermal window available for flame-retardant additive incorporation without degradation.
- Homopolymer PP:High crystallinity delivers superior stiffness and heat distortion temperature for electrical enclosure applications. Appliance manufacturers in Germany and China specify this grade for dishwasher control panels and HVAC housings where dimensional stability under load matters more than impact resistance.
- Random Copolymer PP:Ethylene incorporation improves optical clarity and flexibility for thin-wall injection molding. Packaging producers in Italy leverage this transparency for flame-retardant electronics blister packs where UL 94 V-2 ratings suffice and aesthetic inspection windows are required.
- Block Copolymer PP:Segmented morphology balances rigidity with low-temperature impact resistance. Automotive tier-1 suppliers specify this grade for under-hood components exposed to thermal cycling.
- High Impact PP:Rubber-modified matrix absorbs energy in consumer goods applications. Power tool housings in North American manufacturing clusters favor this resilience.
Homopolymer PP leads on scale; random copolymer PP leads on momentum as thin-wall electronics miniaturization accelerates.
Application:
End-use fire safety codes dictate additive loading levels and smoke toxicity thresholds that reshape compounder formulation priorities.
- Electrical & Electronics:UL 94 V-0 and IEC 60695 glow-wire requirements dominate specifications. Connector manufacturers in Japan and South Korea drive phosphorus-based system adoption as REACH restrictions eliminate brominated alternatives from export-bound production lines.
- Construction Materials:Extended fire resistance ratings and low smoke emission mandates apply. German building profiles and cable management systems require intumescent char stability under EN 13501 classification protocols.
- Consumer Goods:Balanced cost-performance targets predominate. Small appliance producers in India and Vietnam specify mineral-filled grades for heat-resistant kitchen equipment bases.
- Packaging Films:Thin-gauge flame retardancy challenges additive dispersion. Electronics shipping materials in China must satisfy GB standards for warehouse storage safety.
Electrical & electronics commands premium formulation investment; construction materials show steepest expansion trajectory as GB 8624 enforcement tightens.
Flame Retardant Technology:
Regulatory phase-out schedules and OEM sustainability scorecards are concentrating R&D expenditure on specific chemistry transitions.
- Halogenated:Brominated systems retain cost efficiency in legacy automotive wire harness applications. EPA and REACH restrictions are compressing addressable volume to non-export segments and military-specified components.
- Phosphorus-based:Ammonium polyphosphate and red phosphorus derivatives dominate halogen-free migration. Appliance OEMs in the Netherlands and France specify these grades for dishwasher and oven housings to meet AGEC law disclosure requirements.
- Mineral-based:Magnesium hydroxide and aluminum trihydrate provide smoke suppression. EV battery module housings in China incorporate these fillers for thermal runaway containment per GB/T standards.
- Intumescent Systems:Phosphorus-nitrogen synergists form expanded char barriers. High-rise building materials in Germany justify premium pricing through extended fire resistance ratings.
Phosphorus-based formulations capture the fastest substitution volume; intumescent systems defend margin concentration.
End User:
Supply chain power asymmetries concentrate qualified supplier relationships around compounders with captive resin and multi-continent certification libraries.
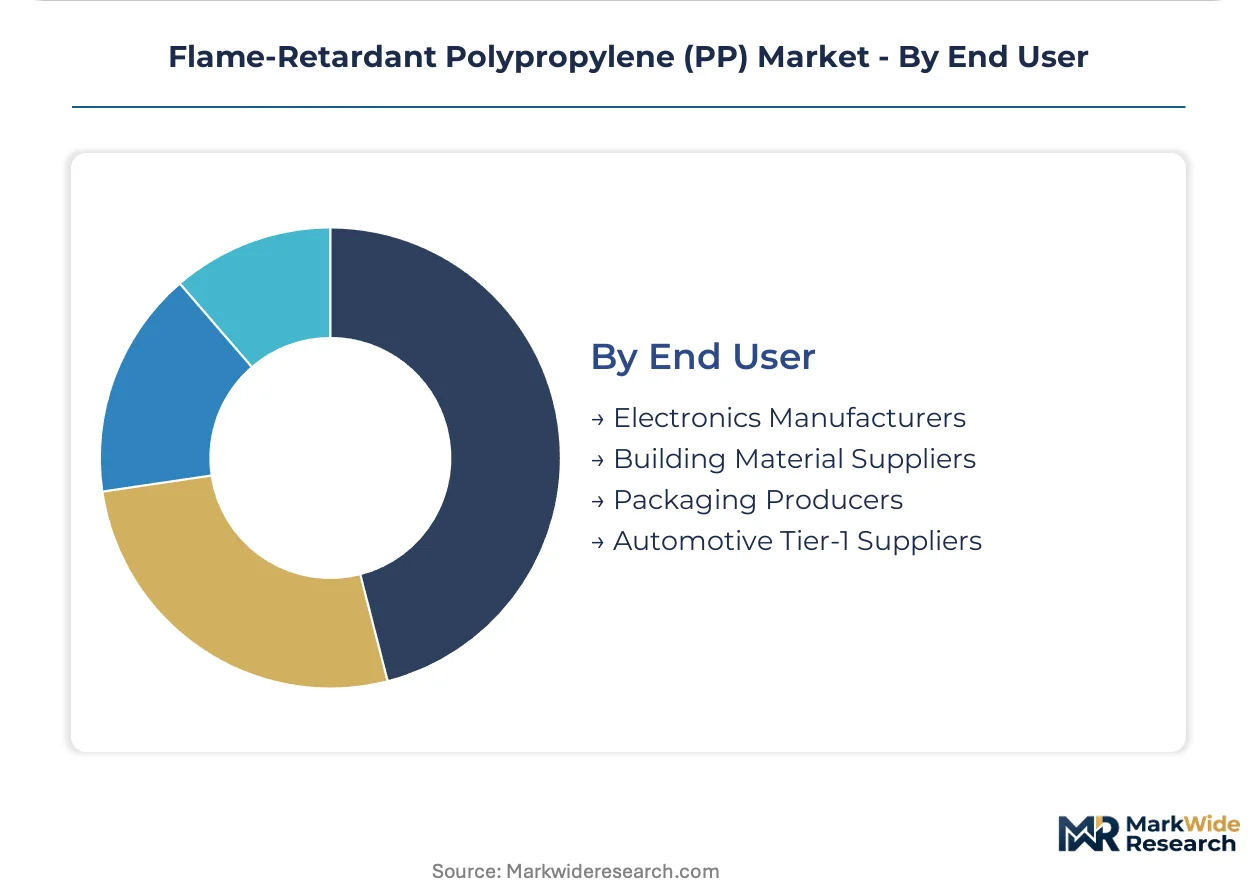
- Electronics Manufacturers:Consolidated procurement from 4-6 strategic compounders replaces fragmented spot-buying. Japanese wire harness suppliers invest in third-party certification to maintain China market access under MEE documentation rules.
- Building Material Suppliers:Regional code variations fragment demand. French construction distributors prioritize CSRD-aligned supply chain disclosure.
- Packaging Producers:Cost pressure limits additive loading to minimum compliance thresholds. Electronics logistics providers in South Korea specify recyclable flame-retardant films.
- Automotive Tier-1 Suppliers:Glow-wire and thermal aging specifications exceed PP capabilities in premium connector sockets. Under-hood applications with moderate temperature requirements retain PP economics.
Electronics manufacturers dictate specification velocity; automotive tier-1 suppliers represent the most demanding qualification barrier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flame-retardant polypropylene formulation and compounding originated in German and U.S. industrial chemical clusters during the 1970s, with Bayer AG and Hercules Inc. pioneering halogenated additive systems for appliance and automotive applications. Production expertise subsequently diffused to Asian manufacturing centers as electronics assembly relocated.
China
Appliance electrification and EV battery manufacturing drive specification volume in Jiangsu and Guangdong provinces. GB standards and MEE enforcement documentation requirements compel compounders to maintain substance-level supply chain disclosure. Haier and Midea assembly clusters in Qingdao and Foshan source localized halogen-free grades for dishwasher and induction cooktop housings.
Germany
REACH Annex XVII restrictions on decaBDE and HBCDD accelerate phosphorus-nitrogen intumescent system adoption across appliance supply chains. The EU Green Deal consolidates procurement requirements for low-smoke, halogen-free grades. Bosch and Miele manufacturing concentrations in Baden-Württemberg and Bavaria specify certified compounds for oven control panels and HVAC components.
United States
EPA volatile organic compound regulations from compounding operations shape formulation plant siting decisions. Tier-1 automotive suppliers in Michigan and Ohio retain PP economics for under-hood applications with moderate temperature requirements. Appliance manufacturers in the Southeast source UL 94 V-0 rated housings for heat-pump dryers and induction cooktops.
India
PLI scheme incentives for white goods production in Gujarat and Tamil Nadu create virgin demand for localized flame-retardant PP compounding. BIS standards alignment with IEC protocols streamlines import substitution for electronics enclosure manufacturers. Haier and Whirlpool assembly plants near Ahmedabad and Chennai pull through specification volumes for mineral-filled grades.
Japan
METI guidance on sustainable manufacturing practices shapes OEM sustainability scorecards for flame-retardant material selection. Automotive wire harness suppliers in Shizuoka and Aichi prefectures invest in third-party certification to maintain China market access under MEE documentation rules. Connector manufacturers drive phosphorus-based system adoption as REACH restrictions eliminate brominated alternatives from export-bound production.
Flame-Retardant Polypropylene (PP) Market Competitive Landscape
Capital-heavy integrated resin producers compete with asset-light specialized compounders for specification control in flame-retardant polypropylene. The market structure concentrates around six to eight strategic suppliers with multi-continent compounding assets and pre-certified formulation libraries. Three archetypes dominate: petrochemical majors with captive PP feedstock, independent compounders with technical service depth, and regional specialists with recycling and recompounding capabilities. Competitive dynamics center on M&A for formulation IP and capacity expansion in high-growth appliance manufacturing clusters.
Among petrochemical majors with integrated feedstock positions, SABIC anchors Middle Eastern supply while LyondellBasell Industries occupies a dominant position in North American volume through broad resin portfolios. Albemarle Corporation represents the legacy halogenated specialist archetype, navigating regulatory transition while sustaining positions in military-specified and non-export segments. These three companies exemplify how scale and certification libraries determine procurement consolidation trends.
| Leading Market Players |
|---|
| Avient Corporation |
| Albemarle Corporation |
| SABIC |
| Clariant |
| DuPont |
| LyondellBasell Industries |
| RTP Company |
| Lanxess |
| BASF SE |
| Others |
Supply & Pricing Matrix
EU Green Deal disclosure mandates gate qualified supply access and premium-tier pricing power for compounders serving appliance OEMs in Germany and the Netherlands, compressing margins for non-certified suppliers while rewarding pre-qualified partners with multi-continent formulation libraries.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates flame-retardant PP procurement, with intumescent systems commanding premium positioning against mineral-filled economy grades. Price differentiation hinges on UL 94 certification tier and captive resin integration, with phosphorus-based formulations narrowing their cost gap versus legacy brominated systems. Cost compression in standard-grade homopolymer PP is intensifying because Chinese compounders are expanding capacity in Jiangsu province. Appliance OEM procurement teams exhibit highest price sensitivity in consumer goods segments, while automotive tier-1 suppliers accept premium pricing for glow-wire compliant block copolymer grades.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore anchor hub-and-spoke patterns for European and Asia-Pacific appliance manufacturing clusters. Raw material supply concentrates in China, Morocco, and Saudi Arabia, with red phosphorus extraction and polypropylene feedstock drawing from these zones. Compounders face single-source vulnerability in ammonium polyphosphate supply from Chinese extraction zones. Distribution runs through qualified supplier networks that consolidate spot-buy relationships into strategic partnerships with SABIC, LyondellBasell, and regional specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flame-retardant polypropylene functions as a geographic-arbitrage play between REACH-restricted European markets and specification-lagging Indian manufacturing clusters, where PLI scheme incentives offset the cost premium for localized halogen-free compounding.
For Market Incumbents: Hedge regulatory transition risk by accelerating phosphorus-nitrogen intumescent R&D while maintaining brominated capacity for military-specified segments. Backward integration into captive polypropylene feedstock secures margin defense against Chinese compounders expanding in Gujarat. Certification investment in parallel UL 94 and GB/T qualification cycles locks in procurement consolidation with Haier and Midea assembly clusters. For New Entrants and Emerging Players: Launch via technical service partnerships with Indian white goods manufacturers seeking localized supply near Ahmedabad and Chennai assembly plants. White-space targets include post-industrial recycled PP with retained flame-retardant certification for EU CSRD compliance, and mineral-filled grades for EV battery module housings under GB/T thermal runaway standards. Go-to-market leverage rests on mechanical recycling and recompounding capabilities that incumbent petrochemical majors lack. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier compounders with pre-certified formulation libraries because procurement consolidation is displacing fragmented spot-buy relationships across appliance supply chains. Long-term viability favors targets with multi-jurisdiction certification assets and phosphorus chemistry expertise. The signal to watch is MEE enforcement documentation requirements tightening supply chain traceability for electronics exports, accelerating third-party certification investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Resin Supply | LyondellBasell and SABIC defend margin compression through integrated polypropylene feedstock control. |
| Phosphorus-Nitrogen Intumescent R&D Expansion | Albemarle and Clariant redirect bromine expertise toward REACH-compliant formulation transitions. |
| India PLI-Aligned Capacity Buildout | Regional specialists capture virgin demand from Haier and Whirlpool assembly near Gujarat. |
| Post-Industrial Recycling Certification | Compounders with mechanical recompounding capabilities access EU AGEC law procurement mandates. |
| Parallel UL-GB Multi-Jurisdiction Qualification | Pre-certified suppliers reduce certification latency for Japanese wire harness exporters to China. |
Research Methodology
Coverage spans China, Germany, the United States, India, and Japan, with primary inputs from each market combining interviews with compounder R&D directors, appliance OEM procurement leads, automotive tier-1 supplier quality engineers, and regulatory compliance officers. Secondary validation draws from customs trade data, ECHA restriction dossiers, SEC 10-K resin segment disclosures, and GB standards evolution documentation. Bottom-up formulation demand modeling triangulates against top-down resin consumption aggregates.
Rate-of-change decomposition separates volume drivers by resin architecture, flame-retardant chemistry tier, end-use certification requirement, and regional regulatory enforcement intensity across the analysis window. Segmentation dimensions include homopolymer versus copolymer grade, halogenated versus phosphorus-based versus mineral technology, and electrical versus construction versus automotive application. CAGRs derive from installed base replacement cycles and OEM specification velocity, with phosphorus-based substitution rates and EV battery housing adoption as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under phosphorus feedstock export licensing disruptions or accelerated REACH Annex XVII expansion. Forecasts reflect assumptions about regulatory harmonization gaps and qualification cycle durations. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petrochemicals
Propylene Market
Petrochemicals
Tert Butyl Hydroperoxide Market
Petrochemicals
Aliphatic Hydrocarbon Market
Petrochemicals
Light Olefins Market
Petrochemicals
Global Butadiene Market
Petrochemicals
Alkylate Isooctane Market
Petrochemicals
Bio Butadiene Market
Petrochemicals
Pentane Market
Petrochemicals
Bioisobutene Market
Petrochemicals
Chemical and Petroleum Containers Market
Petrochemicals
Alkylate Market
Petrochemicals
Synthetic and Biobased Butadiene Market
Petrochemicals
Oman Pyrolysis Gasoline Market
Petrochemicals
Olefin Derivatives Market
Petrochemicals
Petrochemical Feedstock Market
Petrochemicals
Propane Market