
 N-Pentane Market | 2026-2036
N-Pentane Market Size, Share, and Industry Trends Forecast 2026-2036
N-Pentane Market Analysis
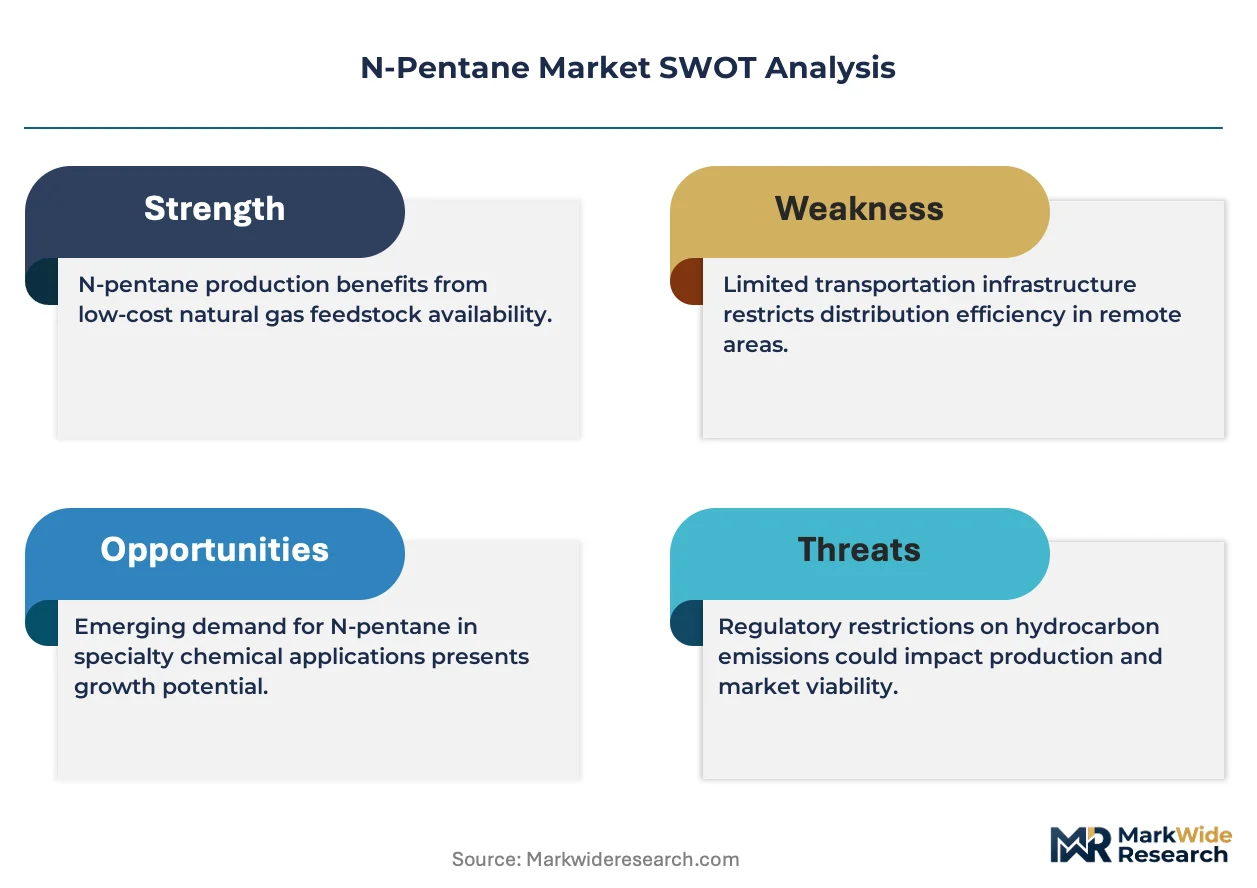
Multi-source procurement from regional refiners is expanding as foam manufacturers reduce dependence on single-origin n-pentane supply. ExxonMobil leverages integrated refining and petrochemical complexes to sustain cost-advantaged feedstock access. Shell anchors its position through global logistics networks that span major demand basins. Junyuan Petroleum Group competes on geographic proximity to East Asian polyurethane producers.
N-pentane is a straight-chain alkane hydrocarbon with molecular formula C₅H₁₂, boiling point 36.1°C, and vapor pressure 422 mmHg at 20°C, serving primarily as a blowing agent in expanded polystyrene and polyurethane foam production and as a non-polar solvent in extraction processes. Industrial grade material dominates volume flows into petrochemical applications where cost sensitivity outweighs purity requirements, while pharmaceutical grade commands tighter specification premiums from drug manufacturers facing pharmacopeial compliance. Chemical intermediate applications are expanding fastest as n-pentane feeds dehydrogenation routes to pentene and subsequent derivative chemistry.
EPA regulations under the Clean Air Act constrain volatile organic compound emissions from solvent applications, while REACH registration requirements in Europe mandate comprehensive hazard documentation for n-pentane imports above one tonne annually. OSHA permissible exposure limits shape workplace handling protocols at US manufacturing facilities. Buyers must weigh feedstock flexibility against regulatory compliance burdens when selecting grade specifications and supplier geographies.
Market Dynamics
Polyurethane foam manufacturers are consolidating supply relationships around integrated petrochemical clusters that can guarantee n-pentane purity above 95 percent while absorbing volatility in upstream crude fractions. This concentration of qualified supply is compressing procurement options for mid-tier foam producers.
Growth Catalysts
- REACH Phase-In Substances:ECHA registration deadlines for hydrocarbon solvents above one tonne annually are filtering out non-compliant traders, redirecting volume toward registered producers with documented hazard profiles.
- Dehydrogenation Feedstock Demand:Chemical intermediate applications for pentene production are expanding as crackers seek lighter feedstocks to optimize ethylene yields from naphtha-heavy slates.
- China's Shandong Province:Multiple integrated refining-petrochemical complexes in this coastal cluster are capturing regional polyurethane foam demand through pipeline-connected n-pentane supply.
Market Restraints
- Crude Oil Fraction Volatility:N-pentane derives from light naphtha cuts, exposing producers to swings in gasoline blending economics that divert C5 molecules toward fuel pools.
- Single-Origin Concentration:East Asian foam manufacturers remain dependent on Shandong-based supply clusters, creating vulnerability to regional maintenance turnarounds or environmental compliance shutdowns.
- Isopentane Substitution:Branched C5 isomers with lower boiling points are displacing n-pentane in select polystyrene foam applications where faster vaporization kinetics reduce cycle times.
Strategic Opportunities
- India's BIS Certification Pathway:Formal adoption of IS 17458 for hydrocarbon blowing agents would create a compliance moat for early-registered suppliers against unregistered imports.
- Pharmaceutical-Grade Extraction:Supercritical extraction of botanical compounds is absorbing high-purity n-pentane as a non-polar solvent in cannabinoid and essential oil processing.
- Carbon Capture Integration:Pentane-based absorption solvents for post-combustion CO2 capture are emerging as a convergence point between petrochemical supply and decarbonization infrastructure.
Industry Challenges
- Process Safety Engineering Talent:Facilities handling high-vapor-pressure hydrocarbons face scarcity of certified process hazard analysis practitioners familiar with OSHA PSM standards.
- Pharmacopeial Certification Timelines:USP-NF and EP monograph compliance for pharmaceutical-grade material requires 18-24 month validation cycles that delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | N-Pentane Market |
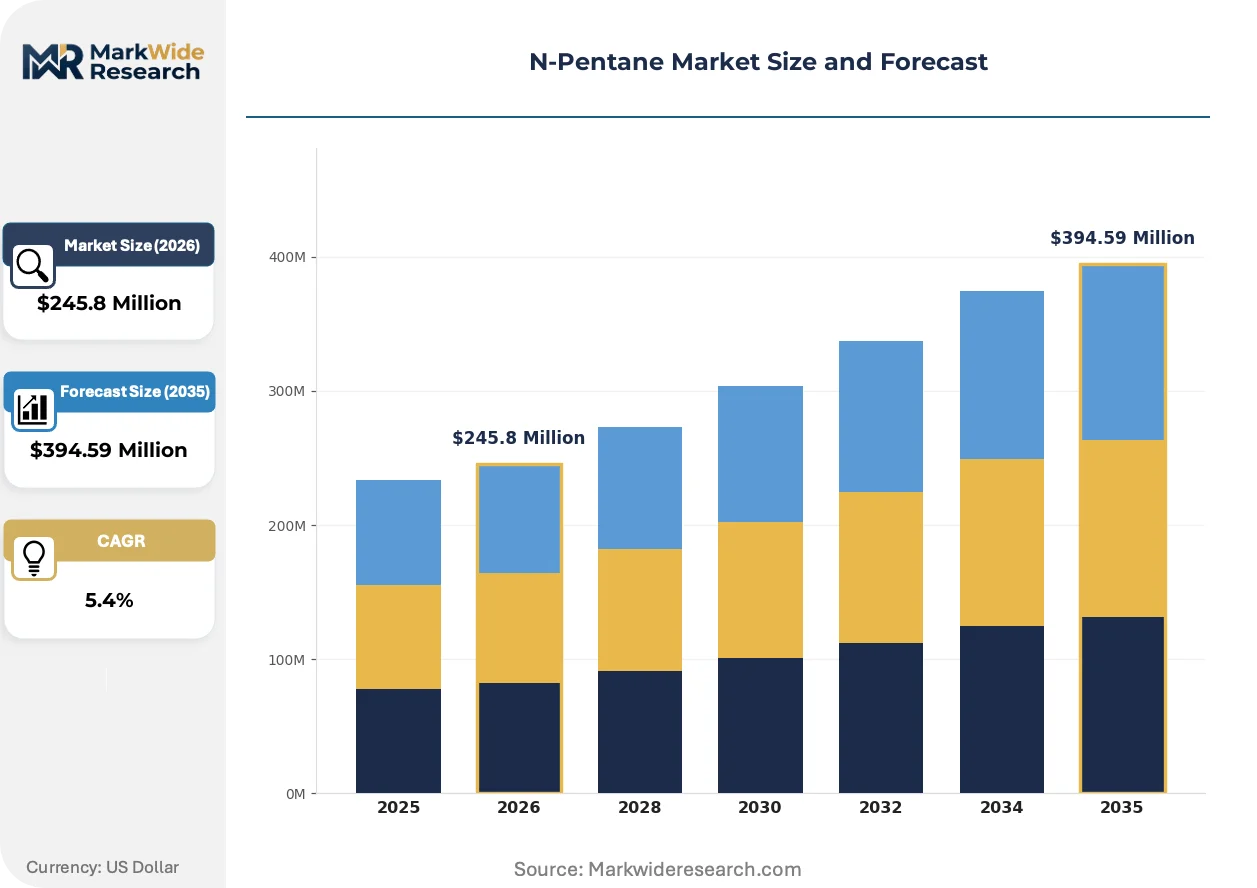
| Market Size in 2026 | $245.8 Million |
| Market Size in 2035 | $394.59 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Pharmaceutical Grade, Laboratory Grade, Analytical Grade Application: Solvent, Extraction, Refrigerant, Chemical Intermediate End User: Petrochemical Industry, Pharmaceutical Manufacturers, Research Laboratories, Food Industry Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | ExxonMobil, Shell, Phillips 66, Chevron Phillips Chemical, Junyuan Petroleum Group, HCS Group, Thai Oil Public Company Limited, LG Chem, INEOS Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
N-Pentane Market Emerging Trajectories
Process intensification in foam manufacturing is compressing the acceptable specification window for blowing agents, rewarding suppliers with tighter distillation control and batch-to-batch consistency. Technology, regulatory, and procurement vectors are converging to reshape competitive positioning.
Membrane separation technology for n-pentane-isopentane splitting is consolidating around polyimide hollow-fiber modules that achieve 99.5 percent purity without energy-intensive fractional distillation. Polyurethane foam producers in Germany and South Korea are adopting this upgrade to meet REACH contaminant thresholds. The technology is consolidating supply advantage among refiners with capital to retrofit existing splitter columns.
EPA's updated National Emission Standards for Hazardous Air Pollutants for synthetic organic chemical manufacturing are tightening leak detection and repair requirements for light hydrocarbon storage. Facilities in Texas and Louisiana face accelerated monitoring frequencies and expanded component counts. Pharmaceutical-grade producers with existing LDAR infrastructure are absorbing compliance costs more readily than industrial-grade competitors.
Long-term offtake contracting is displacing spot procurement among large polyurethane foam manufacturers seeking insulation against Shandong supply disruptions. Tier-one automotive seating producers in Michigan and Bavaria are leading this shift, locking in three-to-five year supply agreements with volume commitments. This pattern is most visible in North American and Western European markets where just-in-time foam delivery requirements leave minimal inventory buffer.
N-Pentane Market Segmentation
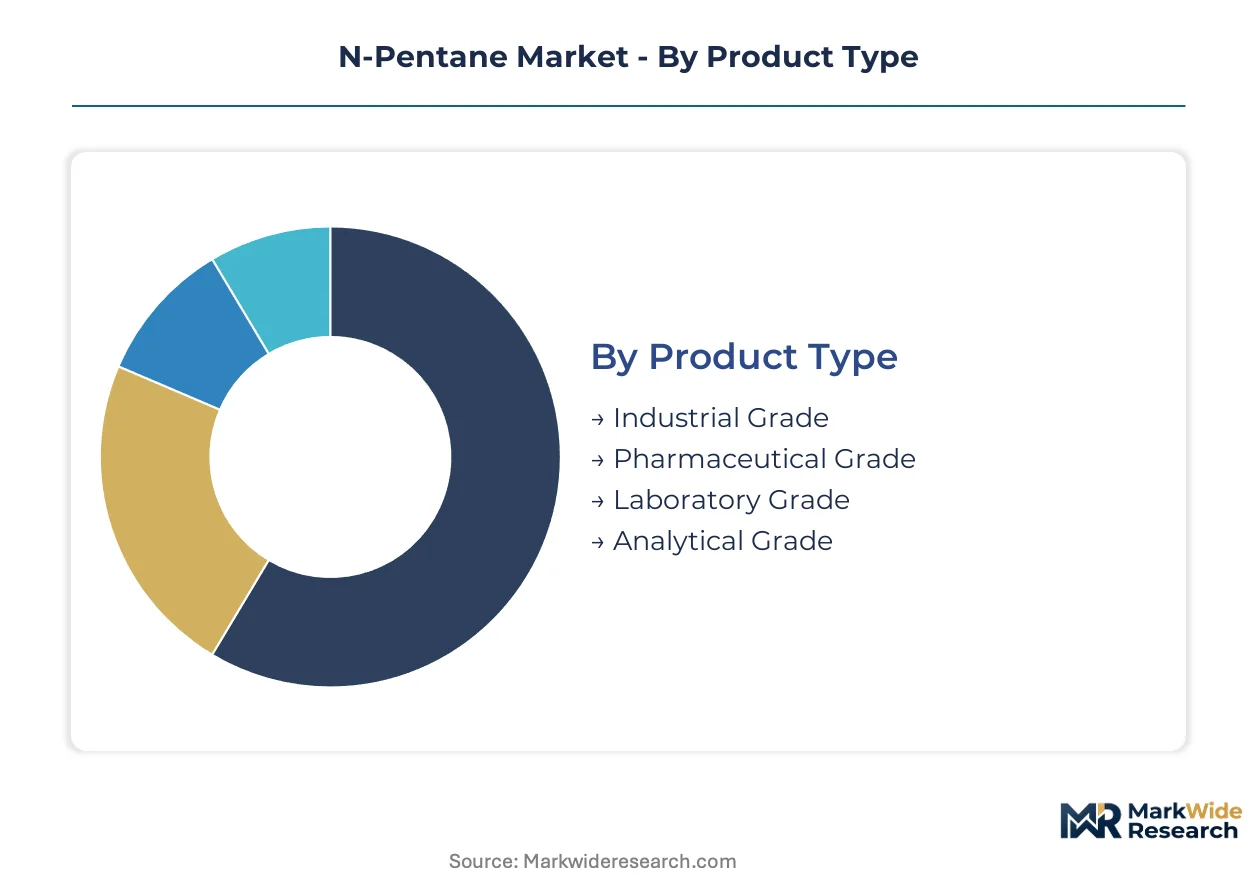
N-pentane market segmentation reflects divergent capital requirements across purity tiers and end-use specifications. Investment intensity varies sharply between industrial-grade volume plays and pharmaceutical-grade compliance infrastructure. Understanding these structural divisions reveals where margin compression and expansion pressures concentrate.
Product Type:
Capital intensity escalates dramatically from industrial through pharmaceutical grades, with distillation train complexity and certification infrastructure driving fixed cost differentials.
- Industrial Grade:Material with 85-95 percent purity serves polyurethane foam blowing and general solvent applications. Demand clusters in China's Shandong province where integrated refiners feed regional petrochemical complexes with pipeline-connected supply. Cost sensitivity dominates procurement decisions as foam manufacturers absorb volatility in upstream crude fractions.
- Pharmaceutical Grade:USP-NF and EP monograph-compliant material commands specification premiums from drug manufacturers facing FDA and EMA inspection protocols. Validation cycles spanning 18-24 months create compliance moats that delay competitor entry. Supercritical botanical extraction applications in North American cannabis processing are absorbing growing volumes.
- Laboratory Grade:ACS-certified specifications support academic and industrial R&D workflows with documented lot traceability.
- Analytical Grade:Ultra-high purity material for chromatography and spectroscopy applications where contaminant thresholds are measured in parts per billion.
Industrial grade absorbs the bulk of installed capacity; pharmaceutical grade is expanding most quickly.
Application:
Application mix determines exposure to regulatory vectors, with solvent and extraction uses facing divergent EPA and REACH compliance burdens.
- Solvent:Non-polar dissolution capacity serves coatings, adhesives, and cleaning formulations. OSHA permissible exposure limits and EPA volatile organic compound regulations constrain formulation flexibility in US manufacturing facilities. REACH registration requirements above one tonne annually filter out non-compliant traders in European markets.
- Extraction:Botanical and essential oil processing absorbs high-purity n-pentane for cannabinoid isolation and natural product concentration. Supercritical extraction technology adoption in Colorado and Oregon is driving specification tightening for contaminant thresholds.
- Refrigerant:Secondary cooling applications in specialized industrial equipment where thermodynamic properties match system requirements.
- Chemical Intermediate:Dehydrogenation feedstock for pentene production as crackers seek lighter feedstocks to optimize ethylene yields.
Solvent applications retain the largest volume footprint; extraction uses are climbing the fastest.
End User:
End-user concentration shapes supplier relationship structures, with petrochemical procurement patterns differing sharply from pharmaceutical qualification protocols.
- Petrochemical Industry:Polyurethane foam manufacturers consolidate supply relationships around integrated clusters guaranteeing purity above 95 percent. Tier-one automotive seating producers in Michigan and Bavaria are locking in three-to-five year offtake agreements to buffer against Shandong supply disruptions.
- Pharmaceutical Manufacturers:FDA and EMA compliance requirements drive pharmacopeial certification investments with extended validation timelines. Existing LDAR infrastructure at US Gulf Coast facilities absorbs EPA leak detection cost burdens more readily than industrial-grade competitors.
- Research Laboratories:Fragmented demand across academic and corporate R&D centers with specification variability.
- Food Industry:Extraction applications for natural flavor and fragrance compounds with FSSAI and FDA food contact compliance requirements.
Petrochemical industry procurement dominates volume flows; pharmaceutical manufacturers are gaining share fastest.
Distribution Channel:
Channel selection reflects customer scale and specification complexity, with direct relationships concentrating among large-volume foam producers.
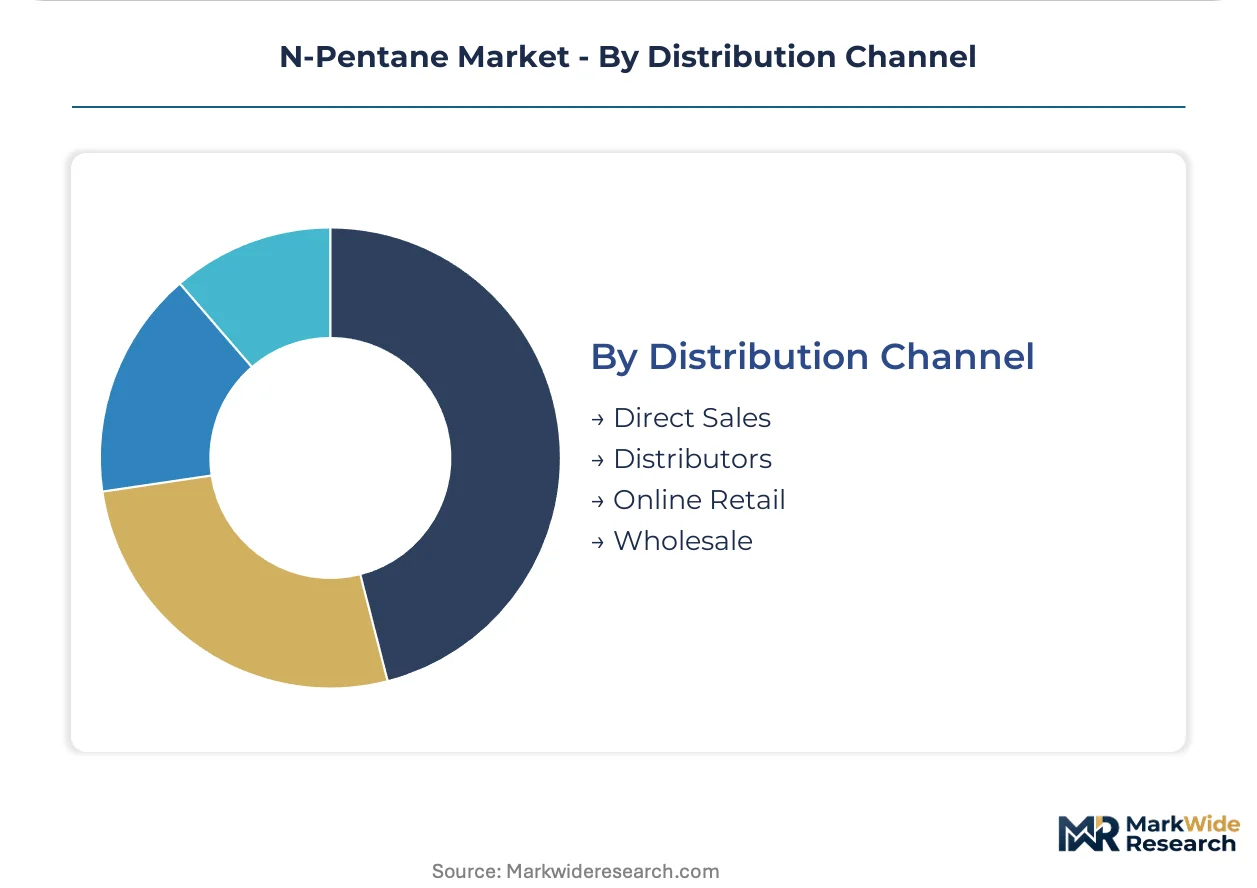
- Direct Sales:Long-term contracting with integrated refiners captures volume commitments from automotive and appliance foam manufacturers. Pipeline-connected supply in Shandong province eliminates intermediary handling for regional polyurethane producers.
- Distributors:Regional chemical distributors serve mid-tier foam producers and specialty solvent blenders with inventory buffering.
- Online Retail:E-commerce platforms absorb small-laboratory and R&D procurement with documented certificate of analysis availability.
- Wholesale:Bulk terminal operators consolidate industrial-grade flows for downstream repackaging and formulation.
Direct sales channels capture the majority of value; online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong province's integrated refining complexes anchor n-pentane supply chains serving polyurethane foam manufacturers across East Asia. Regional demand patterns diverge sharply based on regulatory maturity and downstream industrial concentration.
United States
Polyurethane foam producers in Michigan and Texas absorb industrial-grade volumes for automotive seating and appliance insulation. EPA's National Emission Standards for Hazardous Air Pollutants enforce accelerated leak detection protocols at Gulf Coast storage facilities. The Texas-Louisiana petrochemical corridor concentrates refining capacity that feeds domestic blowing agent demand.
Germany
REACH registration deadlines above one tonne annually filter non-compliant traders, redirecting solvent volumes toward registered producers. ECHA documentation requirements shape procurement protocols for extraction and coating applications. The Ruhr industrial basin hosts distillation infrastructure serving pharmaceutical-grade specifications.
China
Shandong province's pipeline-connected complexes capture regional polyurethane demand through integrated n-pentane production. MEE environmental compliance inspections periodically constrain operating rates at coastal refiners. Qingdao and Zibo clusters supply foam manufacturers with purity guarantees above 95 percent.
South Korea
Membrane separation technology adoption for isomer splitting concentrates among refiners serving domestic foam producers. MFDS pharmaceutical compliance timelines extend validation cycles for USP-grade material. The Ulsan petrochemical complex anchors supply relationships with tier-one automotive seating manufacturers.
India
BIS certification pathways for hydrocarbon blowing agents remain under formal adoption, creating uncertainty for import-dependent foam manufacturers. CDSCO pharmaceutical regulations govern extraction solvent applications in botanical processing. Gujarat's specialty chemical corridor attracts investment in distillation infrastructure.
N-Pentane Market Vendor Landscape
Global majors compete with regional champions across feedstock access and logistics reach. The vendor base stratifies between integrated refiners with captive light naphtha supply and standalone processors dependent on spot feedstock markets. Three archetypes dominate: integrated oil majors controlling upstream fractions, regional petrochemical specialists with geographic proximity to demand clusters, and pharmaceutical-grade refiners with pharmacopeial certification infrastructure. Capacity expansion and long-term offtake contracting represent the dominant competitive moves.
Within the integrated oil major tier, ExxonMobil and Shell exemplify feedstock-integrated positioning through refining-petrochemical complex ownership. Junyuan Petroleum Group occupies a regional specialist position anchoring supply relationships with Shandong-based foam manufacturers. These three represent the structural spectrum from global logistics networks to geographically concentrated pipeline supply.
| Leading Market Players |
|---|
| ExxonMobil |
| Shell |
| Phillips 66 |
| Chevron Phillips Chemical |
| Junyuan Petroleum Group |
| HCS Group |
| Thai Oil Public Company Limited |
| LG Chem |
| INEOS Group |
| Others |
Supply Flow & Price Mechanics
REACH registration deadlines above one tonne annually are forcing European foam manufacturers toward certified suppliers with documented hazard profiles, compressing procurement options and amplifying pricing power for registered producers with existing ECHA compliance infrastructure.
Pricing Analysis
Certificate-of-analysis bundling separates pharmaceutical-grade suppliers charging specification premiums from industrial-grade competitors competing on volume scale. Three-tier pricing structure across pharmaceutical, industrial, and laboratory grades reflects distillation complexity and validation timeline differentials. Cost compression in industrial-grade material is intensifying because Shandong-based integrated refiners absorb upstream crude fraction volatility through captive naphtha supply. Mid-tier polyurethane foam manufacturers exhibit highest price sensitivity, while pharmaceutical extractors facing FDA inspection protocols accept premium pricing for USP-NF monograph compliance.
Supply Chain Analysis
India's pending BIS certification for hydrocarbon blowing agents is reshaping sourcing decisions among import-dependent foam manufacturers, accelerating local distillation investments in Gujarat's specialty chemical corridor. Production gravity centers on China's Shandong province, South Korea's Ulsan complex, and the Texas-Louisiana Gulf Coast petrochemical corridor. Feedstock supply draws from light naphtha cuts, membrane separation modules for isomer splitting, and pharmaceutical-grade distillation trains. Single-source vulnerability concentrates around Shandong pipeline-connected supply serving East Asian foam demand. Distribution runs through long-term offtake contracts with automotive seating manufacturers, regional chemical distributors for mid-tier blenders, and pipeline-connected direct supply for integrated cluster customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around registered producers with pharmacopeial certification infrastructure, as REACH and EPA compliance timelines filter out non-compliant traders and speculative entrants lacking hazard documentation capabilities.
For Market Incumbents: Deepen backward integration into captive light naphtha supply to buffer against gasoline blending economics that divert C5 molecules toward fuel pools. Expand membrane separation retrofit capacity to capture REACH-compliant isomer splitting demand from German and South Korean foam manufacturers facing ECHA contaminant thresholds. Isopentane substitution in polystyrene applications threatens n-pentane volume in select blowing agent segments. For New Entrants and Emerging Players: Small-batch pharmaceutical extractors in Colorado and Oregon represent an underserved buyer archetype seeking high-purity n-pentane with documented lot traceability for supercritical cannabinoid processing. India's BIS certification pathway offers the most penetrable regulatory entry point before formal adoption creates compliance moats against unregistered imports. Target pharmacopeial certification investment as the primary go-to-market angle, accepting extended 18-24 month validation cycles to access premium pricing tiers. For Investors and Strategic Acquirers: The window for entry favors pharmaceutical-grade refiners with existing USP-NF and EP monograph infrastructure, as industrial-grade volume plays face margin compression from Shandong supply concentration. Long-term viability rests on acquisition targets with LDAR-compliant storage facilities absorbing EPA leak detection cost burdens more readily than competitors lacking process safety engineering talent. Watch India's formal BIS adoption timeline as the inflection indicator for regional supply restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive light naphtha supply buffers ExxonMobil and Shell against gasoline blending volatility diverting C5 molecules. |
| Pharmacopeial Certification Investment | USP-NF and EP monograph compliance creates 18-24 month entry barriers protecting premium pricing for certified producers. |
| Membrane Separation Retrofit | Polyimide hollow-fiber modules enable 99.5% purity without energy-intensive distillation, consolidating advantage among capital-rich refiners. |
| Long-term Supply Agreement | Three-to-five year offtake contracts with Michigan and Bavaria automotive seating manufacturers buffer against Shandong disruption risk. |
| Geographic Expansion | Gujarat's specialty chemical corridor attracts distillation investment ahead of India's BIS certification formal adoption. |
Methodological Framework
Trade databases, ECHA registration filings, and SEC 10-K disclosures from petrochemical majors formed the secondary backbone for volume and value estimation. Primary interviews with polyurethane foam procurement leads, refinery operations managers, pharmaceutical extraction facility directors, and specialty chemical distributors validated grade-level demand splits and pricing differentials. Bottom-up and top-down triangulation reconciled Shandong production estimates with downstream consumption patterns across automotive seating, appliance insulation, and botanical extraction applications.
Bottom-up modeling built forecasts from individual grade-application combinations, while top-down validation checked aggregate figures against regional petrochemical consumption trends across the analysis window. Segmentation dimensions included purity tier, end-use industry, and regional regulatory cluster. CAGRs derived from slope analysis of year-on-year growth trajectories, with crude oil fraction economics and REACH compliance timelines as key forecast inputs.
Revisions become necessary when MEE environmental inspections constrain Shandong operating rates, BIS certification formalizes unexpectedly in India, or membrane separation technology achieves cost parity with conventional distillation at scale. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Organic Peroxide Market
Organic Chemicals
4-Tert-Butylcyclohexanone Market
Organic Chemicals
Organic Polysulfide Market
Organic Chemicals
Behenyl Alcohol Market
Organic Chemicals
North America Phenol Market
Organic Chemicals
Phenolic Board Market
Organic Chemicals
Global Ketones Market
Organic Chemicals
Triethylene Glycol Market
Organic Chemicals
Asia-Pacific Organic Acid Market
Organic Chemicals
Methacrylic Acid Market
Organic Chemicals
Synthetic Camphor Market
Organic Chemicals
Heterocyclic and Fluoro Organic Compounds Market
Organic Chemicals
Organic Acids Market
Organic Chemicals
Organic Coating Market
Organic Chemicals
Cyclohexanone Market
Organic Chemicals
Methyl Isobutyl Ketone (MIBK) Market