
 Alkylate Market | 2026-2036
Alkylate Market Size, Share, and Industry Trends Forecast 2026-2036
Alkylate Market Analysis
Refinery process engineering talent scarcity is redrawing competitive boundaries in alkylate production. ExxonMobil Corporation leverages its proprietary alkylation technology portfolio across integrated Gulf Coast facilities. Chevron Corporation sustains advantage through backward integration into sulfuric acid alkylation operations. Marathon Petroleum Corporation anchors Midwest supply chains with concentrated refining logistics.
Alkylate denotes a premium synthetic hydrocarbon mixture produced via catalytic alkylation of isobutane with light olefins, yielding Research Octane Numbers typically exceeding 90 with near-zero sulfur and aromatic content. Its primary purpose centers on clean-burning gasoline blending for compliance with stringent transportation fuel standards. Alkylate gasoline dominates value capture within product type segmentation, while alkylate solvents gain traction in coatings applications requiring low-VOC formulations. Fuel blending anchors end-use volume, though chemical processing applications for high-purity alkylate feedstocks represent the fastest-expanding margin pool.
EPA Tier 3 sulfur limits and EU F-Gas Regulation phase-down schedules compel refiners to prioritize alkylation capacity over reforming routes. The central bank of India and BIS fuel quality mandates similarly redirect Asian refining investment toward alkylation unit retrofits. Stakeholders must weigh sulfuric acid versus hydrofluoric acid process licensing costs against emerging solid-acid catalyst technologies when committing capital to new alkylation infrastructure.
Market Dynamics
Alkylation unit operators face mounting pressure from EPA Tier 3 sulfur mandates and the EU F-Gas Regulation phase-down, forcing capital reallocation away from reforming capacity toward sulfuric acid and solid-acid catalyst systems. This regulatory compression is restructuring competitive economics across gasoline blending value chains.
Growth Catalysts
- EPA Tier 3 Sulfur Limits:US refiners must achieve 10 parts per million gasoline sulfur ceilings, eliminating reformate blending and redirecting volume toward alkylate as the primary high-octane, low-sulfur component.
- India BIS Fuel Quality Mandates:Bharat Stage VI implementation compels domestic refiners to retrofit alkylation capacity, opening infrastructure investment cycles across Mumbai, Jamnagar, and Vadodara refining clusters.
- Solid-Acid Catalyst Systems:Emerging heterogeneous catalyst technologies eliminate liquid acid handling hazards, reducing regulatory compliance burdens and enabling modular unit deployment at smaller refineries.
Market Restraints
- Isobutane Feedstock Concentration:North American isobutane supply concentrates around Mont Belvieu pricing hubs, exposing alkylate producers to NGL fractionation bottlenecks and seasonal volatility.
- Hydrofluoric Acid Regulatory Friction:EPA Risk Management Plan amendments and community safety ordinances impose costly mitigation systems on existing HF alkylation units, constraining capacity expansion.
- Renewable Diesel Displacement:Renewable diesel and sustainable aviation fuel offtake agreements redirect hydrogen and hydrotreating capacity away from alkylate-supporting hydrocracker operations.
Strategic Opportunities
- China Dual Carbon Goals:NMPA and MEE emissions frameworks position alkylate as a bridging compliance fuel, creating licensing windows for sulfuric acid technology transfers to Sinopec and PetroChina facilities.
- Coatings Solvent Applications:Low-VOC alkylate solvents penetrate architectural coatings formulations, capturing share from aromatic hydrocarbons under REACH restriction candidate list pressures.
- Brazil ANVISA Pharmaceutical Purity Standards:High-purity alkylate feedstocks qualify for excipient and API synthesis, opening pharmaceutical-grade production lines for isoparaffinic solvents.
Industry Challenges
- Process Engineering Talent Scarcity:Alkylation unit design and catalyst optimization expertise concentrates among retiring specialists at integrated majors, constraining independent refinery technical staffing.
- Legacy System Integration Complexity:Solid-acid catalyst retrofits require extensive revamp of existing sulfuric acid infrastructure, extending turnaround timelines and compressing effective operating windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alkylate Market |
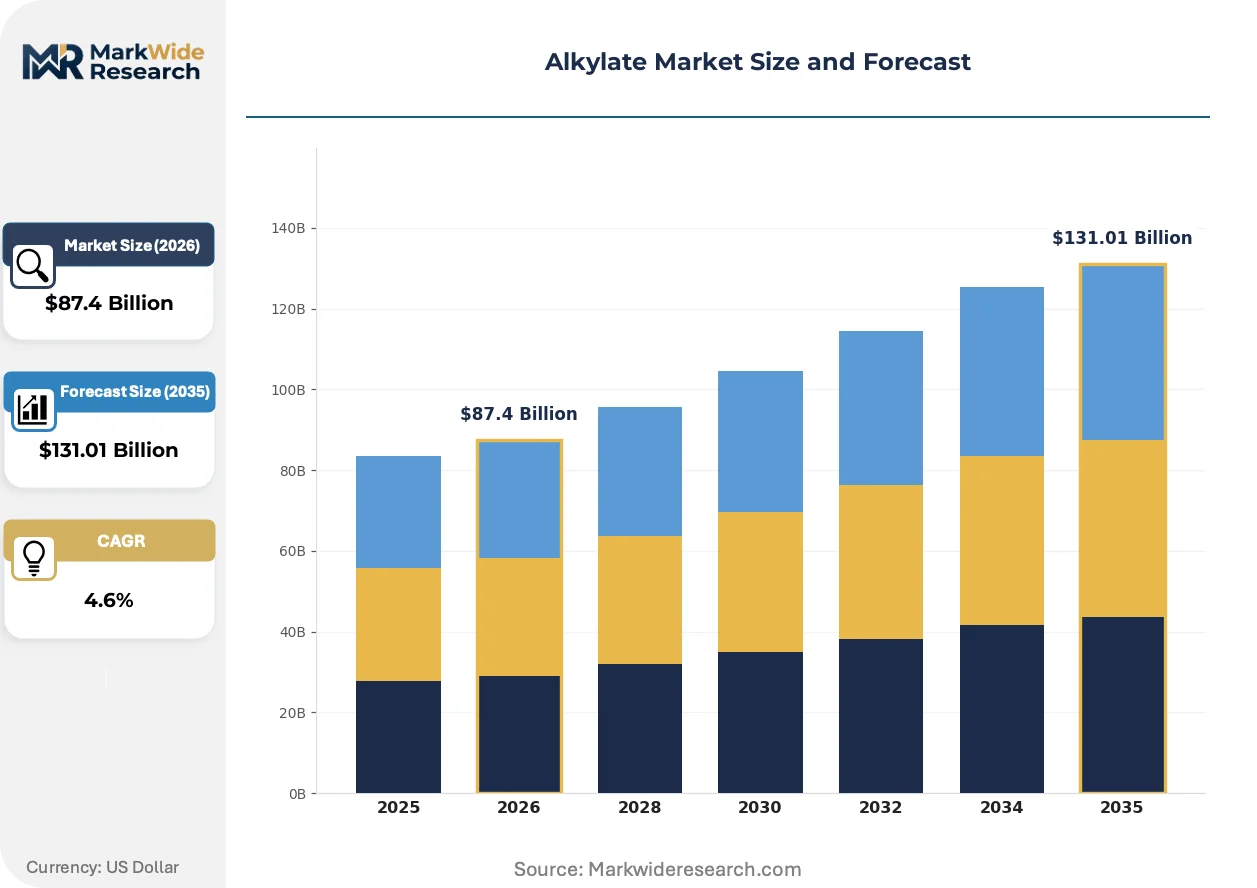
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $131.01 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkylate Gasoline, Alkylate Solvent, Alkylate Additives, Alkylate Chemicals End Use Industry: Automotive, Aerospace, Chemical Processing, Marine Application: Fuel Blending, Lubricants, Coatings, Petrochemicals Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Chevron Corporation, Reliance Industries Limited, ExxonMobil Corporation, Honeywell International Inc., PJSC Lukoil Oil Company, Marathon Petroleum Corporation, Royal Dutch Shell plc, Neste Oyj, Valero Energy Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alkylate Market Emerging Trajectories
Alkylate production technology is bifurcating between legacy liquid acid optimization and solid-acid catalyst commercialization, with regulatory tailwinds accelerating process intensification investments. This divergence is compressing equipment supplier lead times and reshaping licensing economics.
Alkylation process equipment is miniaturizing through modular skid-mounted solid-acid reactor designs. Independent refiners in the US Gulf Coast and Asia-Pacific are adopting these compact units to bypass large-scale sulfuric acid infrastructure requirements. This miniaturization is enabling distributed alkylate production at smaller facilities previously excluded from alkylation economics.
EU F-Gas Regulation phase-down schedules are tightening hydrofluorocarbon containment requirements and extending to refinery process emissions frameworks. European alkylation operators face accelerated HF unit replacement timelines and elevated insurance premiums. German KBA and French ANSM technical inspections are now incorporating alkylation safety audits into operating license renewals.
Refinery procurement patterns are consolidating around integrated catalyst and technology licensing packages. Mid-sized operators increasingly source solid-acid systems through single-source engineering contracts rather than component procurement. This bundling trend is most pronounced in India, where Reliance Industries and Indian Oil Corporation negotiate turnkey alkylation retrofits combining catalyst supply, reactor fabrication, and performance guarantees.
Alkylate Market Segmentation
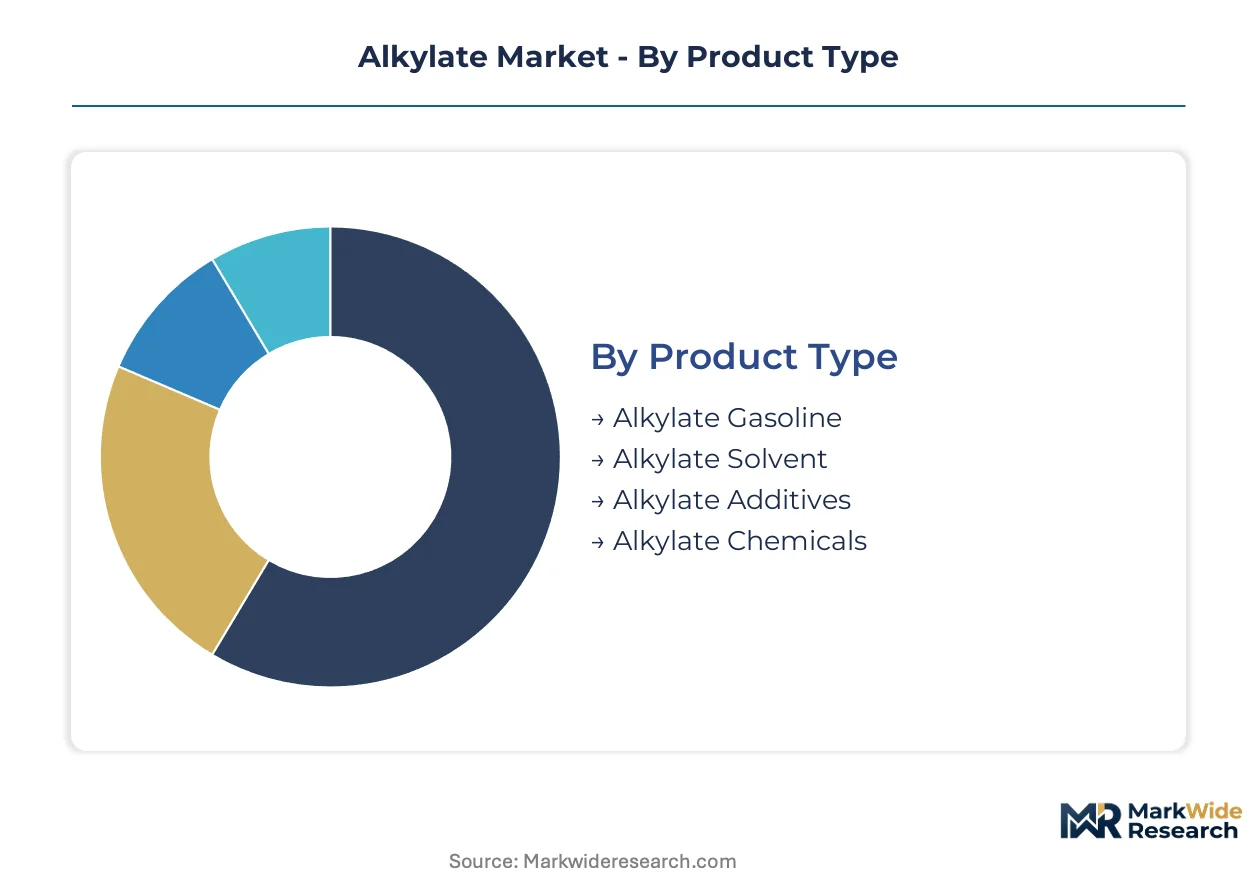
Alkylate market segmentation reveals distinct channel economics and margin structures across product categories. Refinery-direct contracts dominate high-volume fuel blending, while specialty chemical distributors capture premium solvent applications.
Product Type:
Channel-mix patterns diverge sharply: alkylate gasoline flows through refinery term contracts and rack sales, while alkylate solvents route through specialty chemical distributors serving coatings and pharmaceutical formulators.
- Alkylate Gasoline:A synthetic isoparaffinic blendstock with Research Octane Numbers exceeding 90 and near-zero sulfur content, produced via catalytic alkylation of isobutane with light olefins. Demand concentrates at US Gulf Coast refining clusters where EPA Tier 3 compliance mandates eliminate reformate blending alternatives. Marathon Petroleum and Valero anchor procurement through dedicated pipeline connectivity.
- Alkylate Solvent:High-purity isoparaffinic fractions with controlled evaporation rates and minimal aromatic content, qualifying for low-VOC coatings formulations. European coatings manufacturers under REACH restriction candidate list pressures represent the fastest-expanding demand pool, with German and French formulators switching from aromatic hydrocarbons.
- Alkylate Additives:Functionalized alkylate derivatives serving as pour point depressants and viscosity modifiers in lubricant base stocks.
- Alkylate Chemicals:High-purity feedstocks for surfactant synthesis and polymerization processes, qualifying for Brazil ANVISA pharmaceutical-grade specifications.
By volume, alkylate gasoline leads. By growth pace, alkylate solvents are expanding most quickly.
End Use Industry:
Cost-tier segmentation separates commodity fuel blenders from premium specialty chemical buyers, with automotive commanding the lowest per-unit margins and aerospace extracting the highest purity premiums.
- Automotive:Gasoline blenders at US, Indian, and Chinese refineries constitute the foundational demand tier, with Bharat Stage VI and China VI-B mandates forcing alkylation capacity investments.
- Aerospace:Sustainable aviation fuel offtake agreements are redirecting hydrogen capacity, constraining alkylate-supporting hydrocracker operations at integrated refineries.
- Chemical Processing:Petrochemical crackers and surfactant manufacturers source high-purity alkylate for downstream olefin production.
- Marine:IMO 2020 sulfur regulations opened marine gasoil blending applications, though renewable diesel displacement is compressing this segment's expansion trajectory.
Automotive generates the highest absolute volume. Aerospace commands the steepest purity premiums and margin capture.
Application:
Volume concentration favors fuel blending, while margin concentration shifts toward coatings and petrochemical feedstocks as specialty purity requirements escalate.
- Fuel Blending:The dominant application channel, with EPA Tier 3 and EU fuel quality directives mandating alkylate as the primary high-octane, low-sulfur gasoline component.
- Coatings:Architectural and industrial coatings formulators under EU VOC regulations are gaining share fastest, with German KBA technical inspections now incorporating solvent safety audits.
- Lubricants:Base oil producers leverage alkylate-derived synthetic components for Group III+ and Group IV lubricant formulations.
- Petrochemicals:Steam crackers and alkylation units feed integrated olefin production chains.
Fuel blending anchors volume. Coatings applications are climbing the fastest on regulatory tailwinds.
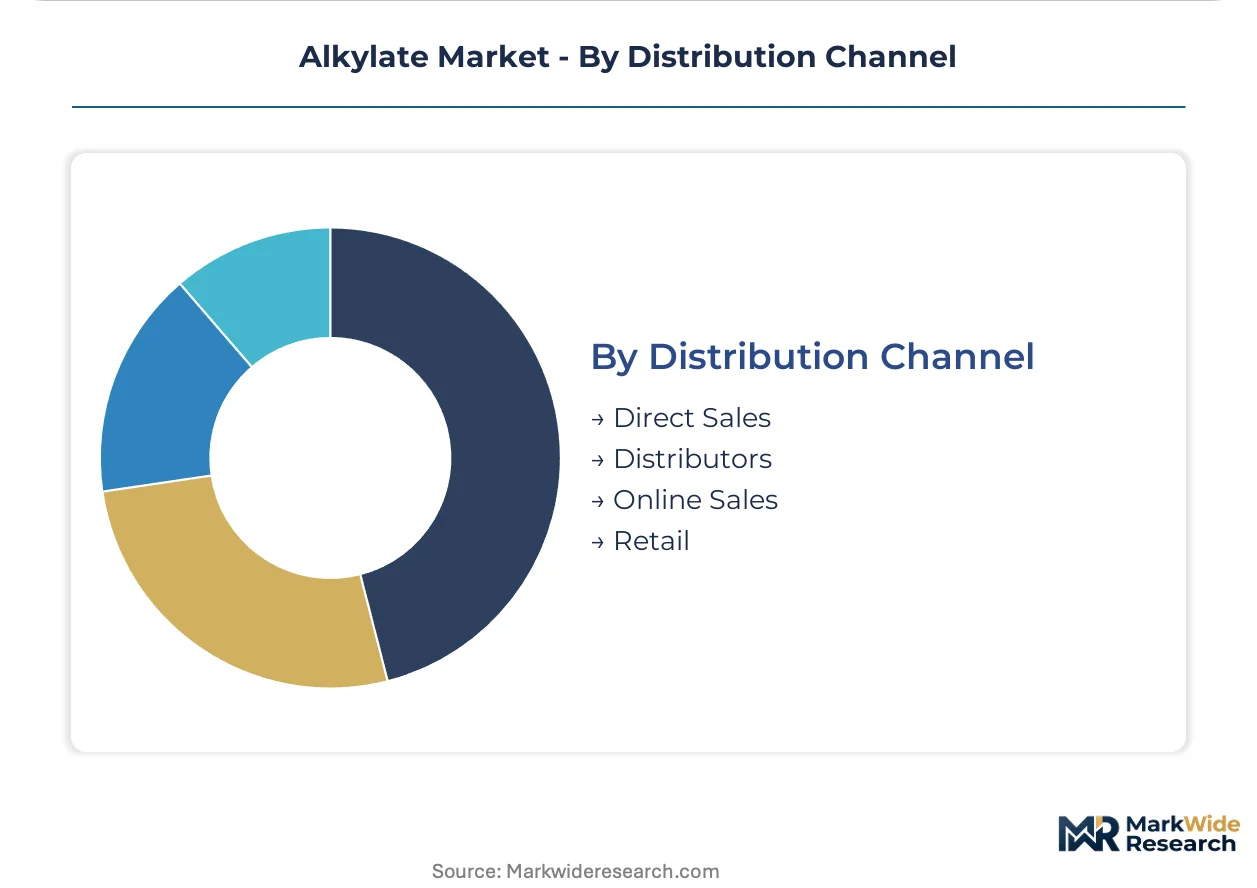
Distribution Channel:
Customer-type segmentation separates integrated refinery operators from independent blenders and specialty chemical purchasers, with contract structures varying by volume commitment and purity specification.
- Direct Sales:Refinery-to-refinery term contracts and dedicated pipeline arrangements dominate alkylate gasoline movements, with Mont Belvieu pricing hubs setting regional benchmarks.
- Distributors:Specialty chemical distributors capture alkylate solvent value through technical service bundling and just-in-time delivery to coatings and pharmaceutical formulators.
- Online Sales:Spot market platforms and digital procurement tools are emerging for smaller independent refiners seeking supplemental alkylate volumes.
- Retail:Limited to packaged solvent sales for laboratory and small-scale industrial applications.
Direct sales capture the highest volume share. Distributors are gaining share fastest in specialty solvent categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mont Belvieu pricing hubs in Texas command premium isobutane valuations that Gulf Coast refiners leverage against Asian buyers facing Bharat Stage VI retrofit costs. This pricing-power asymmetry between North American supply concentration and Asian demand expansion is restructuring contract negotiation leverage across the forecast window.
United States
EPA Tier 3 sulfur mandates and renewable diesel capacity competition frame refinery investment priorities. The 10 parts per million gasoline sulfur ceiling eliminates reformate blending options. Gulf Coast refining clusters around Houston and Port Arthur anchor alkylation unit expansions serving domestic gasoline blenders.
India
BIS fuel quality mandates and Bharat Stage VI implementation compel domestic refinery retrofits. Mumbai, Jamnagar, and Vadodara refining clusters concentrate alkylation infrastructure investment. Reliance Industries and Indian Oil Corporation negotiate turnkey technology licensing packages combining catalyst supply with performance guarantees.
China
NMPA and MEE emissions frameworks position alkylate as a bridging compliance fuel under dual carbon goals. Sinopec and PetroChina facilities absorb sulfuric acid technology transfers. Yangtze River Delta and Pearl River Delta refining hubs prioritize alkylation over reforming for China VI-B gasoline production.
Germany
KBA technical inspections now incorporate alkylation safety audits into operating license renewals under EU F-Gas Regulation phase-down schedules. German refiners face accelerated HF unit replacement timelines. North Rhine-Westphalia's refining corridor absorbs elevated insurance premiums and containment system investments.
Brazil
ANVISA pharmaceutical purity standards open pharmaceutical-grade production lines for isoparaffinic solvents. São Paulo and Rio de Janeiro petrochemical complexes qualify high-purity alkylate feedstocks for excipient and API synthesis. Petrobras refining subsidiaries evaluate solvent diversification beyond fuel blending applications.
Alkylate Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the alkylate production landscape. Integrated majors with proprietary alkylation technology portfolios command licensing revenue streams, while independent refiners concentrate on feedstock arbitrage and operational efficiency. The competitive structure separates into three strategic archetypes: integrated technology licensors, mid-scale refinery operators, and specialty chemical diversifiers. Dominant competitive moves include solid-acid catalyst technology licensing and backward integration into sulfuric acid supply chains.
Within the integrated technology licensor tier, ExxonMobil Corporation and Chevron Corporation anchor proprietary alkylation technology positions across Gulf Coast facilities. Marathon Petroleum Corporation exemplifies the mid-scale refinery operator archetype through concentrated Midwest supply chain logistics. Honeywell International Inc. occupies a distinct position representing process technology and catalyst system suppliers licensing solid-acid systems to independent refiners.
| Leading Market Players |
|---|
| Chevron Corporation |
| Reliance Industries Limited |
| ExxonMobil Corporation |
| Honeywell International Inc. |
| PJSC Lukoil Oil Company |
| Marathon Petroleum Corporation |
| Royal Dutch Shell plc |
| Neste Oyj |
| Valero Energy Corporation |
| Others |
Supply Flow & Price Mechanics
Solid-acid catalyst substitution for legacy liquid acid systems is redrawing supply geography toward modular equipment fabricators while compressing licensing premiums that historically anchored refinery technology economics. This displacement simultaneously fragments procurement patterns and erodes the pricing power of integrated technology licensors.
Pricing Analysis
The customization-premium spread separates turnkey solid-acid reactor packages from standard sulfuric acid unit retrofits, with performance guarantees commanding material uplifts over component procurement. Price differentiation rests on catalyst lifecycle guarantees and bundled engineering services rather than equipment alone. Cost compression in standard-grade alkylate gasoline is intensifying because renewable diesel offtake agreements redirect hydrogen capacity. Independent refiners exhibit highest price sensitivity, while integrated majors prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Inbound logistics costs for isobutane feedstock hinge on Mont Belvieu NGL fractionation capacity and Gulf Coast pipeline availability, exposing Asian buyers to freight differentials and seasonal bottlenecks. Supply concentrates in the United States, India, and China, with isobutane, sulfuric acid, and solid-acid catalysts constituting critical input dependencies. Single-source vulnerability concentrates around proprietary catalyst suppliers, constraining refiner negotiating leverage. Distribution runs through refinery-direct term contracts for gasoline volumes and specialty chemical distributors for solvent grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Alkylate production is approaching a platform-economics inflection where solid-acid catalyst interoperability standards will determine technology licensing dominance, much as semiconductor equipment modularization reshaped fabrication economics.
For Market Incumbents: Consolidate proprietary catalyst intellectual property through exclusive supply agreements with modular reactor fabricators, and anchor backward integration into sulfuric acid production to defend margin position against solid-acid displacement. ExxonMobil and Chevron licensing portfolios face erosion from emerging heterogeneous catalyst suppliers. For New Entrants and Emerging Players: Differentiate on pharmaceutical-grade alkylate solvent purity under Brazil ANVISA and EU REACH frameworks, where certification barriers protect premium positioning. The coatings solvent segment offers lowest incumbent concentration and fastest regulatory tailwinds. Pursue technical service bundling with just-in-time delivery to capture share from aromatic hydrocarbon incumbents. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors solid-acid catalyst licensors with modular deployment capabilities over legacy liquid acid operators. Long-term viability centers on process intensification intellectual property and refinery retrofit execution expertise. Watch EPA Risk Management Plan amendment timelines as inflection signals for HF alkylation unit replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing Partnership | Secures catalyst supply and performance guarantees for refinery retrofits under Bharat Stage VI mandates. |
| Backward Integration into Sulfuric Acid | Captures margin pool and insulates against Mont Belvieu feedstock volatility for Gulf Coast operators. |
| Pharmaceutical-Grade Solvent Line | Qualifies for ANVISA excipient standards and REACH-compliant coatings formulations in São Paulo and Frankfurt clusters. |
| Modular Solid-Acid Deployment | Enables distributed alkylate production at smaller refineries previously excluded from alkylation economics. |
| Process Engineering Talent Acquisition | Addresses scarcity of alkylation unit design expertise concentrated among retiring specialists at integrated majors. |
Methodological Framework
Desk research of refinery capacity databases, EPA regulatory filings, and EU F-Gas implementation schedules preceded structured interviews with alkylation unit operators, catalyst technology licensors, and downstream fuel blenders. Primary fieldwork with process engineering directors and procurement leads at US Gulf Coast and Indian refining clusters combined with secondary validation through customs trade data and SEC 10-K disclosures. Bottom-up unit economics and top-down market sizing underwent iterative triangulation.
Variance decomposition across product type, end-use industry, and regional regulatory framework segments shaped the analytical framework over the projection horizon. CAGRs derived from capacity expansion announcements, retrofit investment cycles, and fuel quality mandate implementation timelines. Modeled inputs included alkylation unit utilization rates, isobutane feedstock pricing differentials, and solid-acid catalyst adoption curves.
Decision-makers should treat outputs as directional under assumptions of sustained EPA Tier 3 enforcement and EU F-Gas phase-down adherence; material deviation in regulatory stringency or renewable diesel subsidy levels would warrant model refresh. Specific risks include hydrogen capacity reallocation to sustainable aviation fuel and isobutane supply disruptions from NGL fractionation bottlenecks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petrochemicals
Fossil Fuel-Based Plastics Market
Petrochemicals
Olefin Derivatives Market
Petrochemicals
Aliphatic Hydrocarbon Market
Petrochemicals
Chemical and Petroleum Containers Market
Petrochemicals
Pentane Market
Petrochemicals
Military Propellants Market
Petrochemicals
Alkylate Isooctane Market
Petrochemicals
Petrochemical Feedstock Market
Petrochemicals
Bio Butadiene Market
Petrochemicals
Propane Market
Petrochemicals
Propylene Carbonate Market
Petrochemicals
Light Olefins Market
Petrochemicals
Propylene Market
Petrochemicals
Global Polypropylene Market
Petrochemicals
Global Perfluorocarbons Market
Petrochemicals
Pentaerythritol Market