
 Global Methyl Tertiary Butyl Ether Market | 2026-2036
Global Methyl Tertiary Butyl Ether Market Size, Share, and Industry Trends Forecast 2026-2036
Global Methyl Tertiary Butyl Ether Market Foresight
REACH compliance is shifting the cost-of-entry calculus for European MTBE exporters, forcing reformulation investments that smaller traders cannot absorb. SABIC leverages captive feedstock access across Saudi Arabia's refining corridor to sustain margin advantages in purified grade supply. LyondellBasell Industries Holdings B.V. anchors its position through backward integration into refinery-grade propylene streams. China Petrochemical Corporation dominates domestic fuel additive volumes, operating the world's largest single-site MTBE train.
Methyl Tertiary Butyl Ether is an oxygenated ether compound manufactured via acid-catalyzed reaction of isobutylene with methanol, typically yielding a product with minimum purity of 98.5 percent and Reid vapor pressure below 8 psi. Its primary commercial purpose centers on gasoline blending, where it elevates octane ratings while reducing tailpipe carbon monoxide emissions through more complete combustion. The fuel additive segment leads absolute volume, though chemical intermediate applications for methyl methacrylate and butyl rubber production represent the fastest-expanding margin pool. Industrial grade supply occupies the mature, price-competitive core, while reagent grade commands premium positioning from pharmaceutical firms requiring sub-ppm sulfur specifications.
The EPA's Renewable Fuel Standard and California's CARB reformulated gasoline rules shape North American blending obligations, while China's MEE enforces dual carbon goals that tighten refinery emission ceilings and alter methanol sourcing economics. ECHA's REACH authorization process and evolving EU F-Gas Regulation indirectly pressure MTBE alternatives in select member states. Stakeholders must monitor regulatory divergence between octane booster mandates and carbon intensity accounting frameworks to align capital deployment with jurisdiction-specific compliance trajectories.
Market Dynamics
Refinery-grade propylene feedstock scarcity is compressing margin structures for non-integrated MTBE producers, forcing asset-light traders toward tolling arrangements or exit. Southeast Asian fuel retailers are accelerating storage infrastructure builds ahead of oxygenated gasoline mandates.
Growth Catalysts
- Indonesia's leaded fuel phase-out:State-owned Pertamina is expanding refinery capacity to meet Euro 4 gasoline specifications, driving oxygenate demand across the archipelago's 17,000-island distribution network.
- REACH authorization timelines:ECHA's substance evaluation protocols are consolidating European supply around registered importers with full dossier compliance, filtering speculative traders from the value chain.
- Fluid catalytic cracking yields:Refinery optimization toward lighter olefin output is expanding captive isobutylene availability for integrated MTBE producers in the US Gulf Coast and Saudi Arabia's refining corridor.
Market Restraints
- Methanol price volatility:Chinese coal-to-methanol economics swing with domestic energy policy, transmitting cost instability to merchant MTBE producers lacking long-term methanol offtake contracts.
- Ethanol substitution mandates:Brazil's ANP biofuel blending requirements and US EPA Renewable Fuel Standard volume obligations cap MTBE's addressable gasoline pool in Western Hemisphere markets.
- Reid vapor pressure constraints:Summer gasoline volatility limits in California's CARB regulations and US EPA standards restrict maximum MTBE inclusion rates in warm-climate formulations.
Strategic Opportunities
- Vietnam's refinery expansion:Nghi Son and Long Son complex ramp-ups are creating demand for imported oxygenates as domestic catalytic reforming capacity lags gasoline output growth.
- Methyl methacrylate feedstock pivot:Chemical-grade MTBE demand is accelerating for MMA production, where purity specifications command 15-25% premia over fuel-grade material.
- Carbon intensity accounting:EU Green Deal delegated acts on transport fuel lifecycle emissions are creating preferential sourcing incentives for MTBE produced with low-carbon methanol or bio-isobutylene.
Industry Challenges
- Process safety certification:OSHA PSM and EU Seveso III compliance for acid-catalyzed alkylation units demands specialized mechanical integrity programs that strain mid-scale operator resources.
- Legacy storage reconciliation:Underground tank remediation for MTBE-impacted groundwater sites in California and New England continues to impose liability reserves on former retail operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Methyl Tertiary Butyl Ether Market |
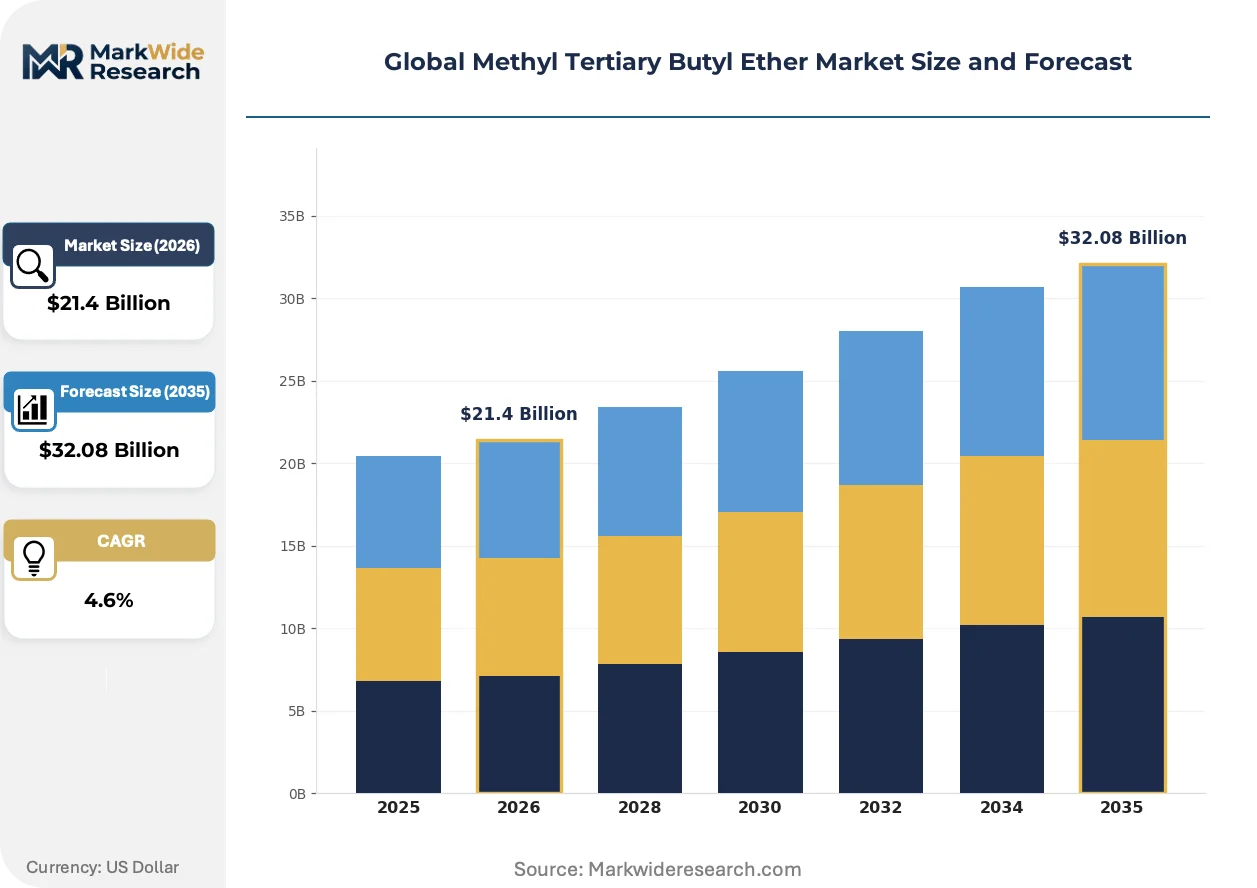
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $32.08 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuel Additive, Solvent, Octane Booster, Chemical Intermediate Grade: Industrial Grade, Reagent Grade, Technical Grade, Purified Grade Application: Petroleum Refining, Chemical Synthesis, Pharmaceutical Manufacturing, Agrochemical Production End Use Industry: Fuel Retailers, Chemical Manufacturers, Pharmaceutical Firms, Agrochemical Suppliers |
| Companies Covered | SABIC, LyondellBasell Industries Holdings B.V., Evonik Industries AG, China Petrochemical Corporation, China National Petroleum Corporation, Reliance Industries Limited, Eni, QAFAC, Huntsman International LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Methyl Tertiary Butyl Ether Market Shifts & Advancements
Process intensification and regulatory carbon accounting are converging to redefine competitive advantage around feedstock provenance rather than scale alone. Technology providers are repositioning around modular reactor designs.
Reactive distillation technology is unifying methanol-isobutylene conversion and product separation into single-unit operations, eliminating intermediate storage and reducing energy intensity by 20-30%. Saudi Aramco and Sinopec are deploying these systems at greenfield sites. The capital efficiency compression is enabling smaller-scale producers to achieve parity with world-scale trains.
China's MEE enforcement of dual carbon goals is tightening refinery emission ceilings and altering methanol sourcing economics for domestic MTBE producers. Coal-to-methanol pathways face mounting carbon intensity penalties, pressuring integrated refiners toward natural gas-based or imported methanol. Coastal provinces are responding with stricter carbon accounting for fuel additive supply chains.
Fuel retailers in Indonesia and Vietnam are consolidating procurement around long-term oxygenate supply contracts with fixed-price methanol pass-through mechanisms. Spot market participation is contracting as national oil companies seek inventory certainty ahead of specification transitions. The contract structure shift is most visible in Jakarta and Ho Chi Minh City terminal operations.
Global Methyl Tertiary Butyl Ether Market Segmentation
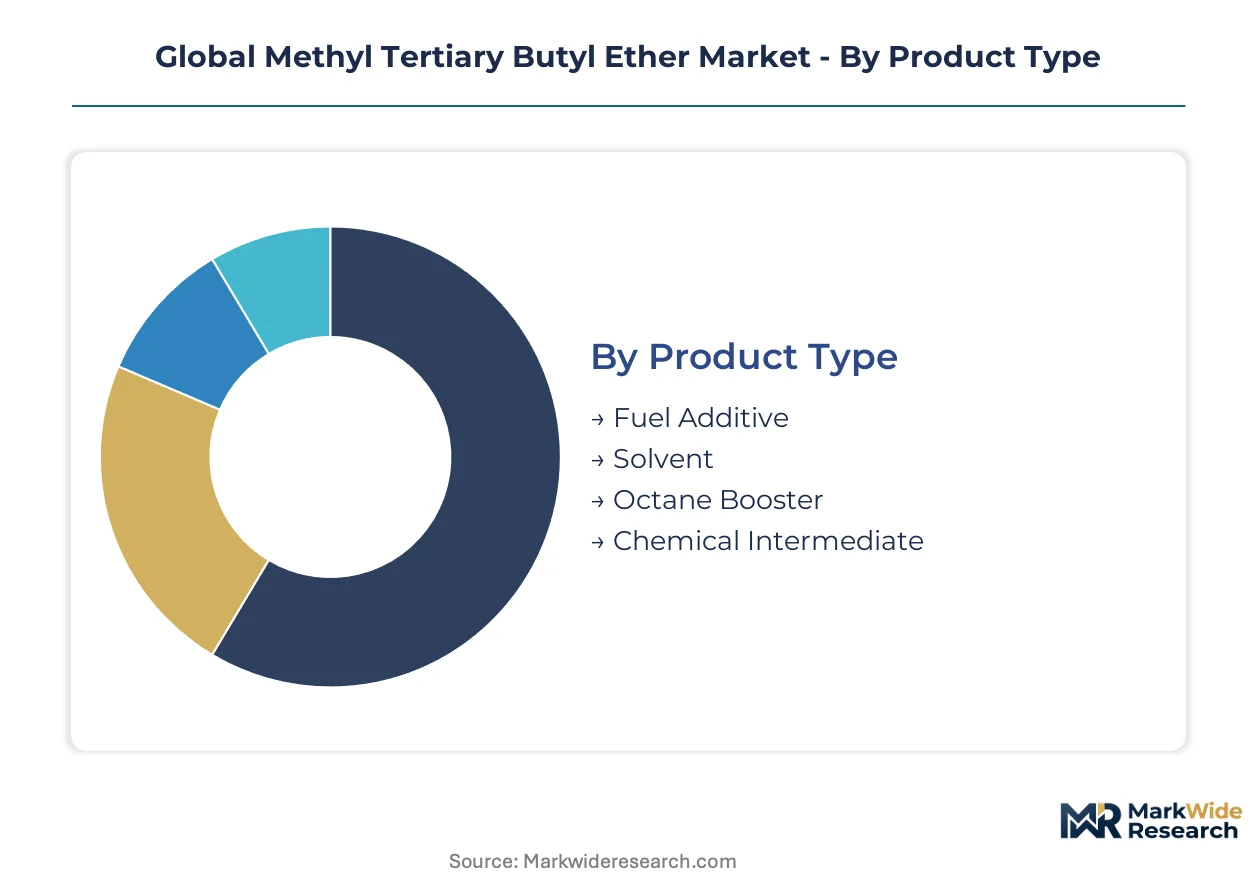
MTBE market segmentation reveals divergent compliance burdens across product tiers. Fuel additive volumes dominate absolute consumption, while chemical intermediate grades command stricter purity certifications and premium positioning.
Product Type:
Certification requirements split sharply across product types. Fuel additive volumes face EPA and CARB volatility specifications, while chemical intermediates must satisfy REACH dossier completeness for European export eligibility.
- Fuel Additive:Comprises minimum 98.5% purity ether blended into gasoline at 10-15% volume to elevate octane ratings and reduce carbon monoxide emissions. Demand concentrates in Indonesia and Vietnam as Pertamina and state retailers phase out leaded fuel across archipelago distribution networks constrained by Euro 4 oxygenate mandates.
- Chemical Intermediate:Serves as feedstock for methyl methacrylate and butyl rubber production with sub-ppm sulfur specifications required for pharmaceutical-grade downstream applications. MMA producers in China and Saudi Arabia are expanding offtake contracts for this segment as acrylic demand outpaces regional polymer capacity.
- Solvent:Functions in extraction and coating applications with moderate purity tolerances.
- Octane Booster:Addresses seasonal gasoline volatility adjustments in warm-climate formulations.
Fuel additive sits at the top of the volume ranking, with chemical intermediate climbing the fastest.
Grade:
Cost tier stratification separates commodity industrial supply from premium reagent positioning. Industrial grade competes on methanol pass-through economics, while reagent grade absorbs 15-25% premia for pharmaceutical certification compliance.
- Industrial Grade:Standard 98.5% minimum purity material for fuel blending and bulk chemical applications. Refinery-integrated producers in Saudi Arabia's refining corridor leverage captive isobutylene access to sustain margin advantages against merchant suppliers facing propylene feedstock scarcity.
- Reagent Grade:Sub-ppm sulfur and ultra-low moisture specifications required for pharmaceutical manufacturing and analytical applications. European importers must maintain full REACH dossier compliance to sustain access, filtering speculative traders from this premium tier.
- Technical Grade:Intermediate purity band for agrochemical and coating applications.
- Purified Grade:Enhanced specifications for electronics and specialty polymer feedstock.
Industrial grade commands the largest volume position, with reagent grade expanding most quickly on pharmaceutical outsourcing trends.
Application:
Application segmentation tracks divergent margin structures across process industries. Petroleum refining absorbs commodity pricing, while pharmaceutical manufacturing imposes batch certification burdens that sustain supplier stickiness.
- Petroleum Refining:Gasoline blending operations at Nghi Son and Long Son complexes in Vietnam. Indonesia's Pertamina is expanding storage infrastructure ahead of oxygenated gasoline mandates across 17,000-island distribution networks.
- Chemical Synthesis:MMA and butyl rubber production with purity specifications commanding supply contract premiums.
- Pharmaceutical Manufacturing:Solvent and extraction applications requiring sub-ppm contaminant thresholds.
- Agrochemical Production:Intermediate applications with moderate purity tolerances and seasonal demand patterns.
Petroleum refining dominates absolute consumption, with chemical synthesis gaining share fastest on polymer capacity expansion.
End Use Industry:
Customer type determines procurement structure and contract duration. National oil companies consolidate around long-term supply agreements, while pharmaceutical firms enforce audit-intensive supplier qualification.
- Fuel Retailers:State-owned Pertamina and Vietnam's national oil company are consolidating procurement around fixed-price methanol pass-through contracts. Spot market participation is contracting as inventory certainty takes priority ahead of specification transitions in Jakarta and Ho Chi Minh City terminals.
- Chemical Manufacturers:Integrated MMA and rubber producers with backward integration into refinery-grade propylene streams.
- Pharmaceutical Firms:Sub-ppm sulfur requirements with batch certification and supplier audit obligations.
- Agrochemical Suppliers:Seasonal offtake patterns with moderate purity specifications.
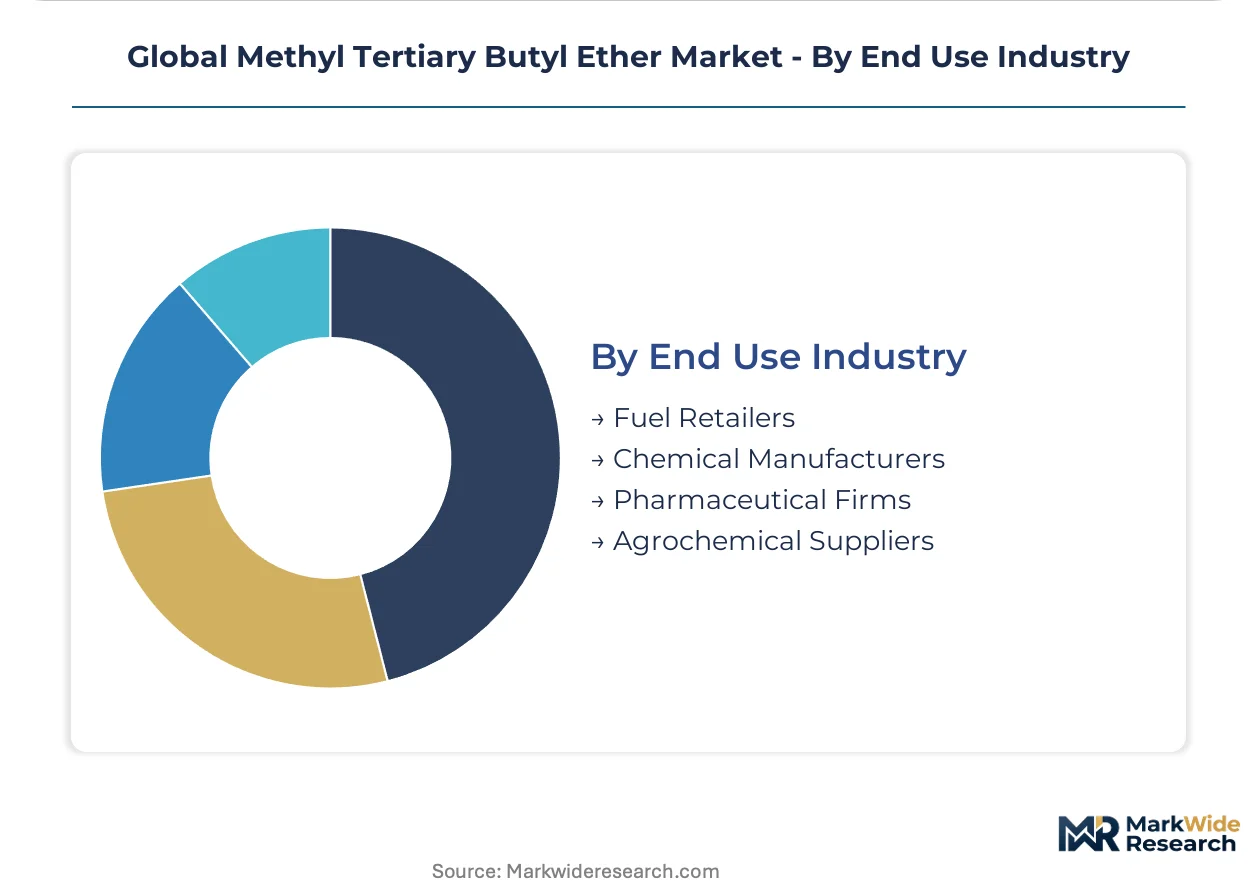
Fuel retailers anchor the volume base, with chemical manufacturers showing the steepest expansion trajectory on downstream polymer demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized refinery chemists and process engineers concentrate in coastal industrial corridors where oxygenate blending infrastructure meets expanding gasoline demand. Their expertise anchors production economics across jurisdictions with diverging carbon accounting rules.
China
Coastal refiners in Shandong and Jiangsu provinces are retrofitting catalytic cracking units to expand isobutylene yields for captive MTBE production. The MEE enforces dual carbon goals that tighten emission ceilings and favor natural gas-based methanol over coal-derived feedstock. The Yangtze River Delta cluster around Ningbo and Shanghai hosts integrated operations where state oil majors consolidate fuel additive supply.
Saudi Arabia
The Eastern Province refining corridor leverages abundant propane dehydrogenation capacity to sustain margin advantages in purified grade ether supply. SFDA chemical registration protocols align with EU REACH dossier requirements for pharmaceutical-grade export eligibility. Jubail Industrial City anchors world-scale production trains with reactive distillation technology deployment.
United States
Gulf Coast refiners optimize fluid catalytic cracking toward lighter olefin output, expanding captive isobutylene for integrated oxygenate production. EPA Renewable Fuel Standard volume obligations cap MTBE's addressable gasoline pool against ethanol substitution mandates. The Houston Ship Channel corridor maintains storage and blending infrastructure for seasonal volatility adjustments.
Indonesia
Pertamina is expanding refinery capacity at Cilacap and Balikpapan to meet Euro 4 gasoline specifications across the archipelago's 17,000-island distribution network. The national oil company consolidates procurement around long-term oxygenate contracts with fixed-price methanol pass-through mechanisms. Jakarta and Surabaya terminals are accelerating storage infrastructure builds ahead of mandate deadlines.
Germany
Specialty chemical producers in the Rhine-Ruhr and Ludwigshafen clusters maintain REACH-registered import channels for pharmaceutical-grade ether supply. ECHA substance evaluation protocols filter speculative traders from the value chain, consolidating European supply around full dossier compliance. The country's central position enables distribution arbitrage between Atlantic and Mediterranean fuel blending terminals.
Global Methyl Tertiary Butyl Ether Market Competitive Landscape
The competitive structure tilts toward refinery-integrated petrochemical conglomerates with captive olefin feedstock access. Three to five integrated national oil companies anchor volume positions while specialty chemical houses occupy premium tiers. Merchant producers without backward integration face margin compression from propylene scarcity. Dominant competitive moves include reactive distillation technology licensing and long-term methanol offtake contracting.
Within the integrated petrochemical tier, SABIC and China Petrochemical Corporation exemplify scale-driven positioning through refining corridor concentration. LyondellBasell Industries Holdings B.V. occupies a position among Western operators with backward integration into propylene streams. These three entities represent divergent geographic archetypes: Gulf-based feedstock abundance, Chinese domestic market dominance, and US Gulf Coast operational scale.
| Leading Market Players |
|---|
| SABIC |
| LyondellBasell Industries Holdings B.V. |
| Evonik Industries AG |
| China Petrochemical Corporation |
| China National Petroleum Corporation |
| Reliance Industries Limited |
| Eni |
| QAFAC |
| Huntsman International LLC |
| Others |
Supply & Pricing Matrix
Methanol contract structures transmit cost volatility from Chinese coal-to-chemicals corridors through to fuel additive pricing tiers downstream. Long-term offtake agreements with fixed-price pass-through mechanisms now dominate procurement between Southeast Asian fuel retailers and integrated producers.
Pricing Analysis
Bundled methanol-isobutylene supply contracts compete against unbundled spot market sourcing for merchant MTBE producers. Three-tier pricing structure across reagent, industrial, and fuel grades reflects certification burden and purity thresholds. Pricing pressure stems from refinery-grade propylene scarcity squeezing non-integrated margins. Fuel retailers show highest price sensitivity due to volume scale and specification mandate deadlines, while pharmaceutical manufacturers absorb premia for sub-ppm sulfur certification.
Supply Chain Analysis
Indonesia's domestic-content requirements for refinery expansion projects are reshaping sourcing patterns for oxygenate infrastructure. Supply concentrates in Saudi Arabia's Eastern Province, China's Shandong-Jiangsu corridor, and the US Gulf Coast. Feedstock dependencies center on isobutylene from fluid catalytic cracking, methanol from coal and natural gas pathways, and refinery-grade propylene for non-integrated producers. Single-source vulnerability runs through methanol supply contracted from Chinese coal-to-chemicals complexes. Distribution runs through coastal terminal storage and barge networks serving archipelago fuel retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The MTBE market functions as a stable compounder anchored by Indonesia and Vietnam's leaded fuel phase-out timelines driving oxygenate mandate compliance.
For Market Incumbents: To counter ethanol substitution mandates in Western Hemisphere markets, deepen backward integration into captive isobutylene supply via refinery FCC optimization and secure long-term methanol offtake contracts with fixed-price mechanisms. Lock in terminal storage partnerships across Jakarta and Ho Chi Minh City ahead of specification transition deadlines. For New Entrants and Emerging Players: Specialty chemical manufacturers seeking pharmaceutical-grade ether supply represent an underserved buyer archetype with 15-25% pricing premia and lower volume concentration risk. Target REACH-registered import channels in the Rhine-Ruhr cluster and Jubail Industrial City's SFDA-aligned export corridors. Lead with reactive distillation technology licensing to achieve capital efficiency parity with world-scale trains. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale merchant producers facing propylene feedstock scarcity because distressed asset valuations and tolling arrangement demand create consolidation leverage. Focus on five-to-ten year viability windows for integrated refining corridor positions. Watch carbon intensity accounting rules under EU Green Deal delegated acts as the signal for preferential sourcing advantage shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isobutylene Supply | Captive FCC yields anchor margin structures against propylene scarcity pressure. |
| Long-term Methanol Offtake Contracting | Fixed-price pass-through mechanisms shield against Chinese coal-to-chemicals volatility. |
| Reactive Distillation Technology Deployment | Saudi Aramco and Sinopec deployments demonstrate 20-30% energy intensity reduction. |
| REACH Dossier Compliance Investment | ECHA substance evaluation protocols filter speculative traders from premium grade access. |
| Terminal Storage Infrastructure Expansion | Pertamina's Cilacap and Balikpapan builds secure inventory certainty for mandate deadlines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining discussions with refinery operations managers, fuel retailer procurement leads, specialty chemical technical directors, and ECHA regulatory affairs specialists with secondary validation from customs trade data, SEC petrochemical filings, and MEE emission policy documents. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic anchors across the analysis window.
Comparable-period anchoring tied projection horizons to historical refinery utilization rates and oxygenate blending mandate implementation timelines. Segmentation modeling spanned product type, grade tier, end-use industry, and regional production hub dimensions. CAGRs derived from volume-demand elasticity curves and methanol-isobutylene feedstock cost dynamics, with specific inputs from FCC yield optimization trends and dual carbon goal enforcement intensity in coastal Chinese provinces.
Underlying measurement precision varies by segment; fuel additive volumes carry tighter precision than emerging chemical intermediate applications due to established customs reporting. Forecasts reflect assumptions around mandate implementation schedules and methanol sourcing economics. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petrochemicals
Malaysia Chemical and Petrochemical Market
Petrochemicals
Propane Market
Petrochemicals
Alkylate Isooctane Market
Petrochemicals
Synthetic and Biobased Butadiene Market
Petrochemicals
Olefin Derivatives Market
Petrochemicals
Flame-Retardant Polypropylene (PP) Market
Petrochemicals
Propylene Carbonate Market
Petrochemicals
Fossil Fuel-Based Plastics Market
Petrochemicals
Chemical and Petroleum Containers Market
Petrochemicals
Basic Petrochemical Market
Petrochemicals
Petrochemicals Market
Petrochemicals
Bio Butadiene Market
Petrochemicals
Petrochemical Feedstock Market
Petrochemicals
Military Propellants Market
Petrochemicals
Tert Butyl Hydroperoxide Market
Petrochemicals
Global Butadiene Market