
 Synthetic and Biobased Butadiene Market | 2026-2036
Synthetic and Biobased Butadiene Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic and Biobased Butadiene Market Analytics
Automotive tire demand is realigning toward sustainable elastomer feedstocks as OEMs enforce Scope 3 emissions targets. BASF SE leverages integrated C4 cracking complexes in Antwerp to sustain cost-advantaged naphtha-derived butadiene output. LG Chem anchors Asia-Pacific supply through dedicated on-purpose butadiene units tied to steam cracker expansions. Synthos competes on specialty rubber grades, while ZEON CORPORATION dominates solution-polymerized styrene-butadiene rubber channels for high-performance tire segments.
Synthetic and biobased butadiene denotes C4 hydrocarbon monomer produced via naphtha steam cracking, ethanol dehydration, or microbial fermentation of biomass sugars, with purity specifications typically exceeding 99.5 percent for polymerization-grade material. The substance serves primarily as a feedstock for emulsion and solution SBR, polybutadiene rubber, and acrylonitrile-butadiene-styrene resins. Chemical synthesis still occupies the largest production method share, though fermentation pathways attract capital as sugar-derived routes achieve cost parity in select geographies. Rubber manufacturing commands the dominant application position, while plastic production registers the fastest structural expansion driven by ABS demand in electronics housings. Automotive end users concentrate procurement volumes, yet electronics is displacing consumer goods as the second-ranked demand vertical.
EPA New Source Performance Standards constrain US Gulf Coast cracker emissions intensity, while EU REACH and the F-Gas Regulation progressively restrict fossil-derived feedstock eligibility in certified sustainable product categories. EMA frameworks for medical-grade elastomers and BIS polymer standards in India further fragment compliance requirements across export destinations. Stakeholders must monitor feedstock certification schemes and cracker decarbonization timelines to secure offtake contracts under shifting regulatory baselines.
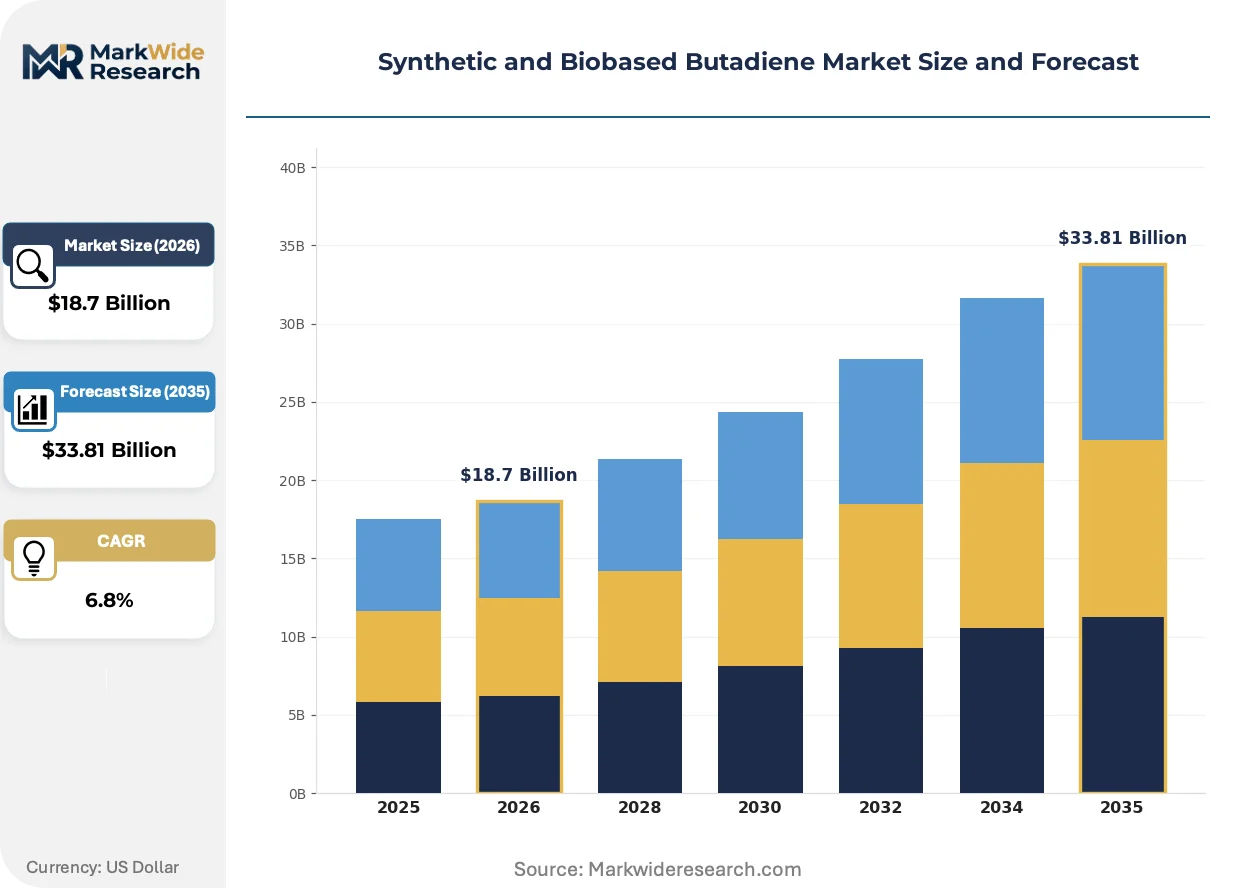
Market Dynamics
The Synthetic and Biobased Butadiene Market is experiencing structural realignment as EU REACH compliance tightens petrochemical pathways and tire manufacturers accelerate biobased feedstock procurement to meet automotive OEM Scope 3 emissions targets.
Growth Catalysts
- EU REACH Restrictions:Fossil-derived feedstock eligibility is narrowing under progressive F-Gas Regulation amendments, redirecting investment toward fermentation-based production pathways.
- Automotive OEM Mandates:Scope 3 emissions targets are forcing tire manufacturers to certify sustainable elastomer content, creating pull-through demand for biobased butadiene in high-performance tire segments.
- C4 Cracking Complex Expansion:Integrated refinery-petrochemical hubs in Antwerp and Rotterdam are achieving scale efficiencies that lower unit costs for polymerization-grade material.
Market Restraints
- Naphtha Price Volatility:Steam cracking economics remain tethered to crude oil fluctuations, compressing margins for conventional butadiene producers during feedstock cost spikes.
- Supply Concentration Risk:Production gravity centers on Germany's Rhine-Ruhr corridor and the US Gulf Coast, creating vulnerability to regional logistics disruptions or extreme weather events.
- Fermentation Yield Limitations:Microbial sugar-to-butadiene conversion rates lag theoretical maxima, constraining batch throughput and capital efficiency relative to petrochemical routes.
Strategic Opportunities
- India BIS Certification Gap:Domestic polymer standards for ABS and synthetic rubber are tightening, creating first-mover advantage for certified biobased suppliers entering this underpenetrated market.
- Electronics Housing Demand:ABS resin consumption for laptop and smartphone chassis is accelerating faster than automotive applications, offering volume diversification beyond tire manufacturing.
- US IRA Clean Chemistry Incentives:Tax credits for bio-based chemical production are improving project economics for fermentation pathway investments in the US Midwest corn belt.
Industry Challenges
- Bioprocess Engineering Talent Scarcity:Industrial microbiology and metabolic pathway optimization expertise concentrates in academic and startup ecosystems, limiting scale-up velocity for commercial fermentation facilities.
- Multi-Standard Certification Complexity:EMA medical-grade elastomer frameworks, BIS polymer standards, and EU REACH sustainable product categories impose overlapping compliance timelines that extend customer qualification periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic and Biobased Butadiene Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Production Method: Chemical Synthesis, Fermentation, Catalytic Cracking, Pyrolysis Application: Rubber Manufacturing, Plastic Production, Coatings, Adhesives End User: Automotive, Consumer Goods, Construction, Electronics Form: Liquid, Gas, Solid, Concentrate |
| Companies Covered | Versalis S.p.A., LANXESS, ZEON CORPORATION, Synthos, SABIC, BASF SE, LyondellBasell Industries, LG Chem, ARLANXEO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic and Biobased Butadiene Market Evolving Landscape
Fermentation pathway technologies are maturing from pilot to commercial scale, while regulatory frameworks fragment across jurisdictions and procurement models evolve toward certified sustainable supply chains.
Microbial fermentation of biomass sugars is consolidating as the dominant alternative production method, achieving cost parity with naphtha-derived routes in select geographies. Specialty chemical producers are retrofitting existing ethanol dehydration infrastructure to handle mixed sugar feedstocks. This technology compression is enabling smaller-scale distributed production models that reduce logistics exposure to concentrated petrochemical hubs.
EU F-Gas Regulation amendments are progressively restricting fossil-derived feedstock eligibility in certified sustainable product categories. Chemical manufacturers must now document carbon intensity across Scope 1, 2, and 3 emissions to maintain polymer-grade certification. Tire and ABS producers serving European automotive OEMs are responding by inserting biobased content mandates into long-term offtake contracts.
Automotive OEMs are unbundling elastomer procurement from tire supplier agreements to directly certify feedstock sustainability credentials. Tier-1 manufacturers must now present blockchain-traceable documentation for butadiene origin and processing emissions. This disintermediation is most visible in Germany, where LANXESS and Continental have established dedicated sustainable material procurement offices.
Synthetic and Biobased Butadiene Market Segmentation
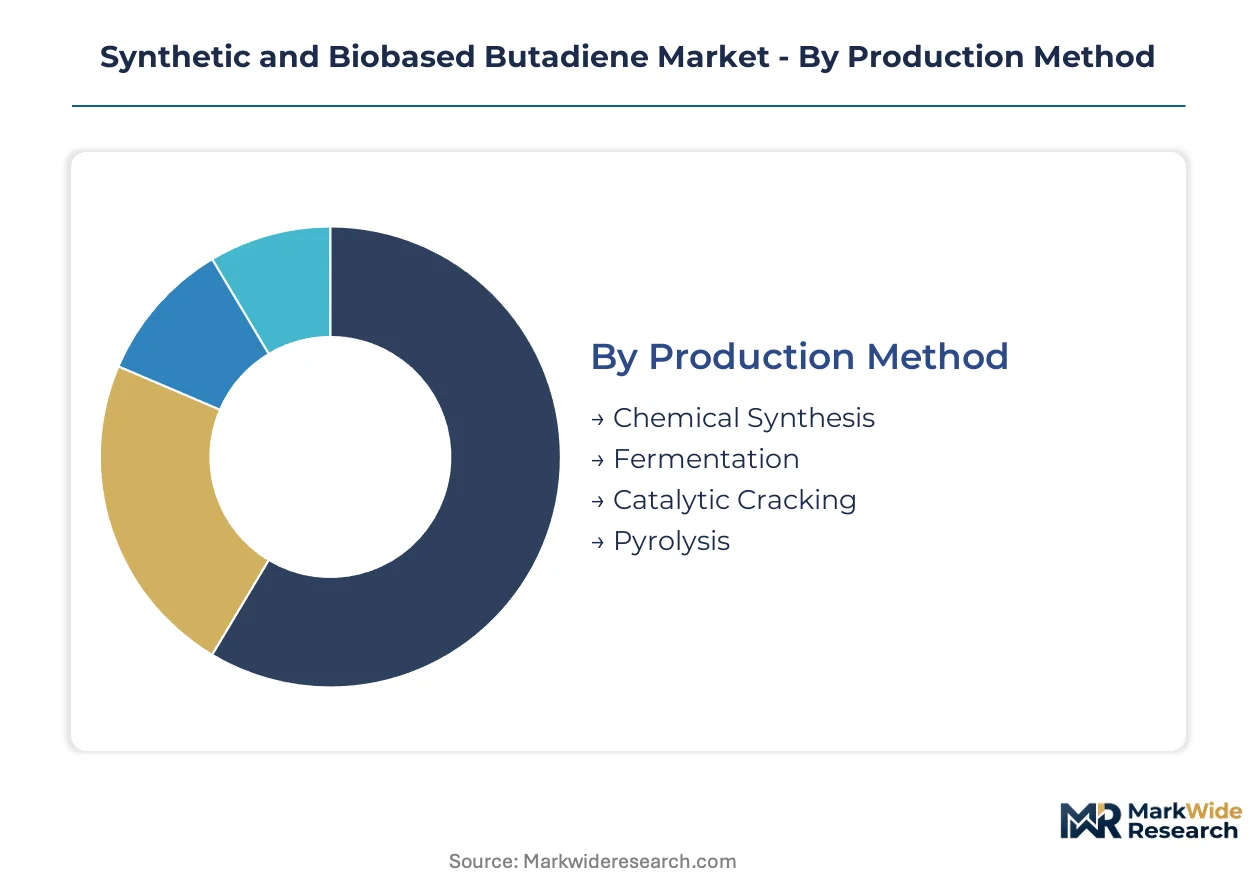
Butadiene procurement decisions hinge on production method certification, application-specific purity grades, and end-user Scope 3 compliance requirements. Each segmentation axis carries distinct margin profiles and regulatory exposure that reshape supplier qualification timelines.
Production Method:
Technology selection determines carbon intensity documentation, feedstock flexibility, and capital recovery periods for new capacity installations.
- Chemical Synthesis:Naphtha steam cracking produces polymerization-grade butadiene exceeding 99.5% purity through C4 fraction separation. BASF SE's Antwerp complex and LG Chem's Korean facilities anchor global supply, though EU REACH tightening constrains long-term feedstock eligibility for certified sustainable product categories.
- Fermentation:Microbial conversion of biomass sugars achieves cost parity with petrochemical routes in select geographies. Sugar beet processing regions in Germany and corn belt locations in the US Midwest attract capital as IRA clean chemistry incentives improve project economics, yet batch throughput limitations persist relative to continuous cracking operations.
- Catalytic Cracking:Fluid catalytic cracker off-gas recovery yields mixed C4 streams requiring downstream purification.
- Pyrolysis:Thermal decomposition of waste rubber or plastic feedstocks generates circular butadiene with emerging certification under EU waste framework directives.
Mature deployment sits with Chemical Synthesis. Newer deployment is concentrated in Fermentation.
Application:
Volume concentration and margin capture diverge sharply between commodity elastomer feedstocks and specialty resin grades.
- Rubber Manufacturing:Emulsion and solution SBR, polybutadiene rubber, and nitrile rubber consume the dominant share of polymerization-grade output. Tire manufacturers in Germany enforce biobased content mandates through direct procurement offices, disintermediating traditional supplier relationships.
- Plastic Production:Acrylonitrile-butadiene-styrene resins for electronics housings are climbing the fastest, driven by laptop and smartphone chassis demand outpacing automotive applications. ABS specifications require precise butadiene content control to achieve impact resistance and surface finish targets.
- Coatings:Hydroxyl-terminated polybutadiene and other derivatives serve marine and industrial protective applications.
- Adhesives:Styrene-butadiene latex formulations bind pressure-sensitive tapes and construction-grade bonding agents.
Steepest expansion trajectory belongs to Plastic Production. Volume concentration remains with Rubber Manufacturing.
End User:
Procurement power and sustainability certification requirements vary dramatically across customer categories.
- Automotive:OEM Scope 3 emissions targets force tier-1 suppliers to present blockchain-traceable feedstock documentation. LANXESS and Continental have established dedicated sustainable material procurement offices in Germany to manage this disintermediation.
- Electronics:ABS resin consumption for device housings is displacing Consumer Goods as the second-ranked demand vertical, with brand owners inserting biobased content requirements into mold supplier contracts.
- Consumer Goods:Footwear, sporting equipment, and household products utilize SBR and polybutadiene for elasticity and durability.
- Construction:Waterproofing membranes, sealants, and flooring applications consume emulsion SBR and modified bitumen additives.
Certification complexity concentrates in Automotive. Fastest volume build is occurring in Electronics.
Form:
Physical state dictates storage infrastructure, transport economics, and downstream handling requirements.
- Liquid:Polymerization-grade butadiene ships in refrigerated tankers or pressurized railcars for rubber and plastics manufacturing. Antwerp and Rotterdam hubs achieve scale efficiencies through integrated storage and distribution terminals.
- Gas:C4 cracking off-gas requires compression and purification before polymer-grade recovery.
- Solid:Polybutadiene rubber bales and compounded masterbatches arrive at tire and industrial goods plants for direct processing.
- Concentrate:High-purity monomer solutions for laboratory and specialty polymer research applications command premium pricing.
Commercial scale concentrates in Liquid. Niche premium capture sits with Concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters concentrate in Germany and the US Gulf Coast, while consumption spreads across automotive manufacturing belts in Asia-Pacific and Continental Europe. This geographic mismatch creates arbitrage opportunities for integrated suppliers with multi-regional logistics networks.
Germany
Automotive OEMs in Stuttgart and Munich enforce Scope 3 emissions targets through direct elastomer procurement offices. EU REACH and F-Gas Regulation amendments progressively restrict fossil-derived feedstock eligibility, redirecting investment toward fermentation pathways. The Rhine-Ruhr corridor anchors production with LANXESS and ARLANXEO facilities serving Continental tire manufacturers.
United States
EPA New Source Performance Standards constrain Gulf Coast cracker emissions intensity, while IRA clean chemistry tax credits improve bioprocess project economics in the Midwest corn belt. ABS resin demand from electronics brands accelerates faster than automotive applications. Houston and Baton Rouge maintain integrated C4 cracking complexes with scale advantages in polymerization-grade output.
China
Dual carbon goals under MIIT guidance pressure naphtha-based producers to document carbon intensity across Scope 1-3 emissions. Electronics housing manufacturers in the Yangtze River Delta consume expanding ABS volumes for laptop and smartphone chassis. Sinopec and private steam cracker operators in Zhejiang and Jiangsu provinces dominate domestic supply.
South Korea
LG Chem anchors Asia-Pacific supply through dedicated on-purpose butadiene units tied to Yeosu and Daesan steam cracker expansions. KBA vehicle certification standards and OEM sustainability mandates create pull-through demand for certified low-carbon elastomers. The Busan-Ulsan industrial corridor concentrates petrochemical integration with export-oriented rubber and plastics output.
India
BIS polymer standards for ABS and synthetic rubber tighten compliance requirements for imported material, creating first-mover advantage for certified biobased suppliers. Automotive manufacturing clusters in Maharashtra and Tamil Nadu expand tire production capacity for domestic and export markets. The PLI scheme for chemicals and petrochemicals incentivizes domestic butadiene derivative manufacturing.
Synthetic and Biobased Butadiene Market Competitive Landscape
Top-tier vendors anchor integrated petrochemical complexes with captive C4 cracking capacity, while mid-scale fermentation specialists and regional distributors compete on certification agility and specialty grades. Market structure tilts toward consolidation among naphtha-based producers with refinery integration, though bioprocess entrants fragment the sustainable segment. Three archetypes dominate: integrated petrochemical majors with backward control over feedstock, fermentation technology licensors with distributed production models, and specialty rubber compounders with formulation expertise. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with players securing long-term offtake contracts under shifting regulatory baselines.
Within the integrated petrochemical tier, BASF SE and LG Chem exemplify scale-driven positioning through Antwerp and Korean cracking complexes. Synthos occupies a position among specialty rubber compounders competing on emulsion and solution SBR grades for high-performance tire segments. These three anchors represent divergent strategic postures: European regulatory compliance leadership, Asia-Pacific volume scale, and specialty formulation differentiation.
| Leading Market Players |
|---|
| Versalis S.p.A. |
| LANXESS |
| ZEON CORPORATION |
| Synthos |
| SABIC |
| BASF SE |
| LyondellBasell Industries |
| LG Chem |
| ARLANXEO |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between EU REACH-compliant biobased butadiene and conventional naphtha-derived material manifests in divergent pricing structures and supply chain architectures. Premium-tier fermentation pathways command valuation multiples tied to carbon intensity documentation, while commodity chemical synthesis routes compete on scale economies through integrated Antwerp and Rotterdam hub-and-spoke distribution.
Pricing Analysis
Short lead-time premiums for polymerization-grade material with blockchain-traceable sustainability credentials separate contract-based long-term offtake agreements from spot market transactions. Price differentiation hinges on certification tier under EU REACH and carbon intensity grade, with volume scale discounts compressing margins for standard naphtha-derived supply. Cost compression in commodity chemical synthesis is intensifying because naphtha price volatility erodes cracking economics. Tire manufacturers serving German automotive OEMs exhibit lowest price sensitivity due to Scope 3 compliance mandates, while Asian ABS resin compounders remain most responsive to per-unit transactional shifts.
Supply Chain Analysis
Freight costs for refrigerated liquid butadiene tankers from Rotterdam to Asia-Pacific electronics manufacturing clusters add substantial landed cost premiums versus regional sourcing. Production concentrates in Germany, the United States, and South Korea, with raw material dependencies spanning naphtha feedstock, biomass sugars, and C4 cracking catalysts. Single-source vulnerability around German Rhine-Ruhr corridor facilities creates exposure to Rhine waterway logistics disruptions. Distribution runs through integrated petrochemical terminals at Antwerp, Houston, and Yeosu serving downstream rubber compounding and ABS resin polymerization plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where EU REACH tightening and automotive OEM Scope 3 mandates force sub-scale fermentation operators and undifferentiated naphtha crackers toward exit or acquisition.
For Market Incumbents: Extend backward integration into biomass sugar supply through dedicated offtake agreements with German sugar beet processors and US Midwest corn belt cooperatives. BASF SE and LG Chem should accelerate capacity addition in certified low-carbon production corridors before BIS standards harden import eligibility for Indian market access. Certification investment in blockchain-traceable carbon accounting systems defends position against specialty fermentation entrants targeting premium tire segments. For New Entrants and Emerging Players: Tire manufacturer procurement offices in Stuttgart and Munich present the most penetrable channel partner type for biobased butadiene qualification. Underpenetrated Indian ABS resin compounders facing BIS polymer standard tightening offer white-space volume build. Electronics housing manufacturers in China's Yangtze River Delta provide alternative demand verticals beyond automotive elastomers. Go-to-market execution should center on direct technical sales to tier-1 rubber compounders with sustainability mandates embedded in OEM supply agreements. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated petrochemical majors seeking fermentation technology stacks and certified production capacity. Five-to-ten year viability favors operators with demonstrated cost parity in sugar-derived routes and established offtake contracts under EU REACH frameworks. Target acquisition archetypes include mid-scale fermentation specialists with German or US Midwest production assets and validated microbial strain IP. Watch for inflection where IRA clean chemistry tax credits trigger Midwest corn belt project financing acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biomass Feedstock | Captive sugar supply from German beet processors secures fermentation pathway cost stability against commodity volatility. |
| Capacity Expansion in Certified Low-Carbon Corridors | Antwerp and Rotterdam hub additions capture EU REACH-compliant volume before competitor qualification cycles complete. |
| Long-term Supply Agreement with Automotive OEMs | Direct procurement office relationships with Continental and LANXESS lock in Scope 3 compliance-driven offtake. |
| Joint Venture with Fermentation Technology Licensor | Microbial strain IP partnerships accelerate yield improvements beyond theoretical batch throughput limitations. |
| Green Manufacturing Transition | Carbon intensity documentation across Scope 1-3 emissions preserves polymer-grade certification under F-Gas Regulation amendments. |
Research Methodology
Independent corroboration across executive interviews at tire manufacturers, procurement leads at automotive OEMs, technical directors at fermentation technology developers, and regulatory affairs specialists at chemical majors underwrites the qualitative findings. Secondary validation draws from EU REACH registration databases, US EPA New Source Performance Standards filings, Indian BIS polymer standard notifications, and SEC disclosures from listed petrochemical operators. Bottom-up capacity installation tracking and top-down elastomer demand modeling triangulate volume estimates across the analysis window.
Comparable-period anchoring to historical naphtha price cycles, steam cracker operating rates, and biobased chemical production cost curves shaped the projection horizon. Segmentation dimensions span production method technology tier, application purity grade, end-use industry vertical, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand functions incorporating automotive production forecasts and electronics housing unit growth. Industry-specific inputs include microbial conversion yield trajectories and EU F-Gas Regulation amendment implementation timelines.
Caveats apply where naphtha price volatility, fermentation batch throughput breakthroughs, or REACH scope expansions could materially shift the outlook. Forecasts reflect assumptions about regulatory enforcement intensity and OEM sustainability mandate adherence without guarantee of uniform implementation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petrochemicals
Global Methyl Tertiary Butyl Ether Market
Petrochemicals
Olefin Derivatives Market
Petrochemicals
Petrochemicals Market
Petrochemicals
Military Propellants Market
Petrochemicals
Bioisobutene Market
Petrochemicals
Bio Butadiene Market
Petrochemicals
Chemical and Petroleum Containers Market
Petrochemicals
Oman Pyrolysis Gasoline Market
Petrochemicals
Malaysia Chemical and Petrochemical Market
Petrochemicals
Flame-Retardant Polypropylene (PP) Market
Petrochemicals
Tert Butyl Hydroperoxide Market
Petrochemicals
Alkylate Isooctane Market
Petrochemicals
Pentane Market
Petrochemicals
Global Perfluorocarbons Market
Petrochemicals
Anthracene Oil Market
Petrochemicals
Propane Market