
 Olefin Derivatives Market | 2026-2036
Olefin Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Olefin Derivatives Market Outlook
Automotive OEMs is bifurcating from construction-grade buyers as the dominant demand archetype for high-performance polypropylene compounds. Dow Inc. leverages its Gulf Coast ethane cracking position to supply specialty-grade resins. SABIC anchors Middle Eastern feedstock cost advantages through integrated propane dehydrogenation complexes. INEOS specializes in European styrenics for automotive interior applications.
Olefin derivatives comprise organic compounds synthesized from ethylene, propylene, and butylene feedstocks through catalytic cracking, steam cracking, or metathesis processes, yielding polymers and intermediates with carbon-carbon double bond reactivity essential for polymerization. These materials serve as foundational inputs for plastics manufacturing, synthetic rubber production, and chemical intermediates across industrial value chains. Ethylene derivatives dominate volume flows through polyethylene and ethylene glycol pathways, while propylene derivatives capture expanding margin pools in automotive compounding and fiber applications. Styrene segments face mature demand curves in packaging but retain pricing power in specialty copolymers for consumer goods.
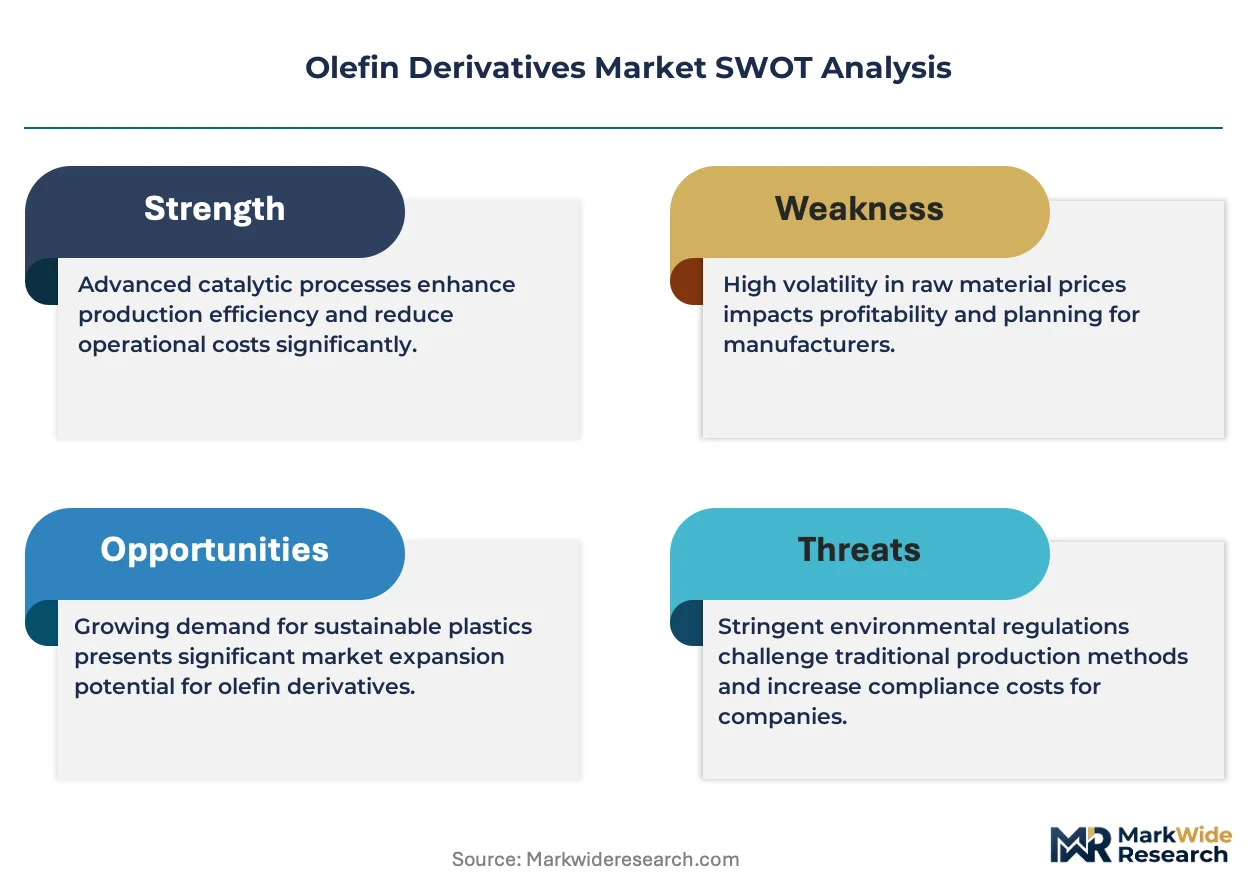
EPA emissions standards under the Clean Air Act constrain US refinery-based olefin production methods, while REACH registration requirements in Europe mandate toxicity documentation for derivative chemical substances. China's MEE enforces dual carbon goals that restrict coal-to-olefin capacity additions in inland provinces. Stakeholders must monitor feedstock cost spreads between ethane, naphtha, and propane routes to preserve margin structures.
Market Dynamics
Automotive lightweighting mandates are compressing demand cycles for high-performance polypropylene compounds while feedstock cost spreads between ethane and naphtha routes determine margin survival for derivative producers.
Growth Catalysts
- EPA emissions standards:The Clean Air Act constrains refinery-based olefin production, advantaging ethane crackers with lower carbon intensity and cleaner output profiles for derivative manufacturing.
- Propylene derivatives:Automotive OEMs consume expanding volumes of engineered polypropylene compounds for interior and under-hood applications requiring thermal stability and weight reduction.
- Ningbo and Dalian clusters:China's coastal petrochemical concentration enables integrated derivative production with direct port access for feedstock import and finished goods export.
Market Restraints
- Ethane-naphtha spread volatility:Feedstock cost advantages flip between regions based on natural gas liquids pricing versus crude-linked naphtha, destabilizing investment returns for new cracking capacity.
- Middle Eastern supply concentration:Integrated propane dehydrogenation complexes in Saudi Arabia and Qatar anchor global cost curves, limiting pricing power for higher-cost producers elsewhere.
- REACH registration friction:ECHA toxicity documentation requirements for derivative chemical substances extend commercialization timelines and raise compliance costs for European market entry.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for advanced chemicals manufacturing attract greenfield olefin derivative investments targeting domestic automotive and packaging growth.
- Metathesis process convergence:Integration of catalytic olefin metathesis with bio-based feedstocks enables renewable carbon pathways for specialty polymer intermediates.
- Direct OEM contracting:Automotive manufacturers bypass traditional distributor channels for engineered compound supply, capturing formulation customization and technical service value.
Industry Challenges
- Catalytic cracking expertise scarcity:Specialized process engineering talent for high-severity cracking operations concentrates with retiring workforce cohorts in established petrochemical regions.
- Dual carbon compliance timelines:China's MEE enforcement of provincial emissions caps accelerates facility retrofit requirements ahead of depreciated asset schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Olefin Derivatives Market |
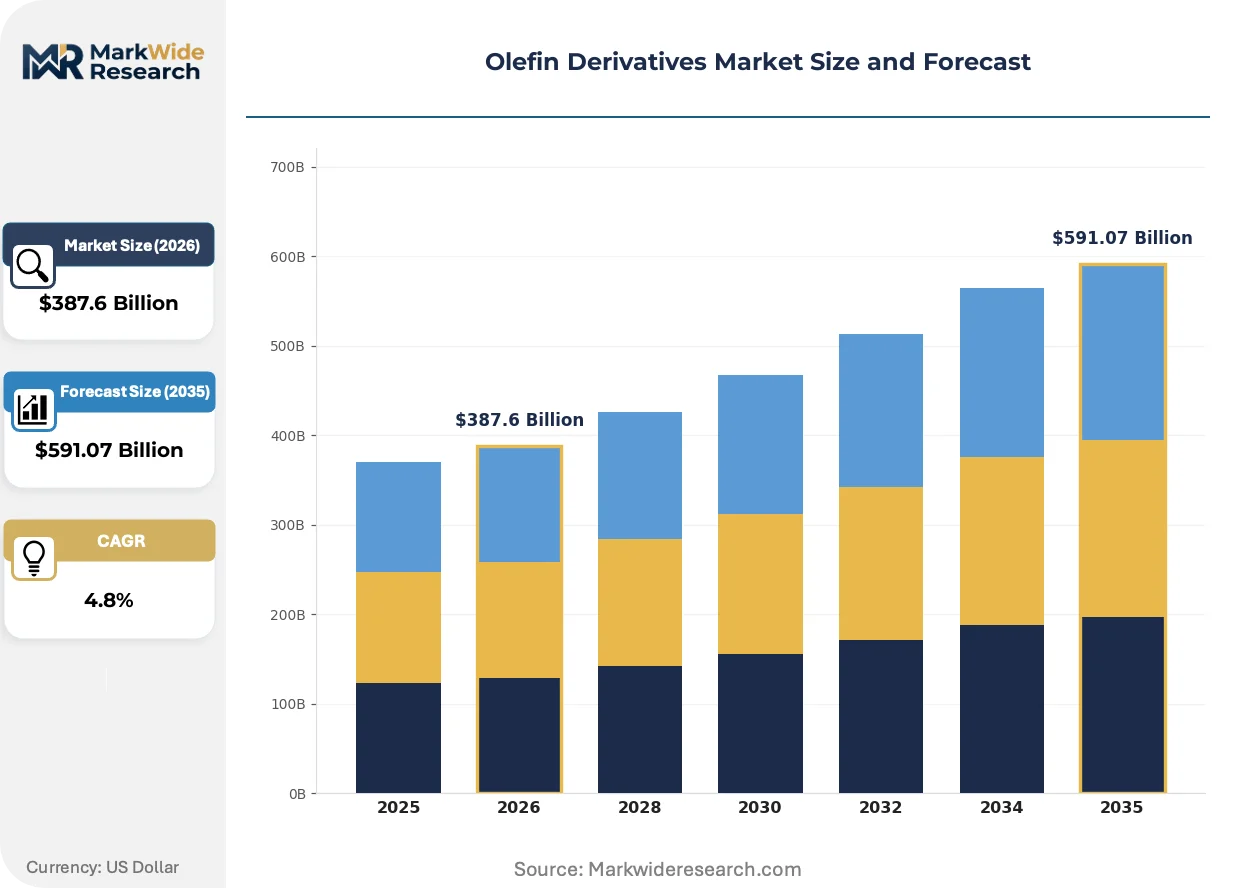
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $591.07 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethylene, Propylene, Butylene, Styrene Application: Plastics, Fibers, Adhesives, Coatings End Use Industry: Automotive, Construction, Consumer Goods, Textile Form: Granules, Pellets, Liquid, Powder |
| Companies Covered | ExxonMobil Corporation, SABIC, Shell, INEOS, LyondellBasell Industries Holdings B.V., Dow Inc., BASF SE, China National Petroleum, Chevron Phillips Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Olefin Derivatives Market Strategic Shifts
Process intensification and feedstock diversification are restructuring competitive economics for olefin derivative production, with technology adoption curves compressing as energy transition pressures mount.
Advanced metathesis catalysts are displacing conventional steam cracking for C4+ olefin interconversion, enabling on-purpose production of high-value linear alpha-olefins from mixed feedstock streams. Specialty chemical producers in the US Gulf Coast deploy these systems to bypass naphtha cracking constraints. The technology is displacing legacy disproportionation units while reducing energy intensity per ton of derivative output.
REACH authorization requirements under ECHA are tightening substance restrictions for styrenic derivatives used in consumer goods contact applications. European compounders face reformulation mandates for automotive interior grades previously reliant on legacy copolymer recipes. German and French automotive suppliers accelerate halogen-free flame retardant qualification programs to maintain CE marking compliance.
Automotive procurement teams now specify recycled content thresholds for polypropylene compounds, forcing compounders to secure post-industrial and post-consumer feedstock streams through qualified recycler networks. Tier-1 suppliers in Michigan and Stuttgart restructure supplier scorecards to weight circularity metrics alongside price and performance. This specification shift concentrates purchasing power with compounders possessing verified mass-balance certification chains.
Olefin Derivatives Market Segmentation
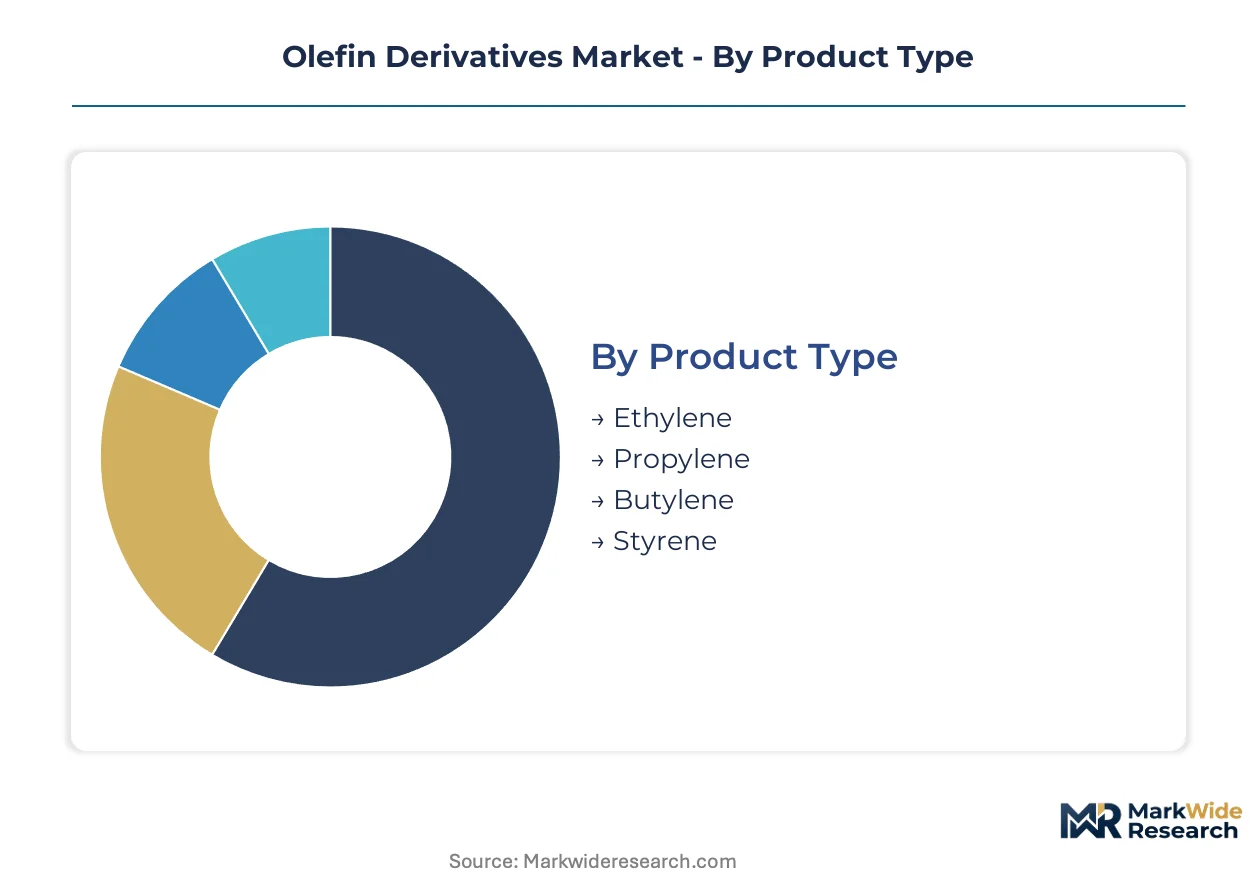
Margin capture in olefin derivatives hinges on feedstock specificity and formulation complexity. Producers optimize across molecular weight distributions, polymerization routes, and end-use certification tiers to defend pricing power.
Product Type:
Margin pools concentrate in propylene derivatives where automotive compounding commands formulation premiums over commodity polyethylene.
- Ethylene:Polyethylene resins and ethylene glycol intermediates constitute the highest-volume pathway. Naphtha crackers in South Korea and ethane crackers along the US Gulf Coast supply differentiated grades for packaging films and PET bottle applications.
- Propylene:On-purpose production via propane dehydrogenation yields polymer-grade material for engineered compounds. Automotive OEMs in Michigan and Baden-Württemberg specify high-crystallinity homopolymers for under-hood thermal management.
- Butylene:C4 fractionation produces butene-1 comonomers for linear low-density polyethylene and methyl tert-butyl ether precursors.
- Styrene:Ethylbenzene dehydrogenation yields monomer for polystyrene and ABS copolymers. REACH authorization constraints in Europe are compressing demand for general-purpose grades while specialty copolymers retain pricing power.
The dominant share belongs to ethylene derivatives, while propylene is closing the gap fastest through automotive lightweighting specifications.
Application:
Application-level profitability tracks certification intensity, with medical and food-contact grades capturing wider spreads than construction commodities.
- Plastics:Injection molding and extrusion grades span commodity polyethylene to high-performance polypropylene compounds. FDA-compliant formulations for food packaging and EPA-permitted agricultural films carry certification premiums over general-purpose resins.
- Fibers:Polypropylene staple and filament grades serve nonwoven medical textiles and geotextile reinforcement. MEE emissions enforcement in China is constraining coal-to-olefin based fiber precursors in inland provinces.
- Adhesives:Hot-melt formulations leverage ethylene-vinyl acetate copolymers for packaging assembly and woodworking applications.
- Coatings:Styrene-acrylic and styrene-butadiene emulsions provide barrier properties for architectural and industrial surface protection.
Plastics commands the volume base, though fibers is expanding most quickly through hygiene and filtration end-use proliferation.
End Use Industry:
Customer concentration patterns separate specification-intensive sectors from price-sensitive commodity buyers.
- Automotive:Interior and under-hood applications demand thermal stability, low VOC emissions, and recycled content verification. Tier-1 suppliers in Stuttgart and Detroit restructure procurement around mass-balance certification chains.
- Construction:Piping, geomembranes, and insulation materials prioritize durability over formulation complexity. Ningbo and Dalian petrochemical clusters supply standardized grades for infrastructure buildout.
- Consumer Goods:Food contact compliance and aesthetic surface finish drive copolymer selection for appliances and packaging.
- Textile:Nonwoven spunbond and meltblown fabrics for hygiene and filtration applications require narrow molecular weight distribution resins.
Automotive holds the premium position, with construction representing the steepest expansion trajectory through infrastructure investment cycles.
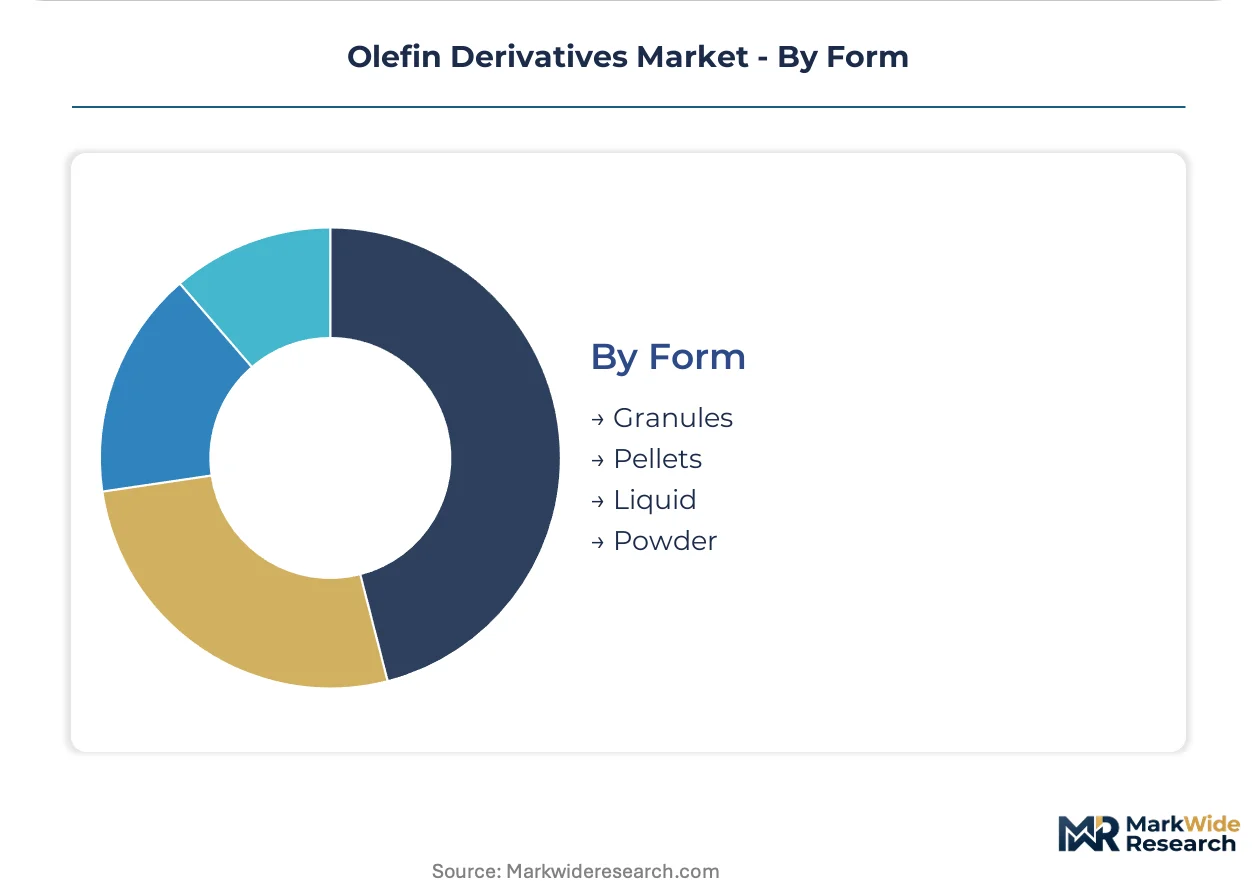
Form:
Physical delivery format determines logistics economics and compounding flexibility for downstream processors.
- Granules:Irregular particle morphology suits dry blending and masterbatch compounding operations. European compounders prefer granule form for multi-component formulations requiring precise additive distribution.
- Pellets:Uniform cylindrical shape enables pneumatic conveying and automated feeding in continuous extrusion lines. Gulf Coast resin producers ship pelletized grades through Houston port terminals to Latin American converters.
- Liquid:Butadiene and specialty monomers move via pressurized railcar and tanker vessel for synthetic rubber and adhesive polymerization.
- Powder:Fine particle size supports rotational molding and sintering processes for tank and playground equipment fabrication.
Pellets retains the dominant logistics share, while granules is gaining share fastest through compounding flexibility demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabian petrochemical exports flow predominantly to China's coastal manufacturing zones, with European automotive hubs and US Gulf Coast derivative producers serving as secondary demand anchors for specialized grades.
United States
Automotive OEMs in Michigan specify recycled-content polypropylene compounds for interior applications. EPA emissions standards under the Clean Air Act constrain refinery-based production, advantaging ethane crackers along the Gulf Coast. Houston port terminals serve as the primary export hub for pelletized grades bound for Latin American converters.
China
Packaging film manufacturers and automotive suppliers drive consumption of polyethylene and engineered polypropylene grades. MEE enforcement of dual carbon goals restricts coal-to-olefin capacity additions in inland provinces. Ningbo and Dalian petrochemical clusters enable integrated derivative production with direct port access for feedstock import.
Germany
Automotive Tier-1 suppliers in Baden-Württemberg restructure procurement around mass-balance certification chains for interior components. REACH authorization requirements under ECHA mandate toxicity documentation for styrenic derivatives used in consumer goods contact applications. BASF SE maintains integrated production complexes in Ludwigshafen serving European compounders.
Saudi Arabia
Integrated propane dehydrogenation complexes anchor global cost curves for polymer-grade propylene supply. SABIC leverages feedstock cost advantages through Jubail and Yanbu industrial cities. Export volumes concentrate on Asian automotive and packaging markets with long-term offtake agreements.
South Korea
Naphtha crackers in Yeosu and Ulsan supply differentiated polyethylene grades for electronics packaging and battery separator films. National emissions regulations accelerate facility retrofit requirements ahead of depreciated asset schedules. Daesan petrochemical complex serves as the primary hub for C4 fractionation and butene-1 comonomer production.
Olefin Derivatives Market Competitive Environment
Listed leaders compete with private specialists across feedstock integration depth, with publicly traded majors commanding capital markets access for cracking capacity expansion while private operators exploit regional feedstock arbitrage. Market structure consolidates around integrated petrochemical majors with captive olefin production, mid-scale regional compounders, and technology licensors. Three archetypes dominate: Gulf Coast ethane crackers, Middle Eastern PDH operators, and European specialty styrenics producers. Competitive moves center on backward integration into feedstock supply and geographic expansion through joint ventures in high-demand Asian markets.
Within the integrated major tier, ExxonMobil Corporation and SABIC occupy positions defined by scale and feedstock access respectively, while Dow Inc. exemplifies the Gulf Coast ethane cracking archetype. SABIC anchors Middle Eastern supply concentration through Jubail and Yanbu production bases. Dow Inc. represents the US-based model leveraging natural gas liquids cost advantages. INEOS sits within the European specialty vector focused on automotive interior applications.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| SABIC |
| Shell |
| INEOS |
| LyondellBasell Industries Holdings B.V. |
| Dow Inc. |
| BASF SE |
| China National Petroleum |
| Chevron Phillips Chemical Company |
| Others |
Value Chain & Pricing Dynamics
REACH authorization requirements under ECHA gate both supplier qualification and price differentiation simultaneously, forcing European compounders to absorb toxicity documentation costs that separate certified automotive interior grades from commodity construction resins. This regulatory screening concentrates pricing power with producers possessing pre-qualified substance portfolios while excluding marginal operators from premium tier access.
Pricing Analysis
Steam cracking technology commands baseline commodity pricing while metathesis-process specialty grades capture formulation premiums and next-generation bio-based pathways remain pre-commercial. Three-tier pricing structure across premium, standard, and economy levels reflects certification intensity and feedstock route, with automotive OEMs least price-sensitive due to specification lock-in and construction buyers most sensitive to resin cost fluctuations. Cost compression in standard-grade polyethylene is intensifying because Middle Eastern PDH operators anchor global cost curves.
Supply Chain Analysis
Strategic stockpiling of polymer-grade propylene dominates automotive compounder procurement while just-in-time ethylene sourcing prevails in packaging film operations. Supply concentrates in Saudi Arabia, the United States, and China, with feedstock dependencies on ethane, naphtha, and propane routes creating margin volatility. Single-source vulnerability runs through Jubail and Yanbu export terminals for Asian long-term offtake agreements. Distribution runs through Houston, Ningbo, and Rotterdam port terminals for pelletized grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized catalytic cracking expertise is retiring faster than training pipelines replenish, creating a capability bottleneck that determines which producers can operate high-severity units for derivative manufacturing.
For Market Incumbents: Consolidate backward integration into Gulf Coast ethane supply and captive propane dehydrogenation capacity to defend margin structures against Middle Eastern feedstock cost advantages. Lock in long-term automotive OEM direct contracts before compounder networks restructure around mass-balance certification requirements. For New Entrants and Emerging Players: Differentiate on bio-based feedstock metathesis pathways for specialty linear alpha-olefins where incumbents lack renewable carbon portfolios. Target India's PLI scheme jurisdictions for greenfield PDH investments serving domestic automotive growth with lower regulatory friction than European REACH compliance. For Investors and Strategic Acquirers: EPA emissions standard tightening under the Clean Air Act reshapes the acquisition landscape toward ethane crackers with lower carbon intensity profiles than refinery-based alternatives. Prioritize mid-scale compounders with verified automotive OEM relationships and mass-balance certification infrastructure. Watch for ethane-naphtha spread compression as the inflection signal for cracking asset repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethane Supply | Gulf Coast crackers secure NGL cost advantages against naphtha-linked competitors. |
| Long-term Supply Agreement with Automotive OEMs | Direct contracting bypasses distributor channels for formulation customization value. |
| Green Manufacturing Transition | Bio-based metathesis pathways enable renewable carbon qualification for CE marking. |
| Joint Venture in Coastal China | Ningbo and Dalian clusters offer integrated port access for feedstock import efficiency. |
| Capacity Expansion in PDH | On-purpose propylene production captures automotive compounding margin pools. |
Study Parameters
Desk research of trade flow databases, SEC petrochemical filings, and ECHA substance registrations preceded structured interviews with olefin derivative plant managers, automotive Tier 1 procurement leads, and technical R&D directors at compounding operations. Primary fieldwork with distribution channel partners and customs data validation enabled bottom-up volume triangulation against top-down feedstock consumption models.
Variance decomposition across feedstock route, grade tier, and end-use industry segments structured the analytical framework throughout the forecast period. Modeled dimensions span polymer type, certification level, regional production hub, and automotive versus construction demand archetype. CAGRs derived from segmented growth rate blending with ethane-naphtha spread assumptions and automotive lightweighting penetration curves.
Material uncertainties — feedstock price volatility, MEE emissions enforcement intensity, and REACH authorization timeline shifts — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding PDH capacity commissioning and automotive recycled content mandate adoption. Revision becomes warranted when ethane-naphtha cost spreads compress below operational breakeven thresholds for naphtha crackers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petrochemicals
Alkylate Isooctane Market
Petrochemicals
Bio Butadiene Market
Petrochemicals
Petrochemicals Market
Petrochemicals
Alkylate Market
Petrochemicals
Light Olefins Market
Petrochemicals
Flame-Retardant Polypropylene (PP) Market
Petrochemicals
Pentane Market
Petrochemicals
Global Methyl Tertiary Butyl Ether Market
Petrochemicals
Tert Butyl Hydroperoxide Market
Petrochemicals
Anthracene Oil Market
Petrochemicals
Global Polypropylene Market
Petrochemicals
Malaysia Chemical and Petrochemical Market
Petrochemicals
Chemical and Petroleum Containers Market
Petrochemicals
Petrochemical Feedstock Market
Petrochemicals
Propylene Market
Petrochemicals
Bioisobutene Market