
 Water Soluble Polymers Market | 2026-2036
Water Soluble Polymers Market Size, Share, and Industry Trends Forecast 2026-2036
Water Soluble Polymers Market Intelligence
Modular polymer blends that combine flocculant, coagulant, and rheology modifier functions in a single delivery system is repositioning procurement patterns for municipal water treatment operators. SNF Group dominates polyacrylamide manufacturing scale across multiple continents. Kemira Oyj anchors its position through deep specialization in pulp and paper chemistry applications. BASF SE extends its reach via backward integration into acrylic acid monomer supply.
Water soluble polymers are macromolecules that dissolve or disperse in aqueous environments to modify viscosity, stabilize emulsions, or enable controlled release, typically synthesized through free-radical polymerization, grafting, or controlled radical techniques to achieve molecular weights ranging from thousands to millions of Daltons. Their primary commercial purpose centers on modifying fluid behavior in processes ranging from oilfield extraction to pharmaceutical tablet coating. Polyvinyl alcohol leads product type revenue due to its established film-forming performance in textile sizing and paper coatings, while pharmaceutical grade formulations command the widest margin pools within the grade dimension as validation costs create supply scarcity. Personal care applications within the application dimension are gaining fastest as formulators replace microplastics with biodegradable rheology modifiers.
EPA effluent limitation guidelines shape polymer selection in United States industrial discharge applications by mandating toxicity reduction in treated outflows. ECHA REACH restrictions on acrylamide monomer residuals compel European manufacturers to invest in purification infrastructure and analytical certification. China's MEE discharge standards for chemical oxygen demand are tightening acceptance thresholds for wastewater treatment polymers. Stakeholders must monitor regulatory divergence between jurisdictions to avoid reformulation costs that fragment product portfolios.
Market Dynamics
Modular polymer blends are compressing procurement cycles for municipal water treatment operators by collapsing three separate chemical inputs into single-dose formulations, forcing legacy suppliers to reconfigure their product architectures around integrated performance rather than individual active ingredients.
Growth Catalysts
- EPA effluent limitation guidelines:Mandated toxicity reductions in industrial discharge applications are compelling manufacturers to upgrade to high-purity polymer grades, accelerating replacement demand across United States metal finishing and textile wet processing facilities.
- China's MEE discharge standards:Tightening chemical oxygen demand thresholds for wastewater treatment plants are pulling significant polymer volumes into capacity expansion projects across industrial zones in Jiangsu and Zhejiang provinces.
- Biodegradable rheology modifiers:Formulators in European personal care markets are substituting microplastic-based thickeners with cellulose-derived and fermentation-based alternatives, opening new specification windows for specialty polymer producers.
Market Restraints
- Acrylamide monomer cost volatility:Feedstock price swings tied to propylene supply disruptions compress margins for polyacrylamide manufacturers, particularly those without captive acrylonitrile production.
- European purification infrastructure:ECHA REACH restrictions on acrylamide residuals compel capital-intensive investments in analytical certification and monomer removal systems that smaller compounders cannot absorb.
- Natural gum substitution:Xanthan and guar derivatives are displacing synthetic polymers in lower-specification oilfield and food applications where thermal stability requirements permit.
Strategic Opportunities
- India's industrial wastewater capacity:Central Pollution Control Board mandates for zero liquid discharge in textile clusters around Tiruppur and Surat are creating specification demand for high-molecular-weight flocculants.
- Controlled-release pharmaceutical coatings:Convergence of hot-melt extrusion and aqueous polymer dispersion technologies is enabling next-generation tablet formulations with tunable dissolution profiles.
- EU Green Deal procurement criteria:Public tender requirements for bio-based content in municipal chemical supplies are redirecting specification authority toward fermentation-derived polyglutamic acid and chitosan suppliers.
Industry Challenges
- Analytical chemistry skill scarcity:Validating pharmaceutical-grade polymer batches requires technicians proficient in gel permeation chromatography and residual monomer quantification, talent pools that concentrate around Basel and Boston hubs.
- Legacy DCS integration:Automated polymer dosing systems in retrofitted water treatment plants must interface with decades-old distributed control architectures, extending commissioning timelines and requiring custom protocol bridges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Soluble Polymers Market |
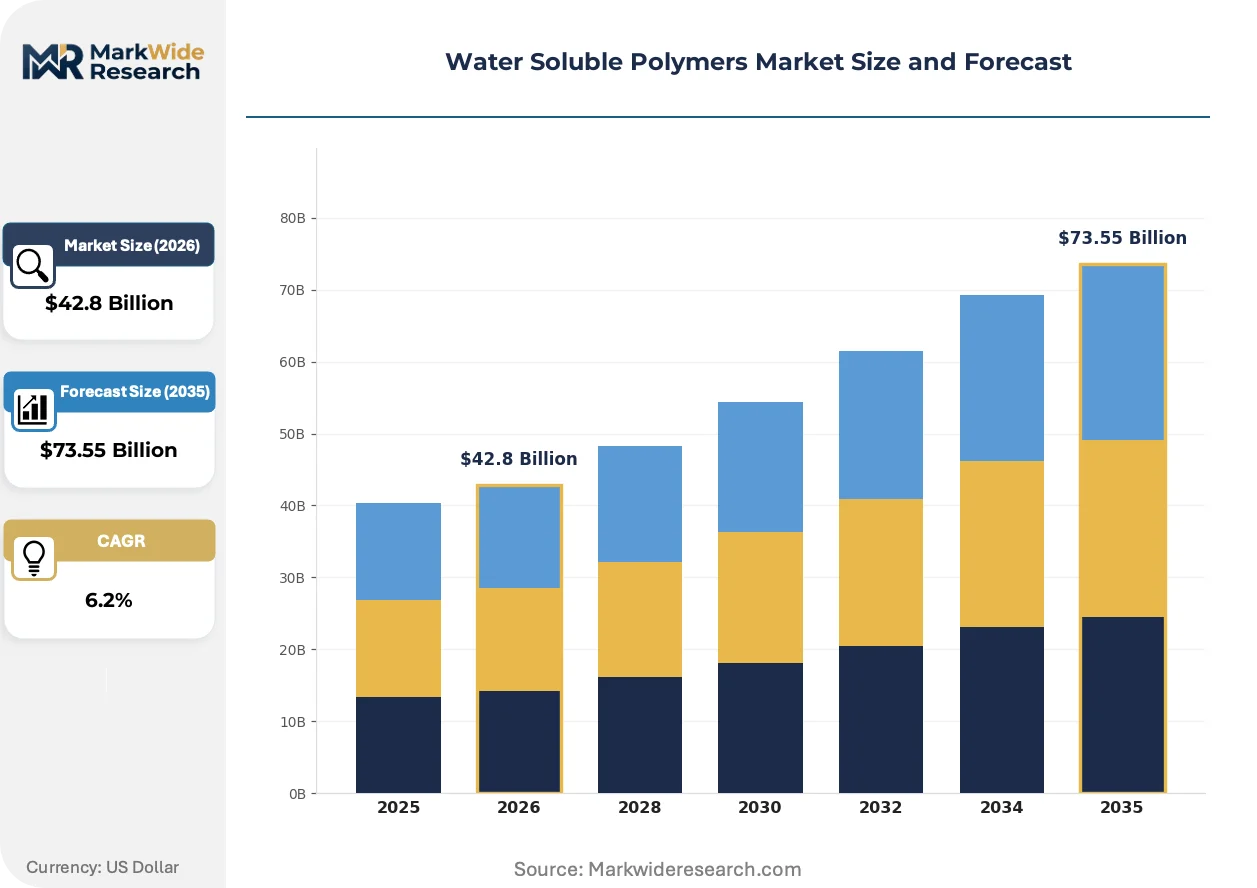
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $73.55 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyvinyl Alcohol, Polyethylene Glycol, Hydroxypropyl Methylcellulose, Sodium Polyacrylate Application: Coatings, Adhesives, Personal Care, Pharmaceuticals End User: Food & Beverage, Healthcare, Cosmetics, Textile Grade: Industrial Grade, Food Grade, Pharmaceutical Grade, Cosmetic Grade |
| Companies Covered | Arkema, DuPont de Nemours Inc., SNF Group, Mitsubishi Chemical Holdings Corporation, Kemira Oyj, BASF SE, Kuraray Co. Ltd., Dow Inc., Ashland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Soluble Polymers Market Strategic Shifts & Innovations
Formulation science is converging with process intensification to collapse multi-step treatment sequences into single-point chemical delivery, while regulatory chemistry requirements are tightening faster than analytical throughput can validate.
Hybrid polymer-silica nanocomposites are unifying flocculation kinetics with adsorptive capacity in a single particle architecture. Municipal operators in water-stressed regions of Spain and Australia are piloting these materials to reduce clarifier footprint and sludge volume. The technology is unifying what were previously separate coagulation and filtration process trains, compressing capital expenditure for greenfield treatment facilities by eliminating dedicated media filtration stages.
REACH restrictions on acrylamide monomer residuals are forcing European manufacturers to deploy secondary purification trains and implement batch-level analytical certification. The regulation is fragmenting product portfolios as export-bound formulations require different purity grades than domestic sales. Pharmaceutical-grade polyacrylamide suppliers in Germany and Switzerland are absorbing the highest compliance burdens, passing validation costs through to contract manufacturing organizations serving ophthalmic and injectable drug markets.
Specification authority is migrating from plant operators to corporate procurement functions with centralized sustainability mandates. Water treatment chemical selections in multinational food and beverage facilities are increasingly governed by enterprise-level bio-based content targets rather than site-specific performance optimization. This shift is most visible in Coca-Cola and Unilever supply chains, where European headquarters procurement teams are consolidating polymer suppliers around vendors with third-party bio-based certifications.
Water Soluble Polymers Market Segmentation
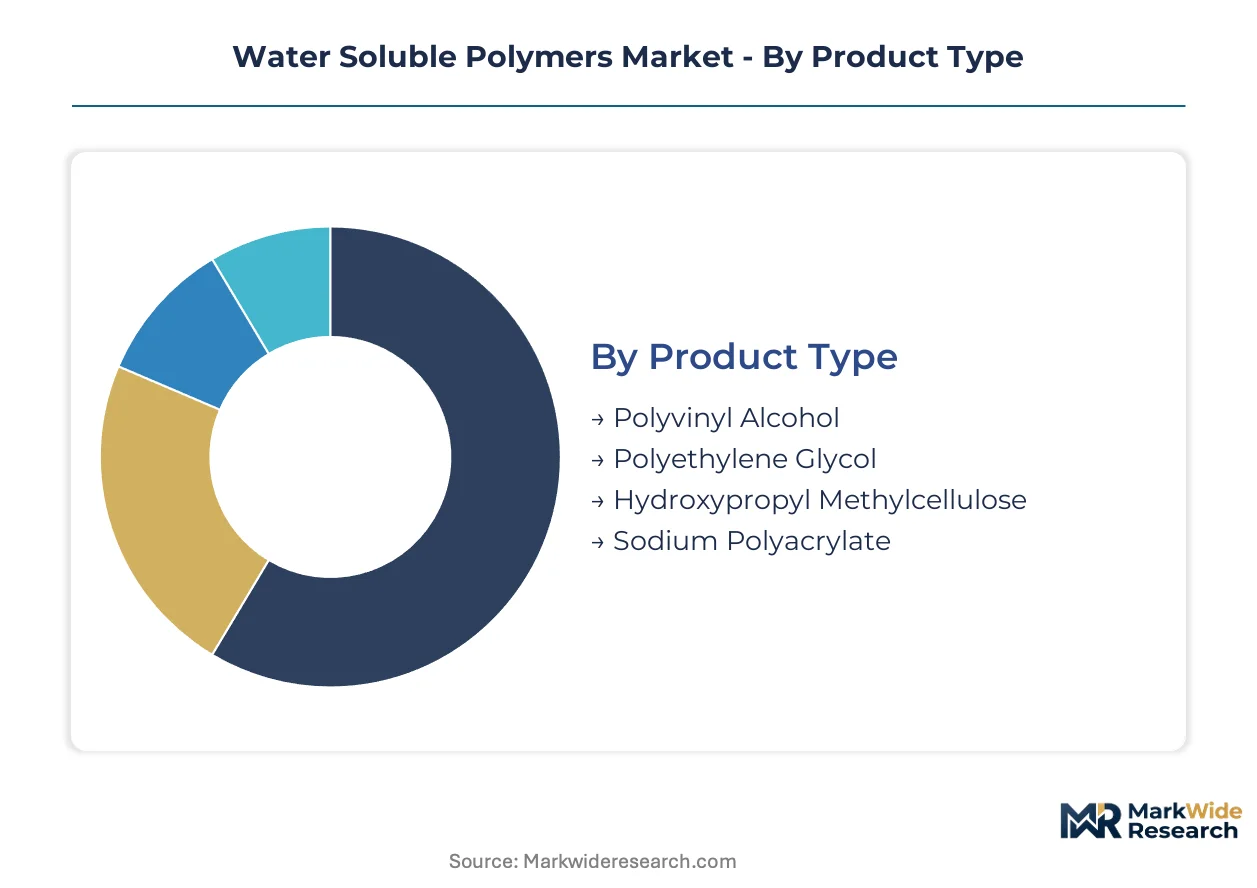
Segmentation in water soluble polymers reveals divergent margin structures across purity tiers and end-use specifications. Industrial buyers prioritize cost-per-kilogram metrics while pharmaceutical and cosmetic formulators absorb premiums for validated batch consistency.
Product Type:
Volume concentration sits with commodity film-formers, while premium pricing accrues to specialty rheology modifiers with narrow specification windows.
- Polyvinyl Alcohol:Partially and fully hydrolyzed grades dominate textile sizing and paper coating applications. Demand concentrates in China's Yangtze River Delta paper manufacturing clusters, where capacity expansions are pulling significant polymer volumes for surface treatment formulations.
- Polyethylene Glycol:Linear polyether structure enables tunable molecular weight ranges from 200 to 20,000 Daltons. Pharmaceutical excipient specifications in Germany and Switzerland command the widest margin pools, as ophthalmic and injectable drug manufacturers require sub-ppm residual impurity profiles.
- Hydroxypropyl Methylcellulose:Cellulose ether derived from wood pulp alkoxylation serves construction and food applications.
- Sodium Polyacrylate:Superabsorbent polymer architecture captures moisture management in hygiene products.
Today's leader: Polyvinyl Alcohol. Tomorrow's challenger: Polyethylene Glycol.
Application:
Coatings and adhesives anchor tonnage demand, whereas personal care and pharmaceutical segments extract value through specification complexity and regulatory validation burdens.
- Coatings:Film-forming polymers enable barrier properties in paper and textile substrates. Water treatment plant infrastructure coatings in Jiangsu province are specifying high-purity grades to meet MEE discharge standards for chemical oxygen demand thresholds.
- Adhesives:Tackifiers and thickeners modify viscoelastic response in packaging and construction bonding. European packaging converters are consolidating procurement around bio-based content certifications under EU Green Deal procurement criteria.
- Personal Care:Rheology modifiers replace microplastic-based thickeners in European formulator pipelines.
- Pharmaceuticals:Controlled-release coatings and tablet binders require batch-level analytical certification.
Coatings and adhesives generate the volume base. Personal care applications are climbing the fastest as microplastic substitution mandates tighten across European markets.
End User:
Food and beverage processors drive food-grade certification demand, while healthcare and cosmetics segments impose the most stringent purity requirements.
- Food & Beverage:Thickeners, stabilizers, and encapsulation matrices modify texture and shelf stability. Coca-Cola and Unilever supply chains are consolidating suppliers around third-party bio-based certifications governed by European headquarters procurement functions.
- Healthcare:Wound dressings, drug delivery systems, and medical device coatings require USP-grade validation. Ophthalmic and injectable drug markets in Basel and Boston hubs absorb the highest compliance burdens for residual monomer quantification.
- Cosmetics:Film-formers and emulsion stabilizers serve skin and hair care formulations.
- Textile:Sizing agents and dye fixatives process natural and synthetic fibers.
Food and beverage anchors tonnage procurement. Healthcare commands the steepest premium expansion trajectory as validation costs create supply scarcity.
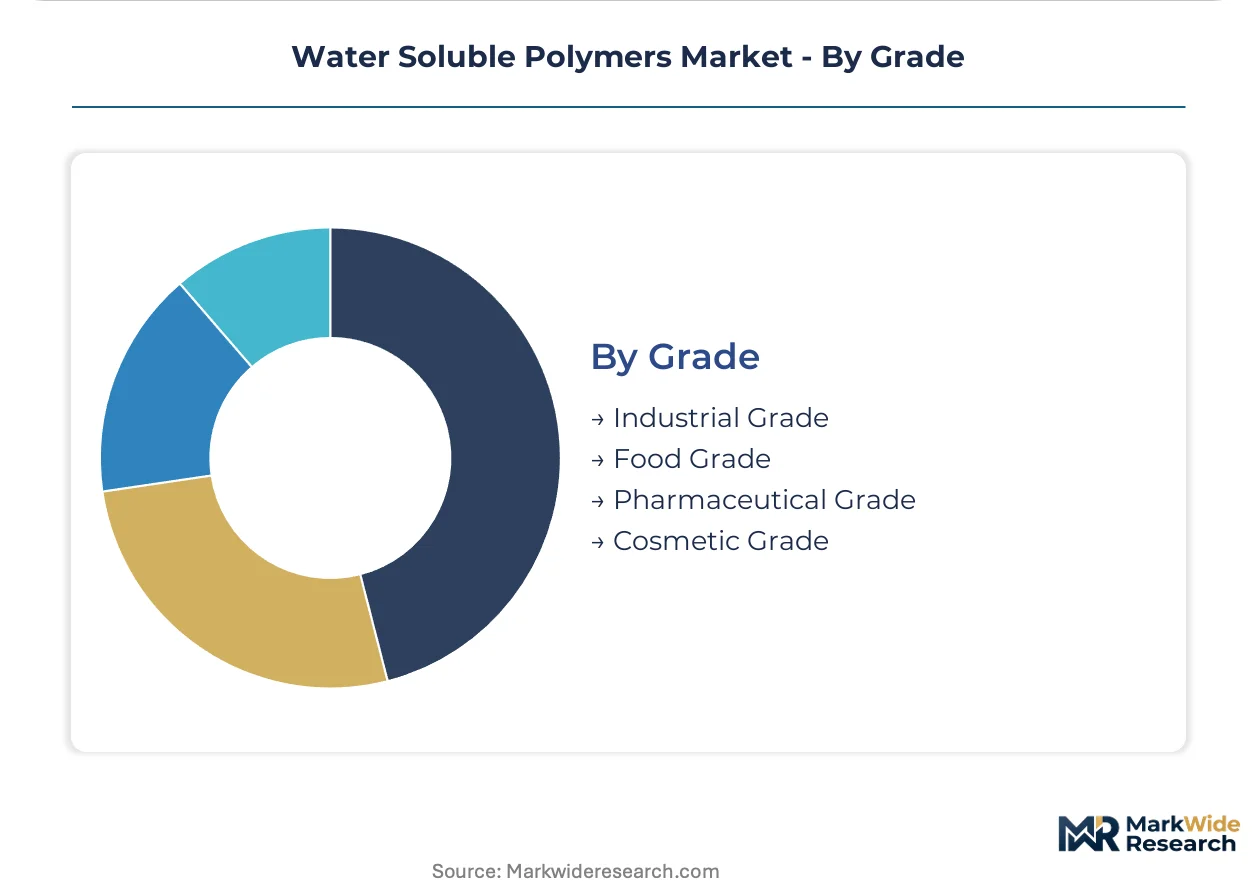
Grade:
Industrial grade captures volume scale, while pharmaceutical and cosmetic grades concentrate margin extraction through analytical certification and batch documentation.
- Industrial Grade:Broad-specification polymers serve water treatment, oilfield, and construction applications. Municipal operators in Spain and Australia are piloting hybrid polymer-silica nanocomposites to reduce clarifier footprint in water-stressed regions.
- Pharmaceutical Grade:Gel permeation chromatography validation and residual monomer quantification are mandatory. ECHA REACH restrictions on acrylamide residuals are fragmenting product portfolios as export-bound formulations require different purity grades than domestic European sales.
- Food Grade:FSSAI and FDA compliance frameworks govern direct food contact applications.
- Cosmetic Grade:Safety assessments and INCI labeling requirements structure supplier qualification.
Industrial grade moves the volume. Pharmaceutical grade captures the margin.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Water soluble polymer manufacturing first scaled in Germany and the United States during the post-war synthetic materials expansion, with industrial clusters later emerging in Japan and China as regional chemical processing capabilities matured.
United States
EPA effluent limitation guidelines mandate toxicity reductions in industrial discharge applications across metal finishing and textile wet processing facilities. The agency's evolving discharge standards compel manufacturers to upgrade to high-purity polymer grades. Municipal water treatment operators in the Great Lakes region are piloting modular polymer blends that collapse flocculant, coagulant, and rheology modifier functions into single-dose formulations.
China
Industrial wastewater treatment capacity additions and paper manufacturing expansion in Jiangsu and Zhejiang provinces are pulling significant polymer volumes. MEE discharge standards for chemical oxygen demand are tightening acceptance thresholds for wastewater treatment polymers. Yangtze River Delta paper manufacturing clusters are specifying high-purity grades for surface treatment formulations.
Germany
ECHA REACH restrictions on acrylamide monomer residuals compel capital-intensive investments in purification infrastructure and analytical certification. Pharmaceutical-grade polyacrylamide suppliers absorb the highest compliance burdens, passing validation costs through to contract manufacturing organizations serving ophthalmic and injectable drug markets. Basel and Boston hubs concentrate scarce analytical chemistry talent for gel permeation chromatography validation.
India
Central Pollution Control Board mandates for zero liquid discharge in textile clusters around Tiruppur and Surat are creating specification demand for high-molecular-weight flocculants. The country's national pollution regulator is tightening enforcement across chemical processing zones. Industrial wastewater capacity expansion in Gujarat and Tamil Nadu is redirecting procurement toward validated polymer suppliers.
Australia
Municipal operators in water-stressed regions are piloting hybrid polymer-silica nanocomposites to reduce clarifier footprint and sludge volume. The technology unifies flocculation kinetics with adsorptive capacity in a single particle architecture. Greenfield treatment facilities in New South Wales and Victoria are eliminating dedicated media filtration stages through integrated chemical delivery systems.
Water Soluble Polymers Market Key Industry Players
Premium-margin players sit above commodity-margin players across the grade dimension, with pharmaceutical and cosmetic certification tiers extracting validation-cost premiums while industrial-grade suppliers compete on cost-per-kilogram metrics. The vendor base organizes into three strategic archetypes: integrated chemical conglomerates with captive monomer supply, specialized water treatment chemical producers with deep application expertise, and regional compounders serving proximity-sensitive construction and oilfield markets. Dominant competitive moves center on backward integration into acrylic acid monomer supply and portfolio diversification toward bio-based fermentation-derived alternatives.
Within the integrated chemical tier, BASF SE and Dow Inc. exemplify scale-driven positioning through in-house production of key feedstocks. SNF Group and Kemira Oyj occupy positions as specialized water treatment chemical producers with differentiated application knowledge. Arkema and DuPont de Nemours Inc. represent diversified material science conglomerates with cross-polymer technology portfolios. Among Japanese and Korean chemical holdings, Mitsubishi Chemical Holdings Corporation and Kuraray Co. Ltd. anchor regional supply positions with proximity advantages across Asia-Pacific industrial zones. Ashland exemplifies the transition archetype, repositioning from commodity industrial chemicals toward higher-margin specialty formulations.
| Leading Market Players |
|---|
| Arkema |
| DuPont de Nemours Inc. |
| SNF Group |
| Mitsubishi Chemical Holdings Corporation |
| Kemira Oyj |
| BASF SE |
| Kuraray Co. Ltd. |
| Dow Inc. |
| Ashland |
| Others |
Cost & Logistics Intelligence
China's MEE discharge standards tightening chemical oxygen demand thresholds are compelling municipal procurement teams to specify high-purity polymer grades, forcing supply chains to absorb purification infrastructure costs that transmit upward through pricing tiers. This regulatory-driven specification shift concentrates purchasing power among validated suppliers while fragmenting product portfolios across purity grades.
Pricing Analysis
Three-tier pricing structure across pharmaceutical, industrial, and economy levels dominates transaction structures in this market. Pharmaceutical-grade formulations command substantial premiums over industrial grades due to gel permeation chromatography validation and residual monomer quantification requirements. Cost compression in industrial-grade polyacrylamide is intensifying because acrylamide monomer cost volatility tied to propylene supply disruptions squeezes non-integrated manufacturers. Municipal water treatment operators exhibit highest price sensitivity, while ophthalmic and injectable drug manufacturers absorb premiums without volume elasticity.
Supply Chain Analysis
India's Central Pollution Control Board mandates for zero liquid discharge in textile clusters are reshaping sourcing patterns toward domestic compounders with validated supply documentation. Manufacturing concentrates in China, Germany, and the United States, with acrylic acid monomer production anchoring cost structures. Feedstock dependencies center on propylene derivatives, acrylonitrile, and wood pulp alkoxylation inputs. Single-source vulnerability runs through acrylamide monomer supply from non-integrated producers. Distribution runs through regional chemical distributors with technical service capabilities and direct mill supply agreements for large-volume paper and textile processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA effluent limitation guidelines and REACH restrictions on acrylamide residuals generate sustained replacement demand across purity tiers.
For Market Incumbents: Acquire purification infrastructure assets in European manufacturing corridors to defend against ECHA REACH compliance cost fragmentation. Secure backward integration into acrylic acid monomer supply to neutralize propylene derivative volatility threatening polyacrylamide margins. Prioritize certification investment for pharmaceutical-grade batch documentation to capture ophthalmic and injectable drug contract manufacturing demand. For New Entrants and Emerging Players: India's Central Pollution Control Board zero liquid discharge mandates in Tiruppur and Surat textile clusters open a window for high-molecular-weight flocculant specialization without incumbent purification infrastructure burdens. Target fermentation-derived polyglutamic acid and chitosan production to exploit EU Green Deal procurement criteria bio-based content thresholds. Pursue direct technical service partnerships with municipal water treatment operators piloting modular polymer blends. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized water treatment chemical producers possessing deep application expertise in pulp and paper chemistry. Five-to-ten-year viability hinges on regulatory divergence between jurisdictions creating sustained reformulation demand rather than commodity substitution. Monitor acrylamide monomer residual threshold tightening across multiple geographies as inflection indicator for purification infrastructure valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive acrylonitrile production insulates BASF and Dow from propylene supply disruption margin compression. |
| Green Manufacturing Transition | Fermentation-derived polyglutamic acid aligns with EU Green Deal procurement criteria redirecting municipal specification authority. |
| Capacity Expansion | Jiangsu and Zhejiang province additions capture China's MEE discharge standard-driven wastewater treatment polymer demand. |
| Long-term Supply Agreement | Coca-Cola and Unilever supply chain consolidation around bio-based certifications locks in specialty polymer volume commitments. |
| Joint Venture | Hybrid polymer-silica nanocomposite development partnerships accelerate pilot adoption in Spain and Australia water-stressed regions. |
Research Approach
Bottom-up water treatment and pulp and paper modeling reconciled against top-down acrylic acid monomer supply tracking forms the analytical core of this study. Primary interviews with municipal procurement directors, plant managers at Yangtze River Delta paper manufacturing clusters, technical R&D directors at specialty chemical producers, and pharmaceutical contract manufacturing organization supply chain leads combined with secondary validation from customs and trade data, SEC 10-K filings, and Cefic industry reports. Triangulation across stakeholder perspectives and documentary sources ensures demand-side and supply-side estimates converge.
Input-output matrices map polymer grade specifications to end-use application requirements across the projection horizon. Segmentation dimensions modeled include grade tier, end-use industry, regional production hub, and regulatory compliance cluster. CAGRs derive from volume trajectory analysis against capacity expansion announcements and purity grade shift elasticity. Forecast inputs incorporate MEE discharge standard enforcement timelines and REACH acrylamide residual threshold evolution patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under propylene supply disruption scenarios or accelerated natural gum substitution in oilfield applications. Assumptions documented throughout reflect regulatory implementation schedules and industrial wastewater capacity addition commitments. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
North America Geopolymer Market
Polymers & Resins
Global Water-Based Resins Market
Polymers & Resins
Global Polyamide Market
Polymers & Resins
Global Polymer Stabilizer Market
Polymers & Resins
United States Polyols Market
Polymers & Resins
Cast Polymers Market
Polymers & Resins
Nonchlorinated Polyolefins Market
Polymers & Resins
BMI Resins Market
Polymers & Resins
Middle-East and Africa Thermoplastics Market
Polymers & Resins
Silicon Anode Binder Polymers for Lithium-Ion Batteries Market
Polymers & Resins
Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Global Polyolefin Powders Market
Polymers & Resins
Germany Polymer Emulsion Market
Polymers & Resins
Polyurethane (PU) Foam Market
Polymers & Resins
Thermoplastic Polyester Engineering Resin (TPER) Market
Polymers & Resins
Asia-Pacific Opaque Polymers Market