
 Petrochemical Feedstock Market | 2026-2036
Petrochemical Feedstock Market Size, Share, and Industry Trends Forecast 2026-2036
Petrochemical Feedstock Market Analytics
Gulf Coast ethane export terminal expansions are broadening supply corridors to Asian crackers. Shell Chemical Company leverages integrated natural gas liquids infrastructure across Louisiana and Texas to sustain feedstock cost advantages. BASF SE anchors European naphtha demand through its Ludwigshaven Verbund complex, while SABIC dominates Middle Eastern ethane availability via Saudi Aramco-linked supply agreements.
Petrochemical feedstock denotes raw hydrocarbon inputs—principally natural gas, naphtha, ethane, and propane—processed through steam cracking at temperatures exceeding 800°C to yield olefins and aromatics for downstream chemical synthesis. These inputs serve as the molecular foundation for plastics, synthetic fibers, and elastomers that permeate industrial and consumer supply chains. Naphtha retains primacy in Asian cracking economics due to refinery integration density, while ethane captures margin pools in North American operations benefiting from shale-associated cost structures. End-user segmentation reveals plastics as the mature volume anchor, with packaging applications driving incremental fermentation-based bio-feedstock trials in European regulatory environments.
The US EPA regulates feedstock-related emissions under Clean Air Act stationary source provisions, while the EU Green Deal and REACH framework constrain carbon-intensive naphtha cracking through emissions trading and chemical safety mandates. China's MEE enforces dual carbon goals that redirect state investment toward lighter feedstock ratios and carbon capture retrofits. Stakeholders must monitor regulatory divergence between carbon-pricing jurisdictions and subsidy-dependent markets to align capital deployment with shifting compliance boundaries.
Market Dynamics
Cracker feedstock switching economics are compressing naphtha margins while ethane-linked operations in shale-adjacent geographies capture structural cost advantages. The divergence between carbon-priced European operations and subsidy-backed Chinese integration projects is fragmenting competitive returns across supply basins.
Growth Catalysts
- EU Green Deal carbon border adjustments:European converters are accelerating bio-based feedstock qualification programs to preempt compliance cost exposure on imported plastics.
- Packaging sector lightweighting mandates:Food and beverage brand owners are specifying higher-ethylene-content resins that favor lighter feedstock slates in cracker configurations.
- US Gulf Coast NGL infrastructure density:Mont Belvieu fractionation expansions are extending ethane cost advantages to export-bound derivative producers.
Market Restraints
- Ethane supply concentration:US midstream operators control 70-plus percent of global export terminal capacity, creating bottleneck risk for Asian buyers.
- Naphtha price volatility:Crude-linked feedstock costs swing with Brent futures, eroding margin predictability for European crackers lacking backward integration.
- REACH chemical safety compliance:The ECHA authorization process delays new bio-based feedstock commercialization by 18-36 months versus conventional hydrocarbons.
Strategic Opportunities
- India petrochemical demand acceleration:Reliance Industries and Indian Oil are expanding cracker capacity 40 percent by 2030, creating import substitution openings for ethane suppliers.
- Carbon capture retrofits at steam crackers:MEE dual carbon enforcement in China is mandating CCUS installation, opening engineering and catalyst licensing revenue streams.
- Pyrolysis oil feedstock qualification:Chemical recycling outputs are achieving ISCC PLUS certification for circular content claims in European automotive supply chains.
Industry Challenges
- Cracker operator skill shortages:Experienced furnace engineers and process control specialists are exiting the workforce faster than apprenticeship programs replenish talent pipelines.
- Feedstock flexibility capex requirements:Dual-feed cracker retrofits demand $200-400 million per unit to handle ethane-naphtha switching, straining mid-cap producer balance sheets.
- ISCC certification timeline compression:Mass-balance chain-of-custody audits for bio-based feedstocks are extending 8-14 months, delaying offtake contract executions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Petrochemical Feedstock Market |
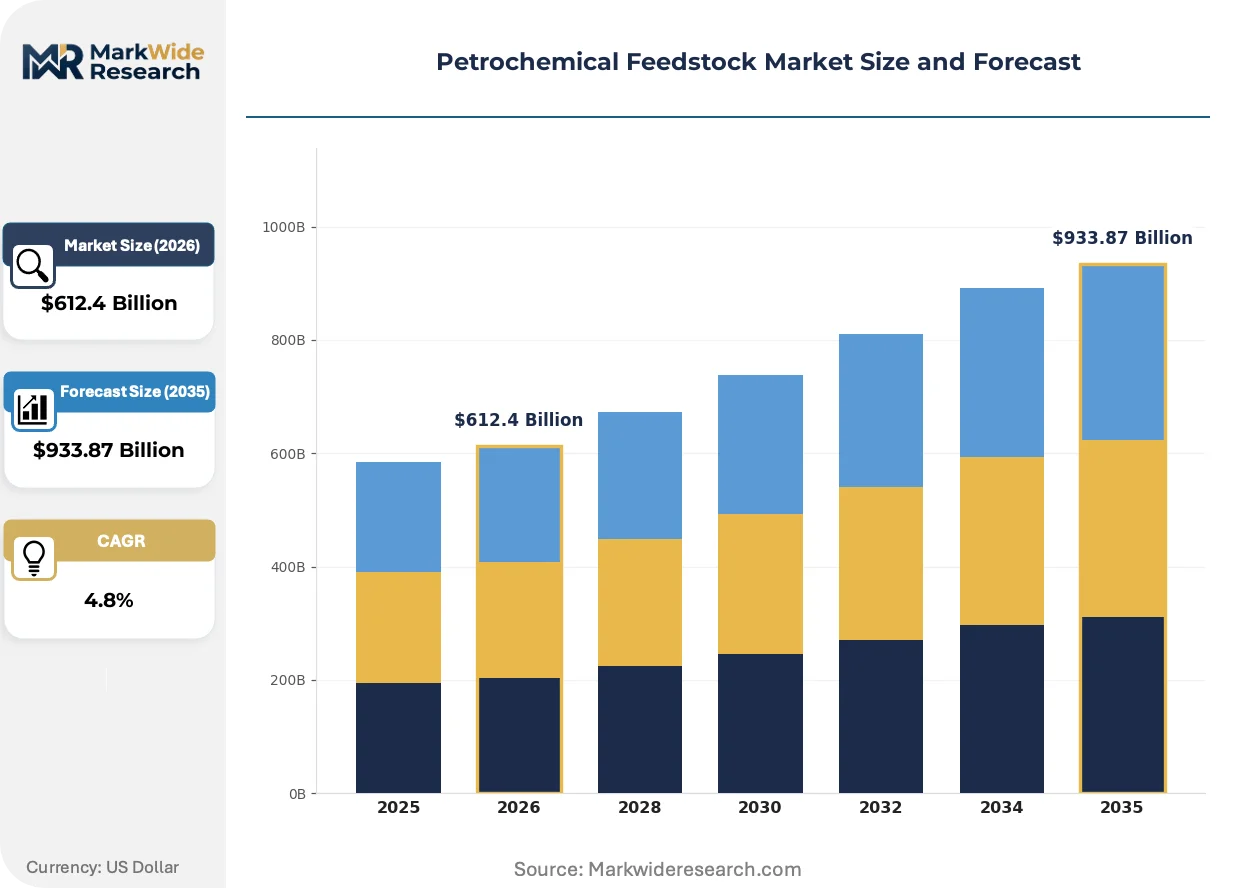
| Market Size in 2026 | $612.4 Billion |
| Market Size in 2035 | $933.87 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feedstock Type: Natural Gas, Naphtha, Ethane, Propane End User: Plastics, Fibers, Synthetic Rubber, Detergents Process Technology: Steam Cracking, Catalytic Cracking, Hydrocracking, Fermentation Application Area: Packaging, Automotive, Construction, Electronics |
| Companies Covered | Shell Chemical Company, TotalEnergies SE, ExxonMobil, Reliance Industries Limited, Sumitomo Chemical Co. Ltd., BASF SE, Chevron Phillips Chemical Company LLC, The Dow Chemical Company, SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Petrochemical Feedstock Market Evolving Landscape
Electrification of steam cracking furnaces and chemical recycling integration are converging to decarbonize molecular production pathways. These technology shifts are reshaping capital allocation priorities across integrated majors and independent refiners alike.
Electric cracking furnaces developed by Linde and BASF are expanding into demonstration phases at Ludwigshafen, with 100-megawatt units targeting 90 percent emissions reduction versus gas-fired equivalents. Chemical majors in carbon-intensive jurisdictions are prioritizing electrification to preserve site operating licenses under tightening EU ETS benchmarks. The technology is expanding into commercial viability assessments for crackers in Rotterdam and Antwerp harbor zones.
REACH authorization amendments and the EU Green Deal's 2050 climate neutrality mandate are tightening emissions performance standards for naphtha-derived olefins. European crackers face incremental carbon cost burdens of €80-100 per tonne under current ETS pricing trajectories. German and Dutch operators are responding with hydrogen fuel-switching trials and carbon capture pre-feasibility studies at Rotterdam and Antwerp clusters.
Brand-led circular content requirements are compressing traditional virgin resin procurement cycles as converters seek mass-balance-certified feedstocks. Unilever and Procter & Gamble are inserting chemical recycling off-take clauses into multi-year polyethylene supply agreements. This behavioral shift is most pronounced in European personal care and food packaging supply chains where ISCC PLUS claims command 8-12 percent price premiums.
Petrochemical Feedstock Market Segmentation
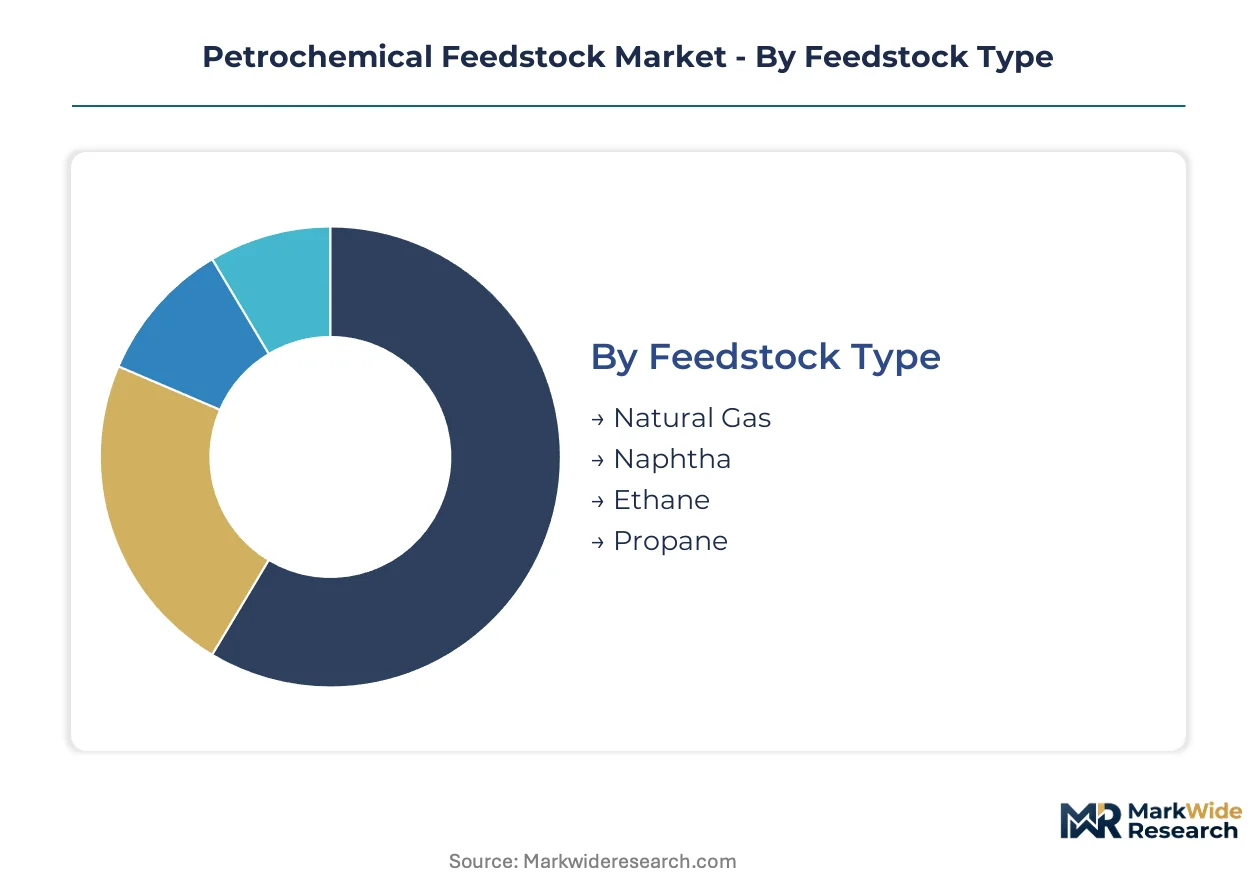
Feedstock segmentation in petrochemicals determines cracker configuration economics, carbon intensity profiles, and regional supply security. Distinct buyer priorities across type, end-use, and technology dimensions create divergent procurement strategies and margin structures.
Feedstock Type:
Cost tier and carbon exposure separate buyers in this category, with shale-adjacent operators pursuing ethane cost pools while European crackers manage naphtha-linked emissions burdens.
- Naphtha:A liquid petroleum distillate with carbon numbers ranging from C5 to C12, serving as the dominant feedstock for integrated refinery-petrochemical complexes. Asian crackers in China and India absorb the majority of traded volumes, driven by refinery integration density and established aromatics co-production economics. Naphtha retains primacy where crackers lack pipeline access to natural gas liquids infrastructure.
- Ethane:A gaseous C2 hydrocarbon extracted from natural gas processing and fractionation operations, yielding ethylene at higher selectivity than liquid alternatives. US Gulf Coast exporters supply Asian crackers through dedicated marine terminals, with Reliance Industries and Formosa Plastics scaling term purchases to displace naphtha in flexible furnaces. Ethane captures margin pools where cracker operators can access Mont Belvieu pricing benchmarks.
- Propane:A C3 saturated hydrocarbon deployed in mixed-feed configurations to balance ethylene and propylene output ratios.
- Natural Gas:Methane-rich feedstock processed through synthesis gas routes to methanol and olefins in regions with stranded gas economics.
Volume sits with naphtha; growth tilts toward ethane.
End User:
Application maturity and specification intensity differentiate buyers, with packaging converters driving lightweight resin demand while automotive tiers enforce circular content verification.
- Plastics:Polyethylene and polypropylene production consumes the majority of global olefin output, with injection molding and film extrusion applications dominating procurement specifications. Chinese packaging converters and Indian rigid container manufacturers are expanding ethane-linked polyethylene capacity to serve food-grade and industrial film segments. Plastics procurement concentrates in flexible cracker configurations that can swing between feedstock types.
- Fibers:Polyester and polyamide synthesis from paraxylene and caprolactam derivatives, with textile manufacturers in Bangladesh and Vietnam specifying recycled content thresholds. Fiber producers face margin compression from purified terephthalic acid oversupply in Asian markets.
- Synthetic Rubber:Styrene-butadiene and polybutadiene production for tire manufacturing, with automotive OEMs inserting sustainability clauses into compound supply agreements.
- Detergents:Linear alkylbenzene and fatty alcohol precursors derived from olefin and aromatic streams, serving household and industrial cleaning formulations.
Plastics commands installed capacity; fibers are expanding most quickly on per-capita consumption convergence.
Process Technology:
Capital intensity and emissions profile separate technology adopters, with electrification trials advancing in carbon-priced jurisdictions while conventional steam cracking retains cost advantages elsewhere.
- Steam Cracking:Thermal decomposition of hydrocarbons at furnace temperatures exceeding 800°C, representing the dominant olefin production pathway globally. Operators in Rotterdam and Antwerp harbor zones are piloting electric furnace retrofits to preserve operating licenses under tightening EU ETS benchmarks. Steam cracking retains cost leadership where natural gas prices suppress hydrogen fuel economics.
- Catalytic Cracking:Fluidized bed processing of heavier petroleum fractions to yield propylene and aromatics, integrated with refinery operations in Middle Eastern and Asian complexes.
- Hydrocracking:Hydrogen addition to heavy feeds under pressure, producing middle distillates and light olefins for integrated downstream chemical synthesis.
- Fermentation:Biological conversion of agricultural sugars to bio-based chemical precursors, with European converters qualifying mass-balance-certified outputs for ISCC PLUS claims in personal care supply chains.
Steam cracking holds throughput dominance; fermentation gains share fastest on regulatory-driven bio-content mandates.
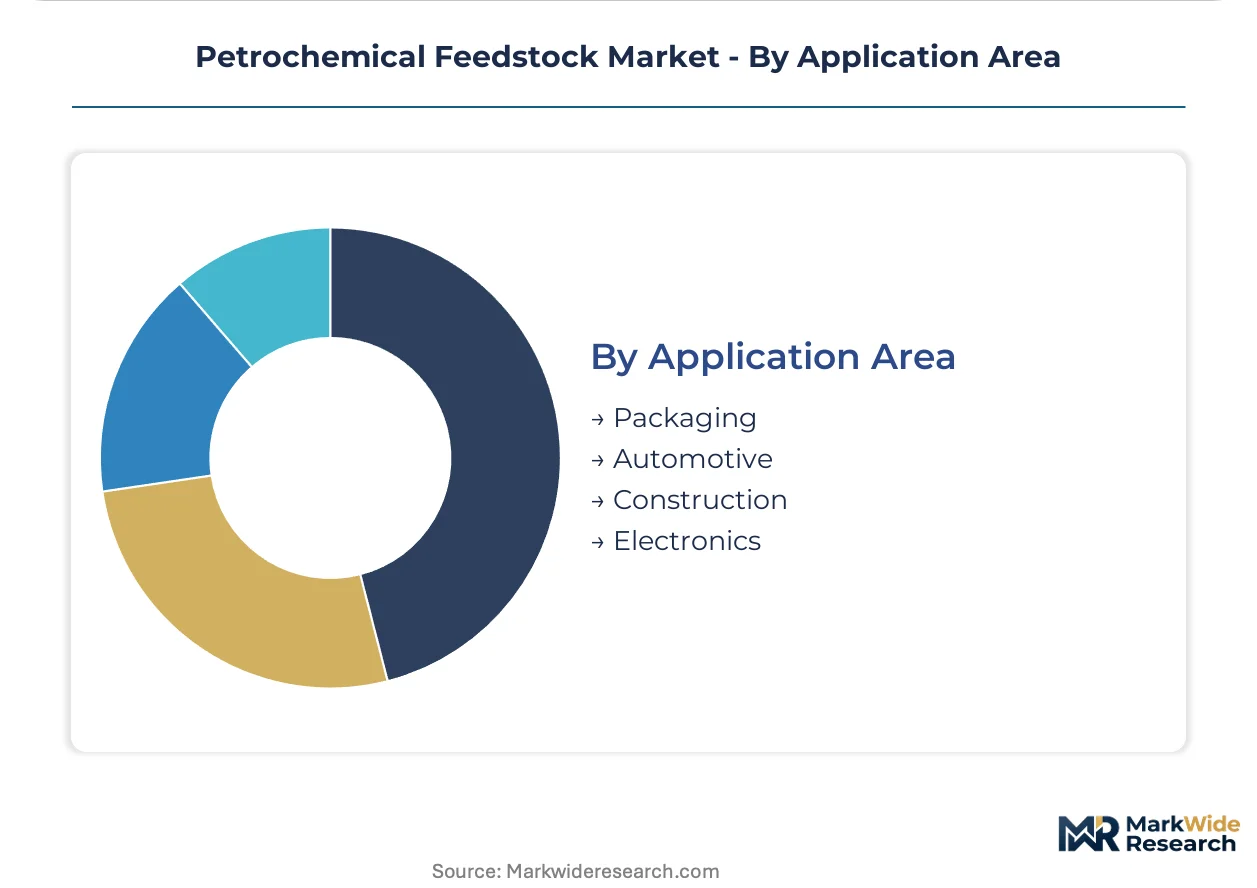
Application Area:
Durability requirements and circular content specifications differentiate buyers, with food packaging converters enforcing lightweighting targets while automotive tiers mandate recycled material quotas.
- Packaging:Flexible films, rigid containers, and protective foams representing the largest olefin demand segment by volume. Unilever and Procter & Gamble are inserting chemical recycling off-take clauses into multi-year polyethylene supply agreements for European personal care applications. Packaging converters prioritize ethane-derived resins for higher ethylene content and improved clarity specifications.
- Automotive:Interior components, under-the-hood applications, and lightweight structural elements, with German OEMs requiring ISCC PLUS certification for mass-balance chain-of-custody verification.
- Construction:Piping, insulation, and membrane applications serving infrastructure and residential building markets.
- Electronics:High-purity polymers for semiconductor encapsulation and consumer device housings, with Asian contract manufacturers specifying halogen-free flame retardant grades.
Packaging anchors volume consumption; automotive shows the steepest expansion trajectory on lightweighting and circular content requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mont Belvieu fractionation hubs anchor North American ethane availability. Naphtha procurement concentrates around integrated refinery corridors in Asia and Europe. Shale-adjacent supply basins are redirecting export terminal capacity toward Asian cracker expansions.
United States
Gulf Coast NGL infrastructure sustains ethane cost advantages for derivative producers. EPA Clean Air Act stationary source provisions regulate cracker emissions across Texas and Louisiana complexes. Mont Belvieu fractionation expansions are extending supply reach to export-bound polyethylene operations.
China
State-backed refinery-petrochemical integration projects absorb record ethane and naphtha volumes for olefin production. MEE dual carbon goals mandate carbon capture retrofits at steam cracking facilities. Yangtze River Delta clusters are piloting electric furnace demonstrations to preserve operating licenses under tightening emissions benchmarks.
Germany
BASF anchors European naphtha demand through its Ludwigshafen Verbund complex. EU ETS pricing trajectories impose incremental carbon costs of €80-100 per tonne on naphtha-derived olefins. Rotterdam and Antwerp harbor zones are advancing hydrogen fuel-switching trials and carbon capture pre-feasibility studies.
Saudi Arabia
SABIC dominates Middle Eastern ethane availability via Saudi Aramco-linked supply agreements. Domestic industrial diversification programs redirect petrochemical investment toward downstream derivative capacity. Eastern Province complexes leverage stranded gas economics for methanol-to-olefins production pathways.
India
Reliance Industries and Indian Oil are expanding cracker capacity to serve packaging and textile demand growth. Central Electricity Authority grid reliability standards influence site selection for energy-intensive steam cracking operations. Gujarat and Maharashtra industrial corridors concentrate import substitution investments for ethane terminal infrastructure.
Petrochemical Feedstock Market Competitive Landscape
Global majors compete with regional champions across feedstock access and cracker configuration flexibility. The vendor base separates into integrated oil majors with captive NGL supplies, national champions with state-backed refinery integration, and independent operators pursuing dual-feed flexibility. Three archetypes dominate: shale-advantaged ethane exporters, naphtha-anchored European integrators, and Middle Eastern low-cost gas processors. Competitive moves concentrate on capacity expansion in high-demand Asian markets and strategic partnerships for carbon capture technology licensing.
Among integrated majors with Gulf Coast NGL infrastructure, Shell Chemical Company and Chevron Phillips Chemical Company LLC exemplify the shale-advantaged archetype. BASF SE occupies a position representing European naphtha-anchored integration through its Ludwigshafen Verbund complex. SABIC sits within the Middle Eastern low-cost gas processor tier through its Saudi Aramco-linked supply structure.
| Leading Market Players |
|---|
| Shell Chemical Company |
| TotalEnergies SE |
| ExxonMobil |
| Reliance Industries Limited |
| Sumitomo Chemical Co. Ltd. |
| BASF SE |
| Chevron Phillips Chemical Company LLC |
| The Dow Chemical Company |
| SABIC |
| Others |
Value Network & Pricing Analysis
Mont Belvieu ethane pricing benchmarks cascade through three-tier pricing structures across premium, standard, and economy levels, with US Gulf Coast fractionation hubs transmitting cost advantages to Asian crackers while European naphtha buyers absorb carbon-adjusted premiums under EU ETS compliance tiers.
Pricing Analysis
Long-term offtake contracts dominate procurement, bundling freight, insurance, and terminal handling while unbundling carbon credit costs for European buyers. Price differentiation separates ISCC PLUS-certified bio-feedstocks from conventional hydrocarbons, with certification premiums widening as EU Green Deal enforcement tightens. Cost compression in naphtha-linked European cracking runs through Brent futures volatility and incremental carbon cost burdens. Asian state-backed integrators exhibit lowest price sensitivity; independent European converters without backward integration face acute margin pressure.
Supply Chain Analysis
Dual-sourcing mandates from Reliance Industries and Formosa Plastics require qualification across US and Middle Eastern ethane suppliers to mitigate concentration risk. Feedstock supply concentrates in the United States, Saudi Arabia, and China, drawing from shale gas processing, stranded gas fields, and refinery integration respectively. Raw material dependencies rest on natural gas liquids fractionation, crude oil distillation, and carbon capture equipment fabrication. Single-source vulnerability concentrates at Mont Belvieu export terminals where midstream operators control marine loading capacity. Distribution runs through dedicated very large ethane carrier fleets and integrated pipeline corridors to coastal cracking complexes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where EU ETS carbon pricing creates a regulatory moat protecting operators with installed CCUS infrastructure while excluding capital-constrained entrants from viable returns.
For Market Incumbents: Deploy carbon capture retrofits as the primary defensive lever, securing operating licenses in Rotterdam and Antwerp harbor zones while locking in term supply agreements with Asian buyers before US Gulf Coast capacity saturates. BASF and Shell Chemical Company exemplify this positioning through Ludwigshafen electric furnace pilots and Louisiana NGL infrastructure control respectively. Threat substitution from pyrolysis oil chemical recycling demands pre-emptive ISCC PLUS certification investment to preserve offtake relationships with Unilever and Procter & Gamble. For New Entrants and Emerging Players: Engineering procurement contractors represent the most accessible channel partner type for market entry, with India's 40 percent cracker capacity expansion creating white-space demand for ethane terminal infrastructure and CCUS technology licensing. Gujarat and Maharashtra industrial corridors offer penetrable geography where Reliance Industries' integration gaps create subcontracting opportunities. Fermentation-based bio-feedstock qualification for European personal care supply chains provides an alternative entry vector with lower capital intensity than conventional cracking. For Investors and Strategic Acquirers: The window for entry favors shale-advantaged midstream operators with captive Mont Belvieu fractionation access and established marine terminal contracts. Long-term viability hinges on carbon border adjustment mechanism expansion entrenching cost advantages for low-carbon intensity feedstock suppliers. Acquisition targets should demonstrate dual-feed cracker flexibility or ISCC PLUS certification completion. The signal to watch is EU ETS price trajectory breaching €100 per tonne, which would accelerate naphtha cracker closures and concentrate margin pools among ethane-linked operators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into NGL Fractionation | Shell Chemical Company secures captive ethane supply through Louisiana pipeline infrastructure control. |
| Carbon Capture Retrofit Installation | China's MEE dual carbon mandates create engineering licensing revenue streams for technology providers. |
| ISCC PLUS Certification Achievement | Mass-balance chain-of-custody verification unlocks 8-12 percent price premiums in European automotive supply chains. |
| Long-term Ethane Supply Agreement | Reliance Industries and Indian Oil lock in term purchases to displace naphtha in flexible furnace configurations. |
| Electric Cracking Furnace Demonstration | Linde and BASF pilot 100-megawatt units targeting 90 percent emissions reduction at Ludwigshafen. |
Research Methodology
Document review covered customs and trade data, SEC 10-K filings, and ACC/Cefic industry reports, complemented by interviews with cracker plant managers, downstream plastics procurement leads at packaging converters, NGL distribution channel partners, and technical R&D directors at catalyst suppliers. Bottom-up capacity and consumption estimates were triangulated against top-down macroeconomic demand projections across feedstock type, end-use industry, and regional production hub segmentation dimensions.
Market size and growth trajectory outputs were generated through integrated modeling of cracker operating rates, feedstock switching economics, and carbon cost pass-through elasticity across the projection horizon. CAGRs were derived from regression analysis of historical ethane-naphtha price spreads, capacity addition timelines, and regulatory enforcement intensity indices. Industry-specific inputs included Mont Belvieu fractionation capacity utilization rates and EU ETS benchmark price forecasting.
Caveats apply where abrupt shifts in crude oil futures volatility, carbon border adjustment mechanism implementation timelines, or US Gulf Coast hurricane disruption frequency could materially shift the outlook. Deviation in China's MEE enforcement intensity or ethane export terminal permitting velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petrochemicals
Alkylate Market
Petrochemicals
Military Propellants Market
Petrochemicals
Global Methyl Tertiary Butyl Ether Market
Petrochemicals
Fossil Fuel-Based Plastics Market
Petrochemicals
Malaysia Chemical and Petrochemical Market
Petrochemicals
Flame-Retardant Polypropylene (PP) Market
Petrochemicals
Alkylate Isooctane Market
Petrochemicals
Anthracene Oil Market
Petrochemicals
Global Perfluorocarbons Market
Petrochemicals
Bioisobutene Market
Petrochemicals
Propane Market
Petrochemicals
Global Polypropylene Market
Petrochemicals
Tert Butyl Hydroperoxide Market
Petrochemicals
Pentane Market
Petrochemicals
Aliphatic Hydrocarbon Market
Petrochemicals
Basic Petrochemical Market