
 Anti-Tacking Agents Market | 2026-2036
Anti-Tacking Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Tacking Agents Market Analysis
The premium silicone and fluoropolymer tier is consolidating around high-purity grades for electronics and medical films, while commodity polyethylene and polypropylene grades compete on bulk pricing for packaging. Croda International leverages its lipid chemistry expertise to sustain differentiation in emulsion-based delivery systems. Peter Greven GmbH anchors European supply through specialized metal soap derivatives. King Industries competes on liquid concentrate formulations for coatings integrators.
Anti-tacking agents are surface-active compounds, typically comprising fatty acid derivatives, metallic soaps, or polymer dispersions, engineered to prevent adhesion between rubber or polymer surfaces during processing and storage at temperatures ranging from ambient to vulcanization conditions. These materials function by forming a microscopically thin, low-surface-energy barrier that permits clean release without contaminating finished substrates. Silicone formulations command margin pools in electronics and medical applications where outgassing specifications are stringent, while polyethylene powders dominate volume in tire and conveyor belt manufacturing. Liquid concentrates are gaining share among adhesive compounders seeking automated dosing compatibility, whereas emulsion forms retain preference in waterborne coating systems.
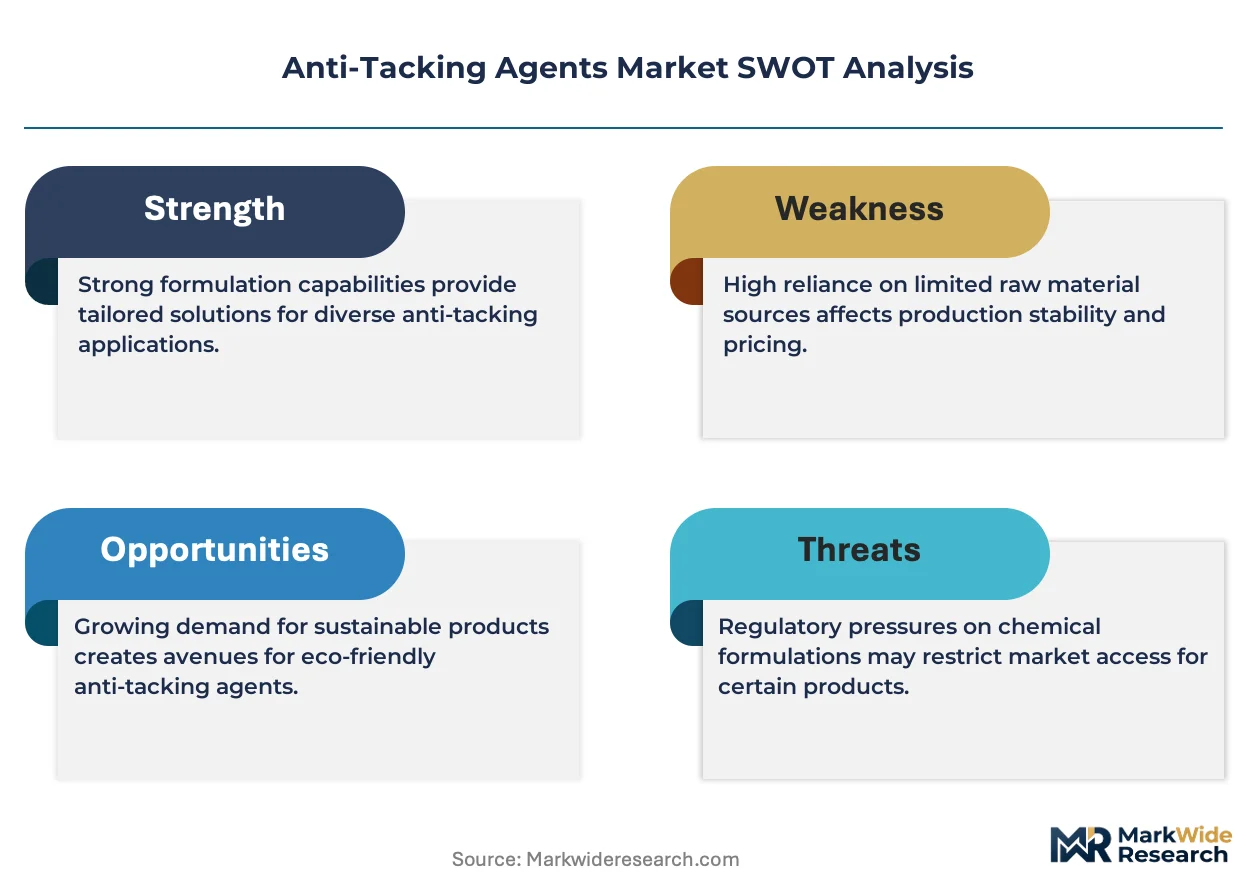
EPA oversight of volatile organic compound emissions shapes formulation chemistry in US coatings applications, while REACH registration requirements in Europe restrict certain metallic soap compositions and drive substitution toward polymer-based alternatives. China's SAMR enforces GB standards for food-contact materials that limit migratable substances in packaging-grade anti-tacking agents. Stakeholders must monitor regulatory divergence between jurisdictions when designing unified product platforms, as compliance in one geography no longer guarantees market access in another.
Market Dynamics
REACH registration requirements in Europe are forcing systematic reformulation away from metallic soap compositions toward polymer-based alternatives, while tire manufacturers in Asia-Pacific accelerate silicone-based agent uptake for high-performance rubber processing.
Growth Catalysts
- Automotive rubber processing corridor expansion:China's tire manufacturing clusters in Shandong and Jiangsu provinces drive concentrated demand for polyethylene powder grades in conveyor belt and tire production.
- REACH compliance substitution effect:ECHA registration deadlines for metallic soap derivatives push European compounders toward fluoropolymer and silicone alternatives with cleaner toxicological profiles.
- Electronics outgassing specifications:Medical film and semiconductor packaging applications require high-purity silicone grades that command sustained margin pools above commodity segments.
Market Restraints
- Palm oil and fatty acid feedstock volatility:Croda International and Peter Greven GmbH face margin compression when vegetable oil markets spike, as lipid chemistry anchors emulsion-based delivery systems.
- Silicone supply concentration:Specialty silicone fluid production clusters in Germany and Japan create geographic chokepoints for electronics-grade anti-tacking agents.
- Fluoropolymer technical limitations:PTFE-based formulations exhibit poor compatibility with certain polar rubber matrices, restricting application scope in nitrile and neoprene processing.
Strategic Opportunities
- Waterborne coating systems penetration:Emulsion-form anti-tacking agents retain preference among adhesive compounders seeking automated dosing compatibility in North American and European facilities.
- India automotive manufacturing scale-up:PLI scheme incentives for tire and rubber component production create virgin demand territory for metallic soap and polymer dispersion suppliers.
- Dual carbon goals alignment:China's MEE enforcement of lower-VOC processing standards favors waterborne emulsion technologies over solvent-based metallic soap alternatives.
Industry Challenges
- Cross-jurisdictional compliance engineering:Formulators must maintain parallel product platforms as EPA VOC rules, REACH substance restrictions, and SAMR GB standards diverge on migratable substance limits.
- High-purity certification timelines:Electronics and medical film grades require extended validation cycles for outgassing and biocompatibility testing, stretching working capital cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Tacking Agents Market |
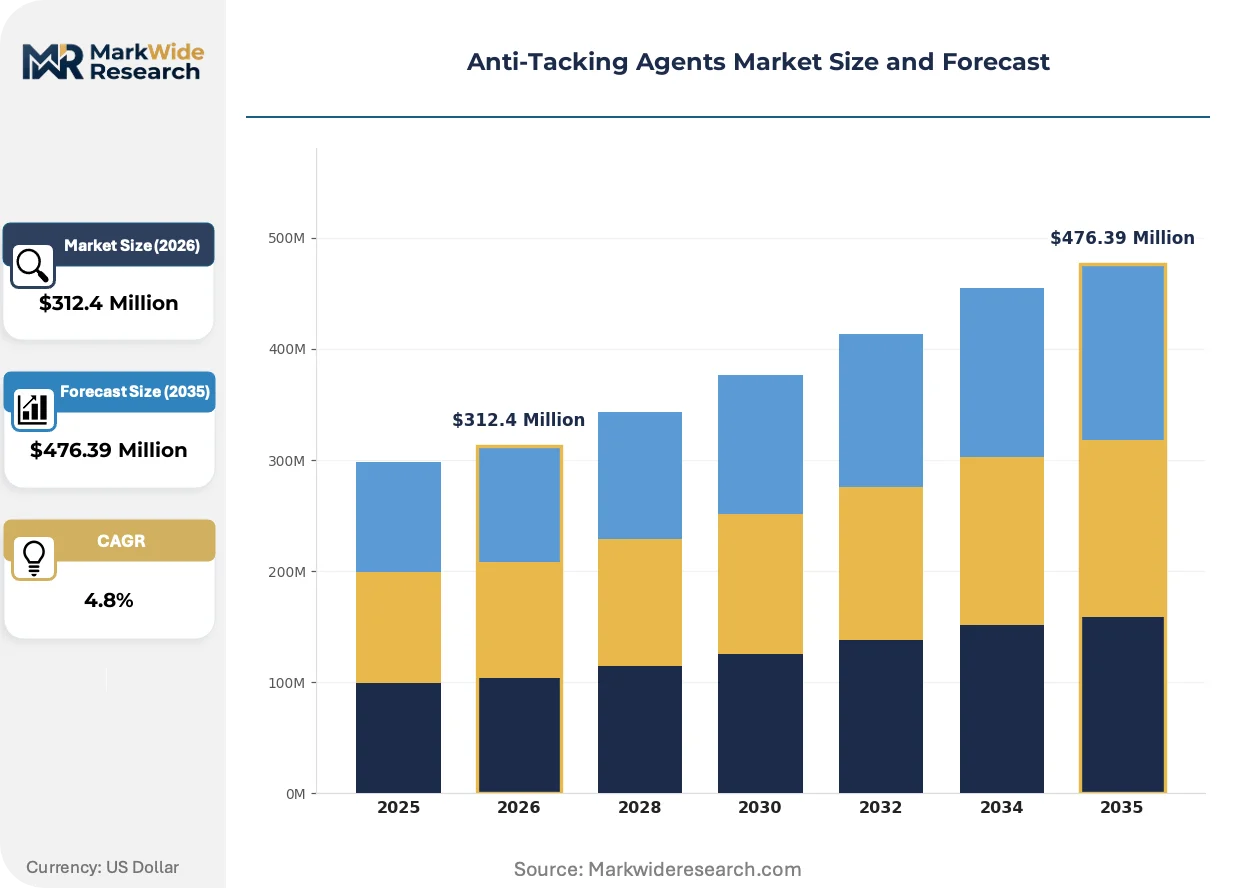
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone, Polyethylene, Polypropylene, Fluoropolymers End Use Industry: Packaging, Automotive, Textile, Electronics Form: Liquid, Powder, Emulsion, Concentrate Application: Coatings, Adhesives, Sealants, Films |
| Companies Covered | Lion Specialty Chemicals, Croda International, King Industries, Evonik Industries, H.L. Blachford, Peter Greven GmbH, Lanxess, FACI SPA, Struktol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Tacking Agents Market Emerging Trajectories
Formulation chemistry is pivoting toward waterborne and low-emission delivery systems as regulatory pressure compounds, while digital dosing infrastructure reshapes how compounders specify and procure anti-tacking agents.
Liquid concentrate technologies are decentralizing procurement and inventory management for mid-scale adhesive compounders. These pumpable formulations enable automated metered dosing without powder handling infrastructure. King Industries and regional distributors report accelerated uptake among North American coatings integrators seeking just-in-time replenishment.
REACH authorization procedures for zinc stearate and related metallic soaps are compressing formulation freedom for European rubber processors. ECHA's sunset date enforcement pushes compounders toward calcium-based and polymer dispersion alternatives. Tire manufacturers in Germany and Poland face reformulation costs while Asian exporters to Europe must certify alternative compositions.
Specification consolidation among tier-one automotive suppliers is compressing approved vendor lists for tire and rubber component manufacturers. Procurement teams at Continental, Bridgestone, and Michelin operations now mandate unified global formulations rather than region-specific grades. This concentration is visible most acutely in Thailand and Indonesia, where tire export platforms must satisfy simultaneous EPA, REACH, and SAMR compliance for multi-destination shipments.
Anti-Tacking Agents Market Segmentation
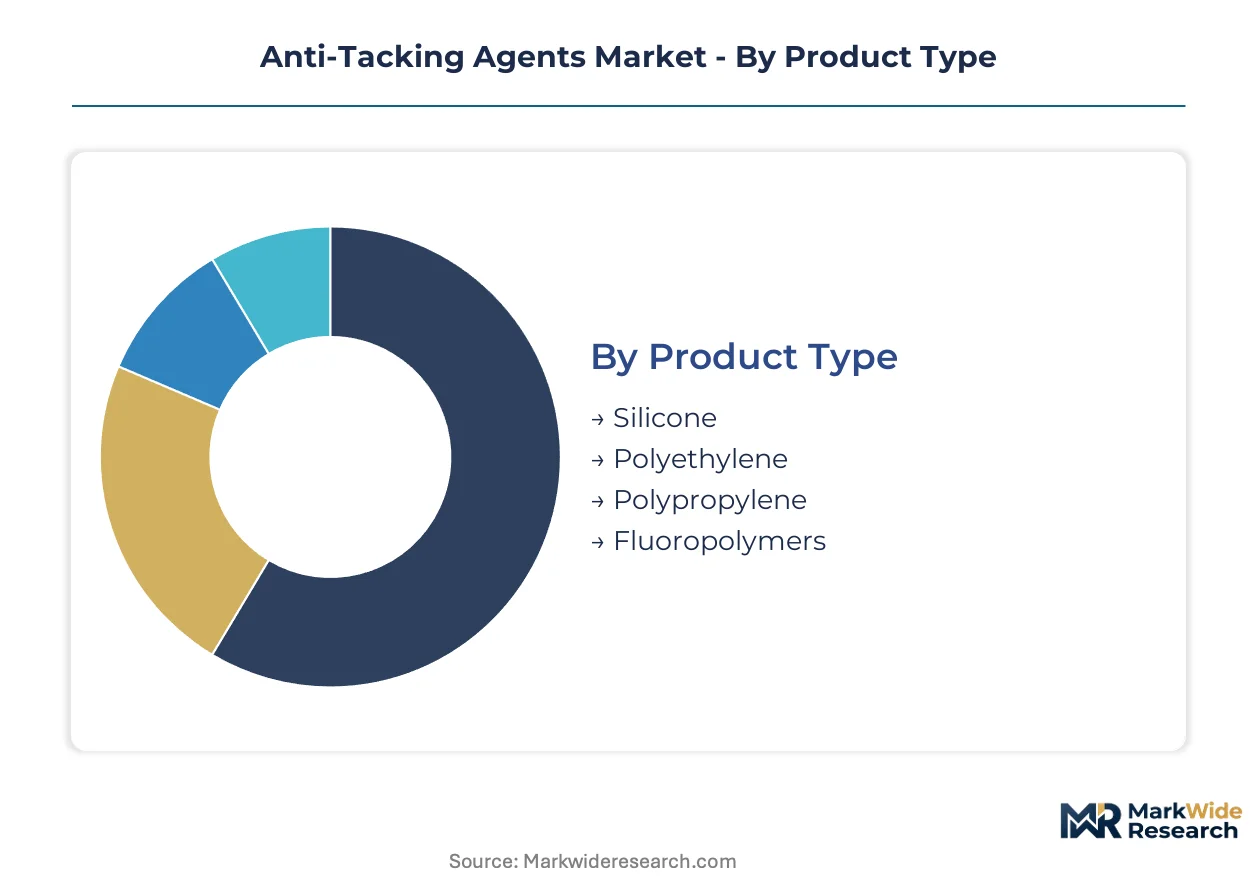
Anti-tacking agents fragment across four intersecting dimensions that determine specification, pricing, and procurement channels. Product chemistry dictates performance ceilings in regulated applications. Form selection shapes dosing infrastructure requirements and inventory economics for compounders.
Product Type:
Specialty fluid production clusters in Germany and Japan concentrate supply for high-purity grades, while commodity polymer powders distribute through regional compounding networks.
- Silicone:Polydimethylsiloxane-based formulations provide ultra-low surface energy barriers with minimal outgassing. Electronics manufacturers in Japan and semiconductor packaging facilities in South Korea specify these grades for wafer handling and medical film production where volatile organic compound limits are stringent.
- Polyethylene:Micronized polyethylene waxes dominate volume in tire manufacturing clusters across China and Thailand. Shandong province rubber processors favor these powders for conveyor belt and tire tread release applications where cost efficiency outweighs premium performance requirements.
- Polypropylene:Higher melting point than polyethylene alternatives suits elevated-temperature processing lines in automotive underhood components.
- Fluoropolymers:PTFE dispersions serve niche electronics and chemical processing equipment markets requiring extreme chemical inertness.
Today's leader: Polyethylene. Tomorrow's challenger: Silicone.
End Use Industry:
Automotive rubber processing corridors generate concentrated demand spikes, while electronics specifications pull margin toward certified high-purity tiers.
- Automotive:Tire and rubber component manufacturing in Jiangsu and Shandong provinces, plus Thailand export platforms, consumes bulk polyethylene and metallic soap grades. Continental and Bridgestone procurement teams mandate unified formulations across multi-destination shipments, compressing approved vendor lists.
- Electronics:Semiconductor packaging and flexible circuit manufacturing in South Korea and Japan require silicone grades with sub-ppm outgassing certification. Extended validation cycles stretch working capital for suppliers seeking entry.
- Packaging:Food-contact film producers navigate China's SAMR GB standards for migratable substance limits.
- Textile:Synthetic fiber processing lines favor emulsion-form agents for waterborne finishing compatibility.
Automotive anchors present volume. Electronics commands future margin expansion.
Form:
Liquid concentrate technologies are gaining share among adhesive compounders seeking automated dosing compatibility, while powder forms retain dominance in high-volume rubber processing.
- Liquid:Pumpable formulations enable metered dosing without powder handling infrastructure. North American coatings integrators favor these for just-in-time replenishment and reduced dust exposure compliance.
- Powder:Free-flowing polyethylene and metallic soap powders dominate tire manufacturing in Asia-Pacific where bulk handling equipment is standardized.
- Emulsion:Waterborne systems align with China's MEE enforcement of lower-VOC processing standards.
- Concentrate:High-solids formulations reduce freight costs for remote rubber processing facilities.
Liquid concentrates are climbing the fastest in North American and European facilities. Powder retains infrastructure lock-in across Asia-Pacific.
Application:
Coatings and adhesives specifications diverge sharply between solvent-borne legacy systems and waterborne reformulation trends.
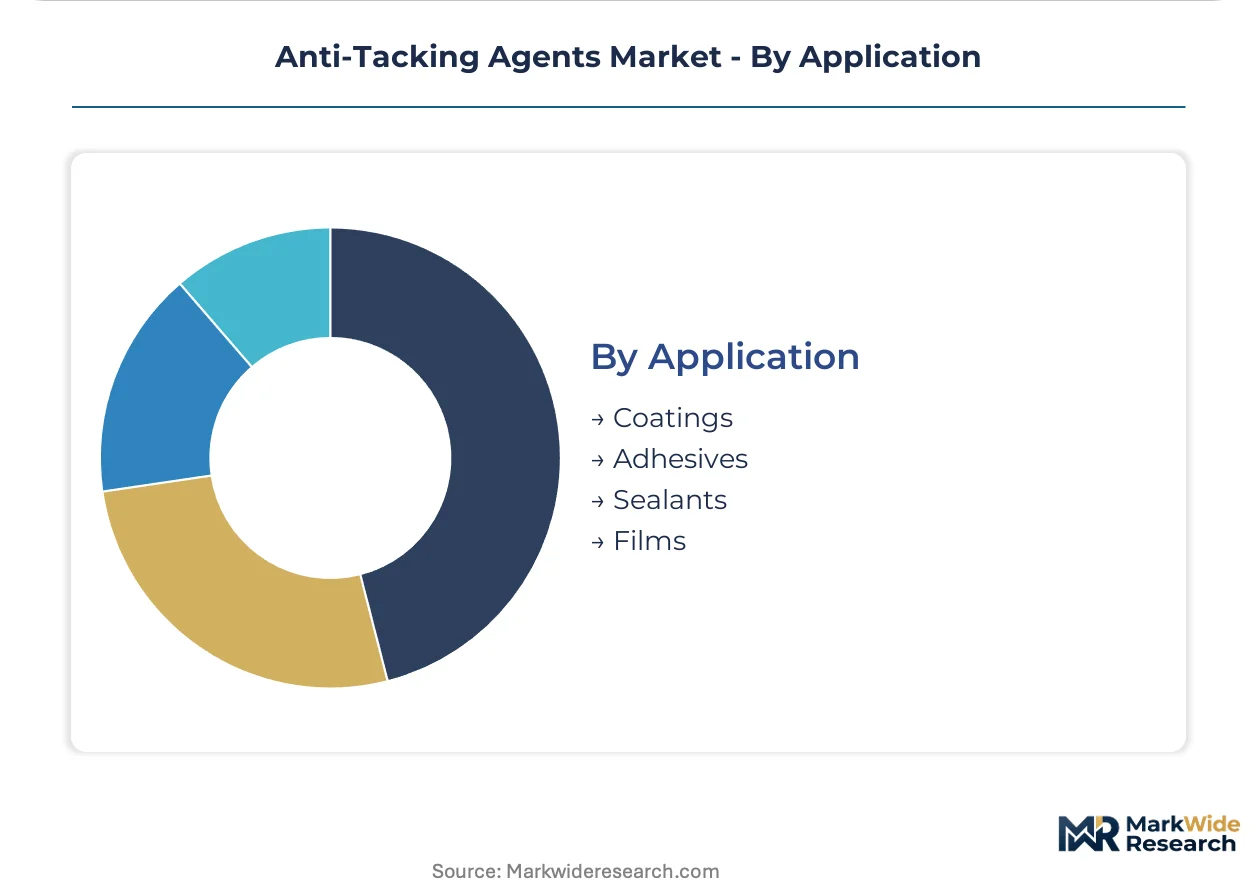
- Coatings:Architectural and industrial coatings compounders in Europe face REACH-driven substitution away from zinc stearate toward polymer dispersions. EPA VOC rules in the US reinforce similar reformulation pressure.
- Adhesives:Pressure-sensitive adhesive manufacturers specify liquid concentrates for automated production lines. Emulsion forms retain preference in waterborne systems for tape and label applications.
- Sealants:Construction and automotive sealant producers balance cure speed requirements with surface release needs.
- Films:Medical and food-contact films demand high-purity silicone or fluoropolymer grades with biocompatibility certification.
Coatings drive regulatory reformulation urgency. Films concentrate premium pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized chemical formulation talent clusters in Germany's industrial corridor and China's eastern manufacturing belt anchor regional supply capabilities for anti-tacking agent production.
China
Tire manufacturing clusters in Shandong and Jiangsu provinces drive concentrated polyethylene powder consumption for conveyor belt and tread release applications. SAMR enforces GB standards for food-contact materials that limit migratable substances in packaging-grade formulations. Qingdao and Yantai rubber processing facilities are expanding silicone-based agent uptake to meet export certification requirements for European and North American automotive customers.
Germany
Automotive rubber component manufacturers in North Rhine-Westphalia and Bavaria face systematic reformulation away from zinc stearate metallic soaps. ECHA REACH authorization deadlines for metallic soap derivatives push compounders toward fluoropolymer and silicone alternatives with cleaner toxicological profiles. Cologne and Leverkusen specialty chemical production clusters concentrate high-purity silicone fluid supply for electronics-grade applications.
United States
Pressure-sensitive adhesive manufacturers in Ohio and Illinois specify liquid concentrates for automated production line compatibility. EPA oversight of volatile organic compound emissions shapes formulation chemistry in coatings applications across the Midwest and Southeast. Automotive rubber processing facilities in Michigan and South Carolina are consolidating approved vendor lists to satisfy multi-destination export compliance.
Japan
Semiconductor packaging and flexible circuit manufacturers in Kyushu and Kansai regions require silicone grades with sub-ppm outgassing certification. METI industrial standards align with international electronics specifications for wafer handling applications. Osaka and Fukuoka production clusters stretch working capital cycles through extended validation requirements for medical film and electronics-grade certification.
India
Tire and rubber component producers in Maharashtra and Gujarat are scaling capacity under PLI scheme incentives for automotive manufacturing. BIS standards for industrial chemical grades create domestic certification requirements for metallic soap and polymer dispersion suppliers. Pune and Ahmedabad rubber processing corridors represent virgin demand territory as export-oriented production platforms mature.
Anti-Tacking Agents Market Vendor Landscape
Top-tier vendors anchor premium silicone and fluoropolymer grades for electronics and medical applications, while mid-scale specialists compete on emulsion-based delivery systems and liquid concentrate formulations for coatings integrators. The vendor base stratifies across chemistry expertise, with lipid chemistry specialists, metal soap derivative producers, and polymer dispersion formulators occupying distinct competitive positions. Three archetypes dominate: chemistry-anchored innovators leveraging proprietary formulation knowledge, scale-driven commodity producers competing on bulk polyethylene and polypropylene powder volumes, and application-focused integrators specializing in automated dosing compatibility. Capacity expansion and geographic certification acquisition represent the dominant competitive moves as stakeholders seek multi-jurisdictional compliance coverage.
Within the chemistry-anchored tier, Croda International exemplifies lipid-based emulsion expertise, while Peter Greven GmbH occupies a position among European metal soap derivative specialists. King Industries represents the application-focused archetype through liquid concentrate formulation capabilities. These three entities illustrate how competitive positioning fragments across technical specialization rather than consolidating around unified product platforms.
| Leading Market Players |
|---|
| Lion Specialty Chemicals |
| Croda International |
| King Industries |
| Evonik Industries |
| H.L. Blachford |
| Peter Greven GmbH |
| Lanxess |
| FACI SPA |
| Struktol |
| Others |
Supply Flow & Price Mechanics
Tier-one tire manufacturers in Shandong and Jiangsu provinces negotiate polyethylene powder contracts on volume-scaled spot pricing with quarterly adjustments, embedding feedstock pass-through clauses that shift palm oil and fatty acid volatility risk onto specialty chemical suppliers.
Pricing Analysis
Unbundled raw material supply dominates commodity polyethylene and metallic soap transactions, while bundled technical service contracts support silicone and fluoropolymer premium tiers. Three-tier pricing structure across electronics-grade silicone, automotive-standard polyethylene, and economy metallic soap segments reflects certification burden and purity thresholds. Pricing pressure stems from palm oil feedstock volatility squeezing emulsion-based delivery margins. Mid-scale adhesive compounders exhibit highest price sensitivity, whereas semiconductor packaging facilities prioritize outgassing compliance over unit cost.
Supply Chain Analysis
REACH registration and electronics-grade outgassing certification gate European and Japanese market access, concentrating high-purity silicone fluid production in Germany and Japan while commodity polyethylene powders distribute through China's eastern manufacturing belt. Specialty chemical supply draws from palm oil derivatives, metallic soap precursors, and silicone monomer feedstocks. Single-source vulnerability clusters in German and Japanese specialty fluid production create geographic chokepoints for electronics-grade agents. Distribution runs through regional compounding networks with direct mill supply relationships for tire manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REACH authorization deadlines for zinc stearate and related metallic soaps systematically displace legacy formulations toward polymer-based alternatives.
For Market Incumbents: Extend certification coverage across REACH, EPA VOC, and SAMR GB standards to capture tier-one automotive supplier consolidation. Deepen backward integration into silicone monomer supply to offset specialty fluid production chokepoints in Germany and Japan. Anchor European market position through fluoropolymer alternative portfolios as metallic soap sunset dates approach. For New Entrants and Emerging Players: Mid-scale waterborne coating compounders in North America represent an underserved buyer archetype seeking automated dosing compatibility without powder handling infrastructure. Target liquid concentrate formulation partnerships with regional distributors serving Ohio and Illinois adhesive manufacturers. Penetrate India's Maharashtra and Gujarat rubber processing corridors under PLI scheme scale-up before incumbent certification barriers solidify. For Investors and Strategic Acquirers: Specialty chemical conglomerates with existing REACH registration infrastructure are the most active acquirers in this space, seeking lipid chemistry and metal soap derivative capabilities to fill portfolio gaps. Long-term viability hinges on multi-jurisdictional compliance coverage rather than single-market dominance. Monitor ECHA authorization timeline enforcement as the inflection signal for metallic soap displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Reformulation Program | European compounders substitute zinc stearate with calcium-based and polymer dispersion alternatives before ECHA sunset dates. |
| Silicone Fluid Backward Integration | German and Japanese production clusters secure captive monomer supply against electronics-grade demand concentration. |
| Liquid Concentrate Distribution Partnership | North American coatings integrators adopt pumpable formulations for just-in-time replenishment without powder infrastructure. |
| India PLI Corridor Market Entry | Maharashtra and Gujarat tire manufacturers scale capacity under automotive manufacturing incentives, creating virgin demand territory. |
| Multi-Jurisdictional Certification Acquisition | Unified EPA, REACH, and SAMR compliance enables tier-one automotive supplier vendor list consolidation. |
Methodological Framework
Bottom-up rubber processing and coatings application modeling reconciled against top-down specialty chemical production tracking forms the analytical core of this study. Primary interviews with tire manufacturing procurement leads, adhesive compounder technical directors, and specialty chemical plant managers combined with secondary validation from ECHA registration databases, SAMR GB standard filings, and customs trade data. SEC 10-K disclosures from lipid chemistry and metal soap derivative specialists provided financial triangulation against volume estimates.
Historical trendline analysis across silicone, polyethylene, polypropylene, and fluoropolymer product categories established baseline growth patterns. Segmentation modeling incorporated product chemistry, end-use industry, physical form, and application dimensions across the projection horizon. CAGRs derived from weighted average of end-use demand trajectories and supply-side capacity announcements, with specific inputs from automotive rubber processing corridor expansion rates and electronics outgassing specification adoption curves.
Underlying measurement precision varies by segment; electronics-grade silicone and medical film certifications carry tighter precision than commodity polyethylene powder volumes. Forecasts reflect assumptions on regulatory enforcement timelines and feedstock price stability. A model refresh is warranted upon material change in ECHA authorization sunset date enforcement or palm oil derivative supply disruption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Capillary Underfill Material Market
Adhesives & Sealants
US Tile Adhesive Market
Adhesives & Sealants
Europe Adhesives Market
Adhesives & Sealants
Asia-Pacific Waterborne Adhesives Market
Adhesives & Sealants
Restorative Materials and Bonding Agents Market
Adhesives & Sealants
United Kingdom Hot-Melt Adhesives Market
Adhesives & Sealants
Acrylic Glue Market
Adhesives & Sealants
Light Curing Adhesives Market
Adhesives & Sealants
Adhesives and Sealants Market
Adhesives & Sealants
Foam Adhesive Market
Adhesives & Sealants
Flexible Packaging Adhesive Market
Adhesives & Sealants
Acrylate Market
Adhesives & Sealants
Asia-Pacific Automotive Adhesives and Sealants Market
Adhesives & Sealants
Europe Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Global Isononyl Acrylate Market
Adhesives & Sealants
Middle East and Africa Epoxy Curing Agents Market