
 Global Polypropylene Market | 2026-2036
Global Polypropylene Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polypropylene Market Outlook
Specialty compound formulation revenue is reshaping margin capture across the polypropylene value chain, as producers seek refuge from commoditized homopolymer pricing. LyondellBasell Industries Holdings B.V. leverages its Spheripol and Spherizone process licensing to command technology premiums in differentiated grades. SABIC anchors its position through backward integration into propane dehydrogenation and regional petrochemical complexes. INEOS competes via disciplined capital allocation across European and North American production hubs.
Polypropylene is a semi-crystalline thermoplastic polymer synthesized from propylene monomer via Ziegler-Natta or metallocene catalysis, with melt flow indices spanning 0.3 to 1000 g/10 min and density near 0.90 g/cm³, serving primarily as a lightweight, chemically resistant substitute for metals and engineering plastics in molded and fiber applications. Homopolymer grades dominate volume flows into rigid packaging and textile filaments where stiffness and heat resistance justify trade-offs in impact performance. Copolymer formulations, particularly random copolymers, are gaining share in healthcare and consumer goods applications demanding optical clarity and flexibility at low temperatures. Block copolymer architectures occupy the structural segment for automotive battery housings and appliance components requiring balanced stiffness and toughness.
REACH registration requirements in Europe and China's GB standards for food-contact plastics are elevating testing burdens and restricting certain catalyst residue thresholds, compelling producers to certify supply chains for medical and food-grade offtake. The US FDA maintains stringent extraction protocols for healthcare applications, creating segmented qualification pathways that filter supplier pools. Stakeholders must monitor feedstock cost spreads between naphtha and propane routes while positioning for circular economy mandates that will redefine acceptable recycled content thresholds across major economies.
Market Dynamics
Automotive lightweighting mandates are forcing resin substitution at scale, as OEMs redesign bumper systems and interior panels to meet fuel efficiency targets. This structural pull is concentrating investment in high-flow copolymer grades and advanced compounding capabilities.
Growth Catalysts
- EU REACH chemical frameworks:Evolving registration requirements are redirecting capital toward recycled and bio-based feedstock certification, opening qualified supply chains for medical and food-grade offtake.
- India packaging sector expansion:Infrastructure build-out and consumer goods growth are drawing new compounding capacity to serve rigid packaging and textile filament demand.
- Propane dehydrogenation integration:Backward integration into PDH units is collapsing feedstock cost volatility for producers with captive propylene supply.
Market Restraints
- Naphtha-propane spread volatility:Feedstock cost differentials between steam cracker and PDH routes are compressing margins for non-integrated producers.
- China dual carbon enforcement:Emissions intensity caps are restricting new coal-to-olefins capacity additions and raising compliance costs for existing assets.
- Engineering plastics substitution:Polyamide and polycarbonate blends are displacing block copolymers in high-heat automotive underhood applications.
Strategic Opportunities
- Battery housing applications:Electric vehicle platform architectures are creating specification windows for flame-retardant compounded grades with thermal management properties.
- US IRA clean manufacturing credits:Domestic content incentives are reshaping investment location decisions for recycled polypropylene production.
- Healthcare optical clarity demand:Random copolymer formulations are capturing share in diagnostic device housings and pharmaceutical packaging.
Industry Challenges
- Metallocene catalyst licensing complexity:Proprietary Ziegler-Natta process patents and metallocene royalty structures are constraining formulation flexibility for mid-scale compounders.
- Recycled content certification timelines:FDA extraction protocols and EU EFSA food-contact approvals for post-consumer resin are extending qualification cycles by 18-24 months.
- Compounding talent scarcity:Formulation chemistry and rheology expertise gaps are limiting speed-to-market for specialty grade development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polypropylene Market |
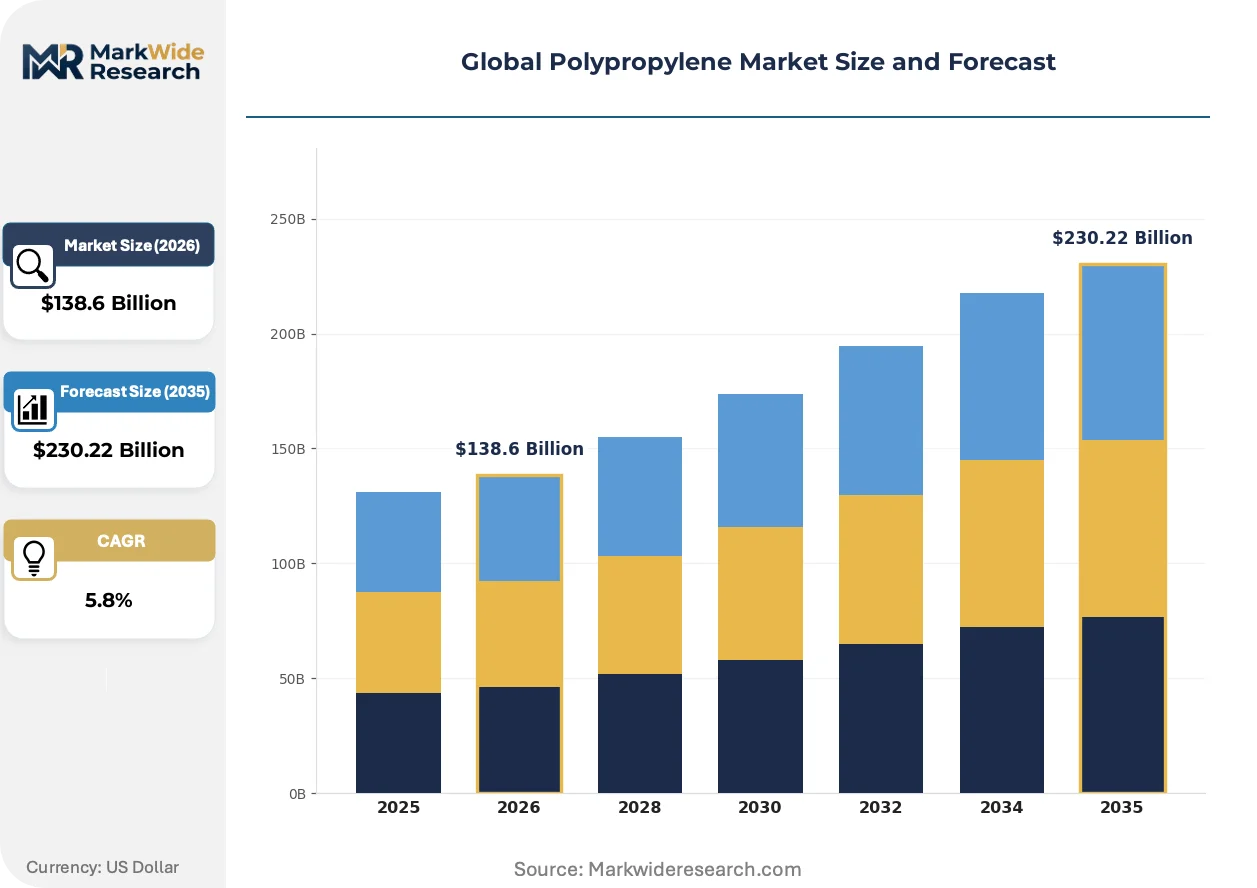
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $230.22 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Homopolymer, Copolymer, Random Copolymer, Block Copolymer Application: Automotive, Packaging, Textiles, Consumer Goods End Use Industry: Aerospace, Construction, Electronics, Healthcare Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | LyondellBasell Industries Holdings B.V., SABIC, ExxonMobil Chemical, INEOS, Borealis AG, TotalEnergies, Reliance Industries Limited, Formosa Plastics Corporation, LG Chem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polypropylene Market Strategic Shifts
Process intensification and molecular architecture control are redefining performance boundaries across homopolymer, random, and block copolymer categories. These advances are compressing traditional grade hierarchies.
Advanced reactor configurations using dual-reactor cascade designs are collapsing the performance gap between standard impact copolymers and premium engineered grades. Tier-one automotive suppliers are qualifying these materials for battery tray and structural bracket applications previously reserved for reinforced polyamides. The cost-positioning advantage is forcing engineering resin producers to defend share through alloy development rather than base polymer performance.
China's GB standards for food-contact plastics and evolving catalyst residue thresholds are elevating testing burdens across Asian supply chains. Producers must now certify supply chains for heavy metal content and oligomer migration limits to serve medical and food-grade offtake. The compliance burden is filtering supplier pools and creating tiered qualification pathways that favor integrated producers with in-house analytical capabilities.
Direct procurement relationships between automotive OEMs and resin producers are disintermediating traditional distribution channels for specialty compounded grades. Tier-one suppliers are negotiating specification control directly with LyondellBasell and SABIC for bumper and interior programs. The channel compression is most visible in Germany and the US Midwest, where just-in-sequence delivery requirements favor localized compounding operations with OEM-proximate logistics.
Global Polypropylene Market Segmentation
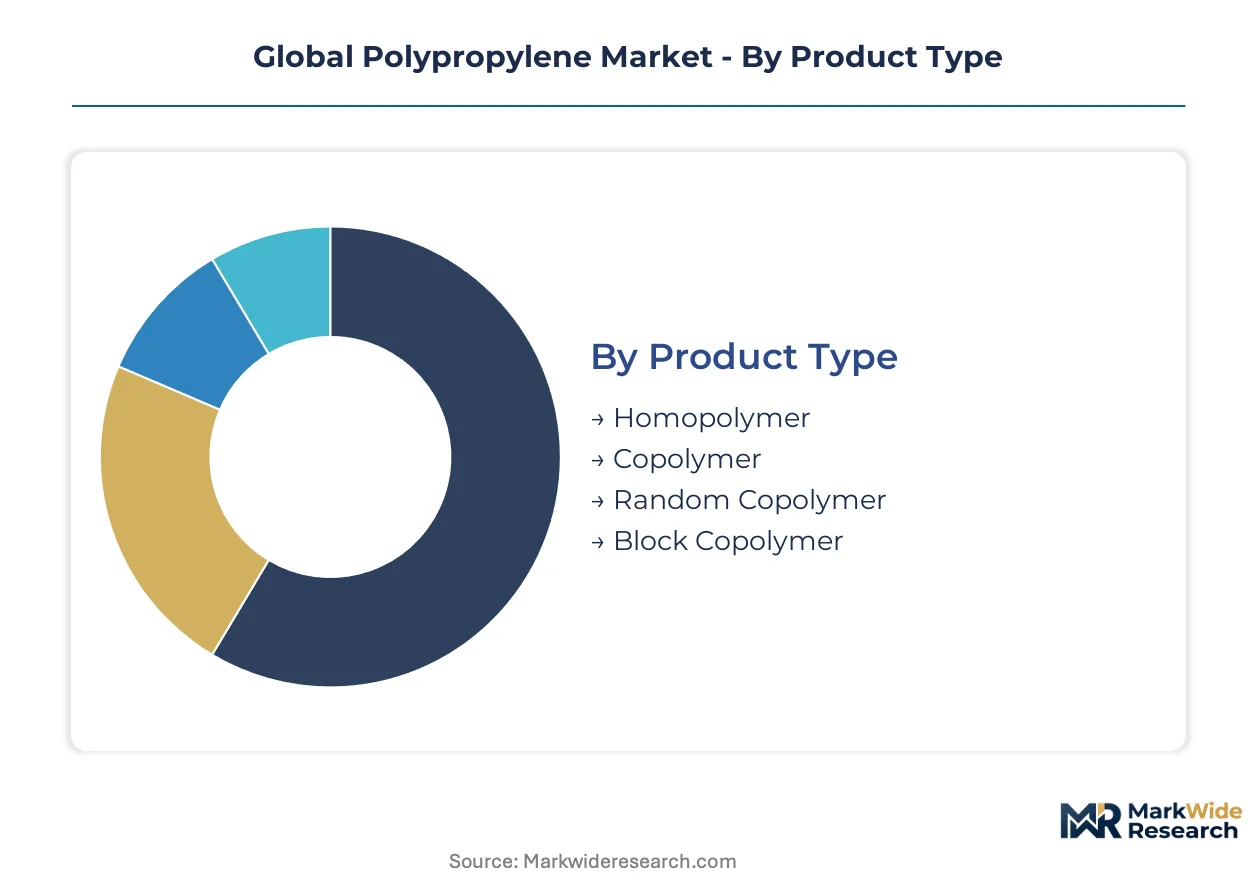
Polypropylene market segmentation reflects divergent margin structures across molecular architectures and end-use specifications. Producers allocate reactor capacity and catalyst selection based on price realization potential rather than volume throughput alone.
Product Type:
Cost tier differentiation separates commodity homopolymer flows from specialty copolymer grades commanding formulation premiums.
- Homopolymer:Single-phase crystalline structure delivers maximum stiffness and heat resistance for rigid packaging and textile filament spinning. Demand concentrates in India's expanding woven sack and flexible intermediate bulk container sector where infrastructure build-out sustains volume offtake. FDA extraction protocols and EU REACH catalyst residue thresholds filter supplier pools for food-grade certification.
- Copolymer:Dual-phase morphology balances stiffness with impact resistance through ethylene incorporation. Automotive battery housing applications in Germany and the US Midwest are qualifying flame-retardant compounded variants for electric vehicle platforms. China's GB standards for food-contact plastics elevate testing burdens for medical-grade supply chains.
- Random Copolymer:Statistical ethylene distribution yields optical clarity and flexibility at reduced temperatures for healthcare diagnostic housings.
- Block Copolymer:Segmented architecture delivers structural toughness for appliance components and automotive brackets requiring load-bearing performance.
Homopolymer holds installed capacity. Copolymer is rotating up the share rankings.
Application:
Application-based segmentation tracks how performance specifications reshape procurement relationships between resin producers and tier-one molders.
- Automotive:Lightweighting mandates are accelerating resin substitution in bumper systems and interior panels as OEMs redesign platforms for fuel efficiency compliance. NHTSA corporate average fuel economy standards and EU CO₂ fleet emission targets concentrate investment in high-flow grades with just-in-sequence delivery requirements in Stuttgart and Detroit metro corridors.
- Packaging:Rigid container demand in India's consumer goods sector draws new compounding capacity for thin-wall injection molding and thermoforming applications. EU EFSA food-contact approvals and FDA extraction protocols extend qualification cycles for post-consumer recycled content.
- Textiles:Filament spinning for industrial fabrics and nonwoven hygiene applications sustains homopolymer volume flows.
- Consumer Goods:Durables and houseware applications favor clarified random copolymers with aesthetic surface finish requirements.
Packaging commands volume leadership. Automotive is climbing the fastest on value per ton metrics.
End Use Industry:
Industry verticals impose distinct certification burdens that stratify supplier qualification pathways.
- Aerospace:Flame-retardant and low-smoke specifications for cabin interior components require extensive OEM qualification cycles with Boeing and Airbus supply chains.
- Construction:Geotextiles and piping systems demand UV-stabilized grades with long-term durability certification for infrastructure projects.
- Electronics:Miniaturized connector housings and thermal management components favor high-flow copolymers with precise dimensional stability.
- Healthcare:Random copolymer formulations are capturing share in pharmaceutical packaging and diagnostic device housings where optical clarity and sterilization compatibility intersect. US FDA maintains stringent extraction protocols that create segmented supplier pools filtering toward integrated producers with in-house analytical capabilities.
Healthcare holds specification premiums. Electronics is gaining share fastest on miniaturization trends.
Distribution Channel:
Channel structure reflects the disintermediation pressure from direct OEM-producer relationships versus traditional distributor networks.
- Online Retail:Digital platforms serve spot market procurement for small-volume compounders and specialized processors seeking rapid material qualification.
- Direct Sales:Tier-one automotive suppliers negotiate specification control directly with resin producers for bumper and interior programs. LyondellBasell and SABIC maintain dedicated account structures for German and US Midwest OEM-proximate compounding operations.
- Distributors:Regional stockholding networks sustain just-in-time delivery for mid-scale processors without captive logistics infrastructure.
- Wholesalers:Volume aggregation serves commodity homopolymer flows to textile spinners and packaging converters with predictable demand patterns.
Direct sales holds margin capture. Online retail is expanding most quickly on small-lot flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Indian packaging converters exhibit acute price sensitivity to naphtha-propane spreads, while German automotive OEMs prioritize specification compliance over feedstock cost differentials. Chinese buyers occupy the middle ground, balancing dual carbon compliance with volume scale.
China
Coal-to-olefins capacity additions face tightening emissions intensity caps under dual carbon enforcement. MEE regulations restrict new project approvals in Inner Mongolia and Shanxi provinces. Yangtze River Delta compounders near Shanghai are pivoting toward bio-based feedstock certification to maintain medical-grade supply chain access.
Germany
Automotive battery housing demand concentrates in Stuttgart and Munich metro corridors for electric vehicle platform qualification. ECHA REACH registration requirements elevate testing burdens for catalyst residue thresholds. BASF's Ludwigshafen complex anchors European specialty copolymer formulation capacity with dedicated OEM-proximate logistics.
United States
Propane dehydrogenation integration along the Gulf Coast collapses feedstock cost volatility for producers with captive propylene supply. IRA clean manufacturing credits are reshaping investment location decisions for recycled polypropylene production. Detroit metro automotive suppliers negotiate direct specification control with resin producers for bumper and interior programs.
India
Infrastructure build-out and consumer goods expansion sustain woven sack and flexible intermediate bulk container demand. BIS standards for food-contact plastics filter supplier pools for heavy metal content certification. Gujarat's Dahej and Hazira industrial corridors attract new compounding capacity to serve rigid packaging converters.
Saudi Arabia
Backward integration into regional petrochemical complexes anchors export-oriented homopolymer production. SFDA pharmaceutical packaging standards create segmented qualification pathways for medical-grade offtake. Jubail Industrial City's integrated complexes supply high-volume flows to Asian and European textile spinners.
Global Polypropylene Market Competitive Environment
Capability concentration sits with integrated petrochemical majors possessing proprietary process licensing; scale advantage sits with regional producers leveraging feedstock proximity. The vendor base stratifies across three tiers: technology licensors commanding formulation premiums, PDH-integrated operators capturing feedstock margin, and regional compounders serving spot-market demand. Dominant competitive moves include strategic partnerships for recycled content certification and capacity expansion in India and China to capture packaging sector growth.
Within the technology licensor tier, LyondellBasell Industries Holdings B.V. and SABIC occupy positions defined by proprietary process platforms and backward integration depth. LyondellBasell represents the archetype of catalyst and reactor technology monetization through global licensing structures. SABIC exemplifies regional petrochemical integration extending from propane feedstock through differentiated grade production. INEOS sits within the European-North American hub operator category, disciplined capital allocation across production assets defining its competitive stance.
| Leading Market Players |
|---|
| LyondellBasell Industries Holdings B.V. |
| SABIC |
| ExxonMobil Chemical |
| INEOS |
| Borealis AG |
| TotalEnergies |
| Reliance Industries Limited |
| Formosa Plastics Corporation |
| LG Chem |
| Others |
Value Chain & Pricing Dynamics
Naphtha-propane spread volatility functions as the dominant risk vector that compresses margins for non-integrated producers while simultaneously concentrating supply chain control among PDH-integrated operators. This feedstock cost differential determines both the premium commanded by backward-integrated suppliers and the geographic clustering of compounding capacity near propylene production hubs.
Pricing Analysis
After-sales formulation services and technical support contracts drive lifetime value capture for specialty copolymer grades. Three-tier pricing structure across medical-certified, automotive-qualified, and commodity homopolymer levels separates value realization tiers. Cost compression in standard homopolymer flows is intensifying because Indian packaging converters exhibit acute price sensitivity to feedstock spreads. Automotive OEMs in Germany and the US Midwest demonstrate least price sensitivity, prioritizing specification compliance and just-in-sequence delivery reliability over unit cost differentials.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for compounders serving cross-border automotive programs. Production gravity centers on Saudi Arabia, China, and the United States as anchor supply points. Propylene monomer, catalyst systems, and compounding additives constitute the critical input dependencies. Single-source vulnerability concentrates around metallocene catalyst licensing controlled by technology licensors. Distribution runs through direct sales relationships for tier-one automotive suppliers and regional stockholding networks for mid-scale processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. REACH registration requirements and FDA extraction protocols create segmented qualification pathways that filter supplier pools and elevate switching costs for qualified offtake.
For Market Incumbents: Insulate formulation premium capture by deepening captive catalyst technology portfolios and expanding medical-grade certification infrastructure. Engineering plastics substitution in high-heat automotive underhood applications represents the most pressing substitute threat. Prioritize capacity addition in Gujarat's Dahej and Hazira corridors to anchor Indian packaging sector relationships.
For New Entrants and Emerging Players: Recycled polypropylene production capacity in US Gulf Coast locations benefiting from IRA clean manufacturing credits represents the most penetrable entry point. Battery housing applications for electric vehicle platforms offer specification windows with less entrenched incumbent relationships. Pursue direct qualification relationships with automotive OEMs rather than distributor channel penetration.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated operators with proprietary process licensing and captive feedstock supply. Long-term viability centers on positioning for circular economy mandates that will redefine acceptable recycled content thresholds. Target acquisition archetypes include regional compounders with established FDA or EU EFSA food-contact approvals. The signal to watch is qualification cycle extension timelines for post-consumer resin certification.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propane Dehydrogenation | Collapses feedstock cost volatility for producers with captive propylene supply. |
| Medical-Grade Certification Investment | Opens segmented qualification pathways filtering toward integrated producers with in-house analytical capabilities. |
| Recycled Content Production Scale-Up | Positions supply chains for EU EFSA and FDA extraction protocol compliance in post-consumer resin. |
| Direct OEM Specification Control | Disintermediates traditional distribution channels for specialty compounded grades in automotive programs. |
| Regional Compounding Capacity Expansion | Serves just-in-sequence delivery requirements in Stuttgart and Detroit metro corridors. |
Study Parameters
Cross-validation between primary interviews with plant managers, procurement leads at downstream OEMs, distribution channel partners, and technical R&D directors and secondary sources including customs and trade data, ACC and Cefic industry reports, and SEC 10-K filings anchors the qualitative findings. Bottom-up grade-level volume estimates and top-down macroeconomic demand drivers undergo iterative reconciliation. Continuous triangulation across data sources ensures analytical robustness.
Calibration against historical capacity utilization rates and feedstock cost spread relationships shapes the projection framework across the analysis window. Segmentation dimensions include molecular architecture tier, end-use industry vertical, certification grade, and regional production hub. CAGRs derive from regression-based demand elasticity modeling incorporating automotive lightweighting penetration curves and packaging sector growth trajectories. Propylene feedstock cost differentials and regulatory compliance burden indices serve as industry-specific forecast inputs.
Stress conditions across naphtha-propane spread volatility, dual carbon enforcement intensity, and engineering plastics substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding catalyst technology adoption curves and recycled content mandate implementation timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petrochemicals
Pentane Market
Petrochemicals
Fossil Fuel-Based Plastics Market
Petrochemicals
Global Methyl Tertiary Butyl Ether Market
Petrochemicals
Global Perfluorocarbons Market
Petrochemicals
Aliphatic Hydrocarbon Market
Petrochemicals
Propane Market
Petrochemicals
Chemical and Petroleum Containers Market
Petrochemicals
Global Butadiene Market
Petrochemicals
Bioisobutene Market
Petrochemicals
Light Olefins Market
Petrochemicals
Petrochemical Feedstock Market
Petrochemicals
Anthracene Oil Market
Petrochemicals
Alkylate Isooctane Market
Petrochemicals
Tert Butyl Hydroperoxide Market
Petrochemicals
Propylene Market
Petrochemicals
Flame-Retardant Polypropylene (PP) Market