
 High Purity Lignin Market | 2026-2036
High Purity Lignin Market Size, Share, and Industry Trends Forecast 2026-2036
High Purity Lignin Market Analysis
Modular formulation kits are repositioning buyer choice in high purity lignin procurement, letting compounders blend standardized lignin fractions with proprietary additives rather than purchasing finished systems. Borregaard ASA leverages its Norwegian biorefinery infrastructure to sustain captive kraft lignin supply chains. Ingevity Corporation differentiates through specialty chemicals integration, while UPM-Kymmene Oyj anchors Nordic pulp-to-lignin conversion at industrial scale.
High purity lignin denotes lignin fractions refined to greater than 90% purity with controlled molecular weight distribution, typically extracted through organosolv or alkaline processes and subsequently purified via membrane filtration or solvent fractionation; it functions primarily as a renewable aromatic polymer substitute in phenolic resins, carbon fiber precursors, and dispersant applications. Low molecular weight grades dominate current adhesive and coating formulations due to superior solubility and reactivity, while lignin derivatives represent the fastest-expanding category as sulfonated and hydroxymethylated variants unlock higher-value pharmaceutical and cosmetic applications. Powder form maintains the largest volume share across construction and agriculture end users, though liquid emulsions gain traction in waterborne coating systems.
EPA bio-based preferred procurement guidelines and REACH substance registration requirements shape product qualification pathways for lignin suppliers targeting North American and European industrial buyers. FDA indirect food contact regulations and ECHA polymer of low concern classifications further delineate market access tiers for pharmaceutical and packaging applications. Stakeholders must monitor evolving carbon border adjustment mechanisms and bio-based content certification standards to secure long-term offtake agreements.
Market Dynamics
Specialty adhesives manufacturers are expanding lignin-based formulations to replace petroleum-derived phenolic resins, driven by tightening chemical disclosure rules under REACH compliance and the EU Green Deal across European industrial clusters.
Growth Catalysts
- REACH substance registration requirements:Tightened chemical disclosure rules in Europe accelerate bio-based feedstock qualification for lignin suppliers targeting industrial buyers in Germany and France.
- Carbon fiber precursor applications:Organosolv extraction processes unlock high-purity lignin fractions for aerospace and automotive composite manufacturers seeking renewable aromatic polymer substitutes.
- Frankfurt-Hamburg industrial corridor:German construction-grade composite pilots concentrate demand for standardized lignin fractions with controlled molecular weight distribution.
Market Restraints
- Hardwood feedstock cost volatility:Kraft pulping input prices fluctuate with Nordic pulp mill capacity constraints, compressing margin structures for non-integrated compounders.
- Membrane filtration capex intensity:Solvent fractionation equipment requires substantial upfront investment, limiting entry for mid-scale purification operators.
- Petroleum phenolic resin substitution resistance:Established adhesive formulators in construction applications maintain incumbent supply contracts despite bio-based performance parity.
Strategic Opportunities
- Pharmaceutical lignin derivatives:Sulfonated and hydroxymethylated variants unlock higher-value cosmetic and drug delivery applications with limited current supplier penetration.
- Waterborne coating emulsions:Liquid lignin formulations gain traction as paint manufacturers reformulate for volatile organic compound reduction under EPA guidelines.
- EU Green Deal bio-based procurement mandates:Public sector preferred purchasing programs create dedicated offtake channels for certified high-purity lignin suppliers.
Industry Challenges
- ECHA polymer of low concern classification timelines:Extended substance evaluation periods delay market access for pharmaceutical and food-contact packaging applications.
- Organosolv process integration complexity:Legacy kraft lignin facilities face retrofitting costs and technical reconfiguration to achieve 90% purity thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Purity Lignin Market |
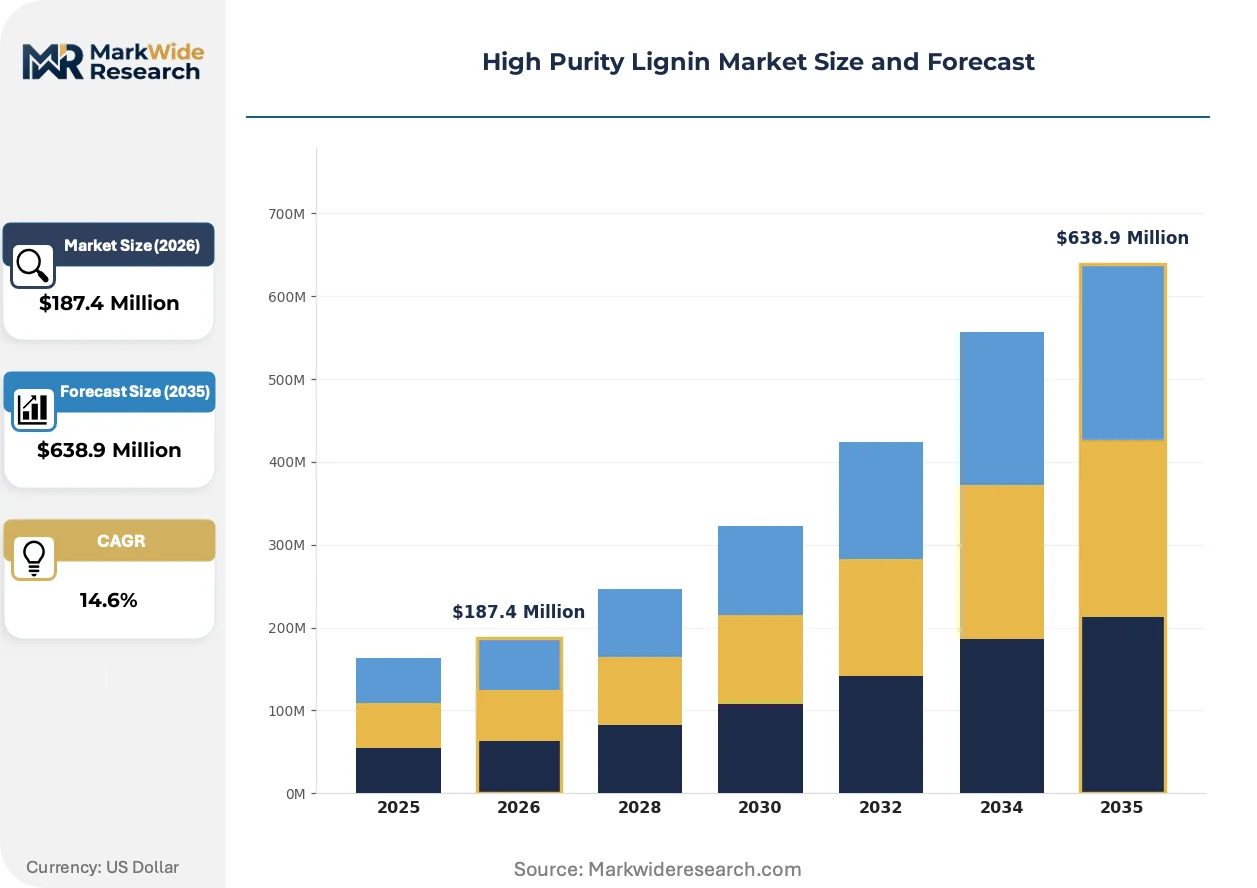
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Molecular Weight, Medium Molecular Weight, High Molecular Weight, Lignin Derivatives Application: Adhesives, Coatings, Plastic Composites, Cosmetics End User: Pulp & Paper, Pharmaceutical, Agriculture, Construction Form: Powder, Granules, Liquid, Emulsion |
| Companies Covered | Stora Enso Oyj, Suzano SA, Domtar Corporation, Borregaard ASA, West Fraser, Ingevity Corporation, Metsä Group, UPM-Kymmene Oyj, Sappi Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Purity Lignin Market Emerging Trajectories
Membrane filtration and solvent fractionation technologies are refining lignin purity thresholds while regulatory frameworks accelerate bio-based substitution in aromatic polymer supply chains.
Organosolv extraction systems are converging with alkaline purification workflows to yield lignin fractions exceeding 90% purity with narrow polydispersity indices. Specialty carbon fiber manufacturers in Germany and Japan are adopting these hybrid process outputs for precursor pitch substitution. The technology convergence is compressing the cost gap between bio-based and petroleum-derived aromatic feedstocks in aerospace composite applications.
EPA bio-based preferred procurement guidelines now mandate minimum renewable content thresholds for federal construction and packaging contracts. Industrial buyers must document feedstock origin and processing chain custody to maintain supplier eligibility. North American adhesive compounders are restructuring formulation portfolios to capture federal procurement preference margins.
Modular formulation kits are displacing finished lignin system purchases among mid-scale compounders seeking proprietary additive blending control. Standardized lignin fraction suppliers now compete directly with integrated formulators for buyer relationships. This pattern concentrates in German industrial clusters where construction composite manufacturers pilot flexible procurement models.
High Purity Lignin Market Segmentation
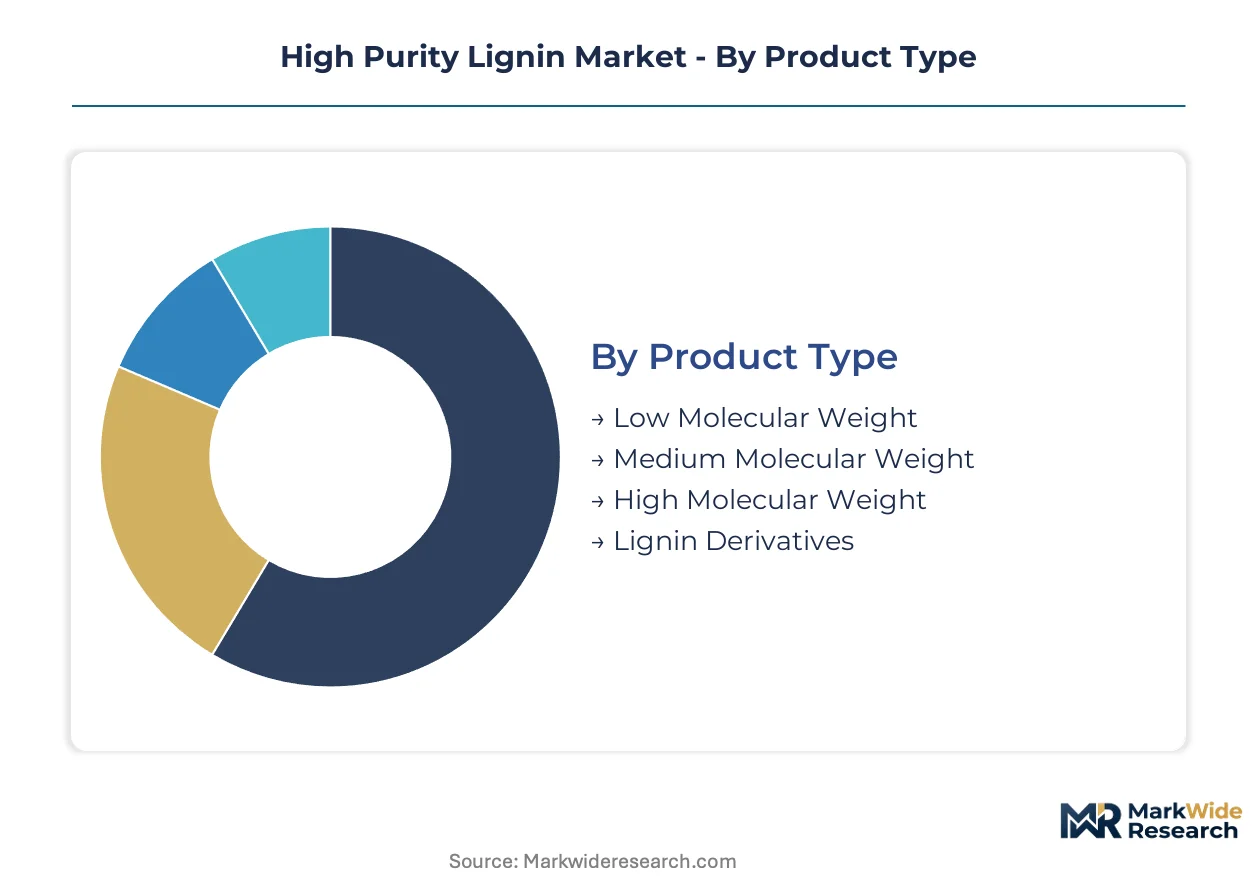
Segmentation in high purity lignin markets reveals how certification burdens, molecular specifications, and form factors partition buyer requirements across adhesive, pharmaceutical, and construction supply chains. Understanding these divides exposes where suppliers must maintain ECHA polymer registrations, FDA indirect food contact clearances, or REACH substance dossiers to secure offtake.
Product Type:
Certification intensity varies sharply across molecular weight tiers, with pharmaceutical applications demanding ECHA polymer of low concern classifications for low molecular weight grades while construction adhesives face lighter REACH substance registration thresholds.
- Low Molecular Weight:Fractions below 1000 Da exhibit superior solubility in polar solvents and enhanced reactivity with formaldehyde in phenolic resin substitution. German adhesive compounders around Frankfurt concentrate procurement here, driven by construction composite pilots requiring rapid curing kinetics under EU Green Deal bio-based mandates.
- Lignin Derivatives:Sulfonated and hydroxymethylated variants undergo functionalization to unlock pharmaceutical drug delivery matrices and cosmetic emulsion stabilizers. EMA and FDA indirect food contact pathways create extended approval timelines, limiting supplier penetration despite premium pricing power in personal care applications.
- Medium Molecular Weight:Intermediate fractions balance processability with mechanical reinforcement in thermoset composites.
- High Molecular Weight:Extended aromatic backbones provide carbon fiber precursor pitch substitution for aerospace manufacturers.
Leading the category by volume: Low Molecular Weight. Expanding most quickly: Lignin Derivatives.
Application:
Cost tier stratification separates commodity construction applications from pharmaceutical and cosmetic segments where purity premiums justify organosolv extraction investments.
- Adhesives:Phenolic resin replacement in plywood and engineered wood products drives the largest volume consumption. REACH compliance and chemical disclosure rules under the EU Green Deal compel German and French formulators to document bio-based feedstock chains for industrial buyers.
- Cosmetics:Antioxidant and UV-absorbing properties position lignin as a natural active ingredient. ECHA cosmetic ingredient registrations and FDA cosmetic facility registrations impose qualification burdens that filter out non-integrated suppliers lacking dedicated regulatory affairs capacity.
- Coatings:Waterborne systems leverage lignin dispersant properties for volatile organic compound reduction under EPA guidelines.
- Plastic Composites:Thermoplastic blending with polypropylene and polyethylene targets automotive interior applications.
Volume concentrates in Adhesives. Steepest expansion trajectory: Cosmetics.
End User:
Customer type determines whether procurement flows through integrated pulp mill captives or independent compounders sourcing standardized fractions.
- Construction:Composite manufacturers and engineered wood producers constitute the dominant demand pool. German industrial clusters around Hamburg pilot lignin integration into load-bearing structural elements, with public procurement mandates under the EU Green Deal creating dedicated offtake channels for certified suppliers.
- Pharmaceutical:Drug delivery excipient and controlled-release matrix applications require EMA marketing authorization dossiers and FDA Type II drug master files. CDSCO in India and PMDA in Japan impose parallel track requirements that fragment market access for non-multinational suppliers.
- Pulp & Paper:Integrated producers consume captive kraft lignin for internal chemical recovery and limited external sales.
- Agriculture:Controlled-release fertilizer coatings and soil amendment applications prioritize cost position over purity thresholds.
Dominant by volume: Construction. Climbing the fastest: Pharmaceutical.
Form:
Supply concentration in Nordic pulp-to-lignin conversion infrastructure favors powder output, while waterborne coating reformulation drives liquid capacity investments.
- Powder:Spray-dried fractions dominate construction and agriculture end users due to extended shelf stability and bulk handling compatibility. Borregaard's Norwegian biorefinery and UPM-Kymmene's Finnish pulp mills anchor supply concentration in Nordic integrated producers.
- Liquid:Aqueous solutions and solvent dispersions gain traction in paint manufacturing as EPA volatile organic compound regulations tighten. Ingevity's specialty chemicals integration enables formulation-ready liquid lignin supply to North American coating manufacturers.
- Granules:Agglomerated forms reduce dust exposure in agricultural field application equipment.
- Emulsion:Stabilized colloidal dispersions target waterborne adhesive systems requiring precise rheology control.
Highest volume share: Powder. Gaining share fastest: Liquid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biorefinery tax incentives in Norway's Green Industry Initiative concentrate lignin purification capacity around the Oslofjord corridor. Nordic pulp-to-chemicals infrastructure anchors European supply. German industrial clusters and Japanese carbon fiber manufacturers drive specialty demand.
Germany
Frankfurt-Hamburg industrial corridor pilots construction-grade lignin composites for engineered wood products. EU Green Deal procurement mandates require bio-based feedstock documentation for public infrastructure contracts. North Rhine-Westphalia adhesive compounders reformulate phenolic resin substitutes under tightened REACH substance registration timelines.
Norway
Captive kraft lignin from Borregaard's Sarpsborg biorefinery supplies specialty chemicals manufacturers across Northern Europe. Norwegian Green Industry Initiative tax credits support organosolv extraction capacity expansions. Oslofjord region membrane filtration operators achieve 90% purity thresholds for carbon fiber precursor applications.
United States
EPA bio-based preferred procurement guidelines mandate minimum renewable content for federal construction and packaging contracts. Ingevity's North Carolina specialty chemicals integration enables formulation-ready liquid lignin supply. Southeast coating manufacturers restructure portfolios to capture federal procurement preference margins under volatile organic compound regulations.
Japan
PMDA marketing authorization pathways for pharmaceutical lignin derivatives create extended approval timelines for drug delivery excipients. METI carbon neutrality roadmaps accelerate aerospace composite feedstock substitution. Nagoya-Tokyo industrial belt carbon fiber manufacturers evaluate organosolv lignin fractions for precursor pitch applications.
High Purity Lignin Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the high purity lignin value chain. Nordic integrated pulp producers and North American specialty chemicals firms anchor supply concentration. Three archetypes dominate: captive biorefinery operators, independent purification specialists, and formulation-integrated compounders. Strategic moves center on membrane filtration capacity additions and modular formulation kit partnerships with mid-scale buyers.
Within the captive biorefinery tier, Borregaard ASA and UPM-Kymmene Oyj occupy positions exemplifying Nordic pulp-to-lignin integration. Ingevity Corporation represents the specialty chemicals archetype with formulation-ready supply capabilities. These three firms anchor competitive positioning across powder and liquid form factors while navigating divergent regulatory pathways in European and North American markets.
| Leading Market Players |
|---|
| Stora Enso Oyj |
| Suzano SA |
| Domtar Corporation |
| Borregaard ASA |
| West Fraser |
| Ingevity Corporation |
| Metsä Group |
| UPM-Kymmene Oyj |
| Sappi Limited |
| Others |
Supply Flow & Price Mechanics
Organosolv extraction scale-up in Norwegian biorefineries is compressing unit economics for 90% purity lignin fractions while concentrating supply control among integrated pulp-to-chemicals operators with captive hardwood feedstock access. This technology transition simultaneously reshapes cost structures and procurement leverage, as membrane filtration capex requirements filter out mid-scale compounders and anchor pricing power with Nordic integrated producers.
Pricing Analysis
Short lead-time premiums dominate transaction economics, with German construction compounders paying marked-up spot rates for standardized low molecular weight fractions against contracted offtake discounts from Nordic suppliers. Pricing stratifies across pharmaceutical-grade ECHA-certified tiers, industrial adhesive standard grades, and bulk agriculture economy levels. Cost compression in construction-grade powder supply is intensifying because hardwood pulp input volatility transmits directly to kraft lignin feedstock costs. Pharmaceutical and cosmetic end users show lowest price sensitivity due to extended regulatory qualification timelines that lock in supplier relationships.
Supply Chain Analysis
Hardwood feedstock supply rests on Nordic pulp mill capacity in Norway, Finland, and Sweden, with German industrial clusters drawing from this concentrated upstream base. Kraft pulping outputs, organosolv extraction equipment, and membrane filtration membranes constitute the critical input trinity. Single-source vulnerability runs through Borregaard's Sarpsborg biorefinery dominance in European specialty grades. Distribution feeds from captive biorefinery direct sales for integrated producers, while independent compounders source through regional chemical distributors with formulation technical support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around membrane filtration capacity holders, as ECHA polymer registration timelines and REACH compliance burdens force non-integrated compounders toward acquisition or exit.
For Market Incumbents: Deepen backward integration into hardwood pulp supply through long-term offtake agreements with Nordic mills, defending against Asian organosolv technology entrants. Anchor capacity additions in the Oslofjord corridor to exploit Norwegian Green Industry Initiative tax credits. Prioritize ECHA polymer of low concern dossier investment to lock pharmaceutical segment access against purification specialists lacking regulatory affairs scale. For New Entrants and Emerging Players: Launch via modular formulation kit partnerships with mid-scale German adhesive compounders seeking proprietary additive blending control. Target pharmaceutical lignin derivatives as the most penetrable white space, where sulfonated and hydroxymethylated variant approval timelines filter out incumbent pure-plays lacking drug master file experience. Pursue joint development agreements with carbon fiber precursor manufacturers in Japan's Nagoya-Tokyo belt as the fastest qualification pathway. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty chemicals conglomerates seeking bio-based aromatic polymer platforms, with financial sponsors holding 5-10 year horizons until EU Green Deal procurement mandates mature. Acquisition target archetype: independent membrane filtration operators with ECHA registrations and existing pharmaceutical customer relationships. Watch PMDA marketing authorization timelines for Japanese pharmaceutical lignin derivatives as the inflection signal for premium tier pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hardwood Feedstock | Long-term pulp supply agreements with Nordic mills secure margin stability against input volatility. |
| Membrane Filtration Capacity Expansion | Oslofjord region investments achieve 90% purity thresholds for carbon fiber precursor qualification. |
| ECHA Polymer Registration Investment | Extended dossier preparation opens pharmaceutical and food-contact packaging market tiers. |
| Modular Formulation Kit Partnership | Flexible procurement models with German compounders displace finished system purchases. |
| Joint Venture with Carbon Fiber Manufacturers | Precursor pitch substitution partnerships in Japan accelerate aerospace composite adoption. |
Methodological Framework
Trade databases, ECHA substance registration filings, and Nordic pulp industry association reports formed the secondary backbone, cross-referenced with primary interviews involving biorefinery operations directors, German adhesive compounder procurement leads, pharmaceutical excipient regulatory affairs managers, and specialty carbon fiber precursor R&D heads. Bottom-up volume triangulation across molecular weight grades, application segments, and end-user industries was reconciled with top-down market sizing from customs data and producer capacity disclosures.
Historical trendline analysis of lignin purification capacity additions, REACH registration timelines, and EU Green Deal procurement mandate progression informed the projection framework across the analysis window. Segmentation modeling incorporated product type tiers, application cost strata, end-user procurement patterns, and geographic regulatory cluster variations. CAGRs were derived from elasticity-adjusted demand curves for phenolic resin substitution, carbon fiber precursor adoption rates, and pharmaceutical excipient qualification pipelines.
Hardwood pulp price volatility, ECHA polymer evaluation delays, and Japanese PMDA marketing authorization timelines are the dominant revision risks to forecast assumptions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
High-Value Chemicals
High-Temperature Epoxy Market
High-Value Chemicals
High Friction Films Market
High-Value Chemicals
Alpha Hydroxy Acid Market
High-Value Chemicals
High Purity Silica Market
High-Value Chemicals
Global High Heat Foam Market
High-Value Chemicals
Asia-Pacific Hydrogen Bromide Market
High-Value Chemicals
Hydroxylamine Sulfate Market
High-Value Chemicals
High Molecular Weight Polyisobutylene Market
High-Value Chemicals
High Purity MTBE Market
High-Value Chemicals
High-Purity Hydrogen Fluoride Market
High-Value Chemicals
High Performance Mercury Sorbent Market
High-Value Chemicals
Barium Hydroxide Monohydrate Market
High-Value Chemicals
Mono Methyl Ether of Hydroquinone (MEHQ) Market
High-Value Chemicals
Global Hydrofluoric Acid Market
High-Value Chemicals
Sodium Hexametaphosphate Market
High-Value Chemicals
High-Purity Boehmite Market