
 Fossil Fuel-Based Plastics Market | 2026-2036
Fossil Fuel-Based Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Fossil Fuel-Based Plastics Market Analytics
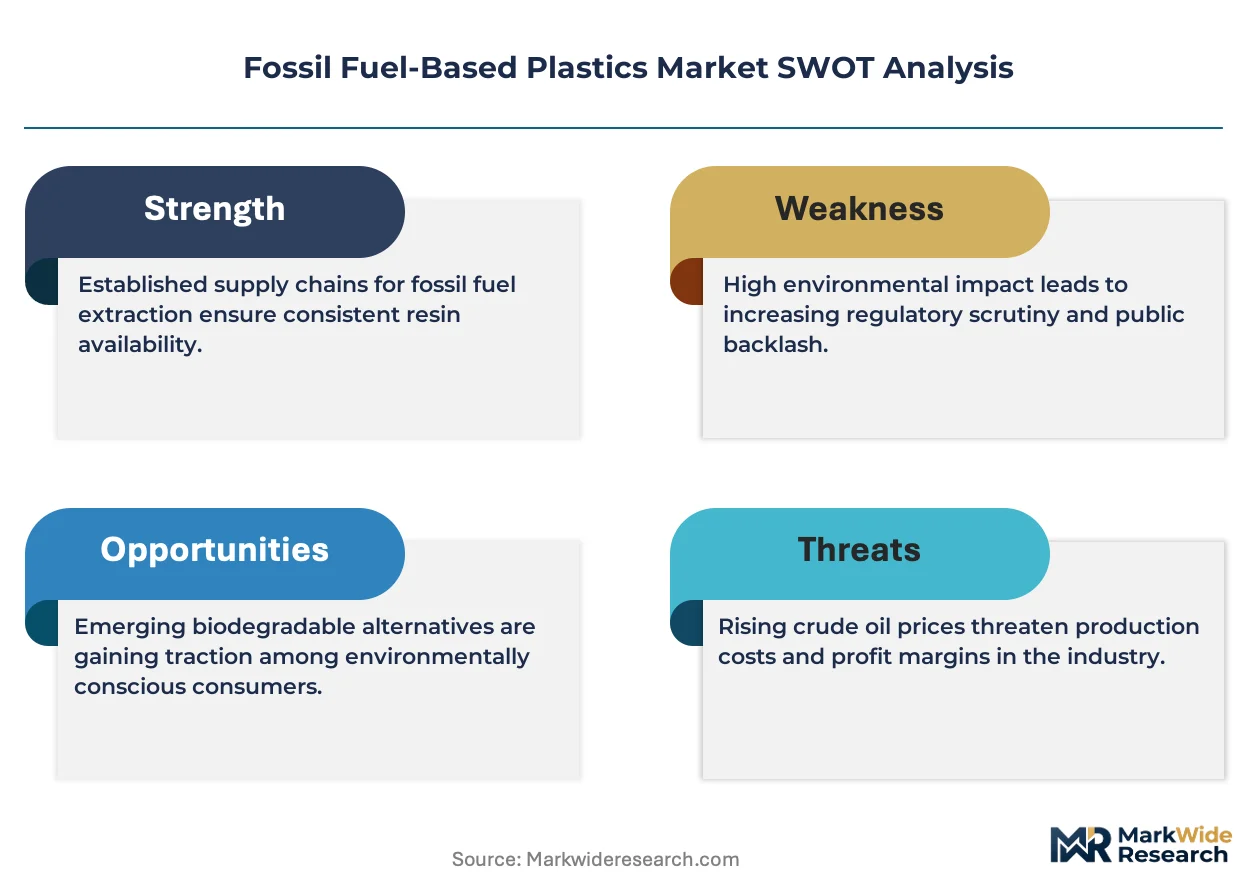
Petrochemical engineering talent scarcity is unwinding capacity expansion timelines across Middle Eastern and Gulf Coast complexes. Dow Inc. leverages its integrated ethylene-to-polyethylene footprint along the US Gulf to sustain margin capture from shale gas feedstock. SABIC anchors its competitive position through advantaged propane dehydrogenation economics at its Jubail complex. BASF SE differentiates via catalyst technology leadership in high-density polyethylene production.
Fossil fuel-based plastics comprise synthetic polymers synthesized from crude oil, natural gas liquids, or coal feedstocks through catalytic polymerization, typically achieving molecular weights exceeding 10,000 daltons and serving as structural, barrier, or insulating materials across industrial supply chains. Polyethylene dominates volume flows due to its versatility in film extrusion and blow-molding processes, while polypropylene captures expanding automotive interior and appliance segments driven by weight-reduction mandates. Polystyrene faces structural demand erosion in disposable food service applications as single-use restrictions proliferate, compressing margin pools toward specialty insulation grades.
The EPA administers emissions standards affecting olefins production under the Clean Air Act, while OSHA mandates process safety management at US petrochemical facilities, collectively elevating capital intensity for grassroots capacity. The EU's F-Gas Regulation and REACH authorization requirements constrain certain fluorinated polymer pathways, redirecting formulation investment. Stakeholders must monitor feedstock cost spreads between naphtha and ethane cracking economics, as this differential determines regional competitiveness more than any demand-side variable.
Market Dynamics
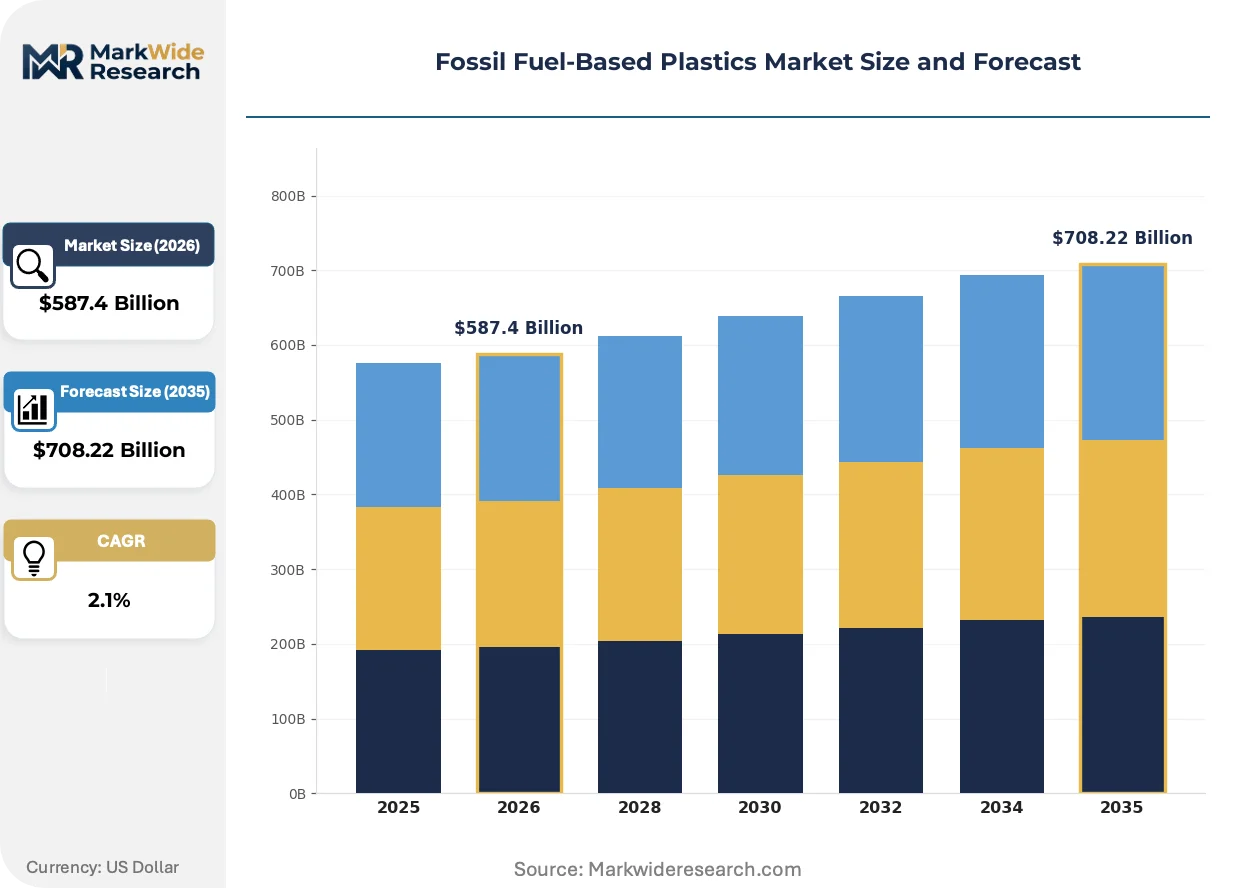
The Fossil Fuel-Based Plastics Market is compressing around feedstock cost spreads between ethane and naphtha cracking, with regional competitiveness hinging more on shale gas access than demand-side innovation. This structural pressure is redirecting capital toward integrated complexes with captive feedstock supply.
Growth Catalysts
- Extended Producer Responsibility schemes:The EU's evolving EPR frameworks redirect investment toward recycling-compatible resin grades, creating pull-through demand for mechanically sorted polyethylene streams in German and French packaging supply chains.
- Automotive lightweighting mandates:Polypropylene captures expanding interior and under-hood segments as OEMs substitute metal components, with Tier 1 suppliers in Thailand and Mexico accelerating tool-up for thin-wall injection molding grades.
- Southeast Asian manufacturing clusters:Packaging buyers in Vietnam, Indonesia, and the Philippines continue expanding polymer consumption despite tightening environmental rules, drawn by cost-advantaged petrochemical feedstock access at integrated Singapore-Johor-Riau corridor facilities.
Market Restraints
- Ethane-naphtha spread volatility:Feedstock cost differentials exceeding $200 per metric ton between US Gulf ethane crackers and European naphtha-based complexes compress margin pools for non-integrated producers in Rotterdam and Antwerp.
- Single-use plastic restrictions:Polystyrene faces structural demand erosion in disposable food service applications as municipal bans proliferate across California, New York, and EU member states, compressing margin pools toward specialty insulation grades.
- Mechanical recycling contamination limits:Technical constraints in multi-layer film sorting cap post-consumer recycled content incorporation rates at 30% for food-contact flexible packaging, limiting circularity claims.
Strategic Opportunities
- Chemical recycling scale-up:Pyrolysis and gasification technologies for mixed plastic waste streams open feedstock arbitrage between landfill tipping fees and virgin naphtha pricing, with project development concentrating in Texas and the Netherlands.
- India's packaging modernization:Underpenetrated flexible film consumption in Indian food and personal care sectors creates white space for biaxially oriented polypropylene investment as modern trade formats expand in Mumbai and Delhi NCR.
- EU Green Deal industrial policy:Carbon border adjustment mechanisms and green hydrogen subsidies for crackers in Rotterdam and Antwerp create first-mover advantages for producers with certified low-emission polyethylene.
Industry Challenges
- Process safety engineering scarcity:Petrochemical engineering talent shortages extend capacity expansion timelines at Middle Eastern and US Gulf Coast complexes, with project delays averaging 8-14 months for grassroots olefins units.
- REACH authorization complexity:ECHA substance evaluation timelines for polymer additives and catalyst residues compress product reformulation windows, requiring dual-track R&D for EU-compliant and non-EU grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fossil Fuel-Based Plastics Market |
| Market Size in 2026 | $587.4 Billion |
| Market Size in 2035 | $708.22 Billion |
| CAGR (2026 – 2036) | 2.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polystyrene, Polyvinyl Chloride End User: Packaging, Construction, Automotive, Consumer Goods Application: Films, Rigid Containers, Sheets, Pipes Distribution Channel: Direct Sales, Distributors, Online Retail, B2B Sales |
| Companies Covered | BASF SE, SABIC, Dow Inc., DuPont de Nemours, Inc., Evonik Industries, Sumitomo Chemical Co., Ltd., Arkema, Celanese Corporation, Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fossil Fuel-Based Plastics Market Evolving Landscape
Advanced recycling infrastructure is decomposing traditional virgin resin demand structures, while regulatory tightening on carbon intensity and single-use formats forces simultaneous adaptation across formulation, process technology, and supply chain configuration.
Pyrolysis-based chemical recycling is decomposing the technical limitations of mechanical sorting by converting mixed polyolefin waste back to synthetic crude feedstock. Petrochemical majors in Rotterdam and Houston are offtaking pyrolysis oil for co-processing in steam crackers at 10-20% blend rates. This technology is decomposing the virgin-recycled price premium for food-contact applications by producing ISCC PLUS certified circular polyethylene with identical performance specifications.
REACH authorization requirements for fluorinated polymer pathways are constraining polytetrafluoroethylene and perfluoroalkoxy alkane production in EU member states. Formulators are redirecting investment toward short-chain fluoropolymer alternatives and non-fluorinated barrier coatings for semiconductor and chemical processing applications. German and French industrial buyers are accelerating qualification timelines for PFAS-free alternatives ahead of 2025 restriction proposals.
Automotive OEMs are consolidating resin specifications around standardized polypropylene compounds to simplify recycling at end-of-life under EU ELV directive revisions. Tier 1 suppliers in Stuttgart and Detroit are reducing approved material grades from 40-plus variants to 12 core formulations. This specification compression is most visible in European and North American interior programs where post-industrial recycled content mandates now exceed 25% by weight.
Fossil Fuel-Based Plastics Market Segmentation
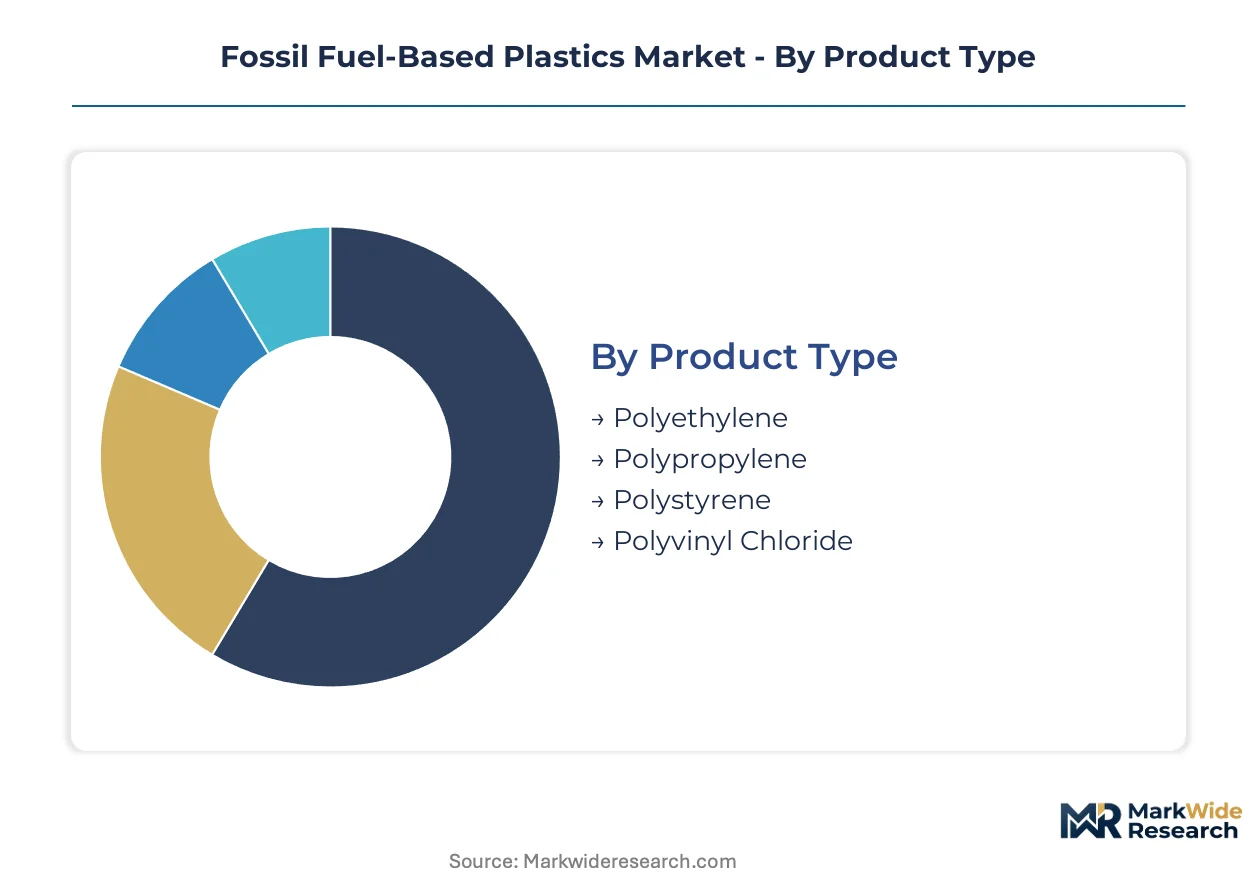
Segmentation reveals where substitution pressures from bio-based polymers and mechanical recycling concentrate most intensely. Understanding these fracture lines guides resin selection and capacity investment decisions across diverging regulatory environments.
Product Type:
Polyethylene and polypropylene face diverging substitution threats—PE from chemical recycling feedstock competition, PP from bio-propylene pilot projects in Rotterdam and Singapore.
- Polyethylene:Linear low-density and high-density grades dominate film extrusion and blow-molding applications. Vietnamese and Indonesian packaging converters consume expanding volumes of metallocene-catalyzed LLDPE for multilayer flexible films despite EU Single-Use Plastics Directive compliance costs.
- Polypropylene:Copolymer and homopolymer variants serve automotive interior panels and appliance housings. Tier 1 suppliers in Stuttgart and Detroit accelerate thin-wall injection molding adoption as OEMs consolidate specifications around 12 core formulations under EU ELV directive revisions.
- Polystyrene:General-purpose and high-impact grades retreat from food service disposables. California and New York municipal bans compress margin pools toward specialty insulation applications in cold-chain logistics.
- Polyvinyl Chloride:Suspension and emulsion PVC resins supply pipe and profile extrusion. German construction regulators under KBA-influenced building codes scrutinize plasticizer migration in potable water applications.
Polyethylene retains volume leadership; polypropylene holds the steepest expansion curve.
End User:
Cost tier stratification separates commodity resin buyers from specification-sensitive automotive and construction segments.
- Packaging:Flexible film and rigid container converters drive bulk polyethylene and polypropylene offtake. German and French EPR schemes redirect investment toward mechanically sorted, recycling-compatible resin grades.
- Construction:Pipe, profile, and membrane applications specify PVC and HDPE for durability. Indian infrastructure projects in Mumbai and Delhi NCR expand biaxially oriented polypropylene consumption as modern trade formats penetrate tier-2 cities.
- Automotive:Interior and under-hood components substitute metal with glass-filled polypropylene compounds. Thailand-based Tier 1 suppliers tool up for 25% post-industrial recycled content mandates in European export programs.
- Consumer Goods:Appliance housings and durables demand high-impact polystyrene and ABS blends. Japanese OEMs under METI circular economy guidelines qualify recycled-content specifications ahead of 2030 targets.
Packaging commands absolute tonnage; automotive delivers the highest margin per kilogram.
Application:
Volume concentration in commodity formats contrasts with specification intensity in engineered applications.
- Films:Multilayer barrier and shrink films consume metallocene polyethylene. Technical constraints cap post-consumer recycled content at 30% for food-contact flexible packaging.
- Rigid Containers:Blow-molded bottles and injection-molded pails serve chemical and food sectors. ISCC PLUS certification enables circular polyethylene claims in Dutch dairy packaging supply chains.
- Sheets:Thermoformed trays and signage substrates utilize high-impact polystyrene and PET. California restrictions on disposable food service accelerate grade substitution toward polypropylene alternatives.
- Pipes:Pressure-rated HDPE and PVC systems deliver water and gas infrastructure. KBA-influenced German building codes enforce migration testing for plasticizer-containing formulations.
Films absorb the largest resin volumes; rigid containers capture premium pricing for certified circular grades.
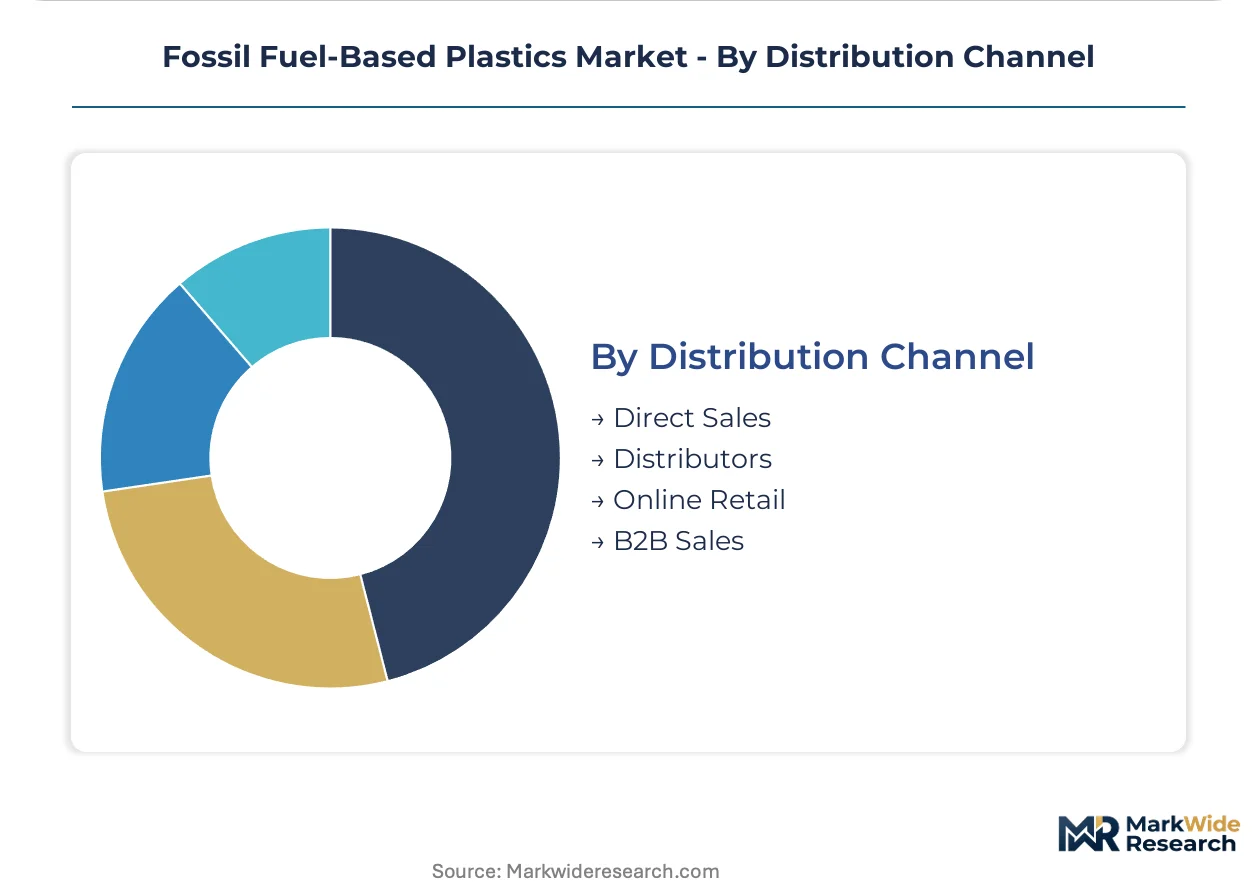
Distribution Channel:
Customer type and procurement scale determine channel selection across integrated and merchant market participants.
- Direct Sales:Captive offtake agreements link major converters to Singapore-Johor-Riau corridor producers. Dow Inc. leverages integrated ethylene-to-polyethylene footprint for Gulf Coast direct supply.
- Distributors:Regional resin merchants stock commodity grades for small and mid-tier processors. Inventory pooling reduces working capital burdens for Vietnamese packaging SMEs.
- Online Retail:Digital platforms emerge for specialty compound and additive procurement. Limited penetration in bulk thermoplastics due to logistics complexity and credit terms.
- B2B Sales:Contracted supply agreements dominate automotive and construction procurement. SABIC anchors long-term offtake through advantaged propane dehydrogenation economics at Jubail.
Direct sales retain volume leadership; distributor networks gain share fastest in emerging economy penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between feedstock-advantaged producers and import-dependent manufacturing hubs. The United States leverages shale gas economics for ethane cracking, while European converters absorb REACH compliance costs. Southeast Asian packaging clusters expand polymer intake despite tightening environmental rules.
United States
Gulf Coast petrochemical complexes consume expanding ethane volumes for polyethylene production. EPA emissions standards under the Clean Air Act elevate capital intensity for grassroots olefins capacity. Dow Inc. anchors integrated ethylene-to-polyethylene operations across Texas and Louisiana shale gas corridors.
Germany
Automotive OEMs in Stuttgart consolidate polypropylene specifications under EU ELV directive revisions. KBA-influenced building codes scrutinize plasticizer migration in PVC potable water applications. The Rhine-Ruhr industrial cluster hosts BASF SE catalyst technology operations for high-density polyethylene production.
China
Packaging converters in the Yangtze River Delta absorb expanding polyethylene volumes for flexible film extrusion. MIIT industrial policy directs investment toward chemical recycling infrastructure for mixed plastic waste streams. Shanghai and Ningbo petrochemical hubs process naphtha feedstock for polymer production.
Saudi Arabia
Jubail industrial city anchors SABIC propane dehydrogenation economics for polypropylene supply. The country's national industrial regulator enforces process safety standards at integrated petrochemical complexes. Eastern Province facilities export resin grades to European and Asian packaging converters.
India
Mumbai and Delhi NCR packaging modernizers expand biaxially oriented polypropylene consumption for food and personal care sectors. BIS standards enforcement tightens quality specifications for construction-grade PVC pipe applications. Gujarat petrochemical corridors attract investment in recycling-compatible polyethylene resin grades.
Fossil Fuel-Based Plastics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in fossil fuel-based plastics supply. Dow Inc. and SABIC capture margin through captive feedstock access at Gulf and Jubail complexes. European chemical conglomerates differentiate via catalyst technology and REACH-compliant formulation expertise. Capacity expansion and strategic partnerships constitute the dominant competitive moves across the forecast window.
Among German chemical conglomerates, BASF SE occupies a position exemplifying catalyst technology leadership in high-density polyethylene production. Dow Inc. represents the integrated Gulf Coast archetype with shale gas feedstock access. SABIC anchors the Middle Eastern tier through advantaged propane dehydrogenation economics.
| Leading Market Players |
|---|
| BASF SE |
| SABIC |
| Dow Inc. |
| DuPont de Nemours, Inc. |
| Evonik Industries |
| Sumitomo Chemical Co., Ltd. |
| Arkema |
| Celanese Corporation |
| Eastman Chemical Company |
| Others |
Value Network & Pricing Analysis
Ninety-day inventory cycles at Rotterdam storage terminals concentrate pricing power among integrated producers with captive ethylene supply. This lead-time band separates Gulf Coast exporters from European naphtha-based complexes, amplifying margin capture where shale gas feedstock anchors cost structures.
Pricing Analysis
Long-term offtake contracts dominate resin procurement between Singapore-Johor-Riau corridor producers and Vietnamese packaging converters. Price differentiation rests on certification grade—ISCC PLUS circular polyethylene commands premiums over commodity grades—and volume scale, with tiered pricing separating spot buyers from annual contract holders. Pricing pressure stems from ethane-naphtha spread volatility compressing European margin pools. Small and mid-tier processors exhibit highest price sensitivity, while automotive Tier 1 suppliers absorb premiums for specification-compliant compounds.
Supply Chain Analysis
Inventory positioning at Antwerp and Houston hubs reflects feedstock arbitrage windows between ethane and naphtha cracking economics. Supply concentrates in the United States, Saudi Arabia, and China, with raw material dependencies on shale gas liquids, propane feedstock, and catalytic polymerization additives. Single-source vulnerability runs through Middle Eastern propane dehydrogenation complexes supplying European polypropylene demand. Distribution runs through direct sales agreements linking integrated producers to major converters, supplemented by regional distributors serving SME packaging processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characteristics emerge from underpenetrated flexible film consumption in Indian food and personal care sectors, where modern trade format penetration accelerates resin qualification timelines.
For Market Incumbents: Compound feedstock integration advantages by securing long-term ethane supply agreements at US Gulf complexes and accelerating ISCC PLUS certification for circular polyethylene grades. Chemical recycling scale-up at Rotterdam and Houston facilities defends position against pyrolysis oil feedstock competition from independent recyclers. Capacity discipline at Jubail and Singapore-Johor-Riau corridors preserves margin pools from oversupply pressure.
For New Entrants and Emerging Players: Chemical recycling service-layer gaps in mixed plastic waste processing offer white-space entry, where incumbent petrochemical majors under-serve small-volume pyrolysis oil offtake. India's biaxially oriented polypropylene segment presents the most penetrable geography, with Mumbai and Delhi NCR converters seeking localized supply alternatives to Singapore-Johor imports. Partner with Dutch dairy packaging supply chains seeking ISCC PLUS certified circular polyethylene to establish qualification credentials.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates divesting non-core polystyrene insulation assets as food service disposable demand erodes. Long-term viability centers on feedstock-advantaged polyethylene and polypropylene positions with chemical recycling optionality. Watch pyrolysis oil-naphtha price convergence as the inflection signal for circular feedstock economics viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethane Supply | Dow Inc. secures shale gas corridor access, insulating margin capture from feedstock volatility. |
| Chemical Recycling Scale-Up | Rotterdam and Houston pyrolysis oil co-processing opens circular polyethylene pathways for Dutch dairy packaging. |
| ISCC PLUS Certification Investment | BASF SE validates circular polyethylene claims, differentiating against commodity resin competitors in EU markets. |
| Long-term Supply Agreement | SABIC anchors Jubail propane dehydrogenation economics through captive offtake to Southeast Asian converters. |
| Joint Venture in India | Biaxially oriented polypropylene partnerships in Mumbai penetrate underdeveloped flexible film modernization. |
Research Methodology
A standing panel of petrochemical plant managers, procurement leads at downstream packaging converters, distribution channel partners, and technical R&D directors provided ongoing calibration across primary fieldwork. Secondary validation drew from customs and trade data, American Chemistry Council and Cefic industry reports, SEC 10-K filings, and EU ECHA substance evaluation databases. Bottom-up resin consumption modeling triangulated against top-down capacity and feedstock supply assessments.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. Segmentation dimensions modeled include polymer grade tier, end-use industry vertical, packaging application format, and regional production hub classification. CAGRs derived from feedstock cost spread trajectories, regulatory compliance cost absorption rates, and substitution elasticity parameters for bio-based alternatives.
Underlying assumptions cover ethane-naphtha spread stability, REACH authorization timeline adherence, and EPR scheme implementation pace, with deviation risk concentrated in pyrolysis oil feedstock qualification delays and automotive specification consolidation speed. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petrochemicals
Synthetic and Biobased Butadiene Market
Petrochemicals
Olefin Derivatives Market
Petrochemicals
Propane Market
Petrochemicals
Tert Butyl Hydroperoxide Market
Petrochemicals
Global Methyl Tertiary Butyl Ether Market
Petrochemicals
Chemical and Petroleum Containers Market
Petrochemicals
Anthracene Oil Market
Petrochemicals
Pentaerythritol Market
Petrochemicals
Aliphatic Hydrocarbon Market
Petrochemicals
Pentane Market
Petrochemicals
Oman Pyrolysis Gasoline Market
Petrochemicals
Alkylate Isooctane Market
Petrochemicals
Bioisobutene Market
Petrochemicals
Flame-Retardant Polypropylene (PP) Market
Petrochemicals
Propylene Market
Petrochemicals
Propylene Carbonate Market