

Bioisobutene Market Size, Share, and Industry Trends Forecast 2026-2036
Bioisobutene Market Insights
The gap between polymer-grade specifications and fuel-additive grades is repositioning how producers allocate fermentation capacity and downstream refining assets. Global Bioenergies leverages its proprietary strain development to anchor European supply of high-purity bioisobutene for specialty chemical contracts. LanzaTech competes through gas-fermentation platforms that convert industrial emissions directly, sustaining cost advantages in carbon-negative feedstock sourcing. Gevo dominates North American offtake agreements with aviation fuel blenders, controlling long-term volume commitments that lock competitors out of renewable jet fuel channels.
Bioisobutene is a four-carbon branched olefin (C₄H₈) produced through microbial fermentation of renewable sugars or syngas, with a boiling point of -6.9°C and Reid vapor pressure suited for high-octane fuel blending and synthetic rubber polymerization. Its primary industrial purpose centers on replacing petroleum-derived isobutene in butyl rubber, polyisobutylene, and alkylate gasoline components. Polymer-grade bioisobutene commands the deepest margin pools due to stringent purity thresholds above 99.5% and long qualification cycles with tire manufacturers. Fuel-additive applications represent the fastest-expanding volume segment as marine and aviation regulators tighten sulfur and carbon intensity standards. Fermentation-based production technology leads current capacity installations, though catalytic conversion from bio-derived intermediates is gaining traction for its compatibility with existing petrochemical infrastructure.
The EPA's Renewable Fuel Standard and the EU Green Deal's Fit for 55 framework jointly shape demand by mandating renewable content thresholds in transportation fuels and setting carbon-border adjustments on imported petrochemicals. REACH registration requirements in Europe and FDA indirect food-contact approvals in the United States further segment market access, with compliance costs favoring producers with integrated analytical and toxicology capabilities. Stakeholders must monitor how California's LCFS credit values and the EU's emerging sustainable carbon cycles certification interact to determine which production pathways secure premium offtake terms.
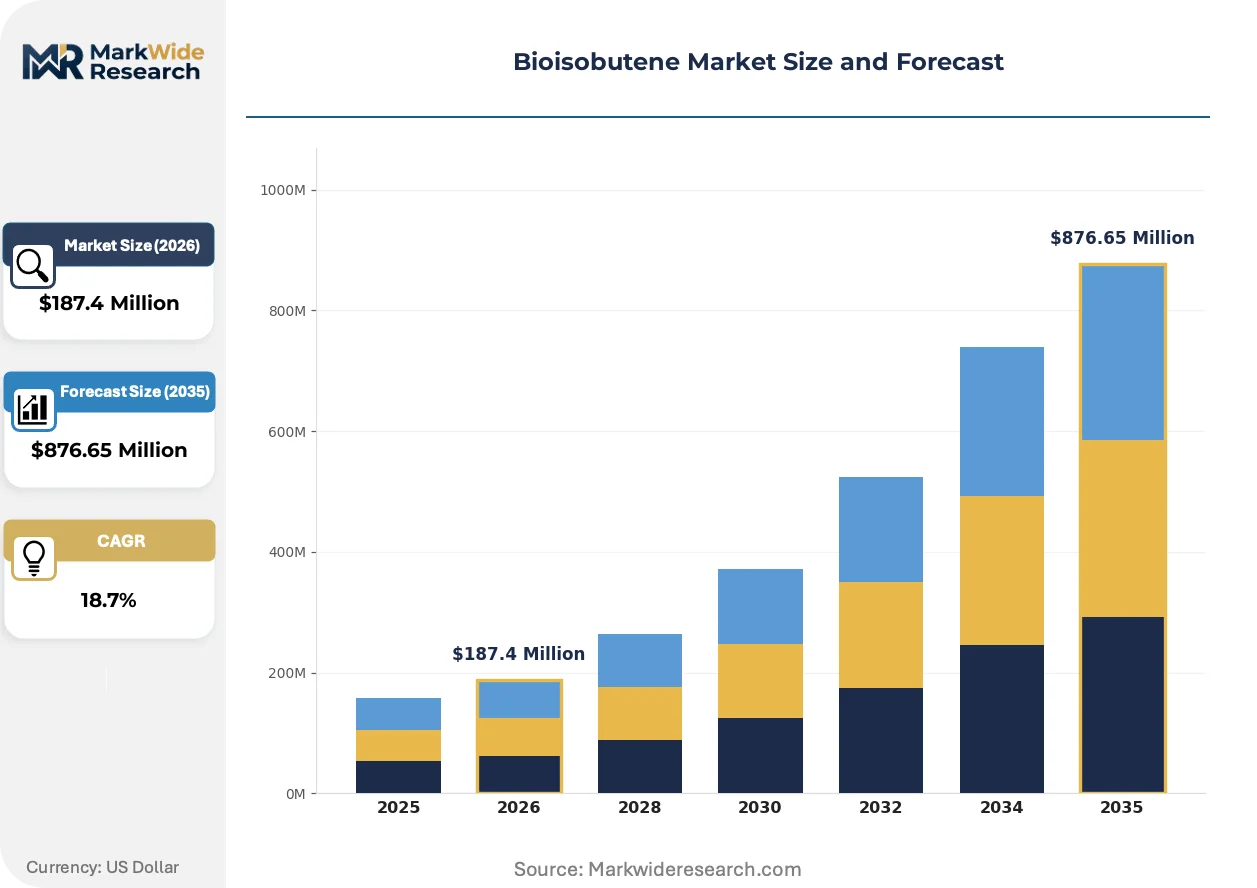
Market Dynamics
The fermentation capacity gap between polymer-grade and fuel-additive specifications is forcing producers to make irreversible asset allocation decisions before offtake contracts mature. This structural tension determines who captures margin pools in synthetic rubber versus aviation fuel channels.
Growth Catalysts
- EU Green Deal Fit for 55:Renewable feedstock mandates in transportation fuels and carbon-border adjustments redirect chemical procurement toward bio-based olefins, tightening petroleum substitution timelines.
- Marine fuel sulfur regulations:International Maritime Organization standards compress demand for high-octane, low-sulfur blendstocks, positioning bioisobutene as a compliant alkylate component.
- Synthetic rubber polymerization:Tire manufacturers seeking petroleum alternatives in butyl rubber production are accelerating qualification cycles for fermentation-derived C₄ feedstocks.
Market Restraints
- Sugar feedstock price volatility:Corn and sugarcane cost swings in Brazil and the US Midwest compress fermentation margins unpredictably, favoring gas-fermentation pathways using industrial emissions.
- Polymer-grade purity thresholds:The 99.5% specification requirement creates a technical moat that concentrates supply among strain-development specialists with multi-year qualification records.
- Petrochemical infrastructure lock-in:Existing steam crackers and catalytic dehydrogenation assets in the US Gulf Coast and Rotterdam harbor sustain cost advantages for fossil isobutene.
Strategic Opportunities
- India's biofuel blending mandates:The country's ethanol-to-aviation fuel roadmap and PLI scheme for advanced biofuels open procurement channels for imported bioisobutene as a jet fuel precursor.
- Gas-fermentation convergence:Integration of LanzaTech's syngas platform with steel mill emissions creates carbon-negative feedstock sourcing that qualifies for California LCFS premium credits.
- Specialty chemical derivatives:High-purity bioisobutene for methyl tert-butyl ether and butylated hydroxytoluene applications commands contract pricing above fuel-additive grades.
Industry Challenges
- Strain development talent scarcity:Microbial metabolic engineering expertise concentrates among academic labs and a handful of commercial platforms, constraining rapid capacity scaling.
- REACH registration timelines:ECHA compliance for novel fermentation products requires 18-24 month toxicology dossiers that delay European market entry for new producers.
- Downstream integration complexity:Fermentation output requires dedicated dehydration and oligomerization units that lack standardization with existing petrochemical equipment.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioisobutene Market Trends and Innovations
Production technology divergence between sugar fermentation and syngas conversion is fragmenting competitive advantage along feedstock access lines rather than scale economics alone. This bifurcation reshapes where capacity locates and who controls offtake relationships.
Gas-fermentation technology using industrial carbon monoxide and hydrogen streams is expanding into steel mill and refinery adjacencies. ArcelorMittal and similar emitters are piloting integrated units that convert waste gases directly to C₄ olefins without sugar intermediates. This pathway is compressing the carbon intensity gap between bio-based and fossil feedstocks while securing offtake from aviation fuel blenders seeking negative-emission certifications.
REACH registration requirements under ECHA are tightening disclosure thresholds for fermentation-derived chemicals entering European polymer supply chains. The regulation forces producers to maintain integrated analytical and toxicology capabilities that smaller entrants cannot replicate. Synthetic rubber manufacturers in Germany and France are responding by consolidating supplier lists to pre-qualified strain developers with complete dossiers.
Buyer concentration among tire manufacturers and aviation fuel blenders is compressing contracting cycles from multi-year framework agreements to annual volume tenders with price reopeners. This shift transfers feedstock risk from end-users to bioisobutene producers. The pattern is most visible in Germany, where BASF and LanzaTech pilot facilities face pressure to demonstrate cost parity with naphtha-derived isobutene before 2026 qualification deadlines.
Bioisobutene Market Segmentation
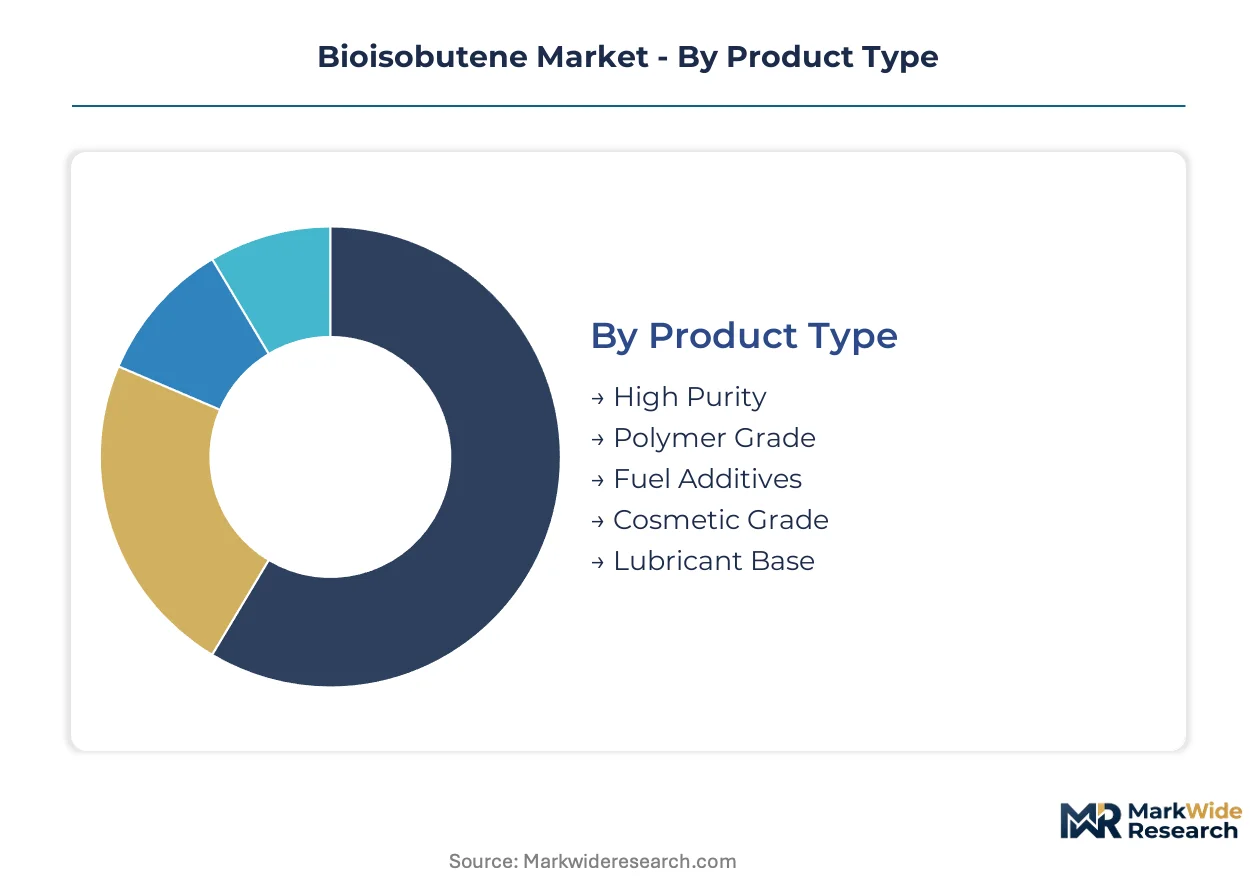
Segmentation in bioisobutene markets determines margin capture and capacity allocation. Producers must choose between polymer-grade purity premiums and fuel-additive volume scale. Each segment carries distinct qualification timelines, feedstock requirements, and offtake contract structures.
Product Type:
Supply concentration in polymer-grade production creates margin pools that strain-development specialists dominate, while fuel-additive volumes attract capital seeking regulatory-driven demand expansion.
- Polymer Grade:Specifications demand purity above 99.5% with controlled sulfur and moisture content for butyl rubber polymerization. Tire manufacturers in Germany and France concentrate procurement here, requiring multi-year strain qualification records that lock out new entrants. REACH dossier completeness determines supplier list inclusion.
- Fuel Additives:Lower purity thresholds suit high-octane gasoline blending and marine fuel alkylate components. Aviation fuel blenders in California and Rotterdam drive fastest volume expansion, drawn by LCFS credit eligibility and IMO sulfur compliance pathways.
- High Purity:Ultra-low impurity profiles serve specialty chemical derivatives and pharmaceutical intermediates.
- Cosmetic Grade:FDA indirect food-contact approvals and EU cosmetic ingredient listings restrict supply to integrated toxicology-capable producers.
- Lubricant Base:Viscosity index requirements align with synthetic ester production for automotive and industrial applications.
Today's leader: Polymer Grade. Tomorrow's challenger: Fuel Additives.
End Use Industry:
Cost tier differentiation separates qualification-intensive synthetic rubber contracts from price-sensitive agrochemical procurement, with automotive lubricants occupying the middle ground on margin and volume.
- Specialty Chemicals:Methyl tert-butyl ether and butylated hydroxytoluene producers command contract premiums above fuel-additive grades. German chemical clusters anchor demand, with BASF pilot facilities supplying qualified volumes under framework agreements.
- Personal Care:Cosmetic-grade specifications require FDA and EU cosmetic regulation compliance that extends registration timelines. Fragrance and skincare formulators in France and Switzerland drive niche demand for fermentation-derived C₄ olefins with carbon-negative certifications.
- Automotive Lubricants:Synthetic base oil blending tolerates broader purity ranges than polymer applications.
- Packaging Materials:Polyisobutylene sealant applications compete with petroleum-derived alternatives on carbon intensity metrics.
- Agrochemicals:Price-sensitive herbicide and pesticide intermediate production favors catalytic conversion pathways over fermentation.
Specialty Chemicals command margin concentration. Personal Care offers steepest expansion trajectory as carbon-negative certifications penetrate premium cosmetic channels.
Application:
Volume concentration in synthetic rubber production contrasts with fuel blending's regulatory-driven expansion, while adhesives and coatings occupy fragmented specialty positions.
- Synthetic Rubbers:Butyl rubber and polyisobutylene polymerization consumes the largest qualified volumes, with tire manufacturers qualifying fermentation-derived feedstocks against naphtha-derived benchmarks. German automotive supply chains enforce the strictest purity protocols.
- Fuel Blending:Marine and aviation sectors expand fastest as IMO sulfur caps and CORSIA carbon intensity thresholds tighten. Rotterdam and Singapore bunkering hubs concentrate demand for low-sulfur alkylate components.
- Plasticizers:Phthalate replacement formulations in EU-regulated markets drive modest specialty volumes.
- Adhesives:Pressure-sensitive and hot-melt applications tolerate broader specification ranges than polymer-grade uses.
- Coatings:Solvent and resin intermediate demand fragments across industrial and protective coating end-uses.
Synthetic Rubbers anchor current revenue. Fuel Blending climbs the fastest as aviation decarbonization deadlines approach.
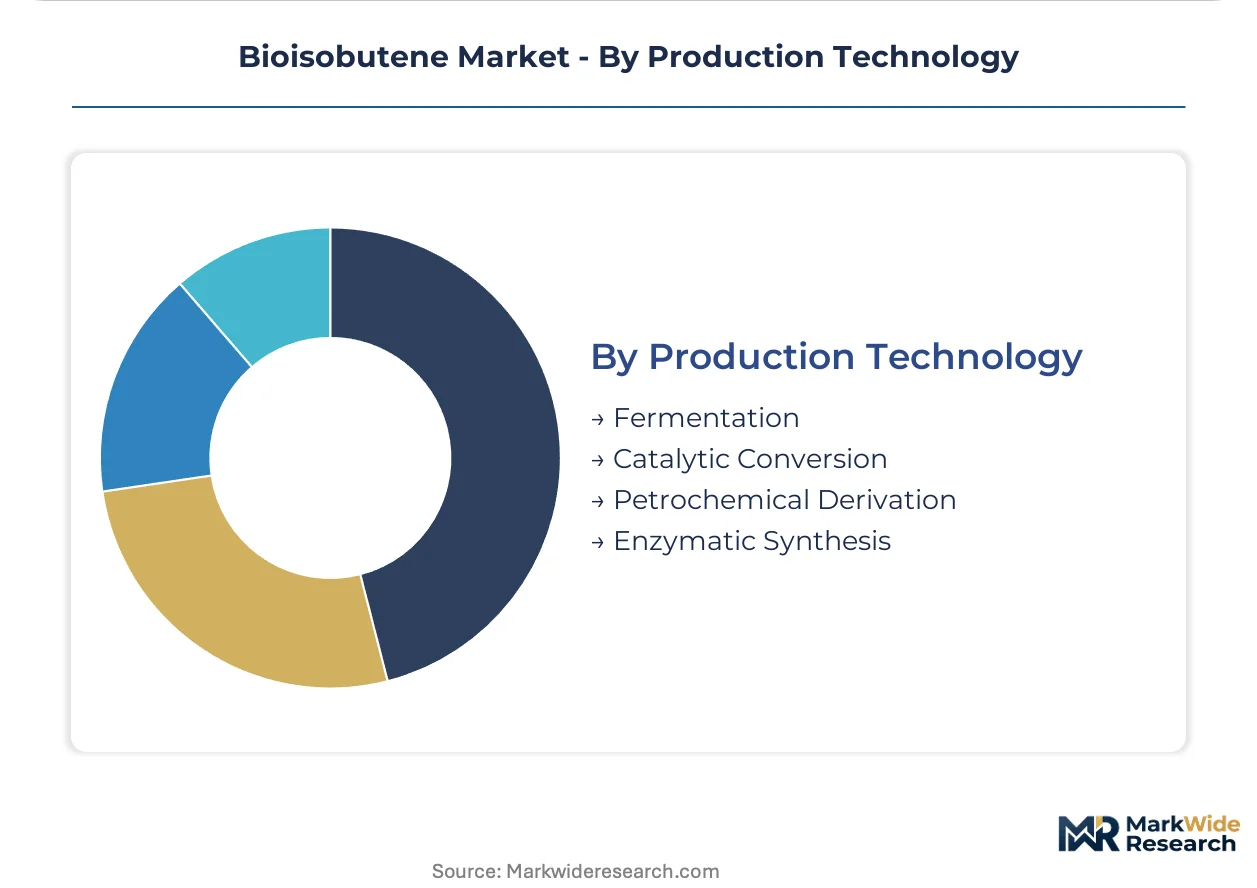
Production Technology:
Technology maturity separates established fermentation capacity from emerging catalytic routes, with feedstock access determining competitive positioning more than scale economics alone.
- Fermentation:Microbial strain engineering of renewable sugars dominates installed European capacity, with Global Bioenergies and LanzaTech platforms achieving polymer-grade purity through proprietary metabolic pathways. Sugar price volatility in Brazil and the US Midwest compresses margins unpredictably.
- Catalytic Conversion:Bio-derived intermediate processing leverages existing petrochemical infrastructure in Rotterdam and the US Gulf Coast, reducing capital requirements versus greenfield fermentation. Compatibility with refinery integration attracts capital seeking lower execution risk.
- Gas-Fermentation:Industrial syngas conversion from steel mill emissions creates carbon-negative feedstock sourcing eligible for California LCFS premium credits.
- Petrochemical Derivation:Fossil naphtha cracking retains cost advantages where carbon pricing remains muted.
- Enzymatic Synthesis:Early-stage biocatalytic routes target specialty chemical derivatives with mild operating conditions.
Fermentation holds incumbent position. Gas-Fermentation gains share fastest as industrial emitter integration spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metabolic engineering talent concentrates in German industrial clusters and California biotechnology corridors, anchoring pilot-scale fermentation capacity near qualified offtake partners.
Germany
Tire manufacturers in the Rhine-Ruhr region accelerate qualification cycles for polymer-grade feedstocks. The EU Green Deal's Fit for 55 framework mandates renewable content thresholds in transportation fuels by 2030. BASF operates pilot fermentation facilities near Ludwigshafen chemical clusters, supplying qualified volumes under multi-year framework agreements with synthetic rubber producers.
United States
Aviation fuel blenders in California and Texas drive fastest volume expansion for fuel-additive grades. The EPA's Renewable Fuel Standard and California LCFS credit mechanisms reward carbon-negative production pathways. Gevo controls long-term offtake agreements with renewable jet fuel channels, locking competitors out of volume commitments through 2030.
France
Specialty chemical derivatives for methyl tert-butyl ether and butylated hydroxytoluene command contract premiums above fuel grades. REACH registration requirements under ECHA force producers to maintain integrated analytical capabilities. Global Bioenergies leverages proprietary strain development to anchor European supply of high-purity bioisobutene from its pilot facilities near Paris-Saclay research clusters.
Netherlands
Marine fuel bunkering hubs in Rotterdam compress demand for low-sulfur alkylate components under IMO sulfur caps. The EU's emerging sustainable carbon cycles certification interacts with California LCFS credit values to determine premium offtake terms. Catalytic conversion pathways leverage existing petrochemical infrastructure in Rotterdam harbor, reducing capital requirements versus greenfield fermentation.
Brazil
Sugar feedstock cost swings in São Paulo state and the Midwest compress fermentation margins unpredictably. The country's ethanol-to-aviation fuel roadmap and PLI scheme for advanced biofuels open procurement channels for imported bioisobutene as a jet fuel precursor. Braskem evaluates bio-based olefin integration at its Triunfo petrochemical complex near Porto Alegre.
Bioisobutene Market Competitive Landscape
Capital-heavy producers compete with asset-light designers for control of strain development intellectual property and offtake relationships. The market structure concentrates supply among fermentation specialists with multi-year qualification records and petrochemical incumbents with existing infrastructure access. Three archetypes dominate: strain-development platforms with proprietary metabolic pathways, gas-fermentation operators integrated with industrial emitters, and diversified chemical majors leveraging catalytic conversion compatibility. Dominant competitive moves include strategic partnerships with steel mills for carbon-negative feedstock sourcing and portfolio diversification into aviation fuel blendstock contracts.
Within the strain-development tier, Global Bioenergies and LanzaTech occupy positions as European anchors for high-purity and gas-fermentation pathways respectively. Gevo exemplifies the North American aviation-focused archetype through its concentration on renewable jet fuel channels. BASF represents the diversified chemical major integrating pilot fermentation with existing polymer supply chain relationships. These three entities collectively illustrate how competitive advantage fragments along feedstock access lines rather than scale economics alone.
| Leading Market Players |
|---|
| Global Bioenergies |
| LanzaTech |
| Gevo |
| BASF |
| ExxonMobil |
| DuPont de Nemours |
| Eastman |
| Ineos |
| Braskem |
| Others |
Pricing and Supply Chain Analysis
Tire manufacturer procurement concentration in Germany and France enforces long-term contract pricing with annual volume reopeners, transferring sugar feedstock volatility risk from buyers to bioisobutene producers. This buyer-archetype dominance compresses margins for fuel-additive grades while preserving polymer-grade premiums.
Pricing Analysis
Contract-based long-term offtake dominates polymer-grade sales to synthetic rubber producers, while spot-adjacent annual tenders govern fuel-additive volumes to aviation blenders. Price differentiation rests on purity certification tiers above 99.5% and REACH dossier completeness, with specialty chemical derivatives commanding premiums above fuel grades. Cost compression in fuel-additive tiers is intensifying because sugar price volatility in Brazil and the US Midwest feeds directly into fermentation economics. Agrochemical intermediates prove most price-sensitive due to catalytic conversion alternatives, whereas polymer-grade buyers accept premium pricing for qualified supply security.
Supply Chain Analysis
Dual-sourcing requirements from tire manufacturers and aviation fuel blenders mandate multi-supplier qualification, forcing producers to maintain parallel strain development and gas-fermentation platforms. Geographic supply concentration centers on Germany, France, and the United States, where pilot fermentation facilities cluster near qualified offtake partners. Raw material dependencies draw from corn and sugarcane feedstocks, industrial syngas streams from steel mills, and specialized dehydration catalysts. Single-source vulnerability concentrates in microbial strain engineering expertise anchored at academic labs and proprietary platforms. Distribution runs through chemical cluster pipeline networks and dedicated iso-tank logistics for polymer-grade volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in bioisobutene hinges on gas-fermentation cost advantages displacing sugar-based pathways, with carbon-negative certifications unlocking premium offtake terms from aviation fuel blenders.
For Market Incumbents: Acquire gas-fermentation platform capabilities to secure carbon-negative feedstock sourcing eligible for California LCFS credits. Incumbents must defend polymer-grade qualification records against emerging catalytic conversion technologies by deepening strain development partnerships with German chemical clusters. Capacity addition in Rotterdam harbor leverages existing petrochemical infrastructure compatibility, reducing execution risk versus greenfield fermentation builds. For New Entrants and Emerging Players: Aviation fuel blenders in California and Singapore bunkering hubs represent the most penetrable channel for fuel-additive grade entry without multi-year polymer qualification barriers. New entrants should target India's ethanol-to-aviation fuel procurement channels opened by PLI scheme incentives for advanced biofuels. A go-to-market angle anchored in carbon-negative certification storytelling bypasses incumbent strain-development moats. For Investors and Strategic Acquirers: Diversified chemical majors with existing petrochemical infrastructure are the most active acquirer in this space, seeking fermentation platform bolt-ons to meet EU Green Deal renewable content mandates. The five-to-ten year viability window favors producers with integrated REACH dossier capabilities and steel mill emission partnerships. Acquisition target archetypes include gas-fermentation specialists with LanzaTech-adjacent syngas platforms. The signal to watch is California LCFS credit value compression, which would erode the carbon-negative premium sustaining gas-fermentation economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Mill Emissions | ArcelorMittal and similar emitters secure carbon-negative feedstock sourcing for aviation fuel blenders. |
| Long-term Supply Agreement with Tire Manufacturers | BASF pilot facilities near Ludwigshafen anchor polymer-grade volumes under multi-year frameworks. |
| Joint Venture with Gas-Fermentation Platform | LanzaTech's syngas technology enables industrial emission conversion without sugar price exposure. |
| Green Manufacturing Transition Certification | REACH dossier completeness under ECHA determines supplier list inclusion for European polymer supply chains. |
| Capacity Expansion in Rotterdam Harbor | Catalytic conversion pathways reduce capital requirements by leveraging existing petrochemical infrastructure. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with plant managers at fermentation facilities, procurement leads at tire manufacturers, aviation fuel blender technical directors, and distribution channel partners combine with secondary validation from customs and trade data, Cefic industry reports, SEC filings, and ECHA registration databases. Triangulation between stakeholder demand signals and installed capacity announcements ensures forecast robustness.
Input-output matrices map fermentation yield rates, sugar feedstock cost curves, and syngas availability against synthetic rubber polymerization demand and aviation fuel blending specifications across the analysis window. Segmentation dimensions include product grade tier, end-use industry, production technology pathway, and regional production hub. CAGRs derive from capacity buildout timelines and offtake contract maturity patterns. Industry-specific forecast inputs incorporate California LCFS credit value trajectories and EU Green Deal renewable mandate enforcement schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to sugar price volatility in Brazil and the US Midwest, steel mill emission regulation enforcement, and strain development talent migration. Deviation in EU carbon-border adjustment implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.