
 Propylene Carbonate Market | 2026-2036
Propylene Carbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Propylene Carbonate Market Analysis
Battery-grade specification upgrades is redrawing competitive boundaries across the propylene carbonate value chain. BASF SE leverages its integrated propylene oxide supply chain to sustain cost advantages in high-purity electrolyte grades. Mitsubishi Chemical Group Corporation anchors its position through captive access to lithium-ion battery manufacturers in East Asia. Huntsman Corporation differentiates via specialized solvent blends for electric vehicle thermal management systems.
Propylene carbonate is a cyclic carbonate ester synthesized from propylene oxide and carbon dioxide, typically exhibiting a boiling point of 242°C and dielectric constant near 65, making it valuable as a polar aprotic solvent. Its primary industrial purpose centers on lithium-ion battery electrolyte formulations where it enhances ionic conductivity and low-temperature performance. Solvent-grade material still occupies the largest volume share, though electrolyte-grade segments command superior margins due to stringent moisture and purity requirements. Battery applications are expanding fastest as automotive OEMs scale electric vehicle platforms, while paint and adhesive segments remain mature demand pools with stable offtake patterns.
EPA oversight of volatile organic compound emissions shapes solvent specifications for coatings applications in the United States. REACH registration requirements in Europe and China's SAMR battery material standards collectively elevate barriers for non-compliant producers. India's BIS certification pathway for imported chemicals adds another compliance layer for market entrants. Stakeholders must monitor how carbon dioxide sourcing regulations evolve, as feedstock availability directly constrains propylene carbonate capacity expansion timelines.
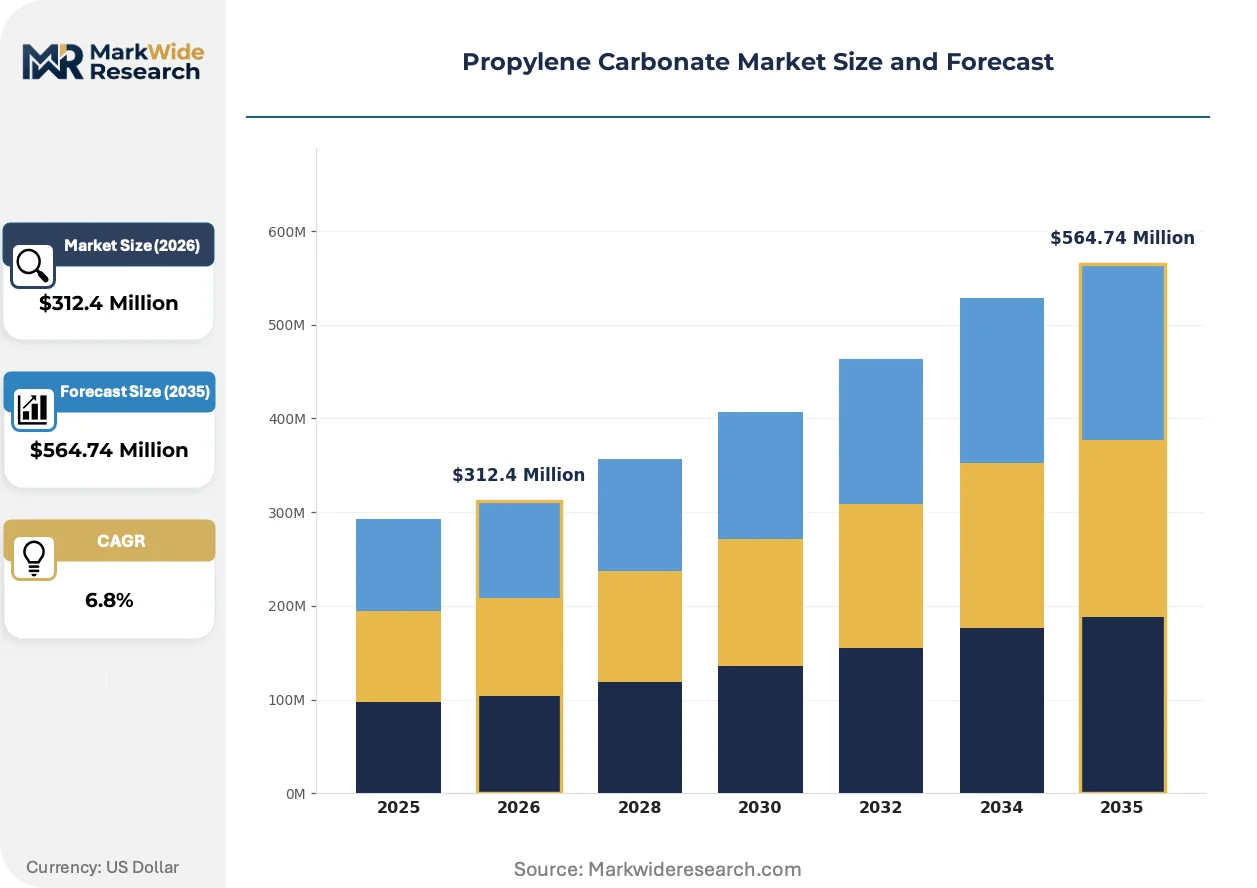
Market Dynamics
Battery-grade electrolyte purity specifications are tightening procurement standards across the propylene carbonate value chain, forcing solvent producers to upgrade distillation infrastructure and secure carbon dioxide feedstock contracts with industrial gas suppliers.
Growth Catalysts
- Electric vehicle platform scaling:Automotive OEMs in China are expanding lithium-ion cell manufacturing, pulling high-purity solvent demand through captive electrolyte formulation facilities.
- REACH registration thresholds:ECHA compliance requirements for cyclic carbonates are consolidating supply toward integrated producers with dedicated regulatory affairs capabilities.
- Propylene oxide cluster proximity:Shandong and Jiangsu provinces concentrate feedstock access, reducing logistics costs for domestic battery material supply chains.
Market Restraints
- Carbon dioxide sourcing constraints:Industrial gas supply volatility limits capacity expansion timelines for propylene carbonate producers dependent on captured CO2 feedstock.
- Ethylene carbonate substitution:Alternative cyclic carbonate solvents with lower viscosity profiles are capturing share in fast-charging battery formulations.
- EPA VOC emission limits:Solvent-grade applications in coatings face formulation reformulation costs as volatile organic compound thresholds tighten.
Strategic Opportunities
- Sodium-ion battery electrolytes:Emerging cell chemistry platforms require alternative solvent blends, opening formulation partnerships outside lithium-ion supply chains.
- India BIS certification pathway:Import compliance requirements create first-mover advantages for producers establishing local technical documentation.
- Solid-state battery interface engineering:Polymer electrolyte development demands ultra-low moisture carbonate grades, commanding premium positioning.
Industry Challenges
- High-purity distillation expertise:Battery-grade moisture specifications below 20 ppm require specialized column design and operational discipline scarce in commodity solvent operations.
- Dual-use facility certification:Producers serving both industrial solvent and battery electrolyte markets face conflicting audit timelines from automotive and chemical sector customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Propylene Carbonate Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent, Electrolyte, Chemical Intermediate, Plasticizer End User: Electronics, Automotive, Coatings, Cosmetics Application: Battery, Paint, Adhesive, Cleaning Agent Distribution Channel: Direct Sales, Online, Wholesalers, Retailers |
| Companies Covered | Empower Materials, Inc., Tokyo Chemical Industry Co., Ltd. (TCI), BASF SE, Shida Shenghua Chemical Group Co., Ltd., Linyi Evergreen Chemical Co., Ltd., LyondellBasell Industries N.V., Shandong Depu Chemical Co., Ltd., Mitsubishi Chemical Group Corporation, Huntsman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Propylene Carbonate Market Emerging Trajectories
Electrolyte formulation complexity is fragmenting solvent procurement patterns, with battery cell manufacturers demanding customized carbonate blends and traceability documentation previously unnecessary in commodity chemical markets.
Membrane-based solvent purification is decomposing conventional distillation economics for high-grade propylene carbonate production. Korean electrolyte compounders are adopting ceramic nanofiltration systems to achieve sub-10 ppm moisture levels without energy-intensive azeotropic drying. This technology is decomposing the capital barrier that previously protected established producers with legacy multi-column assets.
China's SAMR battery material standards are mandating particle contamination thresholds and metal ion limits that exceed prior industry practice. Domestic producers must retrofit analytical laboratories with ICP-MS equipment to certify compliance. Electrolyte-grade segments face the steepest compliance costs, with smaller compounders outsourcing testing to third-party laboratories rather than building in-house capability.
Long-term offtake contracting is displacing spot market purchasing for battery-grade material. Cell manufacturers in Japan and South Korea are securing five-year supply agreements with fixed volume floors and quality escalation clauses. This pattern concentrates procurement power among integrated chemical groups with demonstrated batch consistency, marginalizing traders and re-packagers who previously intermediated solvent flows.
Propylene Carbonate Market Segmentation
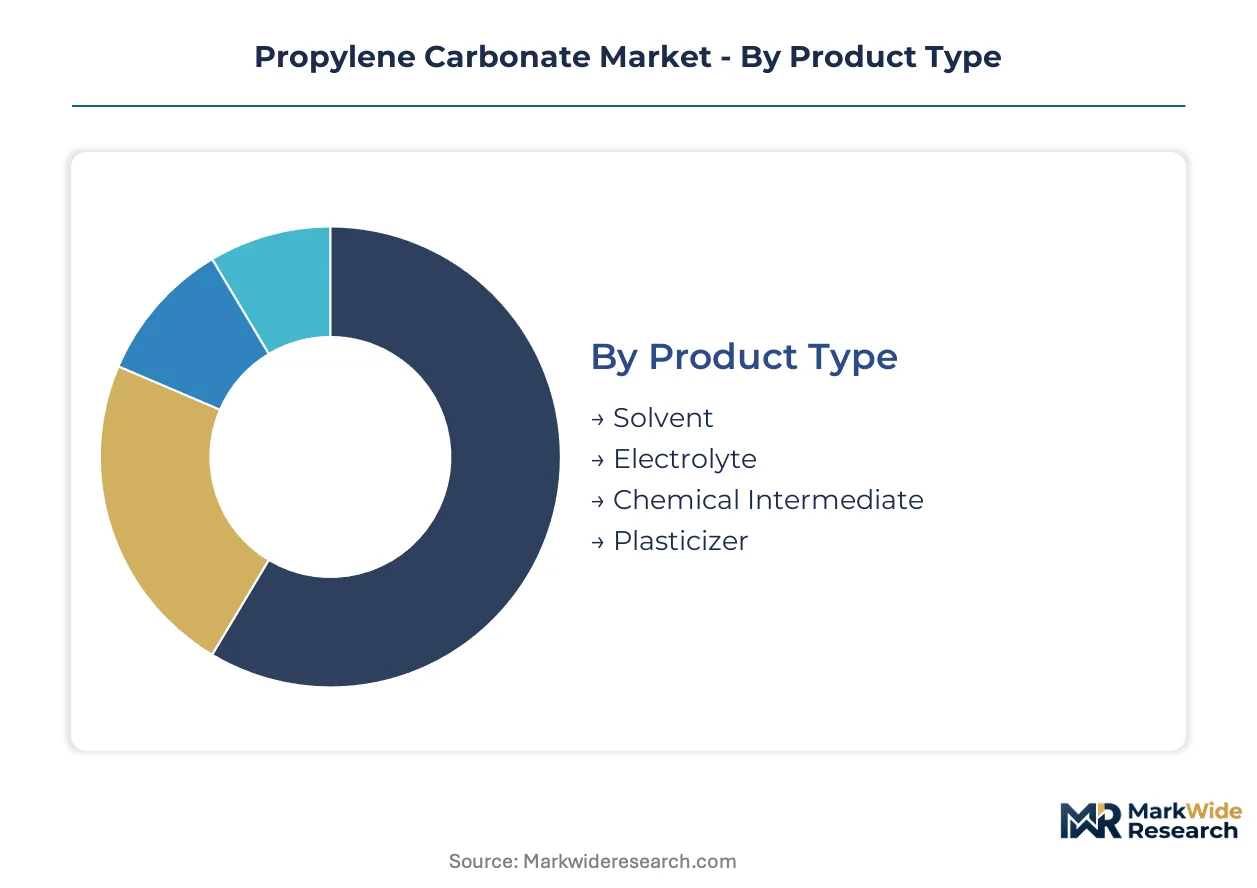
Propylene carbonate segmentation reveals divergent margin structures across product grades and end-use applications. Battery-grade electrolyte specifications command premium positioning through stringent purity thresholds, while solvent-grade volumes anchor capacity utilization.
Product Type:
Electrolyte-grade material captures the steepest margin expansion as automotive OEMs scale lithium-ion manufacturing.
- Electrolyte:Battery-grade propylene carbonate meets moisture specifications below 20 ppm through multi-stage distillation and membrane purification. Electric vehicle manufacturers in China pull demand through captive electrolyte formulation facilities, with Shandong and Jiangsu province producers securing carbon dioxide feedstock contracts to sustain capacity expansion.
- Solvent:Industrial-grade material serves paint stripping, degreasing, and extraction applications with less stringent purity requirements. Coatings formulators face EPA volatile organic compound emission limits that are forcing reformulation away from traditional solvent systems.
- Chemical Intermediate:Feedstock for polycarbonate and polyurethane synthesis via transesterification routes.
- Plasticizer:Additive component in polymer compounding for flexible materials.
Electrolyte holds installed capacity. Solvent is rotating up the share rankings.
End User:
Automotive electrification is concentrating procurement power among cell manufacturers with long-term offtake contracting discipline.
- Automotive:Battery cell producers specify customized carbonate blends with traceability documentation spanning raw material sourcing through batch certification. Japanese and South Korean manufacturers secure five-year supply agreements with fixed volume floors and quality escalation clauses.
- Electronics:Consumer device battery applications demand ultra-low moisture grades for high-density cell architectures. Solid-state battery interface engineering requires polymer electrolyte development with sub-10 ppm moisture thresholds.
- Coatings:Industrial paint and adhesive formulators operate under REACH registration requirements for cyclic carbonates in Europe.
- Cosmetics:Personal care solvent applications utilize pharmaceutical-grade material for extraction and formulation.
Automotive dominates contract value. Electronics is climbing the fastest.
Application:
Battery applications fragment procurement patterns through chemistry-specific solvent blend requirements.
- Battery:Lithium-ion electrolyte formulations leverage propylene carbonate's high dielectric constant and low-temperature performance. Sodium-ion battery chemistry platforms are opening formulation partnerships outside traditional lithium-ion supply chains.
- Paint:Solvent-grade material faces substitution pressure from waterborne and high-solids alternatives.
- Adhesive:Industrial bonding applications maintain stable offtake with mature demand patterns.
- Cleaning Agent:Precision electronics cleaning utilizes high-purity grades with controlled metal ion content.
Battery commands specification leadership. Cleaning Agent is gaining share fastest.
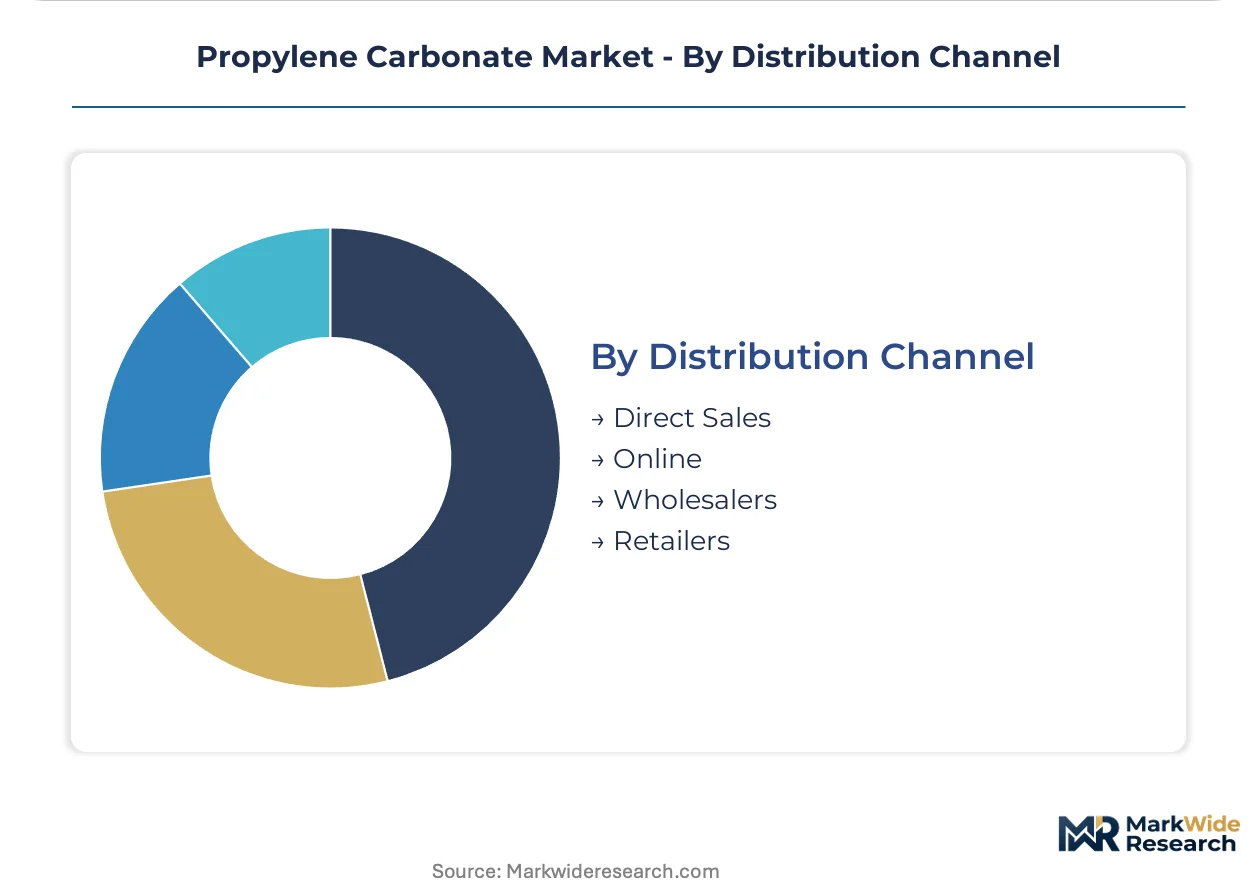
Distribution Channel:
Direct sales relationships are displacing intermediaries as quality documentation requirements intensify.
- Direct Sales:Integrated chemical groups with demonstrated batch consistency secure long-term supply agreements, marginalizing traders and re-packagers who previously intermediated solvent flows.
- Online:Digital procurement platforms serve spot market demand for commodity solvent grades with standardized specifications.
- Wholesalers:Regional distributors maintain inventory positions for industrial solvent applications with predictable consumption patterns.
- Retailers:Small-volume packaging serves specialty chemical and laboratory supply segments.
Direct Sales holds contract volume. Online is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in propylene carbonate track the geographic mismatch between propylene oxide feedstock abundance and battery cell manufacturing scale. Export-oriented producers in feedstock-rich regions supply electrolyte compounders concentrated near automotive OEM assembly networks.
China
Shandong and Jiangsu provinces anchor domestic capacity through integrated propylene oxide clusters serving CATL and BYD electrolyte formulation facilities. SAMR battery material standards mandate particle contamination thresholds and metal ion limits that exceed prior industry practice. Qingdao and Nanjing host retrofitting campaigns for analytical laboratories with ICP-MS certification equipment.
United States
EPA volatile organic compound emission limits force coatings formulators toward reformulated solvent systems, constraining industrial-grade offtake growth. The Inflation Reduction Act domestic content provisions incentivize battery supply chain localization. Texas Gulf Coast petrochemical complexes evaluate propylene carbonate unit additions to serve emerging cell manufacturing in the Southeast.
Germany
REACH registration requirements for cyclic carbonates consolidate supply toward integrated producers with dedicated regulatory affairs capabilities. ECHA compliance thresholds exceed those in competing jurisdictions, elevating barriers for non-European entrants. Ludwigshafen and Marl chemical parks leverage existing propylene oxide infrastructure to sustain electrolyte-grade output.
Japan
Long-term offtake contracting from Panasonic and Toyota Tsusho secures five-year supply agreements with fixed volume floors and quality escalation clauses. METI battery supply chain resilience programs encourage domestic solvent inventory buffers. Osaka and Yokkaichi industrial zones maintain specialized distillation expertise for sub-20 ppm moisture specifications.
South Korea
Samsung SDI and LG Energy Solution procurement teams demand customized carbonate blends with traceability documentation spanning raw material sourcing through batch certification. MFDS chemical registration pathways for battery materials add compliance layers for imported feedstock. Ulsan and Yeosu chemical complexes adopt ceramic nanofiltration systems to achieve sub-10 ppm moisture levels.
Propylene Carbonate Market Vendor Landscape
Concentration sits with integrated chemical groups possessing captive propylene oxide supply and dedicated battery-grade purification infrastructure. The vendor base stratifies across three tiers: multinational diversified chemicals with global electrolyte partnerships, regional Chinese producers leveraging feedstock proximity, and specialized solvent compounders serving niche industrial applications. Strategic moves center on distillation asset upgrades for moisture specification compliance and long-term offtake contracting with cell manufacturers.
Within the integrated chemical tier, BASF SE and Mitsubishi Chemical Group Corporation exemplify archetypes of upstream control combined with downstream electrolyte partnerships. Huntsman Corporation occupies a position representing specialized solvent blend capabilities for thermal management applications. Among China-based producers, Shandong Depu Chemical Co., Ltd. and Shida Shenghua Chemical Group Co., Ltd. anchor regional supply chains through propylene oxide cluster proximity.
| Leading Market Players |
|---|
| Empower Materials, Inc. |
| Tokyo Chemical Industry Co., Ltd. (TCI) |
| BASF SE |
| Shida Shenghua Chemical Group Co., Ltd. |
| Linyi Evergreen Chemical Co., Ltd. |
| LyondellBasell Industries N.V. |
| Shandong Depu Chemical Co., Ltd. |
| Mitsubishi Chemical Group Corporation |
| Huntsman Corporation |
| Others |
Supply Flow & Price Mechanics
Propylene oxide cluster scale economies in Shandong and Jiangsu provinces concentrate purification capacity among integrated producers, establishing cost floors that commodity solvent operations cannot match while elevating battery-grade price premiums through scarcity of sub-20 ppm distillation expertise.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with automotive cell manufacturers securing five-year agreements featuring fixed volume floors and quality escalation clauses. Price differentiation separates electrolyte-grade material commanding certification premiums from solvent-grade volumes facing EPA VOC compliance costs. Pricing pressure stems from ethylene carbonate substitution in fast-charging formulations, compressing margins in commodity carbonate segments. Spot market traders exhibit highest price sensitivity, while integrated chemical groups with captive propylene oxide supply demonstrate lowest sensitivity due to backward integration into feedstock.
Supply Chain Analysis
Carbon dioxide sourcing from industrial gas suppliers constitutes a chokepoint constraining capacity expansion timelines for propylene carbonate producers dependent on captured CO2 feedstock. Manufacturing concentrates in China, Germany, and the United States, with feedstock access in Shandong province and Ludwigshafen chemical park anchoring regional supply. Raw material dependencies encompass propylene oxide from petrochemical complexes, carbon dioxide from ammonia and ethanol plants, and specialized distillation column internals from German engineering suppliers. Single-source vulnerability runs through industrial gas supply contracts. Distribution runs through direct sales relationships with electrolyte compounders, marginalizing traditional chemical traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrolyte formulation complexity fragments procurement patterns across cell chemistry platforms, creating specialist niches for producers with purification expertise outside dominant lithium-ion supply chains.
For Market Incumbents: Compound distillation asset advantages by retrofitting ceramic nanofiltration systems to achieve sub-10 ppm moisture thresholds ahead of SAMR standard escalations. Secure carbon dioxide feedstock contracts with industrial gas suppliers to defend capacity expansion timelines against ethylene carbonate substitution threats in fast-charging segments. For New Entrants and Emerging Players: Lead with sodium-ion battery electrolyte partnerships, targeting formulation white space outside established lithium-ion supply chains with alternative solvent blend requirements. Pursue India BIS certification pathway first-mover positioning before domestic capacity scales, leveraging outsourced ICP-MS testing partnerships to minimize capital intensity. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated producers with demonstrated batch consistency securing long-term automotive offtake agreements. Five-to-ten year viability favors chemical groups with captive propylene oxide supply and existing REACH registration capabilities. Monitor ceramic nanofiltration adoption rates as inflection signal for purification technology disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Oxide | Shandong producers secure feedstock cost advantages against importers facing logistics premiums. |
| Membrane Purification Technology Adoption | Korean electrolyte compounders deploy ceramic nanofiltration to bypass energy-intensive azeotropic drying. |
| Long-term Supply Agreement Structuring | Japanese cell manufacturers lock five-year contracts with quality escalation clauses and fixed volume floors. |
| Regulatory Certification Investment | Domestic Chinese producers retrofit ICP-MS laboratories to meet SAMR particle contamination thresholds. |
| Alternative Chemistry Partnership Formation | Sodium-ion battery developers seek solvent blend suppliers outside established lithium-ion procurement networks. |
Methodological Framework
A spread of perspectives from plant managers at propylene oxide facilities, procurement leads at electrolyte compounders, distribution channel partners in industrial solvents, and technical R&D directors at battery material suppliers converged on the working assumptions. Secondary validation drew from customs and trade data, ACC and Cefic chemical industry reports, SEC 10-K filings from diversified chemical groups, and SAMR regulatory bulletins. Bottom-up capacity estimates and top-down demand modeling triangulated volume projections.
Segmentation dimensions modeled encompass grade tier (electrolyte versus solvent versus intermediate), end-use industry (automotive, electronics, coatings), packaging format (bulk tanker versus drum versus tote), and regional production hub (Shandong cluster, Texas Gulf Coast, Ludwigshafen chemical park). CAGRs were derived through trend extrapolation of battery cell manufacturing capacity announcements and propylene oxide derivative demand elasticity. Forecast inputs incorporated electric vehicle platform scaling timelines and REACH registration threshold compliance costs.
The analysis sits within stated boundaries; outcomes outside sustained carbon dioxide feedstock availability or accelerated ethylene carbonate substitution would require recalibration. Forecasts reflect assumptions regarding SAMR standard enforcement timelines and automotive OEM electrolyte formulation sourcing strategies. Practitioners should keep alternative scenarios live as solid-state battery interface engineering requirements and sodium-ion commercialization timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petrochemicals
Global Methyl Tertiary Butyl Ether Market
Petrochemicals
Fossil Fuel-Based Plastics Market
Petrochemicals
Basic Petrochemical Market
Petrochemicals
Propane Market
Petrochemicals
Synthetic and Biobased Butadiene Market
Petrochemicals
Chemical and Petroleum Containers Market
Petrochemicals
Tert Butyl Hydroperoxide Market
Petrochemicals
Bio Butadiene Market
Petrochemicals
Global Butadiene Market
Petrochemicals
Alkylate Market
Petrochemicals
Olefin Derivatives Market
Petrochemicals
Pentane Market
Petrochemicals
Petrochemical Feedstock Market
Petrochemicals
Alkylate Isooctane Market
Petrochemicals
Aliphatic Hydrocarbon Market
Petrochemicals
Flame-Retardant Polypropylene (PP) Market