
 Pension Fund Management Software Market | 2026-2036
Pension Fund Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Pension Fund Management Software Market Analysis
Corporate pension plan sponsors is collapsing as the dominant buyer archetype, while public sector administrators and multi-employer plans capture a rising share of new software contracts. Oracle Corporation leverages its database heritage to anchor large-scale public fund deployments across North America. SAP SE competes through embedded ERP connectivity that reduces reconciliation overhead for insurance-linked pension products. Workday differentiates via native cloud architecture that appeals to mid-market asset managers seeking faster implementation cycles.
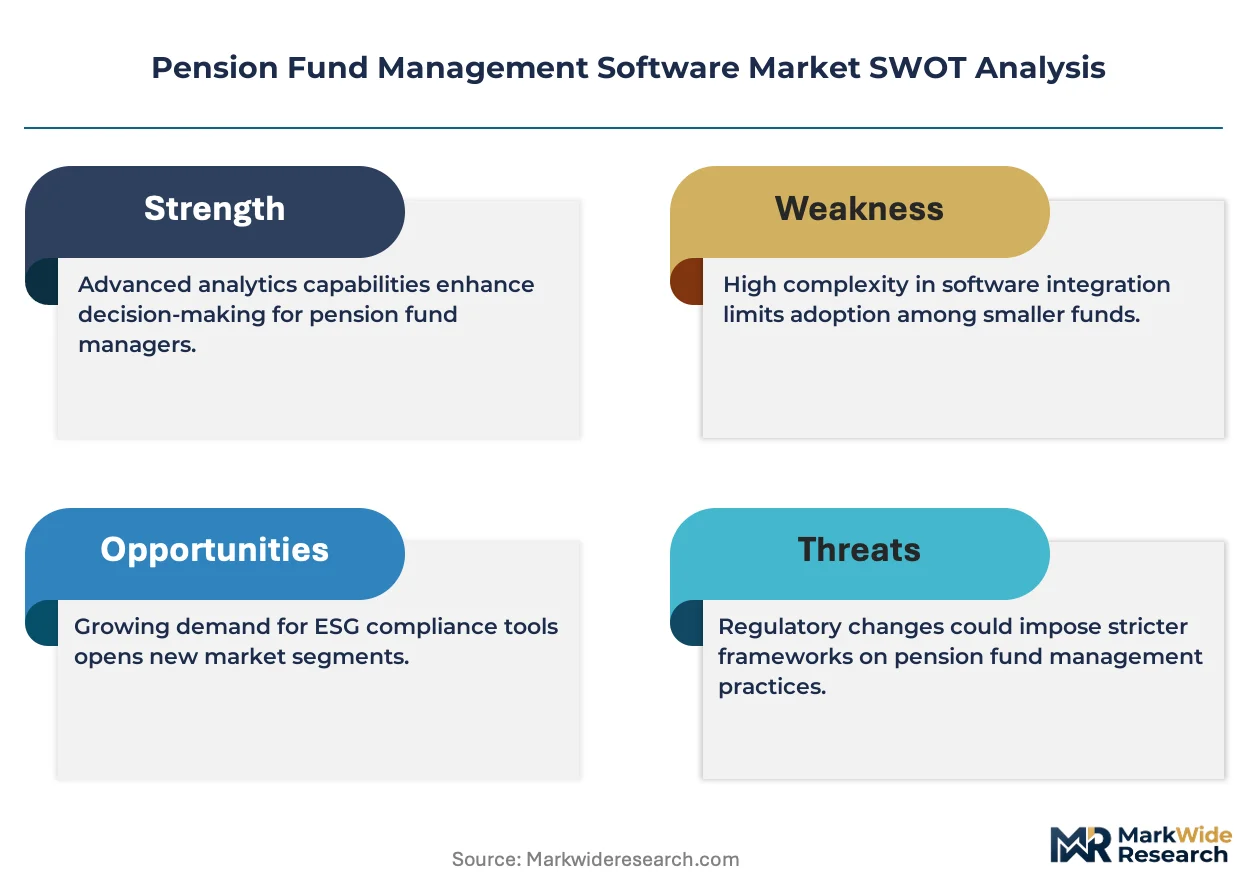
Pension fund management software encompasses integrated platforms that automate actuarial valuation, benefit administration, and investment operations for retirement systems, typically processing participant data across millions of records with sub-second query response requirements. These systems serve the core commercial purpose of ensuring fiduciary compliance while reducing per-participant administrative cost. Portfolio management functionality leads revenue contribution among product type segments, reflecting sustained R&D allocation to real-time asset-liability matching engines. Cloud-based deployment represents the fastest-expanding configuration, though on-premise installations retain margin concentration among sovereign wealth-linked pension pools with data sovereignty mandates. Fund accounting within the functionality dimension occupies the most mature competitive position, with established vendors defending position through regulatory update subscription models.
The United States Department of Labor enforces ERISA reporting standards that compel quarterly benefit statement automation, while the SEC imposes investment adviser custody rules affecting pension fund software audit trails. Europe's EIOPA stress testing framework and the EU AI Act's algorithmic governance requirements are forcing vendors to embed explainable analytics modules for automated investment recommendations. Stakeholders must monitor how jurisdictional fragmentation in pension data protection rules reshapes platform architecture decisions and cross-border hosting strategies.
Market Dynamics
Cloud-native architecture is accelerating procurement cycles among public sector pension administrators, compressing implementation timelines from multi-year deployments to 12-18 month rollouts and reshaping vendor competitive dynamics around subscription pricing models.
Growth Catalysts
- SECURE Act Fiduciary Mandates:The United States Department of Labor's expanded reporting obligations under ERISA are compelling state-level defined benefit plans to automate quarterly benefit statement generation.
- Real-Time Asset-Liability Matching:Investment operations teams at large public funds are demanding sub-second query response engines for dynamic portfolio rebalancing during volatility events.
- EIOPA Stress Testing:Europe's insurance and occupational pensions authority is embedding algorithmic governance requirements that drive procurement of explainable analytics modules.
Market Restraints
- Sovereign Data Mandates:Sovereign wealth-linked pension pools in the Middle East and Asia-Pacific maintain on-premise installation requirements that limit cloud vendor addressable market.
- Actuarial Talent Scarcity:Specialized valuation expertise for hybrid pension products commands premium compensation, inflating total cost of ownership for mid-market deployments.
- Legacy System Entrenchment:COBOL-based administration platforms at mature state retirement systems create technical debt that resists modular replacement.
Strategic Opportunities
- Multi-Employer Plan Consolidation:Taft-Hartley funds in the United States are aggregating administrative functions, creating demand for scalable platforms serving 50,000+ participant pools.
- API-First Ecosystem Integration:Open banking standards and pension data exchange protocols are enabling embedded finance partnerships between administrators and fintech providers.
- Climate Risk Disclosure:The EU Green Deal's sustainability reporting requirements are opening new module categories for carbon footprint tracking across pension portfolios.
Industry Challenges
- Cybersecurity Certification Timelines:FedRAMP and StateRAMP authorization processes for cloud platforms serving public funds extend sales cycles by 9-14 months.
- Participant Data Migration Complexity:Decades of fragmented record-keeping across employer changes create data quality issues that stall go-live dates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pension Fund Management Software Market |
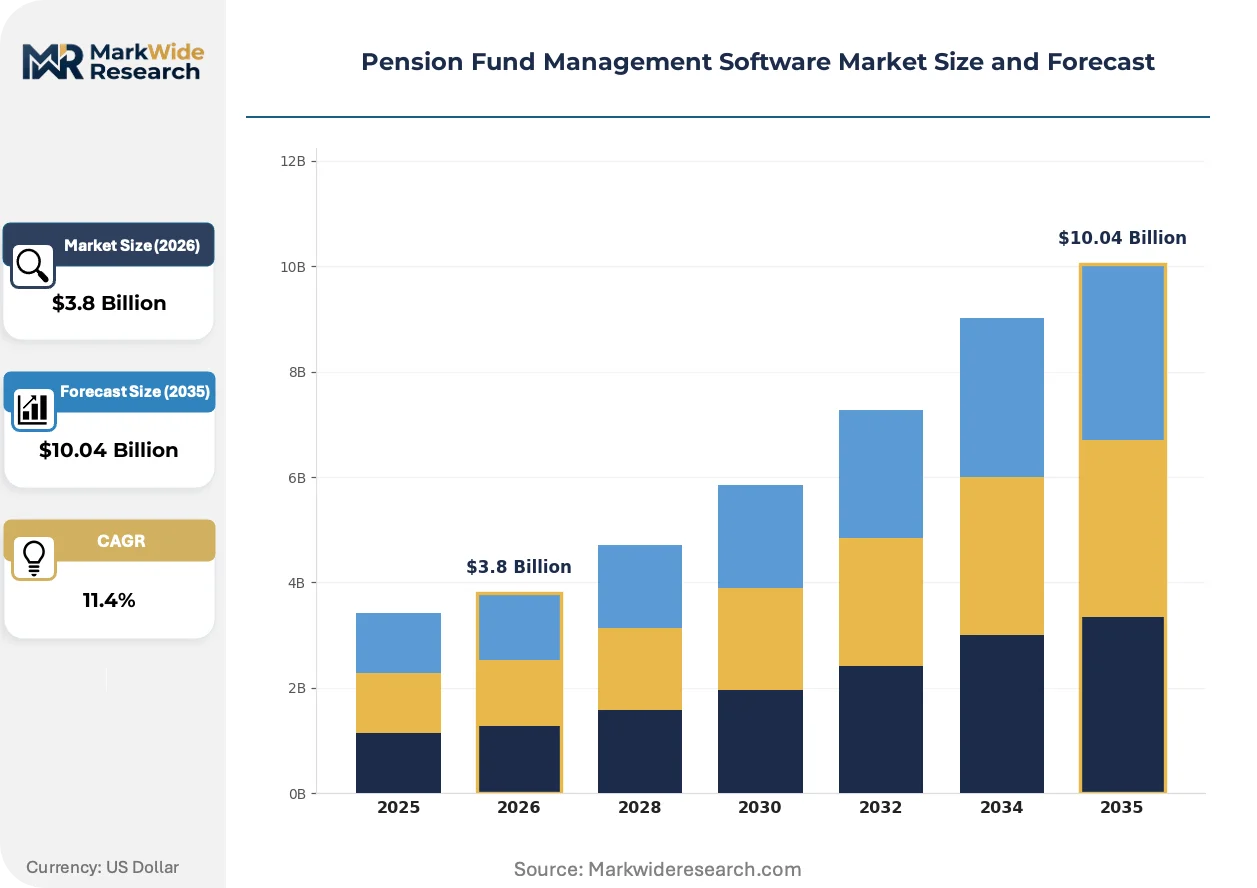
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portfolio Management, Risk Analysis, Compliance Monitoring, Performance Measurement End User: Pension Funds, Insurance Companies, Asset Managers, Banks Deployment: On-Premise, Cloud-Based, Hybrid, Software as a Service Functionality: Data Analytics, Reporting Tools, Fund Accounting, Investment Planning |
| Companies Covered | Vitech Systems Group, Equiniti Group, Milliman, Alight Solutions, Heywood Limited, Oracle Corporation, Sagitec Solutions, Workday, SAP SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pension Fund Management Software Market Emerging Trajectories
Computational infrastructure for pension administration is undergoing platform-level replacement, with vendors racing to embed machine learning into core actuarial functions while regulatory pressure forces architectural transparency.
Embedded artificial intelligence engines for automated investment recommendations are supplanting rules-based rebalancing systems at large asset managers. Public sector pension administrators in California and New York are piloting these platforms for 2025-2026 go-live dates. This shift is compressing vendor differentiation around explainability features rather than raw computational speed.
The EU AI Act's algorithmic governance requirements are mandating human-in-the-loop oversight for automated pension advice systems. Vendors must now document decision pathways and maintain audit trails that satisfy both EIOPA stress testing and national data protection authorities. Product development resources are concentrating in Dublin and Frankfurt regulatory technology clusters to address these overlapping compliance frameworks.
State procurement offices are consolidating vendor relationships through multi-year enterprise agreements that bundle software licensing with implementation services. Mid-market asset managers are responding by demanding modular pricing that unbundles professional services from platform subscriptions. This pattern is most visible in Texas and Florida, where consolidated purchasing authorities now represent 40% of new contract value.
Pension Fund Management Software Market Segmentation
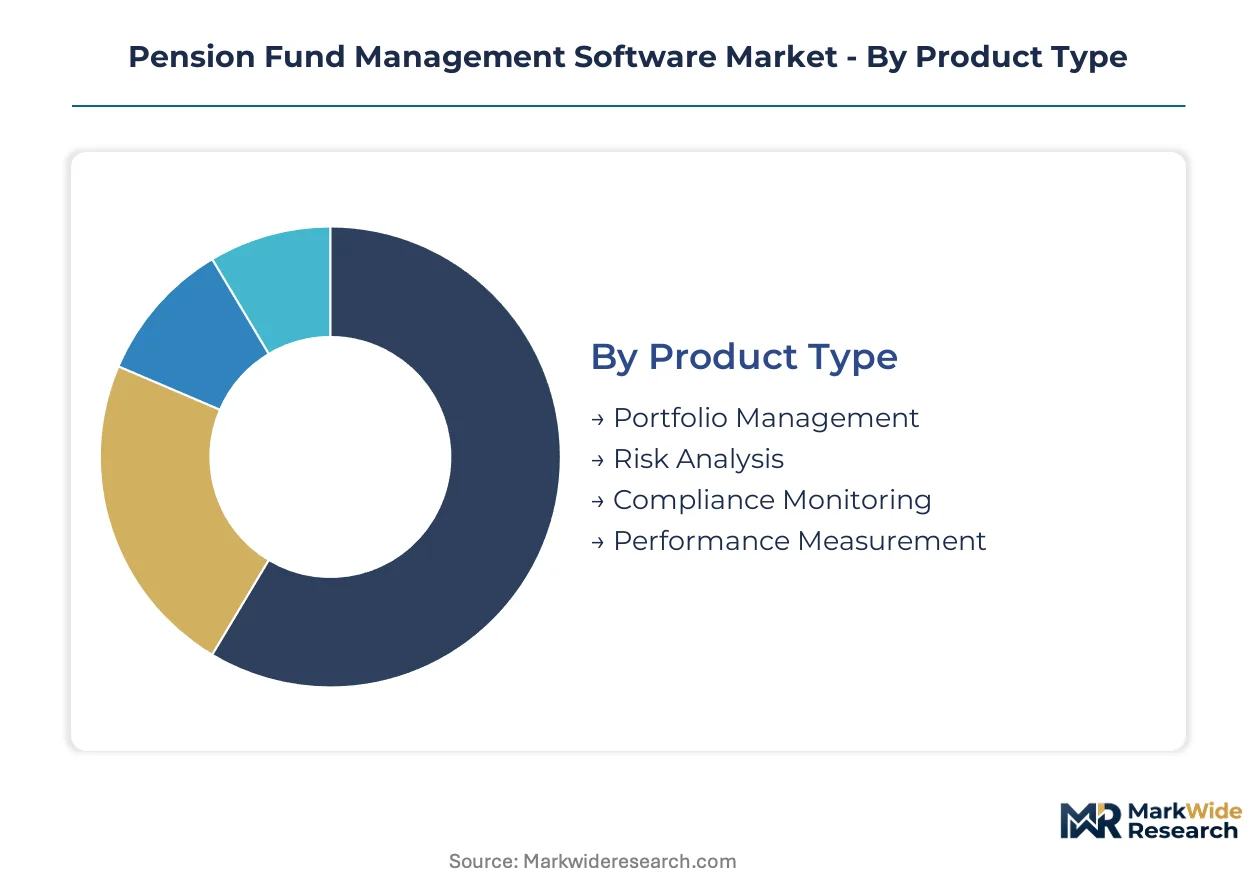
Pension fund management software segmentation reveals how procurement patterns concentrate around regulatory mandates and infrastructure maturity. Understanding these divides exposes where vendors must architect compliance-first versus speed-first solutions.
Product Type:
Margin pools concentrate in modules handling real-time computational loads for large asset bases.
- Portfolio Management:Core platforms process millions of participant records with sub-second query response requirements for dynamic rebalancing. State-level defined benefit plans in the United States are driving procurement here as legacy COBOL systems reach end-of-life.
- Risk Analysis:Stress testing engines embed algorithmic governance features to satisfy EIOPA requirements and EU AI Act audit trail mandates. European pension administrators are prioritizing these modules for explainable analytics capabilities.
- Compliance Monitoring:Automated fiduciary reporting tools address SECURE Act quarterly statement obligations.
- Performance Measurement:Benchmarking engines track fund returns against liability-driven investment targets.
The dominant share belongs to Portfolio Management, while Risk Analysis is closing the gap fastest.
End User:
Customer archetypes split between public procurement cycles and private sector consolidation imperatives.
- Pension Funds:Public sector administrators dominate contract value, with state retirement systems modernizing legacy platforms under compressed 12-18 month timelines. Cloud-native architectures are displacing on-premise installations here.
- Insurance Companies:Embedded ERP connectivity reduces reconciliation overhead for annuity-linked pension products. SAP SE and Oracle Corporation compete aggressively for these deployments across North America.
- Asset Managers:Mid-market firms demand modular pricing and faster implementation cycles.
- Banks:Custody banks require audit trail capabilities satisfying SEC investment adviser rules.
Pension Funds command the largest contract volume, though Insurance Companies are expanding procurement most quickly.
Deployment:
Infrastructure choices reflect data sovereignty mandates against operational velocity trade-offs.
- Cloud-Based:Native architectures compress implementation timelines and enable subscription pricing models. Workday and newer entrants target mid-market asset managers seeking rapid deployment without capital expenditure.
- On-Premise:Sovereign wealth-linked pension pools in the Middle East and Asia-Pacific maintain installation mandates for data localization. These deployments retain higher margin concentration despite shrinking addressable market.
- Hybrid:Split configurations handle sensitive participant data on-premise while outsourcing computational workloads.
- Software as a Service:Multi-tenant platforms serve Taft-Hartley funds consolidating administrative functions.
Cloud-Based configurations capture the steepest expansion trajectory, yet On-Premise installations defend margin concentration in restricted jurisdictions.
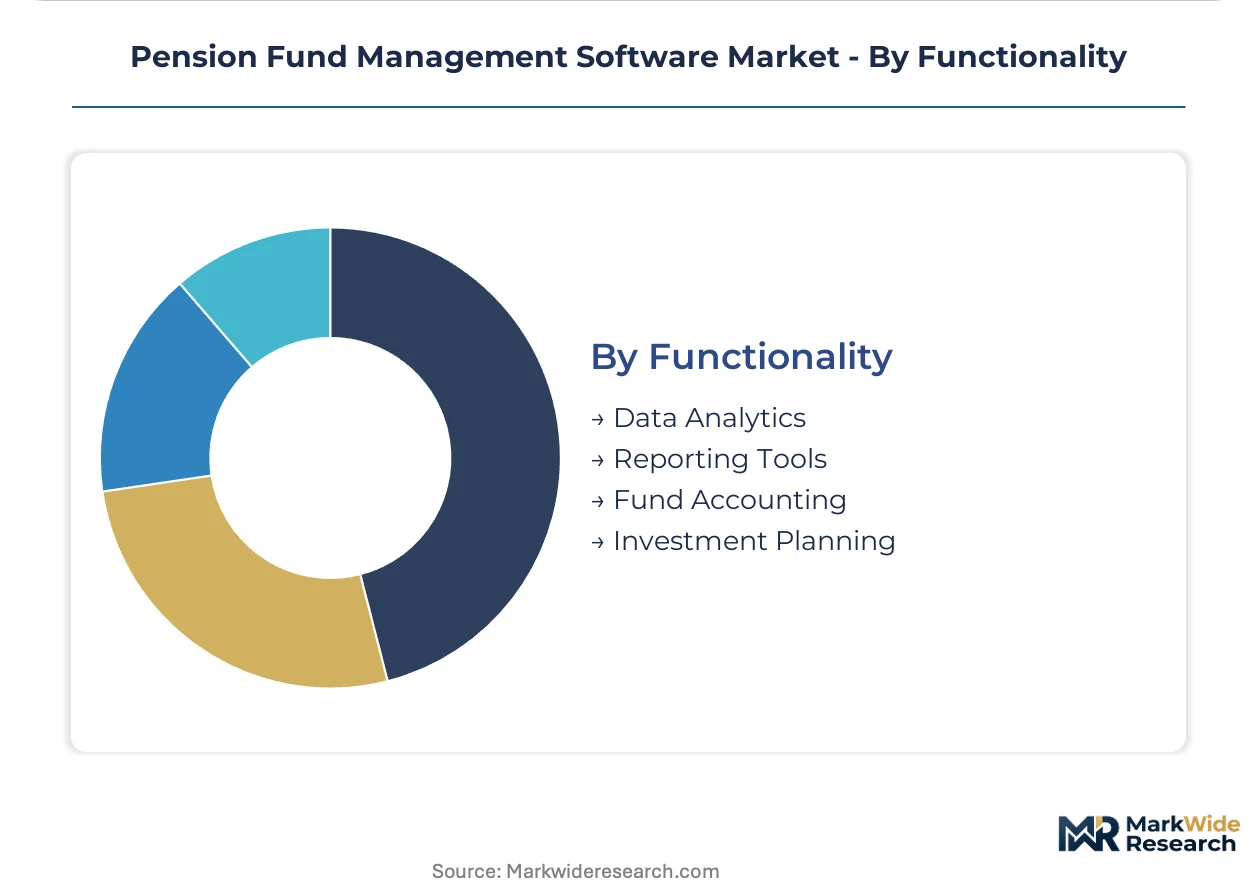
Functionality:
Module maturity varies from commoditized accounting to emerging climate disclosure tools.
- Fund Accounting:Established vendors defend position through regulatory update subscription models. This functionality occupies the most mature competitive position with standardized reporting across jurisdictions.
- Data Analytics:Machine learning engines for automated investment recommendations are supplanting rules-based systems. California and New York public funds are piloting these platforms for near-term go-live dates.
- Reporting Tools:Quarterly benefit statement automation satisfies ERISA obligations.
- Investment Planning:Carbon footprint tracking modules are emerging under EU Green Deal sustainability requirements.
Fund Accounting retains the dominant installed base, while Data Analytics is gaining share fastest among technology-forward administrators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor development resources cluster in regulatory technology hubs serving overlapping compliance frameworks. Cloud-native platform deployment concentrates where fiduciary reporting mandates have accelerated legacy system replacement cycles.
United States
State-level defined benefit plans drive procurement volume as COBOL-based administration platforms reach end-of-life. The Department of Labor enforces ERISA quarterly benefit statement obligations that compress implementation timelines to 12-18 months. California and New York public funds pilot machine learning engines for automated investment recommendations with 2025-2026 go-live targets.
Germany
Insurance-linked pension products demand embedded ERP connectivity to reduce reconciliation overhead. EIOPA stress testing frameworks mandate explainable analytics modules for algorithmic governance compliance. Frankfurt regulatory technology clusters concentrate product development resources addressing overlapping EU AI Act and national data protection requirements.
United Kingdom
Mid-market asset managers seek modular pricing that unbundles professional services from platform subscriptions. The Pensions Regulator's automatic enrollment mandates sustain demand for participant record systems processing millions of accounts. London-based administrators consolidate vendor relationships through multi-year enterprise agreements bundling licensing with implementation services.
Japan
Corporate pension plan sponsors represent a contracting buyer archetype as public sector administrators capture rising contract share. METI guidelines on digital transformation accelerate cloud migration among regional retirement systems. Tokyo metropolitan funds prioritize sub-second query response engines for dynamic portfolio rebalancing during volatility events.
United Arab Emirates
Sovereign wealth-linked pension pools maintain on-premise installation mandates for data localization requirements. MOHAP oversight of occupational pension schemes creates procurement pathways for hybrid deployment configurations. Dubai financial center administrators evaluate split architectures handling sensitive participant data on-premise while outsourcing computational workloads.
Pension Fund Management Software Market Vendor Landscape
Concentration sits with database heritage providers and native cloud architects competing for distinct procurement cycles. Large-scale public fund deployments favor established platform vendors with actuarial calculation engines proven at multi-million participant scale. Three strategic archetypes dominate: ERP-embedded suites, standalone pension administration specialists, and vertical SaaS platforms. Competitive moves center on FedRAMP authorization pursuit for public sector eligibility and API-first ecosystem partnerships enabling embedded finance integrations.
Within the database heritage tier, Oracle Corporation and SAP SE occupy positions anchored to infrastructure consolidation mandates at sovereign funds and insurance-linked deployments. Workday exemplifies the cloud-native archetype appealing to mid-market asset managers seeking compressed implementation timelines without capital expenditure requirements. These three vendors represent divergent architectural bets—on-premise depth versus subscription velocity—that segment addressable market by buyer sophistication and data sovereignty requirements.
| Leading Market Players |
|---|
| Vitech Systems Group |
| Equiniti Group |
| Milliman |
| Alight Solutions |
| Heywood Limited |
| Oracle Corporation |
| Sagitec Solutions |
| Workday |
| SAP SE |
| Others |
Supply Flow & Price Mechanics
Multi-tenant platform scale economies at cloud-native vendors compress marginal delivery costs below on-premise competitors, concentrating supply-side power among FedRAMP-authorized providers while establishing subscription pricing floors that resist commoditization.
Pricing Analysis
Volume-discount tiering structures separate enterprise agreements bundling implementation services from modular SaaS subscriptions targeting mid-market asset managers. Price differentiation hinges on FedRAMP authorization status and actuarial calculation engine certification for multi-million participant scale. Cost compression in the mid-market tier is intensifying because Workday and newer entrants compete on compressed implementation timelines. Public sector pension administrators exhibit lowest price sensitivity due to sovereign budget cycles, while Taft-Hartley consolidation funds drive hardest negotiation on per-participant licensing.
Supply Chain Analysis
Inventory and lead-time observations reveal FedRAMP and StateRAMP authorization processes extending vendor readiness by 9-14 months, creating bottlenecks for cloud platform deployment. Software development concentrates in the United States, Ireland, and Germany where regulatory technology clusters address overlapping EIOPA and EU AI Act requirements. Code repositories draw from open-source actuarial libraries, hyperscaler infrastructure APIs, and embedded finance partnership modules. Single-source vulnerability sits with legacy COBOL migration specialists whose expertise scarcity stalls replacement timelines. Distribution runs through state procurement offices consolidating multi-year enterprise agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as public sector procurement decentralization creates niches for specialized vendors addressing sovereign data mandates and Taft-Hartley consolidation requirements.
For Market Incumbents: Consolidate through acquisition of API-first ecosystem partners enabling embedded finance integrations, while deepening FedRAMP authorization investments to defend against cloud-native entrants targeting compressed implementation cycles. Threat from Workday's subscription velocity demands response through unbundled modular pricing that matches mid-market buyer expectations. For New Entrants and Emerging Players: Lead with explainable analytics modules for EIOPA stress testing compliance as the most penetrable white-space in European procurement cycles. Target Middle Eastern sovereign wealth-linked pension pools with hybrid deployment configurations satisfying data localization mandates. Go-to-market angle centers on human-in-the-loop oversight documentation satisfying EU AI Act algorithmic governance requirements. For Investors and Strategic Acquirers: Cloud-native actuarial specialists with existing FedRAMP authorization represent priority acquisition archetypes for platform consolidation plays. Long-term viability frames around regulatory technology moats deepening over the projection horizon. Signal to watch is California and New York public fund pilot outcomes for machine learning engine adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Pursuit | StateRAMP reciprocity unlocks 40% of new US public sector contract value through consolidated purchasing authorities. |
| API-First Ecosystem Partnership | Open banking standards enable embedded finance integrations between Taft-Hartley administrators and fintech providers. |
| Explainable Analytics Module Development | EIOPA stress testing and EU AI Act requirements force human-in-the-loop oversight documentation for algorithmic investment recommendations. |
| Legacy COBOL Migration Service Acquisition | Technical debt at mature state retirement systems creates captive demand for specialized actuarial calculation engine expertise. |
| Climate Risk Disclosure Module Launch | EU Green Deal sustainability reporting requirements open new revenue categories for carbon footprint tracking across pension portfolios. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC filings, state procurement databases, and EIOPA regulatory guidance. Primary interviews engaged pension fund CIOs, public sector procurement officers, actuarial consulting partners, and cloud platform engineering leads. Secondary validation drew from Department of Labor ERISA enforcement data, FedRAMP authorization repositories, and EU AI Act implementation tracking. Bottom-up participant record scaling estimates triangulate against top-down software licensing revenue aggregation.
Segmentation dimensions modeled span deployment configuration, end-user archetype, functionality module, and regional regulatory cluster. CAGRs derive from cohort-based adoption curve analysis across cloud-native versus on-premise migration patterns. Forecast inputs incorporate state-level defined benefit plan modernization pipeline visibility and Taft-Hartley fund consolidation velocity.
Forecasts assume regulatory continuity in ERISA quarterly statement obligations and EIOPA stress testing frameworks; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Asset Management
Assets Under Management Market
Asset Management
Hardware Asset Management Market
Asset Management
China Mutual Funds Market
Asset Management
Global Infrastructure Asset Management Market
Asset Management
LAMEA Equity Management Software Market
Asset Management
Fixed Income Asset Management Market
Asset Management
Global AI in Asset Management Market
Asset Management
India Asset Management Market
Asset Management
Europe Asset Management Market
Asset Management
Canada Pension Fund Market
Asset Management
Capital Expenditure Market
Asset Management
India AMC Industry Market
Asset Management
Fund Management Fee Market
Asset Management
Smart Asset Management Market
Asset Management
Healthcare Asset Management Market
Asset Management
Global Remote Asset Management Market