
 Global Infrastructure Asset Management Market | 2026-2036
Global Infrastructure Asset Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Infrastructure Asset Management Market Foresight
ISO 55000 certification is redrawing competitive boundaries in infrastructure asset management. WSP leverages its engineering pedigree to anchor large-scale transportation mandates across multiple continents. IBM Corporation competes through AI-driven predictive analytics embedded in enterprise asset platforms. SAP SE extends its dominance by integrating compliance workflows with municipal ERP ecosystems.
Infrastructure asset management encompasses the systematic coordination of physical assets across their complete lifecycles, combining condition assessment protocols, degradation modeling, and capital renewal scheduling to optimize total cost of ownership. The discipline deploys sensor networks, digital twin architectures, and risk-based prioritization matrices to sustain operational continuity across critical public systems. Transportation Networks command the largest share of deployment value due to pavement and bridge backlog volumes across OECD economies. Cloud-Based solutions represent the fastest-expanding deployment model as utility operators migrate legacy SCADA integrations to scalable SaaS architectures. Predictive Maintenance captures concentrated margin pools where algorithmic failure forecasting reduces emergency repair expenditures for water distribution networks.
The U.S. Federal Highway Administration mandates National Bridge Inventory reporting standards that shape software procurement specifications for state departments of transportation. The European Union CSRD extends sustainability disclosure obligations to infrastructure operators, compelling asset managers to quantify embodied carbon in concrete and steel rehabilitation decisions. Japan's METI promotes smart maintenance guidelines through JIS standards for tunnel and dam monitoring systems. Stakeholders must weigh interoperability requirements against vendor lock-in risks as regulatory disclosure frameworks multiply across jurisdictions.
Market Dynamics
The U.S. Bipartisan Infrastructure Law has triggered a structural reallocation of capital toward digitized lifecycle management platforms, forcing municipal procurement offices to consolidate fragmented asset databases into unified predictive systems.
Growth Catalysts
- ISO 55000 certification mandates:European infrastructure operators face CSRD disclosure obligations that embed asset management frameworks into sustainability reporting, accelerating software procurement across utility networks.
- Sensor network densification:Transportation departments deploy IoT-enabled structural health monitoring on bridge decks, generating real-time degradation data that feeds capital renewal algorithms.
- Japan's smart maintenance push:METI's JIS standards for tunnel and dam instrumentation create compliance-driven demand for integrated monitoring platforms.
Market Restraints
- Legacy SCADA integration costs:Water utility operators face prohibitive expenditure to retrofit decades-old control architectures with cloud-native asset platforms.
- Specialized talent scarcity:The intersection of civil engineering and data science remains thinly populated, constraining deployment velocity for predictive maintenance programs.
- Interoperability fragmentation:Proprietary data formats from incumbent vendors lock municipal buyers into single-source dependencies that inflate total cost of ownership.
Strategic Opportunities
- India's urban infrastructure buildout:Smart city initiatives in Mumbai and Bangalore generate greenfield demand for integrated asset platforms absent legacy system drag.
- Digital twin convergence:The fusion of BIM models with operational sensor streams enables real-time structural simulation for critical transportation assets.
- EU Green Deal procurement rules:Embodied carbon accounting requirements in public tenders create premium positioning for asset platforms with lifecycle emissions tracking.
Industry Challenges
- Cross-functional coordination gaps:Finance, engineering, and operations departments maintain siloed data practices that corrupt unified asset registries.
- Cybersecurity certification timelines:Critical infrastructure operators face extended approval cycles for cloud deployments under national security frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Infrastructure Asset Management Market |
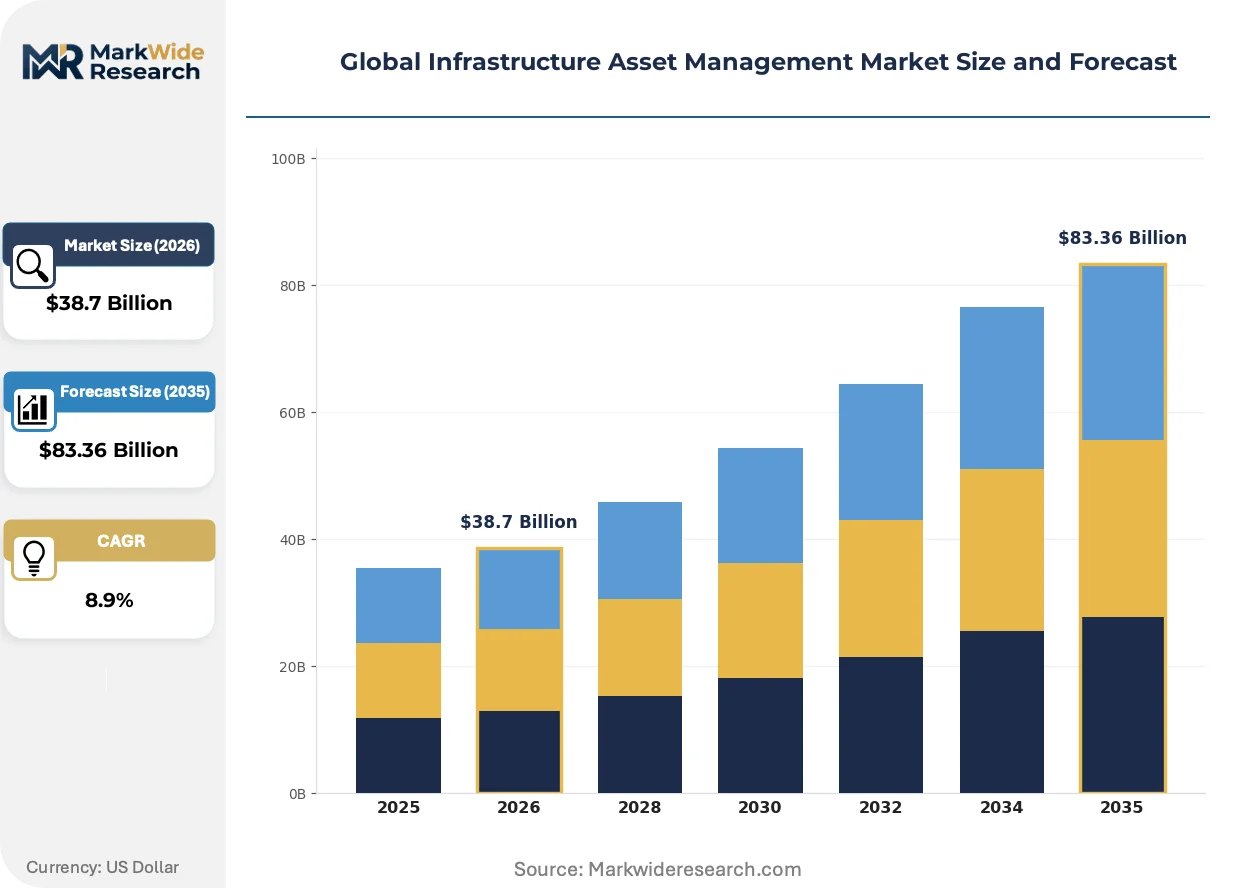
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $83.36 Billion |
| CAGR (2026 – 2036) | 8.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Asset Type: Transportation Networks, Energy Facilities, Water Systems, Telecommunication Infrastructure, Public Buildings Service Offering: Predictive Maintenance, Risk Assessment, Lifecycle Optimization, Compliance Management, Performance Monitoring Deployment Model: On-Premises, Cloud-Based, Hybrid Solutions, Edge Computing, SaaS Platforms End User: Municipal Authorities, Utility Operators, Private Investors, Asset Operators, Investment Trusts |
| Companies Covered | WSP, RPS Group, Brookfield Asset Management, Macquarie Asset Management, Atkins, SIMCO Technologies, Aabasoft Technologies, IBM Corporation, SAP SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Infrastructure Asset Management Market Shifts & Advancements
Digital twin architectures are compressing the feedback loop between field condition assessment and capital planning decisions, restructuring how infrastructure owners prioritize rehabilitation expenditures.
LiDAR-equipped drone inspection systems are decomposing the market for manual bridge assessment contracts. State departments of transportation in Texas and California now mandate aerial structural surveys for spans exceeding defined length thresholds. The technology is decomposing traditional engineering service margins by automating crack detection and spall quantification that previously required rope-access teams.
The EU CSRD extends sustainability disclosure obligations to infrastructure operators, compelling asset managers to quantify embodied carbon in concrete and steel rehabilitation decisions. This regulatory pressure forces integration between ERP procurement modules and environmental impact databases. Transportation network operators in Germany and France now embed carbon cost curves into multi-decade pavement management systems.
Performance-based service contracts are displacing time-and-materials arrangements for water distribution network maintenance. Municipal utilities in Australia and the United Kingdom now procure leakage reduction outcomes rather than repair crew hours. This shift concentrates vendor risk while accelerating algorithmic investment in pressure transient analysis and acoustic leak detection.
Global Infrastructure Asset Management Market Segmentation
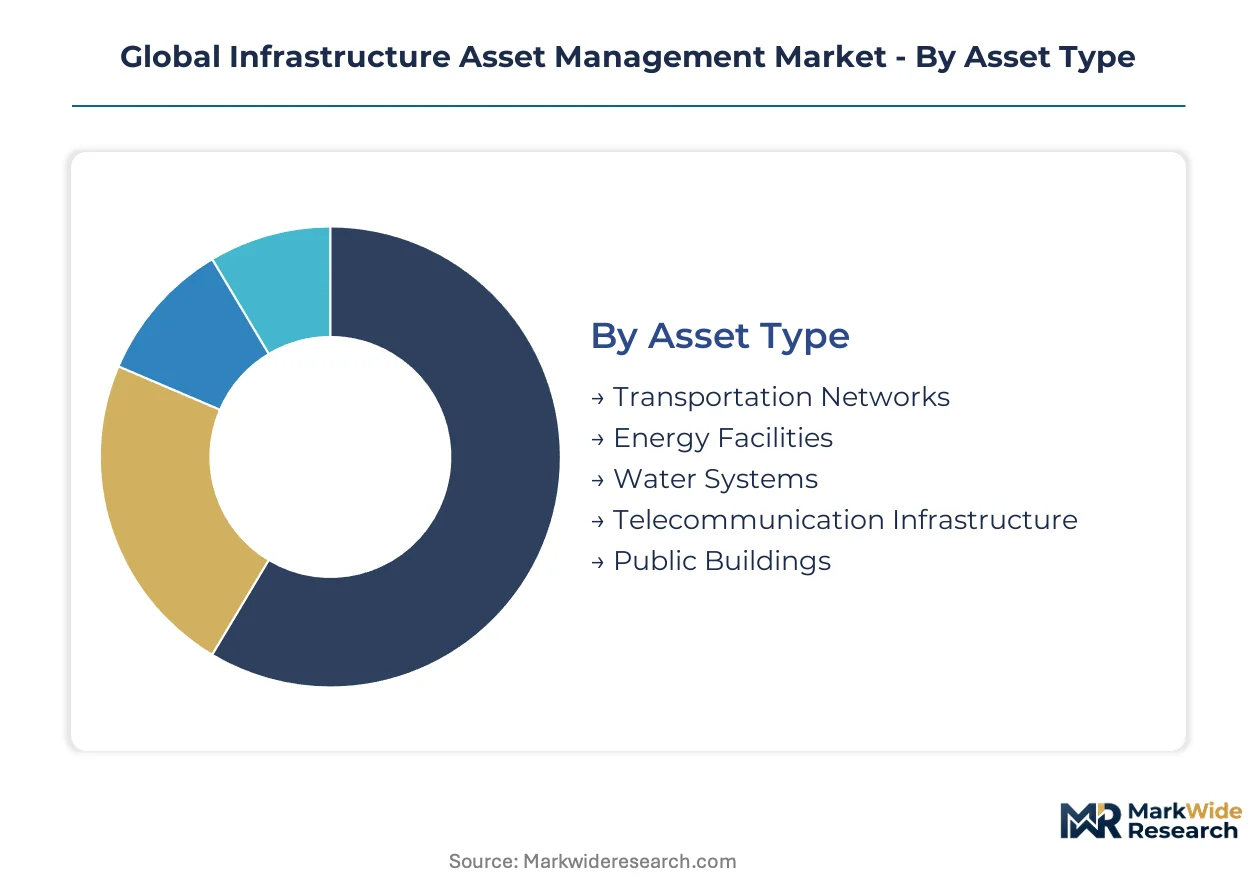
Segmentation in infrastructure asset management reflects divergent regulatory maturity across jurisdictions and the varying capital intensity of asset classes. Procurement specifications from the U.S. Federal Highway Administration, EU CSRD disclosure mandates, and Japan's METI smart maintenance guidelines each favor distinct service configurations and deployment architectures.
Asset Type:
Regulatory disclosure frameworks differentiate procurement specifications by asset class, with transportation and water networks facing the most stringent condition reporting mandates.
- Transportation Networks:Bridge decks, pavement systems, and tunnel infrastructure dominate capital renewal backlogs across OECD economies. State departments of transportation in the United States and Germany's KBA-mandated structural health programs concentrate demand for integrated condition assessment platforms.
- Water Systems:Distribution networks, treatment facilities, and reservoir infrastructure require pressure transient monitoring and leakage detection algorithms. Australian municipal utilities and UK water regulators now mandate outcome-based leakage reduction procurement.
- Energy Facilities:Grid substations, generation assets, and transmission infrastructure demand thermal imaging integration and load forecasting modules.
- Telecommunication Infrastructure:Fiber optic networks, cell towers, and data centers prioritize uptime metrics and redundant pathway modeling.
- Public Buildings:Schools, hospitals, and government facilities emphasize HVAC lifecycle optimization and accessibility compliance tracking.
Transportation Networks handles the majority of throughput; Water Systems is the fastest mover on share.
Service Offering:
Cost tier differentiation separates premium algorithmic forecasting from baseline compliance documentation services.
- Predictive Maintenance:Machine learning models forecast structural degradation and equipment failure before critical thresholds. Water utilities in Singapore and Netherlands deploy acoustic sensors and pressure analytics to shift from reactive repair crews to preemptive intervention scheduling.
- Risk Assessment:Probabilistic models quantify failure likelihood and consequence severity for capital prioritization matrices. California's seismic bridge retrofit programs and Japan's METI dam safety standards drive probabilistic risk framework adoption.
- Lifecycle Optimization:Total cost of ownership modeling balances maintenance expenditure against replacement timing.
- Compliance Management:Automated documentation workflows align asset registries with ISO 55000 and jurisdiction-specific disclosure requirements.
- Performance Monitoring:Real-time dashboards track key performance indicators against service level agreements.
Predictive Maintenance commands premium pricing; Risk Assessment is expanding most quickly as regulatory mandates multiply.
Deployment Model:
Volume concentration tilts toward cloud-native architectures as legacy SCADA retrofit costs decline and cybersecurity certification timelines compress.
- Cloud-Based:Scalable SaaS architectures eliminate capital expenditure for server infrastructure while enabling remote access for distributed asset portfolios. Nordic water utilities and Dutch transportation agencies have migrated entire sensor networks to AWS and Azure government cloud instances.
- Hybrid Solutions:Split architectures retain sensitive operational data on-premises while pushing analytics workloads to cloud environments. German critical infrastructure operators favor this model under BSI cybersecurity guidelines.
- On-Premises:Dedicated server installations persist where national security frameworks restrict external data transmission.
- Edge Computing:Localized processing reduces latency for real-time control decisions in tunnel ventilation and floodgate systems.
- SaaS Platforms:Subscription-based licensing lowers barrier to entry for small and mid-sized municipal authorities.
Cloud-Based deployments account for the largest volume share; Hybrid Solutions are climbing the fastest as security-conscious operators seek architectural compromise.
End User:
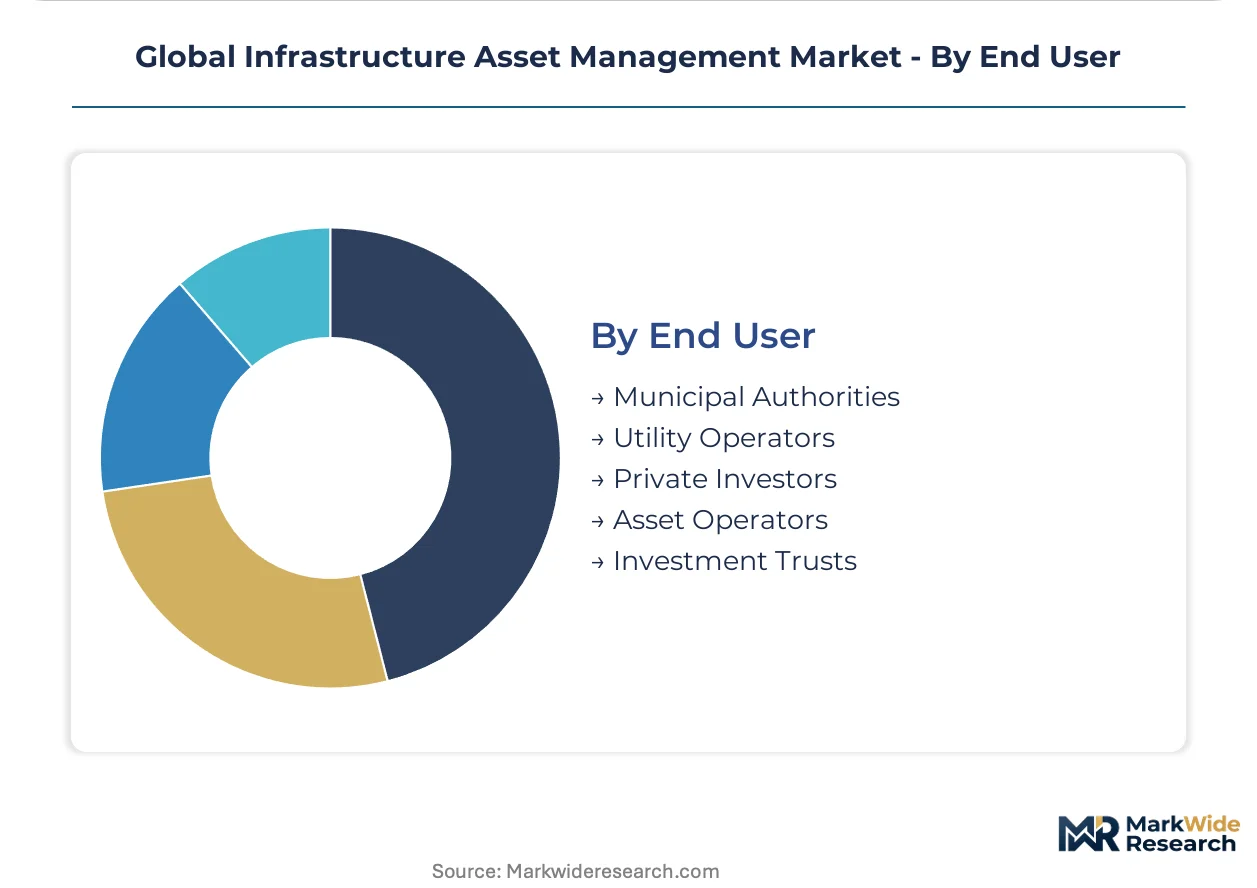
Customer type determines procurement complexity, with municipal authorities favoring multi-year framework agreements and private investors prioritizing yield optimization analytics.
- Municipal Authorities:City and county governments manage the largest installed base of aging infrastructure across road, bridge, and water networks. Federal matching grant programs in the United States and Canada's Infrastructure Bank financing accelerate unified platform procurement.
- Utility Operators:Water, electricity, and gas distribution companies require 24/7 operational continuity and integrated workforce management. UK water companies under Ofwat's AMP8 price review cycle are consolidating asset management systems ahead of performance commitment periods.
- Private Investors:Infrastructure funds and pension managers demand portfolio-level risk dashboards and exit valuation modeling.
- Asset Operators:Specialized contractors managing facilities under performance-based service contracts.
- Investment Trusts:Publicly traded infrastructure vehicles require audit-ready asset registries for shareholder disclosure.
Municipal Authorities represent the dominant customer base; Private Investors are gaining share fastest as infrastructure asset classes attract institutional capital seeking inflation-linked yields.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. Bipartisan Infrastructure Law channels federal matching grants toward digitized asset inventories, accelerating procurement cycles across municipal authorities. Germany's KBA mandates structural health programs for bridge networks, while Japan's METI smart maintenance guidelines reshape tunnel instrumentation standards. India's urban buildout generates greenfield demand absent legacy system constraints.
United States
Federal matching grants incentivize state departments of transportation to consolidate fragmented databases into unified predictive systems. The Federal Highway Administration mandates National Bridge Inventory reporting standards that shape software procurement specifications. Texas and California transportation departments now require LiDAR-equipped aerial surveys for major bridge spans.
Germany
The KBA-mandated structural health programs concentrate demand for integrated condition assessment platforms across federal highway networks. EU CSRD disclosure obligations compel asset managers to quantify embodied carbon in concrete and steel rehabilitation decisions. Transportation operators in Bavaria and North Rhine-Westphalia embed carbon cost curves into multi-decade pavement management systems.
Japan
METI's JIS standards for tunnel and dam monitoring systems create compliance-driven demand for integrated platforms. Smart maintenance guidelines promote sensor densification across critical infrastructure portfolios. Civil engineering firms in the Kanto and Kansai regions deploy real-time degradation monitoring for seismic resilience programs.
India
Smart city initiatives in Mumbai and Bangalore generate greenfield demand for integrated asset platforms without legacy SCADA retrofit burdens. The country's national urban infrastructure programs prioritize lifecycle management for water distribution and transportation networks. Municipal corporations in Maharashtra and Karnataka issue tenders for cloud-native asset registries.
Australia
Outcome-based leakage reduction procurement now dominates water utility maintenance contracts under regulatory pressure. Municipal utilities procure measurable network performance rather than repair crew hours. Sydney and Melbourne operators consolidate pressure transient analysis and acoustic leak detection capabilities.
Global Infrastructure Asset Management Market Competitive Landscape
Listed leaders compete with private specialists across engineering pedigree and software platform dimensions. The market exhibits tiered concentration where global consultancies anchor large-scale transportation mandates while enterprise software vendors capture recurring SaaS revenue streams. Three archetypes dominate: engineering-led integrators, AI-native analytics platforms, and ERP-embedded compliance modules. Consolidation proceeds through strategic technology licensing partnerships and vertical capability acquisitions.
Within the engineering-led integrator tier, WSP and Atkins exemplify firms leveraging multi-continent transportation mandates to anchor recurring asset management contracts. IBM Corporation and SAP SE occupy positions at the enterprise software intersection, where predictive analytics and compliance workflows embed into municipal ERP ecosystems. These three names represent distinct competitive vectors: infrastructure-specific engineering depth, AI-driven operational intelligence, and compliance-integrated platform scale.
| Leading Market Players |
|---|
| WSP |
| RPS Group |
| Brookfield Asset Management |
| Macquarie Asset Management |
| Atkins |
| SIMCO Technologies |
| Aabasoft Technologies |
| IBM Corporation |
| SAP SE |
| Others |
Supply & Pricing Matrix
Performance-based service contracts for water distribution networks lock in multi-year revenue visibility while capping vendor risk exposure. Australian municipal utilities and UK water regulators now procure measurable leakage reduction outcomes rather than repair crew hours, compressing margins for traditional time-and-materials providers.
Pricing Analysis
Certification level (ISO 55000) creates the primary spread between premium and baseline service tiers. SaaS subscription models dominate municipal procurement, with pricing stratifying across predictive analytics bundles, compliance documentation modules, and legacy system integration fees. Cost compression in on-premises deployments is intensifying as cloud-native alternatives eliminate server infrastructure expenditure. Small and mid-sized municipal authorities exhibit highest price sensitivity, while federal matching grant recipients in the United States absorb premium pricing for unified lifecycle platforms.
Supply Chain Analysis
Strategic stockpiling of sensor hardware characterizes procurement patterns among transportation departments facing bridge inspection mandates. Manufacturing concentration centers on Germany, Japan, and the United States for structural health monitoring equipment. Supply chains draw from specialized semiconductor foundries for IoT edge processors, precision optics for LiDAR assemblies, and corrosion-resistant alloys for field instrumentation. Single-source vulnerability persists in government cloud certification pathways, where AWS and Azure government instances dominate downstream distribution to Nordic and Dutch infrastructure operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across ISO 55000, EU CSRD, and Japan's JIS standards fragments procurement specifications, creating specialized niches for compliance-focused platform vendors.
For Market Incumbents: Secure ISO 55000 certification moats by embedding sustainability disclosure workflows directly into municipal ERP ecosystems. Acquire acoustic sensor specialists to preempt leakage detection commoditization. Vertical integration into LiDAR-equipped drone inspection services counters margin erosion from automated bridge assessment technologies. For New Entrants and Emerging Players: Differentiate on carbon accounting integration for EU Green Deal procurement compliance. Target India's smart city initiatives in Mumbai and Bangalore for greenfield deployment absent legacy SCADA retrofit costs. Pursue outcome-based contracting models that shift vendor risk onto algorithmic performance guarantees. For Investors and Strategic Acquirers: Engineering-led integrators with multi-continent transportation mandates offer durable recurring revenue exposure. Infrastructure asset management platforms demonstrate long-term viability anchored in federal matching grant programs and regulatory disclosure mandates. Watch for CSRD enforcement intensity as the inflection signal for European demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 55000 Certification Investment | Unlocks premium municipal procurement tiers under Federal Highway Administration matching grant programs. |
| Digital Twin Platform Integration | Fuses BIM models with sensor streams for real-time structural simulation in Texas and California bridge networks. |
| Carbon Accounting Module Development | Captures EU Green Deal procurement preference through embodied carbon tracking in concrete rehabilitation decisions. |
| Acoustic Sensor Specialist Acquisition | Consolidates leakage detection capabilities ahead of Australia's outcome-based water utility contracting wave. |
| India Smart City Partnership | Establishes cloud-native deployment reference sites in Maharashtra and Karnataka municipal corporations. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with asset management directors at state transportation departments, water utility operations chiefs, and municipal procurement officers; and secondary validation against Federal Highway Administration bridge inventory databases, EU CSRD disclosure filings, METI JIS standard documentation, and AWS government cloud certification records. Bottom-up segment sizing triangulated with top-down infrastructure expenditure tracking across OECD economies.
Across the analysis window, forecasts modeled deployment model migration patterns, asset type capital renewal backlogs, and service offering tier penetration. Segmentation dimensions included transportation versus water versus energy asset classes, cloud-based versus hybrid versus on-premises architectures, and predictive maintenance versus compliance management service mixes. CAGRs derived from infrastructure investment trajectories, regulatory mandate implementation timelines, and sensor network densification curves.
Material uncertainties — federal appropriation volatility, cybersecurity certification delays, and legacy SCADA retrofit cost overruns — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and municipal procurement cycle normalization. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Asset Management
Asset Optimization Solutions Market
Asset Management
Japan Asset Management Market
Asset Management
Assets Under Management Market
Asset Management
India AMC Industry Market
Asset Management
Canada Asset Management Market
Asset Management
US Asset Management Market
Asset Management
Fund Management Software Market
Asset Management
Canada Pension Fund Market
Asset Management
Healthcare Asset Management Market
Asset Management
Global AI in Asset Management Market
Asset Management
LAMEA Equity Management Software Market
Asset Management
India Mutual Fund Market
Asset Management
Asia-Pacific Utilities Asset Management Market
Asset Management
India Asset Management Market
Asset Management
Global Asset Performance Management Market
Asset Management
Hardware Asset Management Market