
 Global Fund Accounting Software Market | 2026-2036
Global Fund Accounting Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fund Accounting Software Market Foresight
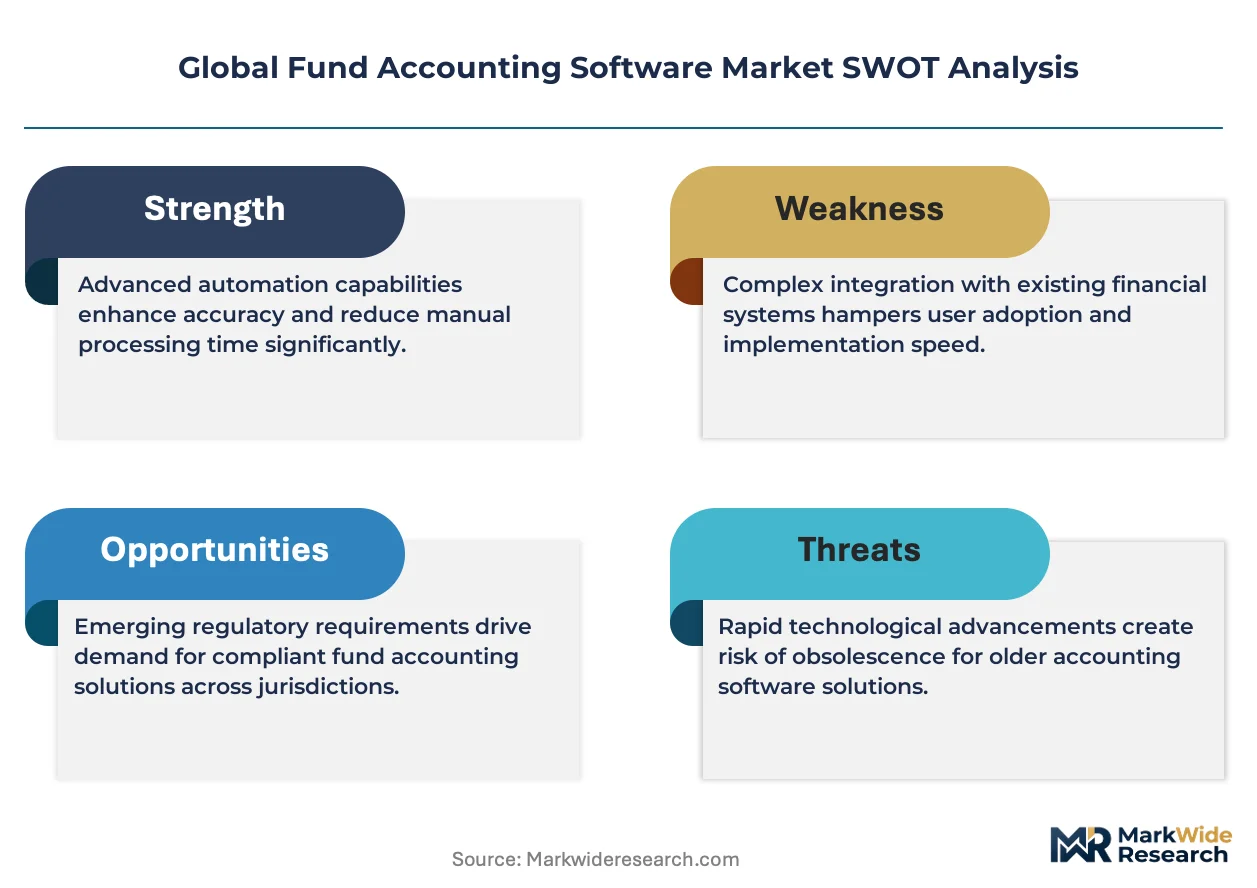
API-first architecture is broadening the interoperability of fund accounting platforms with external data providers and custodian banks. SS&C Technologies leverages its custody network to anchor enterprise-scale deployments across North America and Europe. Sage Group competes through modular cloud offerings tailored to mid-tier asset managers. Oracle dominates in on-premises environments where large sovereign wealth entities require customized ledger configurations.
Fund accounting software encompasses systems that automate general ledger operations, portfolio valuation, and investor reporting for investment management entities, typically processing multi-currency transactions across complex fund structures with NAV calculation accuracy requirements measured in basis points. The primary commercial purpose centers on eliminating manual reconciliation errors while compressing month-end close cycles for asset servicers and fund administrators. Cloud-based deployment leads solution adoption as pension funds and family offices migrate away from legacy client-server installations, while compliance management modules represent the fastest-expanding solution type due to proliferating ESG reporting mandates and alternative investment transparency requirements. Portfolio accounting retains the deepest margin pools among solution categories because implementation complexity sustains multi-year professional services attachments.
The SEC enforces investment adviser custody rules that mandate independent fund accounting verification, directly elevating demand for third-party reconciliation software among US-registered managers. EBA stress-testing guidelines and the EU SFDR compel European asset managers to upgrade reporting infrastructure, tightening compliance software specifications across the continent. Stakeholders must monitor whether emerging central bank digital currency frameworks will force ledger recoding or create entirely new asset-class accounting conventions.
Market Dynamics
Cloud-native ledger architectures are compressing implementation timelines for fund administrators while simultaneously fragmenting vendor competitive moats previously anchored to on-premises customization depth.
Growth Catalysts
- EU AI Act compliance mandates:Asset servicers across Germany, France, and Italy must deploy algorithmic audit trails for NAV calculation engines, forcing infrastructure refreshes.
- Tokenized fund structures:Luxembourg and Singapore regulators have approved security token frameworks that require real-time ledger reconciliation capabilities.
- Family office consolidation:Single-family offices with over $500 million AUM are aggregating into multi-family structures, demanding scalable accounting platforms.
Market Restraints
- Specialized talent scarcity:Fund accounting software implementation requires professionals fluent in both GAAP/IFRS standards and Python-based API integration.
- Custodian bank concentration:Three global custodians control over 60% of securities data feeds, creating single-point-of-failure risk for reconciliation accuracy.
- Legacy system entrenchment:Sovereign wealth funds in the Gulf and East Asia operate 15-20 year old COBOL-based ledgers with prohibitive migration costs.
Strategic Opportunities
- India's mutual fund expansion:SEBI's 2023 regulatory sandbox for fintech-driven fund administration has opened pathways for cloud-native entrants.
- Carbon accounting module bundling:The EU CSRD requires Scope 3 emissions disclosure from portfolio companies, creating attach-rate potential for ESG-integrated platforms.
- Blockchain-DLT convergence:Smart contract-based NAV calculation is enabling T+0 settlement pilots for private fund interests.
Industry Challenges
- Multi-GAAP reconciliation complexity:Cross-border funds operating across US GAAP, IFRS, and UK GAAP jurisdictions require manual overlay workflows that automation has not fully eliminated.
- Certification timeline compression:SOC 1 Type II audits for fund accounting platforms now require 12-month observation periods, delaying go-live dates for new deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fund Accounting Software Market |
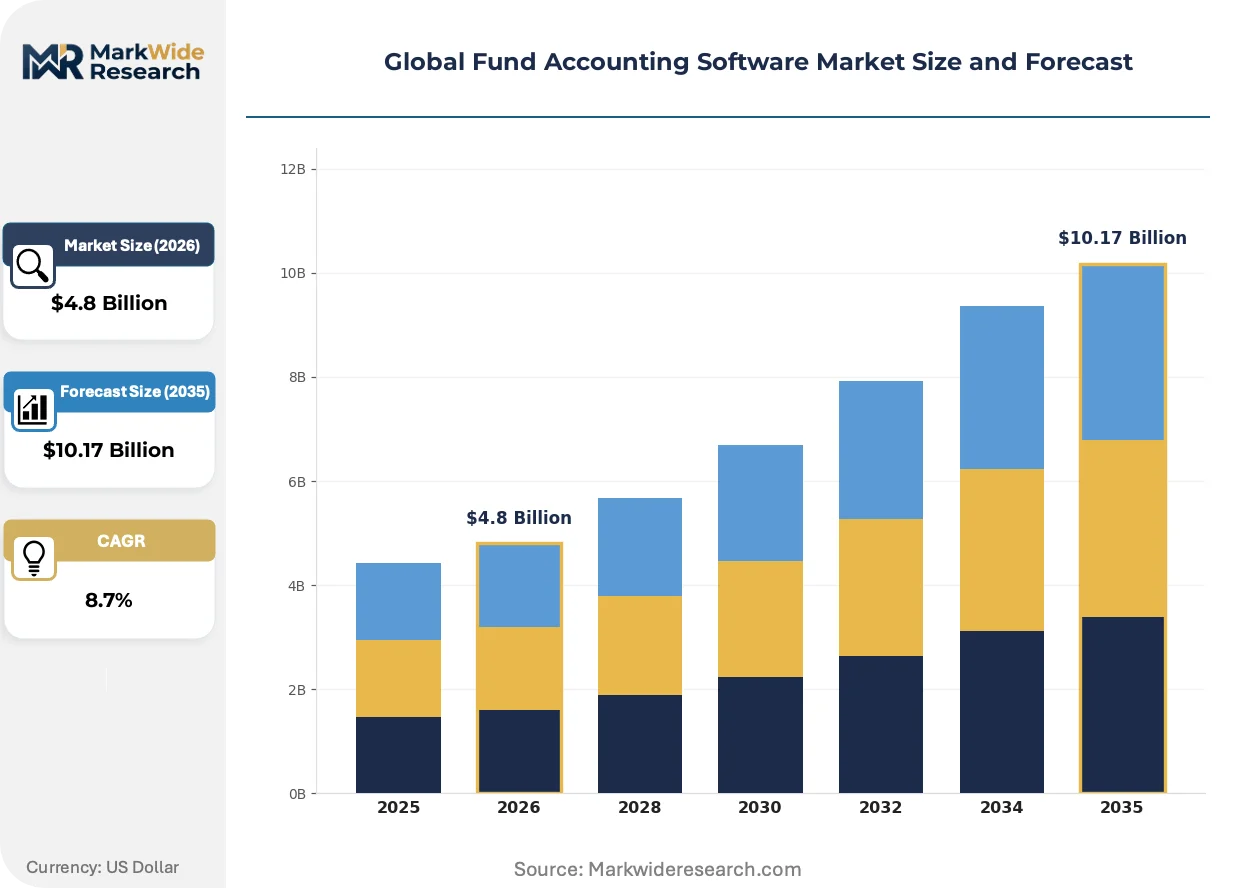
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Hosted, Managed Services Solution Type: General Ledger, Portfolio Accounting, Compliance Management, Investor Reporting, Reconciliation End User: Asset Managers, Pension Funds, Hedge Funds, Family Offices, Sovereign Wealth Entities Investment Strategy: Equity, Fixed Income, Real Assets, Private Equity, Venture Capital |
| Companies Covered | NetSuite, Sage Group, SS&C Technologies, FIS, Oracle, Blackbaud, FinancialForce, Fund EZ, AccuFund, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fund Accounting Software Market Shifts & Advancements
Distributed ledger protocols are reconfiguring custody data flows while regulatory fragmentation across jurisdictions accelerates modular platform architecture investments.
API-first core banking connectivity is decentralizing the fund accounting vendor landscape by enabling mid-tier asset managers to assemble best-of-breed reconciliation, valuation, and reporting components rather than accepting monolithic suites. US mid-market hedge funds and UK private equity firms are adopting this composable approach fastest, compressing traditional 18-month implementation cycles to under 90 days for standardized workflows.
The SEC's climate disclosure rules and the EU SFDR are forcing parallel reporting infrastructure builds that consume 15-20% of annual IT budgets for fund administrators with cross-border operations. Asset servicers are responding by embedding regulatory rule engines directly into ledger platforms rather than maintaining separate compliance overlays.
Subscription-based pricing for accounting modules is displacing perpetual license models among pension funds and insurance asset managers in Australia and Canada. Buyers now prefer consumption-linked contracts tied to NAV calculation volume or investor report distribution frequency, shifting vendor revenue recognition from upfront to recurring streams and compressing sales cycle negotiation timelines.
Global Fund Accounting Software Market Segmentation
Fund accounting software procurement hinges on infrastructure maturity, regulatory exposure, and asset-class complexity. Buyers weigh cloud migration readiness against legacy system entrenchment while calibrating solution depth to fund structure intricacy.
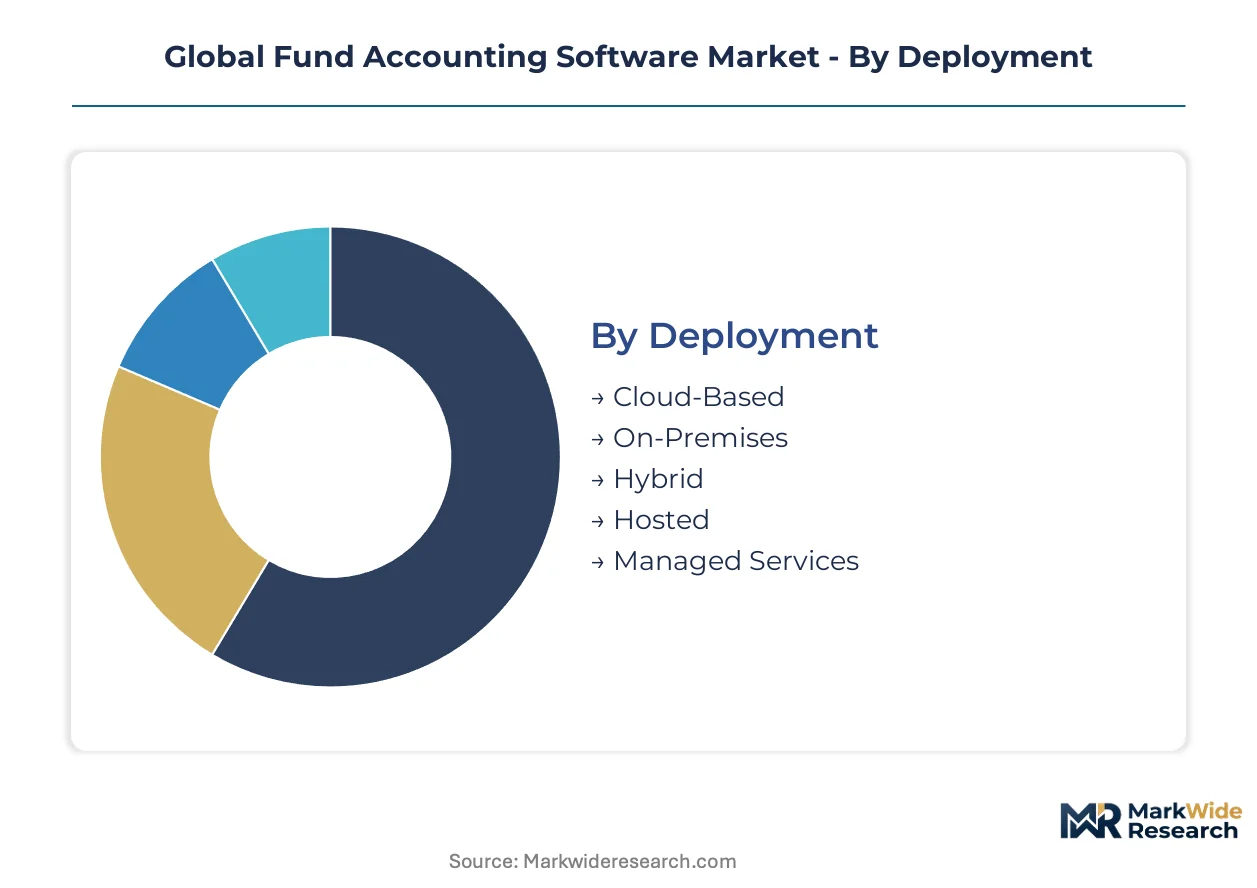
Deployment:
IT budget elasticity and data sovereignty requirements shape deployment selection for asset servicers.
- Cloud-Based:Multi-tenant SaaS architectures enable elastic NAV calculation capacity during month-end peaks. Demand concentrates among US mid-market hedge funds and UK private equity firms seeking compressed implementation timelines.
- On-Premises:Dedicated hardware installations support customized ledger configurations with direct database access. Sovereign wealth entities in the Gulf and East Asia retain these deployments due to data localization mandates and 15-20 year amortization schedules.
- Hybrid:Split architectures segregate sensitive investor data on-premises while routing non-critical workflows to cloud instances.
- Hosted:Single-tenant private cloud deployments managed by third-party infrastructure providers offer middle-ground control.
- Managed Services:Fully outsourced accounting operations bundled with software licensing appeal to family offices lacking internal operations teams.
Cloud-Based leads on scale; Hybrid leads on momentum as regulatory clarity improves.
Solution Type:
Functional priority sequencing follows compliance pressure intensity and workflow automation potential.
- General Ledger:Core double-entry systems processing multi-currency transactions across master-feeder fund structures. Asset managers in Germany and France prioritize these modules for EU AI Act audit trail requirements.
- Portfolio Accounting:Position-level valuation engines handling complex derivatives, side pockets, and illiquid marks. Implementation complexity sustains multi-year professional services attachments, deepening margin pools.
- Compliance Management:Regulatory rule engines embedding SEC climate disclosure and EU SFDR reporting workflows. This segment expands most quickly as ESG mandates proliferate.
- Investor Reporting:Automated statement generation and capital call distribution notices for limited partners.
- Reconciliation:Automated matching of custodian data against internal records with exception management workflows.
Portfolio Accounting leads on scale; Compliance Management leads on momentum.
End User:
Organizational complexity and AUM scale determine platform sophistication requirements.
- Asset Managers:Diverse product ranges spanning mutual funds, ETFs, and separate accounts. US-registered managers drive third-party reconciliation software demand under SEC custody rule mandates.
- Pension Funds:Long-horizon liabilities requiring liability-driven investment accounting. Canadian and Australian public pension funds are migrating from perpetual licenses to consumption-linked contracts.
- Hedge Funds:High-frequency trading operations and prime brokerage relationships. Mid-market US hedge funds adopt API-first composable architectures fastest.
- Family Offices:Consolidated reporting across direct investments, fund commitments, and operating assets. Single-family offices with over $500 million AUM are aggregating into multi-family structures.
- Sovereign Wealth Entities:Multi-asset-class portfolios with geopolitical constraints on vendor selection. COBOL-based legacy systems in Asia and the Middle East create prohibitive migration costs.
Asset Managers leads on scale; Family Offices leads on momentum.
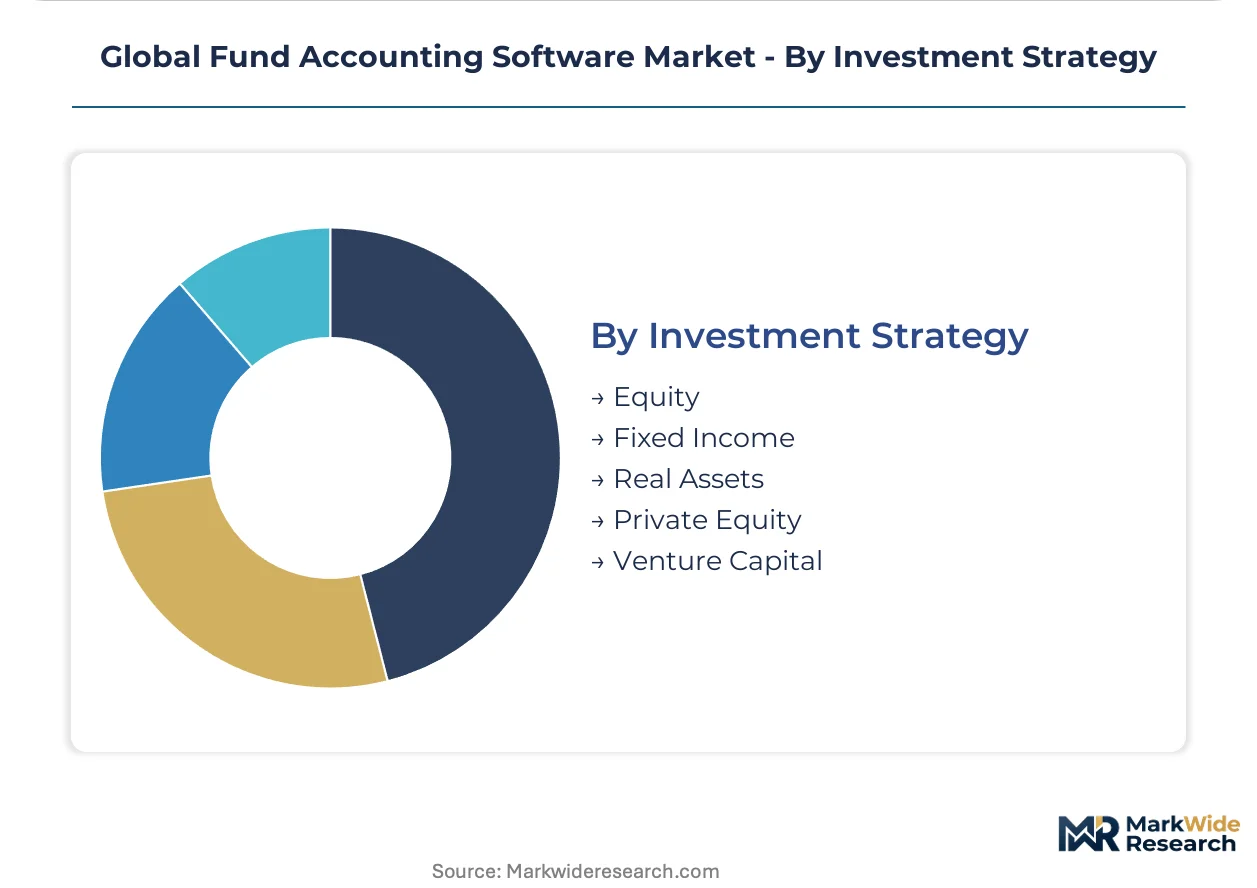
Investment Strategy:
Valuation methodology complexity and liquidity profile drive accounting engine specifications.
- Equity:Long-short and market-neutral strategies requiring real-time position tracking and financing cost attribution. Demand clusters among quantitative managers in Connecticut and London.
- Private Equity:Illiquid holdings with multi-year lockups, waterfall calculations, and carried interest modeling. Luxembourg and Singapore security token frameworks now require real-time ledger reconciliation for fund interests.
- Fixed Income:Accrued interest, amortization schedules, and credit derivative overlays.
- Real Assets:Infrastructure and natural resource investments with depreciation and depletion accounting.
- Venture Capital:Early-stage equity with milestone-based valuation and pro-rata rights tracking.
Equity leads on scale; Private Equity leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial centers in Manhattan, London, and Singapore anchor procurement patterns for fund accounting software. Regulatory divergence across jurisdictions fragments deployment strategies. Cloud-native platforms gain traction where data localization rules remain permissive.
United States
Mid-market hedge funds in Connecticut and private equity firms in New York drive API-first adoption. The SEC enforces investment adviser custody rules mandating independent verification systems. Boston-based asset servicers compress implementation timelines through composable architectures.
United Kingdom
Private equity firms in London and Edinburgh seek modular cloud offerings for waterfall calculations. The FCA implements operational resilience requirements affecting fund administrator technology stacks. The City of London concentrates demand for real-time reconciliation capabilities.
Germany
Asset managers in Frankfurt and Munich upgrade general ledger systems for EU AI Act audit trail mandates. BaFin supervises algorithmic transparency requirements for NAV calculation engines. The Mainhattan financial district hosts infrastructure refreshes across custodian banks.
Singapore
Family offices and sovereign wealth entities adopt platforms for security token frameworks approved by the Monetary Authority of Singapore. The jurisdiction's regulatory sandbox enables T+0 settlement pilots for private fund interests. Marina Bay financial hub attracts cloud-native entrants from global vendors.
India
Mutual fund administrators in Mumbai and Bangalore respond to SEBI's 2023 fintech sandbox for fund administration. The central bank's digital currency pilots prompt ledger recoding discussions. The Bandra-Kurla Complex emerges as a procurement cluster for consumption-linked contracts.
Global Fund Accounting Software Market Competitive Landscape
Global majors compete with regional champions across custody network depth and cloud delivery models. The vendor base stratifies into three tiers: enterprise-scale suite providers, mid-market modular specialists, and niche reconciliation tool vendors. Strategic moves concentrate on custody data feed partnerships and API ecosystem expansion. Vertical integration into professional services deepens margin capture for complex implementation workflows.
Within the enterprise tier, Oracle and SS&C Technologies occupy positions anchored to on-premises customization and custody network scale respectively. Sage Group exemplifies the mid-market modular archetype with cloud-native offerings. These three entities represent distinct competitive vectors: legacy ledger dominance, custody-integrated distribution, and agile cloud delivery for tier-two asset managers.
| Leading Market Players |
|---|
| NetSuite |
| Sage Group |
| SS&C Technologies |
| FIS |
| Oracle |
| Blackbaud |
| FinancialForce |
| Fund EZ |
| AccuFund |
| Others |
Supply & Pricing Matrix
Enterprise-mid-market tier divergence separates custody-integrated suite providers from modular cloud specialists, with the former commanding annual subscriptions exceeding seven figures for multi-entity NAV consolidation while the latter capture mid-tier asset managers through consumption-linked contracts tied to calculation volume. This bifurcation maps directly onto supply chain concentration: custody data feed dependencies anchor premium pricing to three global banks controlling securities infrastructure, whereas API-first vendors source reconciliation engines from distributed fintech providers.
Pricing Analysis
Input-cost pass-through from custody data licensing fees intensifies pricing pressure on mid-market deployments, compressing margins for fund administrators serving sub-$5 billion AUM clients. Three-tier pricing structure across premium, standard, and economy levels differentiates by integration complexity and SOC 1 Type II certification status. Cost compression in the standard tier is intensifying because custodian bank concentration limits vendor negotiation leverage. Family offices and emerging multi-family structures exhibit highest price sensitivity, while sovereign wealth entities in the Gulf demonstrate lowest sensitivity due to data localization mandates requiring bespoke on-premises configurations.
Supply Chain Analysis
Single-source vulnerability sits with custodian banks in the United States, United Kingdom, and Luxembourg controlling over sixty percent of securities data feeds. Software development draws from engineering talent pools in India, Ireland, and Poland for back-end ledger architecture. Tariff exposure on cloud infrastructure services creates margin risk for vendors reliant on hyperscaler compute. Distribution runs through direct enterprise sales teams for complex implementations and channel partners for standardized SaaS modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act compliance deadline compounds demand for algorithmic audit trail infrastructure, elevating fund accounting software from operational utility to regulatory necessity across European asset servicers.
For Market Incumbents: Acquire custody data feed exclusivity arrangements to defend against API-first modular entrants eroding enterprise client relationships. Expand professional services capacity in Frankfurt and Singapore to capture implementation complexity premiums from tokenized fund structure mandates. Regulatory timeline compression for SOC 1 Type II certification represents the primary margin pressure point requiring operational investment.
For New Entrants and Emerging Players: SEBI's 2023 fintech sandbox in India opens a window for cloud-native entrants to establish reference architectures before incumbent localization. Target mid-market hedge funds in Connecticut seeking sub-90-day implementation cycles through composable reconciliation components. Carbon accounting module bundling offers the most penetrable attach-rate opportunity as EU CSRD Scope 3 disclosure requirements proliferate.
For Investors and Strategic Acquirers: Consolidation pressure builds where custody network scale intersects with cloud delivery capability gaps among regional champions. Five-to-ten year viability favors vendors with demonstrated API ecosystem depth and regulatory rule engine embedment. Acquisition target archetype: mid-tier modular specialists with proven India delivery capacity and existing Luxembourg regulatory sandbox participation. Monitor central bank digital currency pilot announcements as inflection indicator for ledger recoding demand.
| Strategic Initiative | Industry Significance |
|---|---|
| API Ecosystem Expansion | SS&C Technologies leverages custody network scale to anchor interoperability with external data providers. |
| Regulatory Rule Engine Embedment | Embedding EU SFDR and SEC climate disclosure workflows directly into ledger platforms reduces compliance overlay maintenance. |
| Cloud-Native Architecture Migration | Sage Group captures mid-tier asset managers through modular offerings compressing traditional eighteen-month cycles. |
| Professional Services Verticalization | Complex portfolio accounting implementations sustain multi-year attachments deepening margin capture. |
| Security Token Framework Certification | Luxembourg and Singapore regulatory approvals require real-time ledger reconciliation capabilities for fund interests. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fund administrators, asset servicers, compliance officers, and custodian bank technology leads against secondary validation through SEC custody rule filings, EBA stress-testing guidelines, SEBI sandbox documentation, and EU SFDR technical standards. Bottom-up deployment estimates across cloud, on-premises, and hybrid architectures triangulated with top-down vendor revenue segmentation.
Segment-weighting approach distributed value projections across deployment models, solution types, end-user categories, and investment strategies, with regional allocation calibrated to regulatory implementation timelines. CAGRs derived from elasticity modeling of NAV calculation volume growth against compliance module attach rates. Forecast inputs incorporated central bank digital currency pilot progression and tokenized fund structure regulatory approvals.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated CBDC mandate introduction or custodian bank data feed consolidation. Forecasts reflect documented assumptions regarding regulatory timeline adherence and cloud migration velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accounting and Taxation Services
Crypto Tax Software Market
Accounting and Taxation Services
Global Financial Accounting Advisory Services Market
Accounting and Taxation Services
AI in Accounting Market
Accounting and Taxation Services
Bookkeeping Services Market
Accounting and Taxation Services
Tax Preparation Services Market
Accounting and Taxation Services
United Kingdom Accounting Software Market
Accounting and Taxation Services
US Accounting Software Market
Accounting and Taxation Services
Germany Accounting Software Market
Accounting and Taxation Services
Forensic Accounting Market
Accounting and Taxation Services
Global Artificial Intelligence for Accounting Market
Accounting and Taxation Services
US Auditing Services Market
Accounting and Taxation Services
Argentina Accounting Software Market
Accounting and Taxation Services
India Forensic Accounting Market
Accounting and Taxation Services
South Korea Accounting & Budgeting Software Market
Accounting and Taxation Services
Europe Forensic Accounting Market
Accounting and Taxation Services
India Accounting Software Market