
 Greece Life and Non-Life Insurance Market | 2026-2036
Greece Life and Non-Life Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Greece Life and Non-Life Insurance Market Foresight
Solvency II alignment through the Bank of Greece is pivoting capital reserve requirements for domestic underwriters. NN Hellenic Life Insurance Company leverages its bancassurance network to sustain premium flow across retail channels. Ethniki Hellenic General Insurance anchors property lines through its historic agency footprint in provincial Greece. Generali Hellas Insurance Company differentiates via specialized marine and cargo offerings tied to Piraeus port activity.
Greece life and non-life insurance encompasses risk transfer instruments covering mortality, morbidity, property damage, and third-party liability through contractual premium mechanisms governed by actuarial reserving and statutory solvency margins. Life Insurance and Health Insurance segments dominate premium income through long-duration individual policies with guaranteed minimum benefits, while Property Insurance captures catastrophe-exposed commercial lines requiring reinsurance backstops. Distribution Channel dynamics reveal Banks as the predominant policy origination point for life products, whereas Brokers control mid-market commercial non-life placement.
The Bank of Greece enforces Solvency II-derived capital standards and local fit-and-proper tests for board governance, while the Hellenic Competition Commission scrutinizes distribution exclusivity arrangements. EU Green Deal disclosure requirements are pressing insurers to model climate transition risks in liability reserves. Stakeholders must monitor how IFRS 17 implementation alters profit recognition timing and whether reinsurance capacity contraction reshapes Greek cession strategies.
Market Dynamics
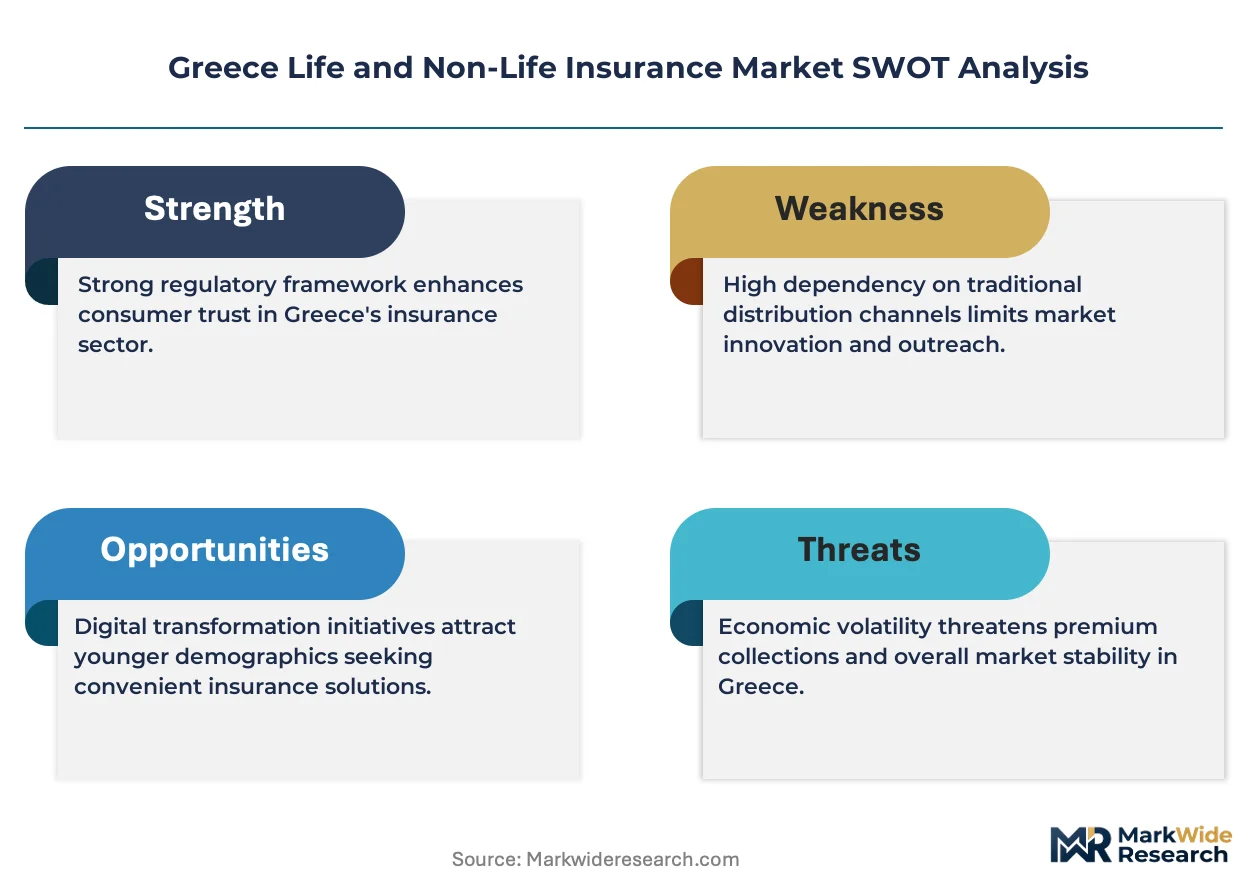
Solvency II capital adequacy thresholds enforced by the Bank of Greece are compressing risk-adjusted returns for domestic underwriters while accelerating consolidation among smaller regional insurers unable to meet elevated reserve requirements.
Growth Catalysts
- EU Green Deal disclosure mandates:Climate transition risk modeling requirements are expanding demand for specialized liability coverage among Piraeus-based shipping conglomerates.
- Athens metropolitan corridor:Concentrated wealth accumulation in Attica is driving premium growth for long-duration life products with guaranteed minimum benefits.
- Bancassurance networks:Embedded distribution through systemic Greek banks is capturing retail policy origination at lower customer acquisition cost than traditional agency channels.
Market Restraints
- Reinsurance capacity contraction:Catastrophe-exposed property lines face shrinking international backstop availability, forcing higher retention ratios on earthquake and flood risks.
- Low-yield sovereign debt:Persistent negative real returns on Greek government bonds are compressing investment income that supports guaranteed life product reserves.
- Provincial agency fragmentation:Historic Ethniki Hellenic General Insurance footprint in rural Greece carries fixed cost burdens disproportionate to premium density.
Strategic Opportunities
- Thessaloniki commercial hub:Northern Greece's industrial concentration remains underpenetrated for mid-market marine cargo coverage relative to Piraeus corridor saturation.
- Parametric insurance structures:Satellite-triggered climate payouts are converging with IoT sensor networks to displace traditional indemnity products in agricultural lines.
- IFRS 17 implementation timeline:Early compliance investment creates competitive separation between capital-resilient underwriters and laggards facing profit recognition volatility.
Industry Challenges
- Actuarial talent scarcity:Solvency II technical reserving expertise concentrates in Athens, leaving regional insurers dependent on outsourced consultancy relationships.
- Legacy policy administration systems:Core platform modernization requires capital commitments that conflict with Bank of Greece dividend restriction guidance during capital build phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Greece Life and Non-Life Insurance Market |
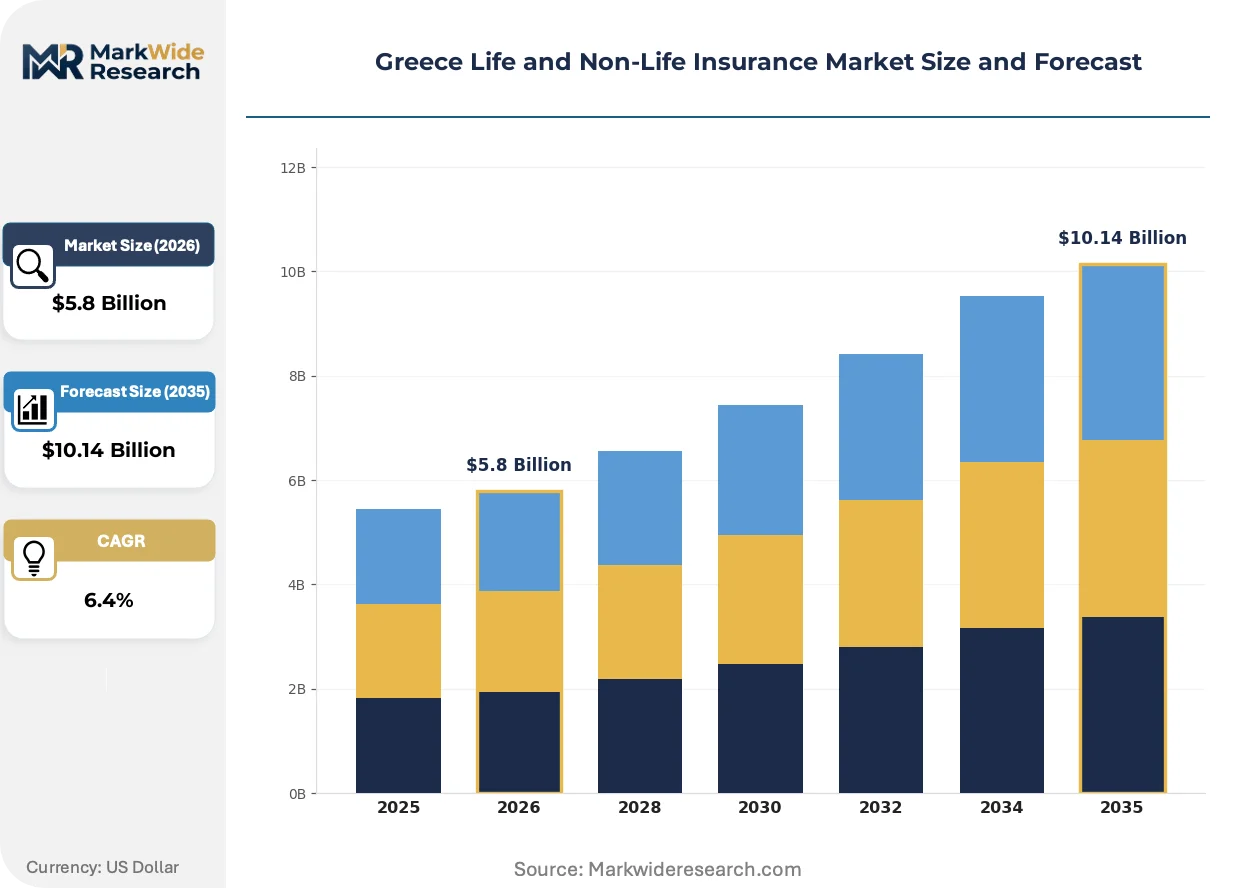
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Life Insurance, Health Insurance, Property Insurance, Liability Insurance Coverage Type: Individual Coverage, Group Coverage, Comprehensive Coverage, Basic Coverage Distribution Channel: Direct Sales, Brokers, Online Platforms, Banks Policy Term: Short-Term, Medium-Term, Long-Term, Lifetime |
| Companies Covered | NN Hellenic Life Insurance Company, ERGO Insurance Company, Ethniki Hellenic General Insurance Company, Groupama Phoenix Hellenic Insurance, AXA Insurance, Generali Hellas Insurance Company, Interamerican Hellenic Insurance, European Reliance General Insurance, Allianz Hellas Insurance Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Greece Life and Non-Life Insurance Market Shifts & Advancements
Digital distribution infrastructure and climate risk quantification are displacing traditional underwriting workflows across Greek insurance operations. These shifts are compressing policy issuance timelines while expanding data granularity for risk selection.
Telematics-enabled usage-based motor coverage is expanding into commercial fleet segments previously dominated by fixed-premium annual contracts. Logistics operators operating across the Athens-Thessaloniki corridor are adopting real-time driver behavior monitoring to capture premium discounts. This technology is expanding into risk-pooled pricing models that compress cross-subsidization between high and low-risk policyholders.
The Bank of Greece's Solvency II-derived fit-and-proper governance tests are tightening board composition requirements for domestic underwriters. Smaller regional insurers face elevated compliance costs to recruit qualified independent directors. The life insurance segment is responding by accelerating bancassurance partnerships that transfer governance burden to systemic bank parent structures.
Broker-controlled placement for mid-market commercial lines is fragmenting as direct digital channels capture standardized property and liability risks. Corporate risk managers in Thessaloniki manufacturing clusters are unbundling advisory services from policy placement to capture fee transparency. This behavioral shift is most visible among shipping-related enterprises seeking marine coverage alternatives to traditional Piraeus broker relationships.
Greece Life and Non-Life Insurance Market Segmentation
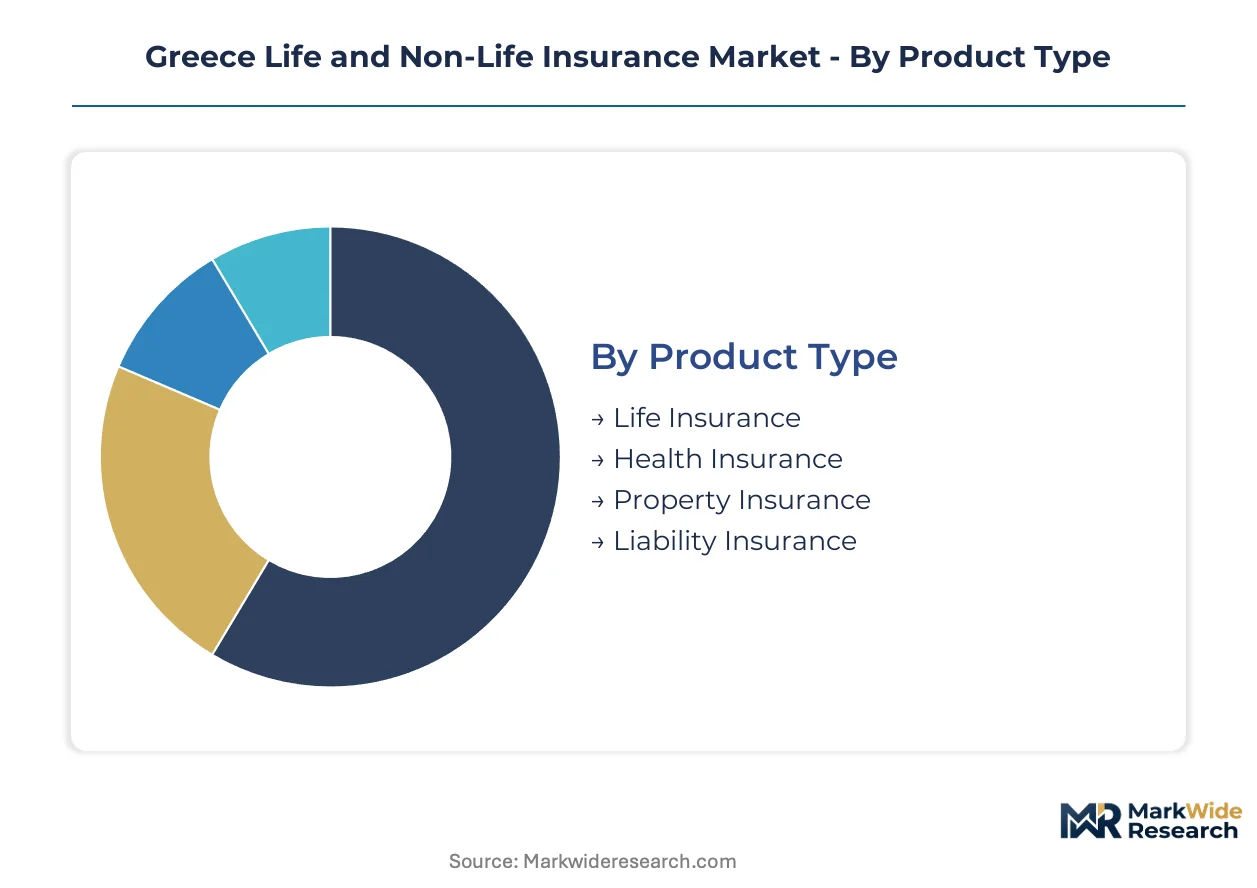
Greek insurance purchasing decisions pivot on risk duration, distribution accessibility, and coverage granularity. Each segmentation dimension reveals distinct buyer priorities across the Attica and Thessaloniki metropolitan corridors.
Product Type:
Premium allocation intensity drives product selection, with buyers weighing guaranteed benefit structures against catastrophe exposure tolerance.
- Life Insurance:Long-duration individual policies carry guaranteed minimum benefits backed by actuarial reserves. Athens metropolitan corridor concentrates demand from wealth accumulators seeking estate preservation instruments.
- Health Insurance:Morbidity coverage with outpatient and inpatient reimbursement tiers captures premium flow through employer-sponsored group schemes. Thessaloniki manufacturing clusters drive corporate placement volume for comprehensive medical benefits.
- Property Insurance:Catastrophe-exposed commercial lines require reinsurance backstops for earthquake and flood risks. Piraeus port logistics operators anchor demand for industrial asset protection.
- Liability Insurance:Third-party coverage spans professional indemnity and marine cargo liability. Greek shipping conglomerates expanding fleets generate specialized marine liability placement.
Life Insurance leads on scale; Health Insurance leads on momentum.
Coverage Type:
Organizational size and risk pooling economics determine whether buyers select individual or collective coverage structures.
- Individual Coverage:Single-policyholder contracts with customized benefit riders serve high-net-worth households in Attica. Bancassurance networks capture origination through embedded bank distribution.
- Group Coverage:Employer-sponsored schemes pool mortality and morbidity risks across employee bases. Mid-market manufacturers in Thessaloniki industrial zones drive placement volume.
- Comprehensive Coverage:All-risk policies bundling property, liability, and business interruption protection command premium multiples over basic tiers. Piraeus shipping enterprises favor bundled marine and cargo protection.
- Basic Coverage:Named-peril policies with coverage caps and higher deductibles serve price-sensitive rural households. Ethniki Hellenic General Insurance's provincial agency footprint distributes these tiers.
Group Coverage dominates premium volume; Comprehensive Coverage gains share fastest.
Distribution Channel:
Customer acquisition cost and advisory intensity channel buyers toward direct, intermediated, or embedded purchase paths.
- Direct Sales:Insurer-employed agents handle policy origination and servicing without intermediary commissions. NN Hellenic Life Insurance Company leverages captive agency forces for guaranteed product distribution.
- Brokers:Independent intermediaries control mid-market commercial non-life placement with unbundled advisory services. Corporate risk managers in Thessaloniki manufacturing clusters seek fee transparency through broker relationships.
- Online Platforms:Digital direct channels capture standardized property and motor risks with compressed issuance timelines. Telematics-enabled usage-based motor coverage expands through platform distribution.
- Banks:Bancassurance partnerships embed life product origination within systemic Greek bank branch networks. Lower customer acquisition costs relative to traditional agency channels sustain premium flow.
Banks lead on scale; Online Platforms lead on momentum.
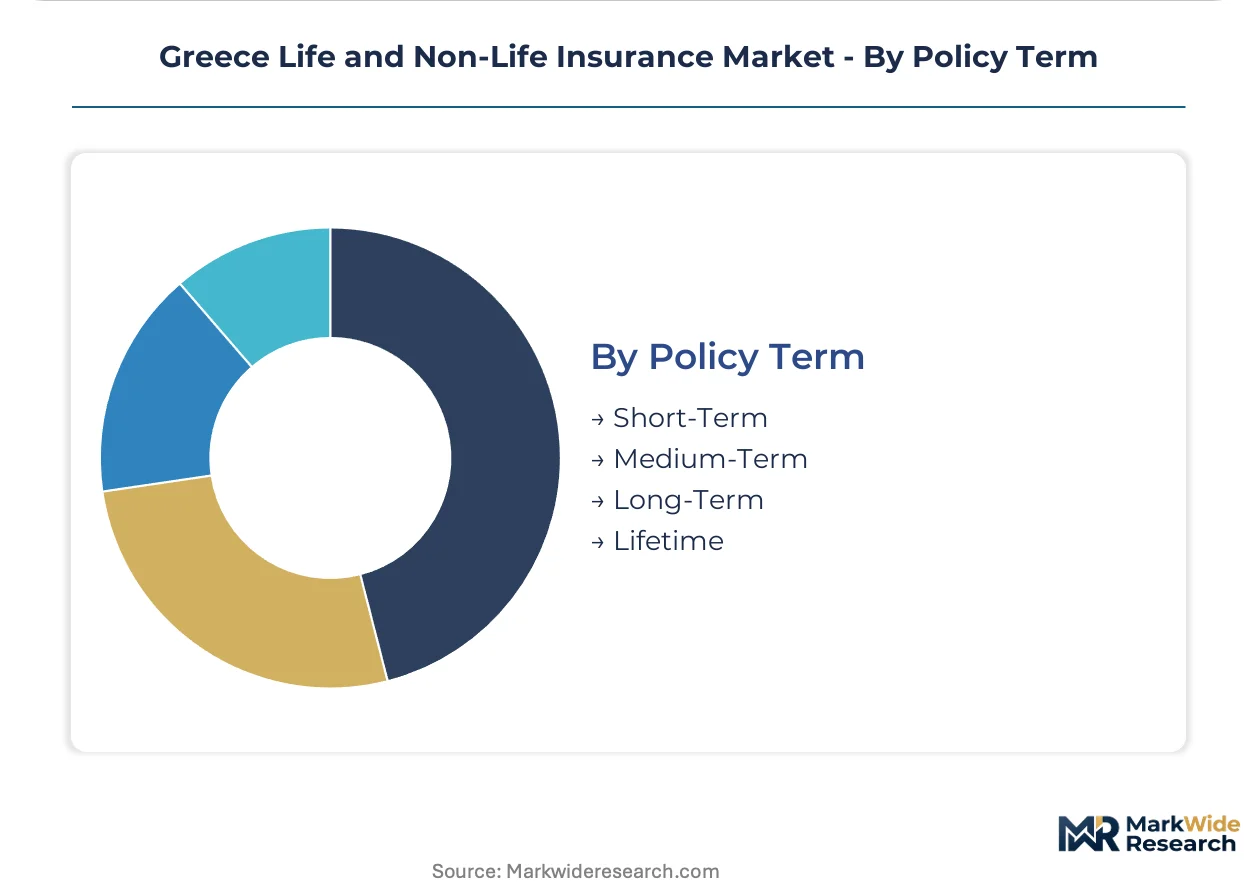
Policy Term:
Liability duration and investment horizon alignment shape term selection across mortality, property, and casualty lines.
- Short-Term:Annual renewable contracts for travel, event cancellation, and seasonal property risks. Tourism operators in Cyclades islands generate concentrated demand for temporary coverage.
- Medium-Term:Three-to-five-year guaranteed renewable structures for health and property lines. Small enterprises in provincial Greece favor predictable premium commitments.
- Long-Term:Ten-to-twenty-year life policies with level premiums and guaranteed interest rate floors. Negative real returns on Greek government bonds compress investment income supporting these reserves.
- Lifetime:Whole life and universal life contracts extending to mortality with cash value accumulation. Athens wealth management advisors recommend these structures for estate liquidity.
Long-Term leads on scale; Short-Term leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Modern insurance practice in Greece traces its codified roots to the 19th-century marine underwriters of Piraeus and Syros, where Ottoman-era customary law first intersected with Lloyd's-style risk pooling for Mediterranean shipping.
Attica
Athens metropolitan corridor concentrates wealth management advisory services driving long-duration life policy origination. Bank of Greece solvency supervision enforces fit-and-proper governance tests compressing smaller underwriter margins. Piraeus port logistics operators anchor specialized marine cargo liability placement.
Central Macedonia
Thessaloniki industrial zones generate employer-sponsored group health scheme demand from manufacturing clusters. EU Green Deal disclosure mandates press regional underwriters to model climate transition risks in liability reserves. Thermi and Sindos logistics parks drive mid-market commercial non-life penetration.
South Aegean
Cyclades island tourism operators generate concentrated seasonal demand for short-term travel and event cancellation coverage. Solvency II capital adequacy thresholds enforced through the Bank of Greece limit regional insurer participation in catastrophe-exposed property lines. Santorini and Mykonos hospitality clusters favor parametric weather-triggered structures over traditional indemnity products.
Peloponnese
Patras port activity and Corinth Canal transit generate marine hull and cargo insurance placement. Ethniki Hellenic General Insurance's historic agency footprint distributes basic coverage tiers to price-sensitive rural households. Kalamata agricultural cooperatives pilot satellite-triggered parametric crop protection.
Epirus
Ioannina and Preveza commercial centers remain underpenetrated for comprehensive business coverage relative to Attica saturation. Reinsurance capacity contraction for earthquake-exposed property lines forces higher retention ratios on regional underwriters. Zagori tourism microenterprises adopt usage-based motor coverage through telematics-enabled platforms.
Greece Life and Non-Life Insurance Market Competitive Landscape
The competitive structure tilts toward bancassurance-anchored conglomerates with systemic bank parentage. Domestic underwriters cluster around three tiers: international group subsidiaries leveraging global reinsurance relationships, historic Greek insurers maintaining provincial agency networks, and digital-first challengers compressing issuance timelines. Consolidation accelerates as Solvency II reserve requirements squeeze regional carriers. Strategic moves center on bancassurance partnership deepening and parametric product development.
Among international group subsidiaries, NN Hellenic Life Insurance Company and Generali Hellas Insurance Company exemplify the bancassurance-integrated archetype. Ethniki Hellenic General Insurance occupies a position representing the historic domestic carrier with entrenched provincial distribution. These three anchors illustrate divergent responses to regulatory capital pressure: embedded bank channel capture, specialized marine line differentiation, and legacy agency network rationalization.
| Leading Market Players |
|---|
| NN Hellenic Life Insurance Company |
| ERGO Insurance Company |
| Ethniki Hellenic General Insurance Company |
| Groupama Phoenix Hellenic Insurance |
| AXA Insurance |
| Generali Hellas Insurance Company |
| Interamerican Hellenic Insurance |
| European Reliance General Insurance |
| Allianz Hellas Insurance Company |
| Others |
Supply & Pricing Matrix
Bancassurance-anchored conglomerates with systemic bank parentage dominate ownership structures across Greek insurance, compressing distribution costs while concentrating pricing power among NN Hellenic Life Insurance Company and Generali Hellas Insurance Company. This ownership pattern feeds into supply chain choices that favor embedded bank channels over independent broker networks, shaping both premium collection efficiency and capital reserve deployment discipline enforced by the Bank of Greece.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs product placement, with guaranteed minimum benefit riders and Solvency II capital adequacy thresholds as primary differentiation drivers. Cost compression in economy tiers is intensifying because regional insurers face elevated reserve requirements without bancassurance scale economies. Piraeus-based shipping conglomerates exhibit lowest price sensitivity for marine liability coverage, while rural households distributed through Ethniki Hellenic General Insurance's provincial footprint drive economy-tier volume.
Supply Chain Analysis
EU Green Deal disclosure mandates reshaping sourcing are pressing Greek underwriters to model climate transition risks in liability reserves, altering reinsurance cession strategies. Geographic supply concentration draws from Germany, Luxembourg, and London for treaty reinsurance capacity, with actuarial talent and core platform technology as critical component dependencies. Single-source vulnerability in international reinsurance backstops for catastrophe-exposed property lines forces higher retention ratios. Distribution runs through bancassurance networks for life products and broker-controlled placement for mid-market commercial non-life lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Greek insurance represents a late-cycle quality story as wealth accumulators in the Athens metropolitan corridor shift demand toward long-duration life products with guaranteed minimum benefits and estate preservation specifications.
For Market Incumbents: Extend bancassurance partnership depth to capture governance burden transfer to systemic bank parent structures, while accelerating parametric product development for agricultural and tourism-exposed lines to offset reinsurance capacity contraction. Solvency II capital adequacy thresholds threaten regional carrier viability; vertical integration into captive reinsurance vehicles or strategic cession to EU-based treaty partners offers defensive positioning. For New Entrants and Emerging Players: The price-point gap between premium guaranteed-benefit life products and basic named-peril property coverage offers white-space targeting opportunity. Thessaloniki industrial zones remain underpenetrated for mid-market marine cargo coverage relative to Piraeus corridor saturation, with employer-sponsored group health schemes as the most penetrable segment. Direct digital channel deployment for standardized motor and property risks, coupled with telematics-enabled usage-based pricing, provides differentiated go-to-market positioning against legacy agency networks. For Investors and Strategic Acquirers: Pan-European insurance groups with existing Southern European footprints are the most active acquirer in this space, seeking distribution scale and Solvency II compliance infrastructure. Five-to-ten year viability favors targets with bancassurance integration depth or specialized marine line differentiation over pure-play regional carriers dependent on outsourced actuarial consultancy. Monitor Bank of Greece dividend restriction guidance and IFRS 17 implementation timelines as inflection indicators for capital-resilient underwriters versus laggards facing profit recognition volatility.| Strategic Initiative | Industry Significance |
|---|---|
| Bancassurance Partnership Deepening | Embedded distribution through systemic Greek banks captures retail policy origination at lower customer acquisition cost than traditional agency channels. |
| Parametric Product Development | Satellite-triggered climate payouts converge with IoT sensor networks to displace traditional indemnity products in agricultural and tourism-exposed lines. |
| Core Platform Modernization | Legacy policy administration system replacement requires capital commitments that conflict with Bank of Greece dividend restriction guidance during capital build phases. |
| Reinsurance Cession Restructuring | International treaty capacity contraction for catastrophe-exposed property lines forces higher retention ratios and alternative risk transfer exploration. |
| IFRS 17 Compliance Investment | Early implementation creates competitive separation between capital-resilient underwriters and laggards facing profit recognition timing volatility. |
Research Methodology
Coverage spans Attica, Central Macedonia, South Aegean, Peloponnese, and Epirus, with primary inputs from each region combined through triangulation of executive interviews with insurance company CFOs, Bank of Greece regulatory affairs officers, bancassurance distribution heads, and reinsurance treaty underwriters. Secondary validation draws from Bank of Greece solvency reports, Hellenic Competition Commission distribution exclusivity filings, EU Green Deal disclosure frameworks, and IFRS 17 implementation guidance documents. Bottom-up premium flow analysis and top-down macroeconomic scenario modeling were reconciled across the analytical envelope.
Granularity-level framing applied product type, coverage type, distribution channel, and policy term as core segmentation dimensions, with geographic concentration in Athens and Thessaloniki metropolitan corridors as an industry-specific overlay. CAGRs were derived through trend extrapolation anchored to historical premium growth patterns and regulatory capital requirement phase-in schedules. Reinsurance capacity availability, sovereign debt yield curves, and bancassurance network penetration served as sector-specific forecast inputs throughout the projection horizon.
Caveats apply where reinsurance capacity contraction, Greek government bond yield volatility, or Bank of Greece solvency enforcement intensity could materially shift the outlook for domestic underwriter profitability and consolidation timing. Forecasts reflect assumptions about regulatory implementation pace and capital market conditions without specific event prediction. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Life and Non Life Insurance
Canada Life and Non-Life Insurance Market
Life and Non Life Insurance
Iran Property and Casualty Insurance Market
Life and Non Life Insurance
UAE Life & Non-Life Insurance Market
Life and Non Life Insurance
Poland Life and Non-Life Insurance Market
Life and Non Life Insurance
US Burial Insurance Market
Life and Non Life Insurance
Australia Life and Non-Life Insurance Market
Life and Non Life Insurance
Russia Life and Non-Life Insurance Market
Life and Non Life Insurance
Children Life Insurance Market
Life and Non Life Insurance
Life Insurance Policy Administration System Market
Life and Non Life Insurance
Ireland Life and Non-Life Insurance Market
Life and Non Life Insurance
Global Life and Non-Life Insurance Market
Life and Non Life Insurance
Indonesia Life and Non-Life Insurance Market
Life and Non Life Insurance
Burial Insurance Market
Life and Non Life Insurance
Czech Republic Life & Non-Life Insurance Market
Life and Non Life Insurance
Malaysia Life Insurance Market
Life and Non Life Insurance
North America Business Income Insurance Market