
 India AMC Industry Market | 2026-2036
India AMC Industry Market Size, Share, and Industry Trends Forecast 2026-2036
India AMC Industry Market Insights
Passive index-tracking instruments are repositioning cost structures across the industry. SBI Mutual Fund leverages its expansive branch network to sustain dominance in tier-two and tier-three city penetration. ICICI Prudential Mutual Fund differentiates through hybrid product engineering that blends equity exposure with downside buffers. HDFC Mutual Fund anchors its competitive stance on direct-plan distribution scale and proprietary digital onboarding infrastructure.
Asset management companies pool capital from retail, institutional, and high-net-worth investors to deploy across equity, debt, and hybrid instruments governed by SEBI-mandated investment mandates and risk classification frameworks. Equity funds command the largest AUM base but face margin compression from regulatory fee caps, while robo-advisory services represent the fastest-growing service type as algorithmic allocation engines reduce human advisor dependency. Retail investor participation through systematic investment plans has emerged as the dominant growth engine, with direct investing channels capturing incremental flows from digitally native demographics.
SEBI's total expense ratio ceilings and mandatory risk-o-meter disclosures are reshaping product economics and distributor compensation structures across the industry. The RBI's monetary policy stance and the CEA's financial stability oversight jointly influence debt fund yield curves and liquidity conditions. Stakeholders must monitor the interplay between SEBI's evolving passive fund regulations and the competitive response of active managers as fee-based advisory models displace commission-driven distribution.
Market Dynamics
SEBI's total expense ratio compression is forcing active fund managers to restructure distributor incentives while accelerating the migration of household savings from physical assets to financial instruments through systematic investment plans.
Growth Catalysts
- Retail SIP Penetration:Monthly systematic investment flows from tier-two and tier-three cities are expanding the addressable investor base beyond traditional metropolitan centers.
- SEBI's Risk-O-Meter Mandate:Standardized six-category risk classification is improving product comparability and reducing information asymmetry for first-time equity investors.
- Digital KYC Infrastructure:Video-based customer onboarding and Aadhaar-linked e-signatures are collapsing account opening timelines from weeks to minutes.
Market Restraints
- Fee Compression Dynamics:SEBI-mandated TER ceilings are squeezing revenue yields on equity schemes to sub-fifty basis points for large-cap categories.
- Distributor Dependency:Commission-driven advisory networks in B-15 cities retain gatekeeper control over investor fund selection despite direct-plan proliferation.
- Debt Fund Liquidity Mismatches:RBI's stance on corporate bond market depth constrains open-ended schemes during redemption pressure episodes.
Strategic Opportunities
- Passive Fund White Space:Index funds and ETFs remain underpenetrated relative to active AUM, offering scale economics without research overhead.
- NPS Distribution Integration:Pension fund regulator PFRDA's tiered contribution structure creates captive annuity-linked asset accumulation pools.
- ESG-Themed Product Engineering:SEBI's BRSR disclosure requirements for listed corporates enable fund managers to construct sustainability-screened portfolios with verifiable data inputs.
Industry Challenges
- Quantitative Talent Scarcity:Algorithmic fund construction and risk analytics functions face acute shortages of domestic data science professionals with capital markets domain expertise.
- Legacy System Integration:Core banking platform migrations at sponsor banks are creating operational friction for AMCs dependent on shared technology infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India AMC Industry Market |
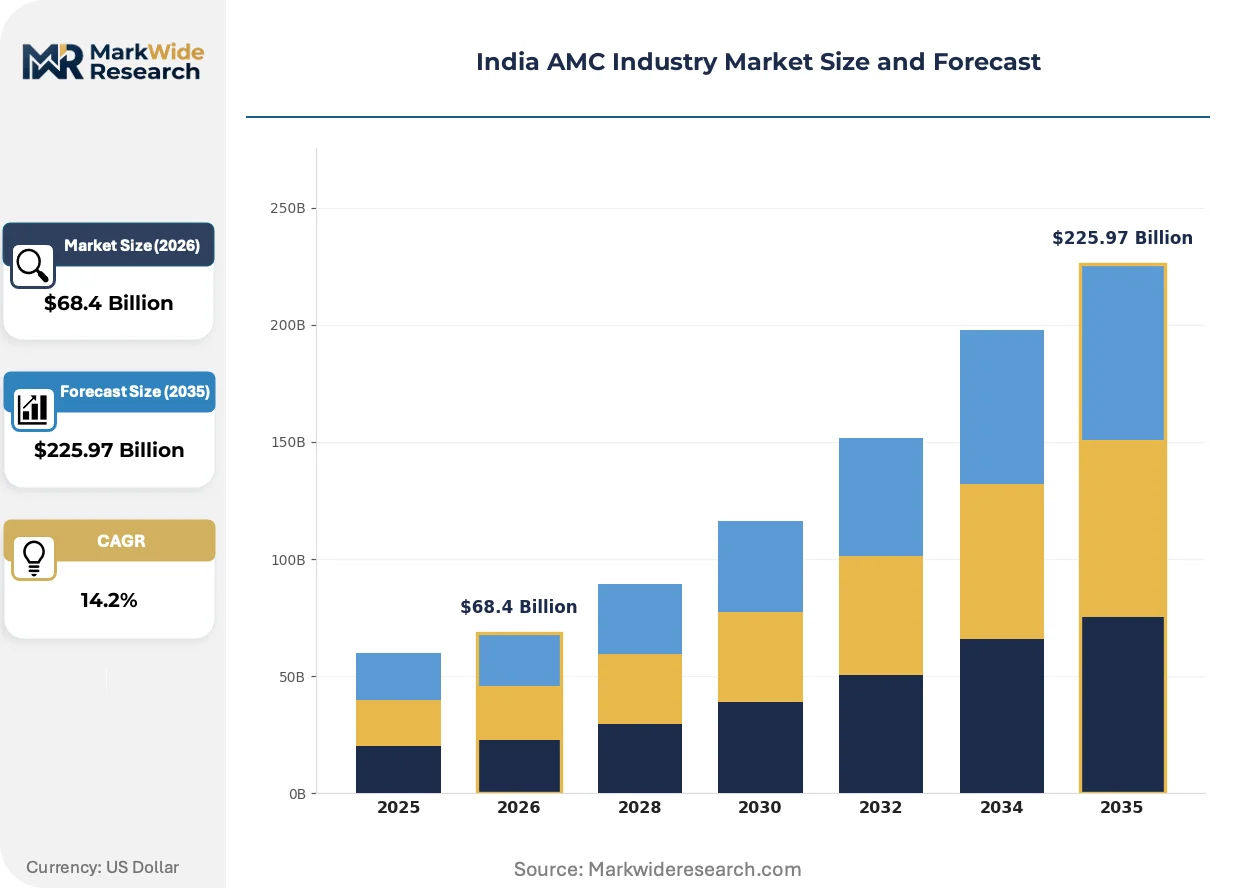
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $225.97 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fund Type: Equity Funds, Debt Funds, Hybrid Funds, Liquid Funds Investor Type: Retail Investors, Institutional Investors, HNWI, Corporates Investment Strategy: Growth Strategy, Value Strategy, Index Strategy, Sectoral Strategy Service Type: Direct Investing, Advisory Services, Discretionary Portfolio Management, Robo-Advisory |
| Companies Covered | SBI Mutual Fund, ICICI Prudential Mutual Fund, HDFC Mutual Fund, Nippon India Mutual Fund, Kotak Mahindra Mutual Fund, Aditya Birla Sun Life Mutual Fund, UTI Mutual Fund, Axis Mutual Fund, DSP Mutual Fund, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India AMC Industry Market Trends and Innovations
Robo-advisory engines and algorithmic portfolio construction are compressing the cost of personalized asset allocation while SEBI's regulatory sandbox enables controlled experimentation with alternative distribution models.
Artificial intelligence-driven risk profiling is automating the mapping of investor behavioral biases to suitable fund categories. Mid-tier AMCs are deploying these engines to match risk tolerance scores against SEBI-mandated product risk classifications. The technology is automating compliance with suitability requirements while reducing human advisor training costs.
SEBI's regulatory sandbox framework for fintech-enabled distribution is permitting limited-scale trials of voice-based transaction interfaces and goal-based SIP modification tools. The framework allows AMCs to test consent-layer innovations without full-scale licensing requirements. Digital-native distributors in Maharashtra and Karnataka are piloting these interfaces with millennial investor cohorts.
Direct-plan adoption is accelerating among digitally literate demographics who bypass distributor commissions entirely. Younger investors in Gujarat and Tamil Nadu are gravitating toward exchange-traded fund accumulation plans through discount brokerage platforms. This channel rotation is visible most prominently among urban professionals with self-directed research capabilities.
India AMC Industry Market Segmentation
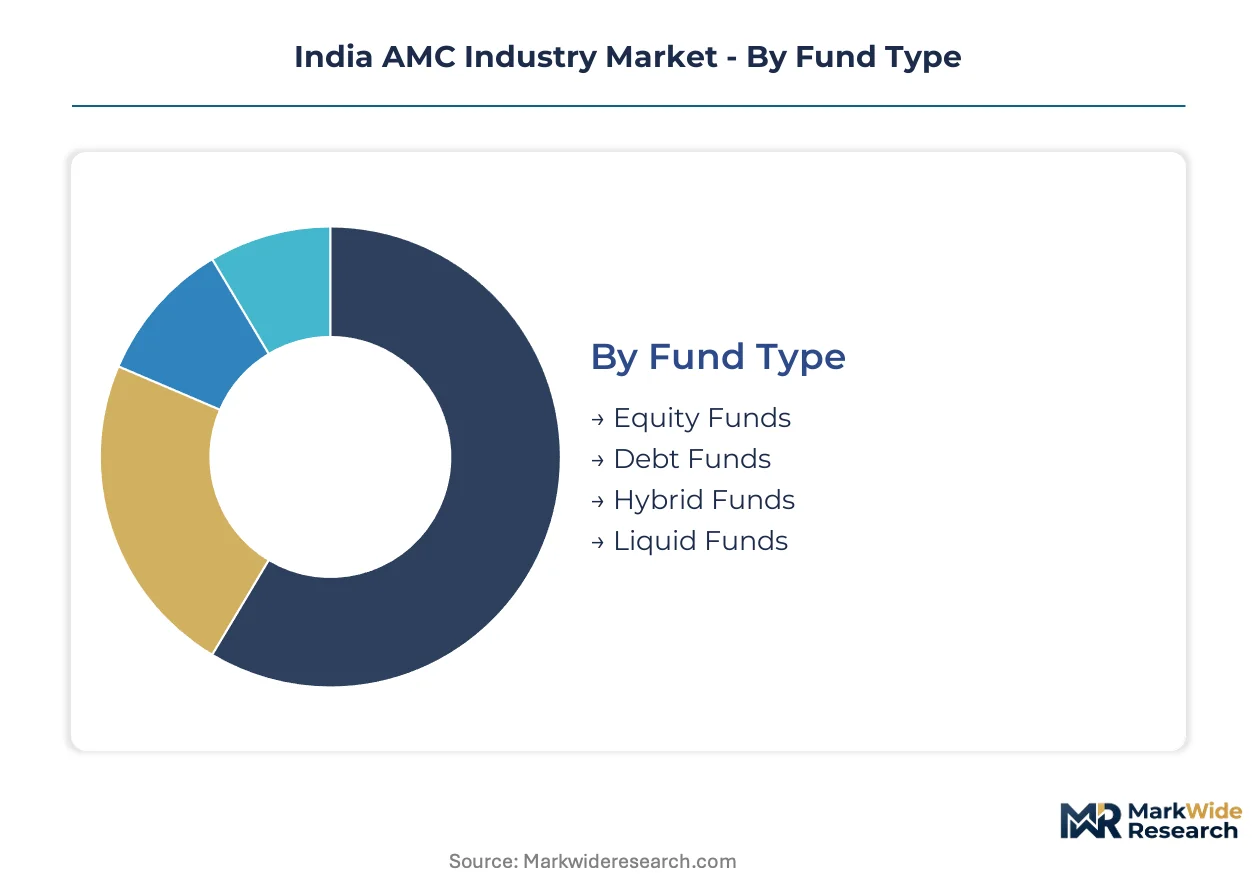
Asset management companies in India deploy distinct product architectures and distribution channels to capture varying risk appetites and wealth accumulation objectives. Segmentation clarity enables AMCs to align SEBI-mandated risk classifications with investor behavioral profiles and fee structures.
Fund Type:
Customization intensity varies sharply across this category, from standardized liquid products to actively managed equity constructs with bespoke sector tilts.
- Equity Funds:These schemes deploy capital across large-cap, mid-cap, and small-cap listed securities with SEBI-defined investment mandates. Demand concentrates in Maharashtra and Gujarat where urban investor density supports higher risk tolerance thresholds. SEBI's TER ceilings compress margins on large-cap categories most severely.
- Debt Funds:Fixed-income instruments invest across government securities, corporate bonds, and money market instruments governed by duration and credit quality parameters. Institutional treasuries in Mumbai and Delhi drive bulk flows, though RBI monetary policy volatility constrains open-ended scheme liquidity during redemption pressure.
- Hybrid Funds:Balanced exposure products blend equity and debt allocations with automatic rebalancing triggers.
- Liquid Funds:Ultra-short duration instruments targeting working capital deployment for corporates and temporary parking for retail investors.
Most installed capacity flows through Equity Funds. Expansion is steepest in Hybrid Funds as investors seek downside buffers without sacrificing growth participation.
Investor Type:
Volume concentration tilts toward retail participation, though margin profiles favor institutional and HNWI relationships with lower servicing costs per rupee invested.
- Retail Investors:Individual households accessing mutual funds through systematic investment plans and lump-sum deployments. Tier-two and tier-three cities in Uttar Pradesh and Bihar are expanding the addressable base beyond traditional metropolitan centers. Digital KYC infrastructure collapses onboarding friction for first-time equity participants.
- Institutional Investors:Pension funds, insurance companies, and provident funds deploying block capital with mandate-driven constraints. SEBI's risk-o-meter standardization enables product comparability for fiduciary committees.
- HNWI:High-net-worth individuals with personalized portfolio management requirements and alternative investment access.
- Corporates:Treasury departments managing surplus liquidity through liquid and ultra-short duration schemes.
Retail Investors command the largest flow volume. HNWI relationships are climbing the fastest as wealth concentration deepens in Mumbai, Delhi, and Bangalore.
Investment Strategy:
Active-to-passive migration is reshaping fee economics across strategy types, with index approaches gaining share from fundamental selection models.
- Growth Strategy:Capital appreciation-focused selection of earnings-expanding companies across consumption, technology, and financial services. Karnataka and Telangana technology corridors concentrate domestic demand for technology sector exposure. SEBI's sectoral concentration limits constrain single-industry fund sizing.
- Value Strategy:Discount-to-intrinsic-value investing targeting mispriced assets with recovery catalyst visibility. Cyclical industrial and public sector holdings dominate portfolio construction.
- Index Strategy:Passive replication of Nifty 50, Sensex, and sectoral indices with minimal tracking error tolerance.
- Sectoral Strategy:Concentrated exposure to banking, infrastructure, or technology themes with higher volatility profiles.
Growth Strategy retains the largest AUM base. Index Strategy is gaining share fastest as cost-conscious investors migrate from active management fees.
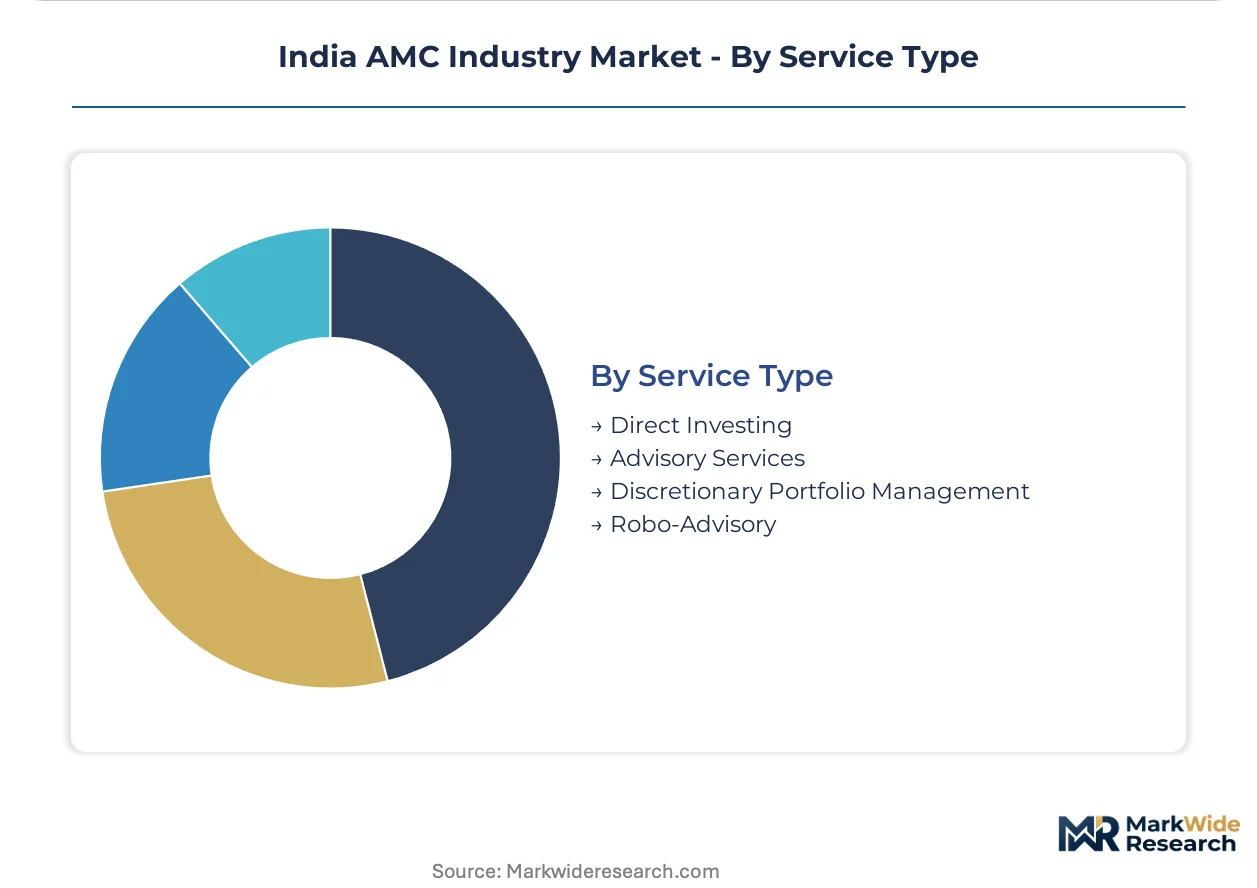
Service Type:
Distribution economics bifurcate between commission-bearing intermediary channels and zero-commission direct platforms with divergent customer acquisition costs.
- Direct Investing:Investor-initiated transactions bypassing distributor commissions through AMC websites and stock exchange platforms. Younger demographics in Gujarat and Tamil Nadu gravitate toward exchange-traded fund accumulation plans via discount brokerage infrastructure. Self-directed research capabilities reduce dependency on advisory intermediation.
- Advisory Services:Human-guided fund selection with suitability assessments against SEBI-mandated risk classifications. B-15 city distributor networks retain gatekeeper control despite direct-plan proliferation.
- Discretionary Portfolio Management:Mandated authority for professional managers to execute strategy shifts without per-transaction consent.
- Robo-Advisory:Algorithmic allocation engines automating risk profiling and fund mapping. This service type is expanding most quickly as mid-tier AMCs deploy AI-driven behavioral bias matching to reduce advisor training costs.
Advisory Services still channel the majority of retail flows. Robo-Advisory is scaling fastest among digitally native investor cohorts in Maharashtra and Karnataka.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai's financial district anchors India's asset management concentration, with the city housing the headquarters of five of the top ten AMCs by AUM. SEBI's regulatory headquarters in Mumbai reinforces this geographic clustering, while satellite operations in Delhi and Bangalore handle technology infrastructure and institutional sales.
Maharashtra
Mumbai and Pune drive the bulk of equity fund inflows, with urban investor density supporting sophisticated product penetration. SEBI's regional office enforces TER compliance and disclosure norms across western India operations. The Bandra-Kurla Complex hosts multiple AMC headquarters, where direct-plan digital onboarding infrastructure receives continuous investment.
Gujarat
Ahmedabad and Surat exhibit the highest per-capita SIP participation rates among major Indian states. RBI's monetary policy transmission affects debt fund liquidity management for treasury operations concentrated in Gandhinagar. The state's discount brokerage ecosystem accelerates ETF adoption among self-directed retail investors.
Karnataka
Bangalore's technology corridor generates demand for growth-oriented equity exposure and robo-advisory services. SEBI's regulatory sandbox permits fintech-enabled distribution trials with voice-based interfaces in this market. Whitefield and Electronic City host back-office operations for multiple AMCs serving southern India.
Tamil Nadu
Chennai's manufacturing base supports corporate treasury deployment into liquid and ultra-short duration schemes. The state's financial literacy programs align with SEBI's investor education mandates for tier-two city expansion. Coimbatore and Madurai emerging as SIP growth centers beyond traditional metropolitan anchors.
Delhi-NCR
The National Capital Region concentrates institutional investor relationships and pension fund distribution networks. PFRDA's NPS tiered contribution structure creates captive annuity-linked asset pools managed from Gurgaon operations. Noida houses technology development centers supporting algorithmic portfolio construction platforms.
India AMC Industry Market Competitive Landscape
Domestic banking-affiliated AMCs compete with independent asset managers and global joint ventures across distribution reach and product engineering dimensions. The market structure tilts toward consolidation around sponsor-backed entities with captive branch networks and proprietary digital infrastructure. Three strategic archetypes dominate: banking-subsidiary AMCs leveraging parent distribution, independent fund houses emphasizing direct-plan scale, and international joint ventures importing global product frameworks. Competitive intensity manifests through SIP acquisition wars in tier-two cities and fee compression battles in large-cap equity categories.
Among banking-subsidiary operators, SBI Mutual Fund and HDFC Mutual Fund exemplify the branch-network archetype, while ICICI Prudential Mutual Fund occupies a position blending hybrid product innovation with institutional distribution depth. These three entities anchor the competitive landscape through divergent strategic postures rather than convergent imitation.
| Leading Market Players |
|---|
| SBI Mutual Fund |
| ICICI Prudential Mutual Fund |
| HDFC Mutual Fund |
| Nippon India Mutual Fund |
| Kotak Mahindra Mutual Fund |
| Aditya Birla Sun Life Mutual Fund |
| UTI Mutual Fund |
| Axis Mutual Fund |
| DSP Mutual Fund |
| Others |
Pricing and Supply Chain Analysis
Quantitative talent concentration in Mumbai's financial district compresses algorithmic portfolio construction costs, widening spreads between premium active management fees and commoditized index-tracking tiers across Maharashtra and Gujarat markets.
Pricing Analysis
Input-cost pass-through from SEBI-mandated TER ceilings flows directly into distributor commission restructuring and technology infrastructure investments. Three-tier pricing structure across premium active equity, standard hybrid, and economy index tiers separates investors by advisory dependency and self-directed capability. Pricing pressure stems from direct-plan proliferation via discount brokerage platforms, particularly among digitally native demographics in Tamil Nadu and Karnataka. Retail SIP participants in tier-two cities exhibit highest price sensitivity, while institutional treasury relationships in Delhi-NCR demonstrate lowest elasticity due to mandate-driven deployment requirements.
Supply Chain Analysis
Domestic-content mandates under SEBI's BRSR disclosure framework reshape portfolio construction data sourcing toward verifiable Indian corporate sustainability metrics. Technology infrastructure draws from domestic cloud providers in Bangalore and Mumbai, research talent feeds from IIT Bombay and IIM Ahmedabad pipelines, and distribution networks rest on Aadhaar-linked KYC rails. Single-source vulnerability concentrates in legacy core banking platform dependencies at sponsor banks undergoing migration. Distribution runs through branch-network AMCs, direct-plan digital platforms, and B-15 city distributor intermediaries in parallel channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Maharashtra's regulatory enforcement density against Bihar's emerging SIP penetration creates a geographic-arbitrage window for cost-optimized product distribution and compliance-light market development.
For Market Incumbents: Deepen proprietary digital onboarding infrastructure to offset SEBI TER compression on large-cap equity margins. Expand algorithmic risk-profiling capabilities to reduce human advisor training costs. Consolidate branch-network advantage in tier-three Uttar Pradesh and Bihar before direct-plan platforms capture first-mover positioning. For New Entrants and Emerging Players: Launch via robo-advisory distribution to bypass B-15 city distributor gatekeeper control. Target Karnataka's technology corridor millennials with voice-based transaction interfaces under SEBI regulatory sandbox permissions. White-space concentration sits in passive ETF accumulation plans for self-directed investors in Gujarat's discount brokerage ecosystem. For Investors and Strategic Acquirers: Banking-subsidiary AMCs are the most active acquirer in this space, seeking technology capabilities and regional distribution fill-ins. Long-term viability hinges on direct-plan scale economics and algorithmic personalization infrastructure. Watch SEBI's evolving passive fund regulations as inflection signal for active-to-passive migration velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Robo-Advisory Platform Deployment | SEBI's regulatory sandbox enables voice-based transaction trials in Karnataka without full licensing requirements. |
| Direct-Plan Digital Infrastructure | Proprietary onboarding systems capture digitally native flows bypassing B-15 city distributor commissions. |
| Passive Fund Product Engineering | Index replication strategies exploit TER compression on active large-cap categories through scale economics. |
| NPS Distribution Integration | PFRDA's tiered contribution structure creates captive annuity-linked asset pools with recurring flow profiles. |
| ESG Data Infrastructure Investment | BRSR disclosure requirements enable sustainability-screened portfolio construction with verifiable corporate inputs. |
Research Methodology
Bottom-up SIP flow modeling reconciled against top-down AMC AUM tracking forms the analytical core of this study. Primary interviews with fund management executives, SEBI compliance officers, distributor network heads, and digital platform engineers combined with secondary validation from SEBI circular archives, RBI monetary policy statements, AMFI industry flow data, and sponsor bank annual disclosures. Triangulation across stakeholder perspectives and regulatory documentation anchors segment-level estimates.
Input-output matrices map investor-type demand elasticity against fund-type supply capacity across the projection horizon. Segmentation dimensions include fund architecture, investor category, investment strategy orientation, and service delivery mode. CAGRs derive from compounding observed flow momentum against regulatory-imposed fee compression trajectories. NPS contribution tier penetration and robo-advisory adoption curves feed industry-specific forecast sensitivity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under RBI liquidity tightening episodes or SEBI TER ceiling expansion. Projections reflect assumptions of continued SIP household financialization and stable regulatory enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Asset Management
US Pension Funds Market
Asset Management
Capital Expenditure Market
Asset Management
APAC Mutual Fund Market
Asset Management
Canada Pension Fund Market
Asset Management
Hardware Asset Management Market
Asset Management
Europe Asset Management Market
Asset Management
Mutual Fund Assets Market
Asset Management
China Mutual Funds Market
Asset Management
Global Asset Performance Management Market
Asset Management
Asset and Wealth Management Market
Asset Management
Global Infrastructure Asset Management Market
Asset Management
LAMEA Equity Management Software Market
Asset Management
Canada Asset Management Market
Asset Management
Global Remote Asset Management Market
Asset Management
Global Investment Management Software Market
Asset Management
India Mutual Fund Market