
 Assets Under Management Market | 2026-2036
Assets Under Management Market Size, Share, and Industry Trends Forecast 2026-2036
Assets Under Management Market Intelligence
Market Context with Strategic Players
Active fixed-income mandates is rebalancing portfolio economics as rising-rate environments pressure fee structures across traditional bond strategies. BlackRock leverages its scale in ETF infrastructure to capture flows from cost-sensitive institutional accounts. Vanguard anchors its competitive position through mutual ownership, passing operational savings directly to end investors. Goldman Sachs Asset Management differentiates via alternatives access, connecting pension clients with private credit and infrastructure sleeves.
Technical Definition and Structural Segments
Assets Under Management denotes the total market value of investment assets administered by financial institutions on behalf of clients, measured through daily net asset value calculations and reported in base-currency terms for regulatory filings. The primary commercial purpose centers on generating fee income through advisory, custody, and performance-based compensation structures tied to portfolio outcomes. Fixed Income commands the largest asset pool among asset class segments, though ETFs within fund structure categories are capturing the fastest flow velocity as taxable investors prioritize intraday liquidity and transparency. Retail Investors represent an expanding investor type segment, drawn by fractional-share platforms and direct-indexing capabilities that lower minimum thresholds.
Regulatory Frame and Forward-Looking Close
The SEC enforces liquidity risk management rules under the Investment Company Act of 1940, requiring open-end funds to classify holdings into buckets that constrain portfolio construction flexibility. The EU's MiFID II and SFDR frameworks impose cost-disclosure and sustainability-labelling obligations on managers distributing products across European jurisdictions, elevating compliance spend as a structural cost layer. Stakeholders must monitor how jurisdictional fragmentation in ESG taxonomy definitions reshapes cross-border product registration strategies and distribution economics.
Market Dynamics
Fee compression across passive mandates is forcing active managers to reconstruct value propositions around alternatives access and customized liability-driven solutions. This structural pressure is redistributing capital toward private markets and direct-indexing platforms that preserve margin while meeting institutional customization demands.
Growth Catalysts
- SEC Climate Disclosure Mandates:Portfolio construction requirements under the new rules are driving demand for carbon-accounting infrastructure and ESG-integrated strategies across US institutional mandates.
- Pension Fund Reallocation:Public and corporate pension systems are accelerating commitments to private credit, infrastructure, and real asset sleeves to match long-duration liabilities.
- Tokenization Infrastructure:Distributed ledger technology is enabling fractional ownership of illiquid alternatives, lowering minimum thresholds for retail and mass-affluent segments.
Market Restraints
- Fee Compression Mechanics:Passive fund expense ratios near zero basis points are compressing revenue per dollar managed across core equity and fixed-income strategies.
- Concentrated Custody Risk:Three global custodian banks dominate securities safekeeping, creating systemic vulnerability and limiting negotiating leverage for mid-size asset managers.
- MiFID II Cost Disclosure:European regulatory requirements for granular fee unbundling have elevated compliance infrastructure costs and reduced cross-border distribution economics.
Strategic Opportunities
- Direct Indexing Penetration:Tax-loss harvesting at the individual security level is capturing taxable wealth management flows previously directed to mutual funds and ETFs.
- India Mutual Fund Expansion:Systematic investment plans and digital distribution channels are accelerating retail participation in formal savings vehicles.
- EU SFDR Article 9 Products:Sustainability-labeled fund categories are attracting Article 173 institutional capital seeking regulatory-aligned impact exposure.
Industry Challenges
- Quantitative Analyst Scarcity:Alternative data integration and machine-learning model development require specialized talent pools that remain concentrated among technology firms and top-tier hedge funds.
- Legacy System Interoperability:Core banking platforms and portfolio accounting systems demand costly middleware development to support real-time data feeds and API-based client reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Assets Under Management Market |
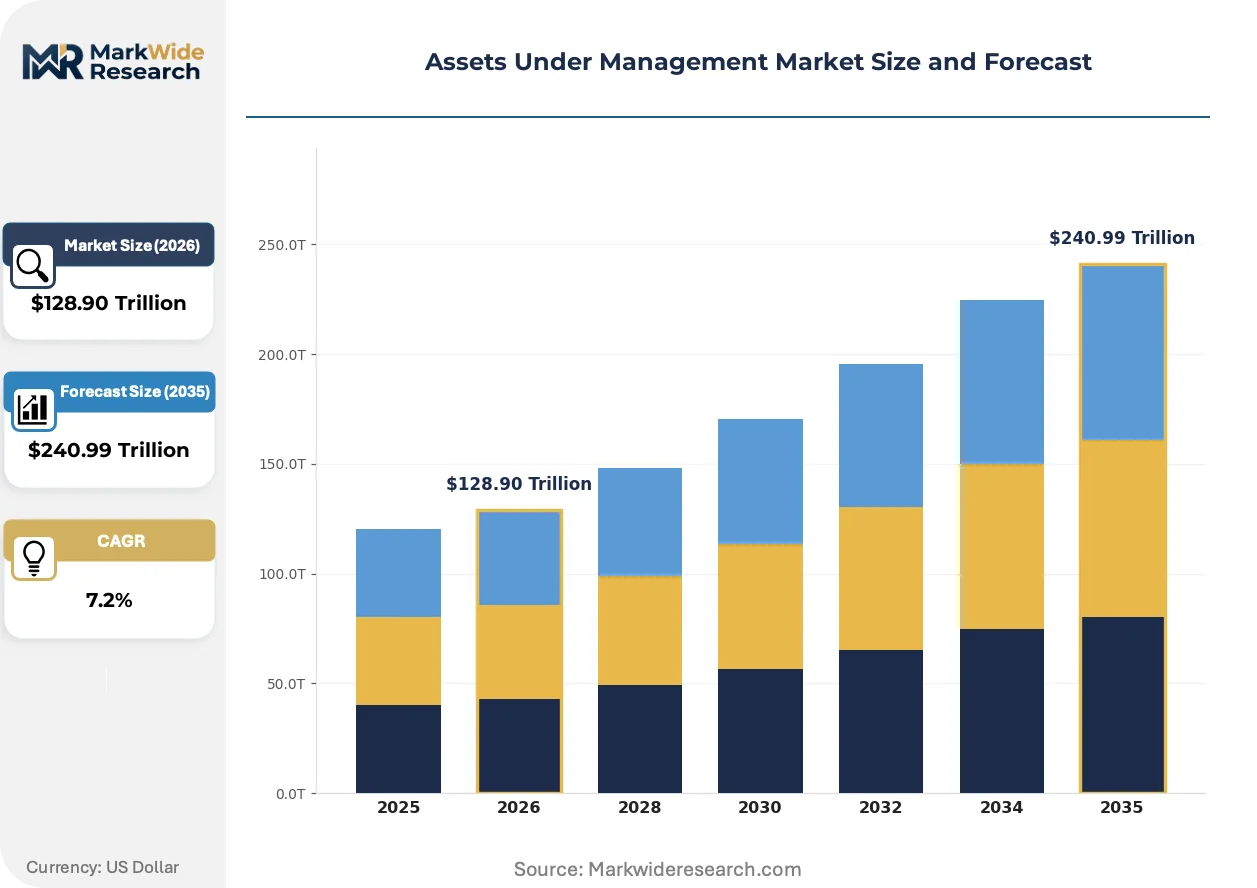
| Market Size in 2026 | $128.90 Trillion |
| Market Size in 2035 | $240.99 Trillion |
| CAGR (2026 – 2036) | 7.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Asset Class: Equities, Fixed Income, Real Estate, Commodities Investor Type: Institutional Investors, Retail Investors, Family Offices, Hedge Funds Fund Structure: Mutual Funds, ETFs, Private Equity, Venture Capital Management Style: Active Management, Passive Management, Quantitative Strategies, Tactical Asset Allocation |
| Companies Covered | State Street Global Advisors, Goldman Sachs Asset Management, BlackRock, Invesco, Capital Group, Vanguard, J.P. Morgan Asset Management, Blackstone, Fidelity Investments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Assets Under Management Market Strategic Shifts & Innovations
Digital infrastructure is dissolving traditional boundaries between asset classes, distribution channels, and client service models. This convergence is compressing product development cycles while elevating data architecture as a competitive differentiator.
Artificial intelligence-driven portfolio construction is unifying risk analytics across public and private holdings. Institutional allocators in North America and Europe are piloting generative models for scenario stress-testing and manager selection. This technology is compressing the traditional due diligence timeline from quarters to weeks while demanding new governance frameworks for model risk oversight.
The SEC's liquidity risk management amendments under the Investment Company Act of 1940 are reshaping open-end fund structure limitations. Managers must now classify holdings into four liquidity buckets, constraining portfolio construction flexibility for alternative strategies offered in daily-liquidity wrappers. US mutual funds with significant private exposure are responding through fund-of-funds structures and interval fund conversions that redefine investor access terms.
Wealth platforms are unbundling investment management from custody and reporting functions. Independent registered investment advisors are selecting best-in-class components across vendors rather than accepting bundled proprietary solutions. This behavior is most pronounced among US advisors with over $500 million in assets under advisement, where technology spending now rivals compensation as the largest operating expense category.
Assets Under Management Market Segmentation
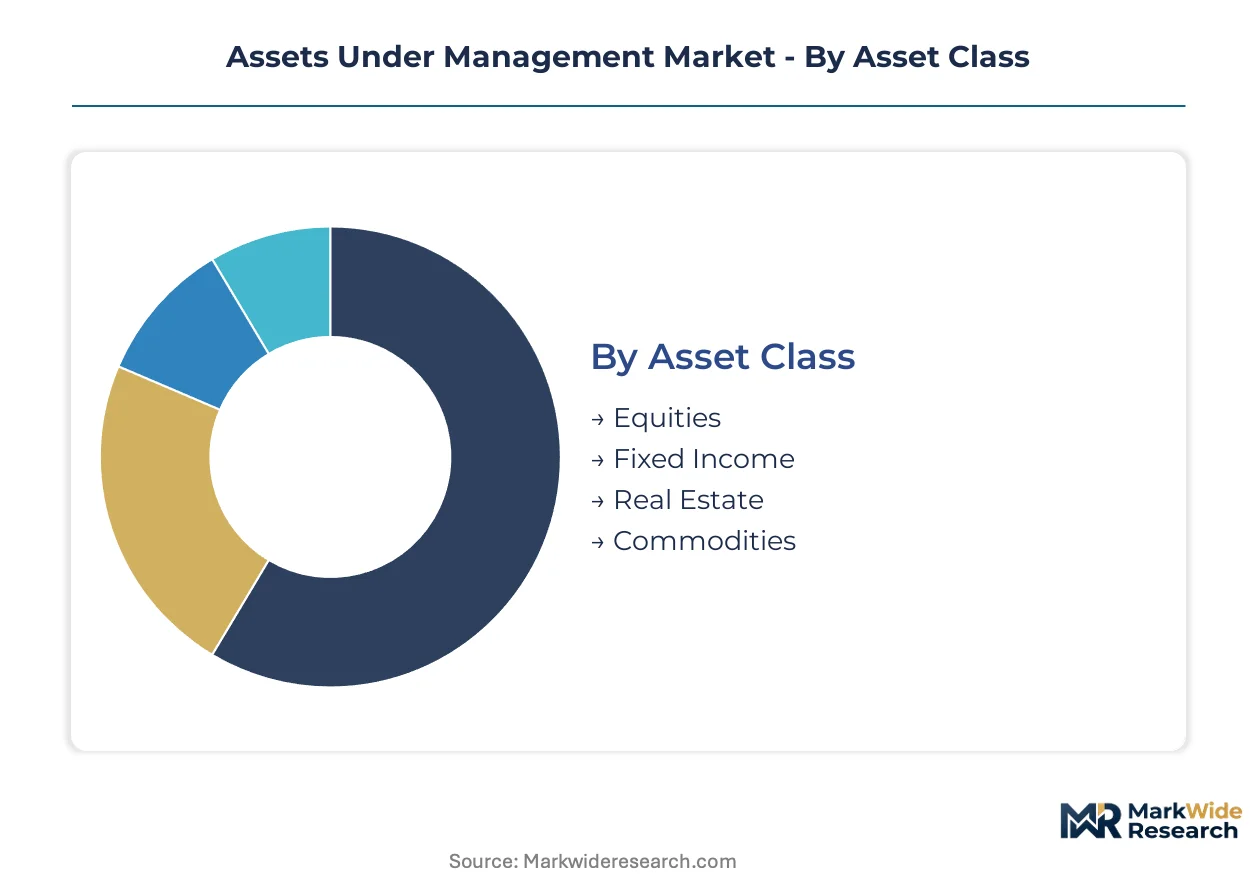
Segmentation in the Assets Under Management market reveals how capital intensity, regulatory treatment, and fee structures vary dramatically across product architectures. Understanding these divisions enables managers to allocate technology spend and distribution resources against margin profiles.
Asset Class:
Capital intensity peaks in Real Estate and infrastructure mandates, where due diligence, valuation, and asset management functions demand dedicated operational platforms.
- Equities:Public equity portfolios deploy algorithmic execution and low-latency data feeds to minimize tracking error. Demand concentrates in US large-cap sleeves as institutional accounts seek dollar-denominated core exposures amid geopolitical fragmentation.
- Fixed Income:Bond mandates require sophisticated duration management and credit research infrastructure. US pension funds and insurance carriers drive allocation flows as liability-driven investment frameworks expand.
- Real Estate:Direct property investments demand appraisal networks and property management capabilities that fixed-income shops cannot replicate.
- Commodities:Physical and futures-based strategies attract inflation-hedge demand from sovereign wealth vehicles.
Most installed capacity flows through Fixed Income. Expansion is steepest in Real Estate.
Investor Type:
Cost tier differentiation separates wholesale institutional relationships from retail distribution economics, with family offices occupying a hybrid service model.
- Institutional Investors:Pension funds, endowments, and sovereign wealth funds negotiate bespoke fee schedules and direct reporting lines. US public pension systems in California and New York deploy the largest alternative allocation programs.
- Retail Investors:Mass-market participants access products through 401(k) platforms and robo-advisors with compressed fee tolerance. Digital onboarding and fractional-share capabilities lower minimum thresholds.
- Family Offices:Ultra-high-net-worth entities demand consolidated reporting across illiquid and public holdings.
- Hedge Funds:Committed capital structures enable capacity-constrained strategies with performance-fee dominance.
Institutional Investors command the deepest relationship economics. Retail Investors are gaining share fastest through platform distribution.
Fund Structure:
Margin profiles diverge sharply between daily-liquidity wrappers and long-lockup vehicles, dictating technology and compliance spend allocation.
- Mutual Funds:Open-end structures under the Investment Company Act of 1940 require daily NAV calculation and liquidity bucketing. US-domiciled funds face SEC amendments constraining alternative asset inclusion.
- ETFs:Exchange-traded vehicles demand authorized participant networks and creation-redemption infrastructure. Taxable investors in the United States prioritize intraday transparency and tax efficiency.
- Private Equity:Closed-end partnerships deploy capital over multi-year horizons with J-curve return profiles.
- Venture Capital:Early-stage focused structures concentrate in technology clusters with concentrated manager track records.
Mutual Funds retain the largest asset base. ETFs are climbing the fastest on flow velocity.
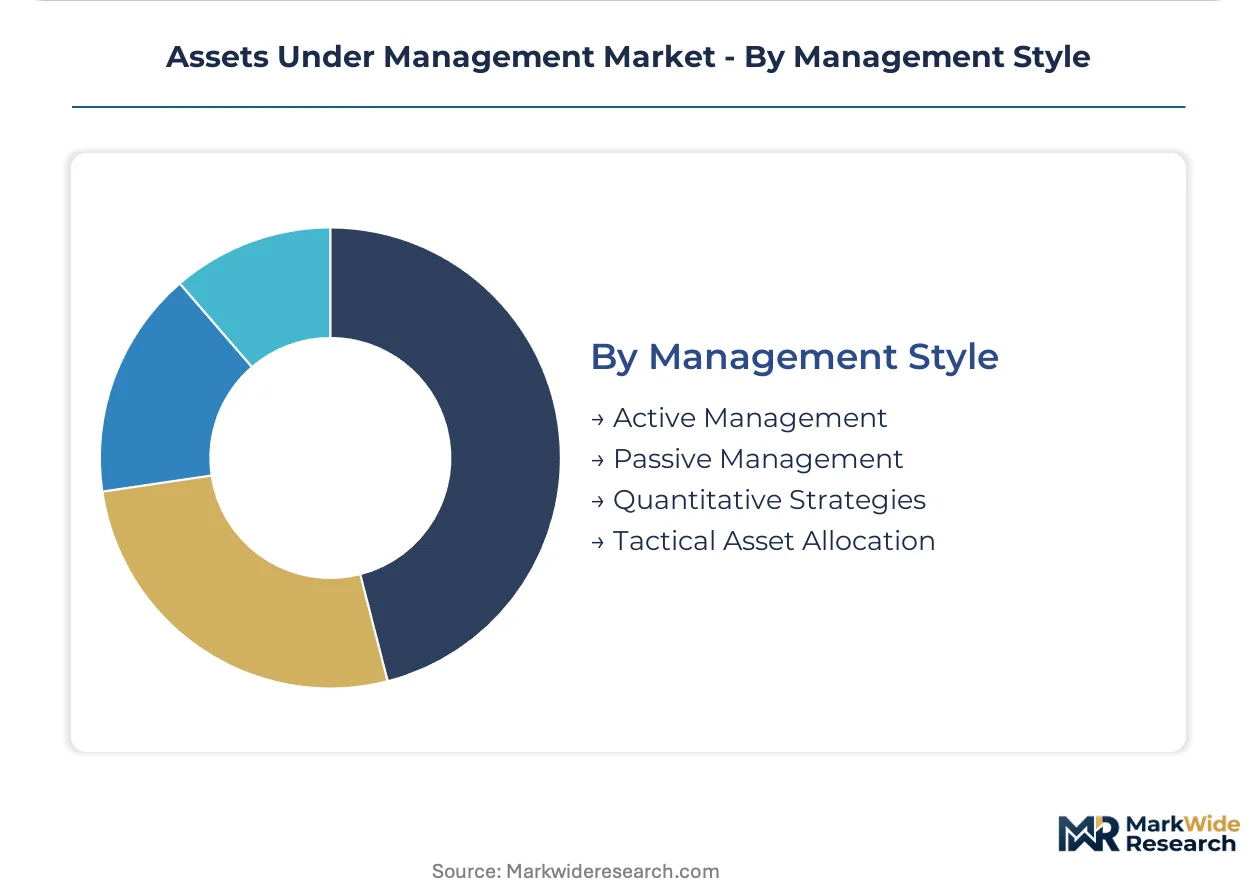
Management Style:
Maturity curves separate legacy active franchises from algorithmic platforms, with quantitative strategies demanding specialized talent and data infrastructure.
- Active Management:Discretionary stock and bond selection relies on fundamental research teams and issuer relationships. Fee compression in core equity and fixed-income strategies pressures revenue per dollar managed.
- Passive Management:Index replication minimizes research overhead through rules-based construction. Scale economies concentrate flows among three US-based providers with proprietary ETF ecosystems.
- Quantitative Strategies:Systematic factor and alternative data models require machine-learning infrastructure and specialized analyst pools concentrated in technology firms and top-tier hedge funds.
- Tactical Asset Allocation:Dynamic overlay strategies demand real-time risk analytics and derivatives execution capabilities.
Passive Management holds the largest asset volume. Quantitative Strategies show the steepest expansion trajectory on alternative data integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New York anchors institutional asset concentration with pension funds and endowments commanding over $4 trillion in delegated capital. Regulatory divergence across major financial centers is fragmenting product registration strategies and elevating compliance infrastructure as a competitive differentiator.
United States
Public pension systems in California and New York deploy the largest alternative allocation programs, driving demand for private credit and infrastructure sleeves. The SEC enforces liquidity risk management rules under the Investment Company Act of 1940, constraining portfolio construction flexibility for daily-liquidity wrappers. Boston's mutual fund cluster responds through interval fund conversions and fund-of-funds structures that redefine investor access terms.
United Kingdom
Defined-benefit pension schemes accelerate liability-driven investment frameworks, expanding demand for long-duration fixed-income and derivative overlays. The FCA implements MiFID II cost-disclosure obligations on managers distributing products across European jurisdictions, elevating compliance spend as a structural cost layer. London's asset management district concentrates ESG-integrated strategy development as institutional capital seeks regulatory-aligned impact exposure.
Germany
Insurance carriers and corporate pension funds drive allocation flows into credit research-intensive bond mandates. BaFin enforces granular fee unbundling requirements that have reduced cross-border distribution economics for US-domiciled products. Frankfurt's banking quarter hosts the largest concentration of liability-driven investment specialists serving continental European institutional accounts.
Japan
Government Pension Investment Fund rebalancing triggers sustained flows into domestic and international equity sleeves. METI guidelines on stewardship codes reshape engagement protocols for active managers overseeing corporate equity positions. Tokyo's financial district concentrates quantitative strategy development as systematic factor models gain institutional acceptance.
Switzerland
Wealth management platforms serving ultra-high-net-worth entities demand consolidated reporting across illiquid and public holdings. FINMA regulations on systemic risk impose liquidity coverage requirements on large asset managers operating cross-border fund structures. Zurich's private banking cluster pioneers direct-indexing capabilities with tax-loss harvesting at the individual security level.
Assets Under Management Market Key Industry Players
Scale-driven consolidation dominates the current landscape as fee compression forces reconstruction of value propositions around alternatives access and customized solutions. The market structure concentrates flows among three US-based providers with proprietary ETF ecosystems, while mid-tier active managers face margin pressure in core equity and fixed-income strategies. Two strategic archetypes define competitive positioning: scale-driven passive platforms capturing cost-sensitive institutional accounts, and alternatives specialists connecting pension clients with private credit and infrastructure sleeves. Dominant competitive moves include M&A activity targeting direct-indexing capabilities and strategic partnerships with tokenization infrastructure providers.
Within the scale-driven tier, BlackRock and Vanguard exemplify divergent ownership models—BlackRock leverages ETF infrastructure to capture flows from cost-sensitive institutional accounts, while Vanguard anchors its position through mutual ownership passing operational savings directly to end investors. Goldman Sachs Asset Management occupies a position connecting pension clients with alternatives access, representing the specialist archetype that differentiates through private market sleeves rather than scale economics.
| Leading Market Players |
|---|
| State Street Global Advisors |
| Goldman Sachs Asset Management |
| BlackRock |
| Invesco |
| Capital Group |
| Vanguard |
| J.P. Morgan Asset Management |
| Blackstone |
| Fidelity Investments |
| Others |
Cost & Logistics Intelligence
Mutual ownership structures at Vanguard and similar cooperatives compress fee pass-through to end investors, anchoring pricing discipline across the United States while forcing asset managers to absorb technology and compliance costs internally rather than distribute them through management fee layers.
Pricing Analysis
Input-cost pass-through in asset management flows through data infrastructure and regulatory compliance expenditures rather than physical raw materials. Basis-point fee compression across passive equity mandates intensifies as ETF expense ratios approach zero, squeezing revenue per dollar managed for mid-tier active managers. Price differentiation separates institutional bespoke mandates with customized reporting from retail robo-advisory tiers with standardized dashboards. Sovereign wealth funds and US public pension systems exhibit lowest price sensitivity due to liability-matching requirements, while mass-market 401(k) participants drive hardest fee negotiations through platform aggregation.
Supply Chain Analysis
Dual-sourcing requirements in custody and securities safekeeping mandate that large asset managers maintain relationships with multiple global custodian banks to mitigate systemic concentration risk. Supply concentrates in the United States, United Kingdom, and Switzerland for core custody infrastructure, while India and Ireland host expanding fund administration and transfer agency operations. Technology vendors providing portfolio accounting systems and risk analytics platforms feed from concentrated pools in Silicon Valley and London. Single-source vulnerability in authorized participant networks for ETF creation-redemption mechanics poses structural fragility. Distribution runs through institutional consultant intermediaries in the United States and open-architecture wealth platforms in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between the United States and European Union jurisdictions exploits divergent SEC and MiFID II compliance cost structures, with US-domiciled managers capturing margin advantage from lighter liquidity bucketing requirements absent granular European fee unbundling mandates.
For Market Incumbents: Deepen alternatives infrastructure capabilities to offset fee compression in core equity and fixed-income mandates. Acquire direct-indexing technology stacks to defend taxable wealth management relationships against robo-advisory entrants. Prioritize interval fund conversions and fund-of-funds structures that preserve private market access within SEC liquidity risk management constraints. For New Entrants and Emerging Players: Capture fractional ownership infrastructure for retail alternative asset exposure through tokenization platforms lowering minimum thresholds. Penetrate India's systematic investment plan market through digital distribution partnerships with local banks. Anchor go-to-market strategy around tax-loss harvesting capabilities at individual security level previously monopolized by incumbent direct-indexing specialists. For Investors and Strategic Acquirers: Private equity firms rolling up mid-size active managers are the most active acquirer in this space, targeting boutiques with specialized private credit or infrastructure track records. Long-term viability over a five-to-ten year window rests on technology infrastructure amortization across expanding asset bases. Watch for inflection in pension fund reallocation velocity toward real assets as signal of alternatives platform valuation expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-Indexing Capability Acquisition | Tax-loss harvesting technology captures taxable wealth flows from mutual fund migration. |
| Interval Fund Structure Conversion | SEC liquidity bucketing constraints drive migration from daily-liquidity mutual fund wrappers. |
| Tokenization Infrastructure Partnership | Distributed ledger fractionalization lowers alternative asset minimums for retail segments. |
| India Digital Distribution Alliance | Systematic investment plan penetration accelerates formal savings vehicle participation. |
| SFDR Article 9 Product Registration | Sustainability-labeled categories attract Article 173 institutional capital seeking regulatory alignment. |
Research Approach
Coverage spans the United States, United Kingdom, Germany, Japan, and Switzerland, with primary inputs from each jurisdiction combining interviews with pension fund chief investment officers, asset management distribution heads, regulatory compliance officers, and ETF authorized participant operations specialists. Secondary validation draws from SEC Investment Company Act filings, EU SFDR disclosure databases, BaFin regulatory circulars, METI stewardship code reports, and FINMA systemic risk assessments. Bottom-up asset flow analysis triangulates against top-down macroeconomic scenario modeling.
Rate-of-change decomposition separates volume expansion from fee compression effects across the projection horizon. Segmentation dimensions include asset class, investor type, fund structure, and management style, with regional regulatory cluster as an additional modeled variable. CAGRs derive from historical flow velocity analysis adjusted for structural break points in passive adoption and alternatives penetration. Forecast inputs incorporate pension fund liability duration extensions and machine-learning infrastructure deployment curves.
Regulatory amendment delays, pension fund reallocation velocity shifts, and tokenization platform adoption rates are the dominant revision risks to modeled outcomes. Deviation in SEC climate disclosure implementation timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Asset Management
Global Remote Asset Management Market
Asset Management
Global Investment Management Software Market
Asset Management
US Asset Management Market
Asset Management
US Healthcare Assets Management Market
Asset Management
Europe Asset Management Market
Asset Management
Capital Expenditure Market
Asset Management
India AMC Industry Market
Asset Management
UK Asset Management Market
Asset Management
LAMEA Equity Management Software Market
Asset Management
APAC Mutual Fund Market
Asset Management
Global Infrastructure Asset Management Market
Asset Management
Smart Asset Management Market
Asset Management
Fixed Income Asset Management Market
Asset Management
Asset Optimization Solutions Market
Asset Management
Healthcare Asset Management Market
Asset Management
China Mutual Funds Market