
 Smart Asset Management Market | 2026-2036
Smart Asset Management Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Asset Management Market Analytics
Buyer concentration among large institutional wealth platforms is pivoting toward diversified allocator bases as family offices and registered investment advisors expand their alternative asset exposure. BlackRock leverages its Aladdin technology infrastructure to anchor institutional market share. Vanguard competes through low-cost index-driven portfolio construction. iCapital specializes in democratizing access to private markets through streamlined digital onboarding.
Smart asset management encompasses the systematic deployment of software platforms, sensor networks, and data analytics to monitor, maintain, and optimize physical and financial asset performance across enterprise environments. Core functionality integrates real-time condition monitoring with predictive failure algorithms to minimize unplanned downtime and extend asset useful life. Cloud-based solutions lead deployment preferences due to elastic scalability and reduced capital expenditure requirements. AI analytics represents the fastest-expanding technology segment as machine learning models improve failure prediction accuracy. Mobile applications remain nascent but capture growing interest among field-service organizations requiring offline-capable inspection tools.
The Securities and Exchange Commission shapes fiduciary standards for digital advisory platforms, while the EU AI Act imposes risk-classification requirements on automated investment decision systems. ISO 55000 provides the asset management framework baseline adopted by multinational industrial operators. Stakeholders must monitor evolving algorithmic transparency mandates and determine compliance architecture investments before regulatory deadlines crystallize.
Market Dynamics
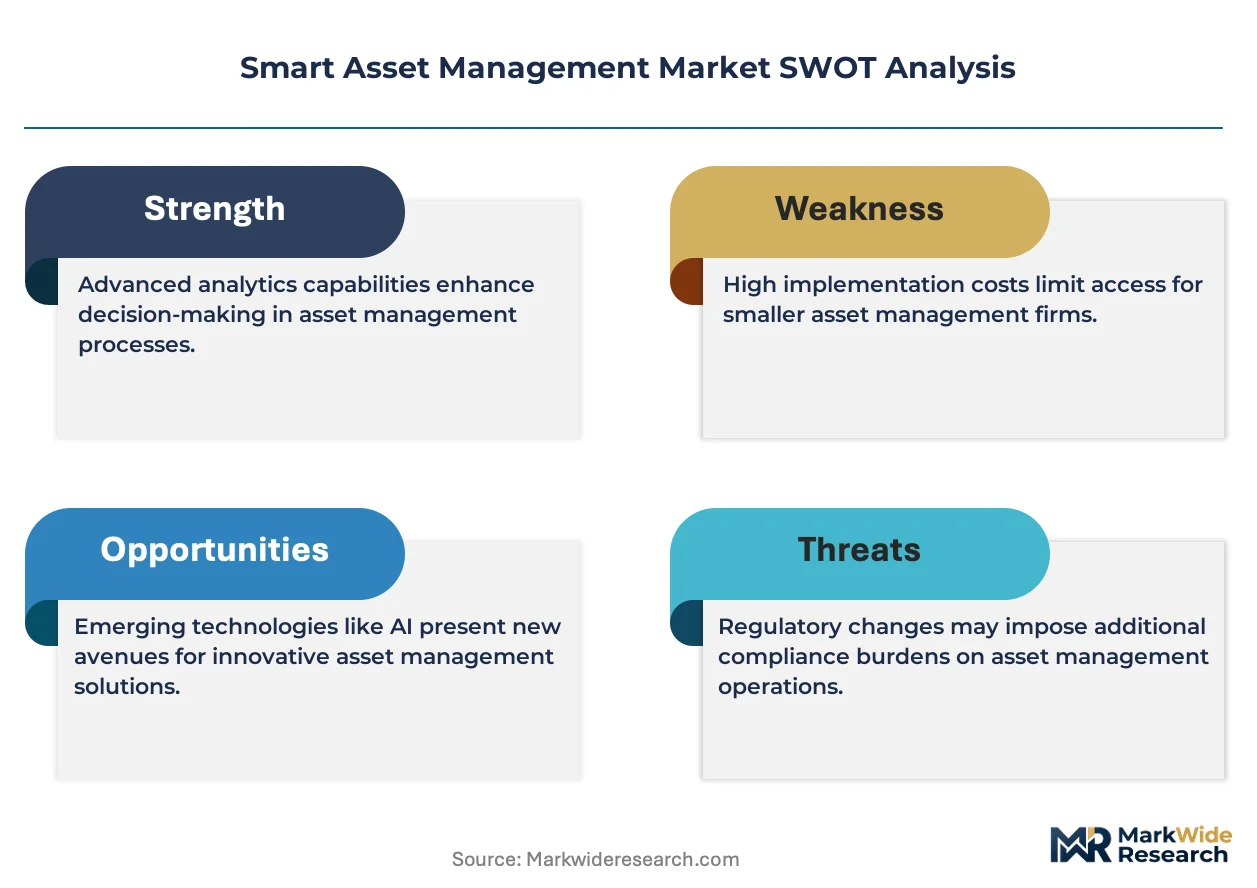
Manufacturing enterprises face mounting pressure from ISO 55000 compliance deadlines and EU AI Act risk-classification mandates, forcing simultaneous upgrades to predictive maintenance infrastructure and algorithmic governance frameworks.
Growth Catalysts
- EU AI Act risk-tier mandates:Automated investment decision systems require enhanced transparency protocols, accelerating enterprise procurement of auditable AI analytics platforms.
- Predictive maintenance penetration in automotive:German and Japanese automotive OEMs deploy sensor networks to compress unplanned downtime intervals and extend production line asset life.
- Cloud elasticity requirements:Mid-market industrial operators abandon on-premise deployments for SaaS-based condition monitoring to eliminate capital expenditure cycles.
Market Restraints
- Specialized sensor supply concentration:Vibration and thermal sensor fabrication concentrates among East Asian contract manufacturers, exposing procurement to geopolitical friction.
- Edge-to-cloud integration complexity:Legacy SCADA architectures resist seamless API connectivity with modern AI analytics layers, inflating deployment timelines.
- Data sovereignty fragmentation:Divergent national cloud localization laws across Germany, Japan, and the United States force redundant infrastructure investments.
Strategic Opportunities
- Field-service mobile enablement:Offline-capable inspection applications capture underserved technician workflows in asset-intensive utilities and oilfield services.
- Digital twin convergence with AI:Physics-based simulation layers merge with machine learning failure models to enable prescriptive rather than merely predictive maintenance.
- CSRD sustainability disclosure:EU corporate sustainability reporting mandates create demand for asset-level carbon accounting and circular economy tracking modules.
Industry Challenges
- Interoperability certification bottlenecks:Multi-vendor sensor ecosystems stall at protocol standardization gaps, delaying enterprise-wide deployment.
- Industrial data science talent scarcity:Competency gaps in failure-mode physics and machine learning engineering constrain platform customization velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Asset Management Market |
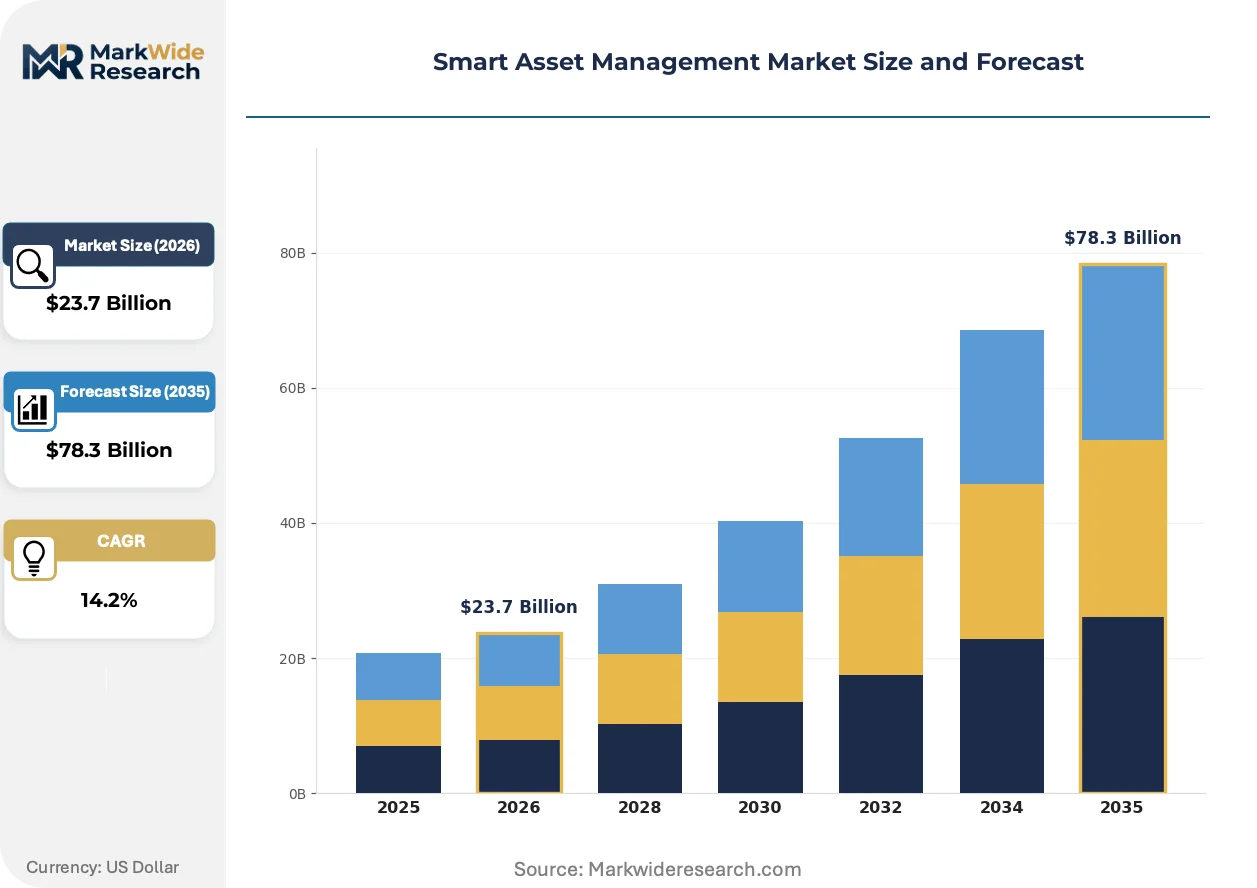
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $78.3 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Cloud-Based Solutions, On-Premise Solutions, Hybrid Solutions, Mobile Applications End User: Manufacturers, Government Agencies, Retail Enterprises, Service Providers Technology: IoT Integration, AI Analytics, Blockchain Technology, Mobile Connectivity Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises |
| Companies Covered | StepStone Private Wealth Solutions, Vanguard, iCapital, Charles Schwab, Fidelity, Canoe Intelligence, BlackRock, Asset Vantage, Ares Wealth Management Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Asset Management Market Evolving Landscape
AI-native predictive analytics are compressing maintenance decision cycles from monthly scheduling to real-time intervention triggers, while regulatory pressure on algorithmic transparency forces architectural redesigns across vendor roadmaps.
Edge-deployed machine learning inference is overtaking cloud-only processing for latency-critical failure detection. Automotive and semiconductor fabrication facilities adopt on-premise GPU clusters to process vibration signatures within 50-millisecond windows. This compression is overtaking traditional SCADA polling architectures and enabling sub-second equipment protection protocols previously unreachable via WAN-dependent analytics.
The EU AI Act's high-risk system classification is reshaping vendor liability frameworks for automated asset decisions. Industrial software providers must now maintain algorithmic audit trails and human-in-the-loop override capabilities. German chemical processing and Japanese precision manufacturing sectors are accelerating procurement of explainable AI modules to preempt regulatory enforcement actions.
Buyer procurement committees now mandate outcome-based performance guarantees rather than perpetual software licenses. Asset-intensive operators in US oil and gas and German utilities negotiate uptime-linked payment structures that transfer operational risk to platform vendors. This shift is most visible in North American midstream infrastructure, where reliability-as-a-service contracts displace traditional maintenance outsourcing arrangements.
Smart Asset Management Market Segmentation
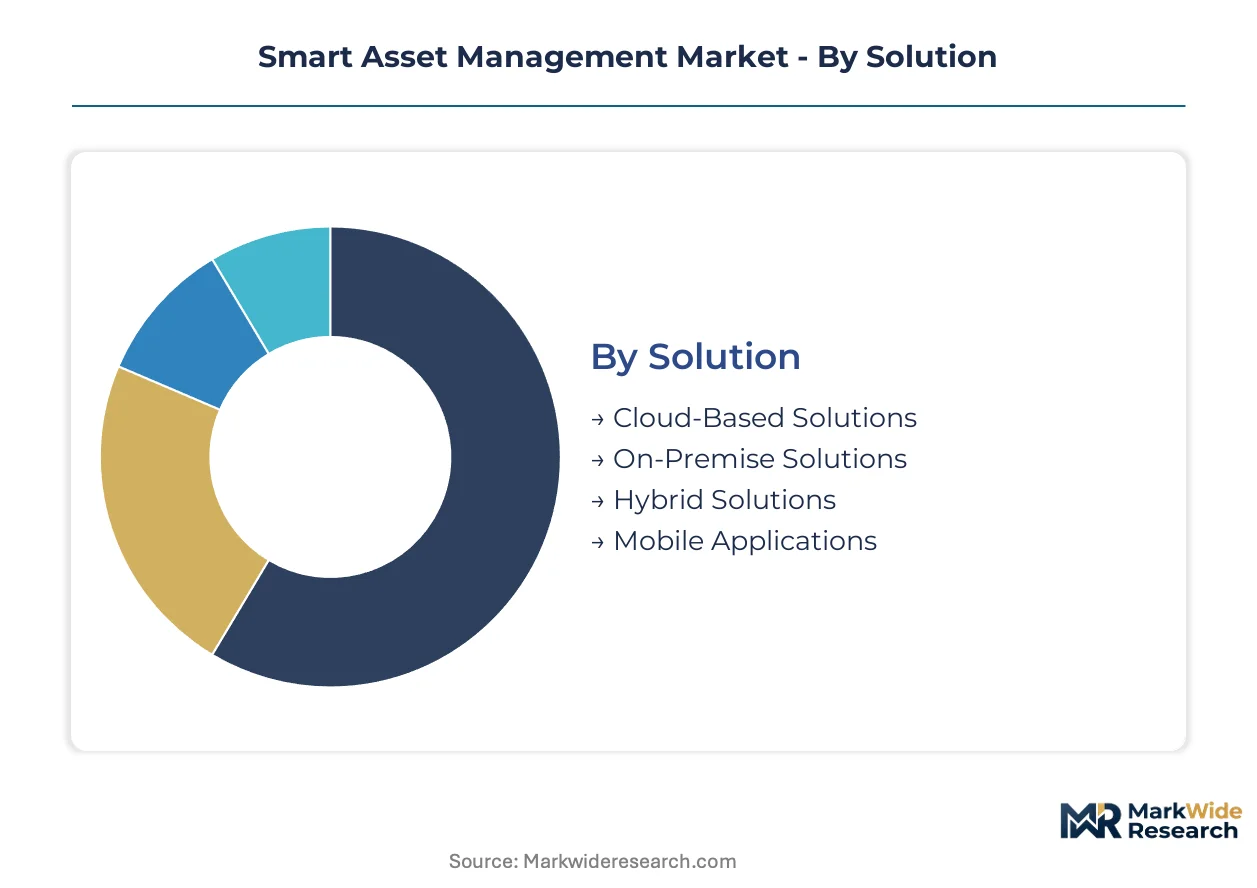
Smart asset management platforms serve heterogeneous operational environments where deployment constraints, data sovereignty requirements, and legacy system architectures dictate divergent solution architectures. Segmentation reveals how vendors calibrate functionality depth against integration friction across industrial, governmental, and commercial buyer profiles.
Solution:
Customization intensity spans from standardized multi-tenant SaaS to highly bespoke on-premise configurations requiring dedicated implementation teams.
- Cloud-Based Solutions:Multi-tenant architectures deliver elastic compute for predictive analytics without capital expenditure cycles. German automotive OEMs and Japanese precision manufacturers prioritize these platforms to compress deployment timelines and satisfy ISO 55000 audit requirements.
- On-Premise Solutions:Air-gapped deployments run within facility-controlled data centers for classified or critical infrastructure assets. US oil and gas midstream operators and German chemical processors mandate these configurations to satisfy data sovereignty and cybersecurity frameworks.
- Hybrid Solutions:Edge inference combined with cloud aggregation balances latency sensitivity against centralized model training.
- Mobile Applications:Offline-capable inspection tools address field-service technician workflows in asset-intensive utilities.
Leading the category by volume: Cloud-Based Solutions. Expanding most quickly: Hybrid Solutions.
End User:
Procurement authority concentrates differently across sectors—capital-intensive manufacturers drive platform R&D roadmaps while government buyers shape compliance certification requirements.
- Manufacturers:Automotive, semiconductor, and chemical producers deploy sensor networks across production lines to minimize unplanned downtime. German and Japanese industrial conglomerates represent the deepest technology adoption with integrated digital twin architectures.
- Government Agencies:Defense, transportation, and municipal infrastructure operators mandate FedRAMP or equivalent security certifications. Procurement cycles extend 18-24 months but anchor long-term maintenance revenue streams.
- Retail Enterprises:Distributed facility footprints across cold chain, HVAC, and energy management drive standardized IoT platform adoption.
- Service Providers:Third-party maintenance contractors purchase white-label platform access to deliver reliability-as-a-service contracts.
Dominant buyer by deployment scale: Manufacturers. Fastest procurement cycle acceleration: Service Providers.
Technology:
Technology layering determines failure prediction accuracy, data integrity guarantees, and field connectivity resilience across operational technology stacks.
- IoT Integration:Vibration, thermal, and acoustic sensor networks stream operational data into analytics platforms. Automotive OEMs in Germany and semiconductor fabricators in Japan drive sensor density requirements for sub-second anomaly detection.
- AI Analytics:Machine learning models trained on historical failure modes enable predictive rather than reactive maintenance scheduling. EU AI Act risk-classification mandates are accelerating explainable AI module procurement.
- Blockchain Technology:Immutable audit trails for maintenance records and spare parts provenance address compliance and counterfeit detection.
- Mobile Connectivity:5G and private LTE networks enable real-time technician dispatch and remote expert assistance.
Widest installed base: IoT Integration. Steepest expansion trajectory: AI Analytics.
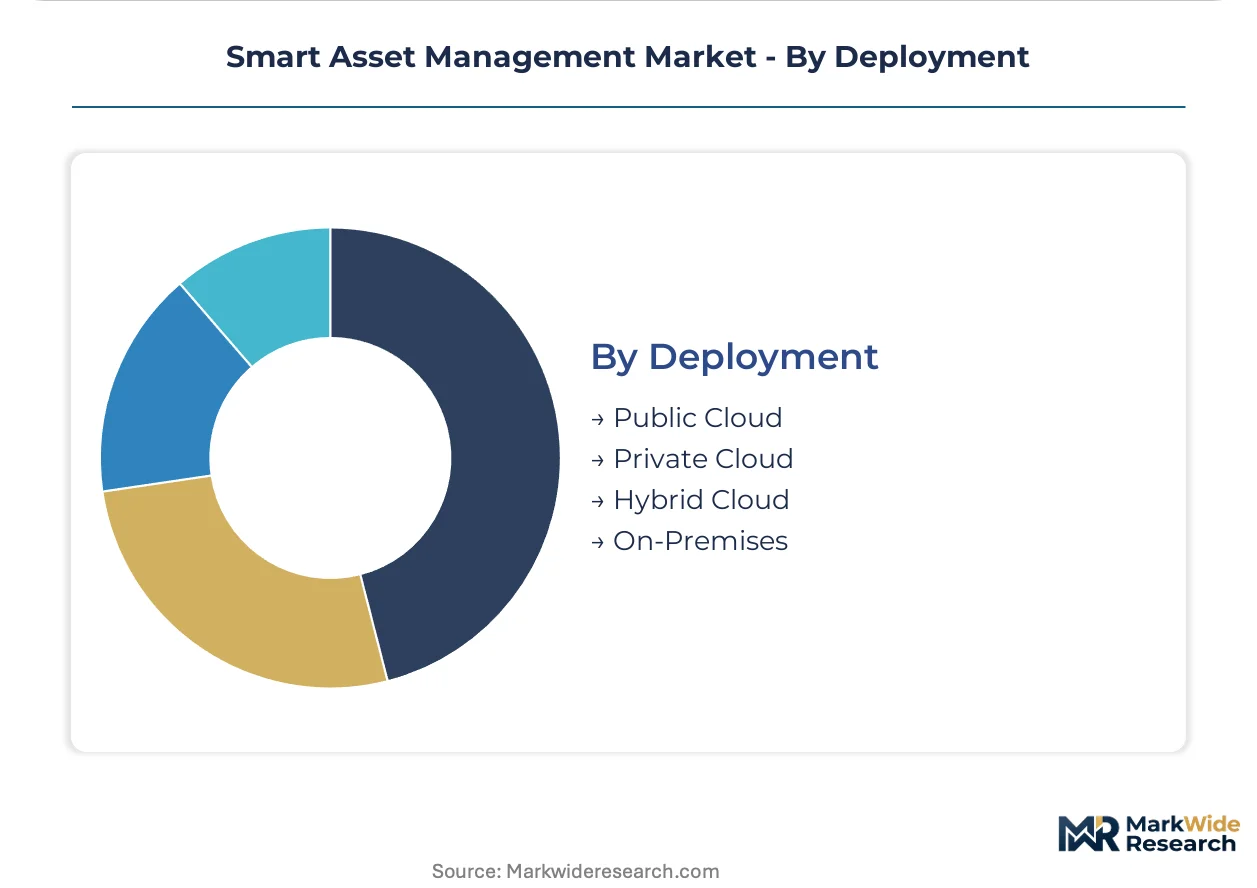
Deployment:
Infrastructure location decisions trade latency performance, regulatory jurisdiction, and operational control against total cost of ownership.
- Public Cloud:Shared infrastructure delivers lowest unit economics for non-critical asset monitoring. Mid-market industrial operators in the United States favor this model to eliminate data center capital commitments.
- Private Cloud:Single-tenant dedicated environments satisfy data residency mandates without full on-premise hardware ownership. German utilities and Japanese manufacturers deploy these to reconcile cloud agility with national localization laws.
- Hybrid Cloud:Sensitive data remains on-premise while anonymized analytics train centralized machine learning models.
- On-Premises:Complete operational autonomy for nuclear, defense, and critical national infrastructure assets.
Highest volume deployment: Public Cloud. Gaining share fastest: Hybrid Cloud.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany, Japan, and the United States as industrial digitization accelerates and regulatory deadlines for asset data governance approach. Manufacturing enterprises in these markets face simultaneous pressure from ISO 55000 compliance mandates and EU AI Act risk-classification requirements. Each geography presents distinct procurement patterns shaped by local regulatory frameworks and industrial cluster specializations.
United States
Oil and gas midstream operators and defense contractors drive procurement of air-gapped, on-premise deployments for critical infrastructure protection. SEC fiduciary standards shape digital advisory platform governance requirements for financial asset components. Houston anchors energy-sector adoption where reliability-as-a-service contracts displace traditional maintenance outsourcing arrangements.
Germany
Automotive OEMs and chemical processors deploy sensor-dense predictive maintenance networks across production lines to compress unplanned downtime. EU AI Act high-risk system classifications accelerate explainable AI module procurement for automated asset decisions. Bavarian industrial conglomerates lead integrated digital twin architecture adoption with combined physics-based simulation and machine learning failure models.
Japan
Precision manufacturers and semiconductor fabricators prioritize sub-second anomaly detection through edge-deployed GPU clusters processing vibration signatures. METI industrial digitization programs provide co-funding for SME predictive maintenance infrastructure upgrades. The Nagoya-Chubu manufacturing corridor exhibits the deepest technology adoption with hybrid cloud deployments balancing latency sensitivity against centralized model training.
United Kingdom
Financial services institutions and utilities procurement committees mandate outcome-based performance guarantees with uptime-linked payment structures. FCA operational resilience requirements intersect with EU AI Act transparency mandates for cross-border asset operators. London-based asset managers drive demand for blockchain-enabled audit trails in alternative investment infrastructure.
India
Mid-market industrial operators abandon on-premise deployments for SaaS-based condition monitoring to eliminate capital expenditure cycles. PLI scheme incentives accelerate domestic sensor network fabrication capacity expansion. Gujarat and Maharashtra manufacturing clusters exhibit fastest procurement cycle acceleration as family offices and industrial conglomerates expand alternative asset exposure through digital platforms.
Smart Asset Management Market Competitive Landscape
United States technology providers anchor the cloud-native and AI analytics tier; German and Japanese industrial software specialists hold positions in edge-deployed, latency-critical segments. The vendor structure fragments across three distinct tiers: diversified financial services conglomerates with captive technology infrastructure, pure-play predictive maintenance software vendors, and vertical-specialist sensor-software integrated providers. Dominant competitive moves include outcome-based pricing restructuring that transfers operational risk to platform vendors, and strategic partnerships between industrial operators and AI analytics firms to preempt regulatory enforcement deadlines.
Within the diversified financial services tier, BlackRock and Vanguard occupy positions reflecting divergent strategic archetypes—technology infrastructure leverage versus low-cost index-driven portfolio construction. iCapital represents the democratization-focused segment streamlining digital onboarding for private market access. Charles Schwab and Fidelity exemplify retail brokerage platforms extending into alternative asset infrastructure. Specialists in data aggregation and intelligence include Canoe Intelligence and Asset Vantage, while Ares Wealth Management Solutions anchors the alternative asset manager technology vertical.
| Leading Market Players |
|---|
| StepStone Private Wealth Solutions |
| Vanguard |
| iCapital |
| Charles Schwab |
| Fidelity |
| Canoe Intelligence |
| BlackRock |
| Asset Vantage |
| Ares Wealth Management Solutions |
| Others |
Value Network & Pricing Analysis
Edge-deployed GPU inference clusters are compressing latency thresholds below 50 milliseconds while simultaneously concentrating procurement leverage among Taiwanese semiconductor foundries and Japanese precision component suppliers. This dual compression redraws cost economics for predictive maintenance platforms and amplifies pricing power asymmetries between sensor-integrated vendors and pure-play software providers.
Pricing Analysis
Volume concentrates in multi-tenant SaaS subscriptions while margins accrue to outcome-based reliability contracts. Three-tier pricing structure across premium, standard, and economy levels stratifies by AI explainability certification tier and sensor integration depth. Pricing pressure stems from mid-market buyers demanding uptime-linked payment structures that transfer operational risk to vendors. Family offices and registered investment advisors exhibit highest price sensitivity; defense contractors and German chemical processors demonstrate lowest.
Supply Chain Analysis
Reverse-logistics flows for refurbished vibration sensors and remanufactured thermal imaging modules are creating secondary supply channels that undercut OEM pricing in aftermarket services. Component fabrication concentrates in Taiwan, South Korea, and Japan. Raw material dependencies span gallium nitride substrates, precision MEMS wafers, and rare-earth magnetic elements. Single-source vulnerability runs through East Asian contract manufacturers for specialized industrial sensors. Distribution runs through direct enterprise sales teams anchored by systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's high-risk system classification functions as a cost-of-compliance barrier that entrenches incumbent vendors with pre-built algorithmic audit trails while excluding undercapitalized entrants. ISO 55000 certification requirements compound this moat for asset-intensive industrial operators.
For Market Incumbents: Anticipate regulatory enforcement deadlines by accelerating explainable AI module deployment ahead of competitor roadmaps. Fortify positions through backward integration into sensor fabrication capacity in Taiwan or Japan to secure supply continuity against geopolitical friction. Prioritize FedRAMP and EU cybersecurity framework certifications to anchor government procurement cycles.
For New Entrants and Emerging Players: Third-party maintenance contractors represent the most penetrable channel partner type for white-label platform access. Target field-service mobile applications in US oilfield services and German utilities where offline-capable inspection tools remain underserved. Pursue reliability-as-a-service contract structures that transfer operational risk and differentiate from perpetual license incumbents.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified industrial software conglomerates seeking AI analytics capabilities. Long-term viability favors vendors with hybrid cloud architectures and proven EU AI Act compliance infrastructure. Monitor procurement committee mandates for outcome-based performance guarantees as the inflection signal for pricing model transformation.
| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Audit Trail Development | EU AI Act compliance creates procurement preference for explainable AI modules in German automotive and chemical sectors. |
| Edge Inference Hardware Partnership | GPU cluster deployments with Japanese semiconductor fabricators enable sub-second anomaly detection for precision manufacturing. |
| Outcome-Based Contract Restructuring | Uptime-linked payment structures transfer operational risk and anchor long-term revenue streams with US midstream operators. |
| Sensor Fabrication Backward Integration | Captive supply of vibration and thermal sensors mitigates East Asian procurement concentration risk. |
| FedRAMP Certification Pathway | US government agency procurement mandates 18-24 month sales cycles but secures decade-long maintenance contracts. |
Research Methodology
Document review covered SEC filings, EU regulatory submissions, ISO 55000 implementation case studies, and hyperscaler capex disclosures, complemented by interviews with predictive maintenance platform executives, industrial plant engineers, asset management procurement leads, and channel integration specialists. Bottom-up modeling triangulated sensor deployment densities and SaaS subscription volumes against top-down industry spend estimates derived from manufacturing digitization budget surveys.
Historical growth trajectories were cross-referenced against expert panel inputs across deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern dimensions. CAGRs were derived through regression analysis of technology penetration curves and regulatory deadline acceleration effects. Forecast inputs incorporated EU AI Act implementation timelines and METI industrial digitization co-funding disbursement patterns.
Caveats apply where geopolitical friction in East Asian semiconductor supply chains or accelerated EU AI Act enforcement could materially shift the outlook. Practitioners should monitor procurement committee mandate shifts toward outcome-based performance guarantees and explainable AI certification requirements for early signals of vendor consolidation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Asset Management
Asset Management System Market
Asset Management
Asset and Wealth Management Market
Asset Management
APAC Mutual Fund Market
Asset Management
Assets Under Management Market
Asset Management
Capital Expenditure Market
Asset Management
Fixed Income Asset Management Market
Asset Management
India Asset Management Market
Asset Management
Asia-Pacific Utilities Asset Management Market
Asset Management
Hardware Asset Management Market
Asset Management
US Healthcare Assets Management Market
Asset Management
US Asset Management Market
Asset Management
India AMC Industry Market
Asset Management
Equity Management Tool Market
Asset Management
Japan Asset Management Market
Asset Management
Global Remote Asset Management Market
Asset Management
Fund Management Fee Market