
 Global AI in Asset Management Market | 2026-2036
Global AI in Asset Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global AI in Asset Management Market Foresight
ISO 42001 certification for artificial intelligence management systems is bifurcating vendor eligibility across institutional procurement channels. BlackRock, Inc. leverages its Aladdin platform to sustain deep integration between risk analytics and portfolio construction workflows. Microsoft anchors enterprise-grade cloud infrastructure for model training and inference at scale across asset managers.
AI in asset management encompasses machine learning algorithms, natural language processing engines, and predictive analytics frameworks deployed to optimize investment decision-making, automate risk quantification, and enhance regulatory reporting accuracy. Cloud-based deployment leads solution delivery by enabling elastic compute for backtesting and real-time signal generation, while portfolio optimization and algorithmic trading concentrate R&D investment among quantitative strategies. Hedge funds and wealth managers represent the most active end-user segments, with family offices accelerating adoption of fraud detection and customer insights tools.
The U.S. SEC enforces AI disclosure rules under investment adviser regulations, while the EU AI Act imposes conformity requirements on high-risk algorithmic systems deployed by European fund managers. The U.K. Financial Conduct Authority scrutinizes model governance and explainability standards for retail-facing robo-advisory platforms. Stakeholders must calibrate compliance investments against the pace of regulatory divergence across jurisdictions.
Market Dynamics
ISO 42001 certification requirements are bifurcating vendor eligibility across institutional procurement channels, forcing asset managers to rebuild compliance infrastructure before contract renewal cycles.
Growth Catalysts
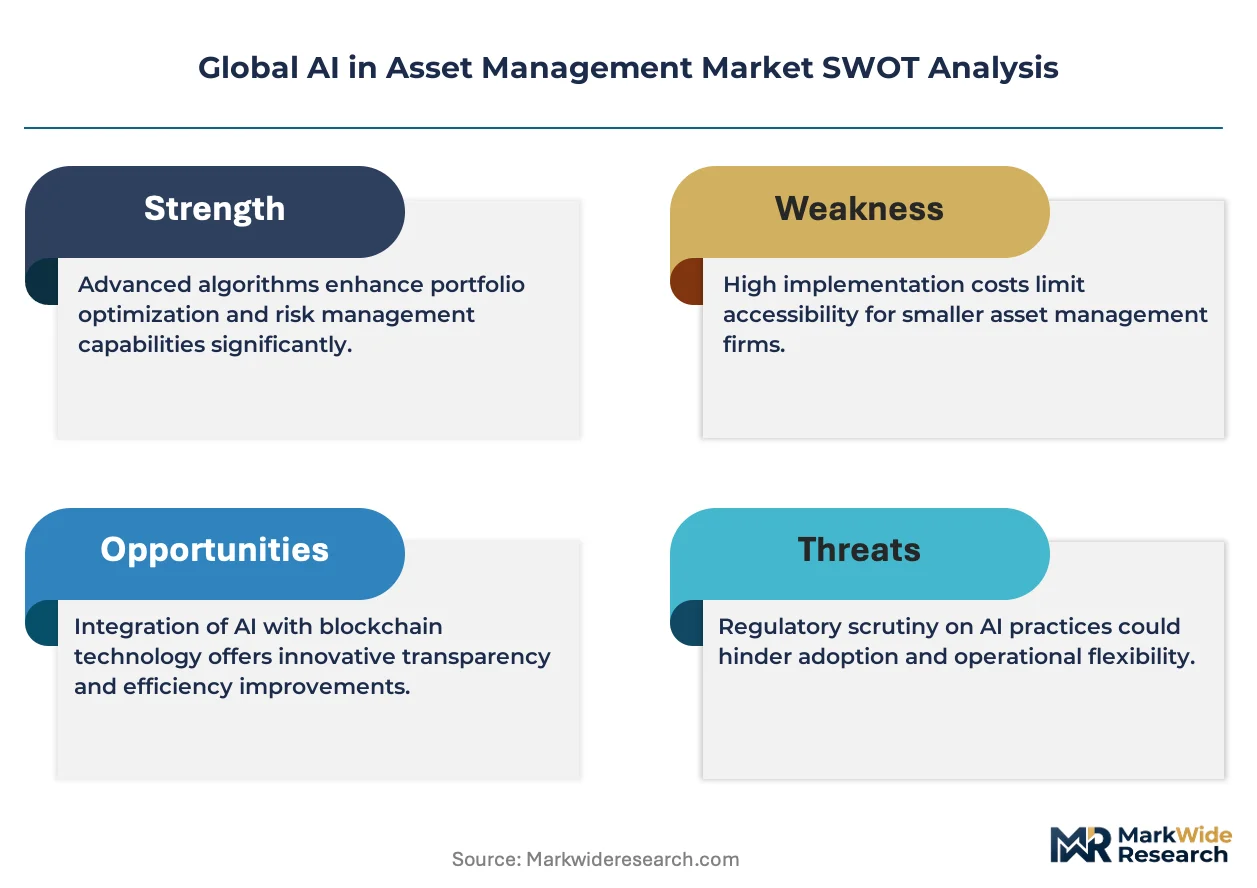
- EU AI Act Conformity Mandates:European fund managers must deploy explainable algorithmic systems by 2025, creating immediate procurement windows for compliant platform vendors.
- Hedge Fund Quantitative Strategies:Systematic funds in the United States are expanding machine learning research budgets to capture alternative data alpha in volatile rate environments.
- Cloud Elastic Compute:Elastic infrastructure for backtesting and real-time signal generation is decomposing capital barriers that previously favored only the largest quantitative shops.
Market Restraints
- GPU Supply Concentration:Model training infrastructure depends on Taiwan Semiconductor Manufacturing capacity, exposing inference pipelines to geopolitical disruption risk.
- Data Licensing Friction:Proprietary alternative datasets command escalating fees that compress strategy margins for mid-sized quantitative funds.
- Model Explainability Standards:The U.K. Financial Conduct Authority's scrutiny of black-box algorithms forces costly architecture redesigns for retail-facing platforms.
Strategic Opportunities
- Family Office Automation:Single-family offices in Singapore and Switzerland remain underpenetrated for fraud detection and customer insights tooling.
- Natural Language Processing Convergence:Large language models integrated with traditional quantitative signals are opening new strategy categories in earnings call analysis.
- U.S. SEC Disclosure Rules:Investment adviser AI transparency requirements are accelerating compliance software procurement cycles among registered investment advisers.
Industry Challenges
- Quantitative Researcher Scarcity:PhD-level talent in machine learning and financial econometrics commands compensation premiums that strain mid-tier fund economics.
- Legacy System Integration:Established asset managers face multi-year timelines to embed AI workflows into core portfolio management systems without operational disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global AI in Asset Management Market |
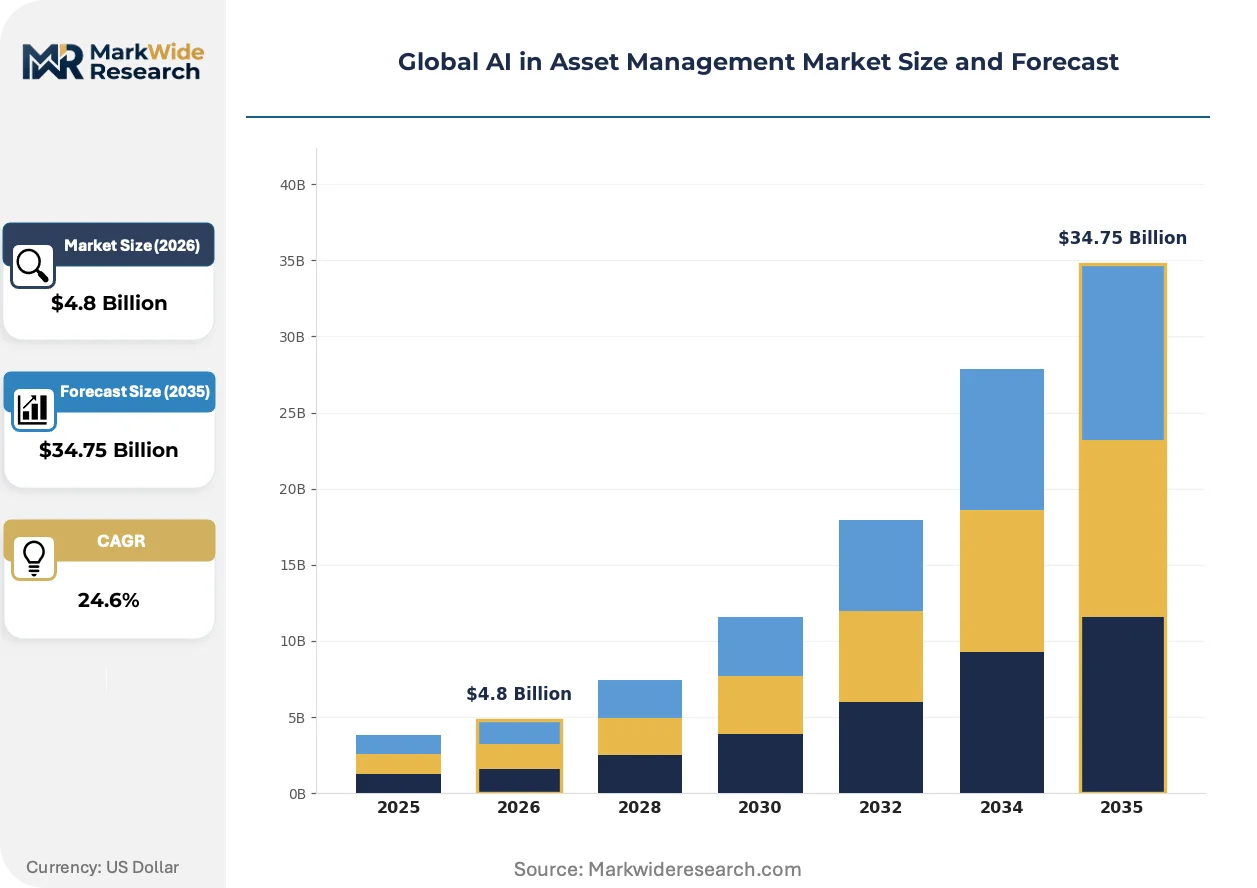
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $34.75 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Portfolio Optimization, Risk Management, Algorithmic Trading, Fraud Detection, Regulatory Compliance, Customer Insights Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing End User: Hedge Funds, Wealth Managers, Pension Funds, Mutual Funds, Family Offices Investment Strategy: Quantitative, Fundamental, Technical, Event-Driven, Income, Growth |
| Companies Covered | BlackRock, Inc., Amazon Web Services, Inc., International Business Machines Corporation, Microsoft, Charles Schwab & Co., Inc., Infosys Limited, Genpact, Salesforce, Inc., IPsoft Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global AI in Asset Management Market Shifts & Advancements
Generative architectures are migrating from experimental pilots to production-grade infrastructure, while regulatory divergence across jurisdictions forces parallel compliance investments.
Transformer-based natural language processing is decomposing the traditional sell-side research value chain. Quantitative funds now deploy proprietary large language models to parse unstructured earnings transcripts and regulatory filings at scale. This capability is compressing information asymmetry windows that previously sustained fundamental equity analyst franchises.
The EU AI Act's high-risk system classification is forcing European fund managers to maintain algorithmic audit trails and human oversight protocols. Compliance departments must document model governance frameworks before deployment. Asset managers in Germany and France are responding by embedding explainability modules directly into portfolio construction workflows.
Institutional procurement of AI tooling is fragmenting across specialized vendors rather than consolidating with legacy platform providers. Pension systems and sovereign wealth funds are building internal data science capabilities while licensing point solutions for specific functions. This pattern is most visible in the United States, where CalPERS and similar large allocators have established dedicated quantitative research divisions with direct vendor relationships.
Global AI in Asset Management Market Segmentation
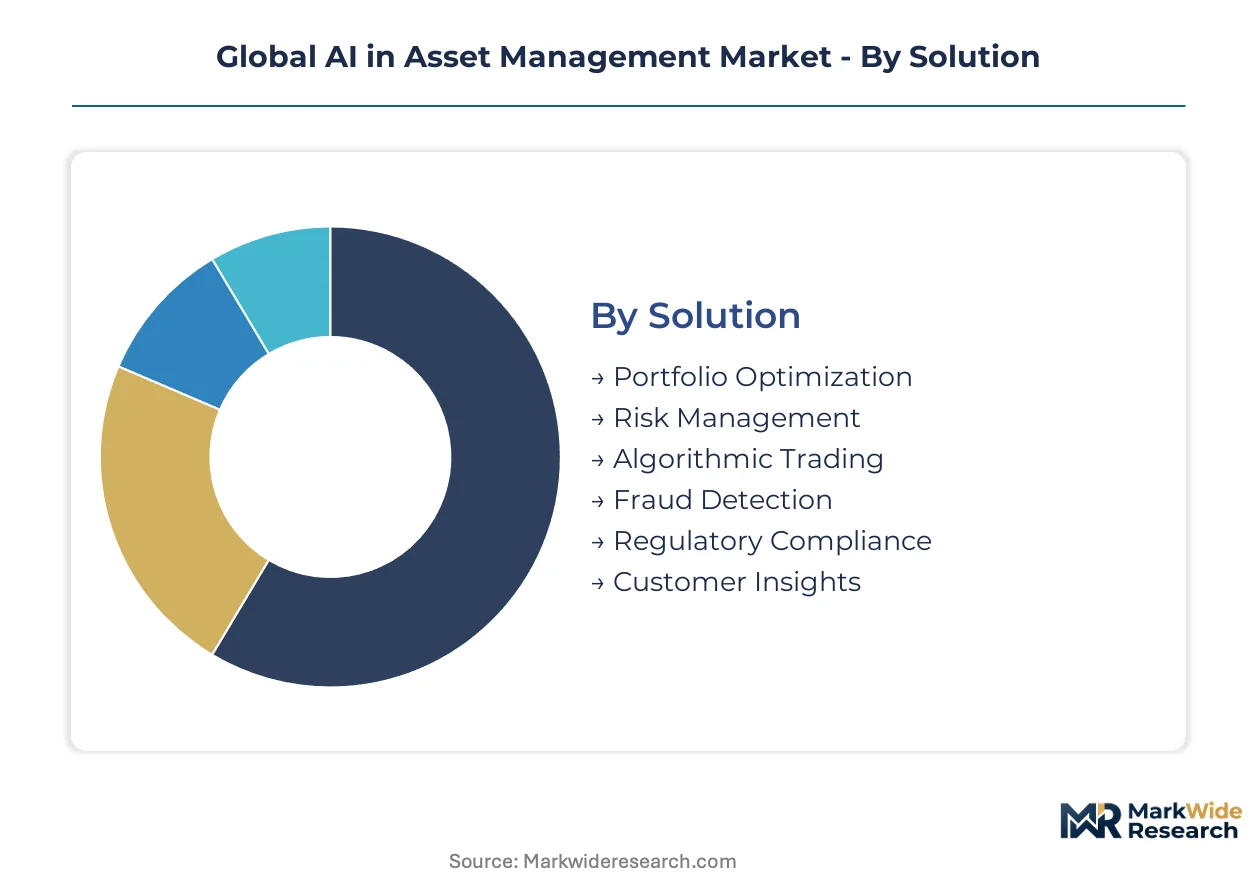
Segmentation in AI asset management reveals distinct procurement patterns across solution types, infrastructure models, and end-user sophistication tiers. Understanding these divides enables vendors to calibrate pricing, compliance features, and integration depth to specific buyer archetypes rather than deploying one-size-fits-all platforms.
Solution:
Substitution pressure concentrates in commoditized analytics modules where open-source libraries and cloud-native alternatives erode proprietary tool margins. Portfolio optimization and risk management functions face the strongest downward price compression from freely available Python-based frameworks.
- Portfolio Optimization:Mathematical engines employing mean-variance analysis, risk parity construction, and factor-based allocation across multi-asset class portfolios. Demand clusters among quantitative hedge funds in the United States seeking to process alternative datasets into executable position sizing. Cloud elasticity has democratized access to backtesting infrastructure previously requiring dedicated server farms.
- Risk Management:Real-time monitoring systems tracking market, credit, and operational risk exposures through Monte Carlo simulation and stress testing protocols. European fund managers under EU AI Act mandates are prioritizing explainable risk models with documented audit trails for regulatory examination.
- Algorithmic Trading:Execution algorithms minimizing market impact through smart order routing and liquidity-seeking strategies.
- Fraud Detection:Anomaly detection systems identifying market manipulation, insider trading patterns, and account compromise across trading operations.
- Regulatory Compliance:Automated reporting tools aligning portfolio disclosures with jurisdiction-specific filing requirements.
- Customer Insights:Behavioral analytics engines segmenting investor preferences for personalized product recommendations.
Portfolio optimization retains volume leadership; regulatory compliance holds the steepest expansion curve.
Deployment:
Cost tier stratification dominates infrastructure selection, with capital intensity and data sovereignty requirements driving divergent deployment patterns across end-user segments. Large institutions with legacy technology estates face higher switching costs than digitally native entrants.
- Cloud-Based:Elastic compute environments enabling on-demand scaling for model training, backtesting, and production inference. Mid-sized quantitative funds in Singapore and Switzerland are migrating core workloads to cloud to avoid capital-intensive hardware procurement.
- On-Premises:Dedicated hardware installations maintaining physical control over sensitive portfolio data and proprietary algorithms. Pension funds in Germany and France with strict data localization mandates continue prioritizing on-premises deployments despite higher total cost of ownership.
- Hybrid:Architectures splitting workloads between private infrastructure and public cloud based on data sensitivity and computational requirements.
- Edge Computing:Distributed processing nodes enabling low-latency signal generation at proximity to exchange matching engines.
Cloud-based deployment captures the broadest user base; edge computing is climbing the fastest as latency-sensitive strategies proliferate.
End User:
Customer type segmentation reflects divergent procurement sophistication, with institutional scale and regulatory burden shaping AI adoption timelines. Family offices and mutual funds occupy opposite ends of the technology maturity spectrum.
- Hedge Funds:Systematic and discretionary funds deploying machine learning for alpha generation, risk management, and execution optimization. Quantitative strategies in the United States command the largest AI research budgets, with multi-manager platforms building dedicated data science teams exceeding fifty researchers.
- Wealth Managers:Advisory practices leveraging robo-advisory platforms and client analytics to scale personalized service delivery. U.K. wealth managers face FCA scrutiny on algorithmic explainability, slowing deployment of black-box recommendation engines.
- Pension Funds:Defined benefit and defined contribution plans applying AI to liability-driven investment and member communication optimization.
- Mutual Funds:Retail-facing fund complexes integrating AI into fund selection tools and distributor analytics.
- Family Offices:Single-family and multi-family offices adopting fraud detection and consolidated reporting automation.
Hedge funds retain volume leadership; family offices are gaining share fastest as automation costs decline.
Investment Strategy:
Maturity gradients separate established quantitative approaches from experimental AI applications in fundamentally oriented strategies. Technical and event-driven categories face technology-driven disruption to traditional practitioner skill sets.
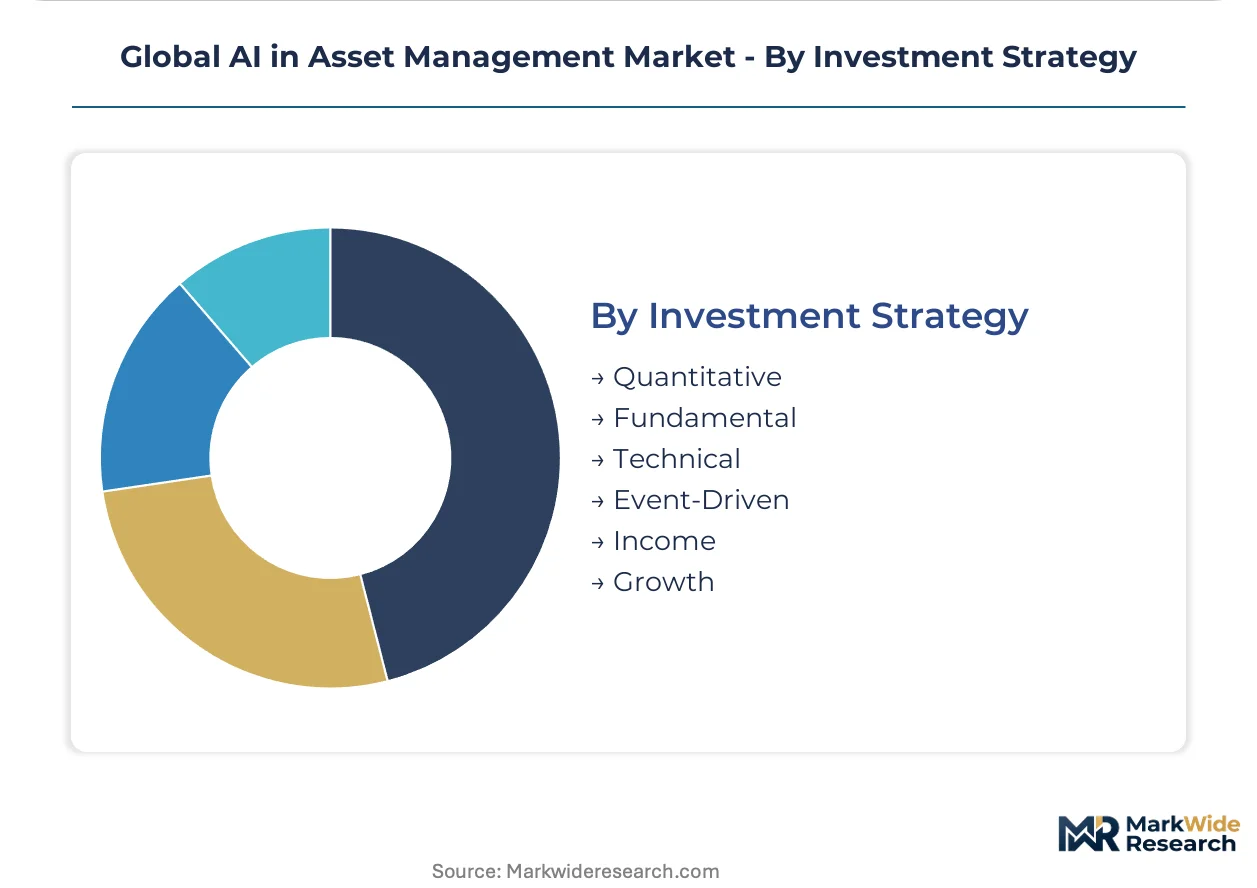
- Quantitative:Systematic strategies deriving investment decisions entirely from mathematical models and algorithmic execution. Quantitative funds in the United States are expanding natural language processing capabilities to parse earnings calls and regulatory filings at scale.
- Fundamental:Research-intensive approaches augmenting analyst judgment with AI-powered screening and sentiment analysis. Fundamental equity teams at European asset managers are adopting large language models to compress research production timelines.
- Technical:Pattern recognition strategies identifying price momentum and trend signals through machine learning classification.
- Event-Driven:Strategies exploiting corporate actions, merger arbitrage, and distressed situations through predictive analytics.
- Income:Fixed-income and dividend-focused approaches applying AI to credit risk assessment and cash flow forecasting.
- Growth:Equity strategies identifying expansion-phase companies through alternative data signals and earnings trajectory modeling.
Quantitative strategies retain volume leadership; fundamental approaches hold the steepest expansion curve as AI augmentation spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hedge funds and pension systems in the United States command the largest procurement budgets for AI-driven portfolio infrastructure, while European fund managers navigate stricter algorithmic transparency mandates. Wealth managers in Singapore and Switzerland are accelerating automation investments as family office demand concentrates in private banking hubs.
United States
Systematic hedge funds in New York and Connecticut are expanding machine learning research teams to process alternative datasets into executable strategies. The SEC enforces AI disclosure rules under investment adviser regulations, requiring registered advisers to document model governance frameworks. The Greater Boston cluster anchors quantitative research talent pipelines feeding multi-manager platforms with dedicated data science divisions.
United Kingdom
Wealth managers in London are deploying robo-advisory platforms while navigating explainability requirements for retail-facing algorithms. The Financial Conduct Authority scrutinizes model governance standards, forcing architecture redesigns for black-box recommendation engines. The Square Mile concentration of asset managers is embedding compliance modules directly into portfolio construction workflows.
Germany
Pension funds in Frankfurt and Munich are prioritizing on-premises deployments to satisfy strict data localization mandates despite higher total cost of ownership. The EU AI Act imposes conformity requirements on high-risk algorithmic systems, compelling documented audit trails before deployment. The Baden-Württemberg engineering cluster is supplying specialized hardware for inference acceleration at asset management operations.
Singapore
Family offices and private banking operations are adopting fraud detection and customer insights tooling as automation costs decline for mid-sized wealth pools. The Monetary Authority of Singapore promotes responsible AI use through industry guidance rather than prescriptive mandates. The Marina Bay financial district is attracting quantitative fund subsidiaries seeking Asian market access with regulatory clarity.
Switzerland
Single-family offices in Geneva and Zurich remain underpenetrated for consolidated reporting automation and behavioral analytics engines. FINMA maintains principle-based oversight of algorithmic trading systems without duplicative EU conformity requirements. The Zug crypto valley spillover is generating demand for AI-powered due diligence on digital asset allocations.
Global AI in Asset Management Market Competitive Landscape
Player mix skews toward cloud infrastructure providers and specialized financial technology vendors rather than consolidated platform monopolies. Tiered competition separates enterprise-grade providers serving institutional scale from point-solution specialists addressing specific compliance or analytics functions. Dominant competitive moves include strategic partnerships between asset managers and cloud hyperscalers, alongside portfolio diversification into explainable AI modules for regulatory markets.
Within the cloud infrastructure tier, Amazon Web Services, Inc. and Microsoft exemplify the scale-driven archetype, occupying positions as default compute environments for model training and inference workloads. BlackRock, Inc. anchors the incumbent asset manager category, representing deep integration between risk analytics and portfolio construction workflows rather than pure technology supply. International Business Machines Corporation sits within the enterprise software tradition, bridging legacy system integration requirements with emerging AI governance tooling demanded by ISO 42001 procurement specifications.
| Leading Market Players |
|---|
| BlackRock, Inc. |
| Amazon Web Services, Inc. |
| International Business Machines Corporation |
| Microsoft |
| Charles Schwab & Co., Inc. |
| Infosys Limited |
| Genpact |
| Salesforce, Inc. |
| IPsoft Inc. |
| Others |
Supply & Pricing Matrix
Ninety-day GPU provisioning lead times at Taiwan Semiconductor Manufacturing are compressing pricing power for mid-tier quantitative funds while amplifying premium capture by cloud hyperscalers with forward capacity commitments. This inventory tension concentrates cost-plus contract leverage among institutional-scale buyers and forces smaller asset managers into spot-market inference pricing.
Pricing Analysis
Cost-plus contracts indexed to NVIDIA H100 unit pricing dominate enterprise AI infrastructure procurement, with annual escalation clauses tied to foundry wafer costs. Three-tier pricing structure across premium certified, standard compliant, and economy unmanaged tiers separates ISO 42001-audited platforms from open-source alternatives. Pricing pressure stems from open-source Python frameworks eroding proprietary analytics margins. Hedge funds with dedicated infrastructure teams exhibit lowest price sensitivity; single-family offices in Switzerland face acute budget constraints.
Supply Chain Analysis
Inbound logistics costs through the Port of Kaohsiung and Shanghai-Ningbo corridor are elevating total landed costs for specialized inference hardware destined to European data centers. Taiwan, South Korea, and the United States anchor GPU and high-bandwidth memory supply. Advanced packaging substrates and CoWoS interposers constitute critical bottlenecks. Single-source dependency on TSMC's Arizona and Hsinchu fabs presents tariff-exposure risk. Distribution runs through direct OEM relationships and cloud marketplace procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global AI in asset management is entering a cyclical recovery phase as interest rate stabilization restores hedge fund deployment budgets for alternative data infrastructure.
For Market Incumbents: Shield core revenue streams by embedding explainability modules into existing Aladdin-class platforms before EU AI Act renewal cycles. Prioritize ISO 42001 pre-certification of risk analytics workflows to lock out unqualified challengers. Acquire specialized natural language processing boutiques in the Greater Boston corridor to preempt talent scarcity. For New Entrants and Emerging Players: Explainable AI tooling gaps in German pension fund procurement specifications offer immediate contract windows. Target family office automation in Singapore and Geneva where incumbent platforms lack consolidated reporting depth. Pursue white-label partnerships with Swiss private banks rather than direct enterprise sales. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment models as GPU-as-a-service commodifies training infrastructure. Five-to-ten-year viability favors point-solution vendors with regulatory compliance moats over horizontal platform plays. Monitor SEC AI disclosure rule enforcement intensity as inflection signal for compliance software procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 42001 Certification Investment | Certification bifurcates vendor eligibility across institutional procurement channels before contract renewals. |
| Explainable AI Module Development | EU AI Act mandates force documented audit trails into portfolio construction workflows. |
| Cloud Partnership Expansion | Microsoft and AWS anchor enterprise-grade training infrastructure for quantitative strategies. |
| Alternative Data Licensing Agreement | Proprietary datasets command escalating fees that compress margins for mid-sized funds. |
| Quantitative Research Talent Acquisition | PhD-level machine learning scarcity in Boston and New York strains fund economics. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with chief technology officers at quantitative hedge funds, compliance officers at European asset managers, cloud procurement leads, and regulatory affairs directors; and secondary validation against SEC enforcement actions, EU AI Act implementation guidance, hyperscaler capex disclosures, and ISO certification registries. Bottom-up segment sizing triangulated against top-down market boundary estimates.
Across the projection horizon, the analytical framework modeled deployment mode, end-user sophistication tier, solution functional category, and regional regulatory cluster. CAGRs derived from segment-level growth rate reconciliation with aggregate market boundary constraints. Forecast inputs incorporated alternative data spending patterns and cloud infrastructure pricing trajectories.
Material uncertainties — regulatory enforcement intensity divergence, GPU supply disruption, and open-source framework substitution velocity — sit outside the modeled envelope. Forecasts reflect documented assumptions about compliance timeline adherence and capital availability for infrastructure migration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Asset Management
India AMC Industry Market
Asset Management
US Healthcare Assets Management Market
Asset Management
Fixed Income Asset Management Market
Asset Management
LAMEA Equity Management Software Market
Asset Management
Europe Asset Management Market
Asset Management
Global Remote Asset Management Market
Asset Management
Asset Optimization Solutions Market
Asset Management
APAC Mutual Fund Market
Asset Management
US Pension Funds Market
Asset Management
Asset Management System Market
Asset Management
Japan Asset Management Market
Asset Management
Asia-Pacific Utilities Asset Management Market
Asset Management
Fund Management Software Market
Asset Management
Canada Asset Management Market
Asset Management
US Asset Management Market
Asset Management
Hardware Asset Management Market