
 Capital Expenditure Market | 2026-2036
Capital Expenditure Market Size, Share, and Industry Trends Forecast 2026-2036
Capital Expenditure Market Analysis
Specialized construction labor and semiconductor equipment engineering talent is bifurcating capital deployment timelines across the technology sector. Microsoft leverages its Azure infrastructure scale to sustain multi-billion-dollar facility investments across North America and Europe. Amazon anchors logistics and fulfillment network expansion through disciplined land acquisition and automated warehouse deployment. Nvidia differentiates by concentrating capex on advanced foundry partnerships and in-house chip packaging capabilities rather than broad vertical integration.
Capital expenditure denotes long-term investments in physical assets—property, machinery, infrastructure, and technology systems—with depreciation schedules typically spanning 5 to 30 years and returns evaluated through net present value or internal rate of return thresholds. These outlays enable capacity expansion, operational efficiency gains, and regulatory compliance across industrial and commercial operations. Assets and infrastructure investment types dominate total spending as energy grid modernization and data center construction absorb disproportionate capital pools. Machinery and facilities categories within the industry vertical dimension show concentrated growth in energy and healthcare as both sectors face aging asset bases and stricter operational standards. Maintenance and expansion spending categories attract the largest funding commitments because upgrade cycles and new development projects compete for limited internal funds and debt capacity.
The US Inflation Reduction Act and Infrastructure Investment and Jobs Act direct federal incentives toward domestic manufacturing reshoring and clean energy deployment, reshaping how corporations prioritize geographic investment decisions. China's MIIT dual carbon goals and GB energy efficiency standards force industrial operators to accelerate equipment replacement cycles or face operational restrictions. India's PLI scheme and CEA grid codes channel capital toward solar manufacturing and transmission infrastructure buildouts. Stakeholders must monitor how divergent subsidy regimes and local content requirements alter project economics and supplier selection across jurisdictions.
Market Dynamics
Cloud hyperscalers are compressing data center construction timelines while federal industrial policy redirects private capital toward domestic manufacturing and clean energy infrastructure, creating bifurcated demand patterns across asset-heavy sectors.
Growth Catalysts
- US Inflation Reduction Act:Production tax credits for solar manufacturing and battery gigafactories are accelerating facility investments across the American Southwest and Midwest industrial corridors.
- Data center power density requirements:AI training clusters now demand 50-100 megawatt deployments per campus, forcing utilities and developers to coordinate transmission infrastructure buildouts at unprecedented scale.
- India PLI scheme:Manufacturing-linked incentives for solar modules and advanced chemistry cell batteries are channeling capital toward Gujarat and Tamil Nadu industrial zones.
Market Restraints
- Specialized construction labor scarcity:Electrical and mechanical trades for hyperscale data centers face 18-24 month lead times in major North American markets, extending project schedules.
- Copper and transformer supply concentration:Grid equipment procurement depends on a limited supplier base concentrated in East Asia, exposing projects to input cost volatility and delivery uncertainty.
- Permitting timeline fragmentation:Environmental review processes under NEPA and state equivalents create 36-60 month approval windows for transmission and industrial projects in the United States.
Strategic Opportunities
- Grid-scale battery storage deployment:Merchant battery projects in ERCOT and CAISO markets capture arbitrage revenues while providing capacity services to renewable developers.
- Modular data center construction:Prefabricated power and cooling modules reduce on-site construction labor requirements and compress commissioning schedules for edge computing deployments.
- EU Green Deal industrial funding:Innovation Fund and Just Transition Mechanism financing supports carbon-intensive sector decarbonization projects in Poland, Romania, and Germany's coal regions.
Industry Challenges
- Semiconductor equipment engineering talent gap:Advanced packaging and lithography system design expertise concentrates at a handful of institutions, constraining foundry expansion timelines.
- Legacy asset integration complexity:Brownfield industrial automation projects must coordinate new digital control systems with 20-30 year old mechanical infrastructure without production disruption.
- CE marking and machinery directive compliance:European industrial equipment exports face extended certification timelines as notified body capacity constrains market access for automation suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Capital Expenditure Market |
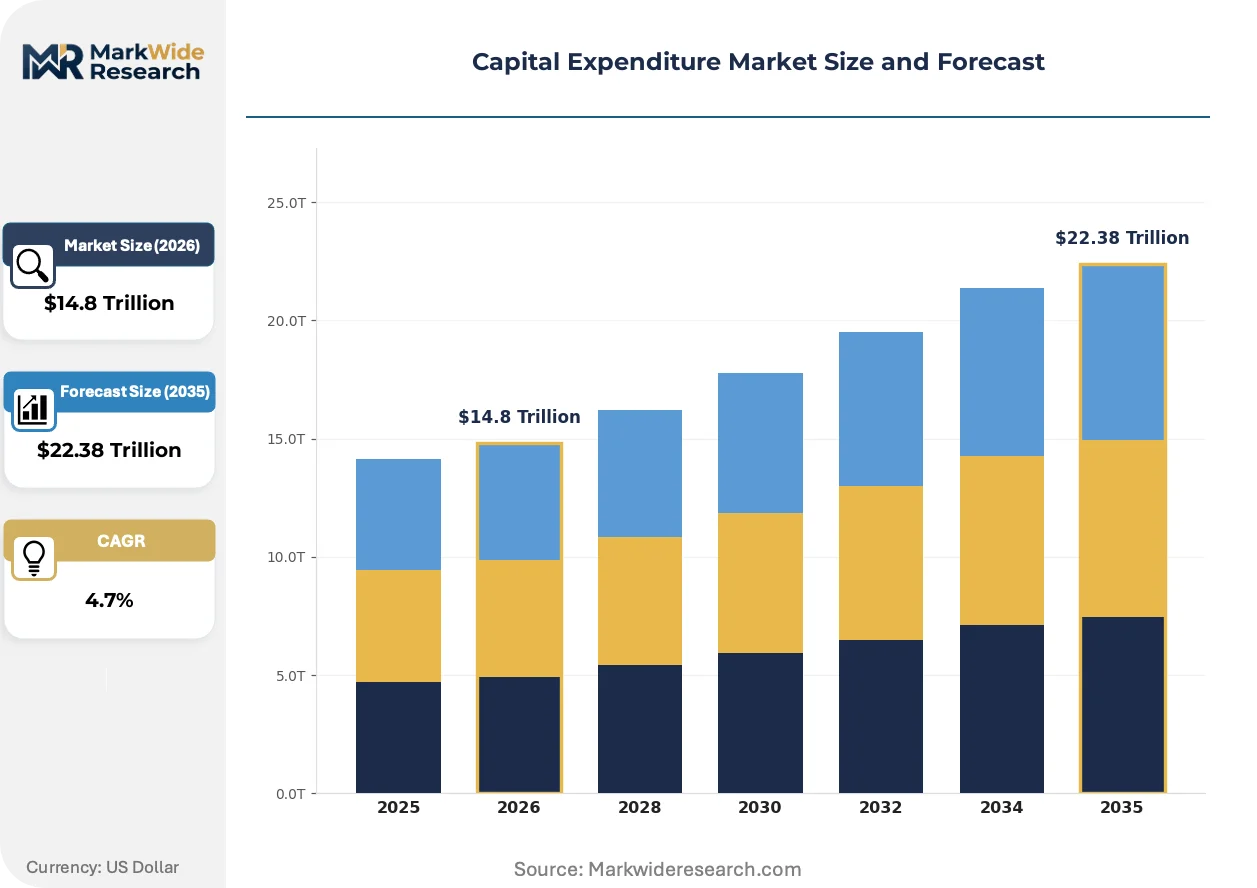
| Market Size in 2026 | $14.8 Trillion |
| Market Size in 2035 | $22.38 Trillion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Type: Assets, Infrastructure, Machinery, Facilities Industry Vertical: Construction, Transportation, Energy, Healthcare Spending Category: Maintenance, Expansion, Upgrade, New Development Funding Source: Equity, Debt, Grants, Internal Funds |
| Companies Covered | Microsoft, Apple, Amazon, Broadcom, Nvidia, Alphabet, Oracle, Netflix, Meta Platforms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Capital Expenditure Market Emerging Trajectories
Capital deployment patterns are fragmenting across three simultaneous pressures: compute infrastructure density requirements, industrial decarbonization mandates, and supply chain regionalization imperatives.
Immersion cooling systems for AI accelerators is miniaturizing thermal management footprints within data center white space. Hyperscalers in Northern Virginia and Frankfurt are piloting two-phase dielectric fluid systems at 100+ kilowatt rack densities. This technology is compressing mechanical infrastructure requirements and enabling facility designs previously constrained by air-cooling limitations.
China's MIIT dual carbon goals and GB energy efficiency standards are forcing industrial operators to accelerate equipment replacement cycles or face operational restrictions. Steel, cement, and chemical producers must retrofit with electric arc furnaces, carbon capture systems, and waste heat recovery by 2025-2027 compliance windows. Heavy industry in Hebei and Shandong provinces faces the most acute capital reallocation pressures as provincial regulators enforce intensity reduction targets.
Energy-as-a-service contracting models are displacing traditional equipment ownership in commercial and industrial segments. Third-party developers finance on-site solar, storage, and combined heat and power assets through 15-20 year power purchase agreements. This procurement evolution is most visible in California and Texas manufacturing facilities where offtakers prioritize balance sheet preservation and operational flexibility over asset control.
Capital Expenditure Market Segmentation
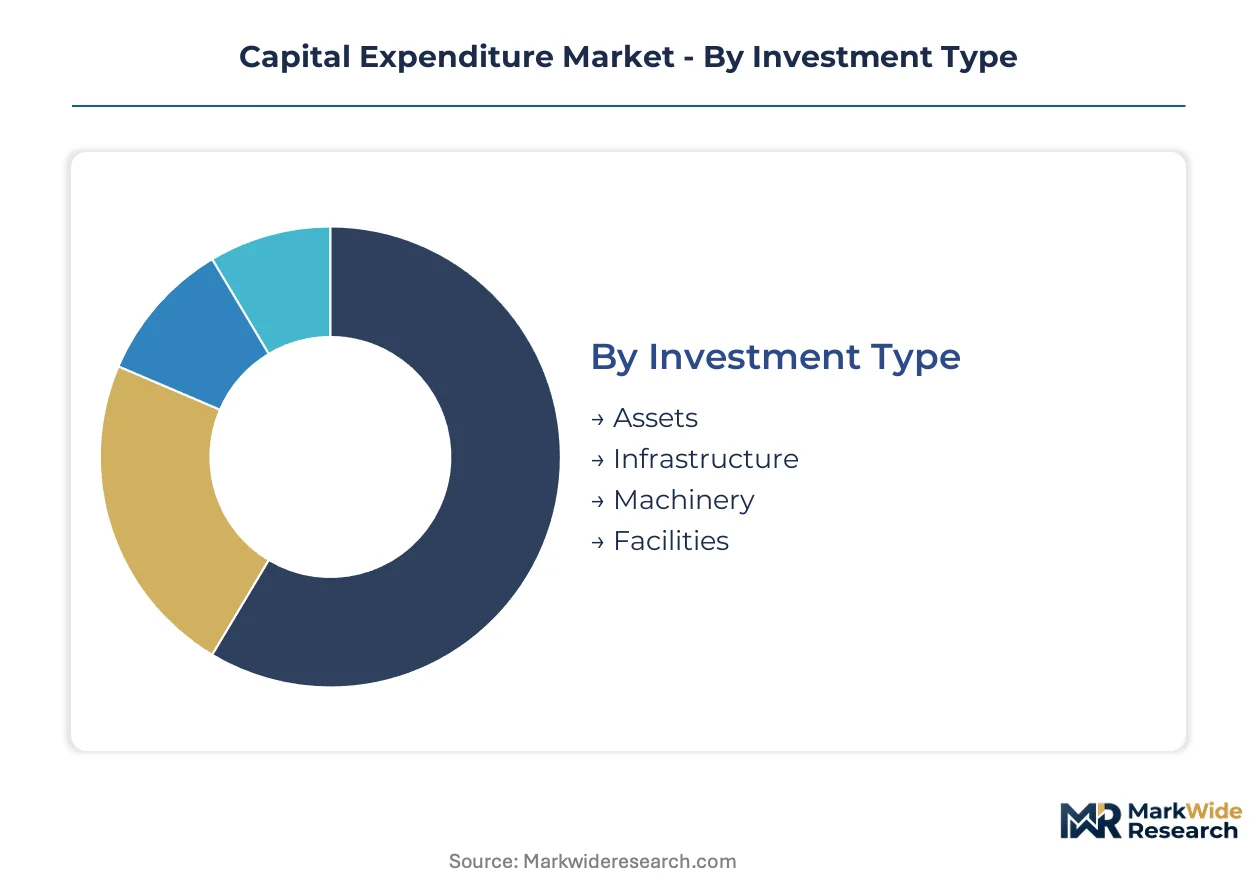
Capital expenditure segmentation reveals how capital pools fragment across asset lifecycles, regulatory compliance windows, and financing structures. Understanding these dimensions exposes where procurement cycles accelerate and where budget approvals face friction.
Investment Type:
Margin pools concentrate in infrastructure deployments where long-dated revenue streams and regulatory mandates protect returns.
- Assets:Balance sheet holdings in property, plant, and equipment with depreciation schedules spanning 5 to 30 years. Energy grid modernization and data center construction in the United States, China, and India absorb disproportionate capital pools as utilities and cloud operators coordinate transmission buildouts.
- Infrastructure:Large-scale civil and utility systems requiring multi-year construction timelines and coordinated permitting. Demand clusters around clean energy corridors in the American Southwest and industrial zones in Gujarat and Tamil Nadu where PLI incentives reduce project payback periods.
- Machinery:Production equipment and industrial automation systems with replacement cycles tied to efficiency mandates. China's MIIT dual carbon goals force steel and cement producers in Hebei and Shandong toward electric arc furnace retrofits.
- Facilities:Commercial and industrial buildings with operational standards shaped by local building codes and energy efficiency regulations. Healthcare and energy verticals show concentrated facility investment as aging asset bases meet stricter operational standards.
The dominant share belongs to Assets, while Infrastructure is closing the gap fastest as federal industrial policy redirects private capital toward domestic manufacturing and clean energy deployment.
Industry Vertical:
Application intensity varies sharply, with energy and healthcare commanding premium capital allocation due to regulatory compliance burdens and asset obsolescence pressures.
- Construction:Residential, commercial, and civil engineering projects with materials procurement exposed to copper and transformer supply concentration in East Asia. Specialized electrical and mechanical trades face 18-24 month lead times in major North American markets.
- Transportation:Logistics networks, port infrastructure, and fleet electrification requiring land acquisition discipline and automated deployment. Amazon anchors fulfillment expansion through systematic warehouse automation across North America and Europe.
- Energy:Generation, transmission, and storage assets absorbing capital from IRA production tax credits and India's CEA grid codes. Merchant battery projects in ERCOT and CAISO markets capture arbitrage revenues while providing capacity services.
- Healthcare:Hospital systems, pharmaceutical manufacturing, and medical device production facing FDA validation requirements and aging infrastructure replacement. Operational standards tighten as asset bases depreciate beyond original design lifecycles.
Energy commands the largest capital allocation, though Healthcare is expanding most quickly as facility modernization backlogs compete for limited debt capacity.
Spending Category:
Customer type determines approval velocity, with maintenance spending flowing through operational budgets while expansion projects require board-level capital committee review.
- Maintenance:Routine asset preservation and compliance-driven replacements funded through operating expenditure conversions. Brownfield industrial automation projects must coordinate new digital control systems with 20-30 year old mechanical infrastructure.
- Expansion:Capacity additions and geographic extension requiring multi-year deployment timelines and coordinated supplier qualification. Cloud hyperscalers compress data center construction schedules while federal policy redirects capital toward domestic manufacturing.
- Upgrade:Technology refresh and efficiency improvement initiatives triggered by regulatory compliance windows or competitive positioning. China's GB energy efficiency standards force equipment replacement cycles or operational restrictions.
- New Development:Greenfield projects with 36-60 month permitting timelines under NEPA and state equivalents in the United States. Environmental review processes fragment approval windows for transmission and industrial deployments.
Maintenance attracts the largest funding commitments, yet New Development is gaining share fastest as reshoring imperatives and clean energy mandates create project pipelines.
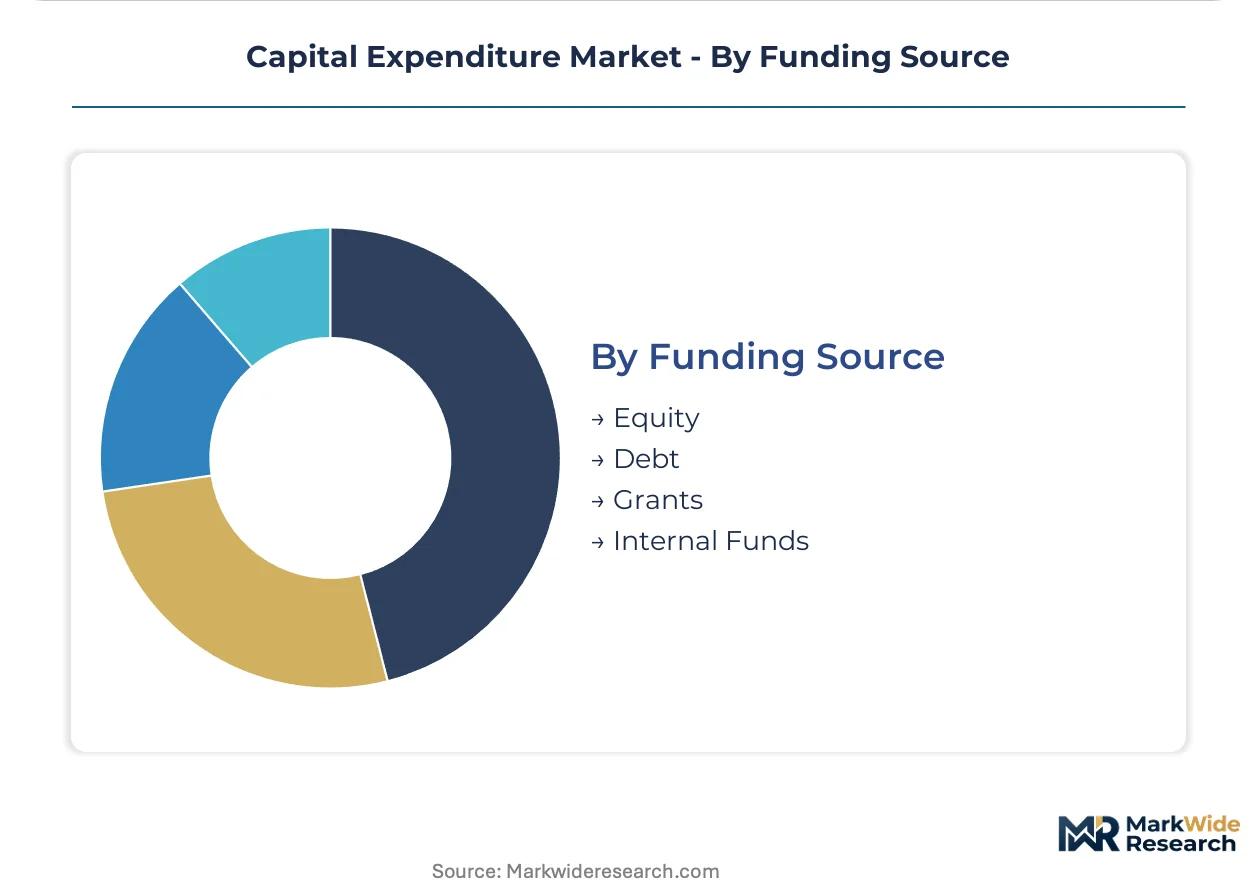
Funding Source:
Cost tier stratification shapes risk-return profiles, with equity financing preserving balance sheet flexibility and debt capturing tax shield advantages at scale.
- Equity:Shareholder capital deployment for strategic initiatives with uncertain cash flow timing or high technical risk. Nvidia concentrates capex on advanced foundry partnerships and in-house chip packaging capabilities.
- Debt:Bond issuance and term loans secured against asset collateral or project cash flows. Energy-as-a-service contracting models displace traditional ownership through 15-20 year power purchase agreements.
- Grants:Federal and state incentive programs including IRA production tax credits and EU Green Deal Innovation Fund. Subsidy regimes alter project economics and supplier selection across jurisdictions.
- Internal Funds:Retained earnings and operating cash flow allocation competing between upgrade cycles and new development. Microsoft leverages Azure infrastructure scale to sustain multi-billion-dollar facility investments.
Debt dominates total funding volume, though Grants are climbing the fastest as divergent industrial policy regimes expand subsidy pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Capital deployment commands premium returns in the United States compared to India, where subsidy-dependent project economics compress margins despite faster volume growth. This pricing-power asymmetry redirects multinational facility strategies toward American industrial corridors while domestic champions capture volume in emerging Asian manufacturing zones.
United States
Data center power density requirements and battery gigafactory buildouts absorb the largest capital pools. IRA production tax credits for solar manufacturing and clean energy infrastructure redirect private investment toward domestic manufacturing reshoring. Northern Virginia and Phoenix anchor hyperscale facility construction as utilities coordinate 50-100 megawatt transmission buildouts per campus.
China
Steel and cement producers face acute equipment replacement pressures under MIIT dual carbon goals and GB energy efficiency standards. Provincial regulators in Hebei and Shandong enforce intensity reduction targets that force electric arc furnace retrofits and carbon capture installations. Yangtze River Delta industrial zones concentrate advanced manufacturing capex as operators accelerate compliance-driven asset cycles.
India
PLI scheme incentives for solar modules and advanced chemistry cell batteries channel capital toward manufacturing-linked expansion. CEA grid codes mandate transmission infrastructure buildouts that compete for limited debt capacity with industrial automation projects. Gujarat and Tamil Nadu industrial zones absorb disproportionate facility investment as domestic champions scale module and cell production.
Germany
EU Green Deal Innovation Fund and Just Transition Mechanism financing support carbon-intensive sector decarbonization in coal regions. CE marking and machinery directive compliance extend certification timelines for industrial equipment exports as notified body capacity constrains market access. Baden-Württemberg and North Rhine-Westphalia anchor automotive and industrial automation capex as producers retrofit for emissions compliance.
Japan
Semiconductor equipment engineering talent concentrates at METI-supported institutions, constraining foundry expansion timelines for advanced packaging and lithography systems. Kanto and Kansai industrial corridors prioritize precision machinery and robotics capex as manufacturers automate aging production lines. Domestic champions concentrate capex on captive supply of critical components rather than broad upstream integration.
Capital Expenditure Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the capital expenditure landscape. Cloud hyperscalers command premium valuations through infrastructure scale and disciplined land acquisition, while industrial operators compete on project execution speed and subsidy capture. Three archetypes dominate: balance-sheet-heavy technology deployers, grant-optimized industrial builders, and specialized equipment engineering houses. Competitive intensity centers on multi-billion-dollar facility investment pacing and foundry partnership structuring rather than direct price competition.
Within the balance-sheet-heavy tier, Microsoft and Amazon exemplify divergent capital deployment philosophies. Microsoft leverages Azure infrastructure scale to sustain facility investments across North America and Europe, while Amazon anchors logistics network expansion through systematic warehouse automation. Nvidia occupies a distinct position concentrating capex on advanced foundry partnerships and in-house chip packaging capabilities. These three represent how technology leadership, cost leadership, and specialized engineering focus fragment competitive positioning across the market.
| Leading Market Players |
|---|
| Microsoft |
| Apple |
| Amazon |
| Broadcom |
| Nvidia |
| Alphabet |
| Oracle |
| Netflix |
| Meta Platforms |
| Others |
Supply Flow & Price Mechanics
CE marking and machinery directive compliance gates both European market access and price tier qualification simultaneously, forcing automation suppliers to absorb extended certification timelines while buyers sort procurement pools by regulatory pedigree. This dual-gate mechanism stratifies vendor selection across premium certified tiers and uncertified economy alternatives.
Pricing Analysis
Capital deployment costs spread widest between the United States and India, where subsidy-dependent project economics in Gujarat and Tamil Nadu compress margins despite faster volume growth against American industrial corridors. Project-based contract structures dominate, with price differentiation resting on equipment certification grade and localized engineering service depth. Cost compression in Indian solar manufacturing is intensifying because PLI incentive stacking attracts oversupplied module capacity. Utility and hyperscale buyers show least price sensitivity, while mid-market industrial operators face acute budget constraints.
Supply Chain Analysis
Transformer and copper conductor inventories face 18-24 month lead times in North American markets, exposing hyperscale data center timelines to procurement bottlenecks. Supply concentrates in China, South Korea, and Germany for grid equipment and precision machinery components. Raw material feeds draw from Chilean copper concentrate, Australian lithium spodumene, and Mongolian rare earth oxide. Single-source vulnerability runs through East Asian semiconductor equipment engineering capacity. Distribution runs through EPC contractor-led turnkey arrangements rather than direct manufacturer sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capital expenditure markets fragment across three simultaneous demand-side shifts—compute infrastructure density requirements, industrial decarbonization mandates, and supply chain regionalization imperatives—creating specialized niches for differentiated positioning.
For Market Incumbents: Fortify data center construction capabilities through captive electrical trade labor development in Northern Virginia and Phoenix corridors, where specialized contractor scarcity threatens project velocity. Deepen foundry partnership structures to lock advanced packaging capacity against emerging fabless competitors. Anchor position by securing long-dated power purchase agreements with ERCOT and CAISO utilities before merchant battery saturation erodes arbitrage margins. For New Entrants and Emerging Players: Differentiate on modular data center construction speed, targeting edge computing deployments where prefabricated power modules compress commissioning schedules against traditional build methods. Enter through EU Green Deal Innovation Fund channels in Poland and Romania's coal regions, where Just Transition Mechanism financing supports carbon-intensive sector decarbonization projects. Pursue energy-as-a-service contracting models that displace traditional equipment ownership through third-party asset financing. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across AI training infrastructure sub-segments, where 50-100 megawatt campus deployments demand unprecedented balance sheet deployment. Target acquisition candidates with demonstrated hyperscale customer qualification and disciplined land acquisition pipelines rather than speculative greenfield development. Watch for inflection when CEA grid code enforcement accelerates transmission infrastructure competition for limited Indian debt capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Data Center Deployment | Prefabricated power modules reduce on-site labor requirements for edge computing buildouts. |
| Foundry Partnership Structuring | Advanced packaging capacity locks secure Nvidia's in-house chip capabilities against fabless rivals. |
| Energy-as-a-Service Contracting | Third-party solar and storage financing displaces traditional equipment ownership in California manufacturing. |
| CE Marking Acceleration | Notified body capacity expansion unlocks European automation equipment market access for certified suppliers. |
| PLI Incentive Stacking | Manufacturing-linked incentives in Gujarat reduce solar module project payback periods for domestic champions. |
Methodological Framework
Cross-validation between hyperscaler capex disclosures and EPC contractor project databases anchors the qualitative findings, combining primary interviews with data center development executives, utility planning officers, industrial procurement leads, and semiconductor equipment engineering directors with secondary validation through SEC filings, FERC interconnection queues, IRA tax credit registration data, and MIIT equipment replacement compliance notices. Bottom-up project aggregation and top-down macroeconomic driver triangulation reconcile volume estimates.
Sensitivity analysis across input cost scenarios and subsidy regime durability frames the projection methodology over the analysis window. Segmentation dimensions modeled include investment type, industry vertical, spending category, funding source, and regional regulatory cluster. CAGRs derive from fitted growth curves against historical deployment patterns, with specific inputs including data center power density requirements, electric arc furnace retrofit compliance deadlines, and PLI scheme incentive trajectories.
The analysis sits within stated boundaries; outcomes outside sustained federal industrial policy commitment and stable commodity input costs would require recalibration. Forecasts reflect documented assumptions regarding permitting timeline fragmentation and specialized labor scarcity persistence. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Asset Management
Mutual Fund Assets Market
Asset Management
Fixed Income Asset Management Market
Asset Management
Equity Management Tool Market
Asset Management
Global Asset Performance Management Market
Asset Management
Assets Under Management Market
Asset Management
Asset and Wealth Management Market
Asset Management
Global Infrastructure Asset Management Market
Asset Management
Asia-Pacific Utilities Asset Management Market
Asset Management
Canada Asset Management Market
Asset Management
LAMEA Equity Management Software Market
Asset Management
Global Remote Asset Management Market
Asset Management
US Pension Funds Market
Asset Management
Fund Management Software Market
Asset Management
Fund Management Fee Market
Asset Management
Asset Optimization Solutions Market
Asset Management
US Healthcare Assets Management Market