
 Hardware Asset Management Market | 2026-2036
Hardware Asset Management Market Size, Share, and Industry Trends Forecast 2026-2036
Hardware Asset Management Market Outlook
Capital-intensity divergence between cloud-native platforms and legacy on-premises toolsets is reorganizing competitive dynamics across the sector. ServiceNow leverages its workflow automation heritage to anchor enterprise-grade subscription revenue. IBM sustains mainframe-integrated asset governance through deep hybrid infrastructure relationships. Microsoft competes by embedding hardware tracking within broader Azure management consoles.
Hardware asset management encompasses the systematic tracking, lifecycle optimization, and financial governance of physical IT equipment from procurement through disposal, typically incorporating automated discovery protocols, depreciation engines, and compliance audit trails that interface with CMDB and procurement systems. Its primary commercial purpose is to eliminate ghost assets, ensure regulatory audit readiness, and optimize total cost of ownership across distributed technology estates. Cloud-based deployment is pulling ahead as enterprises abandon rigid on-premises refresh cycles, while managed services capture expanding margin pools from mid-market buyers lacking internal ITAM expertise. The server segment remains structurally critical due to density-driven data center complexity, though laptop governance is accelerating fastest under hybrid workforce permanence.
FCC equipment authorization rules, EU RoHS substance restrictions, and ISO 55000 asset management standards collectively shape product compliance obligations and procurement qualification pathways for hardware across regulated industries. NIST SP 800-53 security control frameworks further tighten federal agency requirements in the United States, directly influencing vendor certification investments. Stakeholders must monitor convergence between sustainability disclosure mandates and circular economy regulations as these frameworks increasingly dictate hardware refresh timelines and resale market access.
Market Dynamics
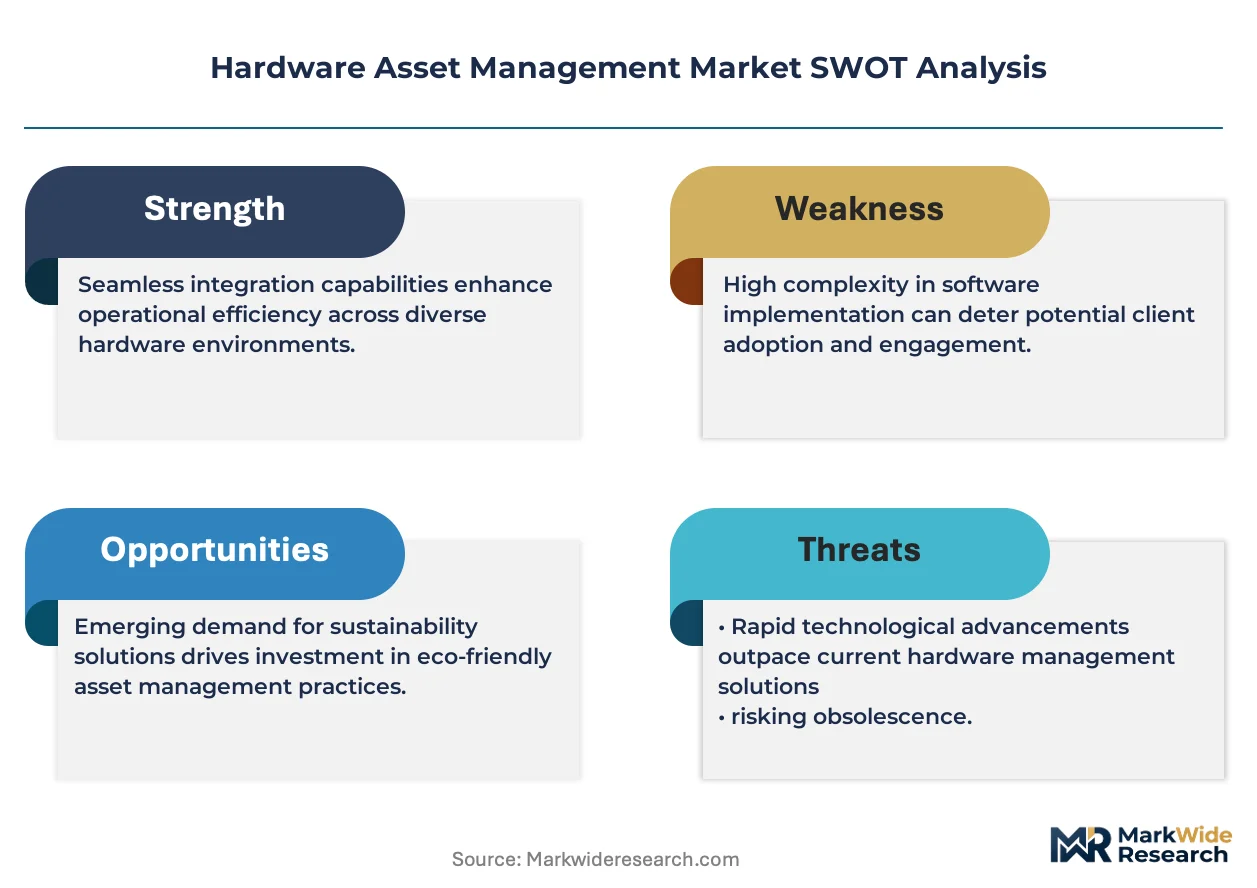
The migration from perpetual-license on-premises systems to cloud-native subscription platforms is compressing vendor margins while expanding addressable markets for automated discovery and lifecycle analytics.
Growth Catalysts
- ISO 55000 Alignment:Asset-intensive enterprises in Germany, France, and the United States are restructuring procurement workflows to satisfy auditor requirements for documented lifecycle governance and depreciation traceability.
- Hybrid Workforce Permanence:Distributed laptop estates across financial services and healthcare verticals require real-time location tracking and automated refresh scheduling to maintain security postures.
- FCC Equipment Authorization:Telecommunications infrastructure expansion is tightening hardware certification requirements, forcing asset managers to integrate compliance documentation into procurement systems.
Market Restraints
- Semiconductor Supply Concentration:Taiwan and South Korea dominate chip fabrication, exposing server and networking hardware procurement to geopolitical disruption and extended lead times.
- Legacy CMDB Integration Debt:Decades-old configuration management databases in federal agencies and regulated utilities resist API-based connectivity with modern asset discovery platforms.
- EU RoHS Substance Restrictions:Cadmium and lead limitations in circuit boards complicate refurbishment economics and secondary market resale pathways for enterprise hardware.
Strategic Opportunities
- India Manufacturing Incentives:PLI scheme subsidies for electronics production are attracting hardware OEMs, creating demand for localized asset tracking systems serving contract manufacturers.
- AI-Driven Predictive Refresh:Machine learning models analyzing utilization telemetry and failure patterns are converging with automated procurement workflows to optimize total cost of ownership.
- Circular Economy Mandates:Extended producer responsibility regulations in the Netherlands and California are opening revenue pools for certified e-waste recovery and remarketing services.
Industry Challenges
- ITAM-SRE Skill Convergence:Organizations struggle to hire professionals who bridge traditional asset governance with site reliability engineering practices for cloud-hybrid estates.
- Multi-Cloud Tagging Standardization:Inconsistent resource labeling conventions across AWS, Azure, and GCP environments complicate unified hardware spend allocation and chargeback accuracy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hardware Asset Management Market |
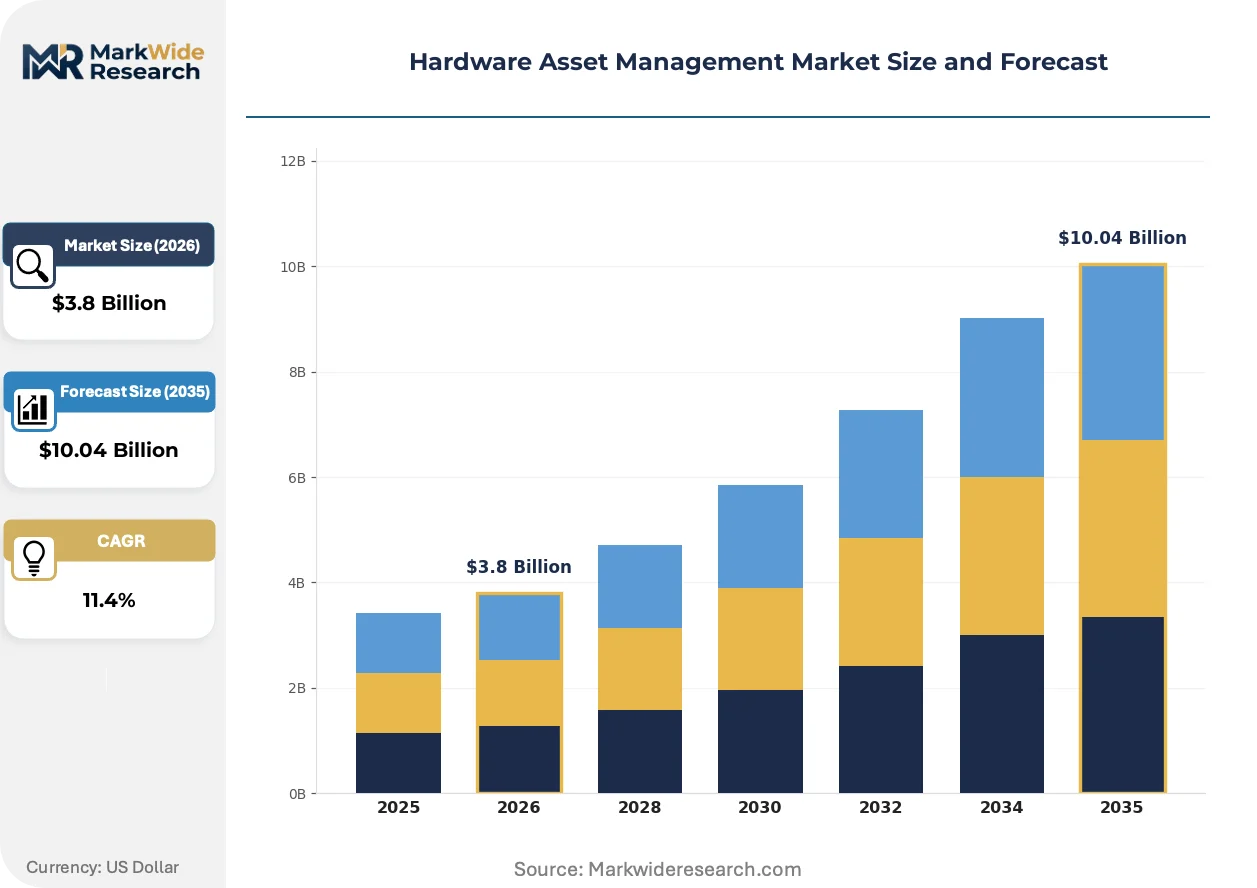
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktops, Laptops, Servers, Printers End User: IT Departments, Enterprises, SMBs, Government Agencies Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services Service Type: Consulting, Integration, Support, Maintenance |
| Companies Covered | ServiceNow, Inc., IBM, Microsoft Corporation, Dell Technologies Inc., HP Inc., Flexera, BMC Software, Inc., SolarWinds Worldwide, LLC, Ivanti, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hardware Asset Management Market Strategic Shifts
Discovery protocols and financial governance engines are separating into distinct architectural layers, with API-first platforms absorbing functionality from monolithic suites.
Radio-frequency identification and Bluetooth Low Energy tagging is bifurcating the asset tracking landscape. Data center operators deploy passive RFID for high-density server rack audits, while field services organizations adopt active BLE beacons for mobile equipment location. This technology split is compressing pricing power for unified-platform vendors unable to serve both latency-sensitive and cost-optimized use cases.
EU CSRD sustainability disclosure requirements are mandating hardware carbon footprint reporting across corporate value chains. Industrial manufacturers must now document scope 3 emissions from purchased IT equipment, forcing asset managers to integrate lifecycle assessment data into procurement decisions. German automotive suppliers and French luxury goods houses are advancing fastest in embedding these metrics into supplier scorecards.
Consumption-based hardware financing is displacing capital purchase models for server and storage infrastructure. Enterprises in the United Kingdom and Australia are contracting with managed service providers for per-utilization pricing, transferring depreciation risk and refresh obligation to vendors. This shift compresses direct software license sales while expanding recurring revenue for integrated platform operators.
Hardware Asset Management Market Segmentation
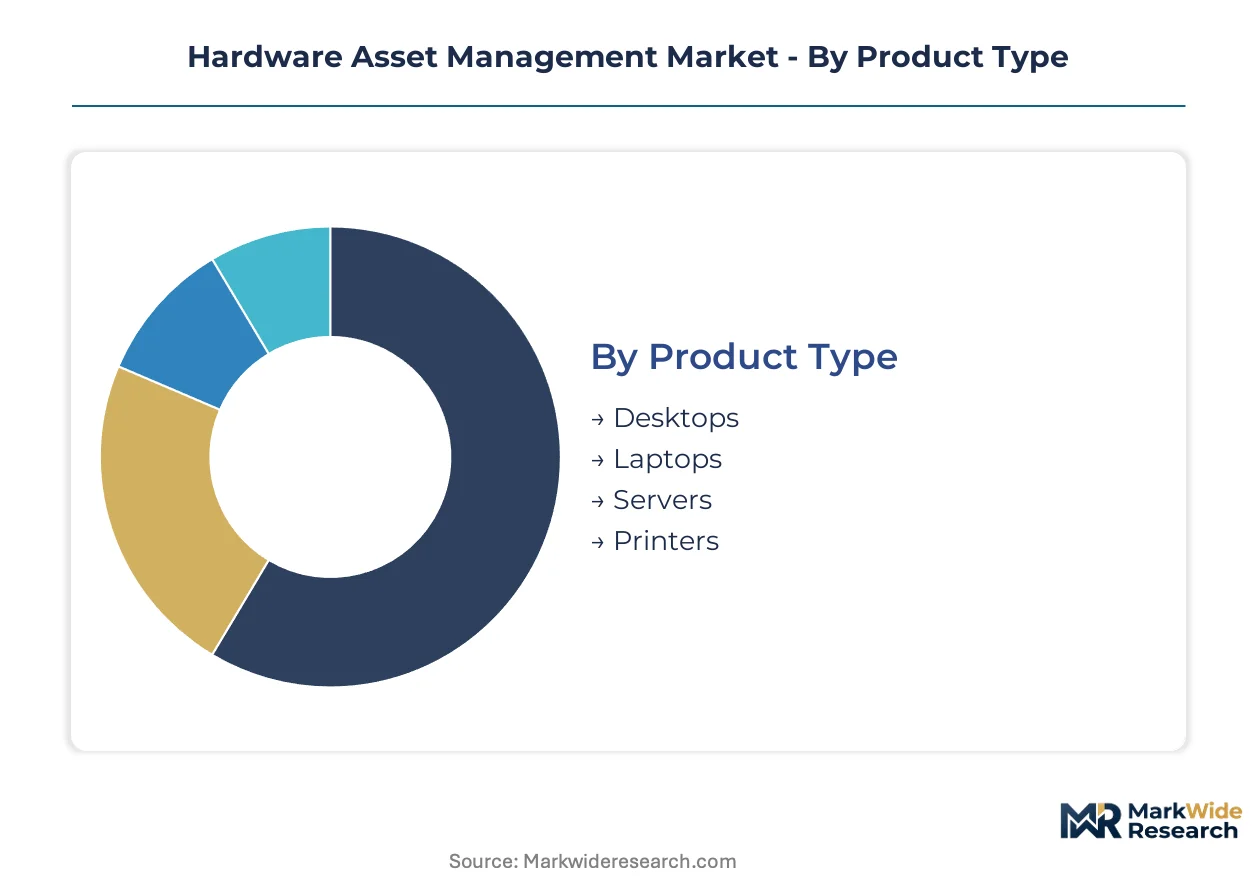
Hardware asset management solutions must align with distinct procurement rhythms, security postures, and lifecycle governance requirements across equipment categories and buyer types. Segmentation reveals where cloud-native platforms displace legacy systems versus where on-premises retention persists.
Product Type:
Server tracking concentrates in Germany's automotive supplier corridor and California's hyperscaler data center clusters, while laptop governance spreads across distributed financial services workforces in London and Singapore.
- Servers:High-density rack configurations demand automated discovery protocols interfacing with DCIM platforms. Demand clusters in Frankfurt's banking infrastructure and Northern Virginia's cloud regions, driven by thermal telemetry integration for refresh optimization.
- Laptops:Mobile endpoint tracking incorporates geolocation fencing and encryption status verification. Financial services firms in New York and healthcare systems in Texas are mandating real-time visibility for hybrid workforces.
- Desktops:Stationary workstation governance persists in regulated manufacturing floors and call center operations.
- Printers:Peripheral tracking focuses on toner consumption metering and secure print queue management in government facilities.
Servers command the established base. The steepest expansion runs through laptops.
End User:
Enterprise procurement teams prioritize ISO 55000 audit readiness, while government buyers embed NIST SP 800-53 controls into RFP requirements.
- Enterprises:Multi-site technology estates require unified CMDB integration across procurement, finance, and security operations. German automotive groups and French luxury conglomerates are embedding carbon footprint metrics into hardware scorecards.
- Government Agencies:Federal buyers in the United States mandate FedRAMP-authorized platforms with immutable audit trails. Defense contractors face DFARS cybersecurity supplement requirements for supply chain hardware tracking.
- IT Departments:Internal service organizations balance shadow IT discovery against centralized procurement policy enforcement.
- SMBs:Mid-market buyers lacking dedicated ITAM expertise are outsourcing asset governance to managed service providers.
Government agencies anchor compliance-driven procurement. SMBs are gaining share fastest through managed service adoption.
Deployment:
Cloud-native platforms compress implementation timelines for distributed estates, while hybrid configurations accommodate mainframe-integrated legacy environments.
- Cloud-Based:API-first architectures enable automated discovery across AWS, Azure, and GCP estates without agent deployment. UK financial services firms and Australian healthcare networks are abandoning perpetual license refresh cycles.
- Managed Services:Outsourced asset governance transfers depreciation risk and refresh obligation to vendors. Mid-market manufacturers in India's PLI scheme corridors are contracting for localized tracking support.
- On-Premises:Air-gapped installations persist in defense and critical infrastructure sectors with data sovereignty requirements.
- Hybrid:Split deployments bridge legacy CMDB investments with cloud analytics layers for gradual migration.
On-premises retains the installed base. Cloud-based deployment is climbing the fastest.
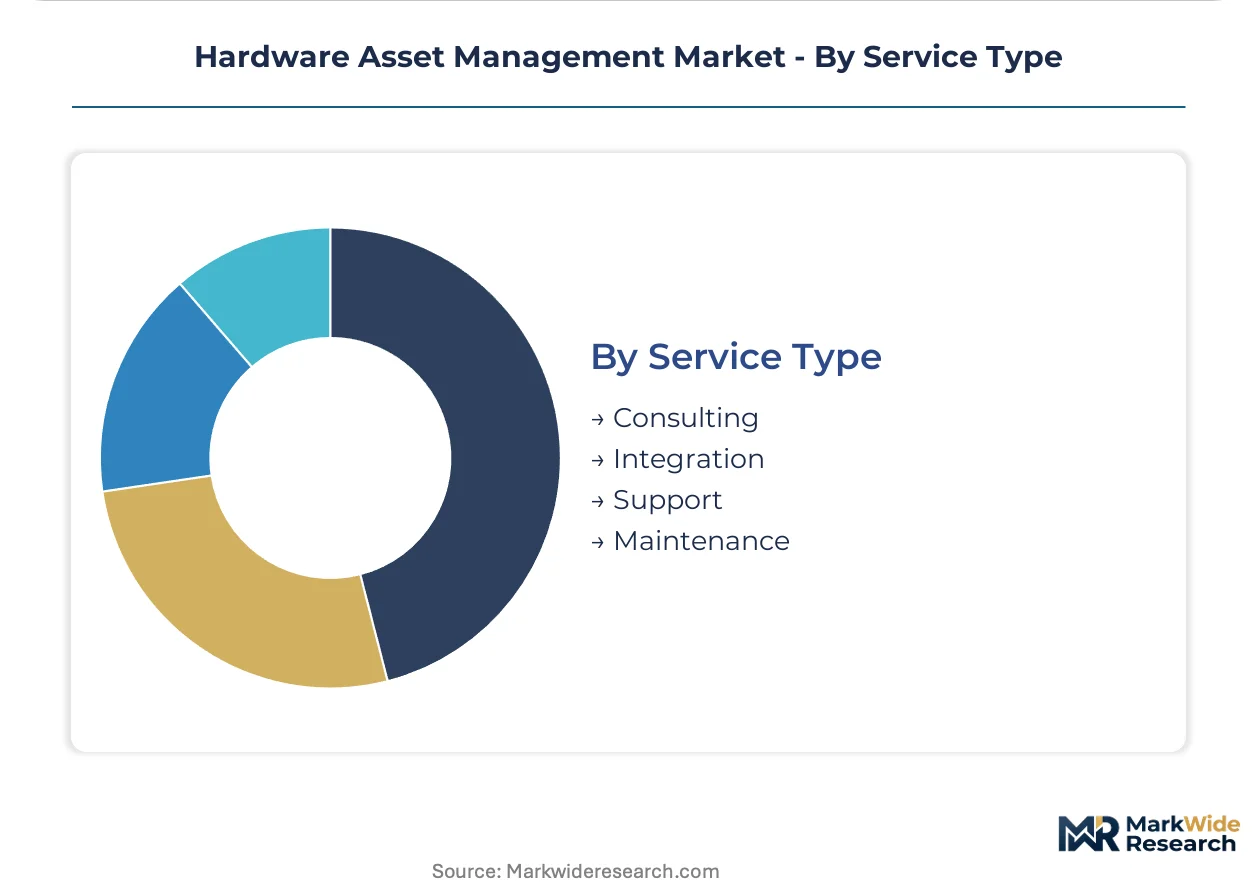
Service Type:
Integration services absorb the largest project budgets as enterprises reconcile decades-old procurement systems with modern discovery platforms.
- Integration:API mapping and data migration projects connect asset discovery engines with SAP, Oracle, and ServiceNow instances. German industrial manufacturers require ISA-95 standard alignment for OT-IT convergence.
- Consulting:ISO 55000 readiness assessments and process redesign engagements dominate in asset-intensive utilities and transportation operators.
- Support:Tiered helpdesk services address agent troubleshooting and discovery protocol optimization.
- Maintenance:Subscription renewals and patch management for on-premises discovery infrastructure.
Integration services capture the largest project value. Consulting is expanding most quickly under sustainability disclosure mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's industrial manufacturing corridor while cost-sensitive adoption accelerates across India's PLI-subsidized electronics zones. This asymmetry shapes vendor go-to-market strategies and localization investments across the forecast window.
United States
Federal agencies mandate FedRAMP-authorized platforms with immutable audit trails under NIST SP 800-53 frameworks. The FCC tightens equipment authorization rules for telecommunications infrastructure hardware. Northern Virginia's hyperscaler data center clusters drive automated discovery protocol demand for thermal telemetry integration.
Germany
Automotive suppliers embed carbon footprint metrics into hardware scorecards under EU CSRD sustainability disclosure requirements. ISO 55000 alignment pressures procurement workflow restructuring across asset-intensive enterprises. Frankfurt's banking infrastructure anchors high-density server tracking demand interfacing with DCIM platforms.
India
Electronics contract manufacturers localize asset tracking systems under PLI scheme production incentives. The country's national electronics regulator enforces BIS certification for imported IT equipment serving government buyers. Tamil Nadu and Karnataka's manufacturing corridors attract hardware OEMs seeking integrated governance platforms.
United Kingdom
Financial services firms abandon perpetual license refresh cycles for cloud-native subscription platforms. Consumption-based hardware financing displaces capital purchase models for server infrastructure. London's distributed banking workforces mandate real-time laptop visibility for hybrid security postures.
Japan
Industrial conglomerates align procurement with METI circular economy guidelines for extended producer responsibility. JIS standards govern enterprise hardware lifecycle documentation for audit readiness. Tokyo-Osaka manufacturing belts integrate predictive refresh analytics with automated procurement workflows.
Hardware Asset Management Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure with limited direct overlap. Enterprise workflow automation specialists anchor premium subscription revenue through deep CMDB integration. Infrastructure hardware OEMs leverage device manufacturing relationships to bundle asset governance tools. Mid-market SaaS providers compress implementation timelines for buyers lacking dedicated ITAM expertise. Dominant competitive moves include API-first platform expansion and managed service capability acquisition.
Within the workflow automation tier, ServiceNow, Inc. and BMC Software, Inc. represent enterprise-grade platform archetypes with heritage configuration management integration. IBM occupies a position bridging mainframe-integrated governance with hybrid cloud analytics layers. These three exemplify how vendor origins in adjacent infrastructure domains shape hardware asset management positioning without requiring identical go-to-market constructions.
| Leading Market Players |
|---|
| ServiceNow, Inc. |
| IBM |
| Microsoft Corporation |
| Dell Technologies Inc. |
| HP Inc. |
| Flexera |
| BMC Software, Inc. |
| SolarWinds Worldwide, LLC |
| Ivanti, Inc. |
| Others |
Value Chain & Pricing Dynamics
FCC equipment authorization rules gate both vendor qualification and price differentiation in hardware asset management platforms, separating FedRAMP-authorized providers from uncertified competitors while compressing margins for mid-market SaaS providers lacking federal channel access.
Pricing Analysis
Configured-to-order pricing for enterprise-grade platforms commands substantial premiums over standard SaaS tiers, with ISO 55000 audit-ready modules and NIST SP 800-53 compliance documentation driving differentiation. Subscription models dominate cloud-native deployments, while perpetual-license residuals persist in air-gapped federal installations. Cost compression intensifies in the mid-market as managed service providers bundle asset tracking into broader IT outsourcing contracts, rendering standalone software purchases uneconomical. Government agencies exhibit lowest price sensitivity due to mandate-driven procurement, while India's PLI-subsidized contract manufacturers represent the most price-conscious buyer segment.
Supply Chain Analysis
Just-in-time inventory strategies dominate cloud-native platform delivery, while strategic stockpiling characterizes on-premises appliance procurement for defense and critical infrastructure buyers. Semiconductor fabrication concentrates in Taiwan and South Korea, with advanced chipsets for discovery hardware drawing from TSMC and Samsung foundries. Server-grade processors, RFID tags, and BLE beacon components constitute critical input dependencies. Single-source vulnerability in advanced node semiconductors exposes procurement timelines to geopolitical disruption. Distribution runs through direct enterprise sales forces for large accounts and hyperscaler marketplaces for mid-market cloud adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware asset management market fragmentation creates niche opportunities as ISO 55000 alignment splits demand between audit-intensive German automotive suppliers and compliance-light Indian contract manufacturers.
For Market Incumbents: Consolidate API-first platform capabilities through targeted acquisition of predictive analytics specialists, defending against cloud-native entrants encroaching on ServiceNow's workflow automation stronghold. Deepen vertical integration into managed service delivery to capture recurring revenue from ITAM expertise-scarce mid-market buyers, while hardening FedRAMP authorization moats against emerging competitors. For New Entrants and Emerging Players: Mid-market SaaS gaps in India's PLI manufacturing corridors offer white-space entry points, with Tamil Nadu and Karnataka contract manufacturers lacking localized asset tracking support. Target consumption-based financing models for UK and Australian server infrastructure buyers seeking depreciation risk transfer. Lead with rapid-deployment cloud-native positioning against legacy CMDB integration debt in federal agencies. For Investors and Strategic Acquirers: EU CSRD sustainability disclosure mandates reshape the acquisition landscape toward platforms with embedded carbon footprint analytics and circular economy compliance modules. Long-term viability favors vendors bridging ITAM-SRE skill convergence for cloud-hybrid estates. Monitor BIS certification enforcement intensity in Indian government procurement as inflection signal for localization premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architectures absorb monolithic suite functionality from ServiceNow and BMC instances. |
| Acquisition of Specialist Firm | Predictive refresh analytics vendors enhance TCO optimization for German automotive suppliers. |
| Geographic Expansion | India PLI corridor localization captures OEM contract manufacturer governance demand. |
| Strategic Partnership | Hyperscaler marketplace listings accelerate mid-market SaaS adoption in UK financial services. |
| Product Launch | BLE beacon solutions for field services complement passive RFID data center offerings. |
Study Parameters
Cross-validation between primary interviews with IT procurement officers, CMDB administrators, and managed service provider executives and secondary validation through SEC filings, hyperscaler capex disclosures, and Gartner ITAM quadrant assessments anchors the qualitative findings. Bottom-up and top-down triangulation reconciles vendor-reported subscription metrics with enterprise technology spend surveys across the United States, Germany, United Kingdom, India, and Japan.
Sensitivity analysis frames the analytical approach across the projection horizon, with segmentation dimensions spanning deployment model, organization size, equipment category, vertical industry, and regional regulatory cluster. CAGRs derive from logistic adoption curves fitted to cloud-native platform penetration rates and managed service contract velocity. Industry-specific inputs incorporate ISO 55000 audit readiness timelines and EU CSRD disclosure implementation schedules.
Underlying assumptions cover sustained hybrid workforce permanence and semiconductor supply normalization, with deviation risk concentrated in Taiwan Strait geopolitical disruption and accelerated circular economy mandate enforcement. Revision becomes warranted when FedRAMP authorization backlogs or BIS certification delays cross thresholds that materially alter vendor competitive positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Asset Management
Canada Pension Fund Market
Asset Management
Fund Management Software Market
Asset Management
Global Investment Management Software Market
Asset Management
Equity Management Tool Market
Asset Management
Fixed Income Asset Management Market
Asset Management
US Healthcare Assets Management Market
Asset Management
Healthcare Asset Management Market
Asset Management
Global Remote Asset Management Market
Asset Management
India Asset Management Market
Asset Management
Asset Management System Market
Asset Management
Europe Asset Management Market
Asset Management
Mutual Fund Assets Market
Asset Management
Japan Asset Management Market
Asset Management
Pension Fund Management Software Market
Asset Management
Global AI in Asset Management Market
Asset Management
Asset and Wealth Management Market