
 India Asset Management Market | 2026-2036
India Asset Management Market Size, Share, and Industry Trends Forecast 2026-2036
India Asset Management Market Foresight
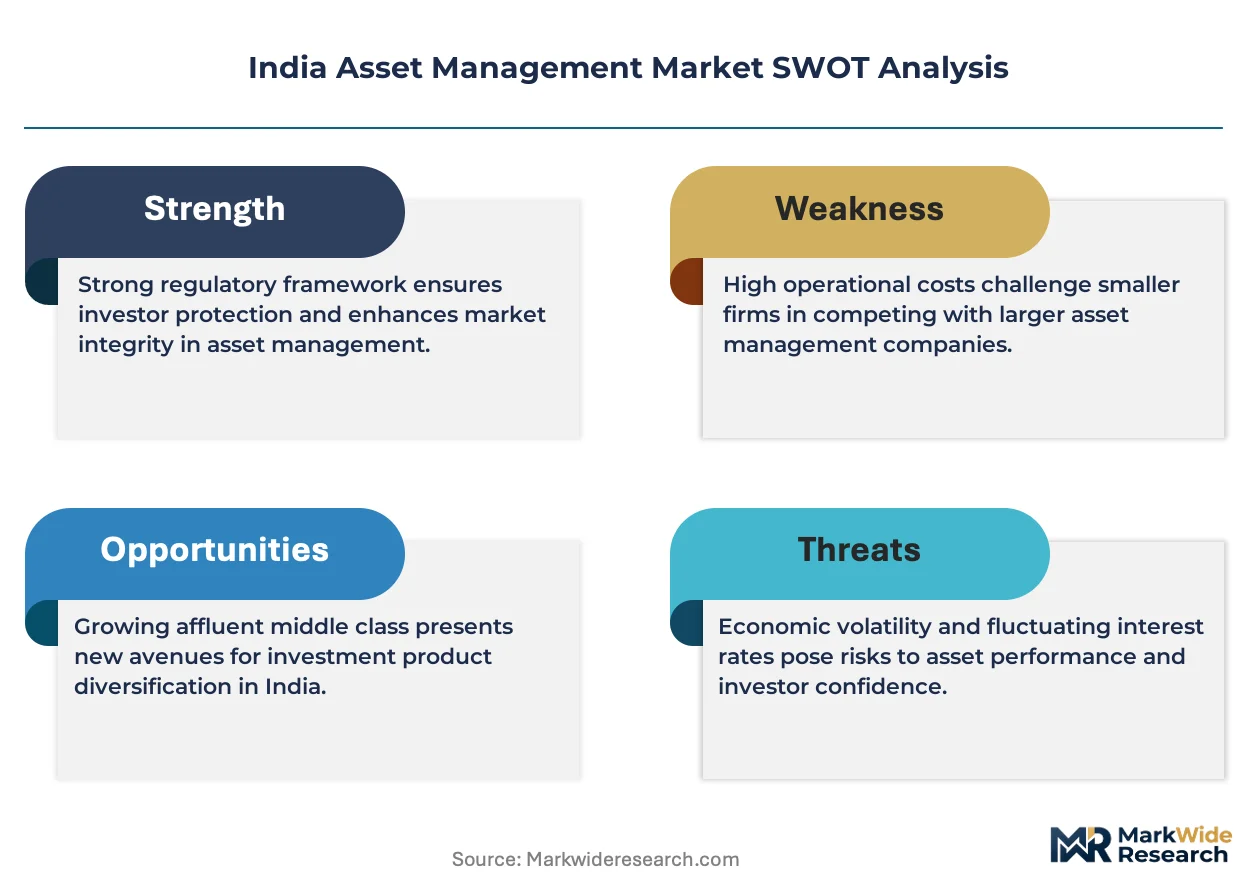
Retail investor participation through systematic investment plans is broadening across India's smaller cities, fragmenting what was once an HNI-concentrated buyer base. SBI Funds Management leverages its sprawling bank branch network to anchor rural penetration. ICICI Prudential Asset Management competes through hybrid fund specialization that balances equity exposure with downside protection. HDFC Asset Management sustains dominant positioning in equity-oriented schemes through sustained distributor relationships and brand recall in metropolitan clusters.
Asset management denotes the professional oversight of investment portfolios comprising equities, debt instruments, hybrid securities, and liquid instruments, governed by mandate-specific risk-return parameters and regulatory investment limits. The practice pools capital from dispersed investors to achieve diversification, liquidity, and economies of scale unattainable through direct security ownership. Equity funds command the largest share of assets under management, though passive management strategies gain structural traction as fee compression intensifies across active mandates. Exchange-traded funds represent the fastest-expanding fund structure, driven by institutional appetite for transparent, low-cost market exposure.
SEBI mandates riskometer classifications and scheme categorization norms that standardize product comparability and curb mis-selling across distributor networks. RBI's monetary policy stance and interest rate trajectory directly influence debt fund flows and duration positioning. The PLI scheme for financial services and SEBI's stewardship code together elevate governance standards while channeling domestic savings into regulated investment vehicles. Stakeholders must monitor how digital onboarding platforms and direct plan adoption reshape distributor economics and fund house profitability models.
Market Dynamics
SEBI's riskometer classification mandate is compressing product differentiation across fund houses while simultaneously elevating transparency standards that retail investors now demand as baseline.
Growth Catalysts
- PLI scheme for financial services:Government production-linked incentives channel domestic savings into regulated investment vehicles through tax-advantaged structures.
- Systematic investment plan automation:Digital SIP onboarding through UPI rails and e-KYC protocols reduces friction for first-time equity investors in tier-two and tier-three cities.
- RBI's accommodative rate cycle:Lower benchmark rates compress debt fund yields, rotating household allocations toward hybrid and equity-oriented schemes.
Market Restraints
- Distributor commission compression:SEBI's total expense ratio caps squeeze front-end loads, forcing fund houses to absorb customer acquisition costs.
- Concentrated AUM geography:Maharashtra and Gujarat account for disproportionate asset flows, leaving northern and eastern states underpenetrated and revenue lumpy.
- Passive fee erosion:Exchange-traded funds and index schemes command sub-20 basis point expense ratios, cannibalizing active equity mandate profitability.
Strategic Opportunities
- Bharat Bond ETF expansion:Retail access to corporate debt through exchange-traded structures opens fixed-income participation beyond institutional investors.
- ESG integration tailwinds:SEBI's stewardship code and mandatory ESG disclosures for top-listed companies create demand for sustainability-themed fund products.
- Video KYC and vernacular interfaces:Regulator-approved remote onboarding in regional languages penetrates investor segments previously excluded by physical branch requirements.
Industry Challenges
- Quantitative research talent scarcity:Factor-based and smart-beta product development requires data science capabilities that traditional fund managers lack.
- Legacy core banking integration:Bank-sponsored asset managers face multi-year system migrations to unify mutual fund operations with deposit and lending platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Asset Management Market |
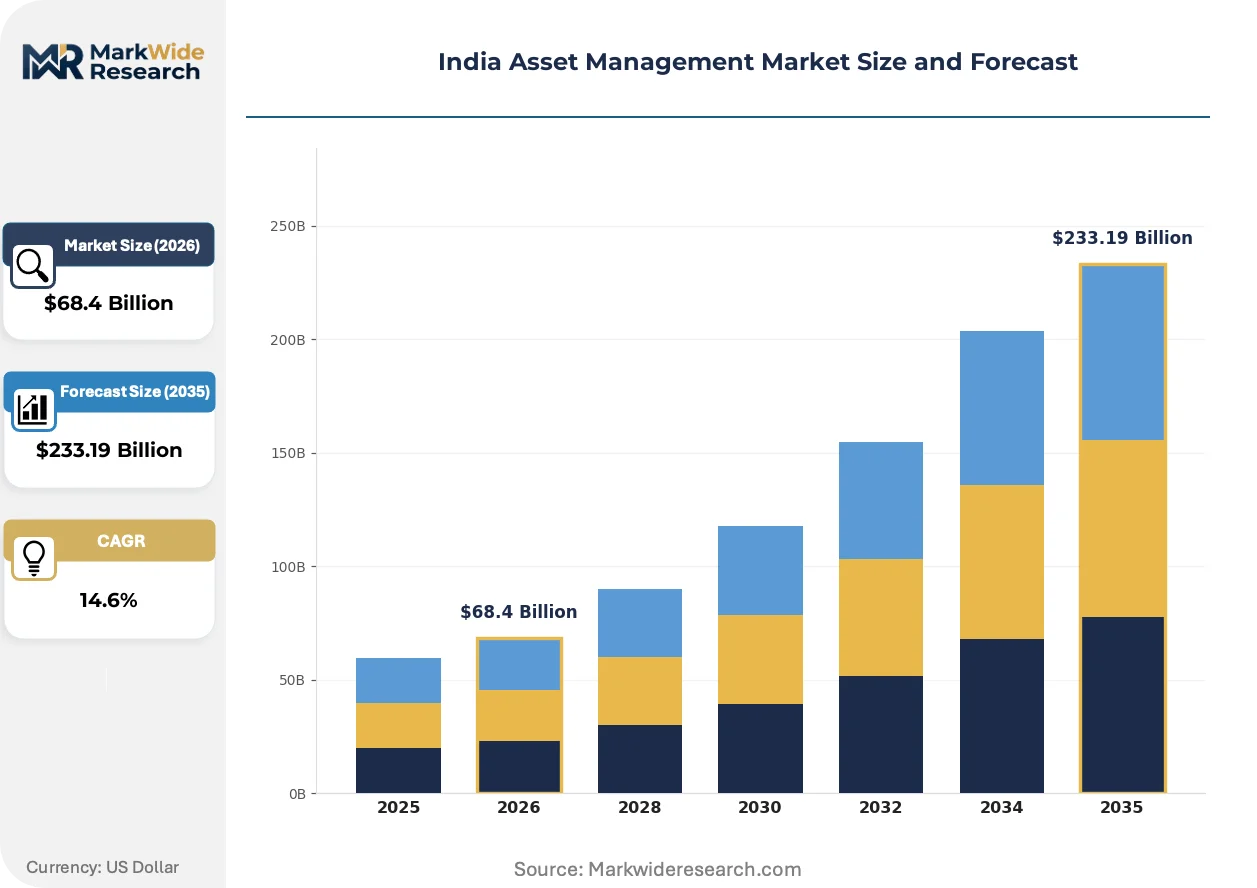
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $233.19 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Equity Funds, Debt Funds, Hybrid Funds, Liquid Funds Client Type: Retail Investors, Institutional Investors, HNIs, Corporates Investment Strategy: Active Management, Passive Management, Target Date, Value Investing Fund Structure: Open-Ended Funds, Closed-Ended Funds, Interval Funds, Exchange-Traded Funds |
| Companies Covered | SBI Funds Management, ICICI Prudential Asset Management, HDFC Asset Management, Nippon India AMC, Axis AMC, UTI AMC, Kotak Mahindra AMC, Aditya Birla Sun Life AMC, Mirae Asset Mutual Fund, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Asset Management Market Shifts & Advancements
Digital distribution infrastructure is fragmenting investor acquisition channels while compressing cost structures that once protected incumbent fund house margins.
Blockchain-based fund registry infrastructure is decentralizing transfer agency functions that historically concentrated with a handful of private record-keepers. Mid-sized asset managers in Gujarat and Tamil Nadu are piloting distributed ledger reconciliation for unit holder registries. This compression eliminates intermediary fees and accelerates settlement cycles from T+3 to T+1.
SEBI's enhanced disclosure norms for risk classification and scheme categorization are standardizing product comparability across distributor networks. Fund houses must now publish granular portfolio holdings monthly rather than quarterly. Active equity schemes face particular pressure as investors migrate toward passively managed alternatives with transparent, rules-based construction.
Direct plan adoption through app-based platforms is disintermediating traditional distributor relationships that dominated mutual fund sales in metropolitan clusters. Urban investors in Mumbai and Bangalore increasingly bypass commission-loaded regular plans for zero-distribution-fee alternatives. This channel shift forces fund houses to build proprietary digital engagement capabilities or cede customer relationships to fintech aggregators.
India Asset Management Market Segmentation
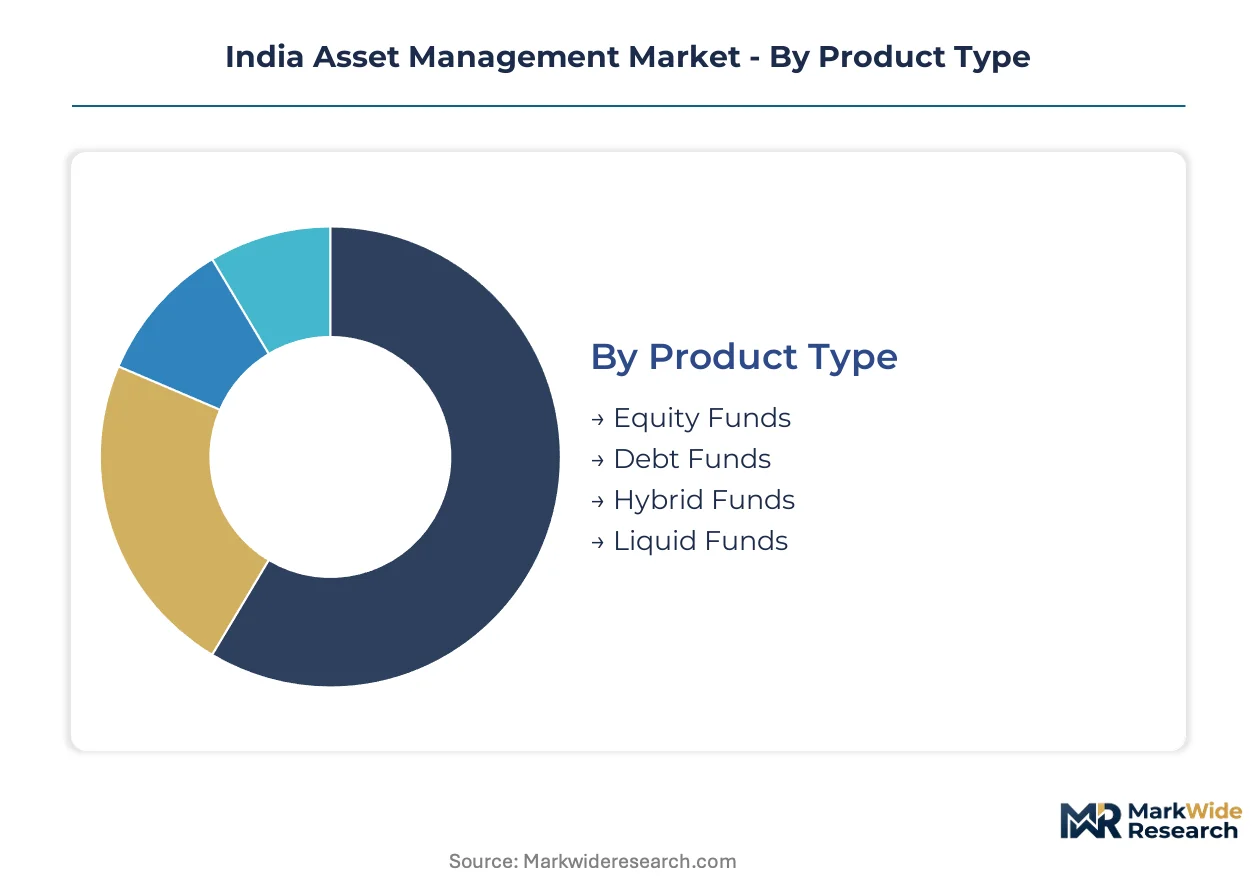
Segmentation in India's asset management market reveals how investor sophistication, risk appetite, and distribution access fragment product demand. Fund houses calibrate fee structures, liquidity provisions, and disclosure intensity differently across each slice.
Product Type:
Investor risk tolerance and return horizon separate buyers across this dimension.
- Equity Funds:These schemes deploy capital predominantly into listed equities across market capitalizations, with SEBI-mandated sectoral caps limiting concentration. Maharashtra and Gujarat households channel systematic investment flows into large-cap oriented offerings, though mid-cap and small-cap variants attract younger demographics seeking inflation-beating returns. SEBI's riskometer classification forces granular disclosure of portfolio volatility.
- Debt Funds:Fixed-income portfolios hold government securities, corporate bonds, and money market instruments with duration-matched maturity profiles. RBI's interest rate trajectory directly shapes flows—accommodative cycles compress yields and rotate allocations toward credit risk funds, while tightening prompts gilt fund accumulation. Institutional treasuries in Mumbai dominate corporate bond fund subscriptions.
- Hybrid Funds:Blended equity-debt allocations balance growth participation with downside containment, appealing to first-time equity investors in tier-two cities.
- Liquid Funds:Ultra-short duration instruments serve working capital parking needs for corporates and high-net-worth individuals requiring T+1 liquidity.
Equity funds lead volumes today; hybrid funds are gaining share fastest.
Client Type:
Wealth concentration and decision-making autonomy distinguish participants here.
- Retail Investors:Individual subscribers deploying household savings through systematic investment plans or lump-sum deployments, typically below threshold limits for personalized advisory. Digital onboarding via UPI-automated SIPs penetrates tier-three cities in Tamil Nadu and Karnataka, with vernacular interfaces reducing friction. SEBI's investor charter mandates grievance redressal timelines protecting this segment.
- Institutional Investors:Pension funds, insurance companies, and provident fund trusts deploying large-ticket allocations with mandate-specific constraints. EPFO's equity expansion and NPS subscriber growth channel incremental flows into index-tracking and large-cap active strategies.
- HNIs:Affluent individuals with personalized portfolio management service mandates and direct plan access through private banking channels.
- Corporates:Treasury departments managing surplus liquidity through overnight and liquid fund structures with T+0 redemption requirements.
Retail investors dominate subscription volumes; institutional participation is expanding most quickly.
Investment Strategy:
Fee sensitivity and belief in manager alpha separate adopters across this category.
- Active Management:Fund managers exercise security selection and timing discretion to outperform benchmark indices, charging expense ratios typically exceeding one percent. Distributor commissions and research costs embed into fee structures under SEBI's total expense ratio caps. Performance pressure intensifies as passive alternatives demonstrate competitive net returns.
- Passive Management:Rules-based replication of indices—Nifty 50, Sensex, or sectoral benchmarks—delivers market exposure at sub-20 basis point costs. Institutional pension mandates and direct plan adoption through fintech platforms accelerate penetration.
- Target Date:Glide-path allocations automatically shift equity exposure downward as a predetermined retirement date approaches, popular among NPS subscribers.
- Value Investing:Contrarian security selection targeting undervalued equities with margin-of-safety disciplines, attracting patient capital from experienced retail participants.
Active strategies retain majority assets; passive management shows the steepest expansion trajectory.
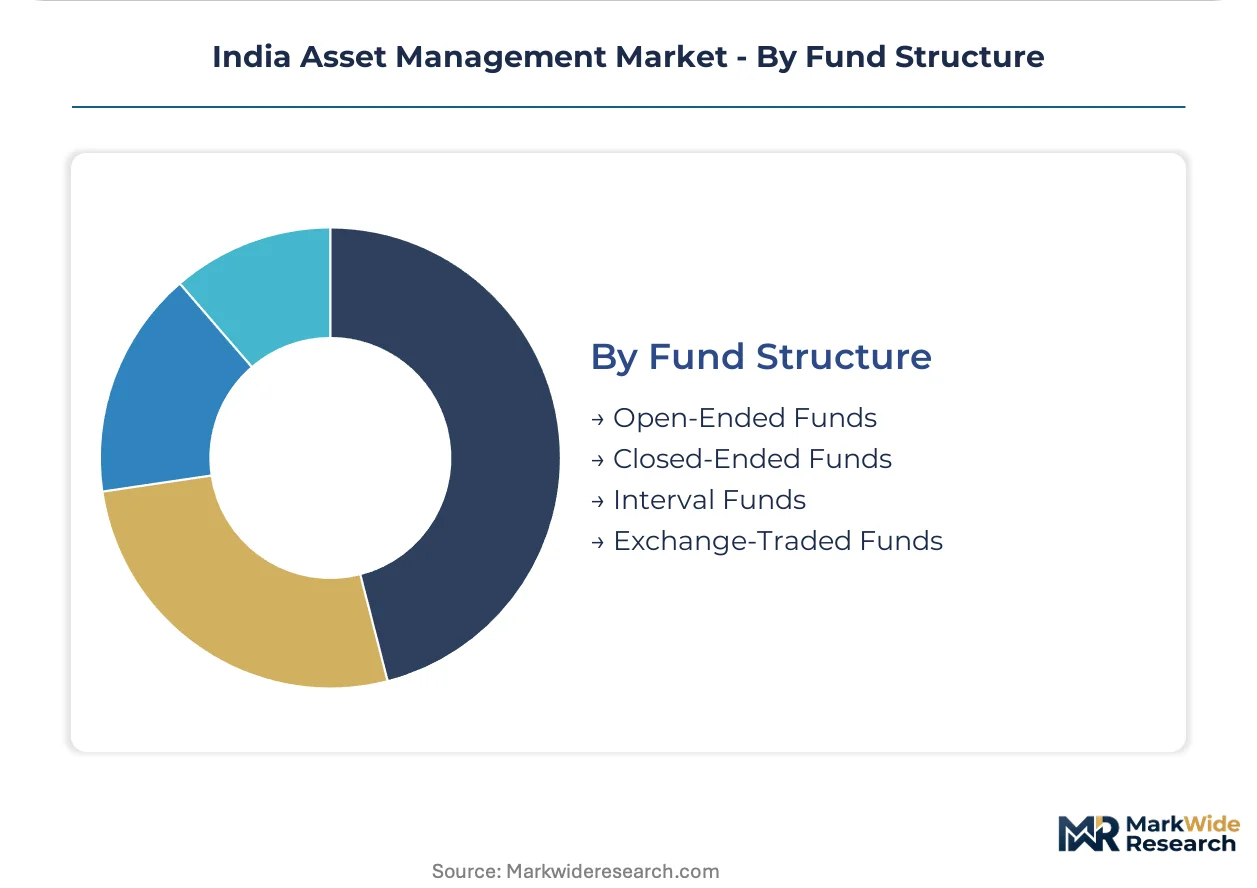
Fund Structure:
Liquidity preferences and trading flexibility determine structural choice.
- Open-Ended Funds:Continuous issuance and redemption at net asset values provide daily liquidity, forming the dominant structure for retail and institutional flows. SEBI mandates minimum holding disclosures and exit load transparency. Most equity and debt schemes operate through this format.
- Exchange-Traded Funds:Exchange-traded units with real-time price discovery and institutional creation-redemption mechanisms. Bharat Bond ETFs and equity index trackers attract pension fund allocations and arbitrageurs seeking low-cost, transparent exposure.
- Closed-Ended Funds:Fixed unit issuance with tenure-defined maturity, typically employed for illiquid credit strategies or thematic equity plays.
- Interval Funds:Periodic repurchase windows—monthly or quarterly—balance liquidity provision with strategy stability for less liquid underlying assets.
Open-ended funds anchor industry assets; exchange-traded funds are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's asset management penetration varies sharply across states, with western and southern regions outpacing northern and eastern counterparts in mutual fund adoption and SIP registrations.
Maharashtra
Mumbai anchors the nation's largest AUM concentration, with institutional treasuries and HNI wealth driving flows into equity and hybrid schemes. SEBI's regional office enforces stringent disclosure compliance across fund houses headquartered in the state. Pune's technology corridor channels salaried professionals into systematic investment plans through digital onboarding platforms.
Gujarat
Ahmedabad and Surat households display elevated risk appetite for equity-oriented products compared to national averages. The state's investor education initiatives, coordinated with SEBI's regional outreach, accelerate financial literacy in trading communities. Gandhinagar's emerging fintech cluster experiments with blockchain-based fund registry pilots for unit holder reconciliation.
Karnataka
Bengaluru's salaried technology workforce dominates direct plan adoption through app-based platforms, bypassing traditional distributor channels. RBI's monetary policy transmission affects debt fund allocations from corporate treasuries based in the city. Mysuru and Mangaluru are registering accelerated SIP growth as vernacular interfaces penetrate tier-two urban centers.
Tamil Nadu
Chennai's manufacturing belt channels provident fund corpus into pension-oriented hybrid schemes through employer-sponsored programs. SEBI's investor charter mandates streamline grievance redressal for retail subscribers in Coimbatore's industrial clusters. Tier-three cities in the state show fastest-growing SIP registration rates via UPI-automated onboarding infrastructure.
Delhi-NCR
The National Capital Region concentrates institutional mandates from insurance companies and pension funds seeking large-cap index exposure. Regulatory coordination between SEBI and RBI shapes product availability for banking channel distribution across Noida and Gurugram. Faridabad's SME sector drives working capital deployment into liquid and overnight fund structures.
India Asset Management Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across India's asset management landscape. Bank-sponsored entities leverage sprawling branch networks for customer acquisition, while independent fund houses compete through investment performance and niche product specialization. Three archetypes dominate: public sector bank affiliates with distribution depth, private bank-backed operators with digital integration, and independent asset managers with thematic expertise. Competitive intensity manifests through direct plan pricing wars and proprietary technology platform development.
Within the public sector bank affiliate tier, SBI Funds Management anchors rural penetration through its parent institution's branch infrastructure. ICICI Prudential Asset Management and HDFC Asset Management occupy positions among private bank-backed operators competing for metropolitan market share. These entities exemplify how sponsor banking relationships shape distribution economics and customer acquisition cost structures across tier-one and tier-two city networks.
| Leading Market Players |
|---|
| SBI Funds Management |
| ICICI Prudential Asset Management |
| HDFC Asset Management |
| Nippon India AMC |
| Axis AMC |
| UTI AMC |
| Kotak Mahindra AMC |
| Aditya Birla Sun Life AMC |
| Mirae Asset Mutual Fund |
| Others |
Supply & Pricing Matrix
Bank-sponsored asset managers with sprawling branch networks anchor supply-side concentration while compressing fee structures that independent fund houses struggle to match. SEBI's total expense ratio caps transmit pricing discipline through distributor commissions, forcing product-level profitability trade-offs that favor scale operators.
Pricing Analysis
Capacity additions in direct plan platforms are reshaping price floors across India's asset management landscape. Three-tier pricing structure across premium, standard, and economy levels stratifies by distributor relationship depth and advisory bundling. Direct plan adoption through app-based interfaces intensifies cost compression in retail segments, while institutional mandates retain pricing power through customized portfolio management services. Retail investors in tier-two cities demonstrate highest price sensitivity, migrating toward zero-commission alternatives, whereas HNI segments absorb premium advisory fees for personalized mandates.
Supply Chain Analysis
Research and analytics talent supply rests on Mumbai and Bengaluru financial services clusters, with quantitative capabilities concentrated among IIT and IIM graduate pipelines. Custodial services draw from domestic banks and foreign institutional arrangements, while transfer agency functions feed from a handful of specialized record-keeping firms. Single-source vulnerability in legacy core banking integration creates operational risk for bank-sponsored managers modernizing mutual fund operations. Distribution runs through bank branch networks, independent financial advisors, and direct digital platforms in roughly equal measure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's asset management market functions as a geographic-arbitrage play, with SEBI's regulatory framework offering disclosure standardization that contrasts with fragmented compliance costs across Southeast Asian peer markets.
For Market Incumbents: Deepen proprietary digital engagement capabilities to retain customer relationships against fintech aggregator encroachment. Build captive distribution through vernacular-language onboarding infrastructure in Tamil Nadu and Karnataka tier-three cities. Counter passive fund fee erosion by developing factor-based and smart-beta products requiring specialized quantitative research talent.
For New Entrants and Emerging Players: Launch via video KYC-enabled direct platforms targeting first-time equity investors in underpenetrated eastern and northern states. Exploit white-space in ESG-themed fund products mandated by SEBI's stewardship code disclosures. Prioritize hybrid fund specialization that balances equity exposure with downside protection for risk-averse retail segments.
For Investors and Strategic Acquirers: Valuations sit cheapest among independent asset managers lacking bank sponsor distribution depth. Long-term viability hinges on digital platform ownership and direct plan subscriber bases rather than legacy distributor relationships. Monitor Bharat Bond ETF expansion rates as inflection indicator for retail fixed-income market penetration.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct Plan Platform Development | Proprietary digital onboarding reduces distributor dependency and captures full expense ratio economics. |
| Vernacular Interface Deployment | Regional language penetration unlocks tier-three city SIP registrations through UPI-automated infrastructure. |
| ESG Product Line Expansion | SEBI's mandatory ESG disclosures for top-listed companies create demand for sustainability-themed fund structures. |
| Blockchain Registry Pilot | Distributed ledger reconciliation compresses transfer agency costs and accelerates settlement cycles toward T+1. |
| Quantitative Research Talent Acquisition | Data science capabilities enable factor-based and smart-beta product development against passive fund competition. |
Research Methodology
Bottom-up investor segmentation modeling reconciled against top-down AUM flow tracking forms the analytical core of this study. Primary interviews with fund house chief investment officers, distributor network heads, SEBI regulatory affairs specialists, and retail investor focus groups in Maharashtra and Gujarat combined with secondary validation. SEBI circulars and scheme categorization norms, RBI monetary policy statements, AMFI industry flow data, and fund house regulatory filings anchored source triangulation.
Historical trendline analysis of SIP registration patterns and AUM concentration by state informed projection frameworks across the analysis window. Segmentation dimensions modeled include product type, client archetype, investment strategy, and fund structure, with regional penetration rates as an additional industry-specific dimension. CAGRs derived from compounding observed flow trajectories adjusted for regulatory intervention effects and interest rate cycle positioning.
Several conditions sit outside the modeled scope, including unannounced SEBI regulatory amendments, extreme RBI monetary policy discontinuities, and systemic financial market dislocations. Forecasts reflect assumptions about continued UPI infrastructure expansion and stable tax treatment of equity-linked savings schemes. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Asset Management
US Pension Funds Market
Asset Management
Asset Management System Market
Asset Management
Mutual Fund Assets Market
Asset Management
Global AI in Asset Management Market
Asset Management
Asia-Pacific Utilities Asset Management Market
Asset Management
Fund Management Software Market
Asset Management
UK Asset Management Market
Asset Management
US Healthcare Assets Management Market
Asset Management
Asset Optimization Solutions Market
Asset Management
APAC Mutual Fund Market
Asset Management
Equity Management Tool Market
Asset Management
Global Infrastructure Asset Management Market
Asset Management
US Asset Management Market
Asset Management
Hardware Asset Management Market
Asset Management
Global Remote Asset Management Market
Asset Management
Asset and Wealth Management Market