
 China Mutual Funds Market | 2026-2036
China Mutual Funds Market Size, Share, and Industry Trends Forecast 2026-2036
China Mutual Funds Market Outlook
The capability gap between bank-distributed giants and digitally native specialists is collapsing as mobile penetration equalizes customer acquisition economics. Harvest Fund Management leverages its quasi-sovereign fund lineage to sustain institutional mandate dominance. E Fund Management anchors retail flows through proprietary app ecosystems with direct subscription functionality. GF Fund Management competes via quantitative product specialization that differentiates its passive lineup from state-bank shelf offerings.
China mutual funds represent pooled investment vehicles regulated under CSRC supervision, comprising portfolios of securities, derivatives, or cash instruments structured as contractual arrangements rather than corporate entities, with NAV calculated daily and redemption terms varying by open-end or closed-end charter. Their commercial purpose channels household savings and institutional capital into diversified exposure across equity, fixed-income, and money-market instruments while outsourcing security selection to licensed managers. Equity funds and mixed funds command the largest AUM pools, though money market funds retain structural importance as liquidity repositories for retail investors migrating from deposit products. Exchange-traded funds within the fund structure dimension are capturing fastest flow growth, as institutional investors seek intraday liquidity and transparent tracking cost structures that active managers struggle to match on fee competitiveness.
CSRC licensing requirements, AMAC registration protocols, and PBOC anti-money-laundering directives collectively shape product approval timelines, distribution channel eligibility, and investor suitability frameworks that constrain market access for unqualified managers. SAMR consumer protection standards and the CSRC fund distribution suitability rules further segment channel economics by imposing compliance cost burdens that favor scale players over boutique entrants. Stakeholders must monitor whether CSRC opens mutual fund passport schemes linking Hong Kong and mainland China, as this would restructure competitive boundaries for cross-border product registration and custody arrangements.
Market Dynamics
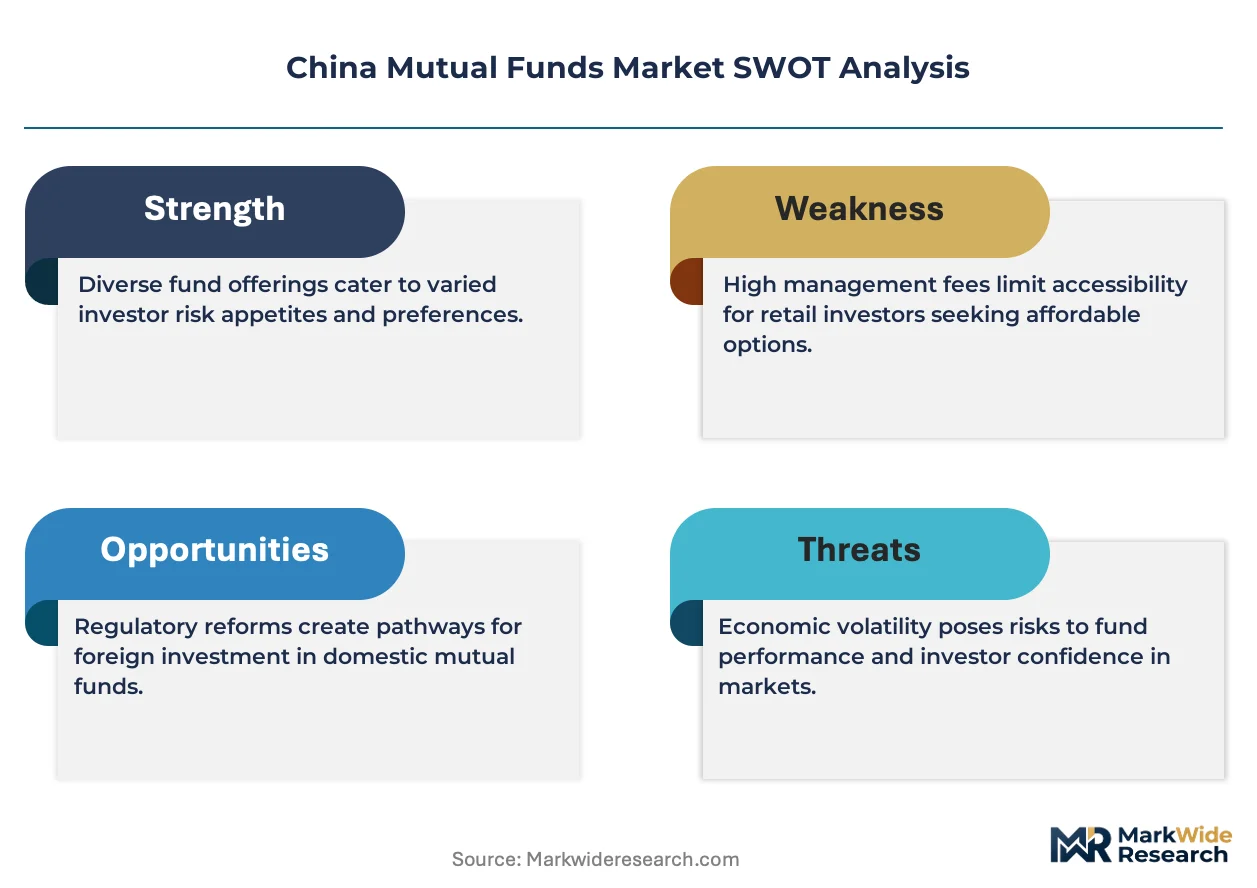
Retail capital migration from property and deposits into fund products is compressing distribution channel hierarchies and forcing fee compression across active and passive product lines simultaneously.
Growth Catalysts
- CSRC disclosure mandates:Standardized reporting frameworks reduce information asymmetry between fund managers and retail subscribers, accelerating informed capital allocation decisions.
- Digital distribution platforms:Mobile-first subscription interfaces bypass traditional bank branch gatekeepers, slashing customer acquisition costs for emerging asset managers.
- First-tier city household savings:Concentrated wealth formation in Shanghai, Beijing, and Shenzhen generates recurring inflows into equity-oriented mixed fund categories.
Market Restraints
- AMAC registration timelines:Product approval protocols create six-to-twelve month launch delays that freeze capital deployment strategies during market windows.
- State-bank distribution concentration:ICBC, CCB, and BOC control shelf access for seventy percent of retail flows, extracting margin-destructive revenue-sharing terms.
- Money market fund yield compression:PBOC rate policy shifts erode the deposit-substitute value proposition that originally attracted retail migration.
Strategic Opportunities
- Quantitative product specialization:Factor-based and smart-beta architectures offer fee-competitive alternatives to saturated active equity offerings.
- Hong Kong mutual fund passport schemes:Cross-border product registration linkages would unlock southbound capital flows for mainland-domiciled managers.
- ETF ecosystem expansion:Intraday liquidity and transparent tracking cost structures attract institutional mandates from pension and insurance allocators.
Industry Challenges
- Quantitative research talent scarcity:Systematic strategy development requires PhD-level statistical expertise that commands compensation premiums beyond traditional fundamental research roles.
- Legacy core banking integration:Fund order management systems must interface with state-bank custody infrastructure that operates on proprietary protocol standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Mutual Funds Market |
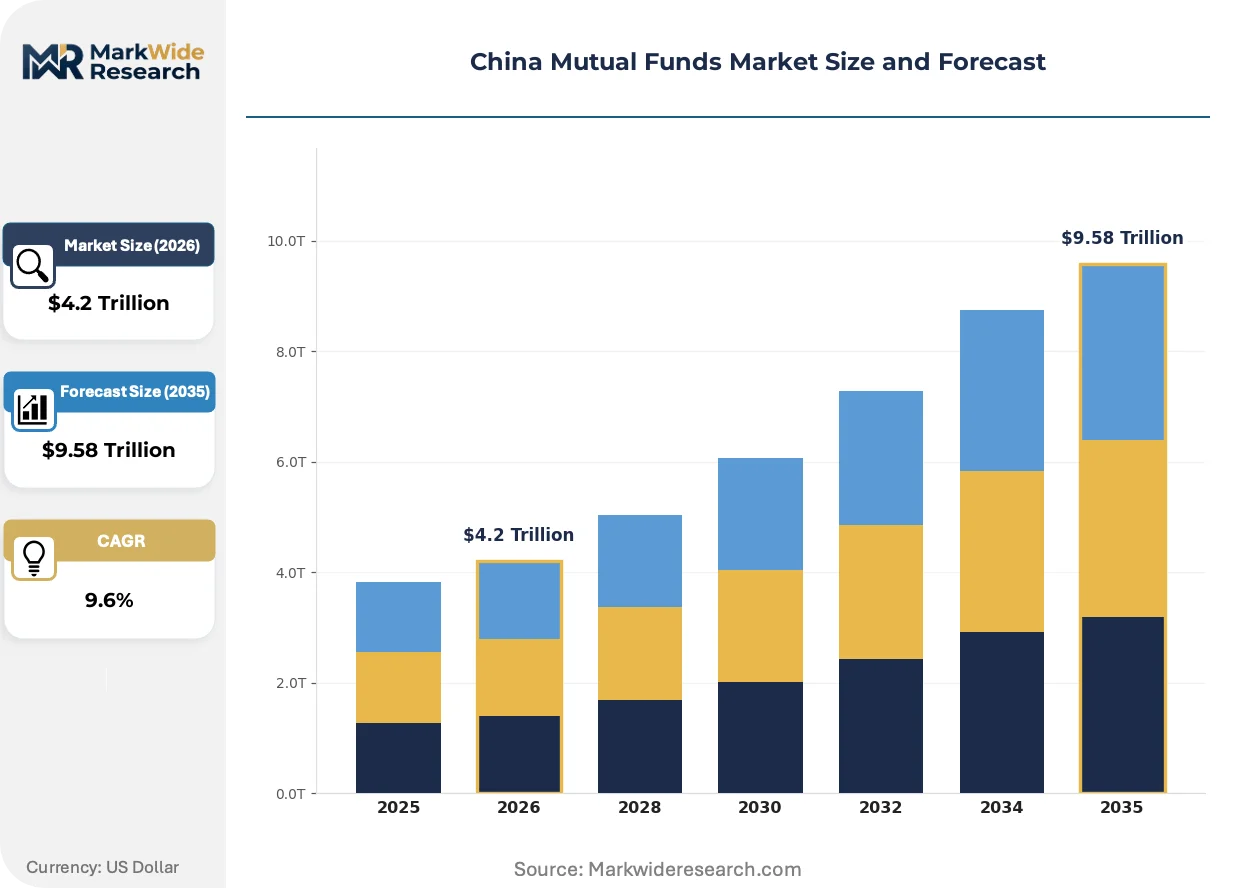
| Market Size in 2026 | $4.2 Trillion |
| Market Size in 2035 | $9.58 Trillion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Asset Class: Equity Funds, Bond Funds, Money Market Funds, Mixed Funds Investor Type: Retail Investors, Institutional Investors, Corporations, High Net Worth Individuals Fund Structure: Open-End Funds, Closed-End Funds, Unit Trusts, Exchange-Traded Funds Investment Strategy: Active Management, Passive Management, Index Tracking, Value Investing |
| Companies Covered | Harvest Fund Management, Southern Asset Management, E Fund Management, Huaxia Fund Management, GF Fund Management, China Asset Management Co. (ChinaAMC), Bosera Asset Management, Penghua Fund Management, ICBC Credit Suisse Asset Management, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Mutual Funds Market Strategic Shifts
Algorithmic distribution interfaces and regulatory technology deployment are compressing the traditional value chain between product construction and end-investor access.
Smart order routing technology is bifurcating execution pathways between institutional block trades and retail fractional subscriptions. Large allocators demand direct market access with minimal slippage, while mass-market platforms optimize for psychological pricing and automated rebalancing triggers. This technological divergence is forcing custody providers to maintain dual infrastructure stacks with incompatible cost structures.
CSRC fund distribution suitability rules are mandating risk-profiling algorithms that match product complexity to investor sophistication tiers. The industrial consequence is a segmentation of the retail base into qualified and non-qualified subscriber pools with differential access to alternative strategies. Private banking channels in Shenzhen and Guangzhou are deploying enhanced due diligence protocols to capture the qualified segment.
Direct subscription functionality through proprietary mobile ecosystems is displacing branch-mediated sales for household segments under age forty. The disintermediated channel captures subscription flows that previously required physical document execution and manual risk disclosure acknowledgment. Shanghai-based fintech platforms are consolidating this behavioral shift through embedded wealth management interfaces within super-app environments.
China Mutual Funds Market Segmentation
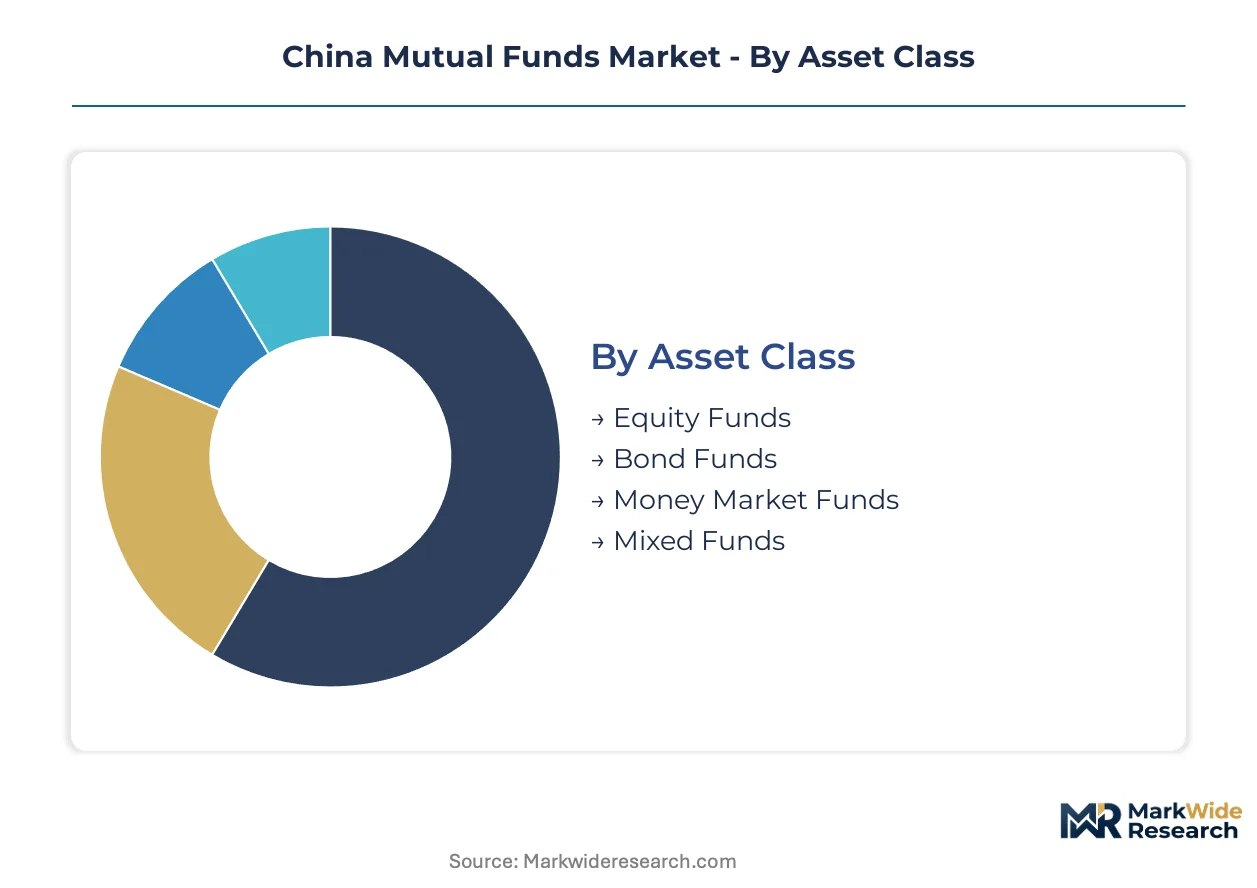
Segmentation in China's mutual funds market reveals how regulatory frameworks and distribution channels allocate capital across product architectures. CSRC licensing tiers and AMAC registration protocols create structural boundaries that shape competitive positioning for managers serving distinct investor pools.
Asset Class:
CSRC disclosure mandates apply differential reporting intensity across asset categories, with equity instruments facing the most stringent NAV transparency requirements.
- Equity Funds:These vehicles hold portfolios comprised primarily of domestically listed A-shares and Hong Kong-listed H-shares, with daily NAV calculation and T+1 settlement cycles. Demand concentrates in first-tier city household savings migrating from property exposure, driven by Shanghai and Beijing retail platforms seeking long-term capital appreciation.
- Mixed Funds:Hybrid architectures blend equity and fixed-income exposure with flexible allocation bands, typically ranging from 30% to 80% equity weighting. Institutional mandates from provincial pension pools favor these structures for liability-matching flexibility, though retail adoption lags due to complexity premiums in fee schedules.
- Bond Funds:Fixed-income portfolios targeting interbank market instruments and exchange-traded government securities.
- Money Market Funds:Short-duration cash management vehicles serving as deposit substitutes for retail liquidity.
Established volume favors Money Market Funds; emerging adoption favors Mixed Funds.
Investor Type:
Distribution economics fragment sharply across customer sophistication tiers, with state-bank channels capturing mass retail while proprietary apps target digitally native segments.
- Retail Investors:Mass-market subscribers accessing products through mobile-first platforms or branch networks, typically deploying household savings in 10,000 to 100,000 RMB increments. Shenzhen and Guangzhou fintech ecosystems are absorbing the fastest flow growth as super-app wealth modules disintermediate traditional distribution.
- Institutional Investors:Pension funds, insurance companies, and sovereign wealth vehicles deploying block capital with customized fee negotiations and direct custody arrangements. These allocators concentrate in Beijing and Shanghai, where CSRC-qualified foreign institutional investor schemes enable cross-border mandate flows.
- Corporations:Treasury management vehicles for non-financial enterprises seeking yield on operating cash reserves.
- High Net Worth Individuals:Qualified investors with 3 million RMB minimum thresholds accessing private fund wrappers.
Fee compression is most severe for Retail Investors; margin stability concentrates with Institutional Investors.
Fund Structure:
Settlement infrastructure and liquidity terms differentiate these architectures, with exchange-traded formats demanding specialized market-making partnerships.
- Open-End Funds:Contractual arrangements with daily subscription and redemption rights, NAV-calculated and settled through CSRC-approved custody banks. These structures dominate retail distribution through Harvest Fund Management and E Fund Management platforms, where continuous liquidity provision matches household savings volatility.
- Exchange-Traded Funds:Exchange-listed vehicles with intraday price discovery and creation-redemption mechanisms for authorized participants. Institutional adoption is climbing the fastest as pension and insurance allocators seek transparent tracking cost structures that active managers struggle to match.
- Closed-End Funds:Fixed-capitalization vehicles with exchange-traded liquidity but no redemption rights.
- Unit Trusts:Trust-law-based structures with distinct beneficiary governance frameworks.
Distribution breadth favors Open-End Funds; institutional mandate capture favors Exchange-Traded Funds.
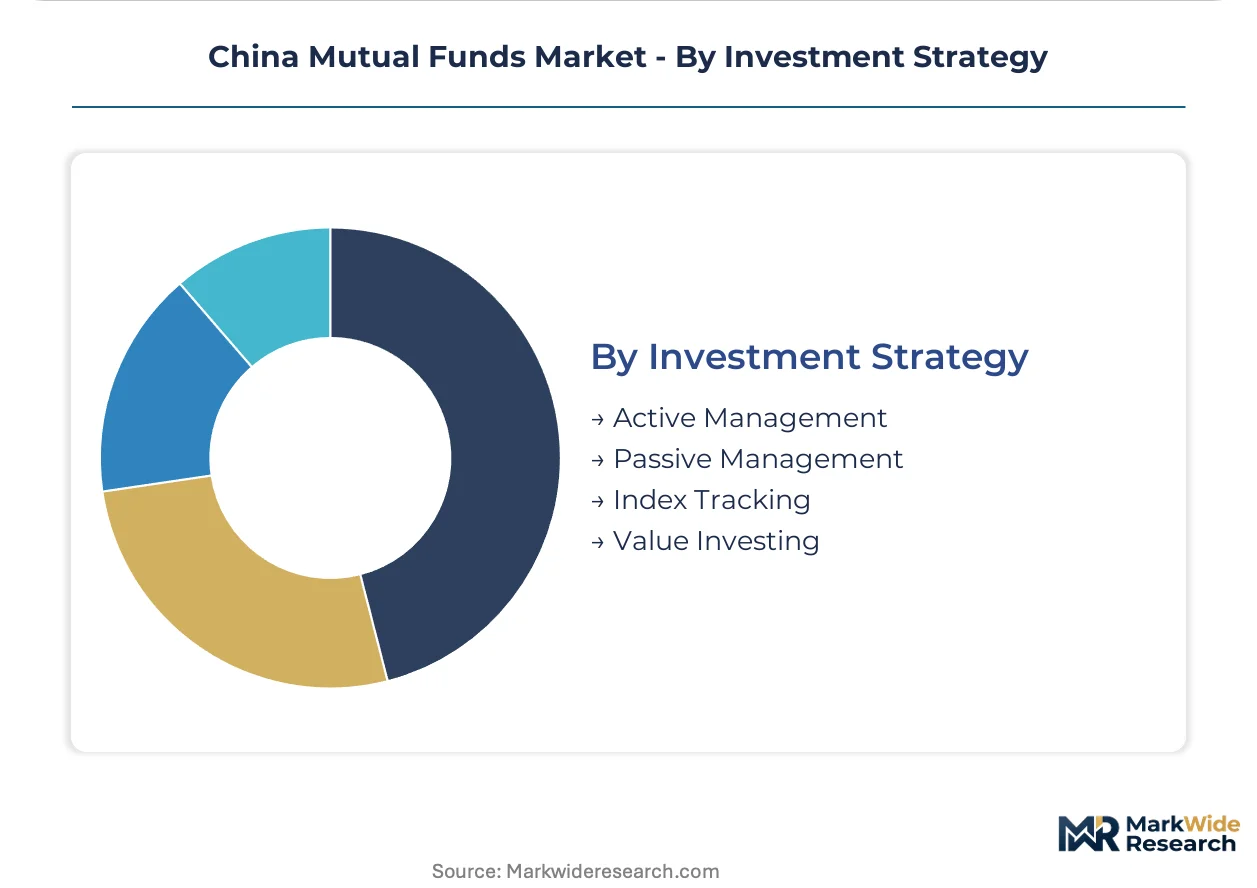
Investment Strategy:
Fee schedules and research cost structures create divergent profitability profiles across active and passive implementation styles.
- Active Management:Discretionary security selection with benchmark-relative performance targets and higher management fee tiers, typically 1.0% to 1.5% annually. First-tier city retail platforms in Beijing sustain demand despite fee pressure, as investors retain confidence in manager alpha generation during volatile A-share regimes.
- Passive Management:Rules-based replication of market-cap or factor-weighted indices with minimal portfolio turnover and compressed fee structures. Quantitative product specialization at GF Fund Management and rival shops is gaining share fastest as smart-beta architectures offer differentiated exposure at cost-competitive price points.
- Index Tracking:Full replication or sampling approaches targeting specific benchmark performance.
- Value Investing:Fundamental strategies targeting discounted cash flow opportunities in state-owned enterprises.
Revenue concentration remains with Active Management; flow velocity favors Passive Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Retail subscription elasticity varies sharply across China's urban hierarchy, with first-tier city investors accepting higher fee loads for active strategies while third-tier city subscribers demand money-market liquidity substitutes at minimal cost.
Beijing-Tianjin-Hebei
Institutional capital concentration and sovereign wealth mandates drive demand for mixed funds with liability-matching flexibility. CSRC-qualified foreign institutional investor schemes enable cross-border mandate flows from Beijing-based allocators. The capital's asset management cluster anchors compliance and custody infrastructure serving northern institutional pools.
Yangtze River Delta
Shanghai household savings migration into equity-oriented products sustains the deepest retail fund penetration nationally. SAMR consumer protection standards and CSRC distribution suitability rules impose algorithmic risk-profiling requirements on local fintech platforms. The city's super-app ecosystems disintermediate traditional bank branches for subscribers under age forty.
Pearl River Delta
Shenzhen and Guangzhou private banking channels deploy enhanced due diligence protocols to capture qualified investor segments above three million RMB thresholds. PBOC anti-money-laundering directives shape subscription documentation workflows for cross-border capital movements. The region's fintech infrastructure leads mobile-first distribution architecture development.
Sichuan-Chongqing
Western wealth formation concentrates in Chengdu's emerging middle-class households seeking deposit alternatives through bank-distributed fund products. AMAC registration timelines create product availability lags that freeze deployment during local market windows. The municipality's custody partnerships with state banks dominate shelf access for retail flows.
Shandong Peninsula
Corporate treasury management demand from manufacturing enterprises generates institutional inflows into short-duration bond funds. Dual carbon goals under MEE supervision redirect capital toward green bond fund wrappers. Qingdao's port-related conglomerates deploy operating cash reserves through qualified money market vehicles.
China Mutual Funds Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with quasi-sovereign fund lineages and bank-affiliated distribution networks commanding shelf access while quantitative boutiques carve factor-based niches. The top tier consolidates around institutional mandate dominance and proprietary mobile ecosystems. Three archetypes define positioning: state-linked giants with custody integration, digitally native specialists with direct subscription platforms, and quantitative shops with smart-beta architectures. Competitive moves concentrate on ETF ecosystem expansion and cross-border product registration readiness for mutual fund passport schemes.
Within the state-linked tier, Harvest Fund Management exemplifies quasi-sovereign lineage sustaining institutional dominance, while E Fund Management anchors retail flow capture through proprietary app ecosystems. GF Fund Management occupies the quantitative specialization vector, differentiating passive lineups from state-bank shelf offerings. These three represent distinct strategic archetypes rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Harvest Fund Management |
| Southern Asset Management |
| E Fund Management |
| Huaxia Fund Management |
| GF Fund Management |
| China Asset Management Co. (ChinaAMC) |
| Bosera Asset Management |
| Penghua Fund Management |
| ICBC Credit Suisse Asset Management |
| Others |
Value Chain & Pricing Dynamics
Long-term custody agreements between fund managers and state-bank distributors lock in shelf access and fee visibility across China's mutual funds landscape. These multi-year contracts anchor revenue-sharing terms while constraining margin flexibility for emerging asset managers seeking to bypass traditional gatekeepers.
Pricing Analysis
After-sales service revenue from investor education and advisory subscriptions drives lifetime value for digitally native fund platforms. Management fee compression runs through active equity products as passive alternatives from quantitative specialists capture flow velocity. Three-tier pricing structure across premium advisory, standard distribution, and economy robo-advisory levels segments retail subscribers by sophistication. First-tier city households show lowest price sensitivity; third-tier deposit migrants demand minimal-cost money market access.
Supply Chain Analysis
Port congestion at Shanghai and Shenzhen container terminals elevates inbound logistics costs for custody infrastructure hardware and data center equipment serving fund operations. Fund manufacturing draws from domestic software development clusters in Beijing and Hangzhou, supplemented by Hong Kong-domiciled cross-border clearing technology. Single-source vulnerability concentrates in state-bank custody networks controlling seventy percent of retail shelf access. Distribution runs through proprietary mobile ecosystems and branch-mediated state-bank channels in parallel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward digitally native retail segments as mobile-first platforms fragment traditional state-bank distribution concentration. This fragmentation compresses margins for incumbents while opening white-space for agile entrants.
For Market Incumbents: Secure proprietary direct subscription functionality to bypass state-bank revenue-sharing extraction. Harvest Fund Management and E Fund Management demonstrate how captive mobile ecosystems defend margin position against quantitative boutiques. CSRC fund distribution suitability rules favor scale players with compliance infrastructure already deployed.
For New Entrants and Emerging Players: AMAC registration fast-track protocols for quantitative product specialization offer entry velocity into smart-beta segments underserved by state-bank shelf offerings. Target Shenzhen and Guangzhou private banking channels deploying enhanced due diligence for qualified investors above three million RMB thresholds. Go-to-market through embedded super-app wealth modules accelerates subscriber acquisition without branch infrastructure.
For Investors and Strategic Acquirers: Digitally native specialist platforms with direct subscription technology and algorithmic risk-profiling capabilities represent acquisition archetypes with structural positioning for passport scheme expansion. Long-term viability hinges on cross-border product registration readiness linking Hong Kong and mainland China. Monitor CSRC mutual fund passport scheme announcements as inflection indicator for competitive boundary restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Mobile Ecosystem Development | Direct subscription functionality bypasses state-bank distribution gatekeepers and their margin-destructive revenue-sharing terms. |
| Quantitative Product Specialization | Smart-beta architectures differentiate passive lineups from saturated active equity offerings at fee-competitive price points. |
| Hong Kong Passport Scheme Readiness | Cross-border product registration linkages unlock southbound capital flows for mainland-domiciled managers. |
| ETF Ecosystem Expansion | Intraday liquidity and transparent tracking cost structures attract institutional mandates from pension and insurance allocators. |
| Algorithmic Risk-Profiling Investment | CSRC distribution suitability rules mandate automated investor segmentation into qualified and non-qualified subscriber pools. |
Study Parameters
A spread of perspectives from fund distribution executives, AMAC registration specialists, custody bank operations heads, and retail platform product managers converged on the working assumptions shaping this analysis. Primary fieldwork combined with secondary validation from CSRC disclosure filings, AMAC registration databases, PBOC policy circulars, and exchange-traded fund flow reports. Bottom-up asset manager interviews and top-down regulatory framework analysis triangulated on market structure conclusions.
Segmentation dimensions modeled include asset class architecture, investor sophistication tier, fund structure liquidity terms, and investment strategy implementation style across the projection horizon. CAGRs were derived from flow velocity analysis by product category and regional subscription elasticity patterns. Forecast inputs incorporated digital distribution penetration curves and regulatory approval timeline distributions.
Underlying assumptions cover CSRC licensing continuity and AMAC registration protocol stability, with deviation risk concentrated in mutual fund passport scheme timing and PBOC rate policy trajectory. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Asset Management
Japan Asset Management Market
Asset Management
Global Asset Performance Management Market
Asset Management
Assets Under Management Market
Asset Management
Fixed Income Asset Management Market
Asset Management
Global Infrastructure Asset Management Market
Asset Management
Smart Asset Management Market
Asset Management
Equity Management Tool Market
Asset Management
Asset and Wealth Management Market
Asset Management
India Asset Management Market
Asset Management
UK Asset Management Market
Asset Management
Pension Fund Management Software Market
Asset Management
Fund Management Fee Market
Asset Management
Global Remote Asset Management Market
Asset Management
US Pension Funds Market
Asset Management
Canada Asset Management Market
Asset Management
Fund Management Software Market