
 Fixed Income Asset Management Market | 2026-2036
Fixed Income Asset Management Market Size, Share, and Industry Trends Forecast 2026-2036
Fixed Income Asset Management Market Analysis
Pension fund demand is recalibrating the fixed income asset management landscape as defined-benefit plans seek liability-driven investment solutions. BlackRock Inc leverages its Aladdin platform to dominate risk analytics for institutional fixed income portfolios. Vanguard Group sustains cost leadership through passive bond index funds that capture flows from fee-sensitive retirement plans.
Fixed income asset management encompasses the professional oversight of debt securities portfolios, including duration targeting, credit analysis, and yield curve positioning across government, corporate, and structured instruments. The practice centers on generating income, preserving capital, and managing interest rate sensitivity for institutional and retail beneficiaries. Active management commands premium fees for credit selection alpha, while passive management captures scale through benchmark replication. Government bonds anchor institutional liability matching, though mortgage-backed securities attract specialized duration-risk managers seeking spread pickup.
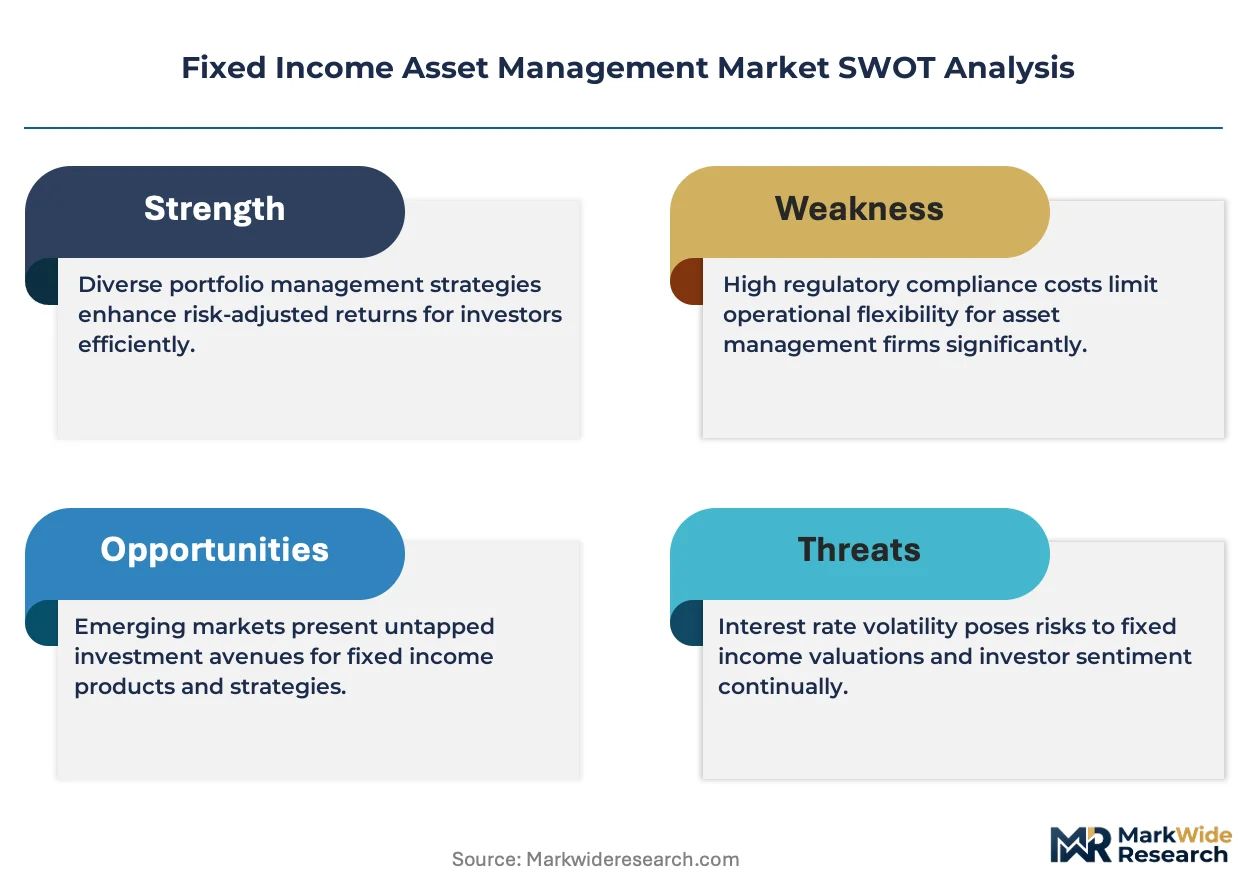
The SEC enforces liquidity risk management programs under Rule 22e-4, forcing open-end funds to classify holdings and stress-test redemption scenarios. The EU's MiFID II disclosure requirements reshape how European managers report bond transaction costs and inducement flows. Portfolio managers must monitor central bank policy divergence and benchmark reform transitions as decisive variables for allocation timing.
Market Dynamics
Institutional liability-driven investment mandates are compressing fee margins while forcing managers to deploy Aladdin-class risk analytics platforms for duration-matched portfolio construction. The SEC's liquidity risk management framework under Rule 22e-4 now governs how open-end funds classify and stress-test fixed income holdings.
Growth Catalysts
- Rule 22e-4 Compliance:The SEC's liquidity risk management program mandates classification and stress-testing protocols that drive demand for specialized risk analytics infrastructure among U.S. mutual fund complexes.
- Pension Fund Liability Matching:Defined-benefit plans across North America and Europe are reallocating toward duration-targeted strategies that align asset cash flows with long-dated benefit obligations.
- ESG Integration Mandates:European regulatory disclosure requirements under MiFID II and the EU Green Deal are compelling managers to embed carbon accounting and sustainability screening into sovereign and corporate credit selection.
Market Restraints
- Fee Compression Mechanics:Passive bond index replication by Vanguard-scale providers has collapsed management fees below 5 basis points for core Treasury and aggregate mandates.
- Central Bank Policy Divergence:Asynchronous rate cycles between the Federal Reserve and European Central Bank complicate cross-border duration positioning and currency-hedged return calculations.
- Illiquidity Concentration:High-yield and emerging market debt strategies face redemption mismatch risks when stress scenarios trigger simultaneous outflows from open-end fund structures.
Strategic Opportunities
- Private Credit Expansion:Direct lending and private placement debt markets offer yield pickup over public benchmarks for institutional investors with locked-up capital structures.
- Transition Finance Products:EU taxonomy-aligned green bonds and sustainability-linked notes create dedicated mandates for managers with verified climate data integration capabilities.
- Insurance-Linked Securities:Catastrophe bonds and collateralized reinsurance instruments attract liability-driven investors seeking decorrelated return streams.
Industry Challenges
- Quantitative Fixed Income Talent Scarcity:Portfolio construction teams lack sufficient practitioners fluent in stochastic rate modeling and credit spread optionality analytics.
- Legacy System Integration Friction:Established asset managers face multi-year migration timelines to unify proprietary risk engines with third-party data feeds for real-time position monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fixed Income Asset Management Market |
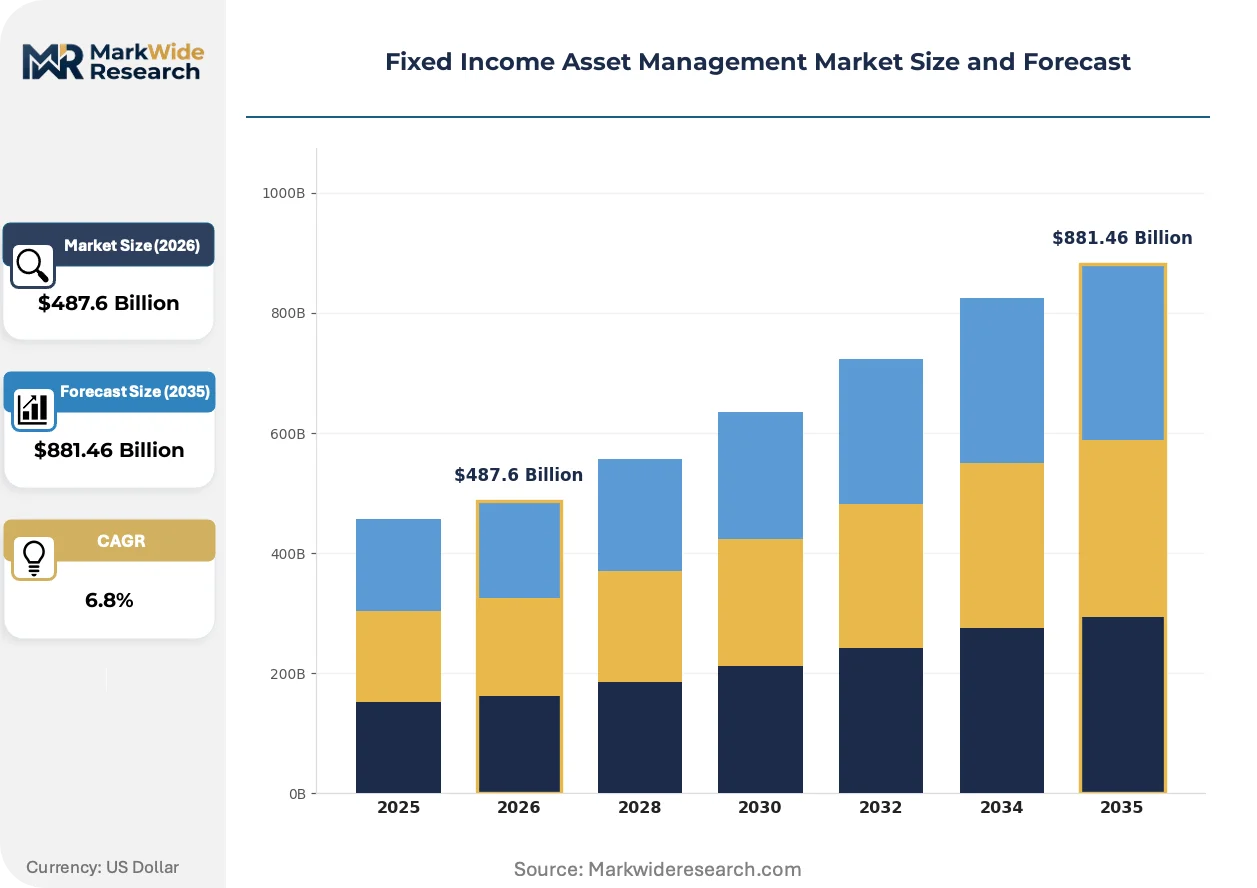
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $881.46 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Strategy: Active Management, Passive Management, Diversified Portfolio, Core Plus Asset Class: Government Bonds, Corporate Bonds, Municipal Bonds, Mortgage-Backed Securities Investor Type: Institutional Investors, Retail Investors, Private Banks, Hedge Funds Duration Risk: Short Duration, Intermediate Duration, Long Duration, Interest Rate Hedge |
| Companies Covered | BlackRock Inc, Vanguard Group, Fidelity Investments, State Street Global Advisors, JPMorgan Chase & Co, Capital Group, Goldman Sachs Group Inc, Invesco Ltd, PIMCO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fixed Income Asset Management Market Emerging Trajectories
Artificial intelligence is absorbing portfolio construction workflows that previously required teams of rate strategists and credit analysts. Machine learning models now forecast prepayment speeds for mortgage-backed securities and predict corporate default probability curves.
Natural language processing engines are absorbing unstructured data from central bank communications, earnings call transcripts, and regulatory filings to generate real-time sentiment signals for duration positioning. Institutional fixed income desks at pension funds and insurance companies are deploying these tools to compress research cycle times from weeks to hours. The structural consequence is a bifurcation between quantitative-native managers and traditional fundamental shops struggling to recruit machine learning talent.
The SEC's liquidity risk management framework is reshaping product architecture across the U.S. mutual fund industry. Rule 22e-4 requires funds to classify holdings across four liquidity buckets and maintain minimum thresholds of highly liquid assets. Open-end bond funds are responding by creating swing pricing mechanisms and establishing committed lines of credit to manage redemption stress. High-yield and bank loan strategies face the most acute compliance burdens given their inherently less liquid underlying collateral.
Institutional procurement of fixed income mandates is rotating toward outcome-based fee structures that align manager compensation with liability-relative performance metrics. Pension fund consultants are displacing traditional asset-based fee negotiations with contracts that reward alpha generation against custom liability benchmarks. This shift is most visible in the United Kingdom and Netherlands, where regulatory funding ratio disclosures intensify scrutiny of tracking error relative to benefit obligations rather than market benchmarks alone.
Fixed Income Asset Management Market Segmentation
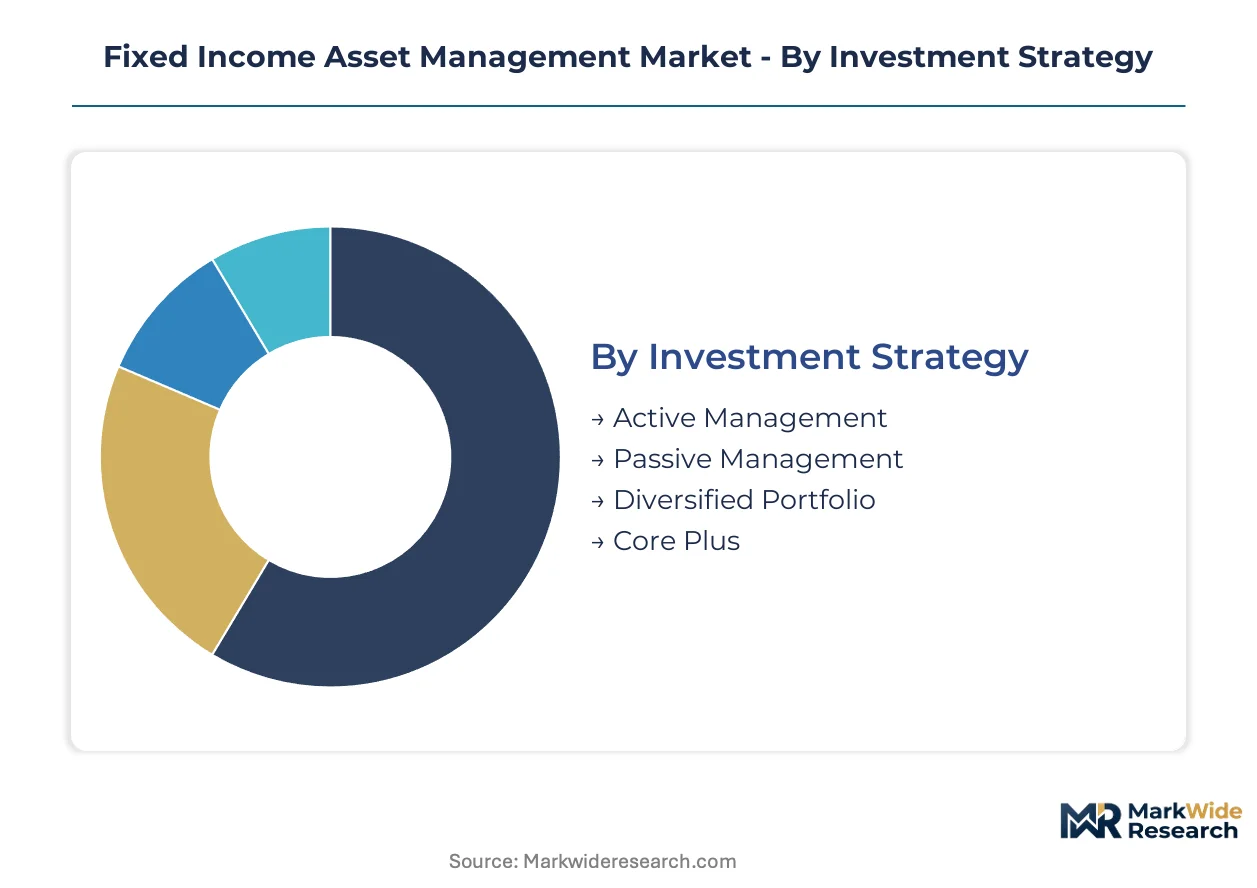
Fixed income asset management strategies diverge sharply across investment philosophy, underlying collateral, and liability profile. Each segmentation axis determines fee structures, risk analytics requirements, and regulatory compliance burdens.
Investment Strategy:
Portfolio construction methodology defines the technology stack and talent composition of management teams.
- Active Management:Discretionary credit selection and duration positioning require teams of rate strategists and fundamental analysts. Demand concentrates at U.S. pension funds and insurance companies seeking alpha generation against liability benchmarks.
- Passive Management:Rules-based replication of bond indices minimizes tracking error through sampling techniques. Vanguard-scale providers capture flows from fee-sensitive defined-contribution retirement plans.
- Diversified Portfolio:Multi-strategy approaches blend active and passive sleeves across duration and credit spectrums.
- Core Plus:Benchmark-aware strategies with limited deviation allowances for spread and sector positioning.
Mature deployment sits with Active Management. Newer deployment is concentrated in Passive Management.
Asset Class:
Collateral type determines liquidity classification under SEC Rule 22e-4 and shapes redemption risk profiles.
- Government Bonds:Sovereign debt instruments carry minimal credit risk and anchor institutional liability-matching portfolios. Central bank reserve managers and pension funds in Germany and Japan concentrate demand here.
- Corporate Bonds:Investment-grade and high-yield credit exposures require issuer-level fundamental analysis. U.S. mutual fund complexes face acute liquidity stress-testing requirements for speculative-grade allocations.
- Municipal Bonds:Tax-advantaged sub-sovereign debt attracts high-net-worth retail investors in the United States.
- Mortgage-Backed Securities:Prepayment-sensitive structured products demand specialized convexity and duration modeling.
Steepest expansion trajectory belongs to Corporate Bonds as credit spreads attract yield-seeking institutional capital.
Investor Type:
Client sophistication and capital structure dictate mandate terms and fee negotiation leverage.
- Institutional Investors:Pension funds, insurance companies, and sovereign wealth funds deploy long-duration strategies with custom liability benchmarks. Consultants in the United Kingdom and Netherlands are displacing traditional asset-based fees with outcome-based contracts.
- Retail Investors:Individual savers access fixed income through mutual funds and exchange-traded products with daily liquidity.
- Private Banks:Wealth management platforms customize tax-efficient bond ladders for ultra-high-net-worth families.
- Hedge Funds:Absolute-return mandates employ leverage and derivatives for spread and volatility arbitrage.
Fee compression pressure originates with Retail Investors. Complex mandate growth clusters with Institutional Investors.
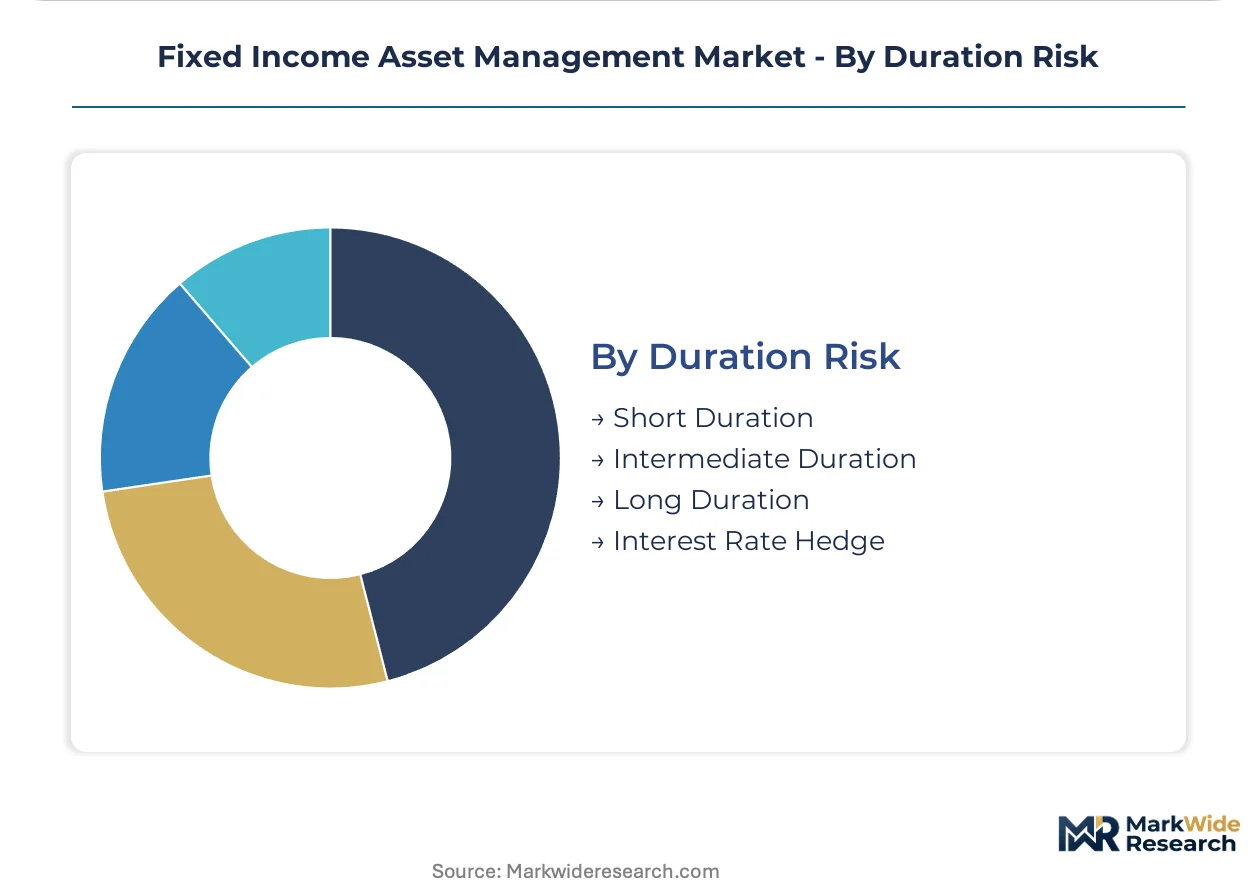
Duration Risk:
Interest rate sensitivity positioning determines portfolio volatility and immunization effectiveness against liability streams.
- Short Duration:Portfolios with weighted average maturities under three years minimize rate volatility. Money market funds and cash-plus strategies in the United States attract inflows during Federal Reserve tightening cycles.
- Intermediate Duration:Core aggregate exposures balance yield pickup against price fluctuation tolerance.
- Long Duration:Extended maturity structures match pension benefit obligations stretching decades into the future.
- Interest Rate Hedge:Derivative overlays and negative duration positions isolate credit exposure from rate movements.
Liability-driven deployment dominates Long Duration. Tactical repositioning flows concentrate in Short Duration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fixed income asset management production concentrates in financial centers with deep institutional capital pools, while consumption spreads across pension-heavy economies seeking liability-matched solutions. The United States generates the largest fee revenues from active mandates. European markets drive ESG-integrated strategy demand.
United States
Defined-benefit pension plans and insurance companies anchor institutional demand for duration-targeted strategies. The SEC's Rule 22e-4 liquidity risk management framework governs open-end fund classification and stress-testing protocols. New York and Boston house the dominant concentration of asset managers deploying Aladdin-class risk analytics platforms for institutional portfolios.
United Kingdom
Pension fund consultants are displacing traditional asset-based fees with outcome-based contracts tied to liability-relative performance. The Pensions Regulator's funding ratio disclosure requirements intensify scrutiny of tracking error against benefit obligations. The City of London remains the primary cluster for liability-driven investment mandate origination across European institutional clients.
Germany
Insurance companies and pension funds drive demand for long-duration government bond strategies matching euro-denominated liabilities. BaFin's implementation of EU MiFID II disclosure rules reshapes how managers report bond transaction costs and inducement flows. Frankfurt anchors the continental European hub for institutional fixed income portfolio construction and risk management services.
Japan
Government Pension Investment Fund allocations sustain demand for domestic and foreign bond mandates with yen-hedged structures. The Financial Services Agency's stewardship code revisions pressure asset managers to demonstrate active engagement on fixed income issuer governance. Tokyo's asset management district concentrates the regional headquarters for global firms serving Asia-Pacific institutional investors.
Australia
Superannuation funds are reallocating toward fixed income as members age into retirement-phase portfolios requiring capital preservation. APRA's prudential standards for liquidity coverage ratios influence how funds construct bond portfolios with daily redemption features. Sydney and Melbourne host the domestic asset management clusters serving the country's institutional retirement capital pool.
Fixed Income Asset Management Market Vendor Landscape
Top-tier vendors anchor the institutional active management tier, while scale-driven passive providers and specialized credit shops occupy distinct competitive positions. The market structure consolidates around three archetypes: integrated platforms with proprietary risk analytics, low-cost index replication specialists, and boutique credit selection firms. Strategic moves center on outcome-based fee contract expansion and AI-enabled portfolio construction capability acquisition.
Within the integrated platform tier, BlackRock Inc and Vanguard Group exemplify divergent competitive positions. BlackRock occupies the risk analytics and institutional active mandate space through its technology-embedded distribution model. Vanguard anchors the passive replication segment with fee-compressed index fund structures capturing defined-contribution retirement plan flows. State Street Global Advisors sits within the institutional custody-integrated asset management archetype, leveraging securities servicing relationships for mandate access.
| Leading Market Players |
|---|
| BlackRock Inc |
| Vanguard Group |
| Fidelity Investments |
| State Street Global Advisors |
| JPMorgan Chase & Co |
| Capital Group |
| Goldman Sachs Group Inc |
| Invesco Ltd |
| PIMCO |
| Others |
Supply Flow & Price Mechanics
Technology infrastructure costs cascade through fixed income asset management pricing tiers, with Aladdin-class risk analytics platforms commanding premium fees at institutional mandates while passive replication engines compress retail-facing products below 5 basis points.
Pricing Analysis
Margin tightening in active management reflects pension fund consultants displacing traditional asset-based fees with outcome-based contracts tied to liability-relative performance metrics. Three-tier pricing structure across institutional active, institutional passive, and retail passive levels separates premium alpha-seeking mandates from benchmark replication products. Cost compression accelerates in core Treasury and aggregate mandates as Vanguard-scale providers capture defined-contribution retirement plan flows. Retail investors exhibit highest price sensitivity, while institutional investors prioritize risk analytics capability over fee minimization.
Supply Chain Analysis
EU MiFID II disclosure requirements and SEC Rule 22e-4 liquidity classification mandates are reshaping how asset managers source data infrastructure and compliance technology. Technology vendors concentrate in the United States, United Kingdom, and Ireland, with risk analytics platforms drawing from proprietary data feeds, third-party pricing services, and regulatory filing databases. Single-source vulnerability sits with concentrated Aladdin-platform dependency among tier-one managers. Distribution runs through direct institutional sales teams, consultant-mediated procurement, and retail fund supermarket platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fixed income asset management is becoming a vertical-integration race, with proprietary risk analytics platforms and captive data infrastructure emerging as the decisive upstream lever separating tier-one integrated players from fee-compressed replicators.
For Market Incumbents: Deepen proprietary technology moats through in-house development of machine learning-enabled portfolio construction tools, insulating against quant-native entrants. Acquire specialized credit analytics boutiques to capture stochastic rate modeling talent scarce in traditional fundamental shops. Consolidate data infrastructure vertically to reduce third-party vendor dependency and defend margin position against passive fee erosion.
For New Entrants and Emerging Players: Consultant relationships with UK and Netherlands pension fund advisors offer the most penetrable channel for liability-driven investment mandate origination. Target ESG-integrated fixed income strategies where verified climate data integration capabilities remain undersupplied relative to EU Green Deal-driven demand. Pursue white-label technology partnerships with regional banks lacking internal portfolio construction infrastructure.
For Investors and Strategic Acquirers: Outcome-based fee contract proliferation is the leading indicator that liability-relative performance measurement will reshape manager economics over the next decade. Acquire boutique credit selection firms with demonstrated alpha generation against custom benchmarks. Watch for inflection when pension funding ratio disclosure requirements expand beyond the United Kingdom and Netherlands into Germany and North America.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Risk Analytics Platform Development | BlackRock's Aladdin platform demonstrates how technology-embedded distribution captures institutional mandate market share. |
| Outcome-Based Fee Contract Expansion | Pension fund consultants in the UK and Netherlands are displacing traditional asset-based fees with liability-relative performance contracts. |
| ESG Data Integration Capability Acquisition | EU Green Deal taxonomy alignment requirements create dedicated mandate demand for verified climate data integration. |
| Machine Learning Talent Recruitment | Quantitative-native managers are bifurcating from traditional fundamental shops through stochastic rate modeling expertise. |
| Private Credit Strategy Buildout | Direct lending markets offer yield pickup over public benchmarks for institutional investors with locked-up capital structures. |
Methodological Framework
SEC filings, EU regulatory disclosure databases, and pension fund consultant procurement records formed the secondary backbone, supplemented by primary interviews with portfolio construction heads, risk analytics platform vendors, and pension fund investment consultants. Bottom-up triangulation across mandate flow data and top-down validation against aggregate AUM reporting anchored the analytical framework.
Historical trendline analysis of fee compression trajectories and mandate origination patterns informed the projection methodology across the analysis window. Segmentation dimensions modeled include investment strategy philosophy, underlying collateral type, investor sophistication tier, and duration risk positioning. CAGRs were derived from regression analysis of institutional allocation shifts and regulatory-driven product architecture changes, with inputs from central bank policy divergence scenarios and benchmark reform transition timelines.
Caveats apply where asynchronous Federal Reserve and European Central Bank rate cycles, or unforeseen liquidity stress events, could materially shift the outlook for open-end fund structures. Forecasts reflect assumptions about pension fund de-risking velocity and ESG regulatory enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Asset Management
Global Remote Asset Management Market
Asset Management
Asia-Pacific Utilities Asset Management Market
Asset Management
India Asset Management Market
Asset Management
Pension Fund Management Software Market
Asset Management
India Mutual Fund Market
Asset Management
Asset and Wealth Management Market
Asset Management
Capital Expenditure Market
Asset Management
Canada Asset Management Market
Asset Management
US Healthcare Assets Management Market
Asset Management
Asset Optimization Solutions Market
Asset Management
Mutual Fund Assets Market
Asset Management
Europe Asset Management Market
Asset Management
UK Asset Management Market
Asset Management
Global AI in Asset Management Market
Asset Management
Healthcare Asset Management Market
Asset Management
Global Investment Management Software Market