
 Canada Pension Fund Market | 2026-2036
Canada Pension Fund Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Pension Fund Market Insights
Canada is reconfiguring its pension fund capacity through expanded alternative asset platforms and enhanced governance frameworks. The Canada Pension Plan Investment Board leverages global infrastructure and private equity mandates to sustain long-term liability matching. Caisse de dépôt et placement du Québec anchors Quebec's institutional capital base through real estate and infrastructure specialization. Ontario Teachers' Pension Plan competes internationally by controlling direct investment capabilities across private markets.
Canada pension funds are pooled investment vehicles managing retirement assets for public and private sector employees, governed by fiduciary standards requiring actuarial solvency testing and risk-adjusted return targets. These entities deploy capital across diversified portfolios to meet defined-benefit obligations and target-date liabilities for millions of beneficiaries. The asset class dimension shows private equity and infrastructure commanding premium allocations due to illiquidity premiums and inflation-hedging characteristics, while public equity maintains foundational liquidity. Investor type segmentation reveals institutional investors dominating contribution flows, with family offices representing a faster-growing participant category seeking co-investment access.
OSFI's pension governance guidelines, provincial securities commission oversight, and the Canadian Association of Pension Supervisory Authorities' harmonized standards collectively shape fund conduct, investment risk disclosure, and funding valuation protocols. These regulatory layers influence product structuring, cross-border investment access, and participant communication requirements. Stakeholders must monitor evolving solvency funding rules and ESG disclosure mandates as determinants of competitive positioning and capital deployment flexibility.
Market Dynamics
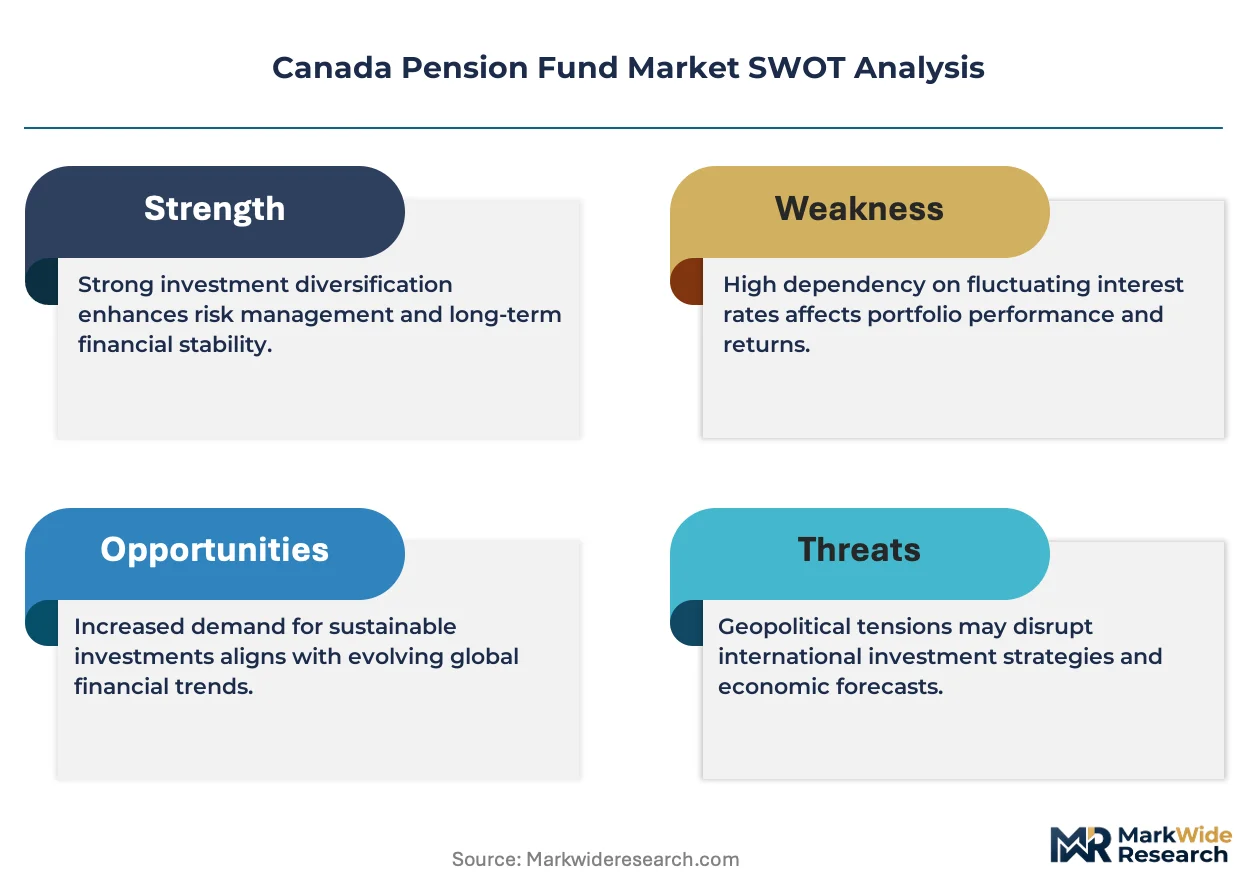
Canada's pension funds face intensifying pressure to match long-dated liabilities with yield-bearing assets as interest rate volatility compresses traditional fixed-income spreads. OSFI's evolving solvency guidelines and provincial funding rules are forcing plans to recalibrate risk tolerance and disclosure frameworks.
Growth Catalysts
- Alternative asset platforms:Infrastructure and private equity allocations generate illiquidity premiums that offset compressed public market returns. Ontario Teachers' Pension Plan and CPPIB anchor this expansion with direct investment capabilities.
- Provincial regulatory harmonization:The Canadian Association of Pension Supervisory Authorities coordinates solvency standards across jurisdictions, reducing compliance fragmentation for multi-provincial plans.
- Quebec's institutional capital concentration:Caisse de dépôt et placement du Québec deploys real estate and infrastructure specialization to capture inflation-hedging characteristics for provincial beneficiaries.
Market Restraints
- Long-duration asset scarcity:Domestic infrastructure and private credit pipelines cannot absorb capital deployment targets, forcing plans into crowded international markets with compressed underwriting margins.
- Interest rate sensitivity:Defined-benefit solvency valuations remain vulnerable to Bank of Canada policy shifts, creating procyclical funding volatility that constrains strategic asset allocation.
- Actuarial liability mismatch:Mortality improvement assumptions and longevity risk transfer market illiquidity expose plans to unhedgeable tail risks in retiree cohorts.
Strategic Opportunities
- Climate transition infrastructure:Federal green bond frameworks and carbon pricing mechanisms create regulatory tailwinds for renewable energy and grid modernization allocations.
- Co-investment platforms:Family offices and mid-market institutional investors seek access to Canadian pension direct deal flow, enabling fee reduction through syndication structures.
- Technology-enabled asset management:Predictive analytics and portfolio risk visualization tools converge with ESG data integration to enhance liability-driven investment precision.
Industry Challenges
- Specialized investment talent scarcity:Direct infrastructure and private equity underwriting capabilities require scarce skill sets in project finance and operational value creation.
- Legacy system integration friction:Pension administration platforms face complex data migration when adopting modern participant communication and benefit calculation engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Pension Fund Market |
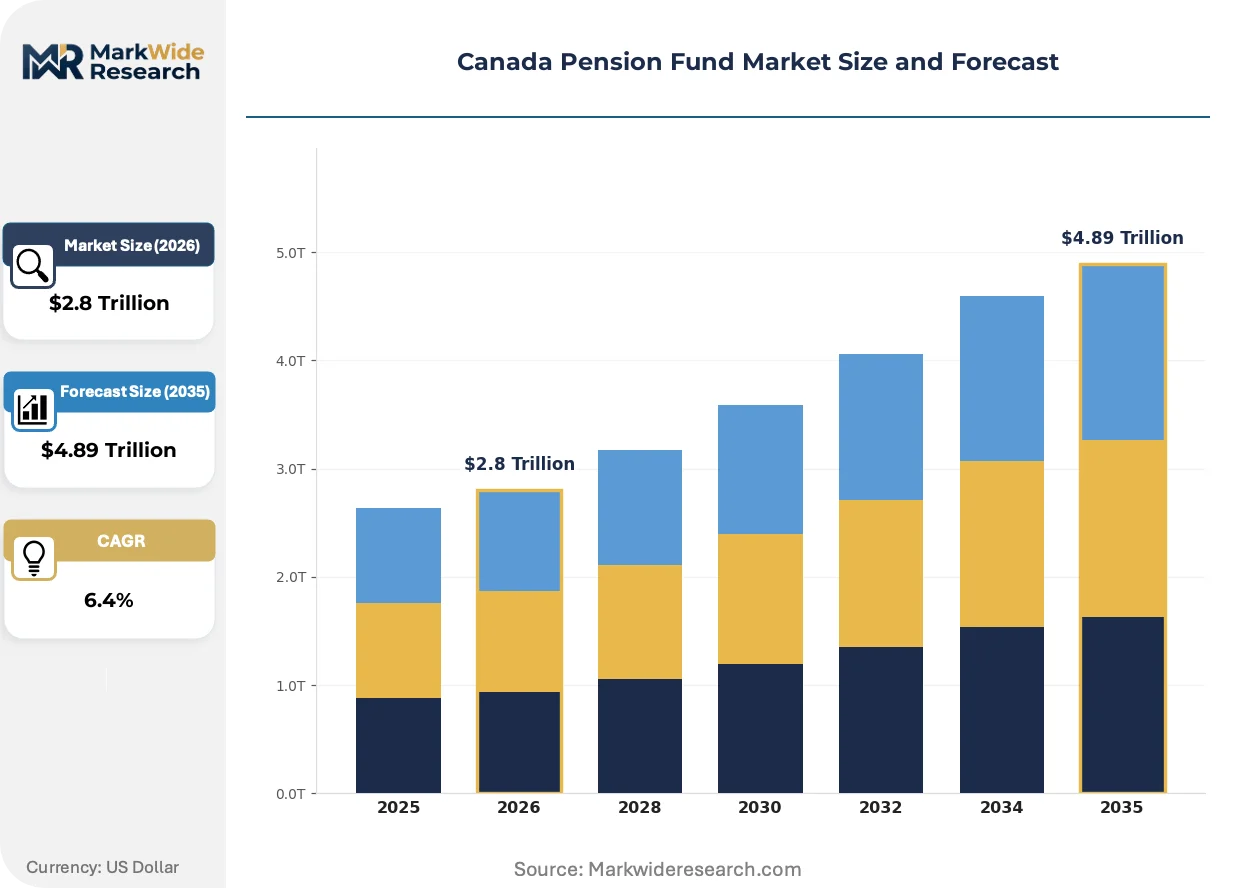
| Market Size in 2026 | $2.8 Trillion |
| Market Size in 2035 | $4.89 Trillion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Strategy: Passive, Active, Alternative, Public Equity Asset Class: Private Equity, Infrastructure, Real Estate, Cash Investor Type: Institutional Investors, Corporations, HNWIs, Family Offices Transaction Size: Micro, Small, Medium, Large |
| Companies Covered | Canada Pension Plan Investment Board, Caisse de dépôt et placement du Québec, Ontario Teachers’ Pension Plan, Ontario Municipal Employees Retirement System, Healthcare of Ontario Pension Plan, Public Sector Pension Investment Board, British Columbia Investment Management Corporation, Alberta Investment Management Corporation, Investment Management Corporation of Ontario, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Pension Fund Market Trends and Innovations
Canadian pension governance is migrating toward integrated risk frameworks that embed climate scenario analysis and participant demographic modeling into strategic asset allocation. This evolution demands new data infrastructure and cross-functional coordination between investment and actuarial functions.
Direct private market investing is migrating from fund-of-funds structures toward captive deal origination and operational control. CPPIB and Ontario Teachers' have built internal teams exceeding five hundred professionals to source infrastructure and private equity transactions. This capability compression eliminates external manager fees and accelerates decision velocity for time-sensitive opportunities.
OSFI's pension governance guidelines are tightening disclosure requirements for environmental and social risk exposure, compelling plans to adopt standardized reporting frameworks. The regulator's 2023 guideline updates mandate board-level accountability for climate risk integration. Large defined-benefit plans in Ontario and Quebec are responding by hiring dedicated sustainability risk officers and adopting TCFD-aligned scenario analysis.
Beneficiary communication preferences are shifting from annual paper statements toward digital engagement platforms with personalized retirement income projections. Younger cohorts in Ontario's municipal and provincial plans demonstrate higher activation rates for mobile-accessible tools. This channel migration is most visible in Quebec, where Caisse de dépôt sponsors financial literacy programs targeting defined-contribution participants nearing retirement decisions.
Canada Pension Fund Market Segmentation
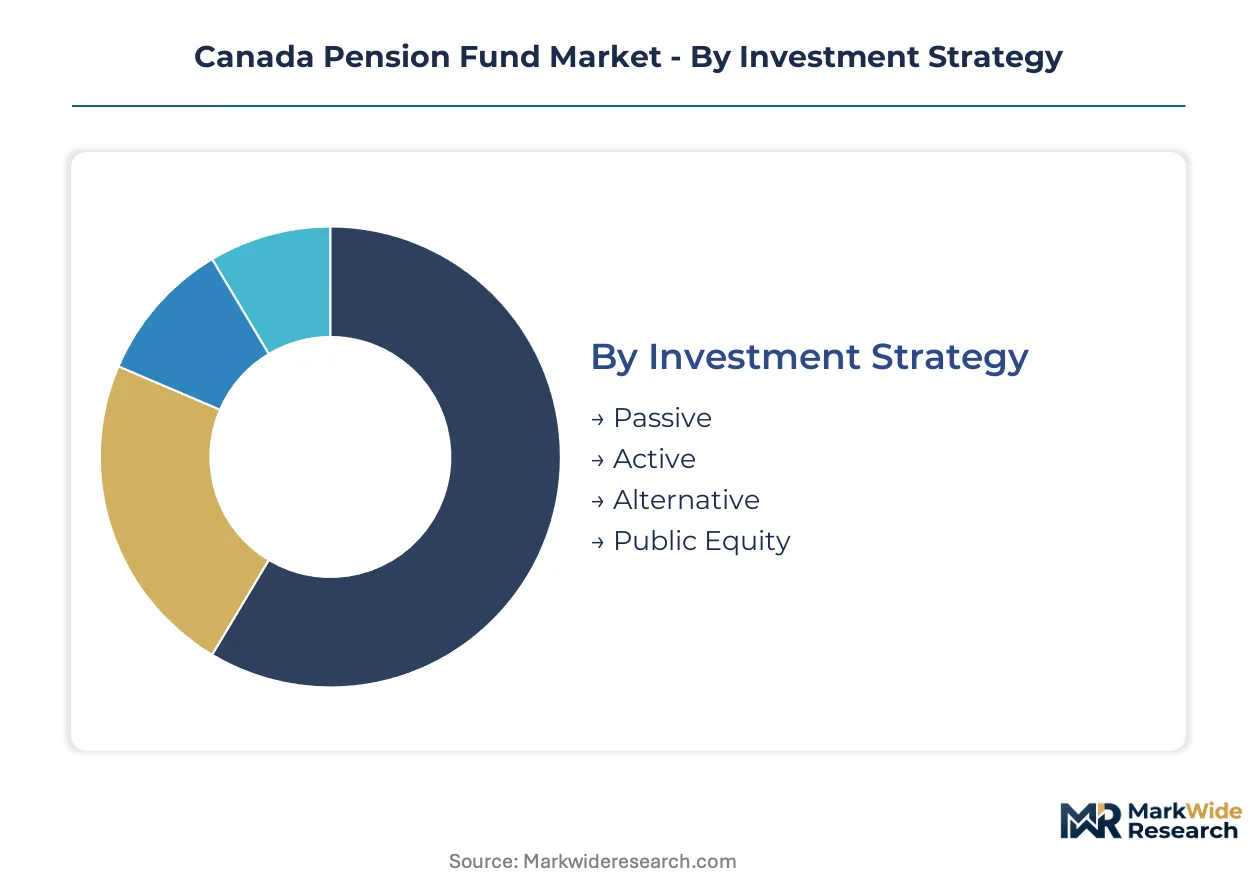
Canadian pension fund segmentation reveals how capital pools differentiate by risk tolerance, liquidity requirements, and governance sophistication. Structural distinctions across strategy, asset class, investor profile, and deployment scale shape fee structures, regulatory treatment, and beneficiary communication protocols.
Investment Strategy:
Mature indexing approaches dominate Canadian pension capital deployment, while emerging direct investment capabilities are reshaping active management economics.
- Passive:Low-cost index replication strategies track broad equity and fixed-income benchmarks. Ontario municipal plans concentrate demand here for cost-efficient core exposure with minimal tracking error.
- Active:Security selection and tactical allocation seek excess returns over benchmarks. Quebec's large defined-benefit plans deploy active mandates in concentrated Canadian equity sleeves where information asymmetries persist.
- Alternative:Direct infrastructure, private equity, and credit investments generate illiquidity premiums. OSFI solvency guidelines increasingly accommodate these long-duration holdings within liability-matching frameworks.
- Public Equity:Listed securities provide foundational liquidity and daily mark-to-market transparency. CPPIB maintains substantial public equity sleeves for rebalancing flexibility and tactical currency hedging.
Passive retains volume leadership; Alternative holds the steepest expansion curve.
Asset Class:
Cost tier differentiation separates premium-yielding illiquid assets from lower-fee liquid allocations across Canadian pension balance sheets.
- Private Equity:Direct company ownership and fund commitments target operational value creation and multiple expansion. Ontario Teachers' Pension Plan has built captive deal origination teams exceeding five hundred professionals to source control transactions.
- Infrastructure:Long-duration tangible assets generate inflation-linked cash flows matching retiree liability profiles. Caisse de dépôt et placement du Québec anchors Quebec's provincial capital base through toll roads, utilities, and energy transmission specialization.
- Real Estate:Core, value-add, and opportunistic property strategies diversify across office, residential, industrial, and retail subsectors. Urban density in Toronto and Vancouver concentrates domestic deployment targets.
- Cash:Liquidity reserves and short-duration instruments meet benefit payment obligations and collateral requirements. Bank of Canada policy rate volatility has compressed cash yields, reducing strategic allocations.
Infrastructure commands the premium fee tier; Private Equity is gaining share fastest through direct investment buildouts.
Investor Type:
Customer type segmentation distinguishes fiduciary-governed pools from discretionary wealth in Canadian pension capital formation.
- Institutional Investors:Public sector retirement systems and corporate defined-benefit plans dominate contribution flows and asset aggregation. OSFI oversight and provincial solvency standards govern their conduct.
- Corporations:Sponsoring employers manage pension obligations as balance sheet liabilities, with de-risking trends accelerating pension risk transfer transactions.
- HNWIs:High-net-worth individuals access pension-style alternative exposure through structured products and co-investment platforms. Family office intermediation is expanding this channel.
- Family Offices:Multi-generational wealth vehicles seek direct deal access and fee reduction through syndication with large Canadian pension plans. This cohort represents the expanding participant category.
Institutional Investors anchor capital formation; Family Offices are climbing the fastest as co-investment demand surges.
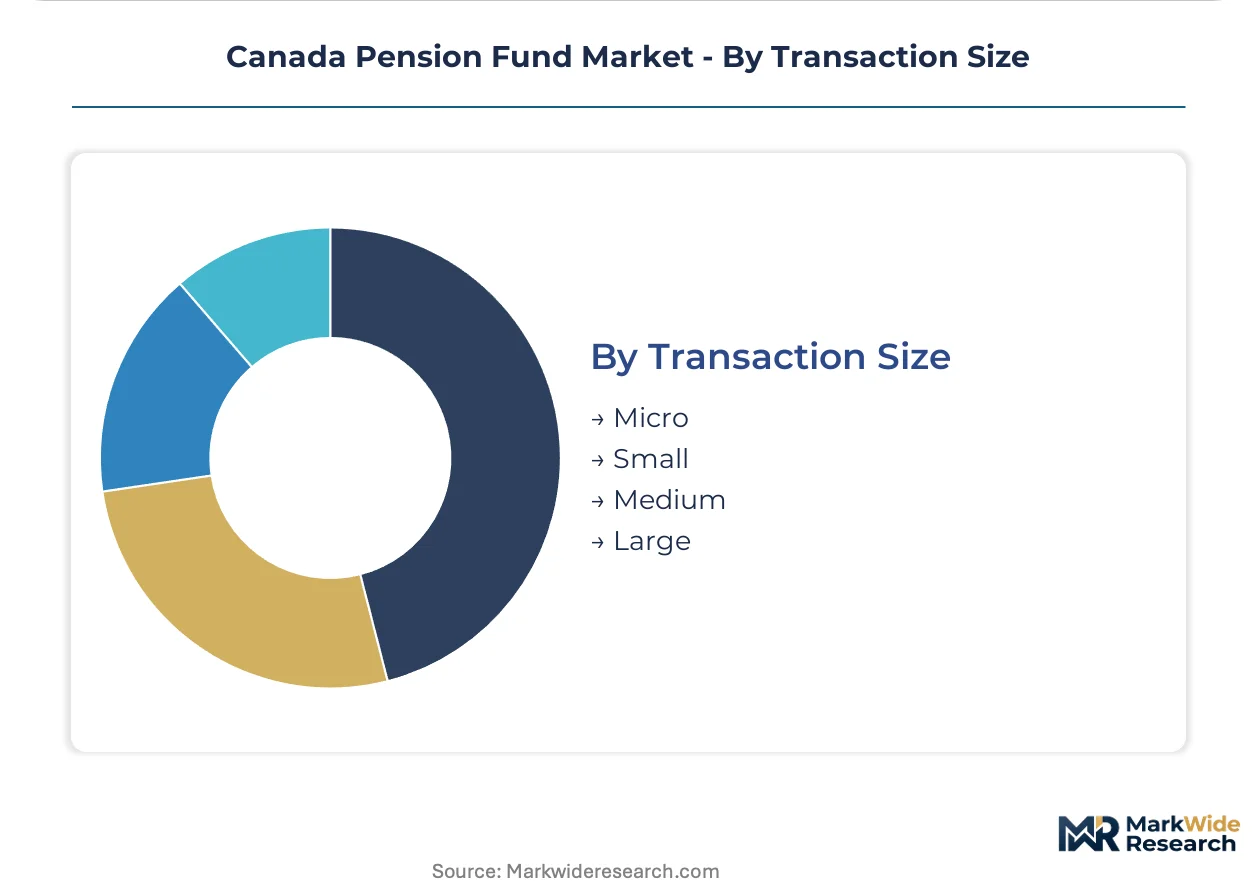
Transaction Size:
Volume concentration in large-ticket deployments shapes Canadian pension fund market structure and intermediary economics.
- Micro:Sub-institutional commitments below standard fund minimums require feeder structures or fund-of-funds access. Retail-suitable products serve this tier.
- Small:Mid-market pension plans and consolidated family wealth deploy capital through commingled vehicles with standardized terms.
- Medium:Provincial and large municipal plans negotiate customized side letters and co-investment rights within established manager relationships.
- Large:Mega-cap transactions and direct control acquisitions characterize CPPIB and Ontario Teachers' deployment. These deals bypass external fund structures entirely.
Large transactions dominate headline deployment; Medium-sized commitments are expanding most quickly as mid-market plans build direct capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian pension fund assets concentrate in Ontario and Quebec, where the largest plans maintain headquarters and deploy capital domestically and abroad. Provincial regulatory frameworks from OSFI and provincial securities commissions govern solvency standards and disclosure requirements across jurisdictions.
Ontario
Ontario hosts the Canada Pension Plan Investment Board and Ontario Teachers' Pension Plan, which anchor national alternative asset deployment. OSFI's pension governance guidelines mandate board-level accountability for climate risk integration and funding valuation protocols. Toronto concentrates direct investment teams exceeding five hundred professionals sourcing infrastructure and private equity transactions.
Quebec
Quebec's institutional capital base centers on Caisse de dépôt et placement du Québec, which specializes in real estate and infrastructure for provincial beneficiaries. The Autorité des marchés financiers coordinates solvency standards with federal regulators, reducing compliance fragmentation. Montreal anchors captive deal origination capabilities across toll roads, utilities, and energy transmission assets.
British Columbia
British Columbia Investment Management Corporation manages public sector retirement assets with expanding allocations to renewable energy and grid modernization. Provincial securities commission oversight aligns with federal green bond frameworks creating regulatory tailwinds for climate transition infrastructure. Vancouver concentrates technology-enabled asset management platforms integrating ESG data for liability-driven investment precision.
Alberta
Alberta Investment Management Corporation deploys capital across energy transition infrastructure and conventional resource assets. The province's regulatory environment accommodates pension risk transfer transactions as sponsoring employers de-risk balance sheet obligations. Calgary anchors specialized investment talent pools in project finance and operational value creation for direct underwriting capabilities.
Canada Pension Fund Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in fragmented niches. The Canada pension fund market structures around mega-cap asset aggregators with internal direct investment capabilities, mid-market provincial plans with hybrid fund-and-direct models, and smaller municipal systems reliant on external managers. Three archetypes dominate: sovereign-scale pools with global infrastructure mandates, provincial champions with sectoral specializations, and consolidated multi-employer plans with standardized commingled access. Competitive moves concentrate on building captive deal origination teams and securing co-investment syndication partnerships with family offices.
Among the sovereign-scale tier, Canada Pension Plan Investment Board and Ontario Teachers' Pension Plan occupy positions representing internalized platform economics. Caisse de dépôt et placement du Québec exemplifies the provincial champion archetype with real estate and infrastructure concentration. These entities anchor the competitive landscape through scale-driven fee compression and direct control acquisition capabilities that bypass external fund structures entirely.
| Leading Market Players |
|---|
| Canada Pension Plan Investment Board |
| Caisse de dépôt et placement du Québec |
| Ontario Teachers' Pension Plan |
| Ontario Municipal Employees Retirement System |
| Healthcare of Ontario Pension Plan |
| Public Sector Pension Investment Board |
| British Columbia Investment Management Corporation |
| Alberta Investment Management Corporation |
| Investment Management Corporation of Ontario |
| Others |
Pricing and Supply Chain Analysis
Toronto's concentration of direct investment teams exceeding five hundred professionals anchors Canada's pension fund pricing power, as proximity to captive deal origination compresses external manager fees and accelerates decision velocity for time-sensitive infrastructure transactions.
Pricing Analysis
OSFI's pension governance guidelines dictate the pricing tier structure across Canadian retirement systems, with three-tier pricing separating large defined-benefit plans with internalized platforms from mid-market provincial systems and smaller municipal funds reliant on external managers. Price differentiation rests on governance sophistication and direct underwriting capability rather than scale alone. Pricing pressure stems from compressed fixed-income spreads as Bank of Canada policy rate volatility constrains liability-matching returns. Mid-market plans exhibit highest price sensitivity as they build hybrid fund-and-direct models.
Supply Chain Analysis
Global infrastructure developers and private equity sponsors hold contract-manufacturing concentration for Canadian pension capital deployment, with Brookfield, Macquarie, and KKR anchoring pipeline origination across toll roads, utilities, and energy transmission assets. Geographic supply concentrates in the United States, Western Europe, and Australia where regulatory frameworks accommodate long-duration asset structures. Raw material dependencies include construction materials, energy commodities, and specialized project finance expertise. Single-source vulnerability runs through concentrated direct investment talent pools in Toronto and Montreal. Distribution feeds from sponsor relationships into co-investment syndication structures with family offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's pension fund market sits in early-cycle expansion as alternative asset platforms displace traditional fixed-income allocations and provincial regulatory harmonization accelerates cross-jurisdictional capital mobility.
For Market Incumbents: Harden direct infrastructure underwriting capabilities against emerging private credit entrants and specialized real estate platforms. Deepen captive deal origination teams in Toronto and Montreal to defend fee compression from external manager displacement. Prioritize certification investment in TCFD-aligned climate risk reporting ahead of OSFI disclosure mandate tightening.
For New Entrants and Emerging Players: Establish a beachhead in mid-market municipal pension systems where hybrid fund-and-direct models remain underdeveloped. Target Quebec's institutional capital base through real estate and infrastructure specialization partnerships with Caisse de dépôt. Pursue co-investment syndication angles with family offices seeking fee reduction through direct deal access.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because scale-driven fee compression and internalized platform economics favor asset aggregators with captive origination capabilities. Acquisition target archetype: mid-market provincial plans with strong beneficiary bases but underdeveloped direct investment infrastructure. Watch for Bank of Canada policy rate stabilization as inflection signal for liability-driven investment precision.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct Investment Platform Buildout | CPPIB and Ontario Teachers' demonstrate how internal teams exceeding five hundred professionals eliminate external manager fees entirely. |
| Climate Risk Integration | OSFI's 2023 guideline updates mandate board-level accountability for TCFD-aligned scenario analysis across large defined-benefit plans. |
| Co-Investment Syndication | Family office intermediation expands fee reduction access for mid-market institutional investors seeking direct deal flow participation. |
| Provincial Regulatory Harmonization | The Canadian Association of Pension Supervisory Authorities coordinates solvency standards, reducing compliance fragmentation for multi-provincial plans. |
| Technology-Enabled Asset Management | Predictive analytics and ESG data integration converge in Vancouver platforms to enhance liability-driven investment precision. |
Research Methodology
A spread of perspectives from pension fund CIOs, OSFI regulatory affairs leads, provincial securities commission officials, and direct investment managing directors converged on the working assumptions. Primary interviews with infrastructure underwriting teams and private equity origination professionals were validated against secondary sources including OSFI pension governance guidelines, provincial solvency funding reports, and Canadian Association of Pension Supervisory Authorities harmonized standards. Bottom-up beneficiary flow analysis and top-down asset aggregation estimates were triangulated to establish market sizing.
Demand-supply balance framing anchored the analytical framework across the projection horizon, modeling contribution inflows against deployable alternative asset pipeline capacity. Segmentation dimensions included investment strategy, asset class, investor type, and transaction size, with additional modeling of provincial regulatory cluster differentiation. CAGRs were derived through trend extrapolation of historical allocation shifts and forward assessment of liability-matching requirements. Forecast inputs incorporated mortality improvement assumptions and longevity risk transfer market development.
Stress conditions across Bank of Canada policy rate trajectories, infrastructure pipeline scarcity, and actuarial liability mismatch were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory stability and beneficiary demographic composition. Quarterly review of OSFI solvency guideline updates and provincial funding rule changes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Asset Management
LAMEA Equity Management Software Market
Asset Management
US Pension Funds Market
Asset Management
Healthcare Asset Management Market
Asset Management
UK Asset Management Market
Asset Management
Asset Optimization Solutions Market
Asset Management
Fixed Income Asset Management Market
Asset Management
Canada Asset Management Market
Asset Management
Fund Management Fee Market
Asset Management
Asset and Wealth Management Market
Asset Management
Global Remote Asset Management Market
Asset Management
China Mutual Funds Market
Asset Management
Japan Asset Management Market
Asset Management
US Healthcare Assets Management Market
Asset Management
APAC Mutual Fund Market
Asset Management
Fund Management Software Market
Asset Management
Asset Management System Market