
 Fund Management Fee Market | 2026-2036
Fund Management Fee Market Size, Share, and Industry Trends Forecast 2026-2036
Fund Management Fee Market Insights
EU SFDR disclosure requirements is expanding the market for transparent, sustainability-linked fee arrangements across European fund managers. BlackRock Investment Management (UK) Limited leverages its scale to standardize ESG-aligned pricing frameworks. Legal & General Investment Management Limited anchors its competitive position through climate-transition mandates with embedded performance benchmarks. Fidelity Worldwide Investment differentiates by integrating carbon accounting tools directly into its fee reporting infrastructure.
Fund management fees represent compensation structures charged by asset managers for portfolio oversight, typically calculated as a percentage of assets under management or as performance-linked incentives tied to benchmark outperformance. These arrangements incorporate base administration charges, hurdle rates, high-water marks, and crystallization periods that govern when incentive fees become payable. Performance fee structures among hedge funds and private equity vehicles command elevated margins due to complex waterfall calculations and carried interest mechanics. Fixed and asset-based fee models dominate the pension fund and institutional investor segments, where scale and duration preferences favor predictable cost structures over variable outcomes.
SEC oversight in the United States mandates fee disclosure under Form ADV and the Investment Advisers Act, while the UK's FCA enforces PRIIPs-compliant cost transparency for retail-facing products. The EU's MiFID II rules impose explicit unbundling of research and execution costs, directly compressing traditional revenue streams for active managers. Stakeholders must monitor how regulatory arbitrage between jurisdictions reshapes fee competitiveness and where fiduciary duty interpretations tighten scrutiny on value-for-money assessments.
Market Dynamics
Performance-linked fee structures are displacing fixed-percentage models across institutional mandates, driven by pension fund demands for alignment between manager compensation and absolute return outcomes.
Growth Catalysts
- EU SFDR disclosure mandates:European fund managers must report sustainability metrics alongside fee schedules, creating standardized frameworks for ESG-linked pricing across the continent.
- Pension fund scale concentration:Large defined-benefit plans in the United States negotiate tiered fee schedules that compress base rates while expanding performance incentive pools.
- Blockchain-based fee crystallization:Distributed ledger technology automates high-water mark calculations and reduces administrative overhead for hedge fund waterfall structures.
Market Restraints
- Regulatory arbitrage friction:Divergent SEC and FCA interpretations of fiduciary duty create compliance complexity for cross-border managers operating dual-registered entities.
- Fee compression in passive mandates:Index-tracking strategies face single-digit basis point pricing floors that eliminate margin cushion for operational investment.
- Research unbundling legacy:MiFID II's explicit separation of execution and research costs permanently removed a revenue stream that formerly subsidized active management fees.
Strategic Opportunities
- Carbon-accounting fee integration:Managers embedding Scope 3 emissions tracking into reporting infrastructure capture mandates from climate-transition-focused institutional allocators.
- Private wealth technology convergence:Robo-advisory platforms combining algorithmic portfolio construction with human advisor overlay create hybrid fee models untapped in retail segments.
- India's pension system expansion:The National Pension System's asset growth generates demand for locally compliant fee structures among international managers seeking emerging market exposure.
Industry Challenges
- Quantitative talent scarcity:Fee analytics and waterfall engineering require specialized computational finance expertise that competes with fintech and proprietary trading salaries.
- Legacy system integration:Established custodians maintaining decades-old fee calculation engines face prohibitive costs to modernize for real-time crystallization reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fund Management Fee Market |
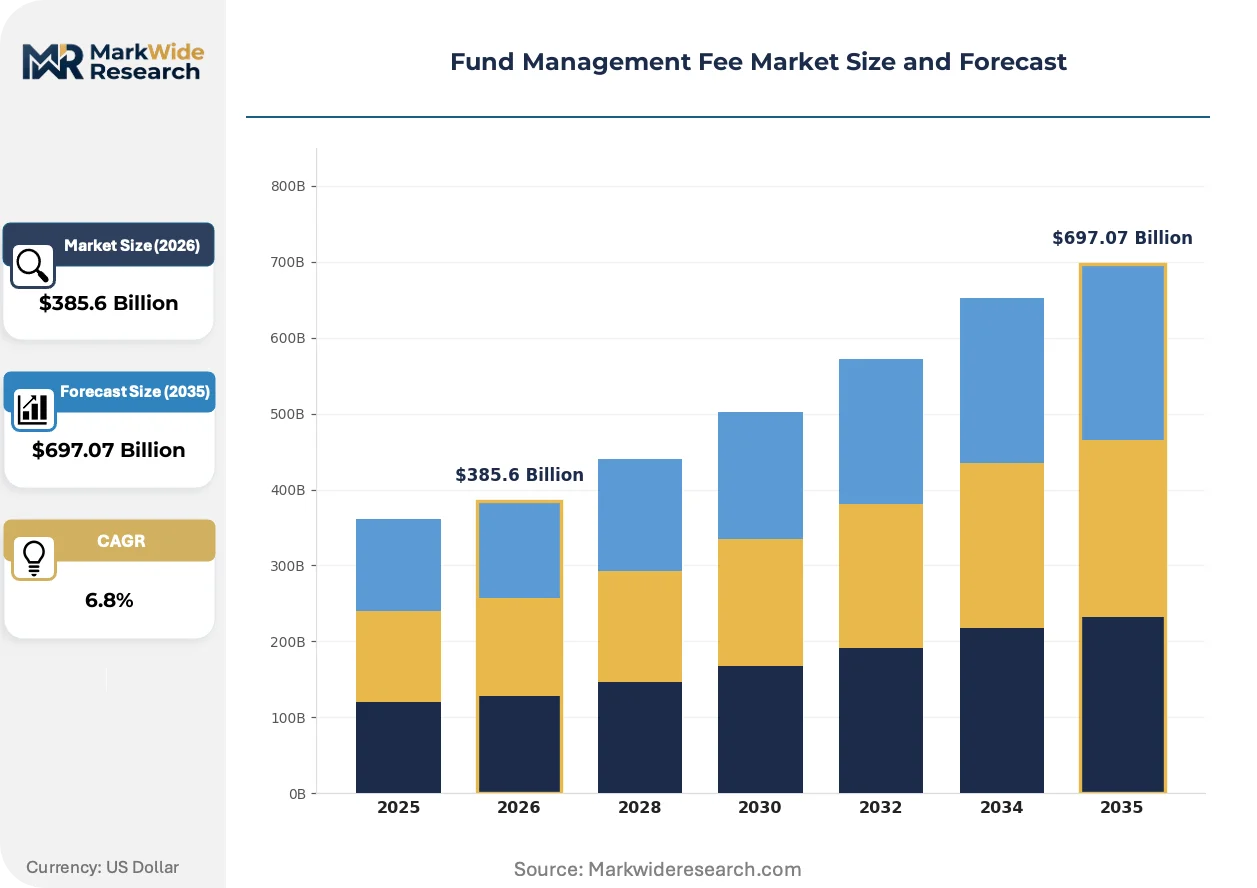
| Market Size in 2026 | $385.6 Billion |
| Market Size in 2035 | $697.07 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fee Structure: Fixed Fee, Performance Fee, Tiered Fee, Flat Fee, Asset-Based Fee Investor Type: High Net Worth Individuals, Family Offices, Institutional Investors, Endowments, Pension Funds Fund Type: Equity Funds, Debt Funds, Hedge Funds, Private Equity, Real Assets Fund Size: Less than $100 Million, $100 Million-$500 Million, $500 Million-$1 Billion, Over $1 Billion |
| Companies Covered | BlackRock Investment Management (UK) Limited, Legal & General Investment Management Limited, Fidelity Worldwide Investment, Baillie Gifford & Co Limited, Jupiter Unit Trust Managers Limited, abrdn Fund Managers Limited, Fundsmith, Invesco, BNY Mellon Fund Managers Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fund Management Fee Market Trends and Innovations
Fee infrastructure is undergoing platformization as asset owners demand granular transparency into every basis point charged across multi-manager portfolios.
API-first fee calculation engines is modularizing how asset servicers deliver waterfall computations, allowing pension funds to plug specialized modules directly into their portfolio accounting systems. Large institutional consultants in the United States and Netherlands are adopting these interfaces to consolidate multi-currency, multi-jurisdictional fee reporting. This architecture is modularizing the competitive landscape by separating calculation logic from custody relationships.
CSRD sustainability disclosure requirements are forcing European managers to attach carbon intensity metrics to every fee schedule, transforming ESG from marketing overlay to contractual pricing component. Asset owners now negotiate penalty clauses for portfolios missing climate transition benchmarks. Private equity funds with European LP bases face the steepest compliance curve as they retrofit waterfall documents with emissions-linked hurdle rates.
Direct indexing platforms are unbundling the traditional mutual fund fee stack by separating security selection from execution and reporting functions. High-net-worth investors in the United States increasingly pay for customization rather than pooled vehicle access, compressing aggregate fee loads while expanding revenue for specialized overlay managers. This fragmentation is most visible among technology sector executives seeking tax-loss harvesting at scale without commingled fund constraints.
Fund Management Fee Market Segmentation
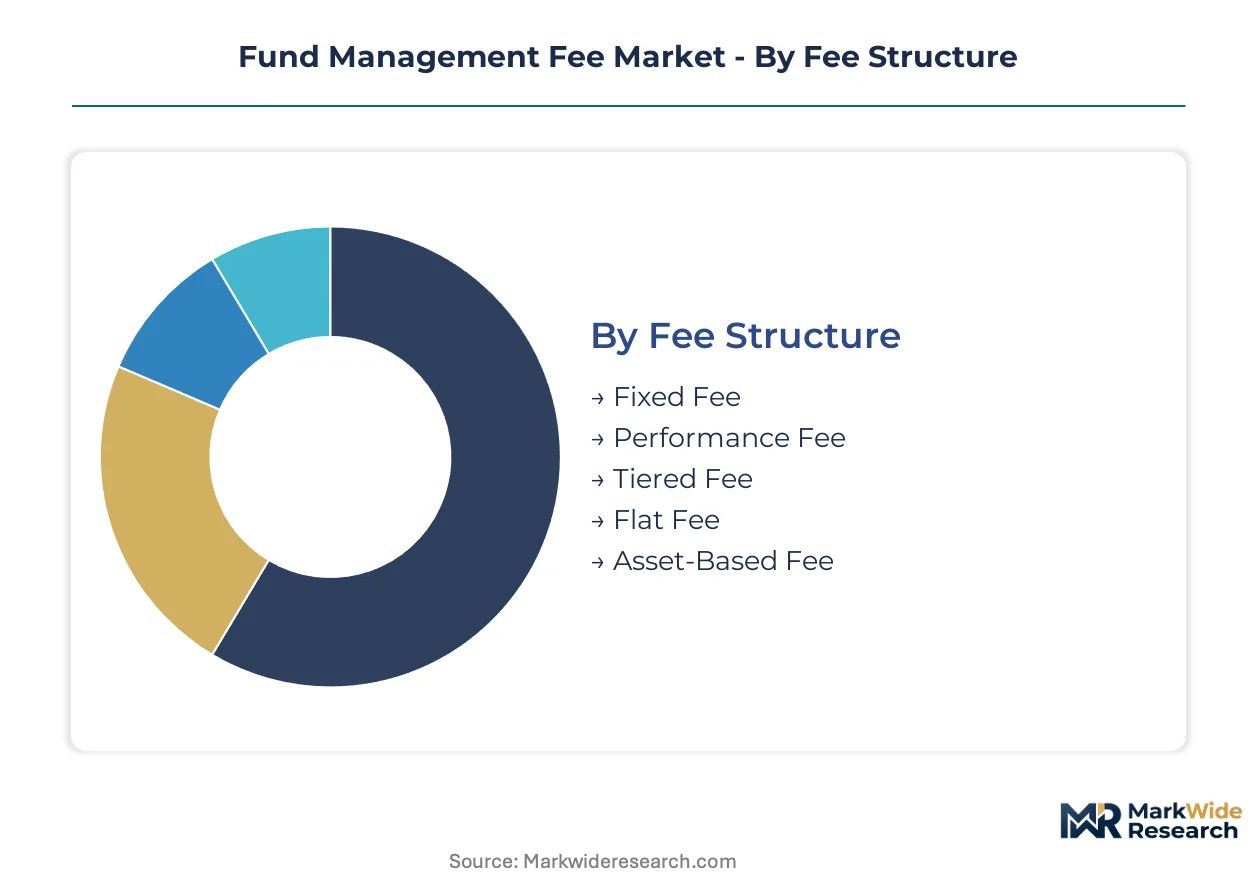
Fee structure heterogeneity determines how asset managers capture value across risk profiles and investor sophistication levels. Segmentation reveals where pricing power concentrates and where competitive pressure forces structural innovation.
Fee Structure:
Investor risk tolerance and performance expectations drive selection among compensation models.
- Fixed Fee:Predictable percentage charges on assets under management dominate pension fund mandates where budget certainty outweighs return variability. United States public sector plans negotiate these structures to align with actuarial liability matching requirements.
- Performance Fee:Incentive compensation tied to benchmark outperformance or absolute return hurdles commands premium economics in hedge fund and private equity vehicles. Crystallization mechanics and high-water mark provisions create complex administrative requirements that sustain specialist service providers.
- Tiered Fee:Sliding scale arrangements reduce marginal rates as assets scale, rewarding long-term capital commitment from large institutional allocators.
- Flat Fee:Nominal fixed-dollar charges per account suit mass-market robo-advisory platforms with standardized portfolio construction.
- Asset-Based Fee:Variable percentage scales tied to portfolio valuation fluctuations align manager incentives with capital preservation objectives in volatile market conditions.
Fixed Fee leads on scale; Performance Fee leads on momentum.
Investor Type:
Capital source characteristics determine fee negotiation leverage and service complexity requirements.
- Institutional Investors:Sovereign wealth funds and insurance company general accounts deploy dedicated procurement teams to extract basis point concessions through competitive tender processes. Their scale concentration in the United States and Netherlands drives industry-wide fee compression benchmarks.
- Pension Funds:Defined-benefit plans with long-duration liabilities prioritize liability-driven investment frameworks that embed performance-linked fee components tied to funding ratio improvement.
- High Net Worth Individuals:Family balance sheets seeking tax optimization and direct indexing customization accept premium pricing for bespoke portfolio construction services.
- Family Offices:Multi-generational wealth structures demand consolidated reporting across alternative asset classes, justifying bundled fee arrangements with specialized administrators.
- Endowments:University and foundation investment offices with perpetual time horizons tolerate illiquidity premiums that support private market fee structures with extended crystallization timelines.
Institutional Investors anchor aggregate fee volume; Family Offices expand most quickly as wealth concentration accelerates.
Fund Type:
Underlying asset class liquidity and complexity differentiate administrative burden and margin potential.
- Private Equity:Carried interest waterfalls with multiple hurdle rates and catch-up provisions require specialized legal and accounting infrastructure. European fundraising faces CSRD-mandated carbon disclosure integration into limited partnership agreements.
- Hedge Funds:High-water mark calculations and multi-period incentive fee accruals demand real-time portfolio accounting systems that support complex crystallization elections.
- Equity Funds:Long-only strategies face acute passive competition that compresses management fees toward single-digit basis point floors.
- Debt Funds:Private credit vehicles with floating-rate benchmarks embed performance components tied to spread capture beyond base rate movements.
- Real Assets:Infrastructure and natural resource funds incorporate inflation-linked fee escalators that preserve manager economics across macroeconomic cycles.
Equity Funds dominate asset-weighted fee generation; Private Equity commands steepest expansion trajectory as capital allocation shifts illiquid.
Fund Size:
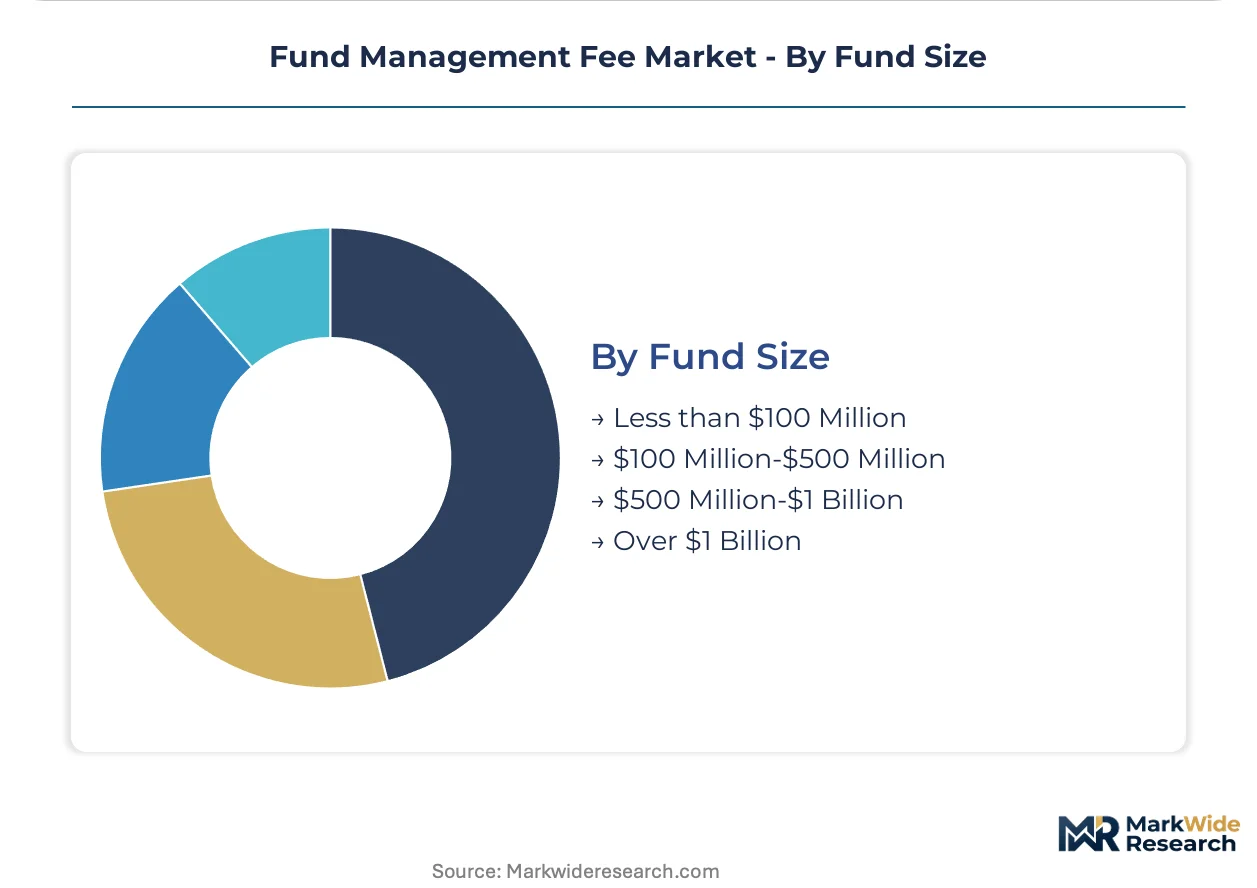
Operational scale thresholds determine whether fixed administrative costs dilute or concentrate per-dollar fee burden.
- Over $1 Billion:Mega-funds achieve operational leverage that supports dedicated investor relations and compliance infrastructure while maintaining competitive net returns. United States buyout vehicles in this category set industry fee benchmarks.
- $500 Million-$1 Billion:Mid-large strategies balance scale economics with investment flexibility, often commanding premium fees for specialized sector or geographic focus.
- $100 Million-$500 Million:Emerging manager mandates from institutional seeding programs accept compressed economics to establish track records.
- Less than $100 Million:Sub-scale vehicles face fixed cost absorption challenges that pressure sustainability without founder fee concessions or outsourced administration.
Over $1 Billion captures institutional capital concentration; $100 Million-$500 Million gains share fastest as emerging manager allocation programs expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Portfolio managers and quantitative analysts cluster in financial centers where regulatory frameworks and institutional capital pools intersect. Talent density in specific cities shapes where fee innovation originates and where pricing power concentrates.
United States
Defined-benefit pension plans in California and New York negotiate tiered fee schedules that compress base rates while expanding performance incentive pools. SEC oversight under Form ADV and the Investment Advisers Act mandates granular fee disclosure that standardizes transparency expectations. Boston and Chicago host concentrated asset servicing infrastructure where custodians modernize legacy calculation engines for real-time reporting.
United Kingdom
Institutional allocators in London and Edinburgh demand ESG-linked pricing frameworks tied to climate-transition benchmarks. The FCA enforces PRIIPs-compliant cost transparency for retail-facing products that reshapes how managers structure bundled arrangements. The City of London remains the dominant European hub for hedge fund administration and complex waterfall engineering.
Germany
Insurance company general accounts in Frankfurt and Munich deploy procurement teams to extract basis point concessions through competitive tender processes. BaFin supervision aligns with EU SFDR disclosure mandates that require sustainability metrics alongside fee schedules. The Frankfurt Main Finance cluster anchors continental European demand for liability-driven investment frameworks.
Netherlands
Pension funds in Amsterdam and Rotterdam pioneered performance-linked fee structures that tie manager compensation to funding ratio improvement. The Dutch central bank and AFM enforce prudent person rules that tighten scrutiny on value-for-money assessments. The Zuidas financial district concentrates European headquarters for institutional consultants adopting API-first fee calculation engines.
Singapore
Sovereign wealth funds and family offices in the city-state negotiate bespoke fee arrangements for alternative asset class exposure. MAS regulatory frameworks govern fund management company licensing that shapes permissible compensation structures. The Marina Bay financial hub serves as the primary Southeast Asian gateway for international managers seeking emerging market mandates.
Fund Management Fee Market Competitive Landscape
Capital-heavy asset servicers compete with asset-light fee analytics specialists for control over fund administration workflows. The vendor base stratifies across three tiers: global custodians with integrated calculation engines, specialized waterfall administrators, and technology platforms offering modular API solutions. Scale-driven consolidation dominates among custody banks seeking operational leverage, while boutique specialists capture premium economics for complex private equity waterfalls. Strategic moves center on technology licensing partnerships and vertical integration into carbon-accounting reporting infrastructure.
Within the UK-based institutional tier, BlackRock Investment Management (UK) Limited and Legal & General Investment Management Limited exemplify scale-driven archetypes that standardize ESG-aligned pricing frameworks across continental mandates. Fidelity Worldwide Investment occupies a position representing the technology-forward segment, integrating carbon accounting tools directly into fee reporting infrastructure. These three entities anchor the competitive landscape where regulatory compliance and fee transparency serve as primary differentiation vectors.
| Leading Market Players |
|---|
| BlackRock Investment Management (UK) Limited |
| Legal & General Investment Management Limited |
| Fidelity Worldwide Investment |
| Baillie Gifford & Co Limited |
| Jupiter Unit Trust Managers Limited |
| abrdn Fund Managers Limited |
| Fundsmith |
| Invesco |
| BNY Mellon Fund Managers Limited |
| Others |
Pricing and Supply Chain Analysis
EU SFDR disclosure mandates gate qualified supply relationships and premium-tier pricing access for European fund managers, forcing asset servicers to embed carbon accounting infrastructure before competing for ESG-linked mandates from Dutch and German institutional allocators.
Pricing Analysis
The bundled-vs-unbundled service split separates traditional custody-integrated fee models from modular API-first calculation engines. Tiered pricing stratifies across premium ESG-aligned, standard active, and economy passive tiers, with differentiation driven by carbon disclosure granularity and real-time reporting capability. Pricing pressure intensifies in the passive tier as single-digit basis point floors eliminate operational margin, while premium ESG mandates sustain elevated fee structures. Pension funds exhibit highest price sensitivity through competitive tender processes; family offices show lowest sensitivity for bespoke direct indexing services.
Supply Chain Analysis
Workforce availability constraints in London, New York, and Singapore determine where complex waterfall engineering talent concentrates for hedge fund and private equity administration. Supply draws from the United Kingdom, United States, and Singapore for quantitative finance expertise, with raw inputs including proprietary portfolio accounting software, regulatory compliance databases, and carbon intensity data feeds. Single-source vulnerability sits with legacy custodian calculation engines that lack modular API architecture. Distribution runs through institutional consultant networks and direct asset owner procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a geographic-arbitrage play between EU SFDR-mandated disclosure costs and lighter-touch Asian regulatory frameworks, with Singapore offering lower compliance overhead for managers serving cross-border emerging market mandates.
For Market Incumbents: Cement dominance in European ESG-linked mandates by retrofitting legacy calculation engines with real-time carbon accounting modules before CSRD deadlines tighten. Acquire specialized waterfall engineering boutiques in London to capture scarce quantitative talent. Defensive priority rests on preventing modular API providers from disintermediating custody relationships.
For New Entrants and Emerging Players: Capture white-space in India's National Pension System by developing locally compliant fee structures for international managers seeking emerging market exposure. Target mid-sized Dutch pension funds with hybrid robo-advisory platforms combining algorithmic construction with human overlay. Go-to-market angle centers on API-first modular pricing that plugs directly into existing portfolio accounting systems.
For Investors and Strategic Acquirers: Roll-up economics work for specialized waterfall administrators because fragmented custody relationships create multiple standalone targets with complementary geographic footprints. Long-term viability across the analysis window favors platforms with demonstrated carbon-accounting integration and European LP access. Watch for inflection when Dutch and German pension funds consolidate administrator relationships into single-platform mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon-Accounting Infrastructure Integration | Captures CSRD-compliant mandates from European institutional allocators requiring Scope 3 disclosure. |
| API-First Fee Calculation Engine Development | Enables direct plug-in to pension fund portfolio accounting systems in Amsterdam and Rotterdam. |
| Specialized Waterfall Engineering Acquisition | Secures scarce quantitative talent for private equity carried interest mechanics in London. |
| India NPS Local Compliance Buildout | Positions for asset growth in emerging market pension system expansion. |
| Hybrid Robo-Advisory Platform Launch | Creates untapped fee models combining algorithmic construction with human advisor overlay. |
Research Methodology
Bottom-up institutional allocator modeling reconciled against top-down asset servicer capacity tracking forms the analytical core. Primary interviews with pension fund procurement officers, hedge fund CFOs, regulatory compliance leads, and institutional consultants combined with secondary validation from SEC Form ADV filings, AFM supervisory disclosures, EU SFDR regulatory texts, and Dutch central bank prudent person guidance. Triangulation across stakeholder perspectives and documentary sources ensures coverage of both disclosed fee schedules and negotiated concession structures.
Input-output matrices map fee structure adoption across investor type, fund vehicle, and geographic regulatory cluster dimensions throughout the forecast period. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific forecast inputs include pension fund AUM growth trajectories, regulatory compliance cost pass-through assumptions, and technology platform substitution elasticities for legacy custody relationships.
Underlying measurement precision varies by segment; institutional investor and pension fund fee disclosures carry tighter precision than family office and high-net-worth individual arrangements where bespoke negotiations obscure standardization. Forecasts reflect assumptions around regulatory implementation timelines and technology adoption curves. Material deviation in EU SFDR enforcement intensity or SEC fiduciary duty interpretation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Asset Management
Asset Optimization Solutions Market
Asset Management
Asia-Pacific Utilities Asset Management Market
Asset Management
Healthcare Asset Management Market
Asset Management
Global AI in Asset Management Market
Asset Management
US Pension Funds Market
Asset Management
Global Remote Asset Management Market
Asset Management
Fund Management Software Market
Asset Management
Global Infrastructure Asset Management Market
Asset Management
Mutual Fund Assets Market
Asset Management
US Asset Management Market
Asset Management
UK Asset Management Market
Asset Management
Capital Expenditure Market
Asset Management
LAMEA Equity Management Software Market
Asset Management
Equity Management Tool Market
Asset Management
Europe Asset Management Market
Asset Management
India AMC Industry Market