
 Fund Management Software Market | 2026-2036
Fund Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Fund Management Software Market Insights
API-first architecture is reconfiguring how portfolio data flows between custodians, accounting engines, and client portals. Envestnet leverages its open-API ecosystem to embed financial wellness tools across third-party wealth platforms. Addepar anchors its position through proprietary data aggregation technology that normalizes illiquid asset valuations across multi-currency portfolios. SS&C Black Diamond competes through deep custody-bank integrations that reduce manual reconciliation workloads for mid-sized advisers.
Fund management software encompasses applications that automate portfolio construction, risk analytics, regulatory reporting, and trade execution for institutional and retail asset managers. Core systems typically integrate real-time market data feeds, position-level accounting, and client-specific compliance rule engines to support investment decision workflows across public and private asset classes. Cloud-based deployment leads segment expansion as sovereign wealth funds and pension funds migrate off aging on-premise installations to reduce infrastructure overhead. Portfolio management and risk management solutions command the deepest margin pools, while compliance tracking is accelerating fastest as SEC, FCA, and ECB disclosure requirements tighten.
The SEC enforces investment adviser regulations requiring automated custody rule monitoring, while the EU's CSRD mandates granular sustainability disclosure that fund software must tag and report. The FCA's operational resilience rules in the United Kingdom further shape vendor roadmaps by mandating recovery-time objectives for critical portfolio systems. Stakeholders must weigh whether to build proprietary data layers or rely on vendor-managed compliance updates as regulatory fragmentation intensifies across jurisdictions.
Market Dynamics
Cloud-native migration is compressing deployment timelines for portfolio management systems as asset managers dismantle decade-old on-premise installations. The SEC's custody rule amendments are forcing synchronous upgrades to compliance modules, creating procurement windows that vendors must synchronize with infrastructure refresh cycles.
Growth Catalysts
- SEC Custody Rule Revisions:United States registered investment advisers must deploy automated monitoring systems by mandated deadlines, accelerating replacement of spreadsheet-based compliance workflows.
- API-First Architecture:Open banking standards and custodian data feeds are enabling real-time portfolio reconciliation that eliminates overnight batch processing delays.
- Family Office Proliferation:Single-family and multi-family offices in the United States are consolidating fragmented software stacks into unified platforms for illiquid asset tracking.
Market Restraints
- Data Migration Complexity:Decades of position-level accounting history in legacy systems creates extraction risks that prolong implementation timelines and inflate professional services costs.
- Specialized Talent Scarcity:Firms struggle to hire engineers fluent in both financial instrument data models and modern cloud infrastructure, particularly in secondary technology hubs.
- Regulatory Fragmentation:Divergent disclosure requirements across SEC, FCA, and ECB jurisdictions force vendors to maintain parallel compliance engines, diluting R&D concentration.
Strategic Opportunities
- Private Markets Expansion:Fund administrators serving private equity and venture capital funds require automated waterfall distribution calculations that generalist platforms cannot execute.
- ESG Data Integration:The EU's CSRD mandates granular sustainability tagging that creates demand for embedded carbon accounting and SFDR-aligned reporting modules.
- Embedded Finance Channels:Retail brokerage platforms are white-labeling portfolio analytics for mass-affluent segments previously served only by human advisers.
Industry Challenges
- Interoperability Debt:Point solutions accumulated through years of tactical procurement resist unified data models, forcing expensive middleware development for cross-system workflows.
- Cybersecurity Certification Burden:SOC 2 Type II and ISO 27001 attestations require continuous audit cycles that consume engineering resources otherwise directed toward feature development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fund Management Software Market |
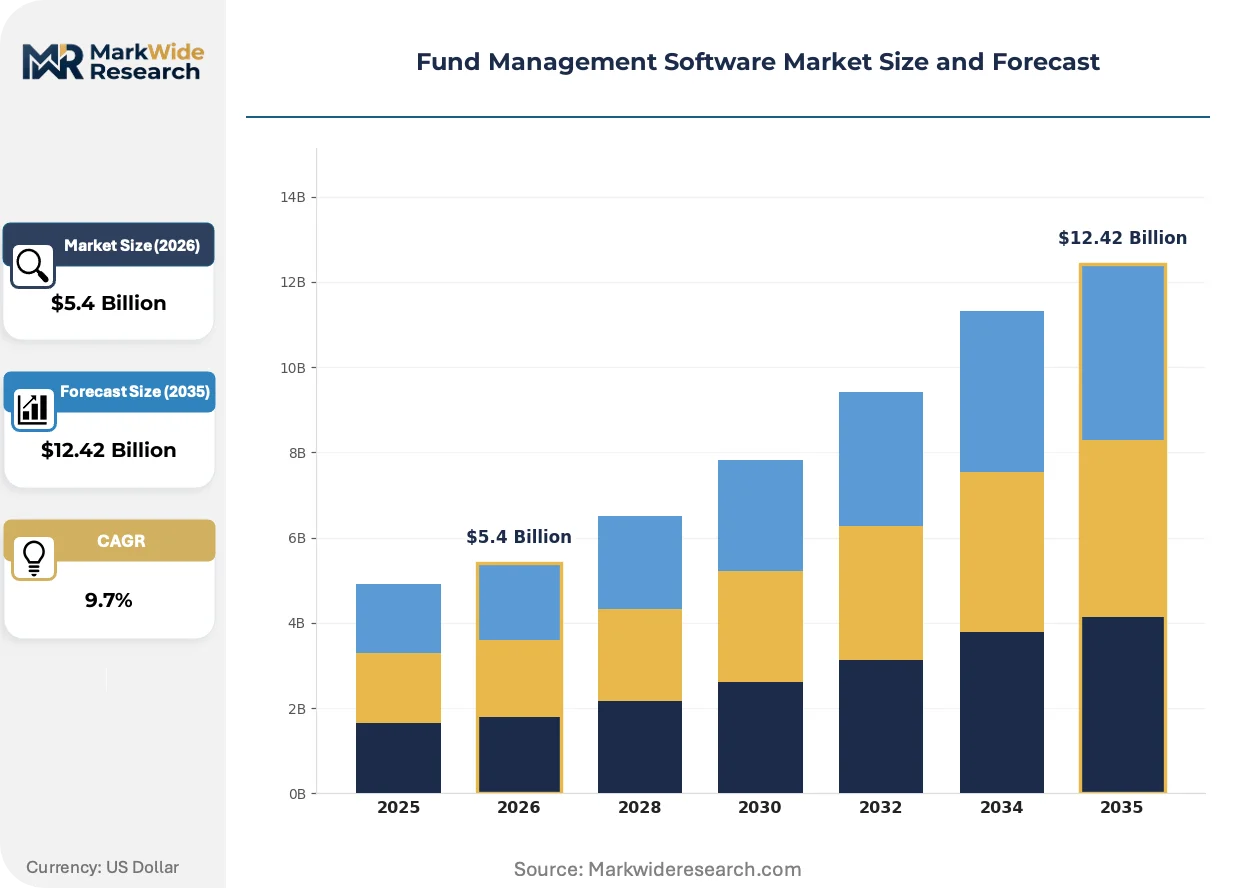
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $12.42 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Hosted, SaaS Solution Type: Portfolio Management, Risk Management, Compliance Tracking, Reporting & Analytics, Trade Order Management End User: Hedge Funds, Pension Funds, Family Offices, Sovereign Wealth Funds, Asset Management Firms Pricing Model: Subscription-Based, Perpetual License, Usage-Based, Freemium, Enterprise Licensing |
| Companies Covered | Envestnet, Orion, Addepar, eFront, Dynamo Software, SS&C Black Diamond, SimCorp, Allvue Systems, Masttro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fund Management Software Market Trends and Innovations
Generative AI is infiltrating investment research workflows while blockchain-based settlement experiments are compressing reconciliation cycles. Vendors are racing to embed these capabilities without destabilizing core accounting engines that process trillions in daily transactions.
Embedded analytics is hybridizing portfolio visualization by embedding interactive dashboards directly into custodian portals and client-facing applications. Family offices and registered investment advisers are adopting these capabilities fastest, replacing standalone reporting tools that required manual data exports. This architecture is compressing vendor margins by reducing the addressable market for discrete reporting modules.
The EU's CSRD is mandating machine-readable sustainability disclosures that fund software must tag at the position level. Asset managers operating across European jurisdictions are reconfiguring data pipelines to capture Scope 3 emissions and supply chain exposures previously excluded from portfolio analytics. Mid-sized fund administrators without dedicated ESG infrastructure are outsourcing compliance module updates to specialized vendors.
Consolidated platform procurement is displacing best-of-breed purchasing as chief technology officers prioritize vendor reduction over feature depth. United States-based registered investment advisers are consolidating from six to eight discrete systems onto two to three integrated platforms, accepting functional trade-offs for operational simplicity. This concentration is strengthening incumbents with broad module coverage while marginalizing point-solution specialists.
Fund Management Software Market Segmentation
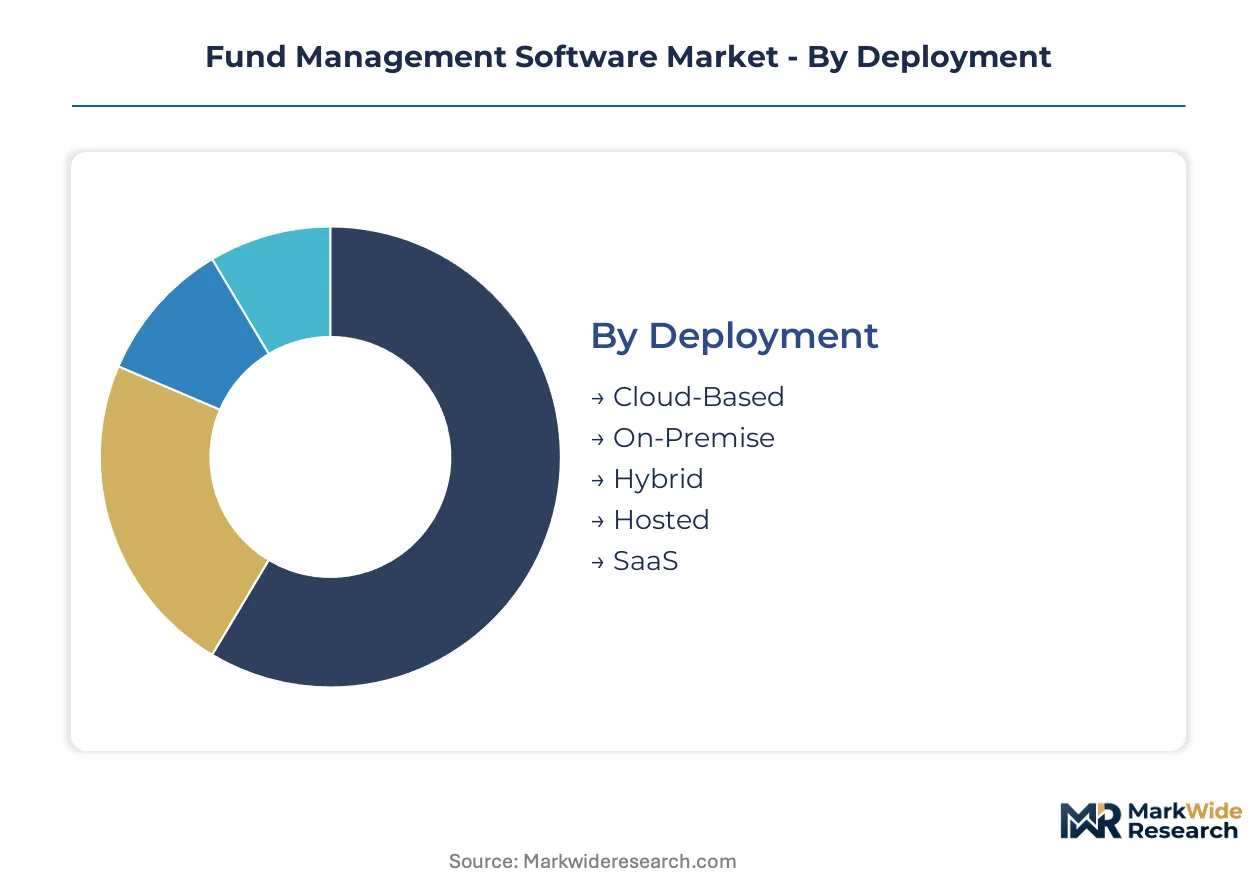
Segmentation in fund management software reveals how procurement cycles, compliance mandates, and infrastructure maturity create divergent vendor economics across deployment modes and customer archetypes. Understanding these fault lines clarifies where platform consolidation will accelerate versus where specialized modules retain pricing power.
Deployment:
Cloud-native architectures compress implementation timelines from years to quarters, while legacy on-premise estates generate the longest-tail maintenance revenue pools.
- Cloud-Based:Multi-tenant architectures enable sovereign wealth funds and pension funds to retire decade-old data centers without capital expenditure spikes. United States family offices are migrating fastest, driven by SEC custody rule deadlines that demand elastic scaling for automated compliance monitoring.
- SaaS:Pre-configured workflows reduce professional services dependency for mid-sized asset managers with limited IT staff. Demand concentrates among registered investment advisers seeking rapid deployment without infrastructure overhead, though data residency requirements in European jurisdictions slow adoption there.
- Hybrid:Sensitive position data remains on-premise while analytics workloads shift to cloud, satisfying risk committees at hedge funds with proprietary strategies.
- On-Premise:Aging installations at large pension funds generate maintenance revenue but face replacement pressure from cloud cost advantages.
- Hosted:Single-tenant cloud deployments appeal to asset managers with customized integrations that resist multi-tenant standardization.
Cloud-Based solutions anchor the volume base while SaaS gains share at the steepest rate.
Solution Type:
Margin profiles diverge sharply between commoditized reporting modules and proprietary risk engines requiring quantitative research investment.
- Portfolio Management:Core position-keeping and performance attribution systems command the deepest integration moats, with switching costs amplified by decades of historical data. United States asset management firms modernizing legacy infrastructure represent the primary demand concentration, though implementation timelines stretch to 18 months for complex multi-currency portfolios.
- Compliance Tracking:Automated rule engines for SEC custody monitoring and EU CSRD sustainability disclosure are expanding most quickly as regulatory deadlines force synchronous procurement. Mid-sized fund administrators without dedicated legal technology staff outsource module updates to specialized vendors.
- Risk Management:VaR and stress testing platforms require quantitative expertise that concentrates vendor differentiation among tier-one institutions.
- Trade Order Management:Execution algorithms and best-execution documentation face margin pressure from embedded brokerage offerings.
- Reporting & Analytics:Dashboard visualization is commoditizing as custodians embed analytics directly into client portals, compressing standalone module pricing.
Portfolio Management systems capture the largest revenue share while Compliance Tracking climbs fastest.
End User:
Technology sophistication and procurement autonomy vary dramatically between regulated institutional pools and agile private wealth structures.
- Asset Management Firms:Diverse product ranges spanning mutual funds, ETFs, and separate accounts demand modular platforms with deep customization capabilities. These institutions drive the largest contract values but impose lengthy vendor evaluation cycles exceeding 12 months for core system replacement.
- Family Offices:Single-family and multi-family offices in the United States are consolidating fragmented software stacks to track illiquid private market positions alongside liquid portfolios. Their procurement autonomy enables rapid decisions compared to committee-governed institutions, though smaller scale limits per-client revenue.
- Hedge Funds:Proprietary trading strategies require specialized risk analytics and prime brokerage integrations that generalist platforms cannot satisfy.
- Pension Funds:Fiduciary oversight committees prioritize vendor stability and SOC 2 certification over feature velocity, extending sales cycles.
- Sovereign Wealth Funds:Long investment horizons and political governance structures create unique workflow requirements around stakeholder reporting.
Asset Management Firms dominate absolute spending while Family Offices expand their vendor footprint most aggressively.
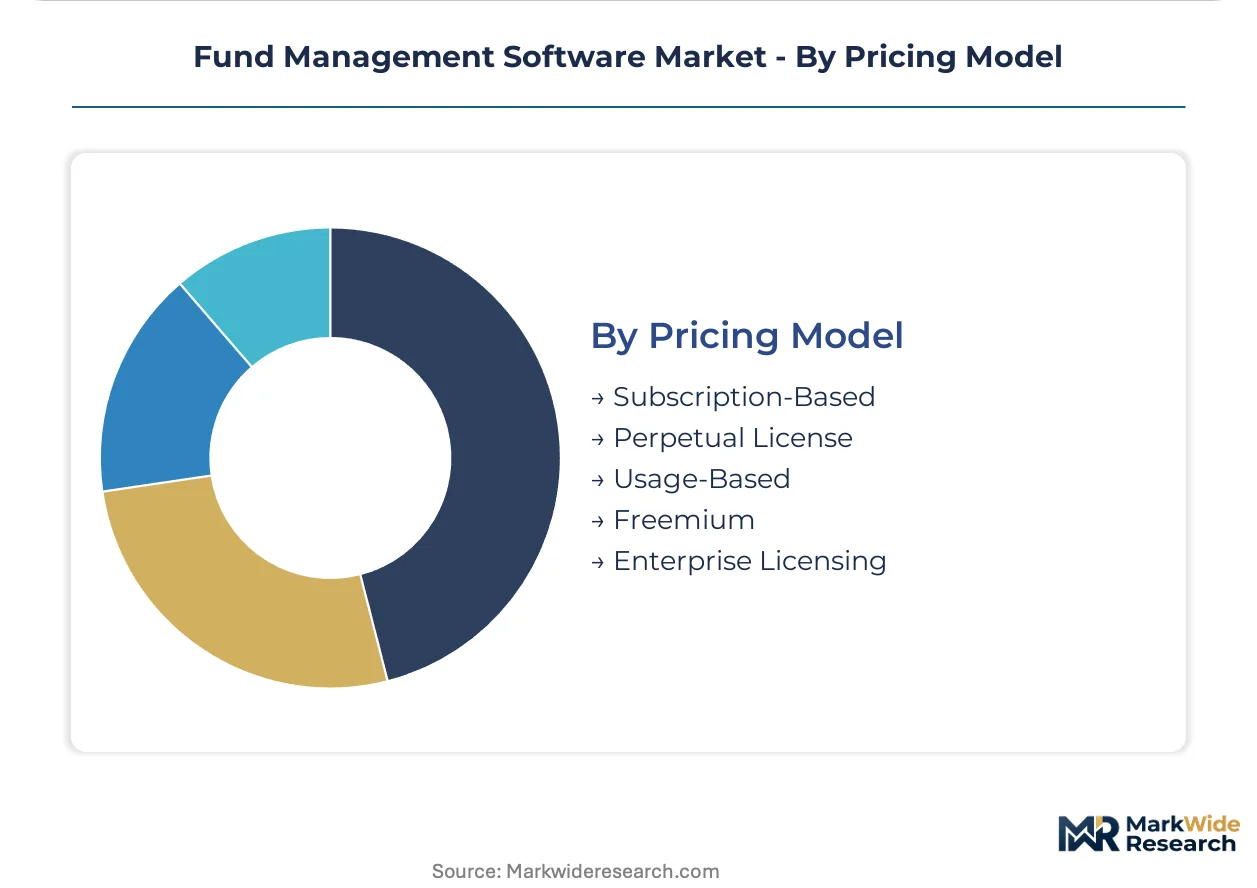
Pricing Model:
Revenue predictability and customer lifetime value trade off against upfront cash flow and implementation friction.
- Subscription-Based:Annual recurring revenue models align vendor incentives with ongoing customer success, reducing churn through embedded workflow dependency. United States registered investment advisers favor this structure for operational expenditure treatment and predictable budgeting.
- Enterprise Licensing:Unlimited-user contracts capture value from large asset managers with thousands of investment professionals, though sales cycles extend to 18-24 months and require executive sponsorship.
- Perpetual License:Upfront payment with maintenance streams appeals to capital-rich institutions preferring balance sheet treatment over ongoing obligations.
- Usage-Based:Transaction or position-count pricing aligns costs with scale for growing fund administrators with variable AUM.
- Freemium:Limited-feature entry tiers attract emerging family offices and small hedge funds, with conversion rates determining unit economics viability.
Subscription-Based contracts constitute the revenue foundation while Enterprise Licensing captures the highest individual deal values.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a substantial trade surplus in fund management software exports, shipping cloud-native portfolio platforms to European asset managers while importing specialized risk analytics modules from London and Zurich. Cross-border data flows now determine competitive positioning more than physical manufacturing footprints.
United States
Family offices and registered investment advisers in New York and Boston are dismantling decade-old on-premise installations for elastic cloud architectures. The SEC's custody rule amendments mandate automated compliance monitoring by specific deadlines, forcing synchronous procurement cycles. Manhattan's fintech corridor hosts the densest concentration of portfolio analytics vendors serving mid-sized advisers.
United Kingdom
London-based hedge funds require specialized prime brokerage integrations that generalist platforms cannot satisfy, sustaining demand for bespoke risk engines. The FCA's operational resilience rules mandate recovery-time objectives for critical portfolio systems, shaping vendor development roadmaps. The City of London cluster concentrates custody-bank technology partnerships that reduce manual reconciliation workloads.
Germany
Asset managers in Frankfurt and Munich are reconfiguring data pipelines to capture EU CSRD-mandated sustainability disclosures at the position level. The Bundesbank's oversight of systemic risk reporting influences software requirements for institutional investors. Bavaria's private banking hub drives adoption of unified platforms consolidating fragmented illiquid asset tracking.
Switzerland
Geneva and Zurich private banks demand multi-currency portfolio normalization for ultra-high-net-worth clients with complex cross-border holdings. FINMA's enhanced due diligence requirements for wealth managers accelerate compliance module procurement. The Lake Geneva region concentrates family office technology spending on embedded analytics replacing standalone reporting tools.
Singapore
Sovereign wealth funds and pension funds are migrating off aging data centers to reduce infrastructure overhead while maintaining data residency controls. The Monetary Authority of Singapore's technology risk management guidelines shape vendor selection criteria for critical systems. The Marina Bay financial district anchors Southeast Asia's fastest-growing concentration of cloud-native portfolio management deployments.
Fund Management Software Market Competitive Landscape
On the supply side, the industry is consolidating around integrated platform providers as chief technology officers prioritize vendor reduction over feature depth. Tier-one incumbents with broad module coverage capture expanding contract values while point-solution specialists face margin compression. Three strategic archetypes dominate: custody-integrated incumbents, API-native challengers, and private-market specialists. Competitive moves concentrate on M&A for data aggregation capabilities and strategic partnerships for embedded finance distribution.
Within the custody-integrated tier, SS&C Black Diamond and SimCorp exemplify vendors leveraging deep banking relationships to reduce reconciliation friction for mid-sized advisers. Addepar occupies a distinct position among data-aggregation specialists, normalizing illiquid asset valuations across multi-currency portfolios. These three companies represent how vendor economics diverge between infrastructure-heavy incumbents and agile challengers targeting family office proliferation.
| Leading Market Players |
|---|
| Envestnet |
| Orion |
| Addepar |
| eFront |
| Dynamo Software |
| SS&C Black Diamond |
| SimCorp |
| Allvue Systems |
| Masttro |
| Others |
Pricing and Supply Chain Analysis
Manhattan's fintech corridor concentrates cloud-native development capacity, creating asymmetric pricing power for vendors serving mid-sized registered investment advisers while legacy on-premise providers absorb margin compression from infrastructure overhead.
Pricing Analysis
Legacy on-premise installations command premium maintenance fees while cloud-native SaaS tiers undercut through multi-tenant efficiency, and next-generation API-first platforms embed usage-based metering that scales with position volume. Subscription-based contracts dominate among United States family offices seeking operational expenditure treatment, though enterprise licensing retains pricing power at asset managers with thousands of seats. Price differentiation hinges on SOC 2 certification tier and depth of custodian integration, with uncertified point solutions facing the steepest erosion. Margins are tightening for standalone reporting modules as custodians embed analytics directly into client portals.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk for hardware-dependent hosted deployments, though pure software vendors remain insulated. Development capacity concentrates in the United States, the United Kingdom, and India, with engineering talent scarcity in secondary hubs prolonging implementation timelines. Cloud infrastructure draws from hyperscaler data centers in Virginia, Frankfurt, and Singapore, with regulatory data residency requirements fragmenting deployment architectures. Single-source vulnerability exists for specialized financial data feeds from Bloomberg and Refinitiv. Distribution runs through direct enterprise sales teams supplemented by systems integrators serving mid-market asset managers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
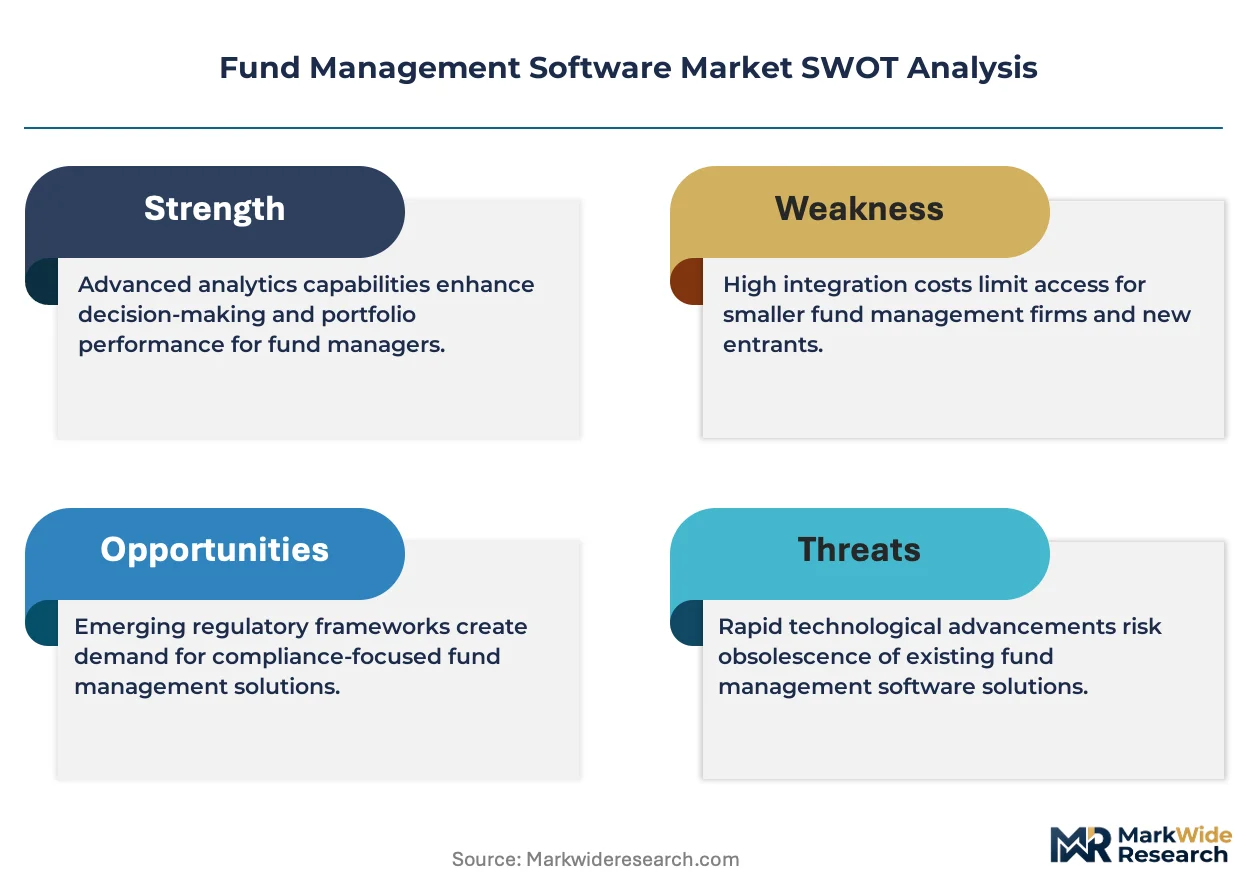
Fragmentation across compliance jurisdictions creates niche opportunities for specialized vendors as SEC, FCA, and ECB mandates diverge, preventing platform consolidation from capturing the full addressable market.
For Market Incumbents: Entrench custody-bank integration moats by deepening partnerships with State Street and BNY Mellon while acquiring data aggregation specialists to neutralize Addepar's illiquid asset normalization advantage. SOC 2 Type II certification investment represents the critical defensive lever as cybersecurity attestation becomes table stakes for pension fund procurement committees.
For New Entrants and Emerging Players: Southeast Asian family offices present the most penetrable white-space target, with Singapore's regulatory sandbox enabling rapid deployment without legacy migration burdens. Private equity waterfall automation offers a narrow entry wedge that generalist platforms cannot execute. A channel partnership strategy with regional fund administrators accelerates credibility building before direct sales investment.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors API-native challengers with embedded finance distribution over infrastructure-heavy incumbents facing cloud transition costs. Long-term viability across the analysis window rests on data layer control rather than application functionality alone. The signal to watch is custodian portal consolidation, which would compress standalone reporting module addressable market by embedding analytics upstream.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Data Aggregation Specialist | Normalizes illiquid asset valuations across multi-currency portfolios for family office clients. |
| Embedded Finance Partnership | White-labels portfolio analytics through retail brokerage platforms serving mass-affluent segments. |
| SOC 2 Type II Certification Investment | Satisfies pension fund procurement requirements for operational resilience attestation. |
| CSRD Compliance Module Development | Captures EU-mandated sustainability disclosure demand from asset managers with European exposure. |
| Private Markets Expansion | Automates waterfall distribution calculations for private equity and venture capital fund administrators. |
Research Methodology
Initial hypotheses were tested against primary input from chief technology officers at asset management firms, compliance officers at registered investment advisers, procurement leads at family offices, and integration specialists at systems integrators and refined through secondary validation against SEC regulatory filings, FCA operational resilience guidance, EU CSRD technical standards, and vendor SEC 10-K disclosures. Bottom-up deployment model sizing was triangulated against top-down addressable market estimates derived from AUM growth projections.
Demand-supply balance across the projection horizon was modeled through segmentation across deployment architecture, solution type, end-user category, and regional regulatory cluster. CAGRs were derived from trend extrapolation of cloud migration velocity and compliance mandate implementation timelines. Industry-specific inputs included SEC custody rule deadline schedules and EU sustainability disclosure phase-in requirements.
The forecast holds incumbent behavior within observed patterns; aggressive moves by API-native challengers or hyperscaler platform entrants would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Asset Management
Asia-Pacific Utilities Asset Management Market
Asset Management
US Asset Management Market
Asset Management
China Mutual Funds Market
Asset Management
Fixed Income Asset Management Market
Asset Management
Hardware Asset Management Market
Asset Management
US Pension Funds Market
Asset Management
Global Remote Asset Management Market
Asset Management
Canada Pension Fund Market
Asset Management
Global AI in Asset Management Market
Asset Management
Canada Asset Management Market
Asset Management
Asset and Wealth Management Market
Asset Management
India Mutual Fund Market
Asset Management
India Asset Management Market
Asset Management
UK Asset Management Market
Asset Management
Fund Management Fee Market
Asset Management
Assets Under Management Market