
 Global Remote Asset Management Market | 2026-2036
Global Remote Asset Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Remote Asset Management Market Foresight
A shift from siloed on-premise systems to multi-vendor cloud architectures is hardening as the dominant sourcing pattern across industrial buyers. Siemens AG leverages its factory automation heritage to anchor large-scale deployments in European manufacturing corridors. Cisco Systems Inc. competes through edge networking dominance, while IBM Corporation differentiates via AI-driven analytics layers integrated with enterprise ERP stacks.
Remote asset management encompasses the centralized monitoring, diagnostics, and optimization of physical equipment through networked sensor arrays, telemetry protocols, and software platforms that process operational data at latencies under 50 milliseconds for critical control loops. Its primary commercial purpose is to replace scheduled maintenance with condition-based interventions, thereby extending asset life and reducing catastrophic failure incidence. Predictive maintenance commands the largest solution-type revenue pool due to its direct linkage with production continuity economics, while edge computing is displacing pure cloud architectures in latency-sensitive applications such as automated manufacturing lines and grid stabilization systems. Asset tracking solutions sustain premium pricing in transportation systems where regulatory audit trails for hazardous materials mandate immutable location records.
The U.S. FCC governs spectrum allocation for industrial IoT transmissions, while the EU AI Act imposes conformity assessment obligations on automated decision systems embedded in remote diagnostics platforms. Japan's METI drives standardization through its Society 5.0 framework, which mandates interoperability across vendor ecosystems in smart factory deployments. Stakeholders must evaluate whether their data governance architectures satisfy divergent jurisdictional requirements before scaling cross-border asset networks.
Market Dynamics
Industrial buyers are consolidating vendor relationships around platforms that unify predictive maintenance, edge analytics, and compliance reporting into single operational dashboards. This procurement compression favors suppliers with pre-certified architectures that satisfy both EU AI Act algorithmic transparency mandates and U.S. FCC spectrum licensing requirements.
Growth Catalysts
- EU AI Act Conformity Assessments:Automated diagnostic systems in German automotive plants now require documented algorithmic accountability, creating replacement demand for auditable remote monitoring platforms.
- Japan METI Society 5.0 Interoperability Mandates:Smart factory deployments in Osaka and Nagoya industrial corridors must demonstrate cross-vendor data exchange, accelerating standardization of telemetry protocols.
- Condition-Based Maintenance Economics:Steel and chemical processing facilities in the U.S. Gulf Coast are retiring calendar-based service contracts in favor of sensor-triggered interventions that reduce catastrophic failure rates.
Market Restraints
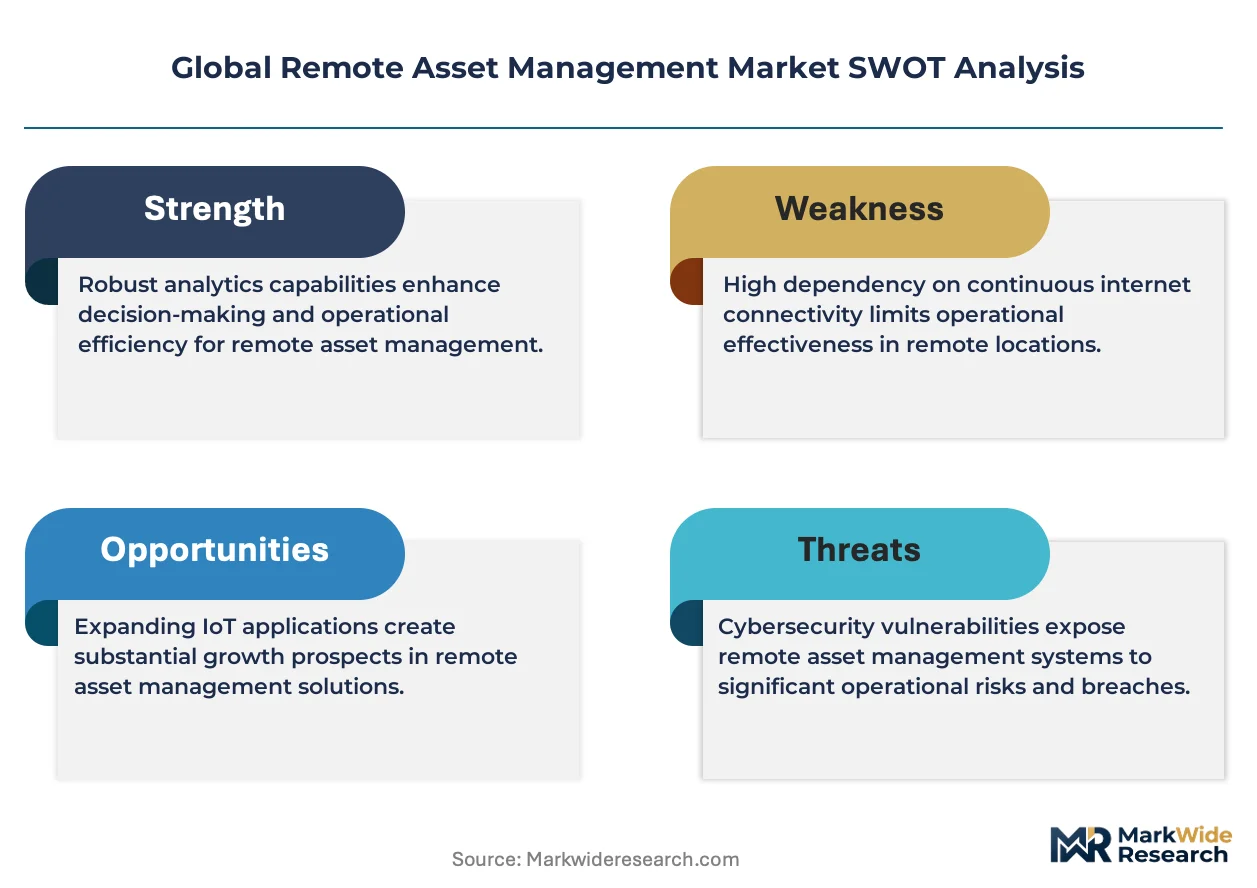
- Semiconductor Component Concentration:Industrial-grade sensor microcontrollers face supply tightness from concentrated East Asian foundry capacity, extending lead times for telemetry hardware.
- Legacy System Integration Costs:Brownfield manufacturing sites in the U.S. Rust Belt require substantial capital outlay to retrofit proprietary SCADA architectures with IP-native remote management layers.
- GDP Jurisdictional Friction:Cross-border asset networks spanning Germany and Switzerland encounter divergent data localization requirements that complicate centralized platform architectures.
Strategic Opportunities
- India Smart Manufacturing PLI Incentives:Production-linked incentive schemes for electronics and automotive component makers are subsidizing first-time remote asset management adoption in Pune and Chennai industrial zones.
- Digital Twin Convergence:Physics-based simulation engines are merging with live telemetry streams to enable pre-failure modeling in wind turbine and railway rolling stock applications.
- 5G Private Network Deployments:Licensed spectrum allocations for industrial campuses in South Korea and Germany are enabling sub-10-millisecond control loops that cloud-only architectures cannot satisfy.
Industry Challenges
- Industrial Cybersecurity Skill Scarcity:OT security architecture expertise remains concentrated among a limited pool of specialists capable of securing converged IT-OT networks.
- Multi-Vendor Certification Timelines:Platform providers must navigate sequential conformity assessments under EU AI Act, IEC 62443, and sector-specific rail or aviation safety standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Remote Asset Management Market |
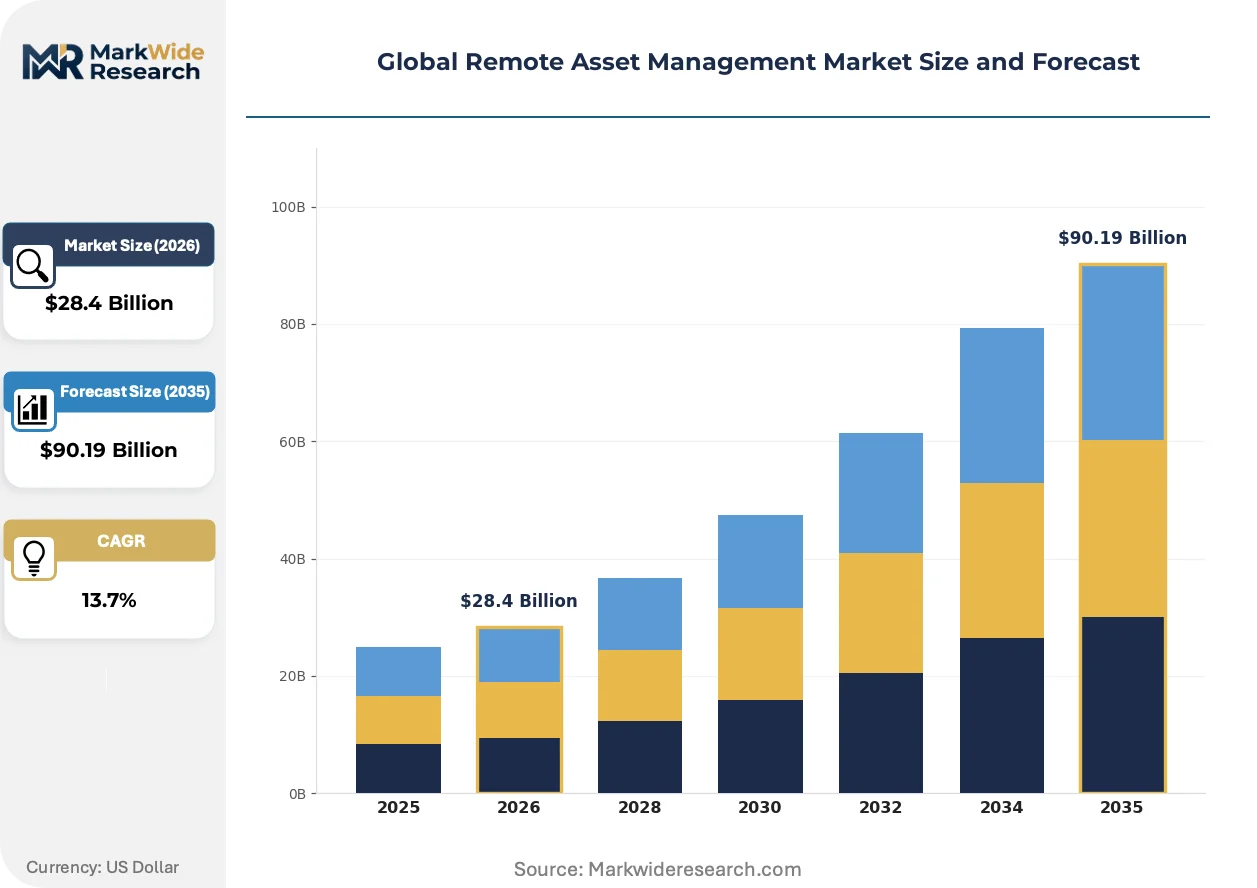
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $90.19 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Predictive Maintenance, Condition Monitoring, Inventory Management, Asset Tracking, Compliance Management Technology: IoT Sensors, Cloud Computing, Artificial Intelligence, Edge Computing, Blockchain Application: Manufacturing Plants, Energy Facilities, Transportation Systems, Smart Cities, Infrastructure Management End User Industry: Heavy Machinery Operators, Telecom Providers, Public Utilities, Construction Firms, Data Centers |
| Companies Covered | Siemens AG, Cisco Systems Inc., IBM Corporation, Schneider Electric, AT&T, Hitachi Ltd., SAP SE, PTC Inc., Rockwell Automation Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Remote Asset Management Market Shifts & Advancements
Edge-native processing architectures are compressing decision latencies below cloud-reachable thresholds, while regulatory frameworks on both sides of the Atlantic harden compliance requirements for automated industrial systems. These forces are reshaping how telemetry data flows from sensor to action.
Digital twin technology is automating the translation of real-time vibration, thermal, and electrical signature data into predictive failure models without human intermediate analysis. Siemens and Schneider Electric are embedding these capabilities into their factory automation portfolios for European automotive and food processing clients. The technology is automating maintenance scheduling decisions that previously required specialist interpretation, compressing response windows from days to minutes.
The EU AI Act's risk classification system imposes conformity assessment obligations on remote diagnostic platforms that automate operational decisions affecting worker safety or environmental compliance. Industrial software vendors must now document training data provenance and algorithmic performance metrics before deploying in German chemical or French nuclear facilities. European manufacturing corridors are responding by demanding pre-certified platform modules that accelerate deployment timelines.
Asset-intensive buyers are unbundling hardware procurement from analytics subscriptions, treating sensor infrastructure as capital expenditure while negotiating usage-based pricing for predictive algorithms. This bifurcation disrupts traditional bundled licensing models and pressures vendors to demonstrate standalone software value. The pattern is most pronounced in U.S. oil and gas and Japanese precision manufacturing sectors where procurement teams have matured their vendor evaluation capabilities.
Global Remote Asset Management Market Segmentation
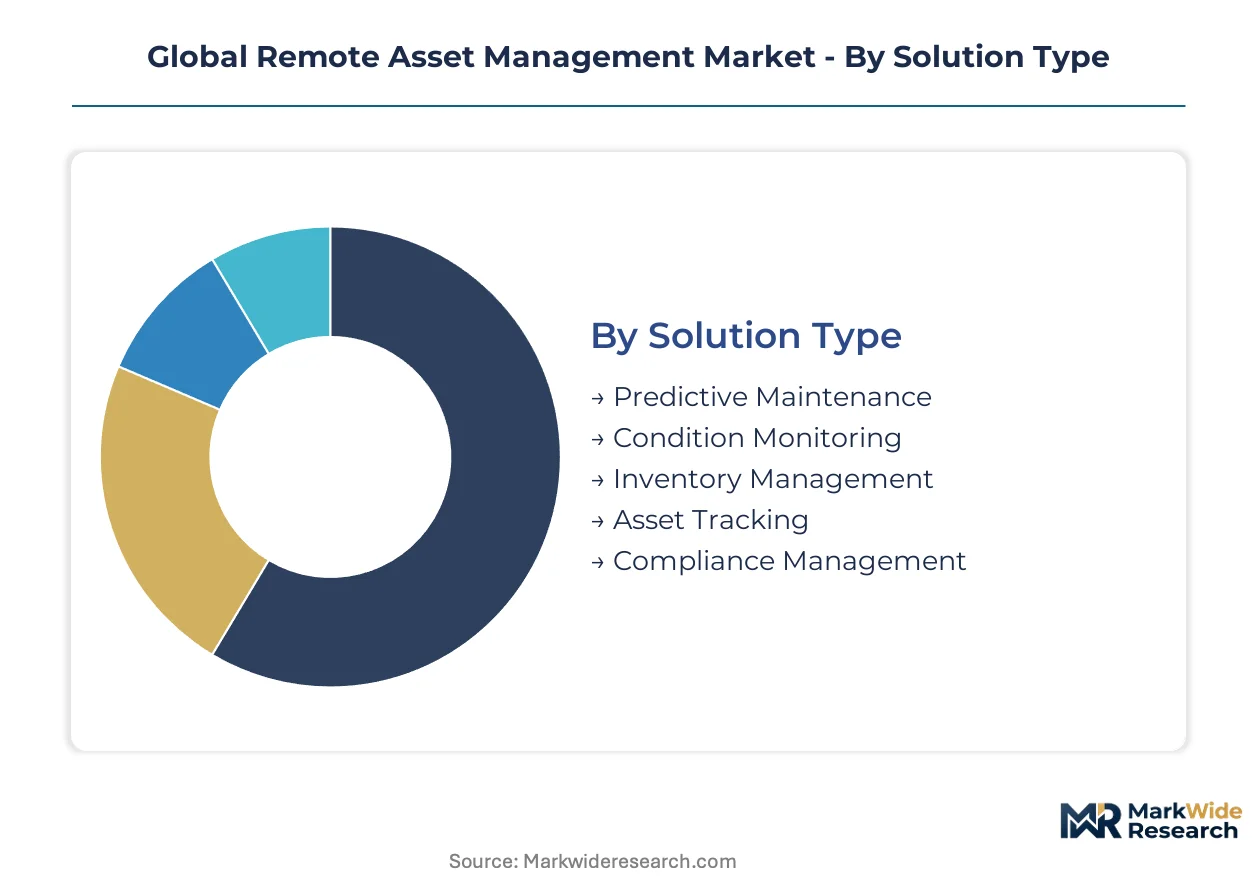
Remote asset management platforms serve heterogeneous operational environments where solution requirements diverge sharply across latency sensitivity, regulatory exposure, and capital intensity. Segmentation reveals how procurement patterns cluster around specific technology combinations rather than generic platform capabilities.
Solution Type:
Replacement cycles for legacy maintenance software are accelerating as EU AI Act conformity deadlines force upgrades of diagnostic systems in German chemical and French nuclear facilities.
- Predictive Maintenance:Algorithms analyze vibration, thermal, and electrical signatures to forecast equipment failure before operational disruption occurs. Demand concentrates in U.S. Gulf Coast steel and chemical processing facilities where sensor-triggered interventions replace calendar-based service contracts and reduce catastrophic failure incidence.
- Condition Monitoring:Real-time telemetry streams track asset health through networked sensor arrays with sub-50-millisecond latency for critical control loops. Japanese automotive plants in Osaka and Nagoya industrial corridors drive adoption under METI Society 5.0 interoperability mandates requiring cross-vendor data exchange.
- Inventory Management:Automated tracking of spare parts and consumables integrates with enterprise ERP stacks to optimize working capital deployment.
- Asset Tracking:Immutable location records satisfy regulatory audit trails for hazardous materials in transportation systems, sustaining premium pricing in this segment.
- Compliance Management:Documented algorithmic accountability modules address EU AI Act risk classification requirements for automated operational decisions.
Predictive Maintenance sits at the top of the volume ranking, with Asset Tracking climbing the fastest as hazardous materials regulations tighten across multiple jurisdictions.
Technology:
Technology selection follows a cost-tier logic where latency requirements and data sovereignty constraints determine architecture choices.
- IoT Sensors:Industrial-grade microcontrollers face supply tightness from concentrated East Asian foundry capacity, extending lead times for telemetry hardware procurement.
- Cloud Computing:Centralized processing architectures remain dominant for non-critical analytics but face displacement in latency-sensitive applications.
- Artificial Intelligence:Machine learning models automate maintenance scheduling decisions that previously required specialist interpretation, compressing response windows from days to minutes in European automotive deployments.
- Edge Computing:Native processing architectures compress decision latencies below cloud-reachable thresholds, enabling sub-10-millisecond control loops in South Korean and German industrial campuses with licensed 5G private spectrum.
- Blockchain:Distributed ledger technology provides tamper-proof audit trails for asset provenance and maintenance history in regulated industries.
IoT Sensors anchor the installed base by volume, while Edge Computing gains share fastest as manufacturing automation demands intensify.
Application:
Application segmentation reflects maturity gradients where digitization program advancement determines adoption velocity.
- Manufacturing Plants:Smart factory deployments integrate predictive maintenance with digital twin simulations for pre-failure modeling in wind turbine and railway rolling stock applications.
- Energy Facilities:Grid stabilization systems require edge-native architectures that pure cloud platforms cannot satisfy due to sub-50-millisecond latency requirements.
- Transportation Systems:Regulatory mandates for hazardous materials tracking drive premium pricing for immutable location record systems.
- Smart Cities:Municipal infrastructure monitoring converges IT and OT networks, creating demand for scarce cybersecurity architecture expertise.
- Infrastructure Management:Brownfield sites require substantial capital outlay to retrofit proprietary SCADA architectures with IP-native remote management layers.
Manufacturing Plants represent the largest addressable base, with Smart Cities expanding most quickly as municipal digitization budgets mature.
End User Industry:
Customer type segmentation tracks procurement sophistication where vendor evaluation capabilities determine unbundling of hardware from analytics subscriptions.
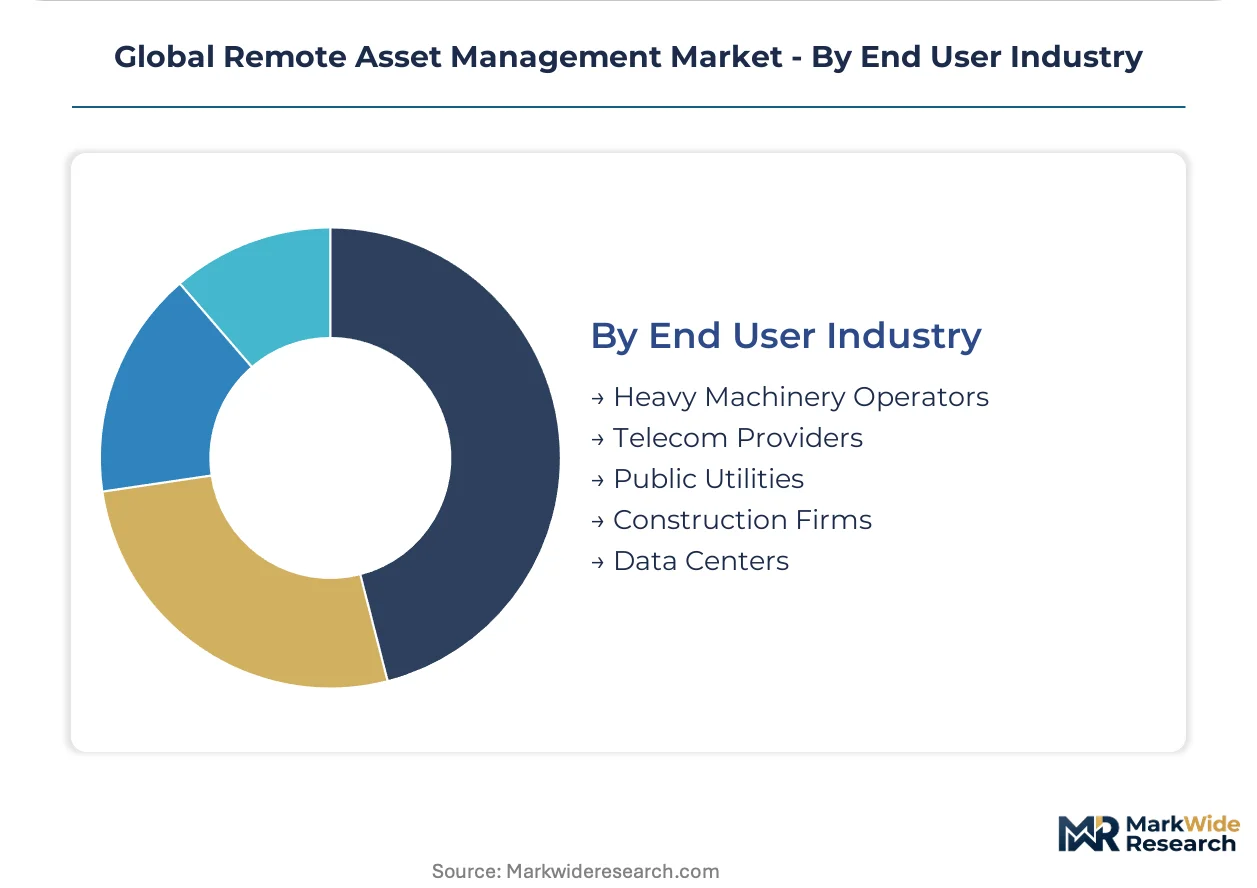
- Heavy Machinery Operators:Asset-intensive buyers treat sensor infrastructure as capital expenditure while negotiating usage-based pricing for predictive algorithms, disrupting traditional bundled licensing models.
- Telecom Providers:5G network operators leverage private spectrum allocations to enable industrial campus deployments with guaranteed quality of service.
- Public Utilities:Cross-border asset networks spanning Germany and Switzerland encounter divergent GDPR data localization requirements that complicate centralized platform architectures.
- Construction Firms:Project-based procurement patterns favor rental and subscription models over permanent infrastructure investment.
- Data Centers:Hyperscale facilities demand pre-certified platform modules that accelerate deployment timelines under multi-vendor certification requirements.
Heavy Machinery Operators dominate current procurement volume, with Data Centers gaining traction fastest as certification timeline pressures intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting industrial digitization investments toward jurisdictions with harmonized compliance frameworks, as manufacturers seek to minimize multi-jurisdictional certification costs while maintaining operational scale.
United States
Gulf Coast chemical processors and Rust Belt automotive plants drive predictive maintenance procurement to replace aging SCADA architectures. FCC spectrum licensing requirements for industrial IoT transmissions create compliance cost tiers that favor large-scale operators with dedicated regulatory teams. Houston and Detroit industrial corridors concentrate deployment activity for sensor-triggered intervention systems.
Germany
Automotive and chemical facilities face EU AI Act conformity assessment deadlines for automated diagnostic platforms, forcing replacement of legacy maintenance software. Algorithmic transparency mandates for worker safety-critical systems elevate demand for pre-certified platform modules. Bavarian and North Rhine-Westphalian manufacturing clusters anchor European deployment volume for auditable remote monitoring architectures.
Japan
METI Society 5.0 interoperability mandates require cross-vendor data exchange in smart factory deployments, accelerating standardization of telemetry protocols. Osaka and Nagoya industrial corridors lead adoption of condition monitoring systems with sub-50-millisecond latency specifications. Precision manufacturing procurement teams increasingly unbundle hardware from analytics subscriptions.
India
Production-linked incentive schemes for electronics and automotive component makers subsidize first-time remote asset management adoption in emerging industrial zones. BIS certification requirements for industrial IoT equipment create entry barriers that favor established platform providers with compliance infrastructure. Pune and Chennai manufacturing clusters concentrate pilot deployments for condition-based maintenance systems.
South Korea
Licensed 5G private spectrum allocations for industrial campuses enable sub-10-millisecond control loops that cloud-only architectures cannot satisfy. Government smart manufacturing initiatives accelerate edge-native processing adoption in semiconductor and display panel fabrication facilities. Gyeonggi-do and Chungcheong industrial belts lead deployment of latency-sensitive automation systems.
Global Remote Asset Management Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue edge-native specializations and compliance-certified niche modules. The vendor landscape stratifies across three maturity tiers: diversified industrial conglomerates with factory automation heritage, networking specialists with edge infrastructure dominance, and software-focused analytics providers. Competitive positioning hinges on pre-certified architecture availability and multi-jurisdictional regulatory coverage. Consolidation pressure favors suppliers capable of bundling predictive maintenance, edge analytics, and compliance reporting into unified operational dashboards.
Within the industrial conglomerate tier, Siemens AG and Schneider Electric exemplify players leveraging factory automation heritage to anchor large-scale European deployments. Cisco Systems Inc. occupies a position among networking specialists competing through edge infrastructure dominance and private 5G campus enablement. IBM Corporation represents the analytics-focused archetype, differentiating via AI-driven layers integrated with enterprise ERP stacks.
| Leading Market Players |
|---|
| Siemens AG |
| Cisco Systems Inc. |
| IBM Corporation |
| Schneider Electric |
| AT&T |
| Hitachi Ltd. |
| SAP SE |
| PTC Inc. |
| Rockwell Automation Inc. |
| Others |
Supply & Pricing Matrix
Captive integration into edge-native processing hardware anchors supply positions for vendors competing on sub-10-millisecond latency specifications. German automotive plants and South Korean semiconductor fabs reward this vertical control with pricing premiums tied to guaranteed interoperability under METI and EU AI Act mandates.
Pricing Analysis
Distributor margins compress as direct-to-OEM channel share expands for predictive maintenance platforms. Three-tier pricing structure across premium certified, standard compliant, and economy unbundled levels separates buyers by audit trail requirements. Cost compression in the economy tier intensifies because East Asian foundry supply tightness extends hardware lead times. Heavy machinery operators exhibit highest price sensitivity, while data center operators accept premium tiers for pre-certified deployment speed.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for industrial-grade sensor microcontrollers. The supply chain draws from Chinese rare earth processing, German precision mechanical components, and Japanese telemetry protocol chipsets. Tariff exposure on cross-border semiconductor shipments threatens margin stability for European system integrators. Distribution runs through authorized industrial automation distributors with certified integration capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where procurement teams reward pre-certified architectures over point solutions. The shift toward EU AI Act conformity assessments elevates specification premiums for algorithmic transparency modules.
For Market Incumbents: Lock in multi-year platform subscriptions by embedding compliance reporting into operational dashboards. Defend against edge-native specialists through captive sensor microcontroller supply agreements with Taiwanese foundries. Certification investment in IEC 62443 and EU AI Act modules preserves pricing power against unbundled software entrants.
For New Entrants and Emerging Players: Launch via usage-based pricing models targeting India's PLI-subsidized electronics manufacturers in Pune and Chennai industrial zones. White-space concentration sits with brownfield SCADA retrofit projects in the US Rust Belt where legacy integration costs deter bundled incumbents. Channel partnerships with regional system integrators accelerate first-deployment references.
For Investors and Strategic Acquirers: Roll-up economics work for compliance-certified niche module providers because EU AI Act deadlines compress customer evaluation windows. Five-to-ten year viability hinges on cross-jurisdictional regulatory coverage breadth. Monitor 5G private spectrum allocation velocity in Germany and South Korea as inflection signal for edge-native architecture demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies predictive maintenance, edge analytics, and EU AI Act compliance reporting into single operational dashboards for German automotive clients. |
| Acquisition of Specialist Firm | Captures scarce OT cybersecurity architecture expertise concentrated among limited pools of IT-OT convergence specialists. |
| Strategic Partnership | Secures licensed 5G private spectrum allocations enabling sub-10-millisecond control loops for South Korean semiconductor fabrication facilities. |
| Geographic Expansion | Establishes compliance infrastructure for BIS certification requirements in India's PLI-subsidized Pune and Chennai manufacturing clusters. |
| Product Launch | Deploys pre-certified platform modules accelerating deployment timelines under multi-vendor certification requirements for data center operators. |
Research Methodology
Bottom-up manufacturing plant modeling reconciled against top-down edge infrastructure tracking forms the analytical core. Primary interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads combine with secondary validation from SEC filings, customs records, hyperscaler capex disclosures, and IEC certification databases. Triangulation across these sources anchors volume estimates.
Historical trendline analysis of predictive maintenance adoption curves informs projection parameters across the modeling period. Segmentation dimensions include solution type, technology tier, application latency sensitivity, and end-user procurement sophistication. CAGRs derive from fitted growth curves applied to equipment installed base turnover rates and regulatory compliance deadline clustering.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor supply disruption or GDPR jurisdictional friction scenarios. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Asset Management
Global AI in Asset Management Market
Asset Management
Asset and Wealth Management Market
Asset Management
Hardware Asset Management Market
Asset Management
Capital Expenditure Market
Asset Management
US Healthcare Assets Management Market
Asset Management
India Asset Management Market
Asset Management
Asset Optimization Solutions Market
Asset Management
India AMC Industry Market
Asset Management
US Asset Management Market
Asset Management
US Pension Funds Market
Asset Management
Global Investment Management Software Market
Asset Management
Global Infrastructure Asset Management Market
Asset Management
UK Asset Management Market
Asset Management
Fixed Income Asset Management Market
Asset Management
APAC Mutual Fund Market
Asset Management
LAMEA Equity Management Software Market