
 Healthcare Asset Management Market | 2026-2036
Healthcare Asset Management Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Asset Management Market Intelligence
Demand from ambulatory surgical centers and telemedicine providers is broadening the traditional hospital-centric end-user base for asset management solutions. This shift creates new opportunities for specialized platform providers. GE Healthcare leverages its deep relationships within hospital systems to offer integrated equipment and software bundles. Siemens Healthineers competes by focusing on asset performance analytics for diagnostic imaging fleets, while IBM Corporation provides scalable cloud-based platforms for large, multi-site healthcare organizations.
Healthcare asset management involves the systematic process of tracking, deploying, maintaining, and disposing of physical assets within a healthcare facility. These systems often utilize real-time location systems (RTLS) through RFID or IoT-enabled sensors to provide continuous visibility. The primary purpose is to maximize asset utilization, reduce capital expenditure, and ensure regulatory compliance. While inventory optimization remains a core application, demand for predictive equipment maintenance solutions is accelerating, driven by cloud-based software platforms that integrate with existing hospital IT infrastructure.
Regulatory frameworks significantly influence system requirements and data handling protocols. In the United States, HIPAA mandates stringent data security for patient-linked asset information, while Europe's MDR requires detailed tracking for medical device lifecycle management. These compliance obligations shape the feature sets of software platforms. Stakeholders must now decide between the security control of on-premise systems and the scalability offered by SaaS and hybrid cloud deployment models.
Market Dynamics
The convergence of intense financial pressure on healthcare providers to reduce operating costs and the technological maturity of real-time location systems (RTLS) is the central force shaping the market. This combination moves asset tracking from a niche application to a core operational imperative.
Growth Catalysts
- Regulatory Mandates:Europe's Medical Device Regulation (MDR) imposes stringent requirements for device lifecycle tracking and traceability, compelling healthcare facilities to adopt sophisticated asset management systems to ensure compliance.
- Technology Economics:The declining cost and miniaturization of Bluetooth Low Energy (BLE) beacons and passive RFID tags make large-scale deployment across thousands of mobile medical assets economically feasible for multi-site hospital networks.
- End-User Expansion:Demand from ambulatory surgical centers and large diagnostic laboratory networks for improved equipment utilization and inventory control is creating a significant growth vector beyond the traditional large hospital segment.
Market Restraints
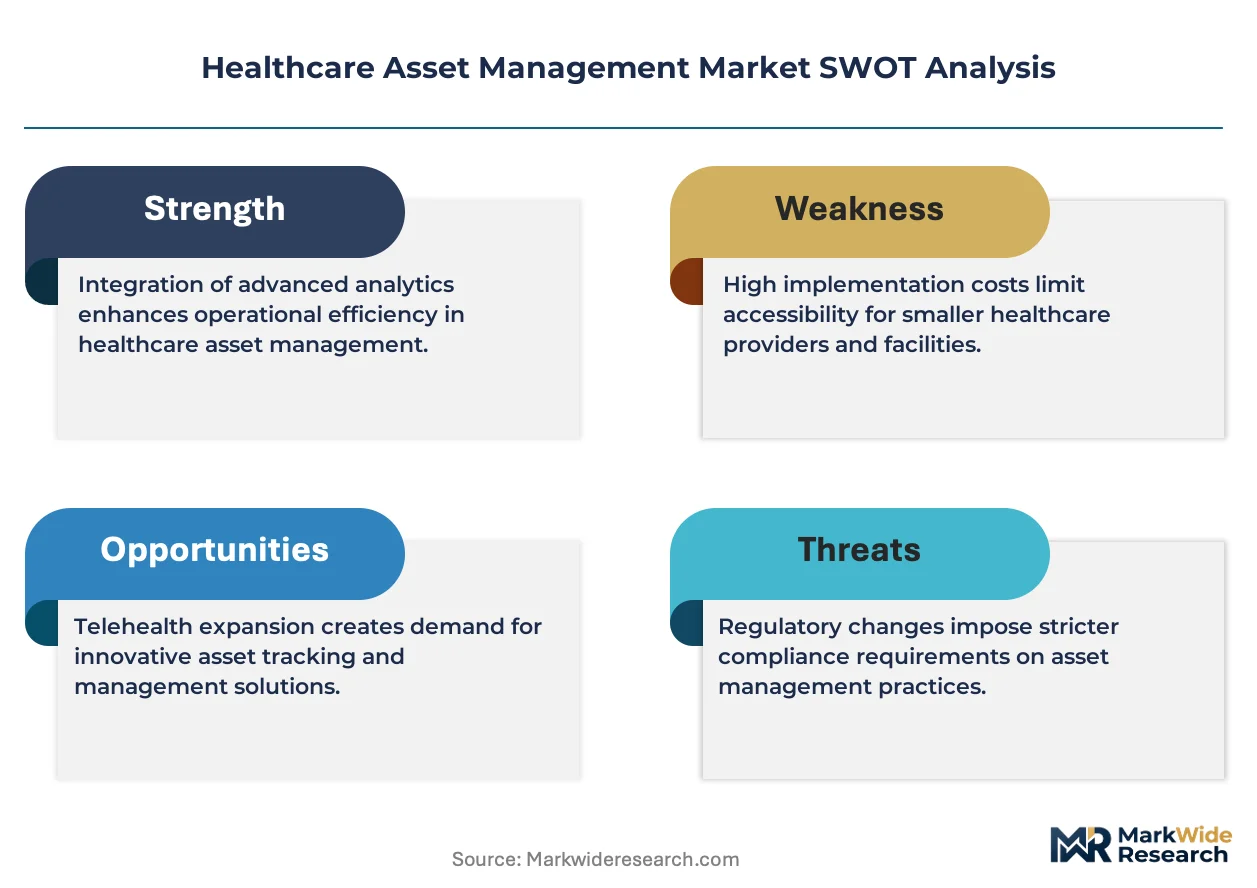
- High Initial Investment:The significant capital expenditure required for RTLS infrastructure, including readers, tags, network servers, and software licenses, presents a substantial adoption barrier for smaller hospitals and independent clinics.
- Signal Integrity Issues:Radio-frequency interference from other medical equipment and signal absorption by building materials in dense hospital environments can compromise the accuracy and reliability of location data, particularly for RFID-based systems.
- Data Security Compliance:In the United States, HIPAA regulations create complexity and cost in system design by mandating stringent security protocols to protect any patient information linked to tracked assets.
Strategic Opportunities
- Predictive Maintenance Analytics:Developing software modules that use asset utilization data to predict maintenance needs for high-value imaging equipment like MRI and CT scanners represents a major value-add beyond simple location tracking.
- EHR System Integration:Creating seamless integration between asset management platforms and Electronic Health Record (EHR) systems allows for linking specific equipment usage to patient procedures, improving billing accuracy and clinical workflow analysis.
- Greenfield Hospital Projects:Emerging economies in the Middle East and Southeast Asia are investing in new hospital construction, offering vendors an opportunity to install integrated, facility-wide asset management systems from the outset.
Industry Challenges
- Legacy System Integration:A primary operational hurdle is the complexity of integrating modern, cloud-based asset management software with a hospital's existing and often fragmented legacy IT infrastructure, including ERP and CMMS platforms.
- Specialized Talent Scarcity:Healthcare organizations face a shortage of IT professionals who possess the dual expertise in IoT network management and clinical workflow optimization necessary to deploy and maintain these systems effectively.
- Interoperability Standards:The absence of universal data communication standards between medical device manufacturers and asset tracking software providers complicates the creation of a unified tracking environment in multi-vendor hospital settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Asset Management Market |
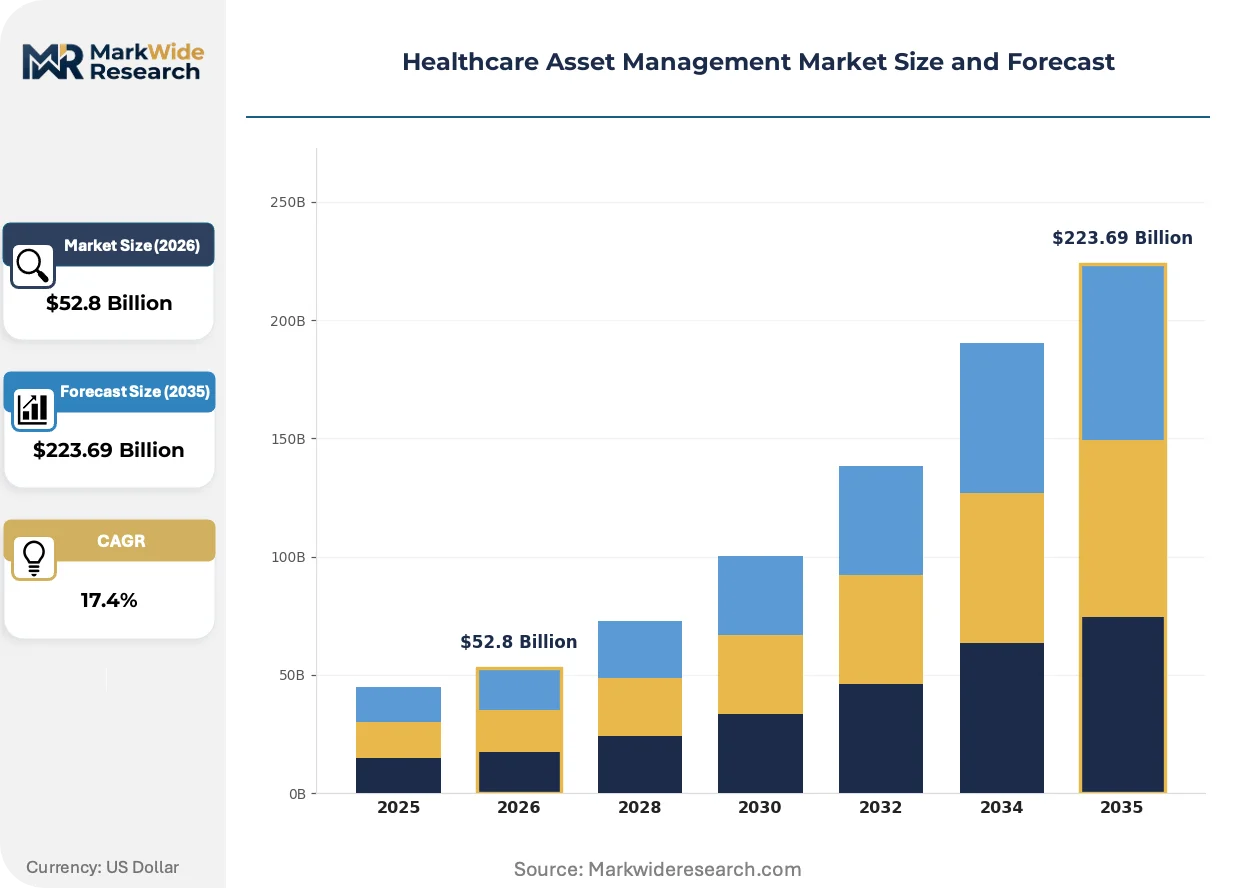
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $223.69 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Offering: Software Platform, Cloud-Based Service, On-Premise System, Mobile Application, RFID Tracking, IoT Integration Application: Inventory Optimization, Equipment Maintenance, Asset Tracking, Compliance Management, Resource Allocation, Utilization Analysis End User: Hospitals, Diagnostic Laboratories, Ambulatory Surgical Centers, Rehabilitation Clinics, Nursing Facilities, Telemedicine Providers Deployment Model: Private Cloud, Public Cloud, Hybrid Cloud, SaaS, Managed Services |
| Companies Covered | IBM Corporation, Motorola Solutions Inc, GE Healthcare, Tyco Security Products, Siemens Healthineers, cenTrak, Infor Inc, Stanley Security Solutions Inc, Airista Flow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Asset Management Market Strategic Shifts & Innovations
The market's evolution is defined by a decisive shift from passive location tracking toward active, data-driven operational intelligence. Systems are no longer just answering "where is the asset?" but are now focused on optimizing its use, condition, and workflow integration.
AI-powered analytics software uses real-time location data to forecast equipment demand hot spots and optimize daily distribution workflows. Large hospital networks in North America and Europe are the principal adopters, driven by the need to increase operating room throughput and minimize spending on rental equipment. This advanced software is automating the previously manual tasks of par-level replenishment and asset allocation, directly improving staff productivity.
The U.S. Food and Drug Administration's (FDA) Unique Device Identification (UDI) rule requires certain medical devices to be marked with a unique identifier. This regulation establishes a standardized data foundation that asset management systems leverage for enhanced recall management, inventory control, and device lifecycle documentation. Infusion pumps, ventilators, and surgical instruments are among the categories most impacted, compelling providers to adopt systems that can scan and log UDI data at multiple points of care.
Providers are increasingly selecting subscription-based Software-as-a-Service (SaaS) platforms over large, upfront capital investments in on-premise hardware and software. This OpEx-friendly model shifts the responsibility for system maintenance, security, and software updates to the vendor, which appeals to budget-conscious healthcare organizations. The trend is most pronounced among mid-sized hospitals and specialized clinic networks that often lack large, dedicated IT departments to manage complex infrastructure internally.
Healthcare Asset Management Market Segmentation
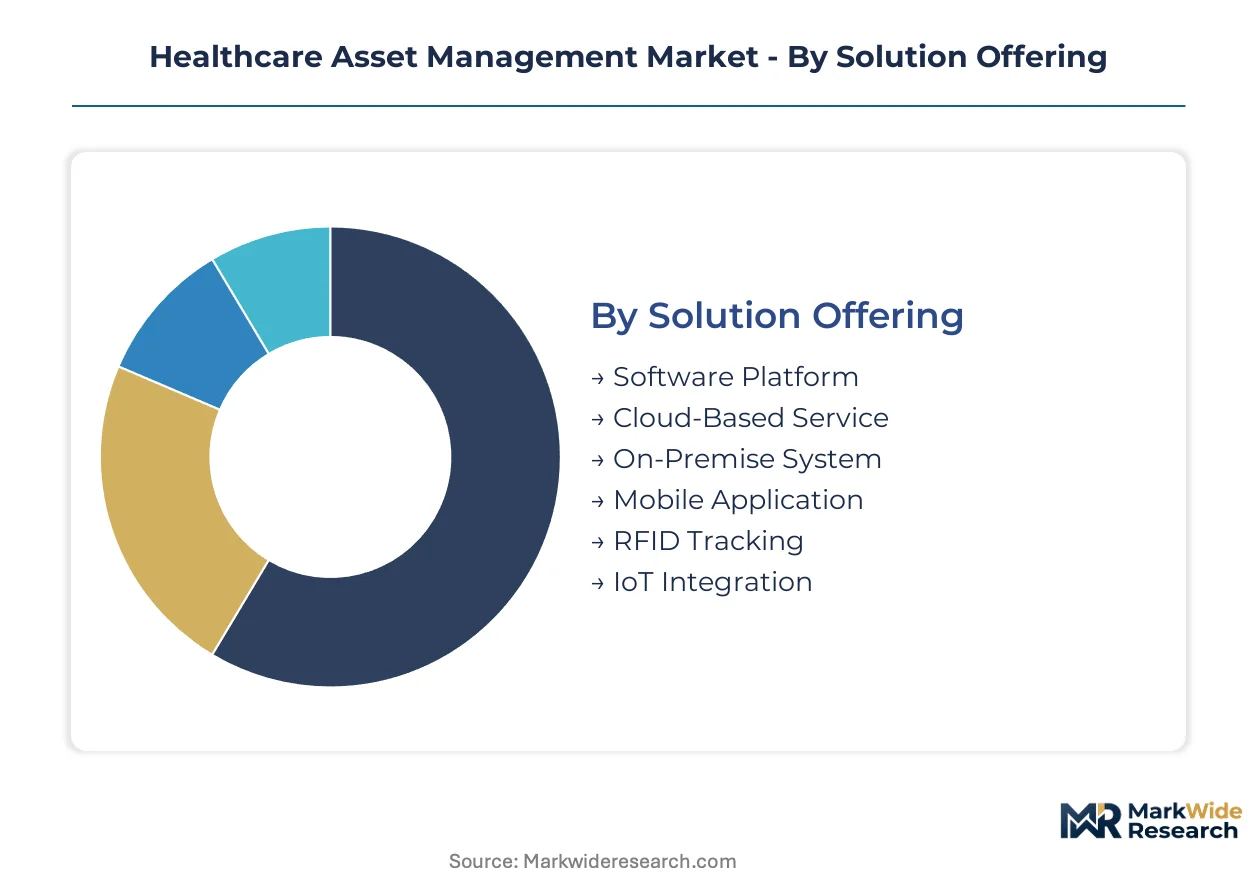
Understanding the segmentation of the healthcare asset management market reveals how providers address varying operational needs and technological preferences. This detailed breakdown highlights areas of concentrated investment and emerging opportunities across the healthcare ecosystem.
Solution Offering:
The solution offering in healthcare asset management splits between high-volume tracking components and premium analytical software.
- Software Platform:These comprehensive digital systems provide the core infrastructure for asset tracking, maintenance scheduling, and utilization reporting across healthcare facilities. Demand concentrates in large hospital networks seeking integrated operational visibility.
- Cloud-Based Service:Delivered over the internet, these services offer scalable, on-demand access to asset management functionalities without significant upfront IT infrastructure investment. Adoption is accelerating among mid-sized hospitals and specialized clinics for cost efficiency.
- On-Premise System:Software and hardware are installed and managed directly within a healthcare organization's own data centers, offering maximum control over data security. Smaller, independent clinics often favor this option for perceived data isolation.
- Mobile Application:These applications provide on-the-go access for staff to locate assets, update status, or initiate maintenance requests using handheld devices. Clinical staff utilize mobile applications for real-time equipment interaction.
- RFID Tracking:Utilizing radio-frequency identification tags, this technology enables automated, real-time location tracking of medical equipment and supplies within designated zones. Hospitals employ RFID for high-value mobile asset visibility.
- IoT Integration:Internet of Things sensors embedded in or attached to assets collect continuous data on location, status, and environmental conditions. This integration supports predictive maintenance and workflow automation in complex environments.
Mature deployment sits with On-Premise System. Newer deployment is concentrated in Cloud-Based Service.
Application:
Applications for healthcare asset management solutions span from foundational cost-saving measures to advanced operational efficiency enhancements.
- Asset Tracking:This core application involves the real-time location and status monitoring of medical equipment, instruments, and supplies within a healthcare facility. Hospitals in the United States prioritize asset tracking to reduce equipment loss and improve staff efficiency.
- Utilization Analysis:This application leverages collected data to assess how frequently and effectively assets are being used, identifying underutilized equipment and optimizing deployment strategies. Large hospital systems in Europe employ utilization analysis to maximize capital expenditure.
- Inventory Optimization:Systems manage the stock levels of consumables and medical devices, ensuring adequate supply while minimizing waste and reducing carrying costs. Diagnostic laboratories use inventory optimization for reagent and specialized kit management.
- Equipment Maintenance:This application schedules and tracks preventive and corrective maintenance activities for medical devices, extending asset lifespans and ensuring operational readiness. Rehabilitation clinics rely on equipment maintenance for specialized therapy devices.
- Compliance Management:Solutions help healthcare providers meet regulatory requirements for medical device tracking, safety, and reporting, such as those mandated by Europe's MDR. Nursing facilities use compliance management for mandated equipment checks.
- Resource Allocation:This application optimizes the deployment of both mobile assets and personnel, ensuring that necessary equipment is available where and when needed. Telemedicine providers utilize resource allocation for remote monitoring device distribution.
Utilization Analysis gains share fastest, reflecting a market shift towards data-driven decisions.
End User:
The end-user landscape for healthcare asset management ranges from large institutional networks to specialized outpatient facilities.
- Hospitals:These large, multi-departmental facilities represent the primary end-users, requiring comprehensive systems for tracking thousands of medical devices and optimizing complex workflows. Hospitals in North America drive significant demand for integrated solutions.
- Ambulatory Surgical Centers:These outpatient facilities perform surgical procedures not requiring overnight stays, increasingly adopting asset management solutions to enhance equipment utilization and streamline operational efficiency. Ambulatory surgical centers in the United States expand their asset management investments.
- Diagnostic Laboratories:These facilities utilize specialized equipment for testing and analysis, implementing asset management to track high-value analyzers and manage reagent inventory effectively. Large diagnostic networks require precise equipment location.
- Rehabilitation Clinics:These centers provide physical and occupational therapy, using asset management to track specialized exercise equipment and mobility aids. Rehabilitation clinics prioritize asset availability for patient care.
- Nursing Facilities:Long-term care and skilled nursing facilities deploy asset management for tracking patient mobility devices, beds, and medical equipment. Nursing facilities ensure critical equipment is always accounted for.
- Telemedicine Providers:These organizations offer remote healthcare services, using asset management for the deployment, tracking, and maintenance of remote monitoring devices and diagnostic kits. Telemedicine providers manage distributed equipment inventories.
Demand concentrates heavily within hospital networks, while ambulatory surgical centers show significant expansion.
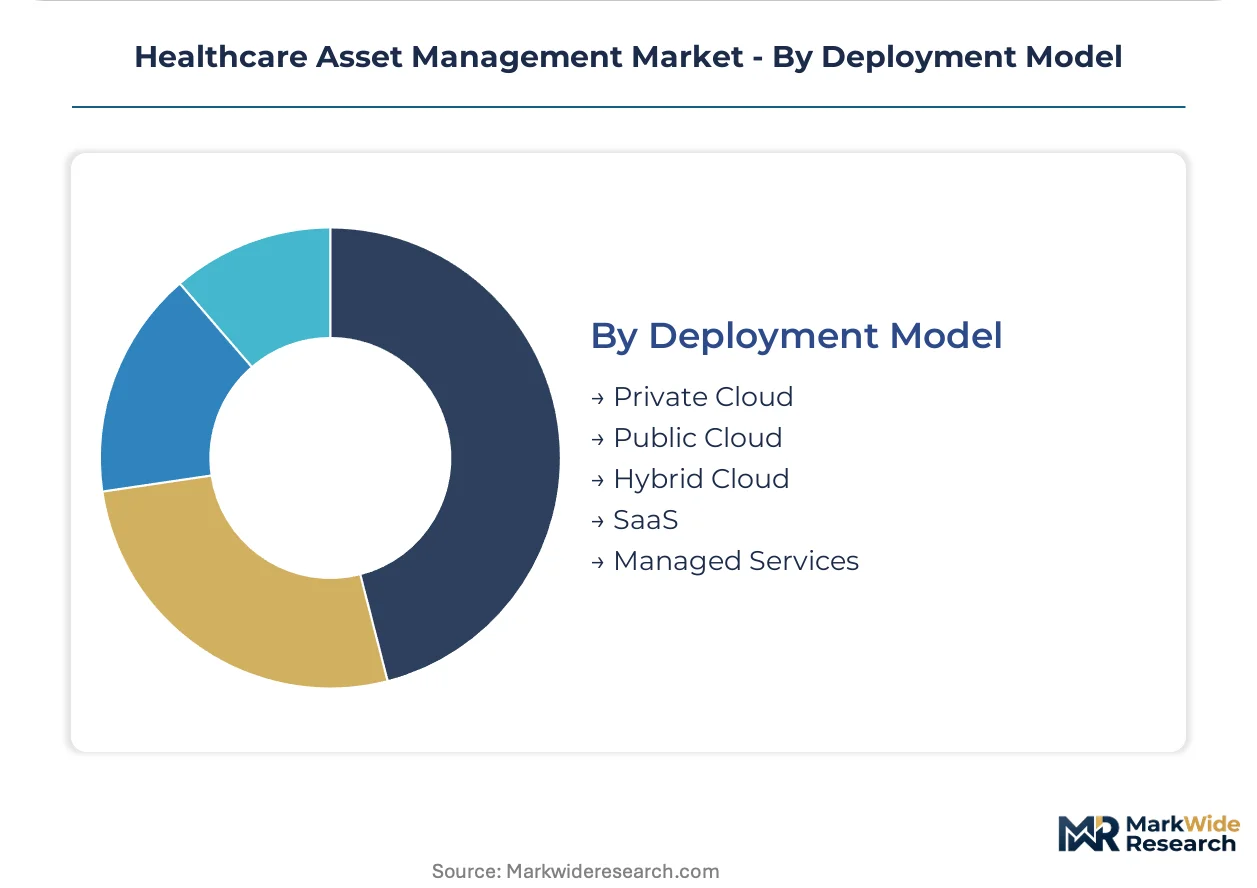
Deployment Model:
Deployment models for healthcare asset management reflect varying levels of infrastructure maturity and security preferences among providers.
- SaaS:Software-as-a-Service platforms offer subscription-based access to asset management software hosted by a third-party vendor, reducing upfront costs and IT burden. Mid-sized hospitals increasingly adopt SaaS for its operational expenditure benefits.
- Hybrid Cloud:This model combines elements of both public and private cloud environments, allowing healthcare organizations to maintain sensitive data on-premise while leveraging cloud scalability for other functions. Large multi-site healthcare organizations favor hybrid cloud for balancing security and flexibility.
- Private Cloud:A dedicated cloud infrastructure managed exclusively for a single organization, providing enhanced security, control, and customization options. Government healthcare systems often choose private cloud for stringent data governance.
- Public Cloud:Services delivered over the public internet by a third-party provider, offering high scalability and cost-effectiveness through shared infrastructure. Start-up clinics might opt for public cloud to minimize initial infrastructure costs.
- Managed Services:Third-party providers manage and maintain the asset management system, including hardware, software, and network infrastructure, for the healthcare organization. Smaller clinics often outsource IT management through managed services.
Healthcare providers increasingly prefer SaaS models, shifting away from traditional on-premise infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The concentration of medical technology innovation in regions like the United States, often bolstered by R&D tax incentives and investment in advanced healthcare infrastructure, drives significant demand for asset management solutions. These zones foster an environment where healthcare providers aggressively adopt new technologies to optimize operations. This focus on efficiency and regulatory compliance underpins regional market dynamics.
United States
Healthcare providers in the United States prioritize asset tracking to reduce equipment loss and improve operational efficiency across complex systems. HIPAA regulations mandate stringent data security for patient-linked asset information, influencing system design and deployment. Major hospital networks in cities like New York and Boston are rapidly integrating RTLS and IoT solutions to manage extensive medical equipment fleets.
Germany
German healthcare facilities adopt asset management systems for robust compliance with medical device regulations and optimizing diagnostic imaging fleets. Europe's MDR imposes stringent requirements for device lifecycle tracking, compelling hospitals to implement sophisticated solutions. Medical technology clusters in cities such as Erlangen and Munich are centers for developing and deploying advanced asset performance analytics.
Japan
Japanese hospitals seek asset management solutions to enhance equipment utilization and improve operational efficiency within a rapidly aging society. National healthcare policies encourage digitalization and smart hospital initiatives, driving investment in real-time tracking technologies. Large hospital groups in the Tokyo metropolitan area are investing in IoT-enabled systems to manage high-value diagnostic and surgical equipment.
India
Emerging economies like India present significant opportunities with new hospital construction projects requiring integrated asset management systems from inception. The National Health Authority (NHA) promotes digital health initiatives, indirectly supporting the adoption of asset tracking for better resource management. Cities such as Hyderabad and Bengaluru are witnessing the establishment of large healthcare campuses that embed facility-wide asset management infrastructure.
Healthcare Asset Management Market Key Industry Players
Top-tier vendors anchor the integrated healthcare solutions segment, while specialized technology providers focus on niche asset tracking functionalities. The market structure exhibits a tiered consolidation, with large conglomerates offering broad portfolios alongside focused software and hardware specialists. Strategic archetypes include comprehensive enterprise solution providers, dedicated real-time location system (RTLS) developers, and cloud-native platform innovators. Portfolio diversification into predictive analytics and strategic partnerships with EHR vendors are dominant competitive moves.
Large technology and healthcare equipment manufacturers represent a significant force, leveraging existing client relationships and extensive R&D capabilities to offer integrated solutions. IBM Corporation exemplifies a provider of scalable cloud-based platforms for large, multi-site healthcare organizations, emphasizing data security and system integration. GE Healthcare occupies a position as an integrated equipment and software bundle provider, leveraging deep hospital system relationships to deliver comprehensive solutions. Siemens Healthineers sits within the segment focusing on asset performance analytics for diagnostic imaging fleets, offering specialized insights into high-value medical devices.
| Leading Market Players |
|---|
| IBM Corporation |
| Motorola Solutions Inc |
| GE Healthcare |
| Tyco Security Products |
| Siemens Healthineers |
| cenTrak |
| Infor Inc |
| Stanley Security Solutions Inc |
| Airista Flow |
| Others |
Cost & Logistics Intelligence
Outsourced manufacturing of core components anchors both the supply position and the pricing power in the healthcare asset management market. This integration choice allows for specialized production efficiencies and cost optimization, influencing the final solution pricing for healthcare providers.
Pricing Analysis
Lead-time-driven pricing structures emerge for rapid deployment of asset management solutions, with premium costs for immediate implementation and discounts for planned project rollouts. Subscription-based SaaS models dominate, offering predictable operational expenditure for healthcare organizations. Price differentiation stems from the level of customization required for integration with existing hospital IT infrastructure and the depth of after-sales support. Pricing pressure stems from intense financial pressure on healthcare providers to reduce operating costs. Mid-sized hospitals and independent clinics exhibit the highest price sensitivity, preferring OpEx-friendly SaaS models.
Supply Chain Analysis
Logistics and freight costs significantly influence the delivery of hardware components for asset management systems. Geographic supply concentration for critical electronic components, such as semiconductors and specialized plastics for RFID tags and BLE beacons, primarily rests in East Asia and Southeast Asia. The supply chain relies on a stable flow of these advanced electronic inputs. A structural risk involves potential component shortages and trade disruptions affecting sensor manufacturing. Distribution runs through direct sales channels for large hospital networks and through specialized value-added resellers for smaller clinics and ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's Medical Device Regulation (MDR) and the U.S. FDA's UDI rule establish a cost-of-compliance narrative, creating a significant barrier-to-entry moat for compliant players in healthcare asset management.
For Market Incumbents:Anchor existing client relationships by deepening integration with Electronic Health Record (EHR) systems, improving billing accuracy and clinical workflow analysis. Pursue strategic acquisitions of specialized RTLS developers to enhance real-time location capabilities and proprietary sensor technology. A significant threat stems from cloud-native platform innovators offering highly scalable, OpEx-friendly solutions. Investment in AI analytics R&D for predictive maintenance is a key lever, extending asset lifespans for high-value diagnostic equipment.
For New Entrants and Emerging Players:Launch via subscription-based SaaS models targeting mid-sized hospitals and specialized clinic networks, which often lack large IT departments. Focus on white-space opportunities within ambulatory surgical centers and telemedicine providers, where equipment utilization and distributed inventory management are critical. The most penetrable segment remains mid-sized hospitals seeking cost-efficient operational improvements. A specific go-to-market angle involves offering solutions tailored to UDI compliance requirements for specific medical device categories like infusion pumps and ventilators.
For Investors and Strategic Acquirers:Exit pathways concentrate in acquisitions by large healthcare technology conglomerates or private equity firms seeking to consolidate market share. The long-term viability of this market appears strong, driven by persistent healthcare cost containment pressures and regulatory mandates over the next 5-10 years. Target acquisition archetypes include cloud-native platform innovators with strong data analytics capabilities and specialized RTLS hardware providers. A signal to watch as an inflection indicator is the rate of EHR system integration success across diverse healthcare settings.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Leverages existing relationships and accelerates adoption within complex healthcare networks. |
| Software Companion Development | Enhances core platform functionality with specialized modules for predictive maintenance. |
| Regulatory Compliance Pathway | Ensures solutions meet stringent data security and device traceability mandates like HIPAA. |
| Platform Integration | Connects asset management with EHR systems for comprehensive patient and equipment data. |
| Geographic Expansion | Captures new market demand in emerging economies with significant hospital construction. |
Research Approach
Independent corroboration across primary interviews with key industry stakeholders, secondary validation from regulatory bodies, and internal proprietary databases underwrites the qualitative findings within this analysis. The methodology combines primary data collection from hospital IT directors, biomedical engineers, GPO contracts managers, and ambulatory surgical center administrators. Secondary data sources include HIPAA compliance reports, European MDR guidelines, hospital procurement databases, and industry technology reports. The analysis employs both bottom-up and top-down triangulation to ensure data accuracy.
Rate-of-change decomposition forms the basis of the quantitative forecast framework, analyzing market dynamics across the projection horizon. The model incorporates segmentation dimensions such as deployment model, application, end-user, solution offering, and regional adoption patterns. Compound annual growth rates are derived through a rigorous statistical analysis of historical data and projected market drivers. Industry-specific forecast inputs include projected healthcare expenditure growth and anticipated medical device regulatory changes impacting asset tracking requirements.
Technological obsolescence, data security breaches, and global economic slowdowns are the dominant revision risks to the market forecasts. These forecasts reflect a set of assumptions regarding market conditions and technological advancements. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Asset Management
APAC Mutual Fund Market
Asset Management
India AMC Industry Market
Asset Management
Capital Expenditure Market
Asset Management
Asset Optimization Solutions Market
Asset Management
Equity Management Tool Market
Asset Management
Global Remote Asset Management Market
Asset Management
US Pension Funds Market
Asset Management
Hardware Asset Management Market
Asset Management
Fund Management Fee Market
Asset Management
Pension Fund Management Software Market
Asset Management
UK Asset Management Market
Asset Management
Global Asset Performance Management Market
Asset Management
Smart Asset Management Market
Asset Management
Asset and Wealth Management Market
Asset Management
Mutual Fund Assets Market
Asset Management
Asia-Pacific Utilities Asset Management Market