
 Europe Asset Management Market | 2026-2036
Europe Asset Management Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Asset Management Market Foresight
France is tilting toward sustainable fund manufacturing as Paris-based Amundi extends its ESG product infrastructure across the continent. BlackRock leverages its scale in passive strategies to dominate the exchange-traded fund segment. Schroders anchors its competitive position through specialized active management in emerging market debt and European equities.
Europe asset management encompasses the professional administration of investment portfolios across equities, fixed income, real assets, and alternative instruments, governed by risk-return parameters, liquidity constraints, and regulatory suitability frameworks. The practice centers on optimizing capital preservation and growth for beneficiaries through diversification, rebalancing, and tax-efficient vehicle structures. Active management commands premium fee structures but faces structural outflows as passive management captures cost-sensitive institutional mandates. Open-end funds retain the dominant fund structure by assets under management, though exchange-traded funds are expanding fastest among retail and advisory channels.
The EU Green Deal, Sustainable Finance Disclosure Regulation, and MiFID II suitability requirements collectively reshape product design, distribution practices, and disclosure obligations across European jurisdictions. EMA and national regulators such as France's AMF and Germany's BaFin enforce divergent interpretations of sustainable investment criteria, complicating cross-border fund passporting. Stakeholders must monitor evolving taxonomy alignment standards and anticipate how CSRD-driven corporate sustainability reporting will reshape underlying asset valuations and portfolio construction methodologies.
Market Dynamics
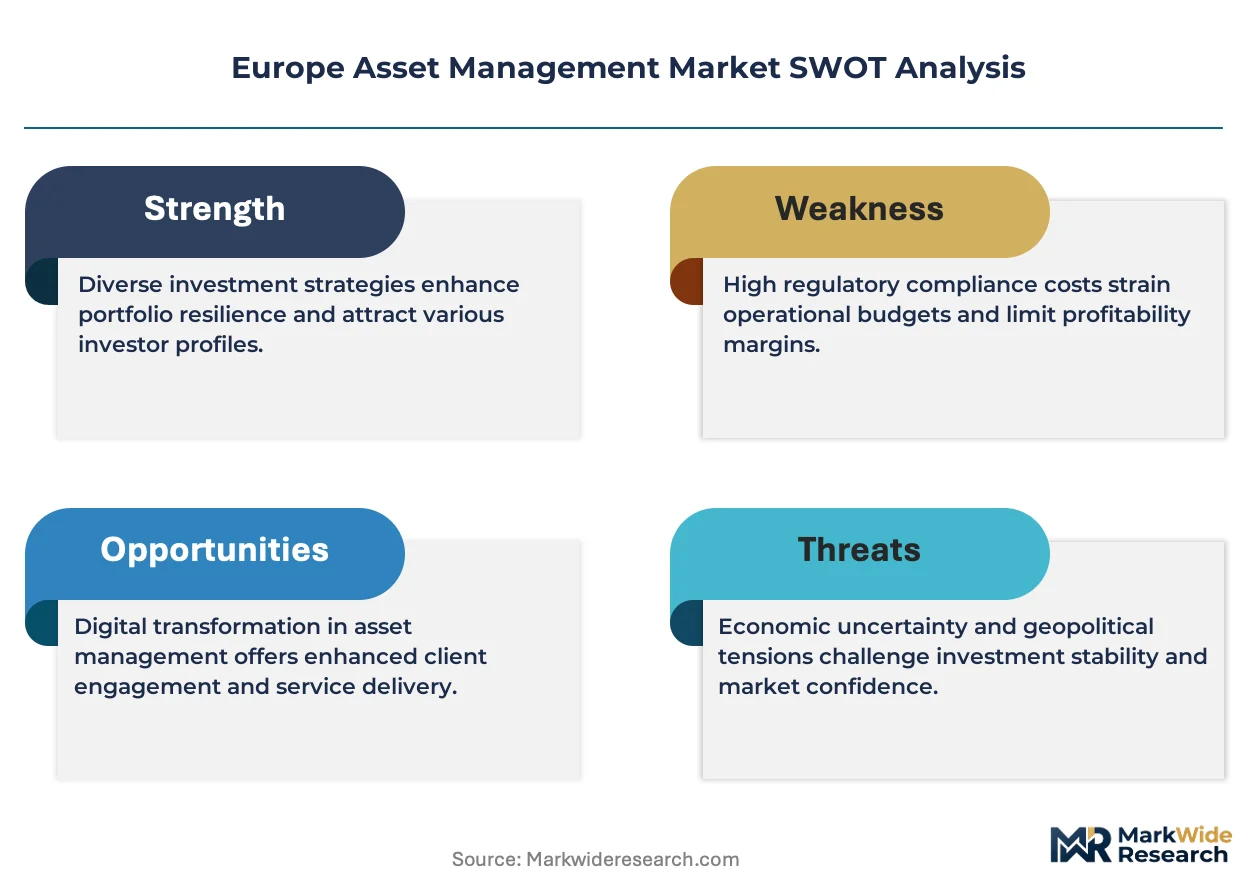
Passive investment vehicles are compressing fee structures across European fund distribution, forcing active managers to demonstrate differentiated alpha generation or surrender assets to low-cost index trackers.
Growth Catalysts
- EU Green Deal capital redirection:Mandatory sustainability disclosures under the Sustainable Finance Disclosure Regulation are channeling institutional flows into taxonomy-aligned portfolios.
- Pension fund alternative allocation:Northern European defined-benefit schemes are increasing exposure to private credit and infrastructure to match long-dated liabilities.
- ETF platform expansion:Digital brokerage infrastructure across Germany and France is lowering distribution costs for exchange-traded products.
Market Restraints
- Fee compression mechanics:Management expense ratios on core equity funds have fallen below 50 basis points, squeezing revenue per dollar of assets under administration.
- Regulatory fragmentation:Divergent interpretations of ESG criteria between France's AMF and Germany's BaFin complicate cross-border fund passporting under UCITS directives.
- Passive substitution threat:Smart-beta and factor-based index strategies are capturing institutional mandates previously held by fundamental active managers.
Strategic Opportunities
- Polish and Romanian market entry:Underpenetrated retail wealth pools in Central Europe offer first-mover advantages for digital-first distribution models.
- CSRD data services:Corporate Sustainability Reporting Directive mandates are creating demand for portfolio-level carbon accounting and transition pathway analytics.
- Tokenized fund structures:Distributed ledger settlement infrastructure is hybridizing with traditional custody arrangements to enable fractional real-asset ownership.
Industry Challenges
- Quantitative sustainable finance expertise:Shortages of professionals capable of modeling climate transition risk and taxonomy alignment at portfolio scale constrain product development velocity.
- Legacy system integration:Core banking platforms at established distributors resist API connectivity with newer portfolio analytics engines, delaying real-time reporting capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Asset Management Market |
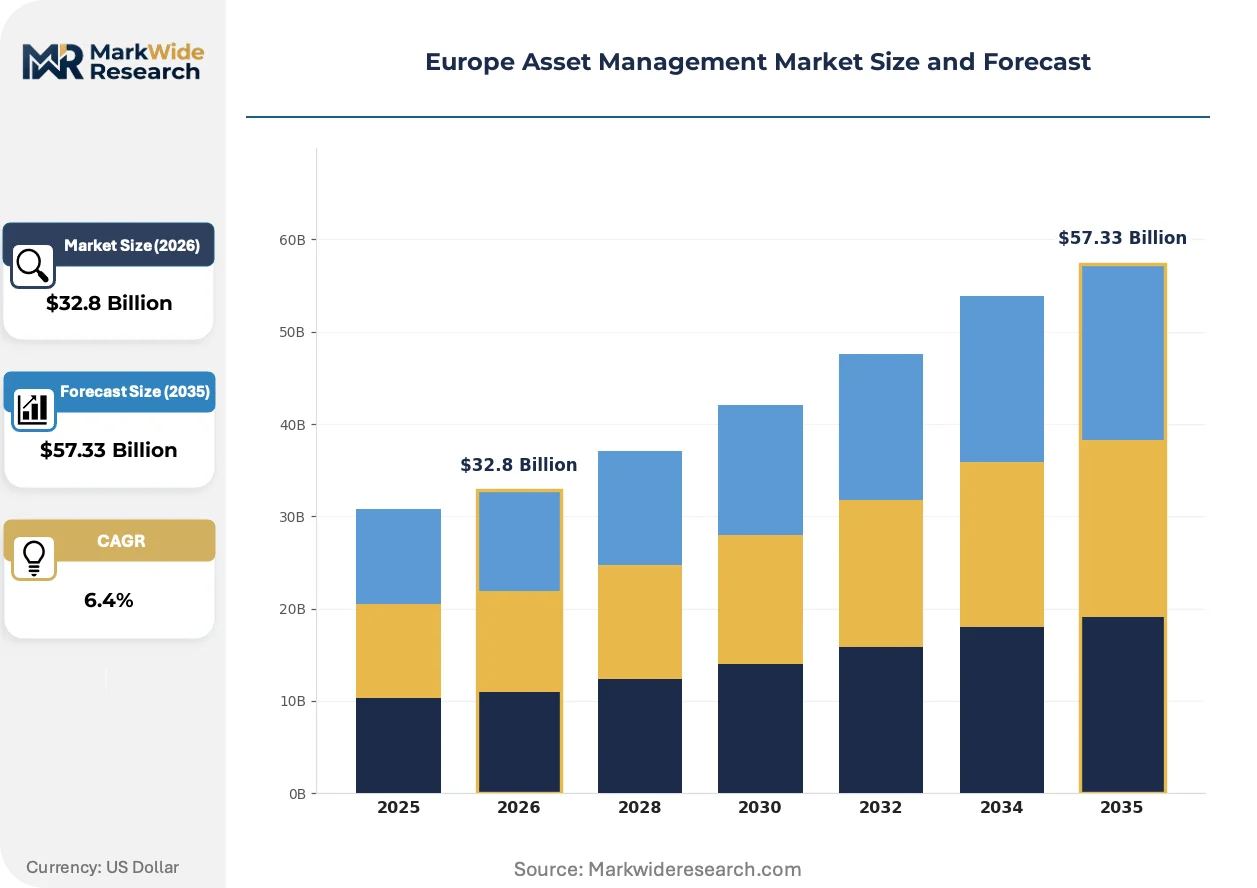
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Strategy: Active Management, Passive Management, Quantitative Investing, Asset Allocation Fund Structure: Open-End Funds, Closed-End Funds, Exchange-Traded Funds, Hedge Funds Investor Type: Institutional Investors, High Net Worth Individuals, Retail Investors, Family Offices Transaction Size: Small Cap, Mid Cap, Large Cap, Mega Cap |
| Companies Covered | DWS, Legal & General, BlackRock, Allianz Global Investors, Schroders, UBS, Vanguard, AXA Investment Managers, Amundi, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Asset Management Market Shifts & Advancements
Artificial intelligence is embedding into investment workflows across European asset managers, altering how research is consumed, risk is monitored, and client portfolios are constructed.
Natural language processing engines are hybridizing fundamental equity research by scanning regulatory filings, earnings transcripts, and alternative data feeds to flag sentiment shifts before they price into securities. Quantitative teams at mid-sized active houses are deploying these tools to augment analyst coverage in underfollowed small-cap segments. The technology is compressing the information-arbitrage window that previously rewarded specialized sector expertise.
The EU AI Act imposes transparency requirements on algorithmic decision systems used in portfolio management, mandating human oversight and explainability documentation for high-risk applications. Asset managers deploying machine-learning models for credit scoring or insurance-linked securities must now maintain audit trails and bias-testing protocols. French and German regulators are issuing supplementary guidance on model governance, with inspection rights extending to third-party vendor algorithms.
Advisory channels are unbundling from product manufacturing as MiFID II inducement rules harden. Independent financial advisors in Italy and Spain are migrating client assets to open-architecture platforms that separate fee-for-advice from fund distribution revenue. This behavioral pivot is pressuring captive distribution networks at bank-owned asset managers to demonstrate performance alpha or lose shelf access.
Europe Asset Management Market Segmentation
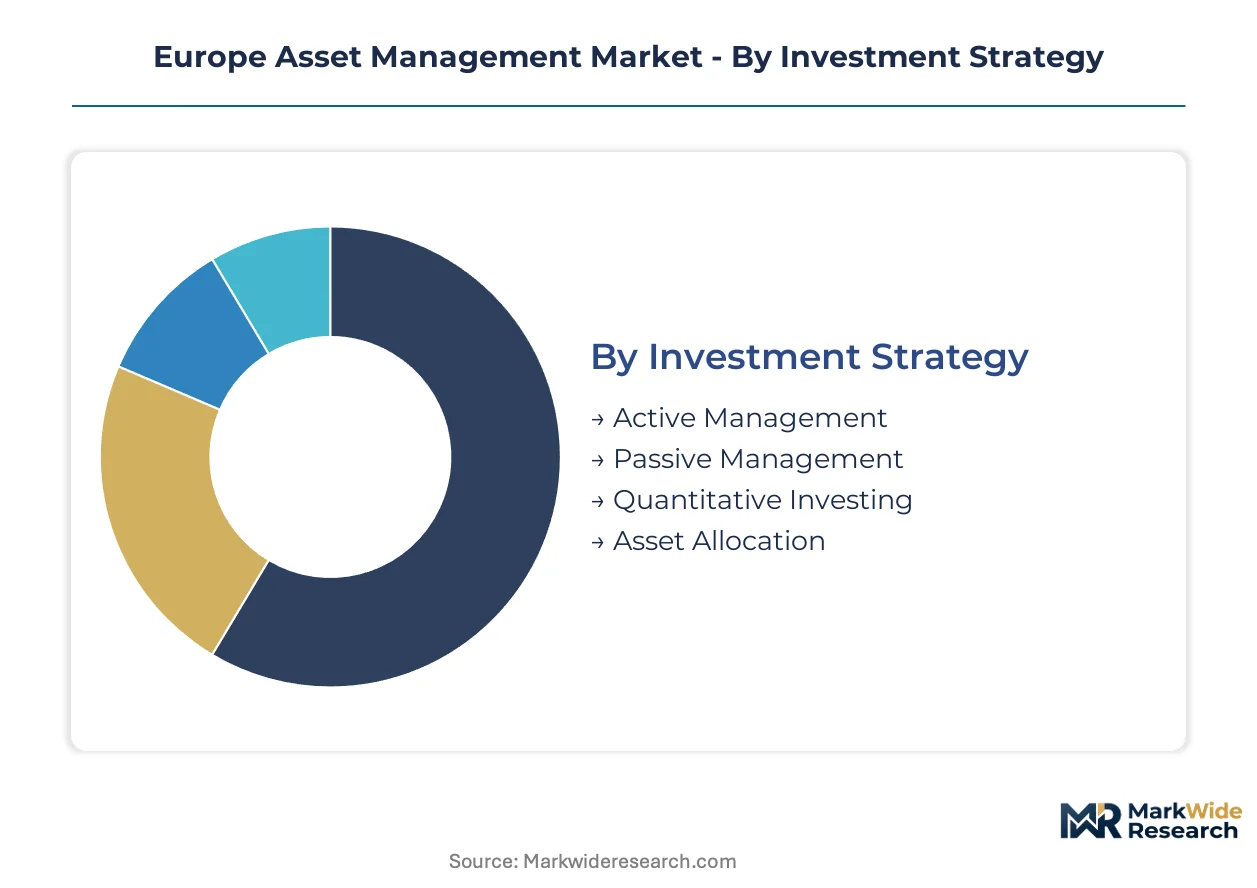
Segmentation in European asset management reveals how capital pools, vehicle structures, and investor sophistication dictate product economics. Understanding these divisions illuminates where fee compression strikes hardest and where premium pricing endures.
Investment Strategy:
Turnover velocity varies dramatically across strategic approaches, with systematic rebalancing cycles ranging from intraday to multi-year horizons.
- Active Management:Portfolio managers deploy discretionary security selection and tactical asset rotation to outperform benchmarks. German and French pension schemes still allocate meaningful capital here, though outflow pressure intensifies as performance attribution scrutiny tightens.
- Passive Management:Rules-based replication of market-cap-weighted or factor indices at minimal cost. Retail platforms across the Netherlands and Scandinavia are channeling net inflows here, driven by MiFID II cost transparency requirements.
- Quantitative Investing:Systematic factor harvesting and statistical arbitrage executed through algorithmic engines.
- Asset Allocation:Strategic and tactical multi-asset framework construction for liability-matching purposes.
Passive Management dominates installed base growth. Active Management is where margin defense concentrates.
Fund Structure:
Structural form determines liquidity transformation, regulatory burden, and distribution access across European jurisdictions.
- Open-End Funds:Continuous issuance and redemption at net asset value, typically through UCITS wrappers. These vehicles retain the bulk of continental European household savings, particularly in Germany's fund-of-funds and Italy's unit-linked insurance channels.
- Exchange-Traded Funds:Exchange-traded, creation-redemption mechanisms enabling intraday liquidity. French and German digital brokerages are expanding platform access here, compressing distribution spreads and cannibalizing traditional mutual fund flows.
- Closed-End Funds:Fixed capital pools with secondary market trading, common for illiquid alternative exposures.
- Hedge Funds:Alternative structures employing leverage and short positions, typically domiciled in Luxembourg or Ireland.
Open-End Funds anchor the installed base. Exchange-Traded Funds are climbing the fastest in net flow terms.
Investor Type:
Client sophistication and scale determine fee negotiation leverage, customization demands, and regulatory treatment under EU suitability frameworks.
- Institutional Investors:Defined-benefit pension funds, insurance general accounts, and sovereign wealth vehicles with fiduciary governance. Northern European schemes in Sweden and Denmark are reallocating here into private credit and infrastructure to match duration.
- High Net Worth Individuals:Affluent households with investable assets exceeding standard retail thresholds, demanding tax-efficient wrappers and cross-border portability. Swiss-resident EU nationals and Monaco-based entrepreneurs drive bespoke mandate growth.
- Retail Investors:Mass-market households accessing funds through bank distribution or direct platforms.
- Family Offices:Dedicated investment vehicles for single or multi-generational wealth, often with direct co-investment rights.
Institutional Investors command the deepest allocation pools. High Net Worth Individuals are where advisory unbundling is advancing most aggressively.
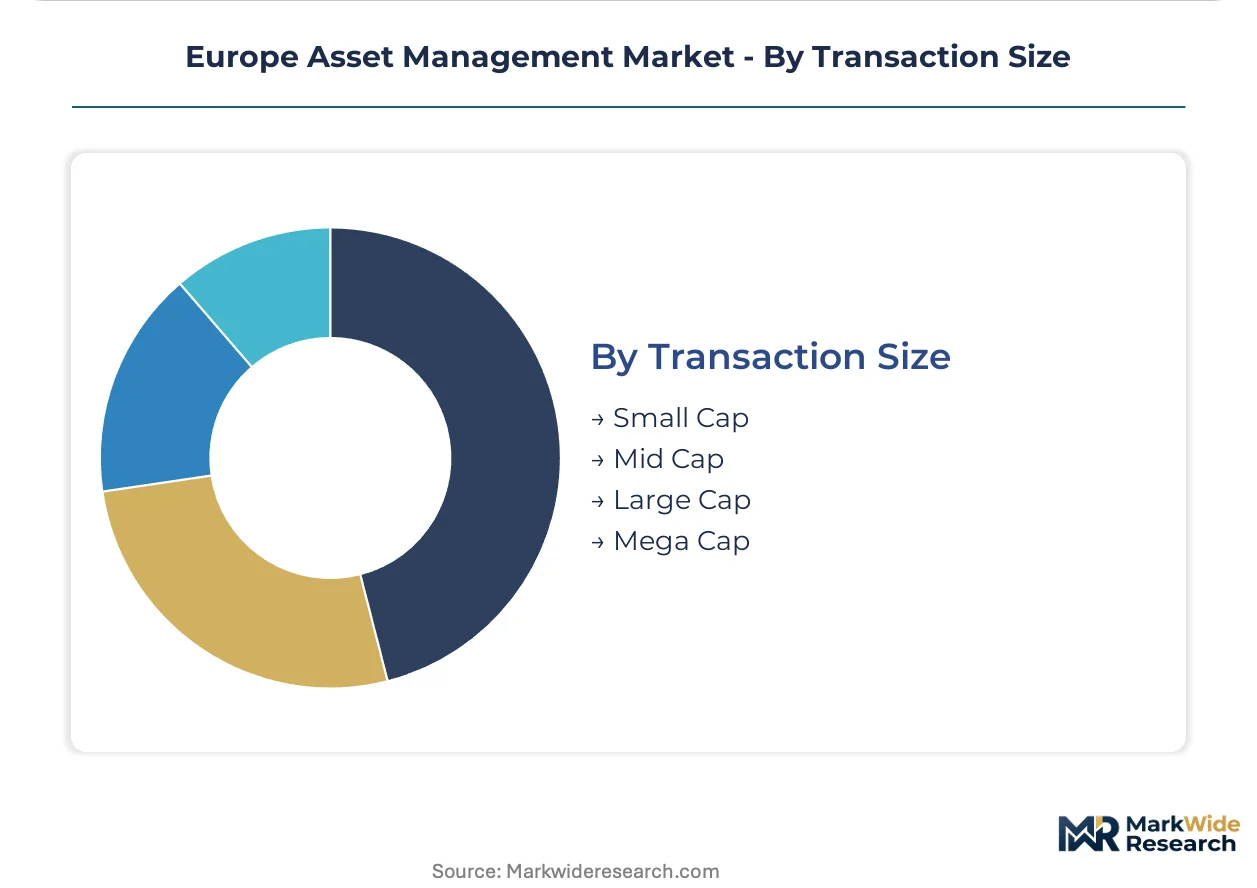
Transaction Size:
Market capitalization segmentation governs liquidity provision, research coverage economics, and index eligibility for passive replication strategies.
- Large Cap:Established issuers with deep secondary market liquidity and broad analyst coverage. Core holdings for French and German equity funds tracking Euro Stoxx 50 constituents, where passive vehicles capture the tightest tracking error.
- Small Cap:Lower-tier issuers with fragmented liquidity and sparse institutional research. Active specialists in London and Frankfurt maintain dedicated teams here, exploiting information asymmetry before quantitative signals price inefficiencies.
- Mid Cap:Transitional issuers between index tiers, often acquisition targets or spin-out candidates.
- Mega Cap:Dominant global issuers with multi-jurisdictional listings and concentrated index weights.
Large Cap anchors benchmark-driven allocation. Small Cap is where active management retention of performance fees persists most stubbornly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asset management infrastructure clusters in Northern and Western Europe, with Luxembourg and Ireland serving as dominant fund domiciliation hubs. Continental distribution networks concentrate in German and French banking centers. Regulatory divergence between national supervisors shapes cross-border product passporting economics.
Germany
BaFin's interpretation of Sustainable Finance Disclosure Regulation criteria shapes product labeling standards across the DACH region. Frankfurt anchors custody and fund administration infrastructure for UCITS vehicles. Digital brokerage platforms in Berlin and Munich are compressing distribution spreads for retail ETF access.
France
AMF enforcement of MiFID II suitability rules drives advisory unbundling in the unit-linked insurance channel. Paris-based fund manufacturers dominate ESG product origination for continental distribution. The Île-de-France cluster houses the continent's largest sustainable fund research infrastructure.
United Kingdom
Defined-benefit pension schemes in London and Edinburgh are reallocating toward private credit and infrastructure duration matching. FCA conduct rules on value-for-money assessments reshape platform economics. The City of London retains dominance in hedge fund and alternative asset servicing despite Brexit-related passporting limitations.
Netherlands
Pension fund consolidation creates concentrated institutional mandates for liability-driven investment strategies. DNB supervisory guidance on climate risk stress testing shapes portfolio construction methodologies. Amsterdam's fintech infrastructure supports tokenized fund settlement pilots.
Switzerland
FINMA's prudential framework for asset managers attracts non-EU capital seeking regulatory stability outside UCITS jurisdiction. Zurich and Geneva anchor private banking distribution for cross-border high-net-worth mandates. The country's fund infrastructure specializes in alternative investment vehicle structuring.
Europe Asset Management Market Competitive Landscape
Scale-driven passive specialists and active boutiques split the market into divergent fee-structure territories. Consolidation pressure intensifies as platform economics favor asset aggregators with manufacturing-to-distribution integration. Three archetypes dominate: diversified banking conglomerates with captive distribution, pure-play asset managers competing on performance alpha, and index specialists capturing cost-sensitive flows. Competitive moves center on ESG data infrastructure acquisitions and digital distribution platform partnerships.
Among European-headquartered institutions, Amundi and Schroders occupy positions bridging active specialization with continental scale. BlackRock anchors the passive-dominant archetype through ETF infrastructure. These entities exemplify how strategic positioning around sustainable finance capabilities and digital distribution access determines shelf space economics across fragmented national markets.
| Leading Market Players |
|---|
| DWS |
| Legal & General |
| BlackRock |
| Allianz Global Investors |
| Schroders |
| UBS |
| Vanguard |
| AXA Investment Managers |
| Amundi |
| Others |
Supply & Pricing Matrix
The Rhine-Alpine freight corridor's cost dynamics amplify supply concentration effects across European fund manufacturing, compressing distribution spreads in Germany while enabling price differentiation for Luxembourg-domiciled vehicles accessing cross-border investor pools.
Pricing Analysis
MiFID II cost transparency mandates dictate the pricing tier structure across European asset management, forcing three-tier pricing separation between premium active mandates, standard hybrid products, and economy passive trackers. Price differentiation rests on regulatory classification intensity and after-sales reporting depth. Cost compression in economy tiers intensifies because digital brokerage platforms eliminate traditional distribution spreads. Retail investors accessing funds through direct platforms exhibit highest price sensitivity, while institutional pension schemes prioritize liability-matching precision over basis-point savings.
Supply Chain Analysis
Upstream data feed licensing from Bloomberg, Refinitiv, and MSCI anchors portfolio construction infrastructure across European asset managers. Manufacturing concentrates in Luxembourg and Ireland for UCITS vehicles, with France and Germany hosting dominant distribution networks. Supply chain risk centers on single-source vulnerability for ESG data provision, where Sustainalytics and MSCI control taxonomy-alignment scoring. Distribution runs through bank-owned captive networks in Italy and Spain, though open-architecture platforms in the Netherlands and Scandinavia are gaining shelf access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European asset management is entering a cyclical recovery phase as pension fund de-risking cycles reverse and institutional rebalancing accelerates capital deployment into duration-matching strategies.
For Market Incumbents: Build switching-cost moats through proprietary ESG data infrastructure and embedded portfolio analytics. Incumbents should deepen API connectivity with core banking platforms at German and French distributors to lock in shelf access. Acquiring specialist climate-risk modeling capabilities addresses the quantitative sustainable finance talent shortage threatening product velocity. For New Entrants and Emerging Players: Build out digital-first distribution infrastructure targeting Poland and Romania's underpenetrated retail wealth pools. White-space concentration exists in CSRD-driven carbon accounting services for mid-sized asset managers lacking in-house transition pathway modeling. A regulatory-technology positioning—delivering MiFID II compliance automation—secures advisory platform partnerships faster than competing on investment performance. For Investors and Strategic Acquirers: Carve-out targets emerge from banking conglomerates spinning non-core asset management units under shareholder pressure. Long-term viability favors boutiques with demonstrated emerging-market debt or infrastructure specialization, where active management retains pricing power. Watch for inflection signals in BaFin-AMF regulatory convergence on sustainable investment criteria, which would unlock cross-border passporting economies.| Strategic Initiative | Industry Significance |
|---|---|
| ESG Data Infrastructure Acquisition | Integrating Sustainalytics or Clarity AI capabilities addresses CSRD-driven demand for portfolio-level carbon accounting. |
| Digital Distribution Platform Partnership | White-label arrangements with Trade Republic or Scalable Capital bypass traditional bank distribution gatekeepers. |
| Tokenized Fund Structure Development | Luxembourg CSSF sandbox participation enables fractional real-asset ownership through distributed ledger settlement. |
| Climate Risk Modeling Capability Buildout | Scenario analysis tools meeting DNB stress-testing guidance attract Dutch pension fund consolidation mandates. |
| Central European Market Entry | Warsaw and Bucharest regulatory licensing captures first-mover advantage in EU's fastest-growing retail wealth pools. |
Research Methodology
Two parallel data streams informed the analysis: structured conversations with fund manufacturing executives, distribution platform heads, regulatory affairs leads at national supervisors, and pension fund investment officers; combined with secondary validation from UCITS fund flow databases, AMF and BaFin enforcement disclosures, EFAMA statistical releases, and EIOPA stress-testing documentation. Bottom-up asset aggregation and top-down macro allocation models were triangulated against reported AUM figures.
Forecast inputs span investment strategy segmentation, fund structure vehicle types, investor sophistication tiers, and transaction size capitalization bands across the modeling period. CAGRs were derived from historical flow trajectories and liability-driven investment cycle positioning. Specific forecast inputs include EU Green Deal capital redirection velocity and MiFID II inducement rule enforcement intensity.
Practitioners should monitor regulatory divergence between AMF and BaFin taxonomy interpretations for early signals of passporting friction. Forecasts reflect assumptions about institutional rebalancing appetite and retail platform adoption curves. Cross-checking against EFAMA quarterly fund flow benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Asset Management
Fund Management Software Market
Asset Management
US Healthcare Assets Management Market
Asset Management
Fixed Income Asset Management Market
Asset Management
Fund Management Fee Market
Asset Management
Capital Expenditure Market
Asset Management
US Pension Funds Market
Asset Management
India Mutual Fund Market
Asset Management
Global Remote Asset Management Market
Asset Management
Hardware Asset Management Market
Asset Management
Smart Asset Management Market
Asset Management
Asset and Wealth Management Market
Asset Management
Global Asset Performance Management Market
Asset Management
LAMEA Equity Management Software Market
Asset Management
Global Infrastructure Asset Management Market
Asset Management
Japan Asset Management Market
Asset Management
Assets Under Management Market