
 Gallbladder Treatment Market | 2026-2036
Gallbladder Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Gallbladder Treatment Market Analysis
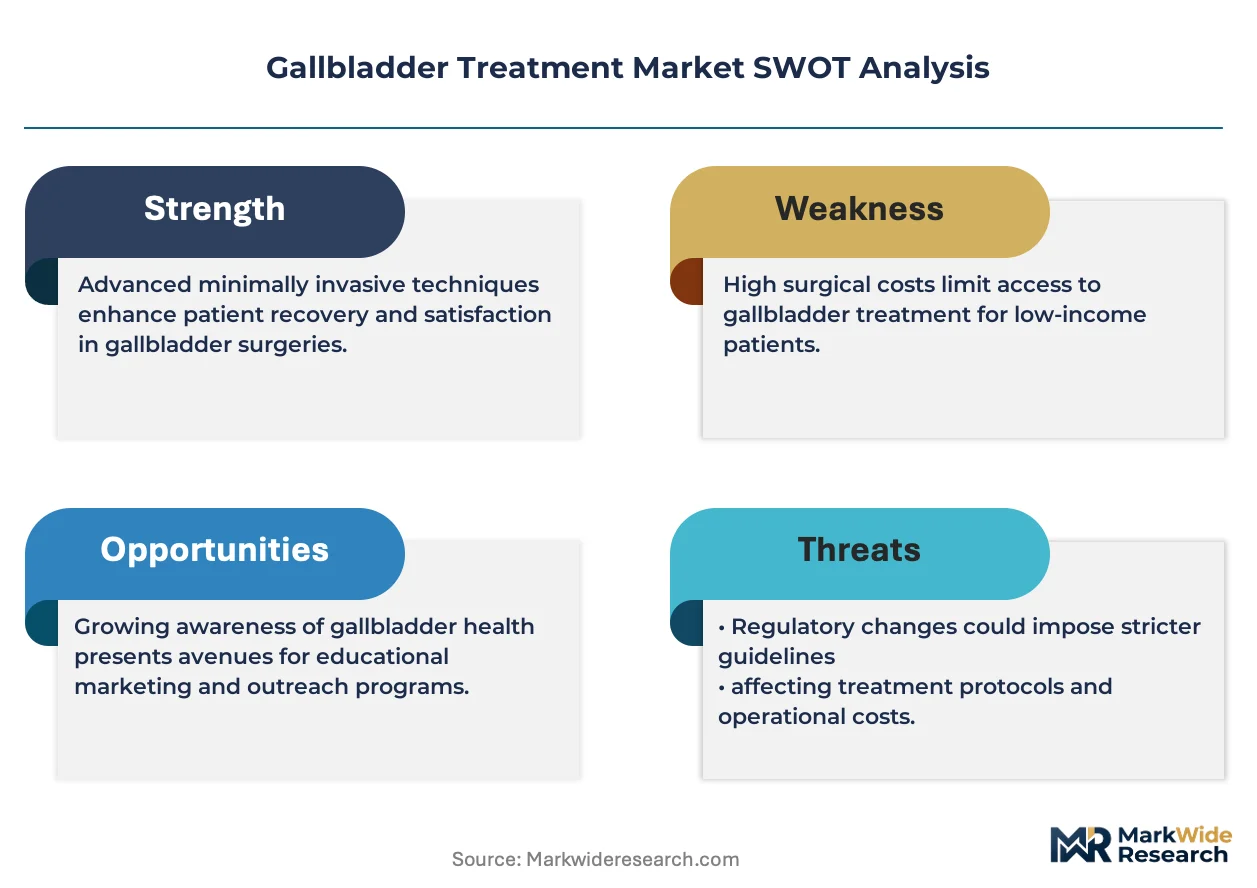
Procedure bundling is rebalancing how payers and hospitals evaluate cholecystectomy economics. Medtronic leverages its integrated surgical portfolio to capture value across laparoscopic instrument sets. Cook Medical anchors its position through specialized endoscopic retrieval devices for complex biliary cases. Boston Scientific competes via advanced sphincterotome designs that reduce procedural complications.
Gallbladder treatment encompasses surgical, pharmacological, and interventional modalities targeting cholelithiasis, cholecystitis, and biliary dyskinesia, with laparoscopic cholecystectomy representing the gold standard involving four 5-12 mm trocar incisions and CO2 insufflation at 12-15 mmHg. The primary purpose is to restore biliary drainage, eliminate symptomatic stone disease, and prevent complications including gallbladder perforation or pancreatitis. Laparoscopic technology leads procedural volume due to established reimbursement pathways and shorter recovery profiles, while robotic platforms represent the fastest-expanding segment as capital costs decline and surgeon training programs proliferate. Medications occupy a mature margin pool serving non-surgical candidates and asymptomatic stone management.
FDA 510(k) clearance pathways shape device commercialization timelines for novel retrieval bags and energy platforms, while the EU MDR transition extends conformity assessment durations for laparoscopic instruments entering European markets. ISO 13485 quality management requirements govern manufacturing consistency across multinational supply chains. Stakeholders must monitor how CMS bundled payment revisions and comparable health technology assessment frameworks in Germany and Japan will redistribute margin capture between device manufacturers and surgical providers.
Market Dynamics
Procedure bundling under CMS payment revisions is compressing margins across laparoscopic instrument sets while accelerating capital deployment into robotic surgical platforms. This structural force is redistributing value capture from device manufacturers toward integrated surgical providers.
Growth Catalysts
- Ambulatory Surgery Center Expansion:United States payers are expanding same-day discharge reimbursement for laparoscopic cholecystectomy, shifting procedural volume from inpatient to outpatient settings and expanding addressable cases for minimally invasive device portfolios.
- EU MDR Harmonization:The Medical Device Regulation transition is consolidating conformity assessment pathways across Germany, France, and Italy, reducing fragmentation for laparoscopic instrument manufacturers seeking multi-country market access.
- Single-Incision Laparoscopy:Advanced trocar designs and articulating instruments are enabling reduced-port cholecystectomy, differentiating premium device suites in competitive hospital procurement cycles.
Market Restraints
- Capital Intensity of Robotic Platforms:Da Vinci system acquisition costs and per-procedure instrument consumables create adoption barriers for mid-tier hospitals and regional medical centers.
- Specialized Surgeon Training Requirements:Proficiency in single-incision and robotic cholecystectomy demands extended learning curves, constraining procedural volume growth outside academic medical centers.
- Reimbursement Compression:CMS bundled payment revisions for gallbladder procedures are capping device spend per episode, pressuring manufacturer pricing power across standard laparoscopic instrument categories.
Strategic Opportunities
- Japan's Aging Surgical Population:METI healthcare infrastructure investments and PMDA accelerated review pathways for robotic surgery systems create favorable entry conditions for next-generation platforms targeting elderly cholelithiasis patients.
- Disposable Retrieval Device Premiumization:Complex biliary cases requiring specialized endoscopic stone extraction bags command pricing premiums and recurring revenue streams in tertiary care settings.
- Integrated Energy Platform Convergence:Combination ultrasonic-electrosurgical devices for gallbladder bed hemostasis are consolidating instrument counts per procedure, creating value-capture opportunities for multi-modality platform vendors.
Industry Challenges
- ISO 13485 Supply Chain Certification:Multinational manufacturers face audit complexity and documentation burdens when qualifying component suppliers across dispersed manufacturing geographies.
- Surgeon Training Program Scalability:Proctoring requirements and simulation-based credentialing for robotic cholecystectomy create bottlenecks in expanding addressable operator pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gallbladder Treatment Market |
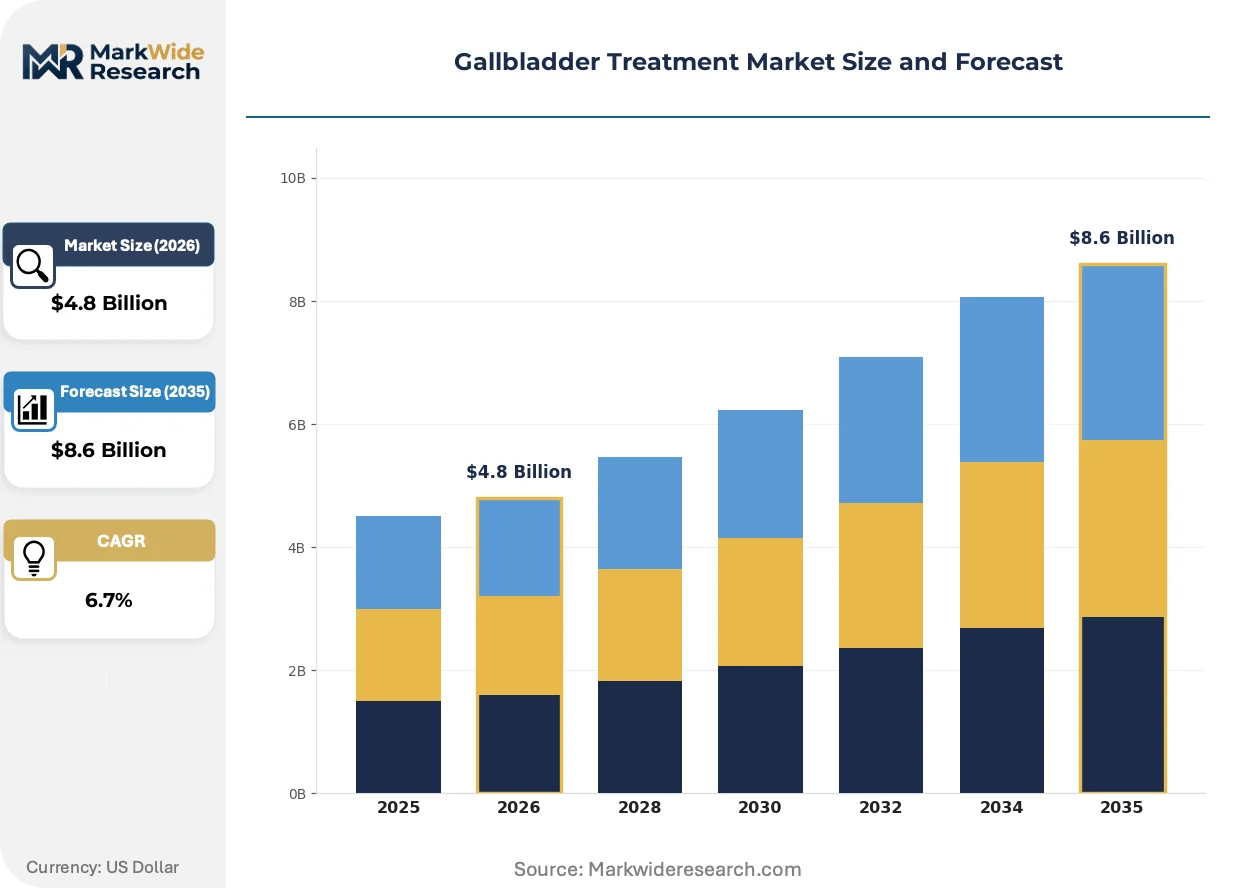
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Surgery, Therapy, Dietary Supplements Technology: Laparoscopic, Open Surgery, Endoscopic, Robotic End User: Hospitals, Clinics, Outpatient Centers, Home Care Treatment Method: Cholecystectomy, Medication Management, Lifestyle Modification, Watchful Waiting |
| Companies Covered | Cook Medical, Medtronic, Abbott Laboratories, Stryker Corporation, Olympus Corporation, Becton, Dickinson and Company, ConMed Corporation, Johnson & Johnson, Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gallbladder Treatment Market Emerging Trajectories
Digital surgical platforms and intelligent instrumentation are redefining intraoperative decision support in gallbladder procedures. These technologies are compressing variation in surgical outcomes while creating new data monetization pathways for device manufacturers.
Firefly fluorescence imaging is integrating near-infrared cholangiography into standard laparoscopic workflows, enabling real-time visualization of biliary anatomy without fluoroscopy. Academic medical centers in Germany and the United States are adopting this capability for complex revision cases and aberrant ductal anatomy. The technology is integrating preoperative imaging fusion with intraoperative navigation, reducing common bile duct injury rates and supporting premium platform positioning.
Japan's PMDA has streamlined software-as-a-medical-device classification for surgical navigation systems, accelerating commercialization timelines for AI-enabled anatomy recognition tools. This regulatory pathway reduces premarket submission burdens for machine learning-based cholangiography interpretation algorithms. European manufacturers are responding by establishing Tokyo-based regulatory affairs capabilities to access this accelerated framework.
Hospital procurement committees are consolidating vendor relationships through integrated surgical platform contracts spanning energy devices, imaging systems, and robotic consoles. This purchasing pattern is displacing discrete instrument sourcing and favoring manufacturers with comprehensive laparoscopic portfolios. The shift is most pronounced in United States integrated delivery networks and German hospital alliances seeking standardization across multi-site surgical programs.
Gallbladder Treatment Market Segmentation
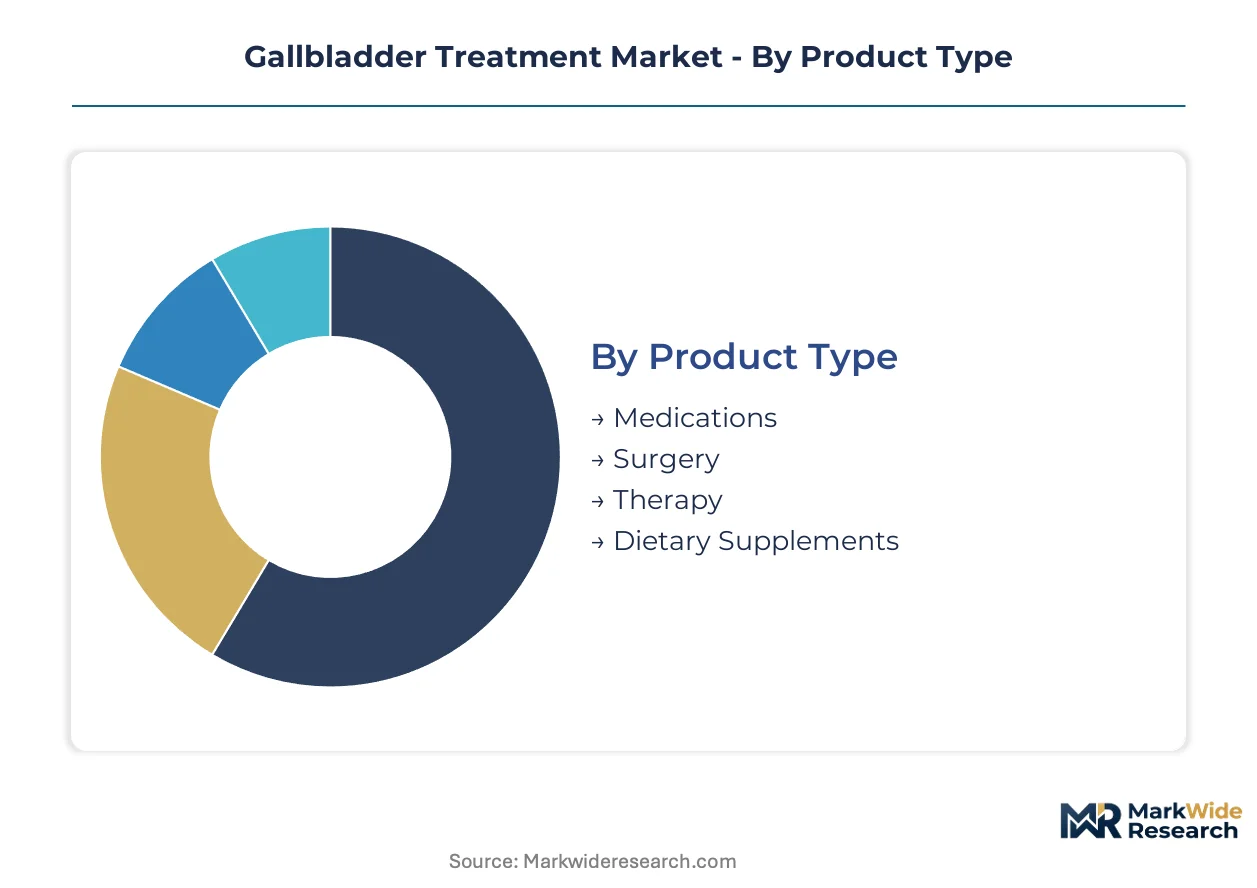
Segmentation in gallbladder treatment reveals divergent capital requirements and margin profiles across modalities. Surgical platforms demand substantial upfront investment in instrumentation and training infrastructure, while pharmaceutical and conservative management segments operate on lighter asset bases with recurring revenue characteristics.
Product Type:
Surgery commands the highest capital intensity through operating room infrastructure, sterilization systems, and specialized instrument sets. Medications and dietary supplements require comparatively modest manufacturing footprints but face distinct regulatory pathways.
- Surgery:Laparoscopic and robotic cholecystectomy systems entail capital outlays for insufflators, energy platforms, and visualization towers. Demand concentrates in United States hospital systems expanding ambulatory surgery programs, driven by CMS reimbursement shifts favoring same-day discharge protocols.
- Medications:Ursodeoxycholic acid formulations and pain management protocols serve non-surgical candidates and preoperative stabilization. Prescription volumes track diagnostic detection rates in Germany and Japan, where imaging access expands asymptomatic stone identification.
- Therapy:Extracorporeal shock wave lithotripsy and drainage procedures occupy niche indications for high-risk surgical candidates. Applications center on tertiary referral centers managing complex biliary obstruction cases.
- Dietary Supplements:Over-the-counter formulations targeting cholesterol saturation and digestive support serve preventive health segments. Distribution runs through retail pharmacy chains and direct-to-consumer channels with minimal clinical oversight requirements.
Surgery absorbs the bulk of installed capacity; Therapy is expanding most quickly among non-surgical alternatives.
Technology:
Technology segmentation tracks the migration from invasive to minimally invasive platforms, with capital deployment intensity varying dramatically across modalities.
- Laparoscopic:Four-port trocar configurations with CO2 insufflation at 12-15 mmHg constitute the procedural standard. United States integrated delivery networks and German hospital alliances standardize on multi-modal energy platforms combining ultrasonic and electrosurgical capabilities.
- Robotic:Da Vinci and competing platforms enable single-site cholecystectomy with wristed instrumentation. Japan's METI infrastructure investments and PMDA accelerated review pathways are reducing adoption barriers for next-generation systems targeting elderly patient populations.
- Open Surgery:Conventional incision techniques persist for emergency cases with perforated gallbladders or severe inflammation. Volume concentrates in resource-limited settings and trauma contexts where laparoscopic conversion fails.
- Endoscopic:ERCP-based stone extraction and sphincterotomy address choledocholithiasis without cholecystectomy. Complex biliary cases in tertiary United States centers drive demand for specialized retrieval devices and cholangioscopy platforms.
Laparoscopic platforms dominate procedural volume; Robotic systems are gaining share fastest as capital costs decline and training programs proliferate.
End User:
End user segmentation reflects the decentralization of gallbladder care from inpatient facilities toward lower-acuity settings, with reimbursement policy as the primary structural determinant.
- Hospitals:Inpatient surgical suites manage complex cases requiring overnight observation and emergency conversion capabilities. Academic medical centers in the United States and Germany anchor training pipelines for advanced laparoscopic and robotic techniques.
- Outpatient Centers:Ambulatory surgery facilities capture elective cholecystectomy volume under expanded Medicare and commercial payer same-day discharge policies. United States payers are actively shifting low-risk cases from hospital outpatient departments to independent ASCs.
- Clinics:Primary and specialty clinics manage diagnostic workup, medical therapy initiation, and postoperative surveillance. Japan's aging population drives clinic-based monitoring for asymptomatic stone management.
- Home Care:Post-discharge recovery support and medication adherence programs serve patients following ambulatory procedures. German statutory health insurance frameworks increasingly cover home nursing for elderly cholecystectomy patients.
Hospitals retain the majority of complex case volume; Outpatient Centers are climbing the fastest as reimbursement migrates toward lower-cost settings.
Treatment Method:
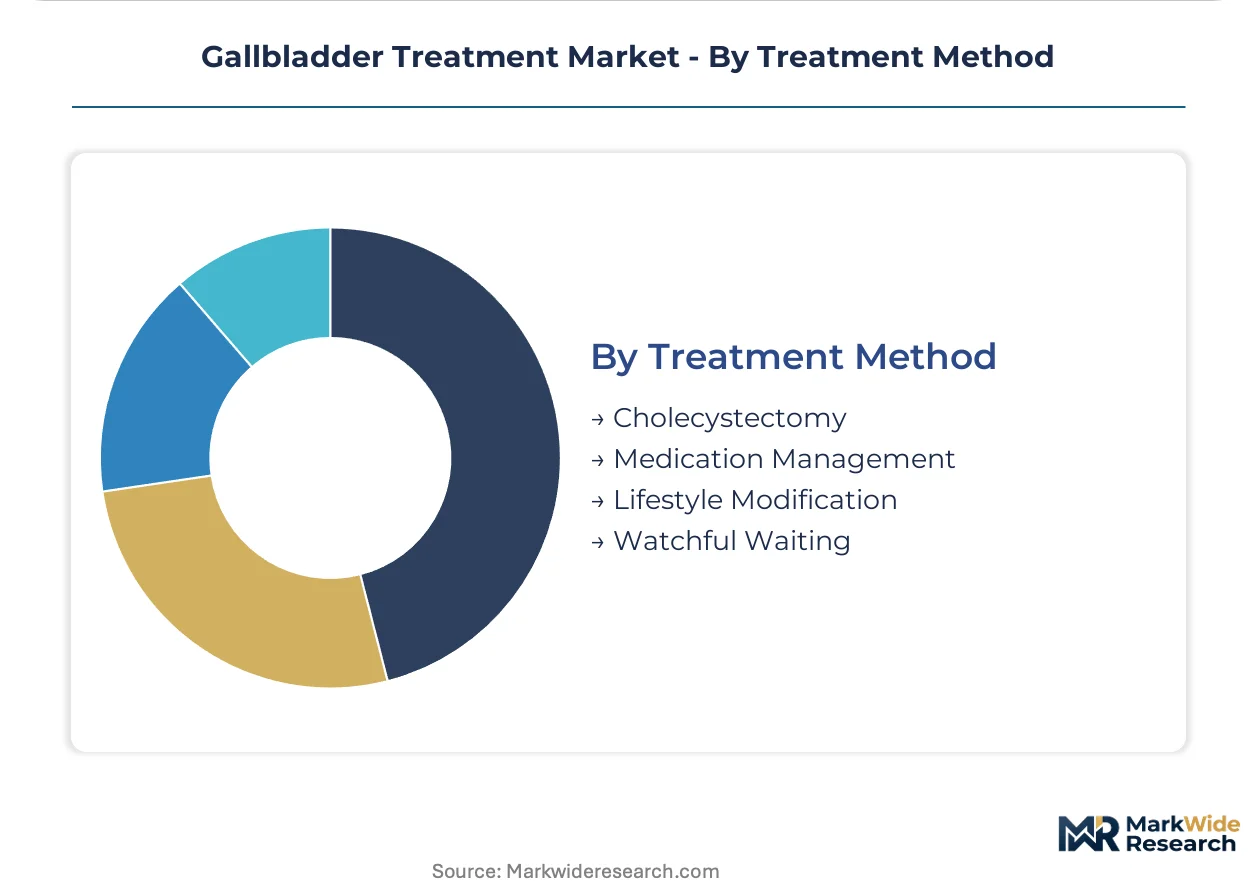
Treatment method segmentation distinguishes definitive surgical intervention from conservative management pathways, with patient selection criteria driving method allocation.
- Cholecystectomy:Surgical gallbladder removal eliminates recurrence risk and remains the definitive intervention for symptomatic cholelithiasis. United States procedural volume benefits from expanded ambulatory eligibility and streamlined preoperative pathways.
- Medication Management:Dissolution therapy and symptom control serve patients with surgical contraindications or patient-declined intervention. German primary care networks maintain substantial prescription volumes for ursodeoxycholic acid in elderly populations.
- Lifestyle Modification:Dietary intervention and weight management target cholesterol stone formation in metabolic syndrome patients. Wellness program integration in Japanese corporate health plans supports preventive engagement.
- Watchful Waiting:Active surveillance for asymptomatic stones avoids intervention risks in low-probability progression cases. Shared decision-making protocols in United States academic centers are formalizing observation pathways with defined escalation triggers.
Cholecystectomy captures the dominant share of definitive treatment; Watchful Waiting is expanding most quickly as imaging detection outpaces symptomatic conversion rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device production concentrates in the United States, Germany, and Japan while procedural consumption spreads across aging populations in all three markets. Manufacturing clusters serve regional demand through localized sterilization and distribution networks. Regulatory harmonization efforts are reshaping cross-border commercialization timelines.
United States
FDA 510(k) clearance pathways enable rapid commercialization for novel retrieval devices and energy platforms. CMS bundled payment revisions for cholecystectomy are compressing device margins while accelerating ambulatory surgery center volume migration. Minneapolis and Irvine anchor laparoscopic instrument manufacturing clusters serving integrated delivery networks.
Germany
EU MDR conformity assessment transitions are extending market entry timelines for laparoscopic portfolios seeking CE marking renewal. German hospital alliances standardize procurement across multi-site surgical programs, favoring comprehensive platform vendors. Tübingen and Erlangen host precision instrument manufacturing serving tertiary care networks.
Japan
METI healthcare infrastructure investments target surgical capacity expansion for elderly cholelithiasis patients. PMDA accelerated review pathways for robotic surgery systems reduce premarket submission burdens for next-generation platforms. Tokyo and Osaka medical device clusters concentrate regulatory affairs capabilities for software-as-a-medical-device classifications.
United Kingdom
NHS England procurement frameworks prioritize value-based assessment for laparoscopic instrument sets across hospital trusts. MHRA post-Brexit regulatory autonomy enables divergence from EU MDR timelines for certain device categories. Oxford and Cambridge surgical innovation corridors anchor academic-industry partnerships for fluorescence imaging development.
South Korea
MFDS streamlined approval processes for minimally invasive surgical devices support domestic manufacturer competitiveness. National health insurance reimbursement expansion for single-incision cholecystectomy drives hospital capital investment. Seoul Capital Area medical centers anchor training pipelines for advanced laparoscopic techniques.
Gallbladder Treatment Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across instrument, imaging, and energy platform categories. The vendor base organizes into three tiers: comprehensive surgical portfolio holders, retrieval device specialists, and regional equipment fabricators. Market structure rewards integrated platform contracts spanning visualization, energy, and instrumentation. Dominant competitive moves include hospital procurement consolidation and robotic console placement strategies.
Within the diversified surgical portfolio tier, Medtronic and Johnson & Johnson exemplify comprehensive platform positioning spanning laparoscopic and robotic modalities. Cook Medical occupies a specialist position in complex biliary retrieval devices. Olympus Corporation anchors visualization and endoscopic instrumentation capabilities. Boston Scientific represents advanced interventional approaches through sphincterotome and drainage device portfolios.
| Leading Market Players |
|---|
| Cook Medical |
| Medtronic |
| Abbott Laboratories |
| Stryker Corporation |
| Olympus Corporation |
| Becton, Dickinson and Company |
| ConMed Corporation |
| Johnson & Johnson |
| Boston Scientific Corporation |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up surgical instrument specialists have consolidated manufacturing footprints across Minnesota and Bavaria, tightening supply discipline while enabling three-tier pricing structures across premium, standard, and economy instrument sets. This ownership pattern concentrates procurement leverage among integrated delivery networks and German hospital alliances, compressing margins for standalone device vendors.
Pricing Analysis
Margin tightening in standard laparoscopic instrument sets reflects CMS bundled payment revisions capping device spend per cholecystectomy episode. Three-tier pricing structure across premium, standard, and economy levels segments by FDA 510(k) clearance tier and after-sales service bundling. Cost-down pressure on retrieval bags accelerates because hospital procurement committees consolidate vendor relationships. Ambulatory surgery centers exhibit highest price sensitivity; academic medical centers with robotic training programs show lowest.
Supply Chain Analysis
Japan's domestic-content mandates for METI-funded healthcare infrastructure are reshaping sourcing patterns for robotic surgical platforms entering Tokyo and Osaka medical centers. Manufacturing concentrates in the United States, Germany, and Japan for laparoscopic instruments. Supply chains draw from medical-grade stainless steel, polymer trocar components, and specialized optical fibers. Single-source vulnerability persists for articulating instrument wrist mechanisms. Distribution runs through GPO contracts and direct hospital procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Surgeon training program bottlenecks constrain operator pool expansion, propping pricing power for platforms with established credentialing pathways. Capacity scarcity in proctored robotic certification limits addressable market growth.
For Market Incumbents: Lock in integrated platform contracts spanning energy devices, imaging systems, and robotic consoles before procurement committee consolidation completes. Defend against specialized retrieval device specialists by deepening backward integration into endoscopic bag manufacturing. Prioritize certification investment in PMDA accelerated review pathways for software-as-a-medical-device classifications. For New Entrants and Emerging Players: Direct-to-surgeon digital training platforms offer low-friction entry before hospital procurement centralizes vendor relationships. Target Japan's aging surgical population with next-generation single-incision platforms. Pursue white-space in complex biliary retrieval devices for tertiary United States centers. For Investors and Strategic Acquirers: FDA 510(k) clearance for near-infrared cholangiography integration is the leading indicator that fluorescence imaging platforms will capture premium positioning. Five-to-ten year viability favors manufacturers with comprehensive laparoscopic portfolios over pure-play retrieval specialists. Watch for PMDA software-as-a-medical-device approvals as inflection signal for AI-enabled surgical navigation.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Integrated delivery network contracts lock in multi-year instrument set commitments across ambulatory expansion. |
| CE Marking Pathway | EU MDR conformity assessment renewal secures German hospital alliance access amid regulatory transition. |
| Software Companion Development | AI-enabled anatomy recognition tools qualify for PMDA accelerated review in Tokyo regulatory affairs hubs. |
| Reimbursement Strategy | CMS bundled payment navigation preserves margin capture for robotic platform vendors in United States ASCs. |
| FDA Submission | 510(k) clearance for Firefly fluorescence imaging integration differentiates premium visualization platforms. |
Methodological Framework
Document review covered FDA 510(k) filings, CMS Medicare reimbursement databases, and EU MDR conformity assessment records, complemented by interviews with hospital purchasing committee directors, GPO contracts managers, and biomedical engineers specializing in minimally invasive surgery. Secondary validation drew from hospital procurement databases, PMDA approval summaries, and METI healthcare infrastructure investment disclosures. Bottom-up procedural volume estimates triangulated against top-down device shipment data.
Segmented outputs across product type, technology platform, end-user setting, and treatment method dimensions fed into the analytical framework over the projection horizon. CAGRs were derived from installed base growth, replacement cycles, and ambulatory surgery center expansion trajectories. Forecast inputs incorporated surgeon training program scalability constraints and reimbursement policy migration patterns.
Inputs from PMDA and FDA regulatory tracking systems were available through the study window; gaps in real-time hospital procurement transaction data introduce uncertainty bands around price elasticity assumptions. Forecasts reflect documented assumptions regarding CMS policy stability and EU MDR implementation timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Corneal Transplant Market
Medical Treatment
Ventral Hernia Treatment Market
Medical Treatment
Leprosy Treatment Market
Medical Treatment
Intensity Modulated Radiation Therapy Market
Medical Treatment
Hyperammonemia Treatment Market
Medical Treatment
Transplantation Market
Medical Treatment
Migraine Treatment Market
Medical Treatment
Global Uterine Fibroids Treatment Market
Medical Treatment
Mexico Hair Transplant Market
Medical Treatment
Global Thyroid Disorder Treatment Market
Medical Treatment
Dementia Treatment Market
Medical Treatment
Dyspareunia Treatment Market
Medical Treatment
Dementia and Alzheimers Disease Treatment Market
Medical Treatment
Global Acromegaly Treatment Market
Medical Treatment
Stereotactic Radiation Therapy Market
Medical Treatment
Histiocytosis Treatment Market