
 Lice Treatment Market | 2026-2036
Lice Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Lice Treatment Market Intelligence
The capability gap between firms with integrated R&D for novel, non-toxic formulations and those reliant on traditional permethrin-based products is collapsing. Prestige Consumer Healthcare leverages its strong brand recognition and legacy status in the over-the-counter space, while Perrigo Company competes effectively through its extensive private-label manufacturing scale for major drugstores. Johnson & Johnson Services sustains its market position through a highly diversified portfolio and deep, established distribution channels reaching both pharmacies and supermarkets.
Lice treatment involves topical products formulated to eradicate infestations of head lice, primarily Pediculus humanus capitis. These treatments function either as neurotoxic pediculicides, such as permethrin, or as physical agents like dimethicone, which suffocates lice and their eggs. While shampoos and lotions represent the largest product segments, specialized combs are essential for physical removal and efficacy verification. Sales through pharmacies and recommendations from pediatricians constitute the core pathways to the end user, shaping brand trust and product adoption.
Product classification and market access are controlled by regulators like the U.S. FDA, the European Medicines Agency (EMA), and Health Canada. These bodies enforce stringent safety and efficacy standards, particularly for formulations intended for pediatric use, which represent the largest consumer base. The primary strategic challenge for all manufacturers remains developing effective solutions to overcome increasing lice resistance to traditional chemical treatments.
Market Dynamics
The central structural force shaping the lice treatment market is the escalating resistance of lice to traditional neurotoxic pediculicides. This biological pressure, combined with heightened safety scrutiny from regulators, is compelling a fundamental shift toward non-pesticide formulations and physical eradication methods.
Growth Catalysts
- Non-Pesticide Formulations:The development of treatments using physical agents like dimethicone, which suffocates lice, bypasses resistance issues. These products meet demand from safety-conscious parents and align with stricter pediatric guidelines from bodies like the U.S. FDA.
- Persistent Infestation Rates:High-density environments such as school clinics and daycare centers, particularly in the United States and Western Europe, experience continuous and recurring outbreaks. This creates a consistent, year-round demand base for effective treatment and prevention products.
- Preventative Product Lines:Manufacturers are expanding into preventative sprays and shampoos containing natural repellents. This strategy taps into a new revenue stream by addressing parental anxiety about initial infestations and re-infestations following treatment.
Market Restraints
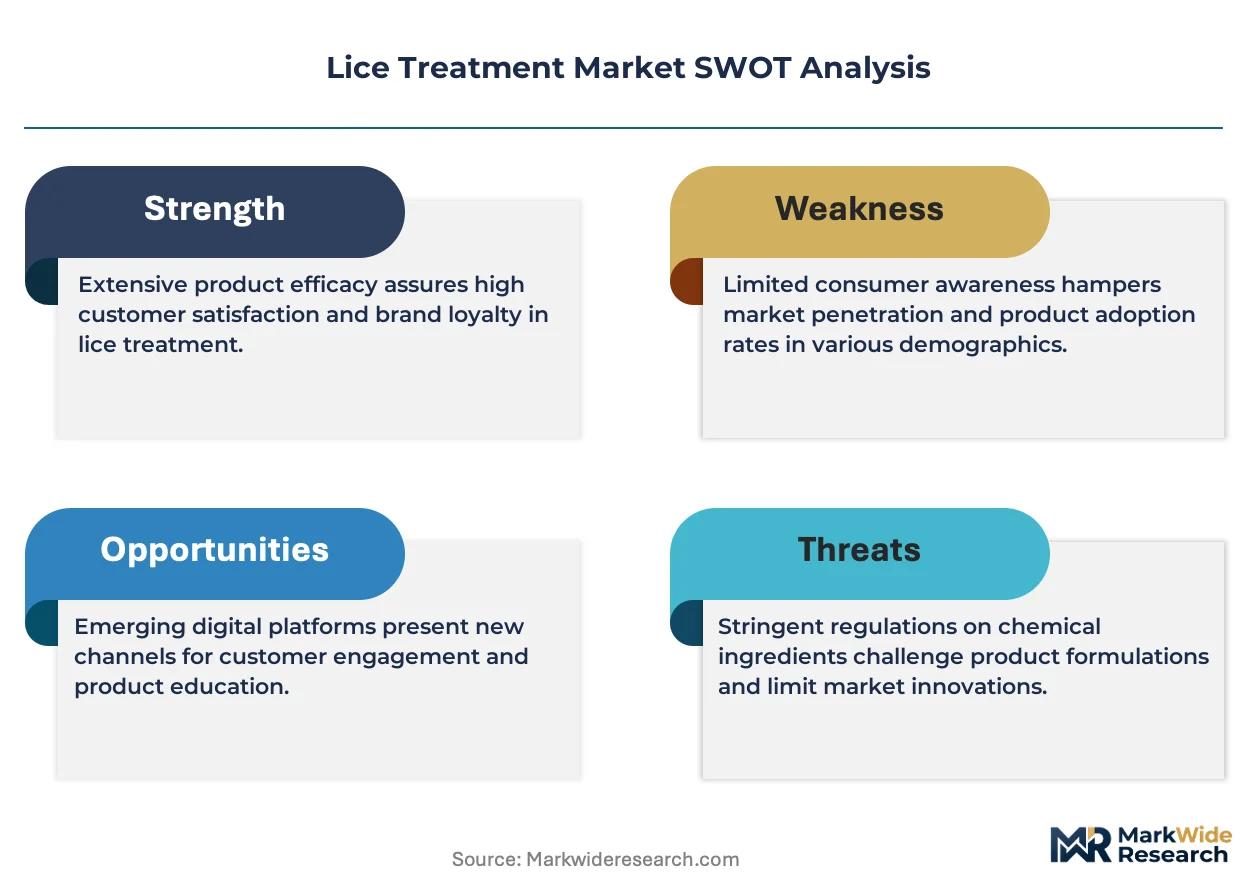
- Pediculicide Resistance:Widespread and genetically inherited resistance to permethrin and pyrethrins renders many legacy over-the-counter products ineffective. This erodes consumer trust and forces costly R&D for alternative active ingredients.
- Substitution by Manual Methods:The perceived failure of chemical treatments leads many consumers to opt for meticulous combing with specialized nit combs as a primary, low-cost alternative. This non-consumption represents a significant revenue barrier for product manufacturers.
- Regulatory Approval Timelines:Gaining market authorization for novel active ingredients from agencies like the EMA or Health Canada is a lengthy and expensive process. These rigorous clinical trial requirements can delay the introduction of more effective solutions.
Strategic Opportunities
- Integrated Treatment Kits:Assembling comprehensive kits that bundle a non-toxic lotion, a high-efficacy comb, and post-treatment preventative spray offers added value. This approach simplifies the consumer purchasing process and improves treatment outcomes, justifying a premium price.
- Channel Expansion into School Health:Developing direct sales and partnership programs with school districts and pediatric clinics creates a new distribution channel. This strategy builds brand trust and captures consumers at the primary point of diagnosis.
- Emerging Market Penetration:Targeting middle-income countries in Latin America and Southeast Asia with affordable and effective formulations presents a major growth vector. These regions have large pediatric populations and developing public health infrastructure.
Industry Challenges
- Consumer Education on Efficacy:A primary operational challenge involves educating parents and healthcare providers about the correct application of new formulations and the importance of follow-up combing. Misuse of products leads to perceived treatment failure and brand damage.
- Navigating Marketing Regulations:Manufacturers must carefully manage product claims to comply with strict advertising standards set by the U.S. FTC and equivalent bodies in Europe. Differentiating product efficacy without making unsubstantiated claims is a constant hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lice Treatment Market |
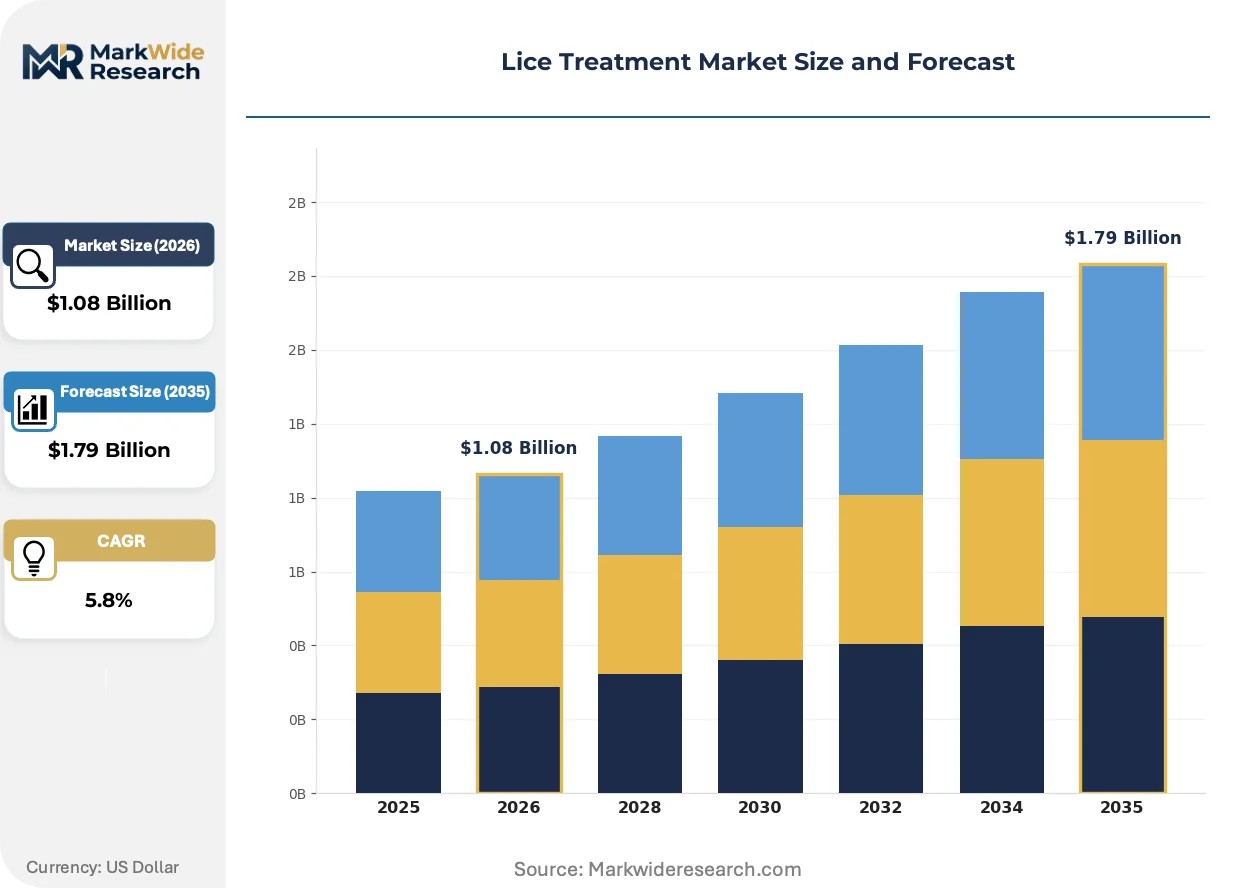
| Market Size in 2026 | $1.08 Billion |
| Market Size in 2035 | $1.79 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoo, Lotion, Spray, Comb, Conditioner, Gel Application: Pediatric Use, Geriatric Care, School Clinics, Travel Kits, Sports Teams, Military End User: Pharmacies, Dermatology Clinics, Pediatricians, Hair Salons, Online Retail, Mobile Clinics Distribution Channel: Drugstores, E-commerce, Supermarkets, Specialty Retailers, Direct Sales, Hospitals |
| Companies Covered | Prestige Consumer Healthcare, Perrigo Company, Johnson & Johnson Services, GlaxoSmithKline, Arbor Pharmaceuticals, Alliance Pharmaceuticals, Oystershell Consumer Health, Reckitt Benckiser Group, Bayer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lice Treatment Market Strategic Shifts & Innovations
The market's evolution is defined by a clear pivot away from neurotoxic chemicals toward solutions emphasizing physical mechanisms and enhanced safety profiles. This shift is driven by a combination of biological resistance, regulatory pressure, and changing consumer preferences for non-pesticide products for children.
Formulations based on silicone oils like dimethicone function by physically blocking the respiratory spiracles of lice, leading to suffocation. Parents and school nurses are rapidly adopting these non-toxic options due to concerns about pesticide exposure and the ineffectiveness of older treatments. The proliferation of these physical-action agents is fragmenting the product landscape once dominated by a few key chemical compounds like permethrin.
Regulatory scrutiny from the European Medicines Agency (EMA) and the U.S. FDA is forcing a higher standard for pediatric topical products. These agencies now favor formulations with minimal systemic absorption and non-neurotoxic modes of action, influencing R&D priorities across the industry. Consequently, over-the-counter products sold in pharmacies, especially within the EU, face increasing pressure to provide extensive safety data or be reformulated.
Consumer purchasing behavior is moving from purely reactive treatment to a more holistic cycle of prevention, detection, and eradication. The single pharmacy purchase is being supplemented by preventative shampoos and repellent sprays used regularly, especially during school seasons. This proactive approach is most prominent in suburban communities in North America and the UK, where schools and parent groups actively promote lice prevention strategies.
Lice Treatment Market Segmentation
Market segmentation provides a critical lens for understanding the diverse needs and purchasing behaviors within the lice treatment landscape. This analysis highlights how product innovation, specific application requirements, varied end-user preferences, and evolving distribution channels shape competitive dynamics and growth opportunities for manufacturers.
Product Type:
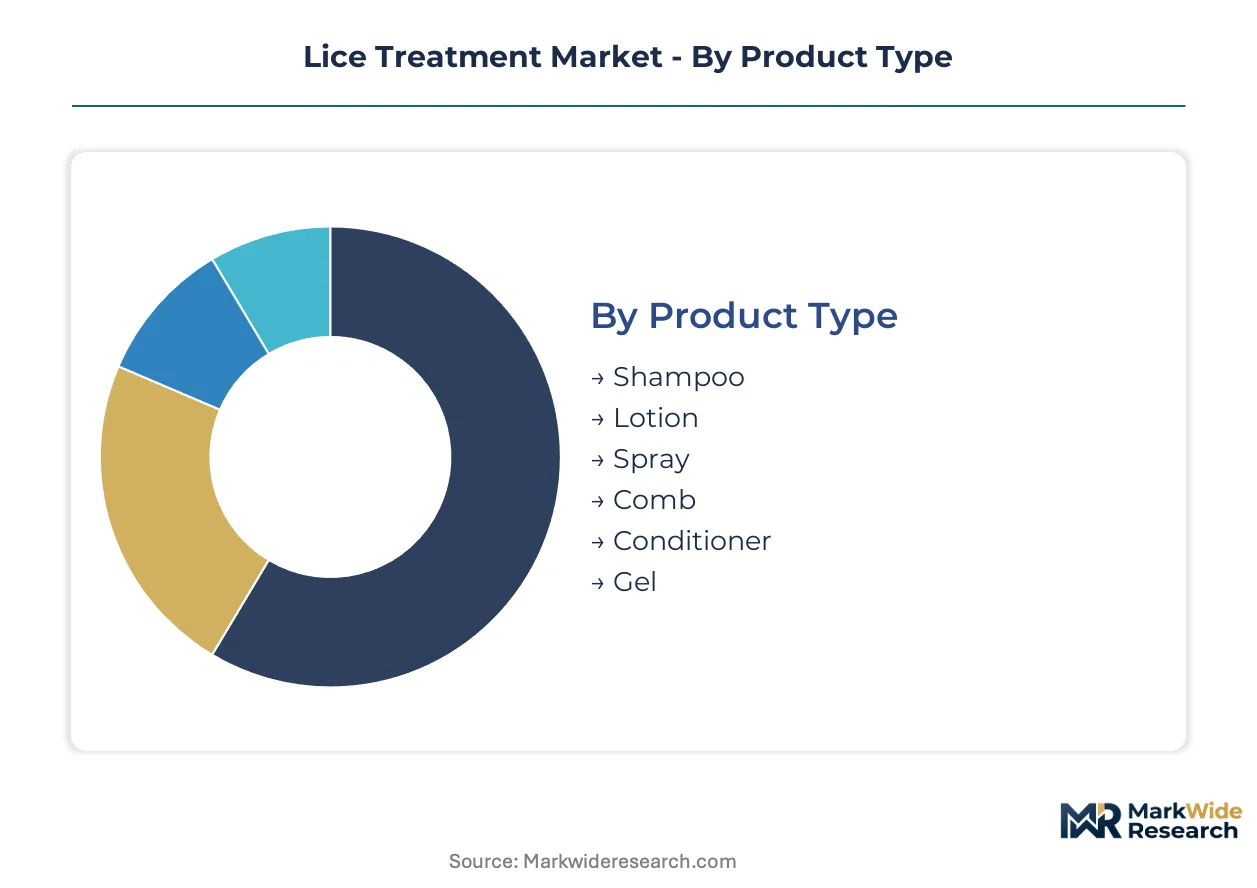
Margin pools within product type segmentation largely concentrate around specialized physical removal tools and advanced non-pesticide formulations.
- Lotion:These viscous formulations often contain dimethicone or other silicone oils, suffocating lice by physical means. Demand for these non-pesticide options is high among safety-conscious parents in Western Europe, driven by regulatory preference for non-neurotoxic agents.
- Comb:Specialized fine-toothed combs are crucial for physically removing nits and adult lice, verifying treatment success. School clinics in the United States emphasize their use as a primary method, especially with rising resistance to chemical treatments.
- Shampoo:Traditional shampoo-based treatments often incorporate pediculicides like permethrin, targeting the lice nervous system.
- Spray:Sprays offer convenient application for treatment and prevention, often containing natural repellents or physical agents.
- Conditioner:Conditioners detangle hair and facilitate nit combing, with some including mild physical agents for lice suffocation.
- Gel:Gel formulations provide a thicker, adherent coating to hair and scalp, ensuring prolonged contact with active ingredients.
The dominant share belongs to Shampoo, while Lotion is closing the gap fastest.
Application:
Application segmentation delineates specific user environments and demographic groups requiring tailored lice treatment solutions.
- Pediatric Use:Products designed for children represent the largest application segment, requiring non-toxic, gentle formulations due to sensitive skin and regulatory scrutiny. Demand is consistently high across high-density school districts in the United States and Western Europe.
- School Clinics:These institutional settings experience continuous infestation cycles, necessitating bulk purchasing and effective, easy-to-apply solutions for rapid intervention. Sustained demand for preventative and treatment products is evident in urban school districts.
- Geriatric Care:Products for elderly populations prioritize gentle, non-irritating formulas, considering skin sensitivities and medication interactions.
- Travel Kits:Compact, portable solutions cater to families on vacation, offering convenience for unexpected infestations away from home.
- Sports Teams:Group settings with close physical contact foster transmission, driving demand for preventative sprays and rapid treatment for athletes.
- Military:Confined living conditions in military barracks create specific needs for effective, rapid-acting treatments to prevent outbreaks.
Pediatric Use accounts for the largest volume, with School Clinics demonstrating the steepest expansion trajectory.
End User:
Supply concentration within end-user segments is heavily weighted towards channels offering immediate access and professional guidance.
- Pharmacies:These retail outlets serve as the primary point of purchase for over-the-counter lice treatments, benefiting from consumer trust and accessibility. Sales are consistently strong across urban and suburban areas, often driven by parental urgency.
- Online Retail:E-commerce platforms provide discrete purchasing options and a wide product selection, appealing to consumers seeking convenience and competitive pricing. This channel shows significant growth in all developed markets, including the United Kingdom.
- Dermatology Clinics:Specialists provide diagnosis and prescription-strength treatments for persistent infestations, offering expert medical advice.
- Pediatricians:Healthcare providers offer initial diagnosis and recommendations, influencing brand trust and product adoption.
- Hair Salons:Some hair salons offer specialized lice removal services and sell preventative products, catering to clients seeking assistance.
- Mobile Clinics:Mobile clinics provide on-site screening and treatment, particularly in underserved communities or during school outbreaks.
Pharmacies remain the dominant end-user channel, while Online Retail is gaining share fastest through convenience.
Distribution Channel:
Distribution channel dynamics reflect varied consumer purchasing behaviors and logistical requirements for product delivery.
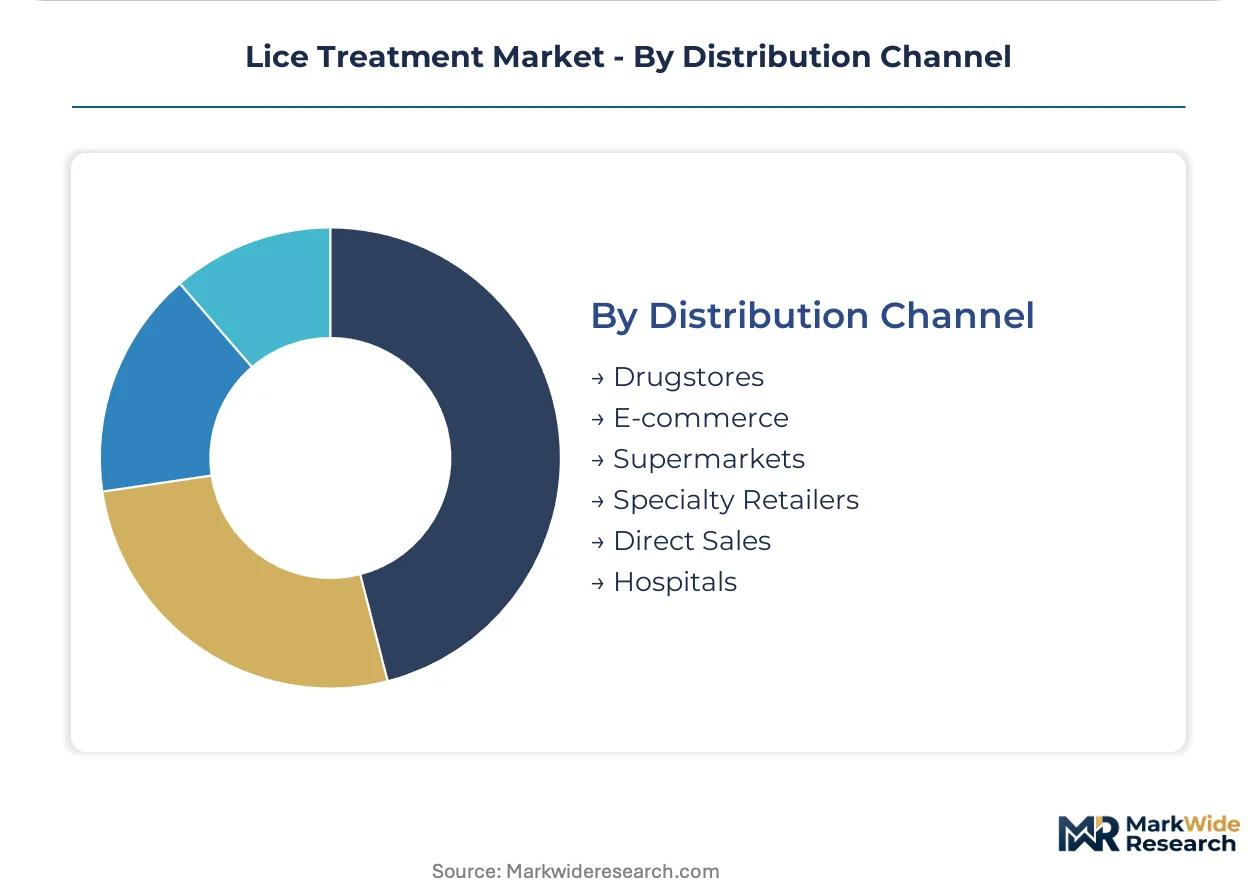
- Drugstores:These retail chains are crucial for immediate consumer access to a broad range of over-the-counter lice treatments, leveraging established brand presence. They serve as a primary distribution point across the United States and Germany, offering convenience.
- E-commerce:Online platforms facilitate wide product availability and discreet home delivery, catering to consumers prioritizing privacy and comparative shopping. This channel exhibits robust expansion in markets with high internet penetration, such as the Netherlands.
- Supermarkets:Large grocery stores integrate lice treatment products into routine shopping, reaching a broad family demographic.
- Specialty Retailers:Specialty retailers focusing on health or natural products provide niche offerings, emphasizing organic or non-chemical solutions.
- Direct Sales:Manufacturers engage directly with institutions like school districts, providing bulk supplies and educational support programs.
- Hospitals:Hospitals stock treatment options for patients in emergency situations or for use in pediatric departments.
Drugstores command significant market presence, with E-commerce platforms expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for lice treatments shows asymmetry, with higher average prices observed in Western Europe compared to emerging markets in Southeast Asia. This disparity reflects differences in regulatory frameworks and consumer willingness to pay for premium non-pesticide formulations. Demand remains strong in high-density school districts globally.
United States
Demand for non-pesticide formulations is high due to persistent infestations in school clinics and parental safety concerns. The U.S. FDA rigorously reviews pediatric topical products, favoring non-neurotoxic modes of action. Major urban centers like New York City and Los Angeles see continuous demand for effective, easy-to-apply solutions. Preventative product lines are gaining traction in suburban communities.
Germany
Pediatric use drives significant demand for gentle, effective lice treatments, aligning with stringent European safety standards. The European Medicines Agency (EMA) enforces strict safety and efficacy requirements for products sold across the EU. Pharmacies in cities like Berlin and Munich are primary distribution points, offering professional guidance and trusted brands.
United Kingdom
High infestation rates in school-aged children generate consistent demand for both treatment and preventative options. The UK's Medicines and Healthcare products Regulatory Agency (MHRA) ensures product safety and efficacy, influencing market access. Online retail in London and other major cities provides discreet purchasing and a wide selection of products.
Brazil
Large pediatric populations in urban centers present a substantial growth vector for affordable and effective lice treatments. Brazil's ANVISA regulates pharmaceutical products, including over-the-counter pediculicides, focusing on public health safety. Developing public health infrastructure in cities like São Paulo and Rio de Janeiro supports market penetration efforts.
India
Market penetration opportunities exist due to a vast pediatric demographic and a growing middle-income consumer base. The Central Drugs Standard Control Organization (CDSCO) governs drug approvals, ensuring product quality and safety. Local pharmacies in Mumbai and Delhi are crucial distribution channels, providing accessible treatment options.
Lice Treatment Market Key Industry Players
Concentration sits with established consumer healthcare brands and large pharmaceutical companies leveraging their existing distribution networks. The market exhibits a tiered structure, with legacy players and private-label manufacturers competing alongside specialized innovators. Strategic archetypes include diversified health conglomerates, over-the-counter specialists, and niche non-pesticide solution providers. Portfolio diversification and channel expansion are dominant competitive moves.
Among the established players, Prestige Consumer Healthcare exemplifies a strong brand recognition strategy within the over-the-counter space. Perrigo Company, with its extensive private-label manufacturing scale, occupies a significant position in drugstore channels. Johnson & Johnson Services, a diversified health conglomerate, anchors its market presence through broad distribution channels reaching pharmacies and supermarkets. These companies collectively illustrate the varied approaches to market leadership, from specialized OTC focus to broad portfolio leverage.
| Leading Market Players |
|---|
| Prestige Consumer Healthcare |
| Perrigo Company |
| Johnson & Johnson Services |
| GlaxoSmithKline |
| Arbor Pharmaceuticals |
| Alliance Pharmaceuticals |
| Oystershell Consumer Health |
| Reckitt Benckiser Group |
| Bayer |
| Others |
Cost & Logistics Intelligence
The substitution of traditional permethrin-based pediculicides with non-pesticide formulations simultaneously reshapes the supply geography for active ingredients and shifts pricing economics toward efficacy premiums. This fundamental transition impacts raw material sourcing and manufacturing complexities across the market.
Pricing Analysis
Configured treatment kits, bundling non-toxic lotions with high-efficacy combs, command a premium spread over standard individual product offerings. The dominant pricing model remains per-unit transactional for most over-the-counter products, supplemented by value-based pricing for comprehensive kits. Price differentiation stems from non-pesticide formulation efficacy and established brand recognition. Pricing pressure stems from the availability of low-cost manual methods, particularly impacting traditional chemical treatments. Safety-conscious parents seeking non-neurotoxic options exhibit lower price sensitivity compared to consumers opting for manual removal due to perceived chemical treatment failures.
Supply Chain Analysis
Strategic stockpile preferences for critical non-pesticide active ingredients are emerging, contrasting with just-in-time practices for established chemical components. Geographic supply concentration for key chemical inputs like permethrin typically centers in China and India, while specialized silicone oils for dimethicone formulations often originate from advanced chemical manufacturers in the United States and Germany. Raw material dependencies include dimethicone, permethrin, and specialized plastics for nit combs. A structural supply chain risk involves single-source vulnerability for novel non-pesticide compounds. Distribution runs primarily through established retail pharmacy networks and increasingly through e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a cyclical recovery, driven by persistent infestation rates within high-density pediatric populations. Manufacturers must adapt to evolving consumer preferences and regulatory pressures for safer, more effective solutions.
For Market Incumbents: Secure integrated R&D capabilities for novel, non-toxic formulations to counter increasing lice resistance to traditional chemical treatments. Invest in clinical validation to build trust and differentiate products from perceived ineffective legacy options. Expand distribution channels through direct sales and partnership programs with school districts, capturing consumers at the primary point of diagnosis. This strategy helps mitigate threats from manual methods and strengthens market position against specialized innovators.
For New Entrants and Emerging Players: Lead with innovative, non-pesticide formulations that address unmet safety and efficacy needs, particularly for pediatric use. Target emerging markets in Latin America and Southeast Asia, offering affordable yet effective solutions tailored to developing public health infrastructures. Develop comprehensive integrated treatment kits that simplify the consumer purchasing process and improve overall treatment outcomes. Focus on digital marketing and online retail channels for discreet access and wider product reach.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with specialized innovators focusing on non-pesticide solutions, offering strong intellectual property in physical-action agents. The long-term viability of this market remains strong, fueled by persistent infestations and a growing demand for safe, effective pediatric treatments. Target companies with robust R&D pipelines for novel active ingredients and established regulatory approvals from bodies like the FDA and EMA. The signal to watch is the accelerated adoption rate of non-pesticide formulations in key Western markets.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D into Non-Pesticide Formulations | Drives innovation to overcome resistance, aligning with regulatory preferences for safer treatments. |
| Integrated Treatment Kit Development | Simplifies consumer choice and improves treatment efficacy through bundled, complementary products. |
| Channel Expansion into School Health | Captures demand at the point of diagnosis, building brand trust with pediatric clinics and schools. |
| Emerging Market Penetration | Unlocks new revenue streams by addressing large pediatric populations with affordable solutions. |
| Consumer Education Campaigns | Ensures correct product application, enhancing perceived efficacy and reducing brand damage from misuse. |
Research Approach
Desk research of regulatory filings, academic literature, and industry reports preceded structured interviews with pediatricians, school nurses, consumer healthcare executives, and regulatory specialists. This approach combined top-down market sizing with bottom-up validation of segment-specific dynamics. Data triangulation across primary and secondary sources ensured robust market insights.
The analytical framework employs variance decomposition to project market growth across the analysis window. Segmentation dimensions modeled include product type, application, end-user, distribution channel, and regional regulatory environment. Compound Annual Growth Rates were derived from historical data analysis and future trend projections. Key industry-specific forecast inputs include evolving lice resistance rates and demographic shifts in school-aged populations.
Forecasts assume regulatory continuity in the U.S. FDA and European Medicines Agency regimes; material policy shifts would require re-modeling. The analysis reflects assumptions regarding technological advancements and consumer behavior patterns. Revision becomes warranted when new resistance patterns or significant regulatory changes cross established thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Giardiasis Treatment Market
Medical Treatment
Europe Platelet Rich Plasma (PRP) Market
Medical Treatment
Hyperbaric Oxygen Therapy (HBOT) Market
Medical Treatment
Lysosomal Disease Treatment Market
Medical Treatment
Onchocerciasis Treatment Market
Medical Treatment
Trauma and Extremities Market
Medical Treatment
Global Von Willebrand Disease Treatment Market
Medical Treatment
Mercury Poisoning Treatment Market
Medical Treatment
Single Dose Radiotherapy Services Market
Medical Treatment
Acupuncture Treatment Market
Medical Treatment
Transplantation Market
Medical Treatment
Kidney Stones Management Market
Medical Treatment
Radiation Therapy Market
Medical Treatment
Molluscum Contagiosum (MC) Treatment Market
Medical Treatment
Bloch-Sulzberger Treatment Market
Medical Treatment
Global Uterine Fibroids Treatment Market