
 Tennis Elbow Treatment Market | 2026-2036
Tennis Elbow Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Tennis Elbow Treatment Market Intelligence
A shift from single-source procurement of orthopedic braces toward multi-source agreements for physical therapy devices is realigning vendor relationships across outpatient networks. DJO Global Inc. leverages its established channel presence in rehabilitation centers to sustain recurring equipment purchases. Zimmer Biomet anchors its position through specialized product lines for tendinopathy management. Stryker Corporation competes by extending its reach into ambulatory surgical centers with integrated procedural kits.
Tennis elbow treatment encompasses non-surgical and minimally invasive interventions targeting lateral epicondylitis, a degenerative condition of the extensor carpi radialis brevis tendon characterized by microtearing and collagen disorganization at the lateral humeral epicondyle. Physical therapy devices and orthopedic braces constitute the mature revenue base, with margin pools shifting toward platelet-rich plasma and ultrasonic therapy equipment as clinicians seek alternatives to corticosteroid injections. The therapy area dimension shows tendinopathy management and tissue regeneration commanding premium positioning, while pain relief and inflammation control segments face commoditization from generic topical analgesics.
The US FDA oversees biologic product classifications for platelet-rich plasma preparations, while the EU MDR framework imposes stricter clinical evidence requirements on orthopedic brace manufacturers seeking CE marking renewal. These regulatory trajectories elevate compliance costs for smaller device makers and favor scaled players with dedicated regulatory affairs infrastructure. Stakeholders must monitor reimbursement policy shifts for home-based treatments and wearable devices as payors recalibrate coverage for remote musculoskeletal care modalities.
Market Dynamics
The tennis elbow treatment market is restructuring around regenerative biologics as clinicians abandon corticosteroid injections amid mounting evidence of tendon degeneration risks. This therapeutic pivot is compressing margins in conventional device categories while elevating reimbursement scrutiny for novel interventions.
Growth Catalysts
- EU MDR framework:Stricter clinical evidence requirements for orthopedic brace CE marking renewal are filtering out marginal competitors and consolidating share among scaled manufacturers with dedicated regulatory infrastructure.
- Sports medicine facilities:Outpatient procedural volumes for lateral epicondylitis are climbing as ambulatory surgical centers expand musculoskeletal service lines and capture cases from hospital-based settings.
- Platelet-rich plasma protocols:Evolving US FDA guidance on regenerative medicine therapies is accelerating clinical adoption by clarifying biologic product classification pathways for autologous blood preparations.
Market Restraints
- Reimbursement opacity:German statutory health insurance funds apply inconsistent coverage criteria for physiotherapy interventions, creating payment uncertainty that delays treatment initiation.
- Input cost volatility:Medical-grade polymers and antimicrobial textiles used in brace manufacturing face petrochemical price swings that compress device margins without corresponding pricing power.
- Technical limitation:Ultrasonic therapy equipment demonstrates variable efficacy across tendon degeneration stages, limiting protocol standardization and clinician confidence in outcomes.
Strategic Opportunities
- Home-based rehabilitation:Wearable resistance devices and connected motion sensors are penetrating the post-acute care segment as payors recalibrate coverage for remote musculoskeletal monitoring.
- Technology convergence:Integration of platelet-rich plasma preparation systems with point-of-care centrifugation is reducing processing time and enabling same-visit treatment administration.
- Underpenetrated geography:Spain presents whitespace for tendinopathy management protocols given lower procedural density relative to Germany and France within the European landscape.
Industry Challenges
- Specialized technician scarcity:Certified physiotherapists trained in eccentric loading protocols for extensor tendon rehabilitation remain concentrated in urban academic medical centers, constraining protocol diffusion.
- Compliance timeline compression:EU MDR technical documentation requirements for class IIa orthopedic devices are extending time-to-market by 12-18 months for manufacturers without prior notified body relationships.
- Legacy system integration:Electronic health record interoperability gaps between physical therapy device data streams and hospital information systems fragment patient outcome tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tennis Elbow Treatment Market |
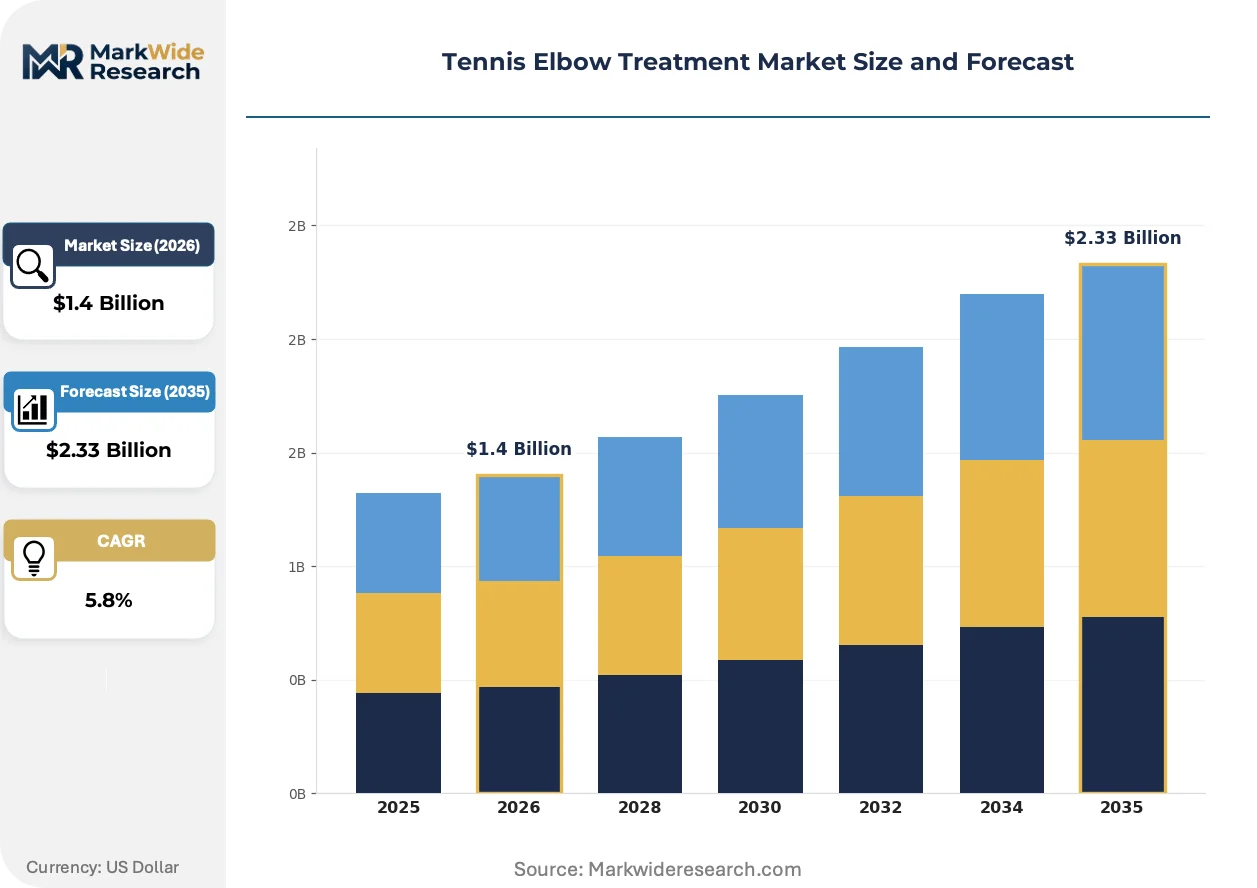
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Physical Therapy Devices, Orthopedic Braces, Topical Analgesics, Steroid Injections, Platelet-Rich Plasma, Ultrasonic Therapy Equipment Therapy Area: Tendinopathy Management, Pain Relief, Inflammation Control, Tissue Regeneration, Mobility Improvement, Circulation Enhancement End User: Orthopedic Clinics, Physiotherapy Centers, Sports Medicine Facilities, Rehabilitation Centers, Chiropractic Offices, Ambulatory Surgical Centers Delivery Mode: In-Clinic Procedures, Home-Based Treatments, Telemedicine Consultations, Injectable Therapies, Manual Therapy, Wearable Devices |
| Companies Covered | 3M, BTL, Zimmer Biomet, Össur, Ottobock HealthCare, DJO Global Inc., AKSIGEN, Stryker Corporation, Teikoku Pharma USA Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tennis Elbow Treatment Market Strategic Shifts & Innovations
Biologic intervention protocols are displacing mechanical modalities as first-line therapy for recalcitrant lateral epicondylitis. This therapeutic reorientation is reshaping capital allocation across device manufacturers and service delivery networks.
Platelet-rich plasma preparation systems are expanding into ambulatory surgical centers as same-day procedural economics displace hospital-based infusion models. Orthopedic surgeons and sports medicine physicians are adopting these platforms at accelerating rates. The technology is expanding into integrated procedural kits that bundle centrifugation, activation, and injection components.
EU MDR clinical evidence requirements are elevating post-market surveillance obligations for orthopedic brace manufacturers. The framework mandates systematic collection of real-world performance data for CE marking maintenance. Class IIa device categories face the steepest compliance cost escalation, favoring scaled players with dedicated clinical affairs infrastructure.
Patient-directed care pathways are fragmenting traditional referral networks for tennis elbow treatment. Direct-to-consumer physical therapy platforms and telehealth consultations are intercepting cases before specialist evaluation. Germany exhibits the most pronounced channel shift given its dense network of statutory insurance-accredited digital health providers.
Tennis Elbow Treatment Market Segmentation
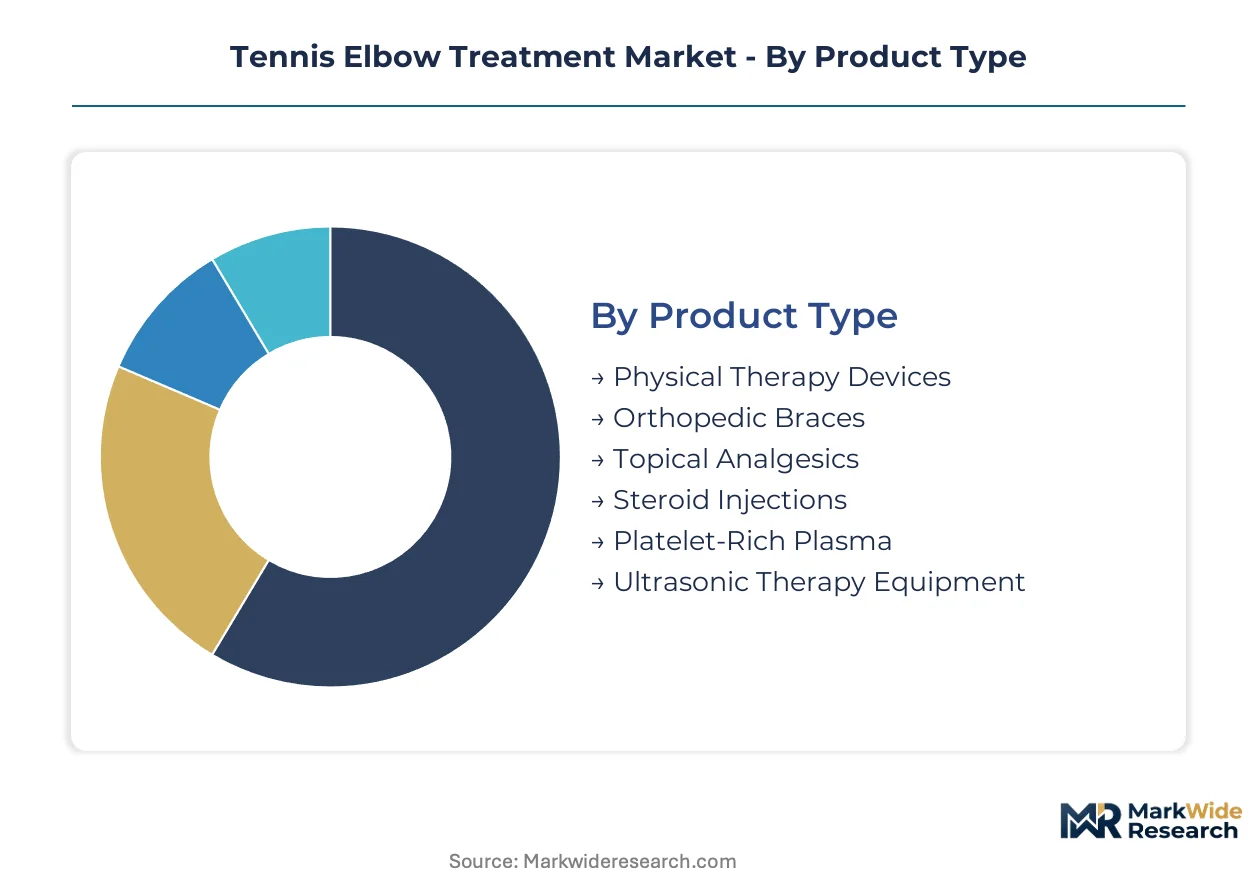
Segmentation in the tennis elbow treatment market reveals how therapeutic priorities are shifting from mechanical support toward biologic regeneration. Product portfolios are fragmenting across intervention intensity levels, while delivery channels are diverging between institutional settings and patient-directed care. Understanding these splits exposes where margin pools are concentrating and which modalities face commoditization pressure.
Product Type:
Standardization dominates commodity segments like braces and analgesics, while customization requirements escalate for biologic preparations and programmable therapeutic devices.
- Physical Therapy Devices:Resistance bands, eccentric loading platforms, and cryotherapy systems constitute the procedural backbone of rehabilitation protocols. Demand concentrates in physiotherapy centers across Germany and the United States as reimbursement clarity for supervised exercise programs improves.
- Orthopedic Braces:Counterforce straps and rigid immobilizers provide mechanical unloading of the extensor tendon origin. Manufacturing margins compress under EU MDR compliance costs and petrochemical input volatility, favoring scaled producers with dedicated notified body relationships.
- Topical Analgesics:NSAID gels and lidocaine patches offer over-the-counter pain management with minimal clinical oversight.
- Steroid Injections:Corticosteroid preparations face declining utilization amid evidence of tendon degeneration risks.
- Platelet-Rich Plasma:Autologous blood concentrates processed through point-of-care centrifugation systems. Same-visit preparation protocols are penetrating ambulatory surgical centers as FDA guidance clarifies biologic classification pathways.
- Ultrasonic Therapy Equipment:Therapeutic ultrasound and extracorporeal shockwave devices target collagen remodeling. Variable efficacy across degeneration stages limits protocol standardization and clinician confidence.
Growing fastest: Platelet-Rich Plasma. Leading the category by volume: Physical Therapy Devices.
Therapy Area:
Application intensity separates acute symptom management from structural tissue repair, with reimbursement policies favoring demonstrable functional outcomes over palliative measures.
- Tendinopathy Management:Eccentric loading protocols and mechanical unloading strategies address the degenerative pathology of extensor carpi radialis brevis microtearing. Sports medicine facilities in the United States prioritize these interventions for recalcitrant cases.
- Pain Relief:Pharmacologic and physical modalities targeting nociceptive signaling without structural modification. Generic topical formulations commoditize this segment across European retail pharmacies.
- Inflammation Control:Corticosteroid injections and cryotherapy applications suppress inflammatory mediators. Declining utilization reflects accumulating evidence of long-term tendon compromise.
- Tissue Regeneration:Biologic interventions including platelet-rich plasma and emerging cell therapies stimulate collagen synthesis and vascular ingrowth. Premium positioning attracts capital allocation from device manufacturers pivoting from mechanical to regenerative platforms.
- Mobility Improvement:Range-of-motion restoration through manual therapy and progressive loading protocols.
- Circulation Enhancement:Thermal modalities and compression therapies supporting healing microenvironments.
Steepest expansion trajectory: Tissue Regeneration. Largest volume share: Tendinopathy Management.
End User:
Customer type determines purchasing authority, with hospital-affiliated centers favoring capital-intensive systems and independent practices prioritizing disposable economics.
- Orthopedic Clinics:Surgeon-directed practices managing surgical candidacy and injection therapies. German orthopedic networks demonstrate highest procedural density for platelet-rich plasma administration.
- Physiotherapy Centers:Exercise-based rehabilitation protocols dominate service delivery. Statutory insurance reimbursement clarity in Germany drives volume concentration.
- Sports Medicine Facilities:Outpatient procedural volumes for lateral epicondylitis are climbing as ambulatory surgical centers expand musculoskeletal service lines.
- Rehabilitation Centers:Post-acute care settings managing workers' compensation and occupational injury cases.
- Chiropractic Offices:Manual therapy and adjunctive modalities for conservative management.
- Ambulatory Surgical Centers:Same-day procedural economics displace hospital-based infusion models for biologic therapies.
Highest volume concentration: Physiotherapy Centers. Fastest channel growth: Ambulatory Surgical Centers.
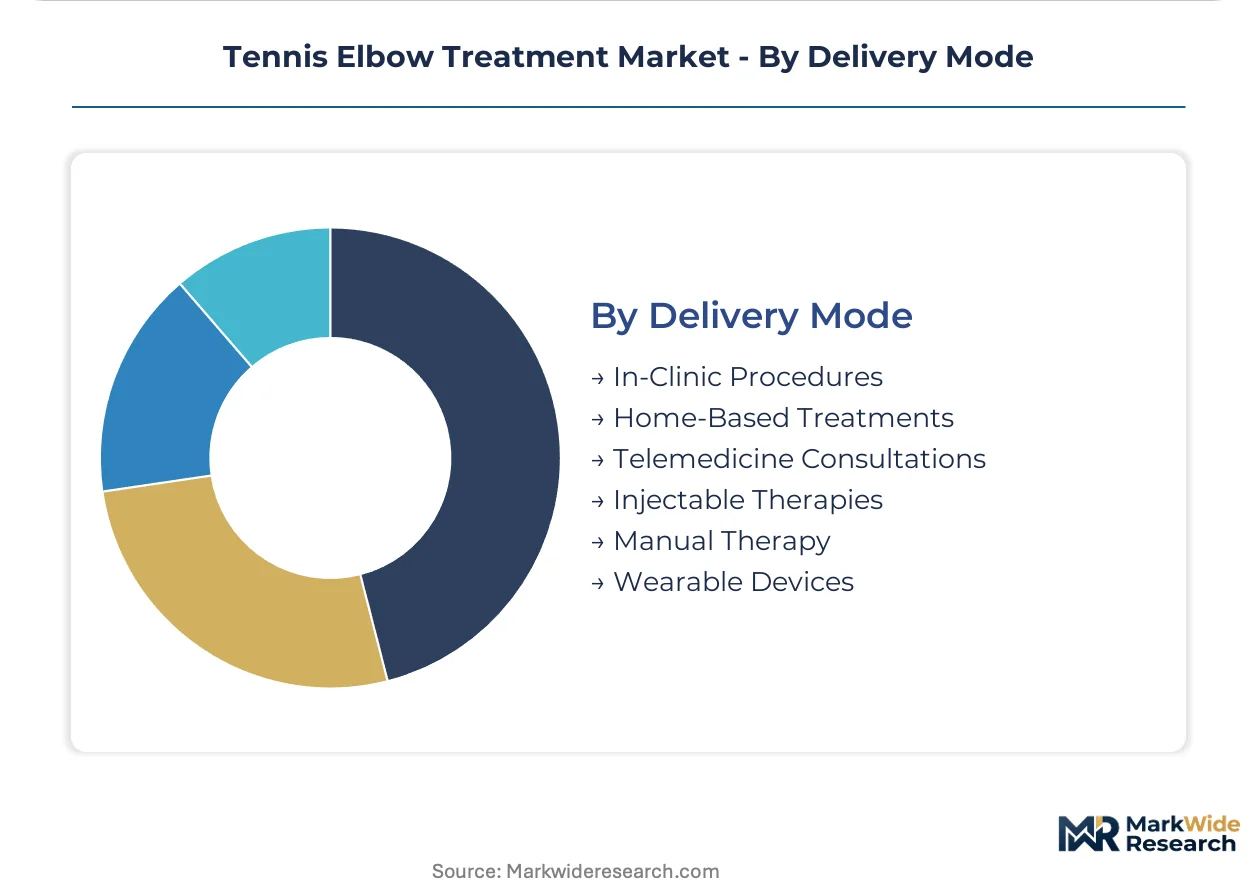
Delivery Mode:
Margin structure inverts between high-touch clinical procedures and scalable remote monitoring, with technology-enabled home solutions capturing expanding reimbursement attention.
- In-Clinic Procedures:Supervised interventions including manual therapy, injection administration, and equipment-based rehabilitation. German statutory health insurance funds apply inconsistent coverage criteria, creating payment uncertainty.
- Home-Based Treatments:Patient-directed protocols using prescribed devices and exercise programs. Wearable resistance devices and connected motion sensors penetrate post-acute care as payors recalibrate remote musculoskeletal coverage.
- Telemedicine Consultations:Digital platforms intercept cases before specialist evaluation. Germany exhibits pronounced channel shift given dense networks of statutory insurance-accredited digital health providers.
- Injectable Therapies:Corticosteroid and biologic preparations requiring clinical administration.
- Manual Therapy:Hands-on techniques delivered by certified practitioners.
- Wearable Devices:Connected sensors enabling remote monitoring and adherence tracking.
Current volume leader: In-Clinic Procedures. Most rapid expansion: Home-Based Treatments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock availability in the US Gulf Coast and Germany's Rhine-Ruhr corridor anchors manufacturing capacity for medical-grade polymers used in orthopedic brace production. Regulatory frameworks diverge sharply across jurisdictions, with the US FDA and EU MDR imposing distinct compliance burdens on device manufacturers.
United States
Ambulatory surgical centers in Texas and Florida are expanding musculoskeletal service lines and capturing lateral epicondylitis cases from hospital-based settings. The FDA's evolving guidance on regenerative medicine therapies clarifies biologic product classification pathways for autologous platelet-rich plasma preparations. Sports medicine facilities cluster around Phoenix and San Diego, where outpatient procedural volumes for tendon interventions are climbing.
Germany
Statutory health insurance funds in Bavaria and North Rhine-Westphalia apply reimbursement clarity for physiotherapy interventions, driving demand concentration. The EU MDR framework imposes stricter clinical evidence requirements on orthopedic brace manufacturers seeking CE marking renewal. Medical technology clusters in Berlin-Brandenburg and Hamburg host scaled players with dedicated regulatory affairs infrastructure for class IIa device compliance.
United Kingdom
NHS Integrated Care Boards in Greater London and the Midlands are recalibrating coverage for remote musculoskeletal care modalities including wearable monitoring devices. The Medicines and Healthcare products Regulatory Agency aligns with EU MDR post-market surveillance obligations for orthopedic devices. Physiotherapy centers in Manchester and Birmingham demonstrate highest procedural density for eccentric loading protocols.
Japan
PMDA oversight of biologic product classifications shapes clinical adoption patterns for platelet-rich plasma therapies in Kanto and Kansai regions. METI industrial policy supports domestic manufacturing of therapeutic ultrasound equipment. Osaka-based rehabilitation networks prioritize tendinopathy management protocols for aging workforce populations.
Spain
Lower procedural density for tendinopathy management relative to Germany and France presents whitespace opportunity in Madrid and Catalonia. Regional health authorities apply inconsistent coverage criteria for home-based physical therapy devices. Barcelona and Valencia host emerging digital health platforms intercepting tennis elbow cases before specialist evaluation.
Tennis Elbow Treatment Market Key Industry Players
Portfolio diversification dominates the current landscape as device manufacturers pivot from mechanical braces toward regenerative biologics platforms. The vendor base stratifies across three tiers: scaled multinationals with dedicated regulatory infrastructure, mid-cap specialists in point-of-care centrifugation systems, and regional fabricators of commodity orthopedic supports. Competitive positioning hinges on EU MDR compliance timelines and FDA biologic classification clarity. M&A activity targets point-of-care preparation systems, while strategic partnerships bridge electronic health record interoperability gaps.
Among US-based multinationals, 3M and Stryker Corporation occupy positions within the scaled tier, anchoring diversified portfolios that span mechanical supports and procedural technologies. Zimmer Biomet exemplifies the orthopedic-focused archetype with specialized positioning in tendinopathy management. DJO Global Inc. sits within the rehabilitation channel specialist tier, leveraging established presence in physical therapy centers for recurring equipment placement.
| Leading Market Players |
|---|
| 3M |
| BTL |
| Zimmer Biomet |
| Össur |
| Ottobock HealthCare |
| DJO Global Inc. |
| AKSIGEN |
| Stryker Corporation |
| Teikoku Pharma USA Inc. |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between EU MDR-compliant orthopedic brace manufacturers and unvalidated commodity producers creates a bifurcated pricing architecture that simultaneously concentrates supply chain leverage among scaled notified body partners and fragments procurement options for cost-constrained buyers. This tier separation manifests in bundled service contracts for premium device tiers versus transactional spot purchasing for economy supports, with warranty terms and clinical training inclusion becoming the primary price differentiation vectors.
Pricing Analysis
Warranty bundling and clinical training inclusion separate premium platelet-rich plasma preparation systems from unbundled commodity orthopedic braces. Three-tier pricing structure across premium, standard, and economy levels tracks certification status and after-sales service depth. Cost compression in brace manufacturing intensifies as petrochemical input volatility erodes margins without corresponding pricing power. Independent physiotherapy centers exhibit highest price sensitivity, while hospital-affiliated orthopedic clinics prioritize outcome guarantees over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with medical-grade polymer feedstock concentrated in the US Gulf Coast and Germany's Rhine-Ruhr corridor. Manufacturing draws from petrochemical derivatives, antimicrobial textiles, and precision-machined centrifuge components. Tariff exposure on imported therapeutic ultrasound subassemblies elevates landed costs for European device assemblers. Distribution runs through specialized medical device distributors and direct hospital system contracts, with ambulatory surgical centers increasingly procuring through integrated procedural kit arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tennis elbow treatment market sits in a technology-transition phase where platelet-rich plasma protocols displace corticosteroid injections as first-line therapy for recalcitrant lateral epicondylitis. This therapeutic pivot demands strategic repositioning across stakeholder archetypes.
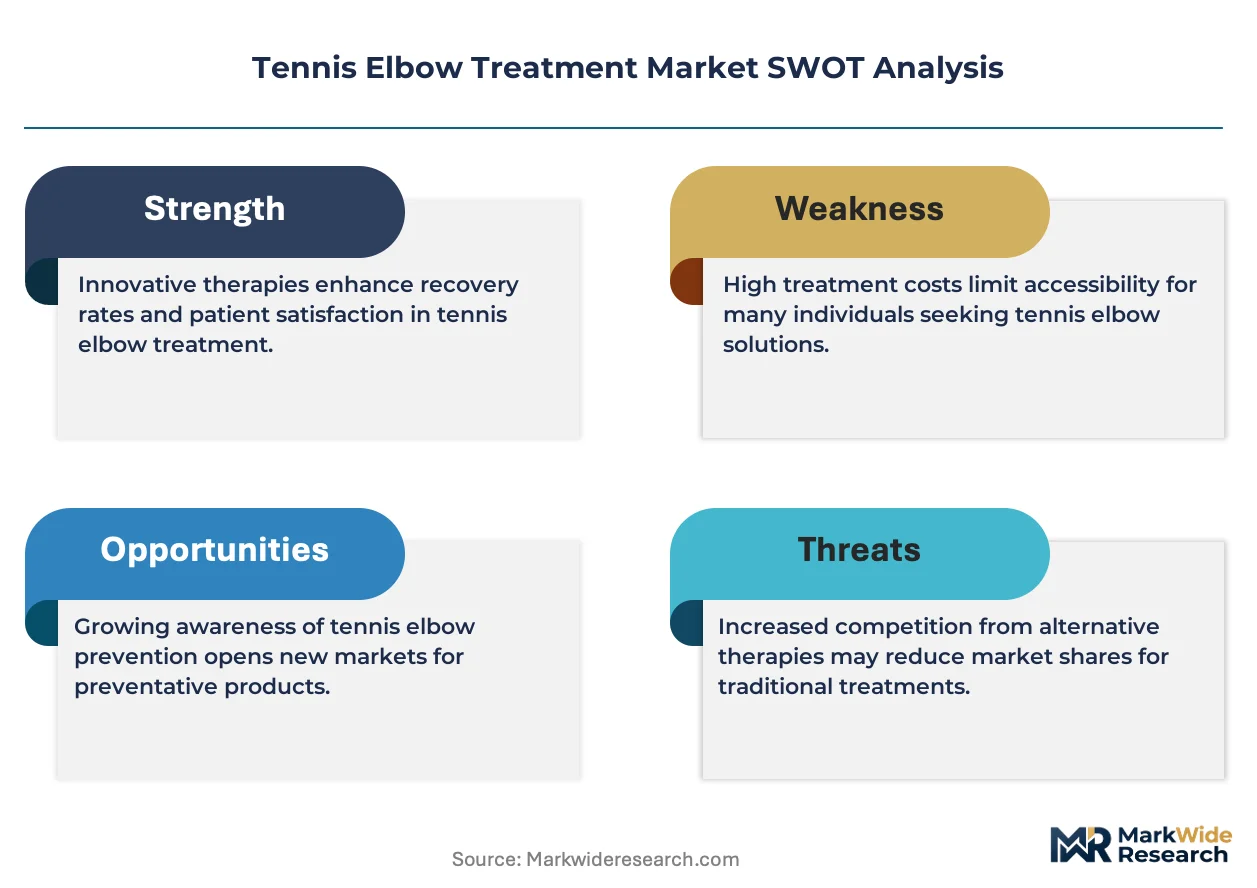
For Market Incumbents: Anticipate margin compression in mechanical brace categories by accelerating point-of-care centrifugation platform development and securing EU MDR notified body relationships ahead of compliance timeline compression. Channel control through exclusive ambulatory surgical center partnerships offers defensive leverage against biologic-focused entrants. R&D investment in integrated procedural kits bundles preparation, activation, and injection components into same-visit economics that hospital systems prefer. For New Entrants and Emerging Players: FDA evolving guidance on regenerative medicine therapies in the United States opens a window for autologous blood concentrate platforms seeking biologic product classification clarity. Spain presents the most penetrable geography given lower procedural density relative to Germany and France. Home-based rehabilitation devices targeting post-acute care reimbursement recalibration offer a direct-to-clinician go-to-market angle that bypasses established distributor relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in point-of-care centrifugation system manufacturers with FDA 510(k) clearance and ambulatory surgical center installed bases. Long-term viability hinges on regulatory moat sustainability and reimbursement policy alignment rather than device innovation cycles alone. The signal to watch is CMS coverage determination shifts for remote musculoskeletal monitoring modalities, which would validate wearable resistance device economics at scale.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation requirements extend time-to-market for class IIa orthopedic devices without prior notified body relationships. |
| Hospital System Partnership | Integrated delivery networks in Texas and Florida prioritize same-day procedural economics for lateral epicondylitis cases. |
| Reimbursement Strategy | German statutory health insurance funds apply inconsistent coverage criteria that create payment uncertainty for physiotherapy interventions. |
| Software Companion Development | Connected motion sensors enable remote adherence tracking as payors recalibrate coverage for home-based musculoskeletal care. |
| FDA Submission | Biologic product classification pathways for autologous platelet-rich plasma preparations clarify under evolving regenerative medicine guidance. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, with primary interviews conducted across orthopedic surgeons, sports medicine physicians, physiotherapy center directors, biomedical engineers, and GPO contracts managers. FDA 510(k) databases, EU MDR notified body documentation, hospital procurement databases, and statutory health insurance reimbursement schedules provided validation layers. Bottom-up sizing of platelet-rich plasma preparation system placements and top-down cross-check against ambulatory surgical center procedural volumes ensured triangulation integrity.
Segment-level granularity modeled product type splits across physical therapy devices, orthopedic braces, and biologic preparations; therapy area distinctions between tendinopathy management and tissue regeneration; end-user channel economics for orthopedic clinics versus physiotherapy centers; and delivery mode divergence between in-clinic and home-based protocols. CAGRs derived from procedure volume trajectories, reimbursement policy elasticity assumptions, and technology substitution curves across the analysis window. Input cost modeling incorporated petrochemical price indices and medical-grade polymer supply constraints.
The model assumes a particular technology adoption path; alternative pathways for ultrasonic therapy equipment demonstrating improved efficacy across tendon degeneration stages would alter the outlook. Forecasts reflect assumptions regarding EU MDR compliance timeline adherence, FDA biologic classification finalization, and statutory insurance reimbursement stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Bromhidrosis Disease Treatment Market
Medical Treatment
Gallbladder Treatment Market
Medical Treatment
Tinea Pedis Treatment Market
Medical Treatment
Cholera Treatment Market
Medical Treatment
Gunshot Injuries Treatment Market
Medical Treatment
Encephalitis Treatment Market
Medical Treatment
Acute Migraine Treatment Market
Medical Treatment
Purpura Treatment Market
Medical Treatment
Anorectal Malformation Treatment Market
Medical Treatment
Factor XIII Deficiency Treatment Market
Medical Treatment
Hereditary Amyloidosis Treatment Market
Medical Treatment
China Nose Reconstruction Market
Medical Treatment
Tendonitis Treatment Market
Medical Treatment
Cytokine Release Syndrome Management Market
Medical Treatment
Seropositive Rheumatoid Arthritis Treatment Market
Medical Treatment
Hyponatremia Treatment Market