
 US Hyperbaric Oxygen Therapy (HBOT) Market | 2026-2036
US Hyperbaric Oxygen Therapy (HBOT) Market Size, Share, and Industry Trends Forecast 2026-2036
US Hyperbaric Oxygen Therapy (HBOT) Market Analytics
Wound healing applications in hospital outpatient settings is recalibrating the US HBOT landscape as administrators prioritize reimbursable chronic care over elective indications. Sechrist Industries sustains manufacturing scale through in-house fabrication of acrylic monoplace shells. Perry Baromedical anchors the premium multipurpose segment with steel-hulled systems rated for higher pressure protocols. Environmental Tectonics Corp. differentiates through simulation-derived engineering that extends chamber lifecycle durability.
Hyperbaric oxygen therapy delivers percent oxygen at elevated ambient pressures to dissolve gas directly into plasma and drive tissue oxygenation beyond hemoglobin capacity. Typical clinical systems operate between two to three atmospheres absolute with treatment cycles lasting sixty to ninety minutes. Monoplace chambers dominate installed base volume due to lower capital requirements and streamlined facility integration. Multipurpose chambers capture concentrated margin pools where hospitals perform complex interventions requiring attendant access during pressurization. Portable and veterinary categories remain nascent but attract development investment from manufacturers seeking indication expansion beyond human reimbursement codes.
FDA 510(k) clearance governs chamber design and clinical claims while CMS reimbursement schedules determine site-level purchase justification. State-level certificate-of-need regulations in markets like New York and Illinois constrain capacity expansion independent of clinical demand. The Joint Commission accreditation standards shape operational protocols that influence equipment specification and staff training requirements. Stakeholders must monitor evolving CMS national coverage determinations for diabetic foot ulcers and radiation injury as these rulings directly shift addressable facility demand.
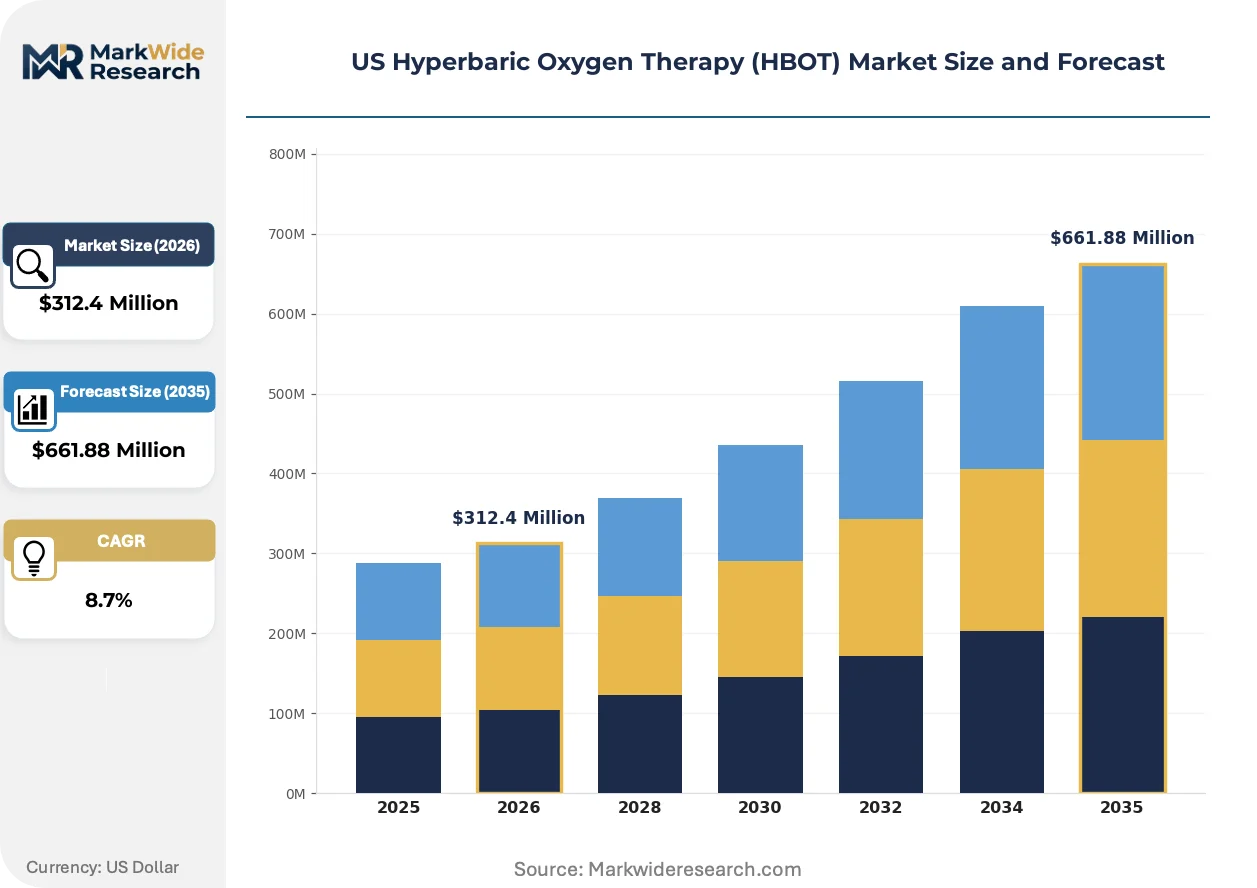
Market Dynamics
CMS reimbursement policy for diabetic foot ulcers and radiation injuries is compressing purchase cycles for hospital outpatient departments while state-level certificate-of-need regulations fragment capacity deployment across high-demand metros.
Growth Catalysts
- CMS National Coverage Determinations:Expanded reimbursement codes for chronic wound protocols pull capital investment into outpatient wound care centers.
- Acrylic monoplace fabrication advances:In-house shell production by domestic manufacturers shortens equipment lead times and reduces total installed cost.
- Texas-Florida-California cluster density:Specialized wound care centers concentrate near aging coastal and Sun Belt populations, creating addressable demand pockets.
Market Restraints
- Certificate-of-need constraints:New York and Illinois regulations cap chamber installations regardless of clinical demand, freezing market entry.
- Steel input cost volatility:Multiplace chamber hull fabrication faces commodity price swings that compress manufacturer margins.
- Substitute negative-pressure wound therapy:NPWT devices capture lower-acuity cases before patients reach HBOT referral thresholds.
Strategic Opportunities
- Veterinary indication white space:Equine and small-animal rehabilitation centers represent an untapped channel beyond human reimbursement codes.
- Portable chamber distribution:Home-health and mobile clinic channels bypass fixed-site CON restrictions entirely.
- FDA 510(k) pathway compression:Streamlined clearance timelines for new indications accelerate manufacturer time-to-revenue.
Industry Challenges
- Hyperbaric technician certification bottlenecks:The Joint Commission staffing standards outpace training program throughput, constraining site activation.
- Legacy EMR integration complexity:Chamber control systems require custom interfacing with hospital record platforms, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Hyperbaric Oxygen Therapy (HBOT) Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoplace Chamber, Multipurpose Chamber, Portable Chamber, Veterinary Chamber Application: Wound Healing, Decompression Sickness, Carbon Monoxide Poisoning, Radiation Injury End User: Hospitals, Clinics, Research Facilities, Sports Centers Delivery Mode: In-Hospital, Outpatient, Home-Based, Mobile Services |
| Companies Covered | Sechrist Industries, Inc., Perry Baromedical Corp., Environmental Tectonics Corp., OxyHealth, Gulf Coast Hyperbarics Inc., Haux Life Support GmbH, Fink Engineering Pty Ltd., Hearmec Co. Ltd., Hyperbaric Modular Systems Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Hyperbaric Oxygen Therapy (HBOT) Market Evolving Landscape
Real-time tissue oxygen monitoring and automated pressure control systems are compressing treatment variance while regulatory pressure on patient safety protocols accelerates capital refresh cycles across installed bases.
Closed-loop oxygen delivery architecture is integrating pulse oximetry feedback with automated ventilator modulation. Hospital outpatient departments adopt these systems to reduce technician oversight burden per session. The technology is integrating clinical workflow efficiency gains that justify premium equipment specification over legacy open-loop designs.
FDA 510(k) clearance timelines for chamber design modifications have compressed following streamlined predicate device pathways. Manufacturers now field iterative pressure vessel improvements without full premarket approval cycles. Steel-hulled multiplace systems face heightened scrutiny on weld inspection documentation, driving specification toward acrylic monoplace alternatives.
Certificate-of-need jurisdictions are fragmenting procurement authority toward regional health system consolidation. Independent wound care clinics lose access to capital leasing channels as lenders demand hospital sponsorship. Texas and Florida markets exhibit the strongest concentration of de novo outpatient center formation outside CON-constrained states.
US Hyperbaric Oxygen Therapy (HBOT) Market Segmentation
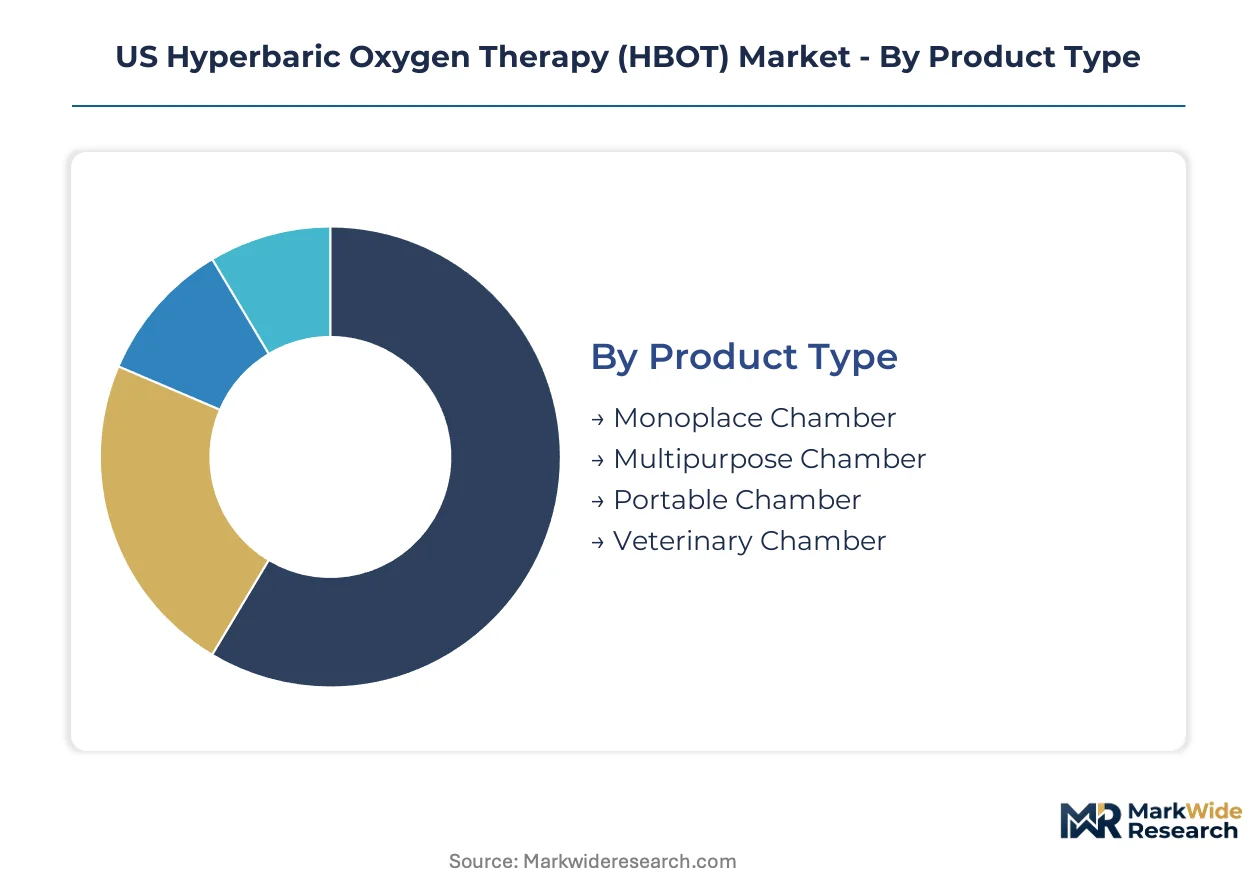
HBOT equipment specification varies sharply across clinical settings, with chamber architecture, pressure ratings, and integration requirements diverging between hospital outpatient departments and alternative care sites. Understanding these segment boundaries clarifies where capital deployment concentrates and which configurations face regulatory or reimbursement headwinds.
Product Type:
Acrylic shell fabrication versus steel-hull engineering defines the customization-to-standardization spectrum, with monoplace systems approaching commodity production while multiplace configurations retain bespoke engineering cycles.
- Monoplace Chamber:Single-patient acrylic vessels operating at two to three atmospheres absolute with automated pressure control. Texas and Florida wound care centers drive installed base expansion as hospital outpatient departments prioritize reimbursable chronic care protocols.
- Multipurpose Chamber:Steel-hulled systems rated for higher pressure protocols with attendant access during pressurization. Academic medical centers in California concentrate demand for complex interventions requiring internal patient monitoring.
- Portable Chamber:Collapsible fabric or lightweight composite designs for field deployment and home-health channels.
- Veterinary Chamber:Species-adapted pressure vessels for equine and small-animal rehabilitation centers outside human reimbursement codes.
Most installed capacity flows through Monoplace Chamber configurations. Expansion is steepest in Portable Chamber distribution as mobile services bypass certificate-of-need restrictions.
Application:
Reimbursement coding density separates high-volume indications from niche clinical protocols, with CMS national coverage determinations concentrating capital investment in specific therapeutic areas.
- Wound Healing:Diabetic foot ulcer and chronic wound protocols dominate hospital outpatient department utilization. California, Texas, and Florida cluster density aligns with aging population concentration and specialized wound care center formation.
- Decompression Sickness:Hyperbaric intervention for diving-related gas bubble formation requiring immediate pressure reduction. Coastal markets and dive tourism corridors sustain dedicated chamber availability.
- Carbon Monoxide Poisoning:Emergency department activation for acute toxic exposure with high-pressure oxygen dissolution therapy.
- Radiation Injury:Post-radiation tissue necrosis treatment with expanding CMS coverage determination support.
Wound Healing commands the largest share of reimbursable sessions. Radiation Injury is gaining share fastest as coverage determinations broaden facility eligibility.
End User:
Capital access and accreditation requirements stratify procurement authority, with hospital sponsorship unlocking leasing channels that independent operators cannot secure.
- Hospitals:Academic medical centers and community hospital outpatient departments anchor equipment procurement through bundled capital budgets. The Joint Commission accreditation standards shape operational protocols and staff certification requirements.
- Clinics:Independent wound care centers face tightening lender requirements for hospital sponsorship in certificate-of-need jurisdictions like New York.
- Research Facilities:Investigational protocol chambers for FDA 510(k) predicate device development and new indication trials.
- Sports Centers:Athlete recovery installations outside standard reimbursement codes, concentrated in performance training clusters.
Hospital systems control the majority of chamber installations. Clinic expansion is accelerating most quickly in Texas and Florida outside CON-constrained states.
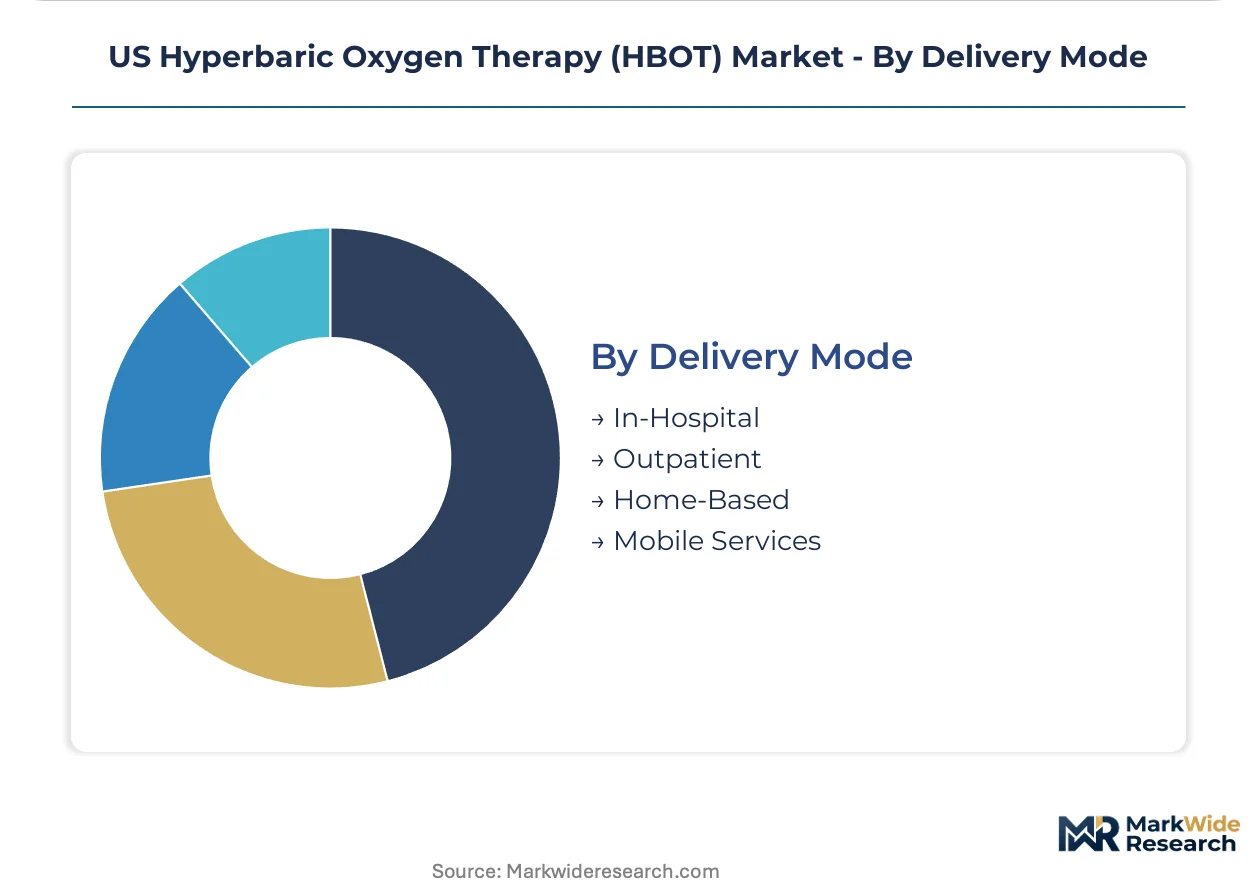
Delivery Mode:
Site-of-care migration reshapes equipment specification, with fixed installations giving way to distributed models that evade regulatory capacity constraints.
- In-Hospital:Integrated emergency department and inpatient hyperbaric units with 24-hour staffing coverage. FDA clearance pathways and CMS reimbursement schedules determine purchase justification cycles.
- Outpatient:Dedicated wound care centers with scheduled session blocks and technician specialization.
- Home-Based:Consumer-grade portable systems for chronic condition management outside institutional billing codes.
- Mobile Services:Trailer-mounted or transportable chambers delivering rural and post-acute care without fixed-site certificate-of-need compliance.
Outpatient delivery channels process the highest session volumes. Mobile Services are climbing the fastest as regional health systems seek geographic extension without CON-constrained capital deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Texas-Florida-California wound care corridor concentrates the majority of US HBOT infrastructure investment as aging demographics and specialized center formation drive regional deployment patterns.
Texas
Houston and Dallas-Fort Worth anchor the nation's densest cluster of independent wound care centers. The Texas Medical Center complex sustains multiplace chamber installations for complex intervention protocols. State absence of certificate-of-need regulations accelerates de novo outpatient facility formation beyond hospital system control.
Florida
South Florida's retiree concentration generates chronic wound referral volume that exceeds installed chamber capacity in Palm Beach and Broward counties. Tampa Bay and Orlando health systems expand outpatient hyperbaric units under bundled payment models. The state Medicaid program's wound care carve-outs influence site-level equipment procurement specifications.
California
Los Angeles County academic medical centers concentrate demand for steel-hulled multiplace systems rated above standard pressure protocols. Northern California's Kaiser Permanente integrated network standardizes monoplace chamber specifications across ambulatory surgery centers. State environmental regulations on medical gas storage shape facility siting decisions in dense urban corridors.
New York
Certificate-of-need regulations freeze hyperbaric capacity expansion in New York City and Long Island despite documented clinical demand. Upstate health systems redirect capital toward mobile service partnerships that bypass CON jurisdiction. The state Department of Health's CON review timelines extend equipment procurement cycles beyond national averages.
Illinois
Chicago-area hospital outpatient departments operate at chamber utilization ceilings imposed by state capacity restrictions. Downstate wound care clinics consolidate under regional health system sponsorship to unlock capital leasing channels. The Illinois Health Facilities and Services Review Board's certificate-of-need determinations fragment procurement authority across independent and affiliated sites.
US Hyperbaric Oxygen Therapy (HBOT) Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers scale acrylic shell fabrication and hospital outpatient departments accelerate chamber installation timelines. The vendor base stratifies across three tiers: domestic specialists with captive manufacturing, European engineering houses with premium positioning, and Asian fabricators serving cost-sensitive procurement. Strategic archetypes include in-house acrylic production specialists, steel-hull multiplace engineers, and portable chamber developers. Geographic expansion and FDA 510(k) pathway optimization represent the dominant competitive moves.
Among domestic manufacturers, Sechrist Industries, Perry Baromedical, and Environmental Tectonics occupy positions that exemplify contrasting engineering philosophies. Sechrist represents the vertically integrated fabrication archetype through captive acrylic shell production. Perry Baromedical anchors the premium multiplace segment where steel-hulled construction supports higher-pressure clinical protocols. Environmental Tectonics exemplifies simulation-derived engineering approaches that extend equipment lifecycle performance. These three firms collectively illustrate how chamber architecture specialization—acrylic monoplace, steel multiplace, and simulation-optimized systems—shapes competitive positioning within reimbursement-constrained procurement environments.
| Leading Market Players |
|---|
| Sechrist Industries, Inc. |
| Perry Baromedical Corp. |
| Environmental Tectonics Corp. |
| OxyHealth |
| Gulf Coast Hyperbarics Inc. |
| Haux Life Support GmbH |
| Fink Engineering Pty Ltd. |
| Hearmec Co. Ltd. |
| Hyperbaric Modular Systems Inc. |
| Others |
Value Network & Pricing Analysis
Acrylic shell fabrication automation is compressing monoplace chamber production economics while concentrating supply leverage among domestic manufacturers with captive molding operations. This technology transition simultaneously reduces per-unit capital requirements for hospital outpatient departments and reinforces pricing power for vertically integrated fabricators against steel-hull competitors exposed to commodity volatility.
Pricing Analysis
Steel input cost pass-through dominates multiplace chamber pricing, with hull fabrication accounting for substantial cost share and exposing Perry Baromedical and European engineering houses to margin compression when commodity indices spike. Price differentiation rests on pressure rating certification and The Joint Commission compliance bundling, with premium tiers capturing academic medical center procurement. Pricing pressure stems from acrylic monoplace commoditization as Sechrist Industries and OxyHealth scale in-house shell production. Independent wound care clinics exhibit highest price sensitivity, constrained by capital access limitations, while hospital systems prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
Reverse-logistics flows for chamber refurbishment and acrylic shell replacement parts extend equipment lifecycle and sustain aftermarket revenue for domestic manufacturers. Supply concentration centers on the United States, Germany, and Australia, with Sechrist Industries and Perry Baromedical anchoring North American fabrication. Raw material dependencies include medical-grade acrylic resin, pressure-rated steel plate, and FDA-compliant sealing systems. Supply chain risk centers on single-source vulnerability for specialized acrylic formulations subject to chemical feedstock volatility. Distribution runs through hospital GPO contracts and direct regional health system procurement, bypassing traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Texas and Florida's absence of certificate-of-need regulations enables capital deployment at roughly half the regulatory carrying cost of New York or Illinois, compressing payback periods for identical equipment specifications.
For Market Incumbents: Anticipate negative-pressure wound therapy substitution in lower-acuity segments by embedding real-time tissue oxygen monitoring as standard equipment specification, closing the clinical efficacy gap that drives HBOT referral. Deepen backward integration into medical-grade acrylic resin supply through long-term offtake agreements with chemical producers, insulating fabrication margins from petrochemical volatility that threatens steel-hull competitors. Prioritize FDA 510(k) pathway optimization for automated pressure control systems to accelerate time-to-revenue against emerging portable chamber entrants. For New Entrants and Emerging Players: Launch via mobile service partnerships that bypass fixed-site CON restrictions entirely, capturing rural and post-acute care demand that hospital systems cannot address under state capacity caps. Target veterinary rehabilitation centers in Texas and Florida as the most penetrable white-space channel, operating outside human CMS reimbursement complexity with streamlined purchase cycles. Penetrate independent wound care clinic formation through equipment-as-a-service financing that substitutes for hospital sponsorship requirements constraining capital leasing channels. For Investors and Strategic Acquirers: Valuations sit cheapest among regional mobile service operators with trailer-mounted chamber fleets, trading at discount to fixed-site multiples despite superior regulatory optionality across CON-constrained states. Long-term viability favors manufacturers with captive acrylic fabrication and software-integrated chamber control systems, positioned for recurring revenue attachment as equipment refresh cycles accelerate. Monitor CMS national coverage determination timelines for radiation injury protocols as the critical inflection signal, with expanded reimbursement codes triggering hospital outpatient department capital deployment waves.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Optimization | Streamlined predicate device clearance compresses manufacturer time-to-revenue for pressure vessel modifications. |
| Hospital System Partnership | Affiliation with regional health systems unlocks GPO contracting and capital leasing channels for independent clinics. |
| Software Companion Development | Closed-loop oxygen delivery integration with EMR platforms reduces technician burden and justifies premium specification. |
| Reimbursement Strategy | Coverage determination alignment with CMS diabetic foot ulcer protocols concentrates demand in reimbursable indications. |
| Geographic Expansion | Texas and Florida facility formation exploits regulatory arbitrage against CON-constrained Northeast markets. |
Research Methodology
Multiple input streams — structured interviews with hyperbaric physicians and wound care center administrators, biomedical engineering directors at hospital systems, and GPO contract managers — were reconciled against secondary validation from FDA 510(k) clearance databases, CMS national coverage determination records, and state certificate-of-need regulatory filings. Primary fieldwork captured equipment specification priorities, procurement cycle timing, and technician certification constraints. Secondary sources included hospital procurement databases, The Joint Commission accreditation standards, and acrylic resin trade flow data. Bottom-up chamber installation counts by state were triangulated against top-down market sizing derived from CMS reimbursement claims patterns.
Historical installation trajectories in Texas, Florida, and California were cross-referenced against panel input from manufacturer sales leadership and regional health system capital planning officers to anchor growth assumptions. Segmentation modeling spanned chamber architecture, pressure rating tier, delivery mode, and end-user accreditation status across the projection horizon. CAGRs were derived from equipment replacement cycles, demographic wound incidence projections, and regulatory capacity constraint elasticity estimates. Forecast inputs incorporated FDA clearance timeline compression, state-level CON repeal probability assessments, and negative-pressure wound therapy substitution elasticity in lower-acuity segments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt CMS reimbursement code contraction or accelerated state CON expansion. Practitioners should monitor CMS national coverage determination announcements, state health facility regulatory board dockets, and acrylic resin commodity index movements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
US and Japan Platelet Rich Plasma Market
Medical Treatment
CINV Treatment Market
Medical Treatment
Hereditary Amyloidosis Treatment Market
Medical Treatment
Allergic Rhinitis Treatment Market
Medical Treatment
Brazilian Hemorrhagic Fever (Bzhf) Treatment Market
Medical Treatment
Tendonitis Treatment Market
Medical Treatment
Radiotherapy Induced Oral Mucositis Treatment Market
Medical Treatment
Adenomyosis Treatment Market
Medical Treatment
Hyperkalemia Treatment Market
Medical Treatment
Andersen Tawil Syndrome Treatment Market
Medical Treatment
Parathyroid Disease Treatment Market
Medical Treatment
Porphyria Treatment Market
Medical Treatment
Global Uterine Fibroids Treatment Market
Medical Treatment
Anorectal Malformation Treatment Market
Medical Treatment
Lung Cancer Surgery Market
Medical Treatment
Surgical Procedures Volume Market