
 Global Genitourinary Drugs Market | 2026-2036
Global Genitourinary Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Genitourinary Drugs Market Foresight
The widening gap between biologic precision therapies and commoditized alpha blockers is repositioning how manufacturers allocate R&D capital across the genitourinary landscape. Pfizer Inc. leverages its established urology franchise to sustain formulary access in mature markets, while Astellas Pharma Inc. anchors its competitive stance through deep specialization in overactive bladder and prostate therapeutic segments. Bayer AG differentiates by controlling manufacturing scale for hormone-modulating compounds used across multiple indications.
Genitourinary drugs comprise pharmaceutical agents targeting renal, bladder, prostate, and reproductive system pathologies, formulated as oral tablets, injectables, transdermal patches, topical gels, and suppositories to achieve localized or systemic therapeutic effects. These agents modulate alpha-adrenergic receptors, phosphodiesterase enzymes, or hormonal pathways to restore urinary function, manage benign prostatic hyperplasia, or treat erectile dysfunction. Phosphodiesterase inhibitors occupy the highest-margin tier due to patent-protected mechanisms and direct-to-consumer channel dynamics, while hormone replacement therapies represent the fastest-expanding category as aging demographics in developed economies drive prostate cancer adjuvant demand. Alpha blockers constitute the most mature segment, with pricing pressure concentrated among genericized molecules distributed through pharmacy chains.
FDA review standards for urology new molecular entities, EMA's MDR-aligned clinical evidence requirements, and Japan's PMDA pharmacovigilance protocols collectively shape trial design costs and market entry timelines across major jurisdictions. REACH and RoHS frameworks in Europe additionally govern excipient purity and packaging material compliance for transdermal and topical delivery systems. Stakeholders must monitor how regulator divergence on real-world evidence acceptance is fragmenting development strategies between the United States and European Union approval pathways.
Market Dynamics
Biologic precision therapies are compressing the commercial viability of genericized alpha blockers, forcing manufacturers to reallocate R&D capital toward hormone-modulating compounds and receptor-targeting mechanisms that command sustained formulary access.
Growth Catalysts
- FDA Streamlined Review Pathways:The FDA's accelerated assessment protocols for urological new molecular entities are compressing development timelines and attracting venture funding toward novel mechanisms.
- Aging Demographics in Developed Economies:Prostate cancer adjuvant demand and overactive bladder prevalence in Germany, Japan, and the United States are expanding the addressable patient pool for hormone replacement therapies.
- Specialty Clinic Infrastructure:Urology specialty clinics in the United States and Germany are deepening their prescribing capacity for advanced injectable and transdermal delivery systems.
Market Restraints
- Genericized Alpha Blocker Pricing Collapse:Pharmacy chain consolidation in the United States is intensifying bidding pressure on commoditized molecules with expired patent protection.
- EMA MDR-Aligned Evidence Requirements:The European Medicines Agency's tightened clinical evidence standards for transdermal and topical delivery systems are extending trial durations and inflating regulatory compliance costs.
- Active Pharmaceutical Ingredient Concentration:Manufacturing scale for hormone-modulating compounds concentrates among a limited supplier base in India and China, exposing formulators to input volatility.
Strategic Opportunities
- Underpenetrated Japanese Adjuvant Market:Japan's PMDA pharmacovigilance protocols, once navigated, create durable competitive moats for hormone replacement therapies in prostate cancer care.
- Direct-to-Consumer Channel Expansion:Phosphodiesterase inhibitors are migrating toward telehealth platforms and direct-to-consumer distribution, bypassing traditional pharmacy intermediaries.
- REACH and RoHS Compliance Differentiation:European excipient purity and packaging material standards are creating premium positioning opportunities for manufacturers with verified sustainable supply chains.
Industry Challenges
- Real-World Evidence Divergence:The FDA and EMA are fragmenting on acceptable real-world evidence standards, forcing developers to maintain parallel trial designs for dual-territory approval.
- Complex Biologic Manufacturing Scale-Up:Cell-line development and bioreactor optimization for precision therapies require capital-intensive facility investments with extended validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Genitourinary Drugs Market |
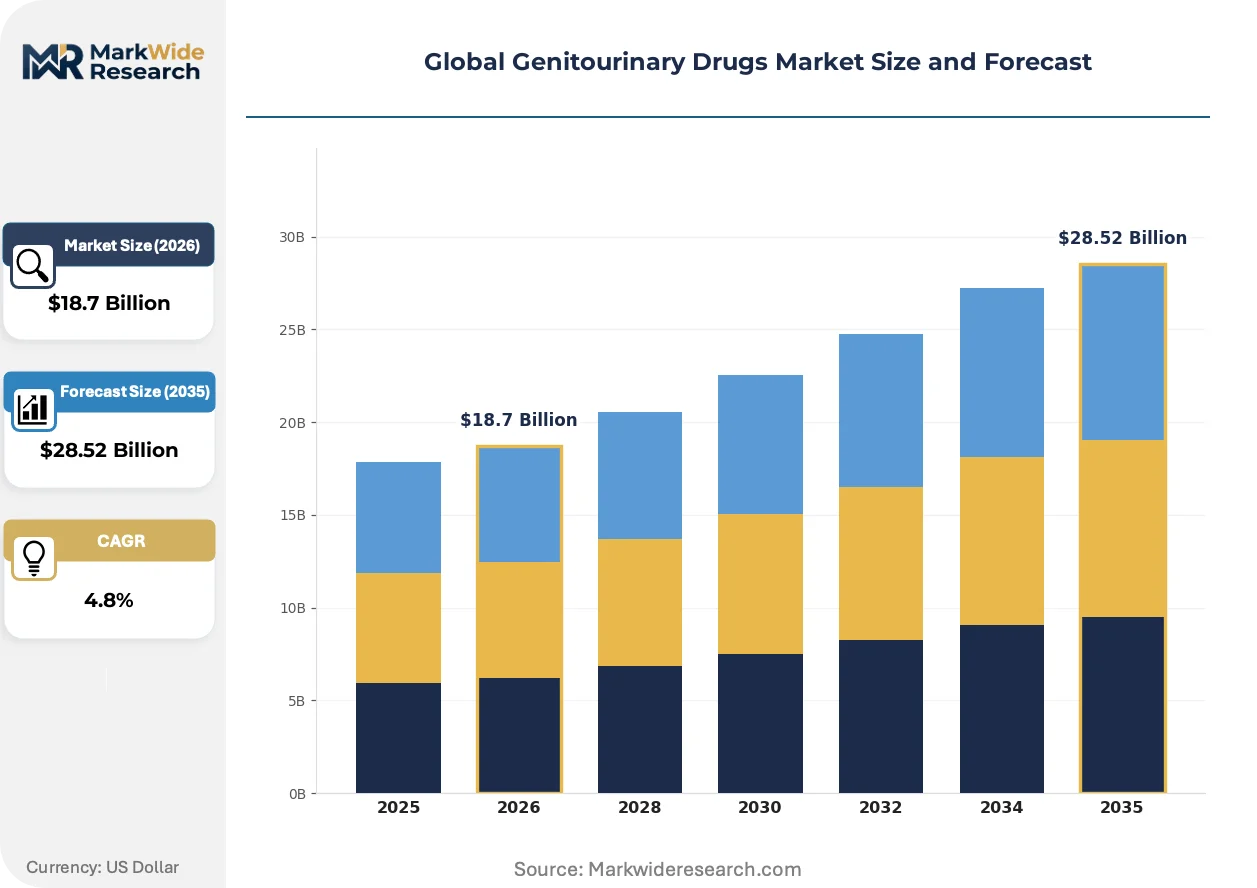
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Alpha Blockers, Anticholinergics, Phosphodiesterase Inhibitors, Hormone Replacement Therapies, Others Indication: Benign Prostatic Hyperplasia, Erectile Dysfunction, Urinary Incontinence, Overactive Bladder, Interstitial Cystitis End User: Specialty Clinics, Physician Offices, Ambulatory Surgical Centers, Pharmacy Chains Formulation: Oral Tablets, Topical Gels, Injectables, Transdermal Patches, Suppositories |
| Companies Covered | Pfizer Inc., Astellas Pharma Inc., Bayer AG, Novartis AG, Merck & Co. Inc., Eli Lilly and Company, GlaxoSmithKline plc, AstraZeneca plc, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Genitourinary Drugs Market Shifts & Advancements
Receptor-targeting biologics and localized delivery mechanisms are displacing systemic small-molecule approaches across multiple genitourinary indications, compressing development priorities toward precision mechanisms.
Antibody-drug conjugates targeting prostate-specific membrane antigens are consolidating the metastatic castration-resistant prostate cancer treatment paradigm. Academic medical centers in the United States and Germany are prioritizing these agents in adjuvant protocols ahead of standard chemotherapy. The technology is consolidating patient volume toward tertiary referral networks capable of managing infusion logistics and immune monitoring.
The European Union's Medical Device Regulation alignment with pharmaceutical excipient standards is tightening purity requirements for transdermal patches and topical gels. Manufacturers must now submit extended stability data and leachable assessments for polymer-based delivery systems. German and French regulators are enforcing these provisions most stringently, delaying market entry for formulations with legacy packaging materials.
Urology group purchasing organizations in the United States are consolidating formulary decisions across regional health systems, compressing physician autonomy in product selection. Specialty distributors are responding by unbundling value-added services from product margins to maintain contract eligibility. This concentration is most visible in the southeastern and midwestern United States, where hospital system mergers have reduced independent clinic purchasing power.
Global Genitourinary Drugs Market Segmentation
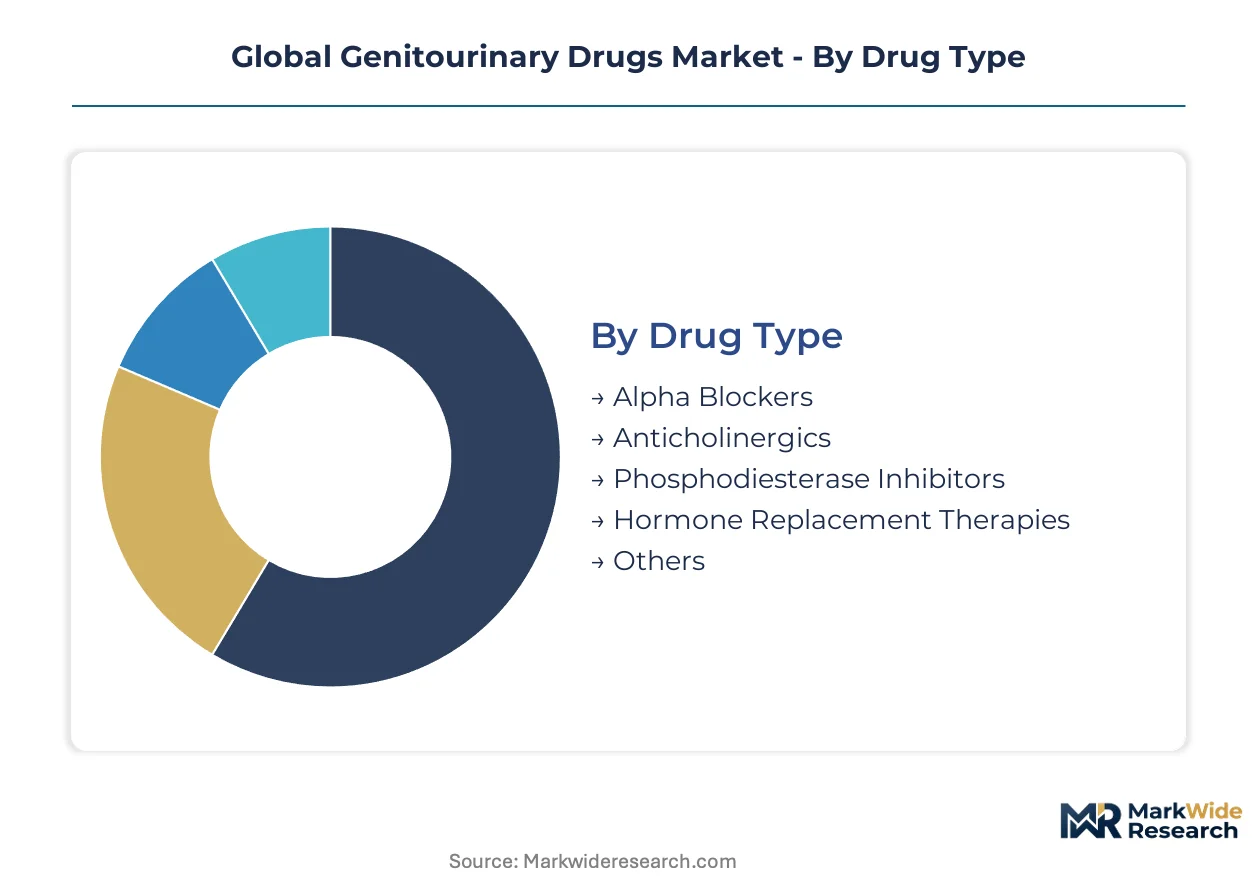
Genitourinary drug manufacturers segment their portfolios across four axes to align R&D investment with reimbursement pathways and prescribing site capabilities. Each dimension reflects distinct technical requirements, regulatory burdens, and margin structures that determine competitive positioning.
Drug Type:
Pharmacological mechanism determines manufacturing complexity, patent protection duration, and formulary access tier across institutional buyers.
- Phosphodiesterase Inhibitors:Small-molecule compounds targeting cyclic GMP degradation command premium pricing through direct-to-consumer channels and telehealth platforms. United States pharmacy benefit managers classify these agents as specialty tier with limited generic substitution, preserving margin for originator manufacturers.
- Hormone Replacement Therapies:Androgen deprivation formulations and anti-androgens require cold-chain logistics and extended stability validation. Germany's EMA-aligned reimbursement authorities accelerate access for prostate cancer adjuvant protocols, expanding prescribing volume in academic medical centers.
- Alpha Blockers:Genericized selective alpha-1 antagonists face concentrated bidding pressure from United States pharmacy chain consolidation.
- Anticholinergics:Muscarinic receptor antagonists for overactive bladder compete on tolerability profiles and cognitive side-effect differentiation.
- Others:Emerging biologic precision therapies and antibody-drug conjugates occupy development pipelines for metastatic indications.
Phosphodiesterase inhibitors lead on scale; hormone replacement therapies lead on momentum.
Indication:
Disease prevalence and treatment paradigm maturity create divergent addressable patient pools and pricing power across therapeutic areas.
- Erectile Dysfunction:High-diagnosis-rate condition with established direct-to-consumer pathways and minimal prior authorization requirements in United States commercial plans. Telehealth platforms have displaced traditional urology referrals for initial prescribing.
- Benign Prostatic Hyperplasia:Age-correlated prevalence drives volume in Germany and Japan where specialty clinic infrastructure supports combination therapy protocols. Alpha blocker and 5-alpha reductase inhibitor co-prescribing extends treatment duration.
- Overactive Bladder:Underdiagnosed condition with expanding anticholinergic and beta-3 agonist therapeutic options.
- Urinary Incontinence:Stress and urge subtypes require distinct pharmacological approaches with varying surgical crossover rates.
- Interstitial Cystitis:Orphan-disease designation in multiple jurisdictions supports premium pricing for limited therapeutic alternatives.
Benign prostatic hyperplasia anchors volume concentration; erectile dysfunction maintains margin leadership.
End User:
Site-of-care economics and reimbursement mechanics fragment demand across institutional settings with varying formulary control.
- Specialty Clinics:United States urology group practices concentrate prescribing for injectable and implantable delivery systems. Infusion center capabilities support biologic administration with higher reimbursement rates than office-based settings.
- Pharmacy Chains:CVS Health and Walgreens Boots Alliance negotiate consolidated purchasing for oral solid dosage forms, compressing net prices for genericized molecules.
- Physician Offices:Independent urology practices retain autonomy for sample-based initiation of novel therapies.
- Ambulatory Surgical Centers:Procedure-integrated drug delivery for intraoperative and immediate postoperative applications.
Specialty clinics lead on therapeutic complexity; pharmacy chains lead on volume throughput.
Formulation:
Delivery technology determines bioavailability profiles, patient adherence metrics, and manufacturing capital requirements.
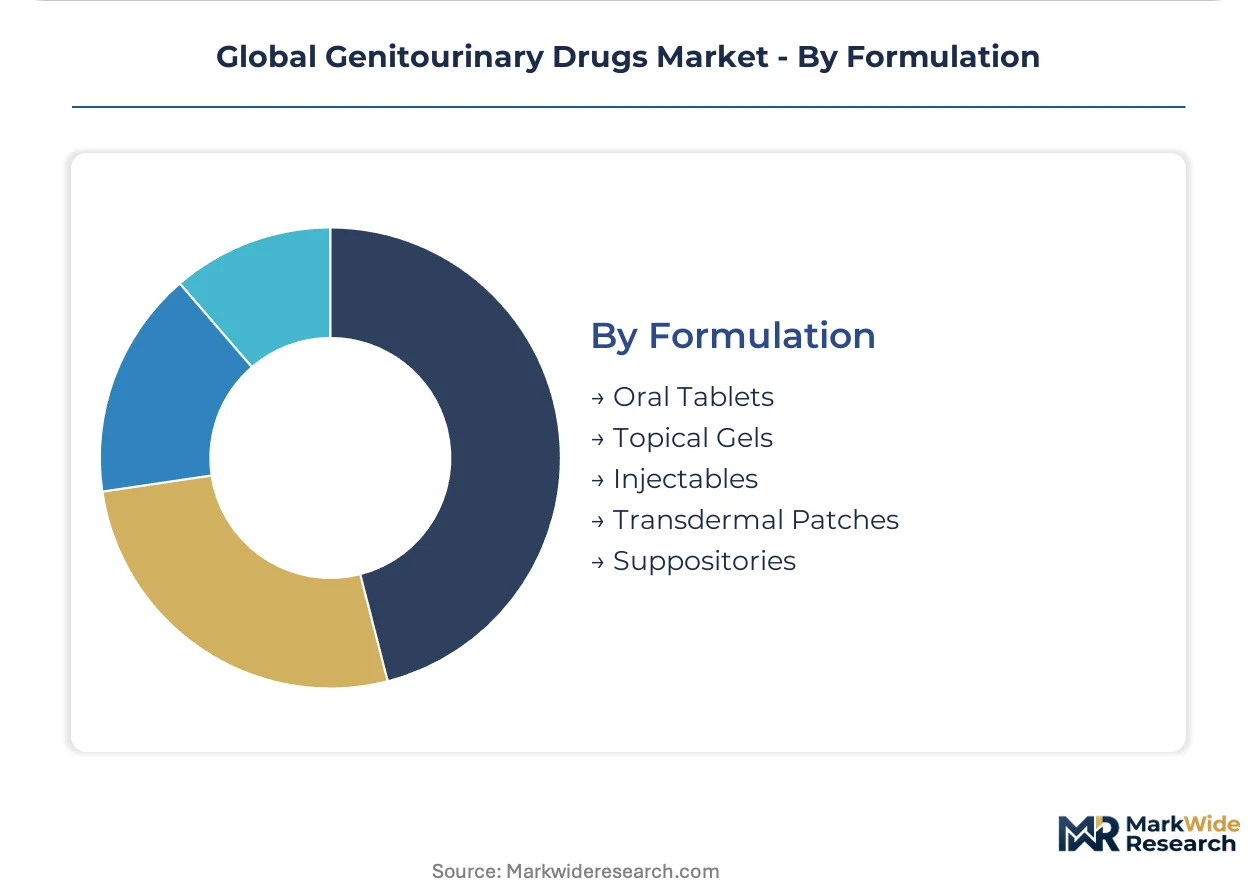
- Oral Tablets:Immediate-release and extended-release solid dosage forms dominate prescription volume with established bioequivalence pathways for generic entry. United States ANDA filings concentrate in this category.
- Injectables:Depot formulations and subcutaneous biologics require aseptic manufacturing suites with extended validation timelines. PMDA pharmacovigilance protocols in Japan create durable competitive moats for approved products.
- Transdermal Patches:EMA MDR-aligned excipient purity standards extend development timelines for polymer-based delivery systems.
- Topical Gels:Localized absorption profiles reduce systemic exposure for hormone replacement applications.
- Suppositories:Rectal and urethral delivery for localized urological conditions with limited commercial scale.
Oral tablets dominate prescription volume; injectables command the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands higher per-capita spending on phosphodiesterase inhibitors than Germany, yet Japan's prostate cancer adjuvant protocols drive faster volume growth for hormone replacement therapies. Regulatory divergence between FDA and EMA pathways is fragmenting development strategies across these three mature markets.
United States
Urology group purchasing organizations concentrate formulary decisions across southeastern and midwestern hospital systems, reducing independent clinic purchasing power. FDA accelerated assessment protocols for urological new molecular entities compress development timelines and attract venture funding. Specialty clinics in Texas and Florida deepen prescribing capacity for advanced injectable delivery systems.
Germany
Academic medical centers in Bavaria and Baden-Württemberg prioritize antibody-drug conjugates in adjuvant protocols ahead of standard chemotherapy. EMA MDR-aligned evidence requirements extend trial durations for transdermal and topical delivery systems. The Rhine-Ruhr metropolitan region anchors manufacturing scale for hormone-modulating compounds serving multiple European indications.
Japan
Aging demographics expand the addressable patient pool for overactive bladder and benign prostatic hyperplasia therapies. PMDA pharmacovigilance protocols create durable competitive moats for approved hormone replacement therapies once navigated. The Kanto region around Tokyo concentrates urology specialty infrastructure capable of managing biologic infusion logistics.
India
Domestic demand for alpha blockers rises as diagnosis rates for benign prostatic hyperplasia improve in urban centers. CDSCO streamlined review pathways for urological generics accelerate market entry for domestic manufacturers. The Mumbai-Pune corridor hosts active pharmaceutical ingredient suppliers serving hormone-modulating compound formulators.
United Kingdom
NHS integrated care systems consolidate prescribing decisions for erectile dysfunction therapies toward pharmacy-led pathways. MHRA post-Brexit regulatory autonomy permits divergence from EMA timelines for novel urological mechanisms. The Greater London area concentrates telehealth platforms displacing traditional urology referrals for initial phosphodiesterase inhibitor prescribing.
Global Genitourinary Drugs Market Competitive Landscape
Top-tier vendors anchor the phosphodiesterase inhibitor segment through direct-to-consumer channel control, while mid-scale specialists concentrate on hormone-modulating compounds and receptor-targeting biologics. The vendor base stratifies across three archetypes: diversified pharmaceutical conglomerates with established urology franchises, pure-play urological specialists with deep indication focus, and emerging biologic developers advancing precision mechanisms. Consolidation pressures intensify as pharmacy chain bidding and group purchasing organization concentration compress margins for genericized molecules.
Within the diversified pharmaceutical tier, Pfizer Inc. and Bayer AG exemplify scale-driven positioning across multiple genitourinary indications, while Astellas Pharma Inc. occupies a specialist position anchored in overactive bladder and prostate therapeutic segments. These three entities represent contrasting strategic postures: broad portfolio leverage versus deep indication specialization.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Astellas Pharma Inc. |
| Bayer AG |
| Novartis AG |
| Merck & Co. Inc. |
| Eli Lilly and Company |
| GlaxoSmithKline plc |
| AstraZeneca plc |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
Hormone-modulating API spot prices in India and China cascade through formulation tiers, compressing margins for generic alpha blockers while preserving premium capture for biologic precision therapies with captive manufacturing.
Pricing Analysis
Capacity additions in China and India are reshaping price floors for hormone-modulating compounds, forcing three-tier pricing structure across premium, standard, and economy levels. Brand-protected phosphodiesterase inhibitors command premium positioning through direct-to-consumer channels, while pharmacy chain consolidation in the United States intensifies bidding pressure on genericized alpha blockers. Cost compression in the alpha blocker tier reflects formulary exclusion by CVS Health and Walgreens Boots Alliance, whereas specialty clinics exhibit lowest price sensitivity for injectable biologics with infusion logistics bundled into reimbursement.
Supply Chain Analysis
Direct-to-specialty-clinic channels handle advanced injectable and transdermal demand, bypassing pharmacy intermediaries for higher-margin therapies. Active pharmaceutical ingredient manufacturing concentrates in India, China, and Germany, with hormone-modulating compound synthesis drawing from steroid precursor supplies in the Mumbai-Pune corridor. Cold-chain logistics for biologics rests on single-source vulnerability in specialized aseptic filling capacity. Distribution runs through regional specialty distributors in the United States and academic medical center networks in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Genitourinary Drugs Market represents a late-cycle quality story as prostate cancer adjuvant protocols in Japan and Germany shift demand toward antibody-drug conjugates with premium reimbursement durability.
For Market Incumbents: To counter genericized alpha blocker pricing collapse, Pfizer Inc. and Astellas Pharma Inc. should deepen backward integration into hormone-modulating API supply through captive manufacturing in the Rhine-Ruhr corridor. Formulary access defense requires investment in real-world evidence generation aligned with FDA accelerated assessment protocols. For New Entrants and Emerging Players: Enter via Japan's underpenetrated adjuvant therapy segment where PMDA pharmacovigilance protocols create durable competitive moats post-approval. Telehealth-integrated direct-to-consumer channels for phosphodiesterase inhibitors offer the most penetrable go-to-market angle, displacing traditional pharmacy intermediaries through platform partnerships. For Investors and Strategic Acquirers: Asymmetric upside sits with biologic precision therapy developers advancing prostate-specific membrane antigen-targeting mechanisms. Long-term viability hinges on cell-line development capabilities and infusion center network access. The signal to watch is EMA-FDA divergence on real-world evidence acceptance standards fragmenting dual-territory approval economics.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Antibody-drug conjugate programs in metastatic castration-resistant prostate cancer consolidate academic medical center prescribing in Germany and the United States. |
| Regulatory Approval Pathway | FDA accelerated assessment protocols for urological new molecular entities compress development timelines and attract venture funding toward novel mechanisms. |
| Backward Integration | Captive hormone-modulating API production insulates formulators from input volatility concentrated among Indian and Chinese suppliers. |
| Direct-to-Consumer Channel Expansion | Telehealth platform partnerships for phosphodiesterase inhibitors bypass pharmacy benefit manager intermediaries and preserve margin. |
| Manufacturing Scale-Up | Aseptic bioreactor capacity expansion supports precision therapy commercialization with extended validation timelines creating competitive moats. |
Research Methodology
Multiple input streams — regulatory filings, hospital procurement databases, and API trade flows — were reconciled through bottom-up and top-down triangulation. Primary interviews with drug development executives, formulary directors at United States pharmacy benefit managers, regulatory affairs leads, and hospital procurement managers were validated against secondary sources including FDA submissions, EMA assessment reports, ClinicalTrials.gov protocols, and formulary exclusion databases. Cross-referencing manufacturer capacity disclosures with customs data on hormone-modulating compound imports anchored supply-side estimates.
Historical volume trajectories were stress-tested against expert panel inputs on reimbursement pathway shifts across the projection horizon. Segmentation modeling incorporated drug type, indication, end-user site of care, and formulation technology dimensions alongside regional regulatory cluster effects. CAGRs were derived from patient population epidemiology, treatment paradigm evolution, and pricing tier migration assumptions. Forecast inputs included prostate cancer incidence projections, specialty clinic infrastructure buildout rates, and PMDA pharmacovigilance navigation timelines for Japanese market entry.
Inputs from FDA and EMA regulatory databases were available through the study window; gaps in real-world evidence submission timelines for novel biologics introduce uncertainty bands around adoption curve assumptions. Forecasts reflect documented assumptions on reimbursement durability and regulatory convergence trajectories, with periodic stress-testing of base assumptions recommended given EMA-FDA divergence on evidence standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Lamotrigine API Market
Pharmaceuticals
Allergic Rhinitis Drugs Market
Pharmaceuticals
Global Acyclovir Market
Pharmaceuticals
Psychedelic Drugs Market
Pharmaceuticals
Global Anti-Infective Agents Market
Pharmaceuticals
Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Adapalene Market
Pharmaceuticals
Computer-Aided Drug Discovery Market
Pharmaceuticals
Global Immunomodulators Market
Pharmaceuticals
Artificial Intelligence in Drug Screening Market
Pharmaceuticals
Metformin Hydrochloride Market
Pharmaceuticals
Mexico Dimenhydrinate Market
Pharmaceuticals
Gamma-Hydroxybutyric Acid Market
Pharmaceuticals
Russia Diabetes Drugs Market
Pharmaceuticals
Sporanox Market
Pharmaceuticals
China Human Papillomavirus Vaccine Market