
 United Kingdom Plastic Caps and Closures Market | 2026-2036
United Kingdom Plastic Caps and Closures Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Plastic Caps and Closures Market Insights
The gap between premium dispensing closures and commodity screw caps is realigning procurement priorities across UK packaging buyers. UNITED CAPS Dinnington Ltd leverages its Yorkshire manufacturing base to dominate high-volume food-grade closures. Berry Global Inc. anchors the pharmaceutical segment with cleanroom-certified production. Silgan Holdings Inc. differentiates through advanced tamper-evident technologies for beverage brands.
Plastic caps and closures are threaded or snap-fit sealing devices, typically injection-moulded from polypropylene or polyethylene with tolerances below 0.1 mm, designed to preserve product integrity and enable controlled dispensing. Screw caps retain the largest volume share across UK beverage and food applications, though dispensing caps capture expanding margin pools in cosmetics and pharmaceuticals. Polypropylene leads material selection for its chemical resistance and recyclability under UK packaging regulations, while polyethylene sustains cost-sensitive food segments.
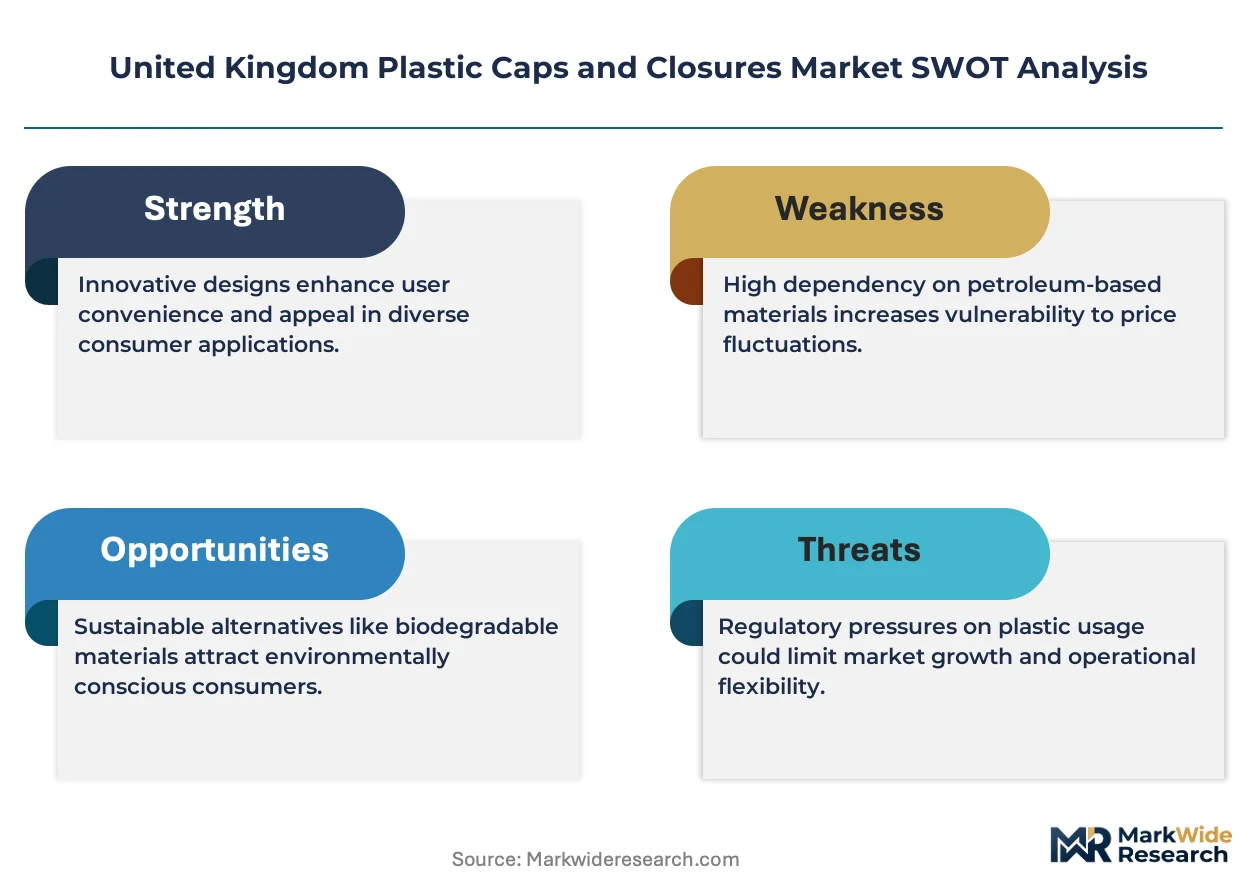
The UK Plastic Packaging Tax, enforced by HM Revenue and Customs, mandates minimum recycled content thresholds that reshape resin sourcing and moulding specifications. BSI standards for child-resistant closures and food contact materials further constrain design freedom and compliance costs. The Environment Agency's extended producer responsibility framework tightens post-consumer collection targets, forcing converters to redesign for recyclability. Stakeholders must weigh capital allocation between recycled-content compliance and premium closure innovation as regulatory thresholds tighten.
Market Dynamics
The UK Plastic Packaging Tax is compressing margins across converters while simultaneously unlocking premium pricing for compliant recycled-content closures. This single regulatory instrument now governs capital allocation decisions from resin sourcing through moulding equipment upgrades.
Growth Catalysts
- Extended Producer Responsibility frameworks:The Environment Agency's tightening post-consumer collection targets force brand owners to specify recyclable mono-material closures, expanding addressable demand for compatible cap designs.
- Pharmaceutical serialization mandates:MHRA requirements for tamper-evidence and track-and-trace integration drive replacement cycles across prescription packaging lines.
- Polypropylene chemical resistance:Superior performance in carbonated beverage applications sustains material preference despite recycled-content compliance costs.
Market Restraints
- Post-consumer resin price volatility:rPP and rPE supply constraints in England's industrial corridor inflate raw material costs unpredictably.
- Moulding equipment concentration:High-tonnage injection press availability clusters in South Yorkshire and West Midlands, creating geographic supply risk.
- Aluminium substitution in premium beverages:Crown corks and screw threads capture share in craft beer and sparkling water segments.
Strategic Opportunities
- Scottish beverage manufacturing expansion:Distillery and soft drink bottling investments in Speyside and Glasgow create underserved closure demand.
- Smart closure integration:NFC-enabled and QR-coded dispensing caps bridge physical packaging with digital authentication platforms.
- Plastic Packaging Tax thresholds:Anticipated tightening of recycled-content minimums from 2027 positions early-compliant converters for locked-in supply contracts.
Industry Challenges
- Food contact certification timelines:Novel polymer approvals through the Food Standards Agency extend product development cycles by 18-24 months.
- Recyclability design integration:Balancing child-resistant mechanisms with mono-material construction demands specialized tooling investments that strain mid-cap converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Plastic Caps and Closures Market |
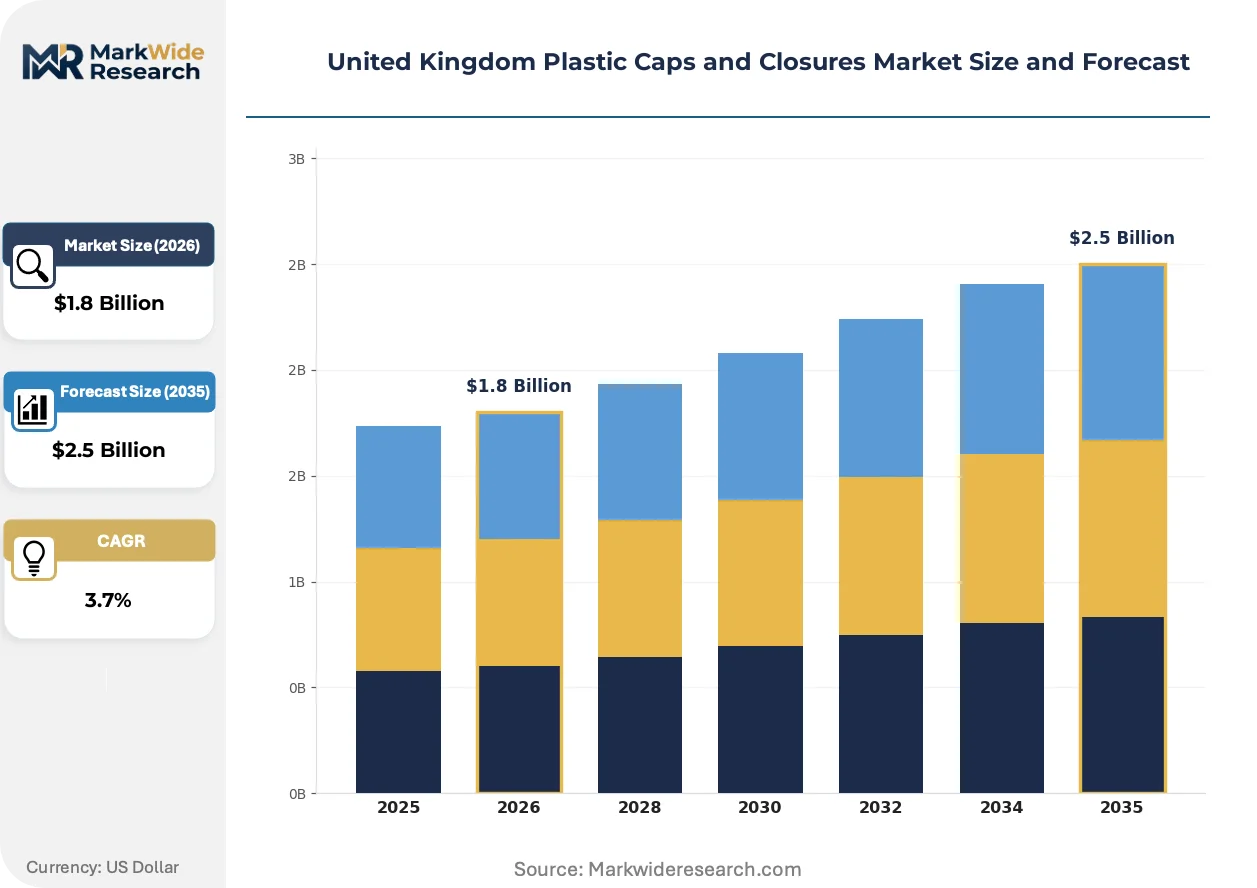
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screw Caps, Snap-Fit Caps, Dispensing Caps, Tamper-Evident Caps Material: Polyethylene, Polypropylene, PET, PVC End User: Beverage, Food, Cosmetics, Pharmaceuticals Closure Type: Flip-Top, Cork, Push-Down, Crown |
| Companies Covered | UNITED CAPS Dinnington Ltd, Berlin Packaging UK, Bericap UK Limited, Berry Global Inc., Silgan Holdings Inc., P. Wilkinson Containers Ltd, Plastic Closures Limited, UB Plastics Limited, Robinson PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Plastic Caps and Closures Market Trends and Innovations
Digital printing and smart packaging integration are redefining how closures communicate with consumers and supply chains. These capabilities now separate premium positioning from commodity supply.
Mono-material polypropylene closures with integrated living hinges are electrifying sustainable packaging roadmaps. Major beverage brands in England's Midlands manufacturing belt are specifying these designs for 2025 product refreshes. The technology is electrifying converter R&D budgets while compressing tolerance for multi-component assemblies.
HM Revenue and Customs enforcement of Plastic Packaging Tax documentation requirements is reshaping supplier qualification protocols. Brand owners now demand certified mass-balance accounting from closure vendors before contract award. Food and pharmaceutical packagers in Greater Manchester face the steepest compliance verification burdens.
Direct procurement relationships between brand owners and specialised closure converters are displacing traditional distribution intermediaries. Large beverage groups in Birmingham and Solihull now negotiate resin-grade specifications directly with moulders. This pattern concentrates most visibly in carbonated soft drink and ready-to-drink alcohol segments.
United Kingdom Plastic Caps and Closures Market Segmentation
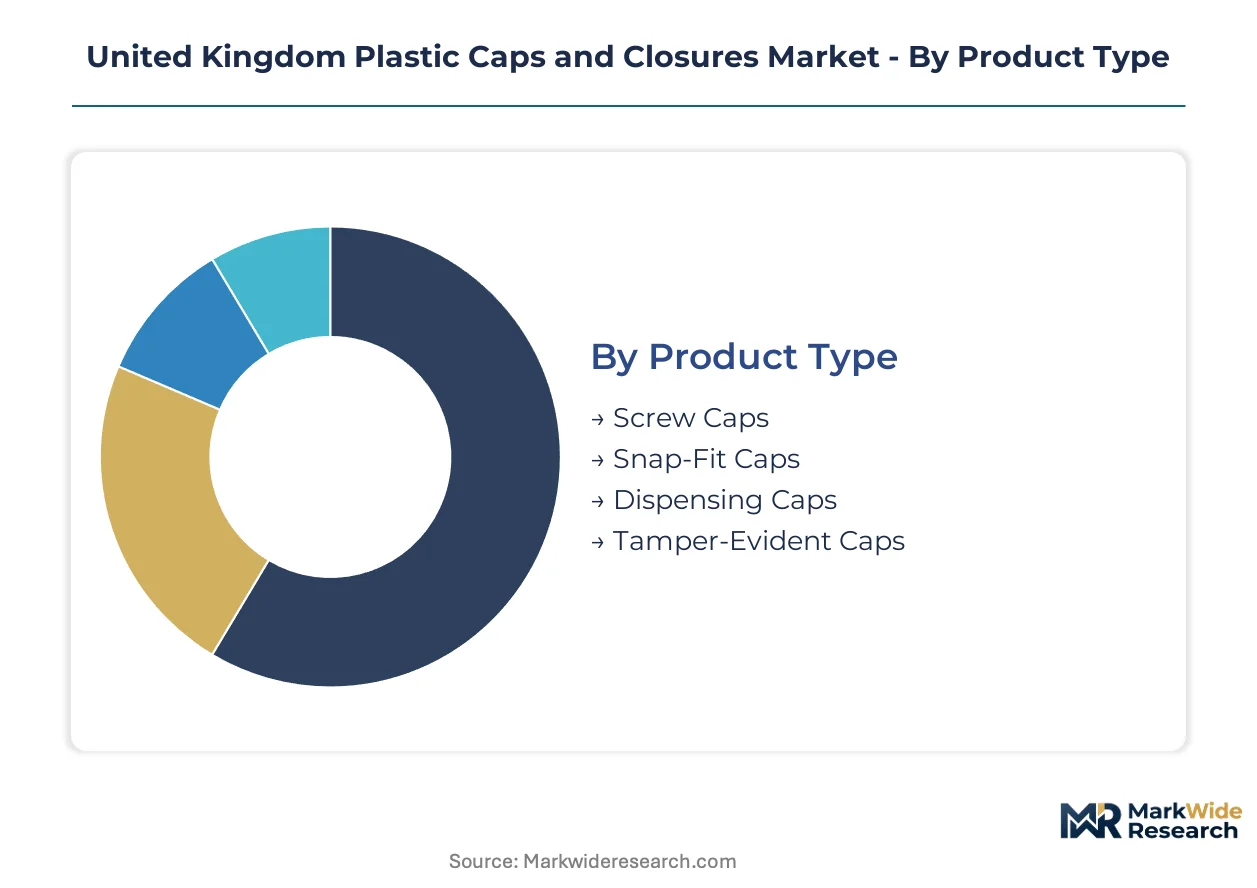
Segmentation in the UK plastic caps and closures market reveals how capital deployment, regulatory compliance, and end-use specifications fragment manufacturing capabilities. Each dimension shapes tooling investments, resin sourcing, and moulding line configurations differently.
Product Type:
Screw caps demand the heaviest upfront capital given their precision threading requirements and high-cavitation moulding lines. Snap-fit and dispensing variants require more complex tooling but run at lower volumes.
- Screw Caps:Injection-moulded with continuous helical threads and torque-release specifications, these dominate carbonated beverage lines across Birmingham and Solihull bottling plants. The segment ties up the longest production runs and dedicated high-tonnage presses.
- Dispensing Caps:Living-hinge and pump mechanisms integrate multiple functional components into single moulded assemblies. Cosmetics manufacturers in Greater Manchester specify these for premium skincare lines where controlled dosing commands price premiums.
- Snap-Fit Caps:Radial interference fit designs serve cost-sensitive food segments with simpler tooling requirements.
- Tamper-Evident Caps:Break-ring and band technologies satisfy MHRA pharmaceutical mandates and beverage safety protocols.
Screw caps absorb the bulk of installed capacity; dispensing caps are expanding most quickly.
Material:
Resin selection stratifies around chemical resistance needs, recyclability compliance, and the Plastic Packaging Tax's recycled-content thresholds. Each polymer demands distinct moulding temperatures and cycle optimisation.
- Polypropylene:Semi-crystalline thermoplastic with excellent fatigue resistance and compatibility with hot-fill applications. Carbonated soft drink bottlers in England's Midlands manufacturing belt specify homopolymer grades for crown retention and pressure stability.
- Polyethylene:Lower density and softer sealing characteristics suit dairy and condiment applications where torque consistency matters less than cost containment.
- PET:Polyester clarity supports transparent closure demands in premium cosmetics and bottled water segments.
- PVC:Rigid formulations persist in specific pharmaceutical blister and container applications despite recyclability constraints.
Polypropylene commands the deepest tooling investments; polyethylene offers the lowest barrier to entry for new converters.
End User:
End-use concentration determines quality certification burdens and batch traceability requirements. Pharmaceutical and food segments impose the steepest compliance costs.
- Beverage:Carbonated soft drinks, bottled water, and ready-to-drink alcohol drive the highest volume throughput. Major brand owners in Manchester and Birmingham negotiate resin specifications directly with moulders, bypassing distribution intermediaries.
- Pharmaceutical:MHRA-mandated child-resistant and tamper-evident features require cleanroom-certified production environments. Berry Global Inc. anchors this segment with dedicated pharmaceutical-grade facilities.
- Food:Condiment, sauce, and dairy applications prioritise oxygen barrier performance and food contact certification through the Food Standards Agency.
- Cosmetics:Premium dispensing and airless pump closures support skincare and fragrance positioning in London and Edinburgh retail markets.
Beverage consumption dominates resin tonnage; pharmaceutical specifications extract the highest per-unit margins.
Closure Type:
Mechanism design separates commodity supply from premium positioning. Each type demands distinct tooling geometries and automation integration.
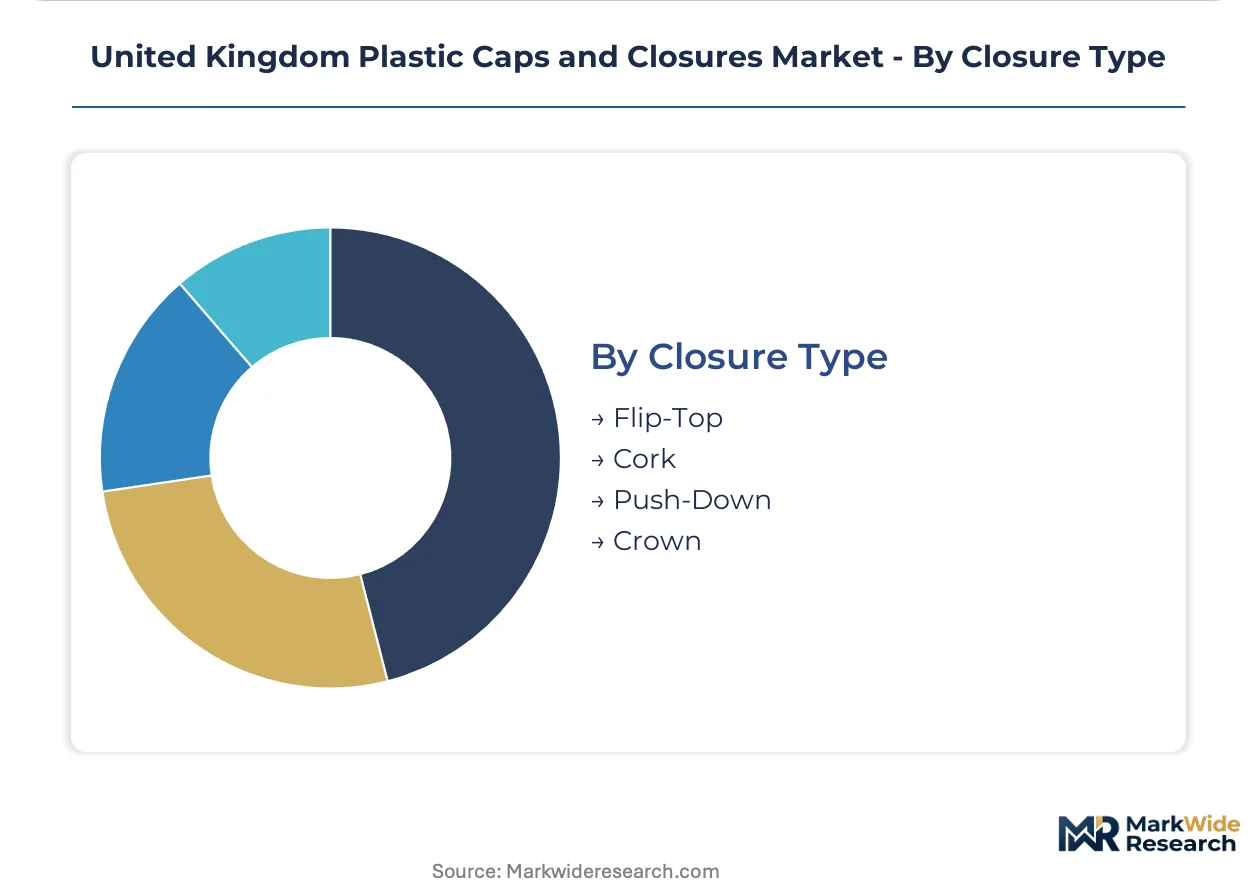
- Flip-Top:Integrated living hinges enable single-handed dispensing for condiments and personal care products. Mono-material polypropylene constructions satisfy emerging recyclability mandates from major FMCG brand owners.
- Push-Down:Child-resistant mechanisms combine compression and rotation forces for pharmaceutical compliance.
- Cork:Synthetic and natural cork alternatives serve wine and spirits applications in Scottish distillery operations.
- Crown:Crimped metal-plastic hybrids retain share in craft beer segments despite aluminium substitution pressure.
Flip-top designs capture the broadest application range; push-down mechanisms carry the steepest regulatory compliance burden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Manchester-Birmingham industrial corridor anchors UK plastic caps and closures production, with high-tonnage injection moulding clusters concentrated across South Yorkshire and the West Midlands. England's manufacturing belt generates the dominant share of domestic closure output, while Scottish beverage bottling and Welsh polymer processing extend the geographic footprint.
England
Carbonated soft drink bottlers in Birmingham and Solihull negotiate resin specifications directly with moulders, bypassing traditional distribution channels. HM Revenue and Customs enforces Plastic Packaging Tax documentation requirements that reshape supplier qualification protocols across Greater Manchester. The South Yorkshire moulding cluster hosts dedicated pharmaceutical-grade facilities serving MHRA-mandated child-resistant closure demand.
Scotland
Distillery and soft drink bottling investments in Speyside and Glasgow create expanding closure demand from premium spirits and ready-to-drink alcohol segments. The Scottish Environment Protection Agency aligns with UK-wide extended producer responsibility frameworks for post-consumer collection targets. Edinburgh's cosmetics packaging sector specifies premium dispensing caps for skincare lines targeting London retail markets.
Wales
Polymer processing operations in South Wales supply recycled-content polyethylene grades for cost-sensitive food applications. Welsh Government industrial strategy supports circular economy investments that align with Plastic Packaging Tax compliance timelines. The Cardiff-Newport corridor hosts mid-cap converters balancing recycled-content mandates with pharmaceutical certification requirements.
Northern Ireland
Beverage packaging demand from Belfast's food and drink manufacturing base drives screw cap consumption across dairy and condiment segments. Northern Ireland Environment Agency regulations mirror UK packaging compliance standards while creating cross-border supply chain coordination with Ireland. The Greater Belfast area concentrates moulding capacity serving local food processors and export-oriented distilleries.
United Kingdom Plastic Caps and Closures Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tiers, with pharmaceutical-grade and food-contact certified facilities commanding pricing power over standard beverage closures. The vendor base stratifies into three archetypes: multinational converters with cleanroom-certified production, regional specialists leveraging geographic proximity to England's industrial corridor, and mid-cap players pursuing recycled-content compliance as a differentiation vector. Dominant competitive moves include direct procurement relationships displacing distribution intermediaries, and moulding equipment upgrades targeting mono-material recyclability specifications.
Among UK-based and internationally anchored fabricators, UNITED CAPS Dinnington Ltd and Berry Global Inc. occupy positions at opposite ends of the certification spectrum, with the former exemplifying high-volume food-grade production from its Yorkshire base and the latter representing pharmaceutical-grade facility investment. Silgan Holdings Inc. sits within the technology-differentiated tier, while regional specialists including P. Wilkinson Containers Ltd and Plastic Closures Limited anchor mid-market supply for cost-sensitive segments. Berlin Packaging UK and Bericap UK Limited represent continental European parentage with UK distribution and conversion capabilities.
| Leading Market Players |
|---|
| UNITED CAPS Dinnington Ltd |
| Berlin Packaging UK |
| Bericap UK Limited |
| Berry Global Inc. |
| Silgan Holdings Inc. |
| P. Wilkinson Containers Ltd |
| Plastic Closures Limited |
| UB Plastics Limited |
| Robinson PLC |
| Others |
Pricing and Supply Chain Analysis
Post-consumer resin price volatility feeds directly through to tiered pricing structures across England's industrial corridor, with rPP and rPE cost swings compressing margins for mid-cap converters while premium-grade pharmaceutical closures sustain pricing power through MHRA certification requirements.
Pricing Analysis
Outcome-based pricing anchored to child-resistant certification tiers separates pharmaceutical-grade closures from commodity beverage supply. Three-tier pricing structure across premium, standard, and economy levels reflects MHRA compliance burdens, food-contact FSA approvals, and basic torque specifications respectively. Pricing pressure stems from Plastic Packaging Tax compliance costs as brand owners demand certified mass-balance accounting. Food processors in Greater Manchester exhibit highest price sensitivity; pharmaceutical packagers absorb premiums for tamper-evidence integration.
Supply Chain Analysis
Direct-to-brand-owner channels displace distribution intermediaries for high-volume beverage contracts across Birmingham and Solihull. Raw material sourcing draws from polymer processing operations in South Wales, virgin resin imports, and domestic rPP/rPE reclaimers. Supply chain risk centers on single-source vulnerability for high-tonnage injection press capacity clustered in South Yorkshire and West Midlands. Distribution runs through specialized logistics networks serving cleanroom-certified pharmaceutical facilities and high-throughput food-grade lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over recycled-content resin supply determines compliance positioning and margin defense against Plastic Packaging Tax thresholds.
For Market Incumbents: Deploy captive rPP sourcing agreements to lock in Plastic Packaging Tax-compliant feedstock before anticipated threshold tightening. Add dedicated mono-material living-hinge capacity in South Yorkshire to capture beverage brand refreshes. Aluminum substitution in craft beer and Crown cork share gains threaten standard screw cap volumes.
For New Entrants and Emerging Players: Begin with Scottish distillery and soft drink bottling investments in Speyside and Glasgow where closure supply remains underserved. Target premium dispensing cap demand from Edinburgh cosmetics manufacturers specifying airless pump designs for London retail. Pursue direct procurement relationships bypassing traditional distribution layers.
For Investors and Strategic Acquirers: Anticipated tightening of Plastic Packaging Tax recycled-content minimums is the leading indicator that early-compliant converters will secure locked-in supply contracts. Five-to-ten-year viability favors facilities with certified mass-balance accounting and pharmaceutical-grade cleanroom infrastructure. Watch for brand owner direct resin specification negotiations as signal of converter consolidation opportunity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPP Supply | Captive recycled resin sourcing secures Plastic Packaging Tax compliance ahead of regulatory tightening. |
| Mono-Material Living-Hinge Capacity Expansion | Beverage brands across England's Midlands specify these designs for sustainable packaging roadmaps. |
| Pharmaceutical Cleanroom Certification Investment | MHRA-mandated child-resistant production extracts highest per-unit margins in the market. |
| Smart Closure NFC Integration | QR-coded and NFC-enabled caps bridge physical packaging with digital authentication platforms. |
| Scottish Manufacturing Footprint Establishment | Distillery and soft drink bottling growth in Speyside creates underserved closure demand. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with plant managers at injection moulding facilities, procurement leads at beverage bottlers, pharmaceutical packaging engineers, and resin sourcing directors combined with HM Revenue and Customs enforcement documentation, Food Standards Agency certification timelines, and Environment Agency extended producer responsibility frameworks. Bottom-up volume triangulation across product type, material grade, and end-use segments validated top-down market sizing.
Segment-level modeling captured screw cap, dispensing cap, snap-fit, and tamper-evident variants across polypropylene, polyethylene, PET, and PVC material grades for beverage, pharmaceutical, food, and cosmetics end uses. CAGRs derived from regression analysis of historical volume trends, regulatory compliance cost trajectories, and brand owner procurement pattern shifts. Forecast inputs incorporated Plastic Packaging Tax threshold anticipation, aluminium substitution elasticity in premium beverages, and Scottish beverage manufacturing expansion plans.
Underlying measurement precision varies by segment; pharmaceutical and food-contact certified closures carry tighter precision than commodity beverage supply given certification documentation availability. Forecasts reflect assumptions about regulatory enforcement consistency, resin price volatility persistence, and brand owner sustainability commitment durability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Vented Caps Market
Caps and Closures
Ribbed Closures Market
Caps and Closures
Twist Dispensing Closures Market
Caps and Closures
Flat Valve Caps and Closures Market
Caps and Closures
Italy Plastic Caps and Closures Market
Caps and Closures
South Africa Plastic Caps and Closures Market
Caps and Closures
Handheld Induction Cap Sealers Market
Caps and Closures
Ring Pull Caps Market
Caps and Closures
Egypt Plastic Caps and Closures Market
Caps and Closures
Snap-On Closures Market
Caps and Closures
Drum Plugs Market
Caps and Closures
IBC Caps Market
Caps and Closures
Child Resistant Dropper Caps Market
Caps and Closures
Steel Ring Pull Caps Market
Caps and Closures
Polypropylene Screw Caps Market
Caps and Closures
Nordic Plastic Caps and Closures Market