
 Spain Plastic Cap and Closure Market | 2026-2036
Spain Plastic Cap and Closure Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Plastic Cap and Closure Market Insights
Portugal's Iberian packaging corridor is reshaping supply dynamics for Spanish converters. BERICAP Holding GmbH leverages its Portuguese manufacturing base to serve cross-border beverage accounts. AptarGroup Inc sustains R&D intensity in dispensing systems for Iberian cosmetics brands. Guala Closures S.p.A anchors premium spirits closure supply through its specialized tamper-evident designs.
Spain plastic caps and closures are injection-molded or compression-molded thermoplastic sealing devices, typically manufactured from polyolefins with specified thread profiles and torque-release mechanisms, designed to ensure product containment, shelf-life extension, and consumer safety across liquid and semi-solid packaged goods. Polypropylene formulations dominate beverage applications due to thermal stability and recyclability alignment with EU packaging targets. Screw caps retain volume leadership in bottled water and edible oils, while dispensing caps capture margin pools in pharmaceutical and personal care segments where precision dosing commands premium positioning.
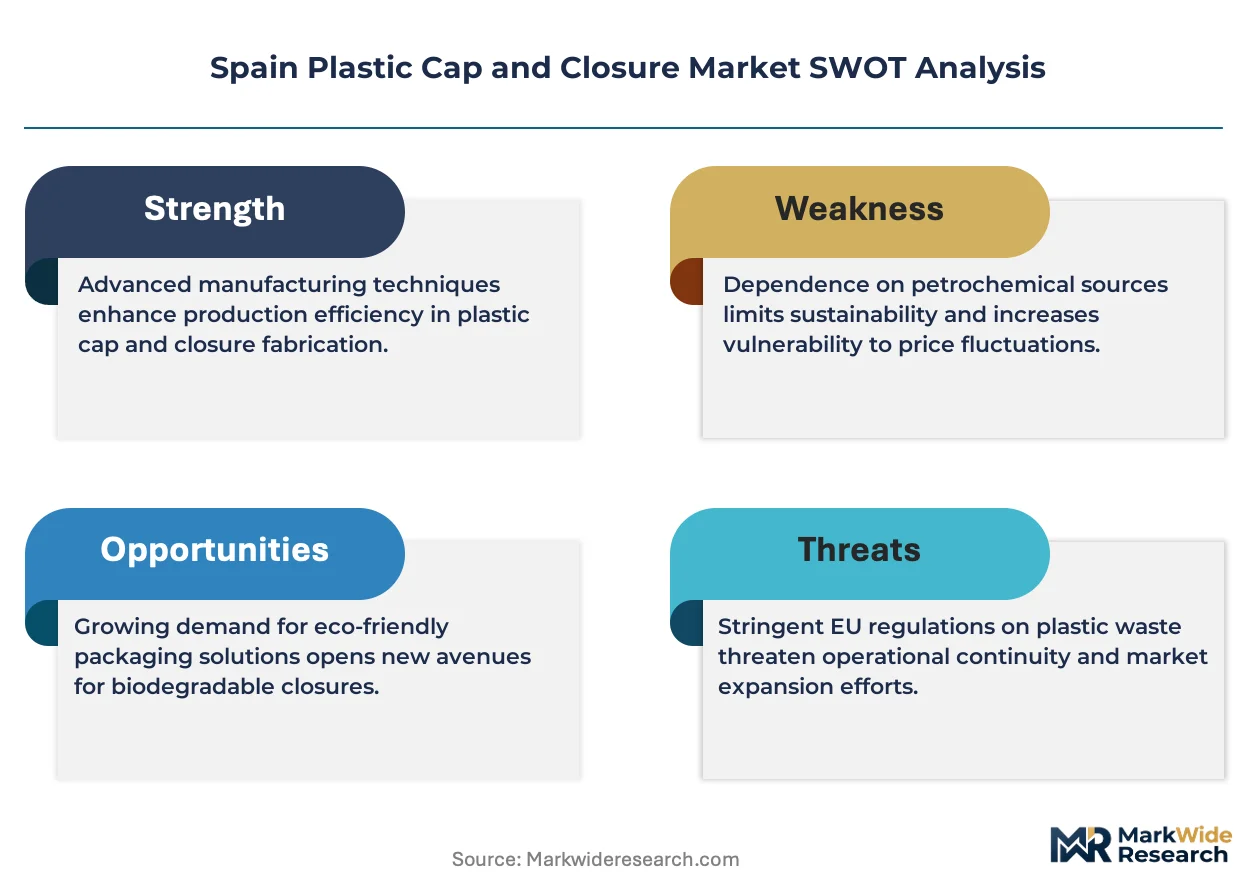
Spain's Ministry for the Ecological Transition enforces extended producer responsibility frameworks that mandate recycled content thresholds in plastic packaging, directly shaping resin procurement strategies for domestic molders. BIS-equivalent Spanish standardization bodies and EU REACH compliance requirements govern material migration limits and food-contact safety certifications. Stakeholders must monitor pending revisions to Spain's Packaging and Packaging Waste Regulation implementation, as stricter recycling quotas will determine which material technologies retain market access across Iberian supply chains.
Market Dynamics
Spain's plastic cap and closure sector confronts a structural compression between EU-mandated recycled content thresholds and the technical limitations of rPET in high-torque applications, forcing molders to reengineer resin formulations and thread geometries simultaneously.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandatory recycled content floors in beverage packaging accelerate rPET-capable closure development, with Spanish bottlers retrofitting filling lines to handle lighter-weight designs.
- Catalonia's packaging cluster:Concentrated converter capacity around Barcelona enables rapid prototyping for export-oriented cosmetics brands seeking tamper-evident dispensing solutions.
- Compression molding advancement:Reduced cycle times and material waste in high-volume beverage applications support polypropylene retention against alternative substrates.
Market Restraints
- rPET feedstock volatility:Post-consumer bale quality inconsistency from Spanish municipal collection systems elevates resin purification costs and batch rejection rates.
- Iberian supply concentration:Portuguese-owned manufacturing bases control cross-border logistics corridors, creating dependency risks for Spanish distributors during peak seasonal demand.
- REACH migration limits:Stricter ECHA thresholds for food-contact substances restrict additive packages that previously enabled high-clarity polypropylene in premium spirits closures.
Strategic Opportunities
- Andalusia agricultural chemicals:Underpenetrated agrochemical dispensing closure demand from olive oil and vineyard protection products offers specialty tamper-evident volume.
- Bio-based polypropylene:Mass balance certification schemes under EU Green Deal frameworks allow premium positioning in organic food and natural cosmetics channels.
- Direct-to-brand digital sampling:Virtual prototyping platforms collapse development cycles for Barcelona-headquartered cosmetics houses seeking rapid closure customization.
Industry Challenges
- Migration testing bottlenecks:EFSA notification queues for novel food-contact substances extend certification timelines, delaying rPET blend approvals.
- Retrofitting capex burdens:Existing injection molding lines require substantial modification to process post-industrial recycled streams without torque consistency degradation.
- Thread standard harmonization:Divergent neck finish specifications between Iberian beverage brands and Northern European export markets complicate inventory pooling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Plastic Cap and Closure Market |
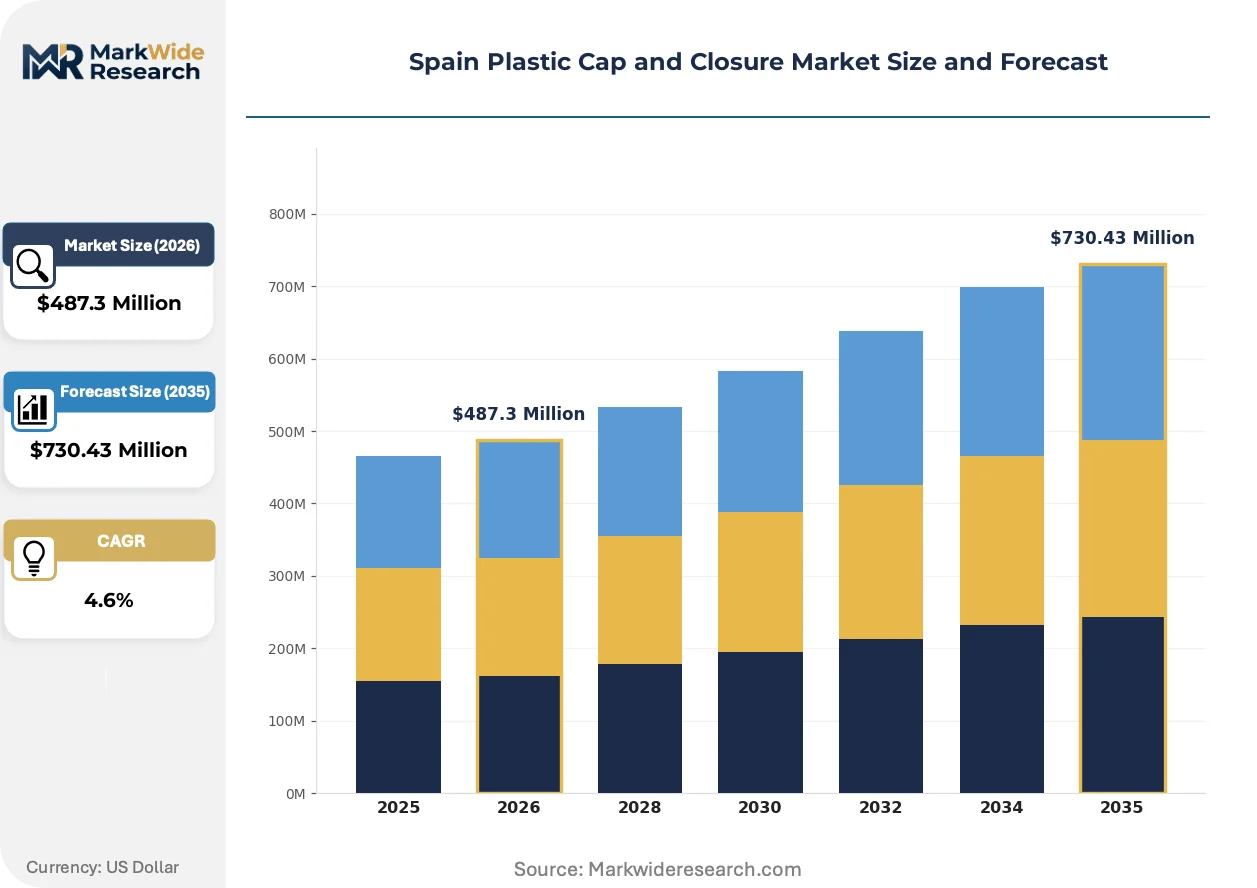
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $730.43 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screw Caps, Snap-On Caps, Push-Pull Caps, Dispensing Caps Material: Polyethylene, Polypropylene, Polystyrene, PET End User: Food & Beverage, Pharmaceuticals, Cosmetics, Household Products Packaging Type: Bottles, Jars, Tubes, Cans |
| Companies Covered | Berry Global Inc, BERICAP Holding GmbH, AptarGroup Inc, UNITED CAPS LUXEMBOURG S.A., Amcor Group GmbH, Silgan Holdings Inc, Guala Closures S.p.A, Weener Plastics Group BV, ALPLA Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Plastic Cap and Closure Market Trends and Innovations
Active transformation in Spain's closure market centers on material substitution pressures, regulatory compliance automation, and compressed buyer-producer collaboration models that bypass traditional distribution tiers.
Mono-material polypropylene designs are collapsing multi-component assembly requirements in beverage applications. Spanish water bottlers accelerate adoption to satisfy EU recyclability labeling mandates. The structural consequence is margin compression for converters maintaining legacy two-piece sports cap inventories.
Spain's Packaging and Packaging Waste Regulation implementation tightens extended producer responsibility frameworks. Domestic molders face mandatory recycled content verification and modulated fee structures based on recyclability scores. Premium cosmetics segments absorb compliance costs through packaging redesign rather than price erosion.
Brand-direct technical partnerships replace distributor-mediated specification processes. Barcelona-based cosmetics houses now embed closure engineers in product development teams. This shift concentrates demand intelligence with converters possessing in-house design capabilities.
Spain Plastic Cap and Closure Market Segmentation
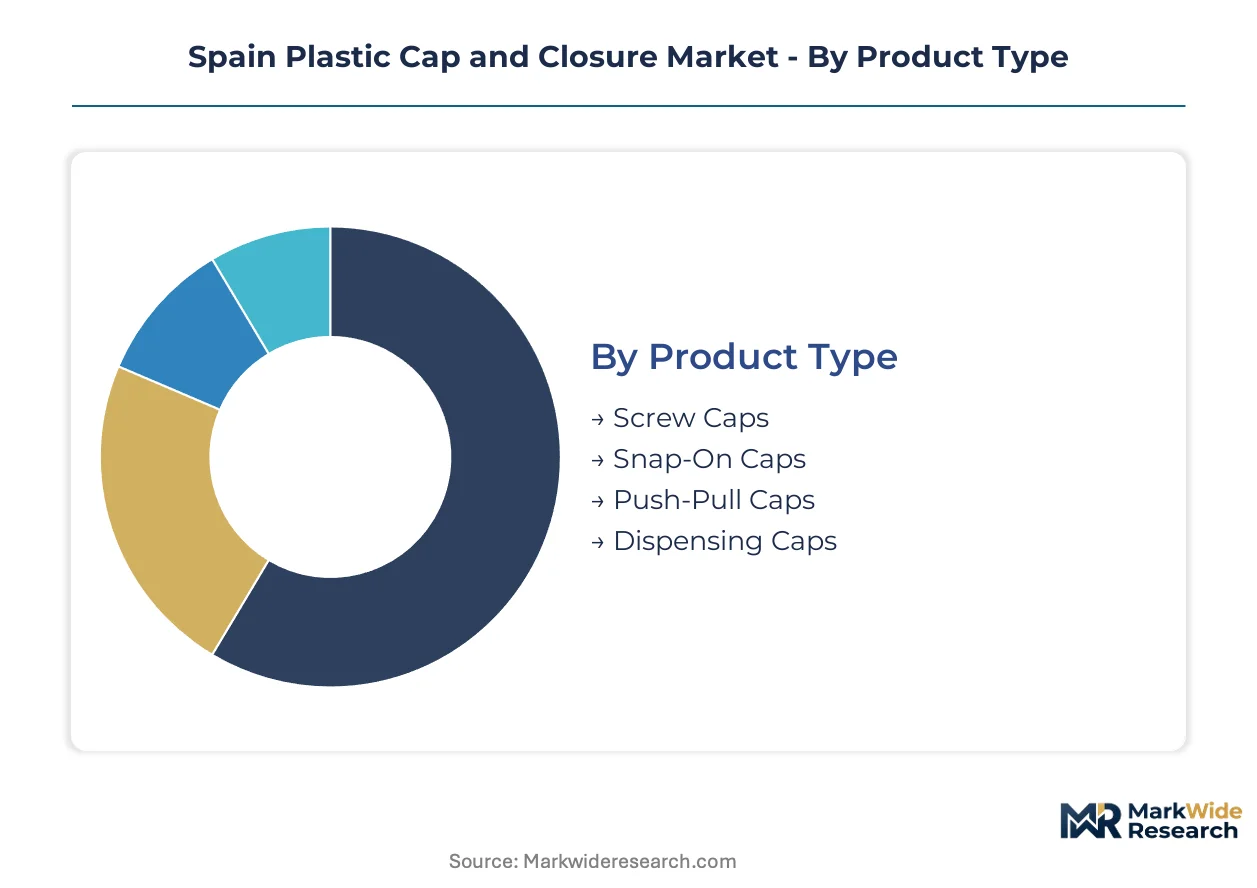
Spain's plastic cap and closure market segments along four intersecting dimensions that determine resin selection, molding technology, and regulatory compliance pathways. Each segmentation axis carries distinct margin profiles and supplier capability requirements.
Product Type:
Application mechanics dictate torque specifications, consumer interaction models, and line integration complexity across Spanish filling operations.
- Screw Caps:Threaded thermoplastic closures with standardized 28mm neck finishes dominate Spanish bottled water and edible oil packaging. Catalonia's beverage bottlers retrofit lines to accommodate lighter-weight polypropylene variants that satisfy EU recyclability mandates.
- Dispensing Caps:Precision-engineered pump and flip-top mechanisms command premium positioning in Barcelona-headquartered cosmetics brands. Technical partnerships between converters and brand R&D teams compress development cycles for tamper-evident designs.
- Snap-On Caps:Friction-fit closures serve low-torque applications in dairy and ready-to-drink beverages where resealability remains secondary to cost efficiency.
- Push-Pull Caps:Single-motion dispensing mechanisms capture sports nutrition and functional beverage segments requiring one-handed consumption.
Screw caps command the established base. The steepest expansion runs through dispensing caps.
Material:
Polymer selection balances thermal performance, migration compliance, and recycled content eligibility under Spain's extended producer responsibility framework.
- Polypropylene:Semi-crystalline thermoplastic with superior thermal stability and established recycling streams dominates Spanish beverage applications. Compression molding advances reduce cycle times while maintaining torque consistency in high-volume water bottling.
- PET:Post-consumer recycled grades face technical limitations in high-torque thread applications, forcing molders to reengineer formulations for EU-mandated content floors. EFSA notification queues delay novel blend approvals.
- Polyethylene:Linear low-density formulations serve flexible tube closures and squeeze-bottle applications in household products where ductility outweighs rigidity requirements.
- Polystyrene:Crystal and high-impact grades retain niche positioning in pharmaceutical vial seals where clarity and sterilization compatibility prove critical.
Polypropylene anchors volume leadership. PET faces the most acute technical transition pressure.
End User:
Customer industry determines regulatory stringency, batch size economics, and specification customization depth.
- Food & Beverage:Spain's largest demand concentration spans water, edible oils, and dairy applications where ECHA migration limits and EU Single-Use Plastics Directive compliance reshape procurement.
- Cosmetics:Barcelona's export-oriented beauty brands drive tamper-evident dispensing innovation through embedded converter partnerships that bypass traditional distribution tiers.
- Pharmaceuticals:Child-resistant and senior-friendly closure standards govern Madrid and Barcelona manufacturing clusters serving domestic and export markets.
- Household Products:Agrochemical and cleaning applications in Andalusia generate specialty demand for chemical-resistant thread designs.
Food and beverage retains volume dominance. Cosmetics generates the highest margin capture.
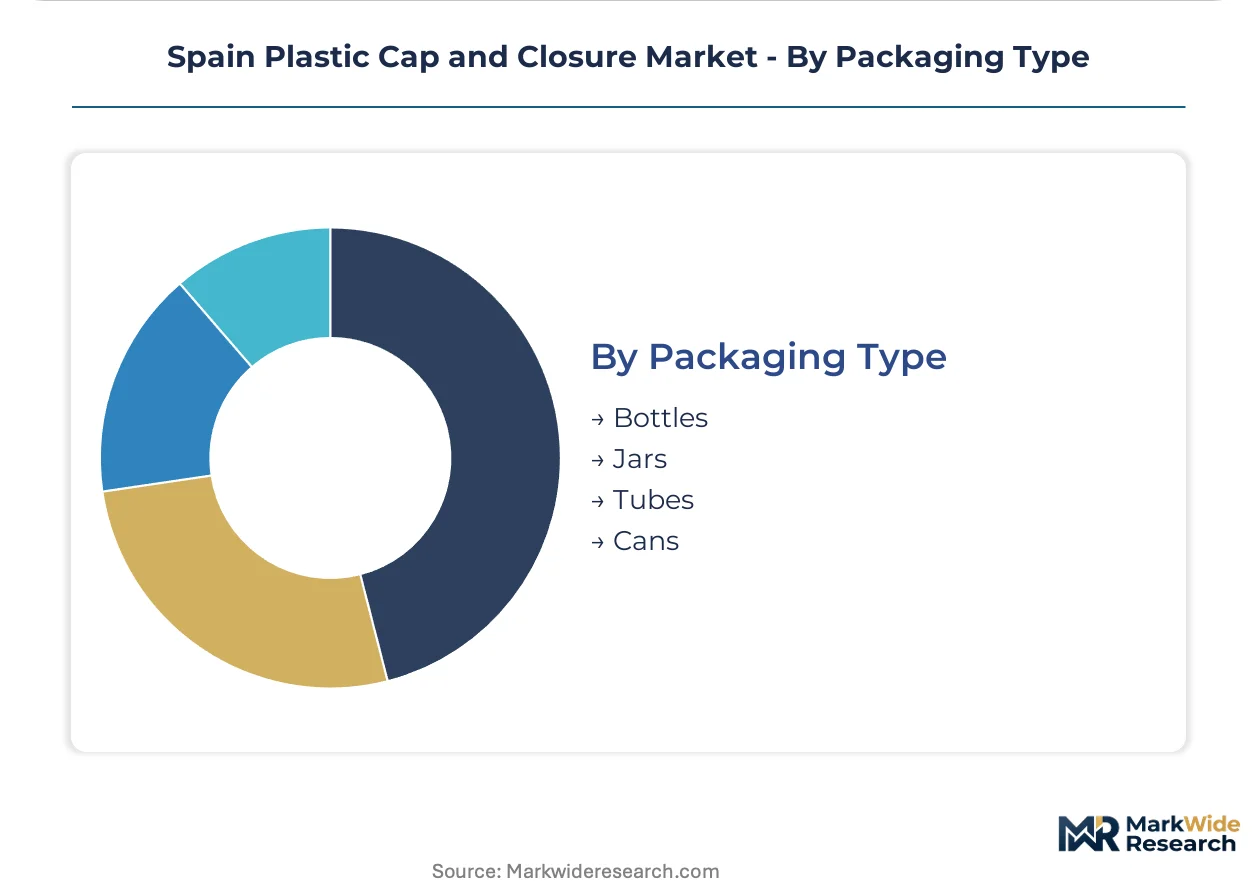
Packaging Type:
Container geometry dictates closure diameter ranges, thread pitch standards, and capping head compatibility across Iberian conversion lines.
- Bottles:PET and HDPE containers from 100ml to 5 liters generate standardized neck finish demand that supports inventory pooling across Spanish bottlers.
- Jars:Wide-mouth containers for spreads and cosmetics require specialized lug or continuous thread designs with enhanced shelf-stability seals.
- Tubes:Laminated and extruded plastic tubes for personal care demand flip-top and stand-up cap configurations with precise orifice control.
- Cans:Aerosol and specialty beverage cans integrate plastic overcaps and dispensing actuators with metal valve compatibility requirements.
Bottle closures represent the volume core. Tube dispensing systems climb fastest on cosmetics demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter capacity clusters along Spain's Mediterranean corridor, with cross-border supply relationships extending into Portugal's industrial zones. Catalonia's packaging ecosystem dominates technical development, while Madrid anchors regulatory compliance infrastructure.
Catalonia
Barcelona's packaging cluster generates concentrated demand for tamper-evident dispensing closures from export-oriented cosmetics brands. ECHA REACH migration limits govern material selection for food-contact applications. Conversion lines in Terrassa and Sant Boi de Llobregat serve pan-European beverage accounts with lightweight screw cap designs.
Madrid
Central government procurement and pharmaceutical manufacturing drive child-resistant closure specifications for domestic and export markets. Spain's Ministry for the Ecological Transition enforces extended producer responsibility frameworks from its Madrid headquarters. Packaging distributors in the capital region coordinate inventory pooling for Iberian bottlers.
Basque Country
Advanced manufacturing heritage supports precision molding equipment suppliers serving closure converters nationwide. EU Green Deal mass balance certification schemes attract bio-based polypropylene pilot programs. Bilbao's port infrastructure handles rPET feedstock imports for northern Spanish molders.
Andalusia
Olive oil and vineyard protection products generate underpenetrated demand for agrochemical dispensing closures with chemical-resistant thread designs. Andalusian regional development programs incentivize packaging supplier localization. Seville and Málaga conversion facilities serve southern European export routes.
Valencia
Citrus juice processing and horchata bottling sustain regional demand for 28mm neck finish standardization. Port logistics connect Valencian converters to North African export markets. Local molders retrofit injection lines for post-industrial recycled stream processing.
Spain Plastic Cap and Closure Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in material and tooling supply. The Spanish market exhibits moderate consolidation, with pan-European packaging groups holding volume positions alongside regional specialists focused on premium dispensing applications. Three archetypes dominate: diversified packaging conglomerates with Iberian manufacturing footprints, closure-focused specialists leveraging Catalonia's technical ecosystem, and cross-border Portuguese operators serving Spanish beverage accounts. Competitive dynamics center on M&A-driven portfolio expansion into sustainable materials and strategic partnerships with Barcelona-headquartered cosmetics brands for embedded design services.
Among German-origin industrial groups, BERICAP Holding GmbH exemplifies the cross-border manufacturing archetype, while Berry Global Inc and AptarGroup Inc represent North American diversified packaging platforms with European closure operations. Guala Closures S.p.A anchors Italian-origin premium spirits closure supply through specialized tamper-evident expertise. These operators occupy positions across the premium-to-mass-market spectrum without vertical integration into resin production.
| Leading Market Players |
|---|
| Berry Global Inc |
| BERICAP Holding GmbH |
| AptarGroup Inc |
| UNITED CAPS LUXEMBOURG S.A. |
| Amcor Group GmbH |
| Silgan Holdings Inc |
| Guala Closures S.p.A |
| Weener Plastics Group BV |
| ALPLA Group |
| Others |
Pricing and Supply Chain Analysis
The Barcelona-Port freight corridor channels polypropylene resin shipments from Portuguese and northwestern European petrochemical hubs into Catalonia's packaging cluster, with its cost volatility directly amplifying margin pressure on converters while enabling price differentiation between rPET-compliant premium tiers and standard polypropylene offerings.
Pricing Analysis
Spain's Packaging and Packaging Waste Regulation dictates the pricing tier structure across the Spanish plastic cap and closure market, separating mass-market beverage closures from certified rPET and bio-based alternatives. Price differentiation hinges on EU Green Deal mass balance certification and volume scale, with premium cosmetics brands absorbing compliance costs through packaging redesign. Cost compression in standard polypropylene segments is intensifying due to Iberian feedstock competition, while agrochemical dispensing applications in Andalusia prove least price-sensitive due to specialized thread engineering requirements.
Supply Chain Analysis
Polypropylene pellet supply draws from petrochemical complexes in Belgium, the Netherlands, and Germany, with rPET feedstock sourcing from Spanish municipal collection systems and Portuguese recycling infrastructure. Raw material dependencies center on propylene monomer, post-consumer bale streams, and specialized additive packages for migration compliance. Single-source vulnerability concentrates in Catalonia's converter cluster around Barcelona, where distribution runs through pan-European packaging distributors and direct-to-brand technical partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Spanish plastic cap and closure market functions as a defensive-moat industry where EU regulatory entrenchment creates substantial switching costs for beverage bottlers and cosmetics brands seeking EFSA-compliant closure supply.
For Market Incumbents: Pre-empt rPET-capable capacity constraints by retrofitting Terrassa and Sant Boi de Llobregat conversion lines for post-industrial recycled stream processing before EFSA notification queues clear. Anchor backward integration into Portuguese resin supply corridors to neutralize Iberian cross-border logistics dependency risks during peak seasonal demand.
For New Entrants and Emerging Players: Establish a beachhead in Andalusia's underpenetrated agrochemical dispensing closure segment, where olive oil and vineyard protection products generate specialty tamper-evident volume with limited incumbent presence. Pursue direct technical partnerships with Barcelona-headquartered cosmetics houses seeking rapid closure customization through embedded design services.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified European packaging conglomerates seeking to divest non-core closure operations amid portfolio rationalization pressures. Long-term viability favors converters with in-house mass balance certification capabilities and Catalonia-based technical development infrastructure. Monitor EFSA rPET blend approval timelines as the critical inflection signal for recycled content compliance economics.
| Strategic Initiative | Industry Significance |
|---|---|
| rPET-Capable Line Retrofit | Enables compliance with Spain's Packaging and Packaging Waste Regulation recycled content mandates. |
| Mass Balance Certification Investment | Unlocks premium positioning in EU Green Deal-aligned organic food and natural cosmetics channels. |
| Direct-to-Brand Technical Partnership | Bypasses distributor tiers for Barcelona cosmetics houses requiring rapid tamper-evident prototyping. |
| Andalusian Agrochemical Dispensing Expansion | Captures specialty volume from olive oil and vineyard protection product applications. |
| Portuguese Cross-Border Logistics Integration | Neutralizes Iberian supply concentration risks through BERICAP-style corridor control. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant managers at Catalonia-based converters, procurement leads at Iberian beverage bottlers, technical R&D directors at dispensing system specialists, and regulatory affairs officers at EFSA-notified bodies; alongside secondary validation through EU REACH registration databases, Spanish Ministry for the Ecological Transition policy filings, ECHA migration limit guidance documents, and pan-European packaging trade association statistics. Bottom-up volume estimates from individual converter capacity and top-down demand modeling from end-use industry consumption patterns underwent iterative triangulation.
Forecast inputs considered product type segmentation across screw, dispensing, snap-on, and push-pull mechanisms; material trajectories for polypropylene, rPET, polyethylene, and polystyrene; end-use industry dynamics spanning food and beverage, cosmetics, pharmaceuticals, and household products; and packaging type configurations from bottles through tubes. CAGRs were derived from regression analysis against historical volume trends and regulatory compliance cost curves, with specific weighting for EFSA notification queue durations and EU Single-Use Plastics Directive implementation timelines across the projection horizon.
Macroeconomic conditions sit as an overlay; deviation in propylene feedstock pricing, Iberian logistics capacity utilization, or euro-zone manufacturing sentiment would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and rPET feedstock quality stabilization. Cross-checking against ECHA substance volume tracking data and Spanish packaging waste registry statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Gamma Seal Lids Market
Caps and Closures
PCR Closures Market
Caps and Closures
Sport Caps and Closures Market
Caps and Closures
PET Dome Lids Market
Caps and Closures
Crimp-On Spouts Market
Caps and Closures
Laminated Tube Closure Market
Caps and Closures
Peelable Lid Stock Market
Caps and Closures
Nordic Plastic Caps and Closures Market
Caps and Closures
Caps and Closures Market
Caps and Closures
Lined Lug Caps Market
Caps and Closures
Cap Seals Market
Caps and Closures
Snap Cap Vials Market
Caps and Closures
Bar Top Corks Market
Caps and Closures
Tear-Tab Lids Market
Caps and Closures
Dauber Caps Market
Caps and Closures
Crown Caps Market