
 Gable Top Cap and Closures Market | 2026-2036
Gable Top Cap and Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Gable Top Cap and Closures Market Foresight
Direct procurement between closure suppliers and dairy cooperatives is rewriting traditional distributor relationships in the gable top packaging channel. Tetra Pak International S.A. leverages its integrated filling-equipment ecosystem to lock in multi-year closure supply contracts. SIG Combibloc Group AG anchors its position through precision-molded high-density polyethylene caps engineered for aseptic filling speeds. Elopak AS differentiates via aluminum-cap portfolios targeting organic dairy brands with premium positioning.
Gable top caps and closures are precision-engineered dispensing and sealing devices, typically injection-molded from polyethylene or polypropylene resins with thread geometries measured in millimeter tolerances, designed to maintain product integrity across refrigerated supply chains for liquid cartons. Their primary purpose is to enable resealable consumer access while preserving shelf stability for perishable fluids. Plastic caps dominate volume throughput in the milk and dairy application due to cost efficiency at billion-unit dairy industry scale. Snap-on formats represent the fastest-growing product type as beverage manufacturers seek reduced plastic content without sacrificing opening torque performance. Biodegradable resin materials command premium positioning but remain supply-constrained, concentrating margin pools with early-stage compounders.
FDA food-contact substance regulations and EU REACH chemical safety frameworks govern resin composition and migration limits for polyethylene and polypropylene closures in dairy and beverage contact. Germany's national packaging ordinance, aligned with EU Circular Economy Action Plan mandates, shapes recyclability design requirements and extended producer fee structures. China's GB standards for food packaging materials impose additional testing protocols on exporters serving Greatview Aseptic Packaging's domestic supply base. Stakeholders must monitor evolving extended producer responsibility schemes and bio-based certification standards to align material roadmaps with compliance timelines.
Market Dynamics
Material substitution pressure from the EU Single-Use Plastics Directive is forcing closure manufacturers to requalify resin formulations while maintaining thread tolerances and torque performance for high-speed filling lines. Dairy cooperatives in Germany and beverage processors across North America are simultaneously demanding tamper-evident formats and bio-based compatibility, compressing supplier development cycles.
Growth Catalysts
- Tamper-Evident Mandates:North American beverage manufacturers are expanding orders for tamper-evident closure systems to meet retailer security requirements and consumer safety expectations.
- REACH Chemical Frameworks:EU REACH migration limits for polyethylene and polypropylene are accelerating investment in compliant resin purification and testing infrastructure.
- Snap-On Format Adoption:Reduced-plastic snap-on caps are displacing threaded formats in private-label dairy segments where opening torque specifications have relaxed.
Market Restraints
- Bio-Based Resin Supply Scarcity:Early-stage compounders cannot match billion-unit dairy industry scale, concentrating margin pools and creating allocation risk.
- Millimeter Tolerance Requirements:Thread geometry precision for aseptic filling speeds limits supplier qualification to molders with multi-cavity hot-runner expertise.
- Extended Producer Fee Structures:Germany's packaging ordinance imposes circular economy compliance costs that disadvantage smaller closure suppliers without integrated recycling partnerships.
Strategic Opportunities
- Organic Dairy Premium Positioning:Aluminum-cap portfolios targeting certified organic brands command price premiums and longer contract terms.
- China GB Standard Export Pathway:Exporters serving Greatview Aseptic Packaging's domestic supply base can capture volume through additional testing protocol compliance.
- Retrofit Filling Line Integration:Dairy cooperatives in Germany are retrofitting legacy equipment with compatible screw-cap formats, creating captive demand for precision-molded systems.
Industry Challenges
- Multi-Cavity Hot-Runner Engineering Talent:Mold flow simulation and cavity balancing expertise is concentrated among aging specialists in European tooling clusters.
- Legacy Equipment Integration Friction:Retrofitting 1990s-era gable top formers with modern closure application stations requires custom mechanical adaptation and control system upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gable Top Cap and Closures Market |
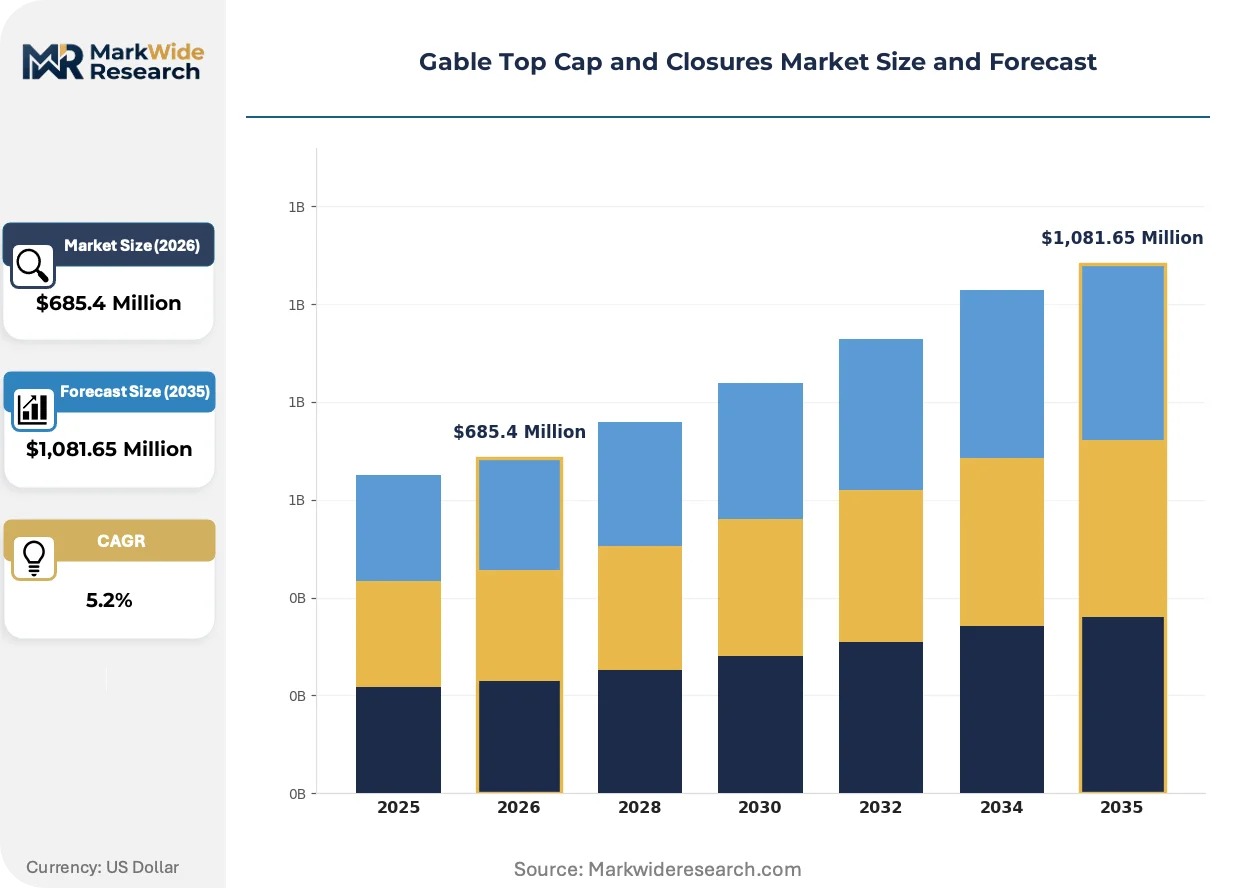
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,081.65 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Caps, Aluminum Caps, Screw Caps, Snap-on Caps, Flip-top Caps Material: Polyethylene, Polypropylene, High-Density Polyethylene, Biodegradable Resin, Metal Alloys Application: Milk & Dairy, Beverage, Edible Oils, Liquid Detergents, Household Chemicals End User: Dairy Producers, Beverage Manufacturers, Food Processors, Chemical Suppliers, Household Goods Producers |
| Companies Covered | Tetra Pak International S.A., SIG Combibloc Group AG, Evergreen Packaging LLC, Elopak AS, International Paper Company, Greatview Aseptic Packaging, IPI, Bericap GmbH & Co. KG, Silgan Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gable Top Cap and Closures Market Shifts & Advancements
Closure material science is converging with regulatory chemistry and filling-line automation, producing formats that must simultaneously satisfy migration limits, torque specifications, and high-speed application reliability. The technical frontier centers on reconciling bio-based content claims with performance parity.
Biodegradable resin formulations are hybridizing conventional polyethylene thread geometries with polylactic acid blends to maintain seal integrity while enabling compostability claims. German dairy cooperatives are piloting these formats at reduced line speeds to validate torque retention over refrigerated shelf life. The structural consequence is a bifurcation between performance-certified bio-hybrids and commodity fossil-based caps.
EU REACH chemical safety frameworks are tightening migration limit enforcement for food-contact polyolefins, forcing compounders to document additive packages and impurity profiles. Closure suppliers serving European dairy brands must now maintain dual resin inventories: REACH-compliant grades for EU-bound volume and standard grades for other markets. Aseptic filling applications face the steepest requalification burden due to elevated temperature exposure during sterilization.
Direct procurement contracts between closure suppliers and dairy cooperatives are displacing traditional distributor relationships in the gable top channel. Beverage manufacturers are consolidating supplier panels to capture volume pricing and technical service integration. This concentration is most visible in Germany, where retrofit filling line projects require embedded engineering support that distributors cannot provide.
Gable Top Cap and Closures Market Segmentation
Gable top cap purchasing cycles vary dramatically by segment, with beverage manufacturers rotating closure specifications quarterly while dairy cooperatives lock in multi-year resin contracts. Understanding these velocity differences enables suppliers to align inventory and technical service resources against predictable demand patterns.
Product Type:
Cycle times range from rapid SKU turnover in beverage applications to decade-long specification locks in dairy infrastructure, reshaping how molders prioritize cavity investments.
- Plastic Caps:Injection-molded polyethylene and polypropylene closures dominate billion-unit dairy throughput with cost efficiency at scale. German dairy cooperatives specify these for retrofit filling lines, though EU Single-Use Plastics Directive compliance costs are compressing margins for non-specialized molders.
- Snap-on Caps:Reduced-plastic formats with optimized opening torque profiles are displacing threaded alternatives in private-label segments. Beverage manufacturers across North America are expanding orders fastest here, prioritizing tamper-evident functionality without screw-thread complexity.
- Screw Caps:Precision-threaded formats maintain seal integrity across refrigerated supply chains for extended-shelf-life dairy.
- Aluminum Caps:Premium-positioned closures targeting organic dairy brands with extended contract terms and price premiums.
- Flip-top Caps:Consumer-convenience formats concentrated in single-serve beverage and on-the-go dairy applications.
Plastic caps dominate installed base. Snap-on formats are where expansion concentrates.
Material:
Cost tiers stratify sharply between commodity polyolefins and certified bio-based grades, with qualification timelines creating captive relationships between compounders and closure specialists.
- Polyethylene:Standard-grade resin for high-volume dairy applications with established FDA food-contact and EU REACH migration compliance. Dairy producers in Germany and North America maintain dual inventories to satisfy divergent regulatory requirements.
- Biodegradable Resin:Polylactic acid blends hybridized with conventional polyethylene thread geometries enable compostability claims while preserving seal integrity. Early-stage compounders cannot match billion-unit dairy scale, concentrating margin pools and creating allocation risk for buyers.
- Polypropylene:Higher thermal stability suits aseptic filling applications with elevated sterilization temperatures.
- High-Density Polyethylene:Stiffness-optimized grades for precision-molded screw-cap formats at high-speed filling velocities.
- Metal Alloys:Aluminum and steel substrates for premium organic dairy positioning and extended shelf-life barrier performance.
Polyethylene dominates installed base. Biodegradable resin is where expansion concentrates.
Application:
Volume concentration in dairy contrasts with margin opportunity in chemical and specialty beverage segments, redirecting technical sales force deployment.
- Milk & Dairy:Perishable fluid applications demanding resealable consumer access with refrigerated supply chain integrity. German dairy cooperatives are retrofitting filling lines with compatible screw-cap formats, creating captive demand for precision-molded systems.
- Beverage:Diverse format requirements spanning juice, ready-to-drink, and functional beverages with aggressive tamper-evident mandates. North American beverage manufacturers are consolidating supplier panels to capture volume pricing and embedded engineering support.
- Edible Oils:Oxygen-sensitive applications requiring enhanced barrier properties and pour-control functionality.
- Liquid Detergents:Chemical resistance specifications and child-safety closure requirements distinct from food-contact grades.
- Household Chemicals:Regulatory compliance with EPA and REACH chemical safety frameworks for non-food contact applications.
Milk and dairy dominate installed base. Beverage is where expansion concentrates.
End User:
Customer type determines procurement sophistication, with direct supplier relationships displacing traditional distributor channels among technical buyers.
- Dairy Producers:Cooperative and proprietary processors specifying thread tolerances measured in millimeters for high-speed aseptic lines. Direct procurement contracts are rewriting traditional distributor relationships in the gable top channel.
- Beverage Manufacturers:Brand owners and contract packagers demanding tamper-evident systems and bio-based compatibility simultaneously. These buyers are compressing supplier development cycles with dual requirements.
- Food Processors:Diverse application needs spanning sauces, broths, and prepared foods with distinct viscosity and shelf-stability requirements.
- Chemical Suppliers:Industrial and institutional buyers prioritizing chemical resistance and regulatory documentation over consumer convenience features.
- Household Goods Producers:Brand owners balancing child-safety mandates with ergonomic adult opening torque specifications.
Dairy producers dominate installed base. Beverage manufacturers are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany where retrofit filling line demand outstrips precision-molding capacity, while Chinese suppliers compete on volume through Greatview Aseptic Packaging's domestic supply base. This asymmetry redirects procurement decisions toward captive engineering relationships in Western Europe.
Germany
Dairy cooperatives in Lower Saxony and Bavaria are retrofitting legacy filling equipment with compatible screw-cap formats, creating sustained demand for millimeter-tolerance molders. The national packaging ordinance, aligned with EU Circular Economy Action Plan mandates, imposes extended producer fee structures that favor suppliers with integrated recycling partnerships. Stuttgart-area tooling clusters concentrate multi-cavity hot-runner expertise that younger competitors cannot replicate.
United States
Beverage manufacturers across the Midwest and Southeast are expanding orders for tamper-evident closure systems to satisfy retailer security mandates. FDA food-contact substance regulations govern resin composition and migration limits for polyethylene and polypropylene closures in dairy contact. Wisconsin and California dairy processing corridors drive volume concentration for high-throughput plastic cap specifications.
China
Greatview Aseptic Packaging's domestic supply base creates export pathways for closure suppliers compliant with GB standards for food packaging materials. The Ministry of Ecology and Environment enforces dual carbon goals that accelerate material transitions toward lower-emission resin formulations. Yangtze River Delta molding clusters serve both domestic dairy brands and multinational co-packers seeking cost-optimized volumes.
France
Organic dairy brands in Brittany and Normandy command premium positioning for aluminum-cap portfolios with extended contract terms. ANSM and EFSA frameworks govern food-contact safety documentation for bio-based resin formulations entering premium segments. Lyon-area compounders pilot polylactic acid hybrid blends to validate compostability claims at reduced line speeds.
India
Dairy cooperatives in Gujarat and Maharashtra are upgrading aseptic filling infrastructure to capture extended-shelf-life milk demand in urban corridors. FSSAI standards for food packaging materials impose testing protocols that parallel FDA and EU REACH migration limit structures. Anand and Mumbai industrial zones concentrate blow-molding capacity for domestic juice and flavored milk applications.
Gable Top Cap and Closures Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream, supplying precision-molded closures to filling-equipment ecosystems. The market structures around three tiers: integrated packaging systems houses with captive closure supply, independent closure specialists serving retrofit installations, and regional molders competing on resin cost. Strategic moves concentrate on direct procurement contract capture with dairy cooperatives and bio-based resin qualification partnerships with early-stage compounders.
Within the integrated systems tier, Tetra Pak International S.A. and SIG Combibloc Group AG exemplify platform integrators leveraging filling-equipment ecosystems to secure multi-year closure supply relationships. Elopak AS occupies a differentiated position through aluminum-cap portfolios targeting premium organic dairy positioning. Among component specialists, Bericap GmbH & Co. KG represents precision-molding expertise for high-density polyethylene formats, while Silgan Holdings Inc. anchors North American beverage manufacturer relationships through tamper-evident system supply.
| Leading Market Players |
|---|
| Tetra Pak International S.A. |
| SIG Combibloc Group AG |
| Evergreen Packaging LLC |
| Elopak AS |
| International Paper Company |
| Greatview Aseptic Packaging |
| IPI |
| Bericap GmbH & Co. KG |
| Silgan Holdings Inc. |
| Others |
Supply & Pricing Matrix
Stuttgart-area tooling clusters concentrate multi-cavity hot-runner expertise that younger competitors cannot replicate, granting incumbent molders pricing power over German dairy cooperatives retrofitting legacy filling lines. This geographic concentration of precision-molding capacity creates asymmetric leverage where qualified suppliers command premium configured-to-order pricing against standard commodity caps.
Pricing Analysis
The customization-premium spread separates precision-molded screw-cap formats for aseptic lines from commodity snap-on alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—REACH-compliant bio-based resins command top tier, FDA-grade polyethylene occupies mid-tier, and non-certified commodity polypropylene sits at base. Pricing pressure stems from EU Single-Use Plastics Directive compliance costs compressing margins for non-specialized molders. Beverage manufacturers exhibit highest price sensitivity due to quarterly SKU rotation, while dairy cooperatives accept longer-term contract premiums for embedded engineering support.
Supply Chain Analysis
Contract-manufacturing concentration rests with Bericap GmbH & Co. KG and Silgan Holdings Inc. holding precision-molding capacity for high-density polyethylene formats and tamper-evident systems respectively. Geographic supply concentration centers on Germany, China, and the United States—Stuttgart and Yangtze River Delta clusters serve precision applications, while Midwest US corridors handle high-volume dairy throughput. Raw material dependencies draw from polyethylene resin purification, polylactic acid bio-compounders, and aluminum substrate suppliers. Single-source vulnerability concentrates in early-stage biodegradable resin compounders unable to match billion-unit dairy scale. Distribution runs through direct procurement contracts displacing traditional distributor relationships, particularly for retrofit filling line projects requiring embedded technical service.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gable top cap market functions as a service-attach opportunity where technical support contracts and resin requalification services expand faster than hardware unit growth. Recurring engineering engagement for filling line integration and compliance documentation now exceeds standalone component margins.
For Market Incumbents: Harden multi-year closure supply relationships by embedding field engineering teams with dairy cooperative retrofit projects, denying competitors access to captive demand. Deepen backward integration into REACH-compliant resin purification to offset margin compression from EU Single-Use Plastics Directive compliance costs. Control channel access by displacing distributor relationships with direct procurement contracts that bundle technical service.
For New Entrants and Emerging Players: Build out biodegradable resin qualification partnerships with early-stage compounders, capturing allocation-constrained premium positioning before supply scales. Target private-label beverage segments in North America where tamper-evident snap-on formats face relaxed opening torque specifications and less entrenched supplier panels. Lead with rapid prototyping capabilities for quarterly SKU rotation cycles that incumbent molders serving dairy infrastructure cannot match.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision-molding specialists with multi-cavity hot-runner expertise over commodity resin processors. Long-term viability hinges on bio-based material transition completion and aseptic filling line retrofit saturation across German dairy cooperatives. Acquisition target archetype: independent closure specialists serving retrofit installations with embedded engineering relationships. The signal to watch is allocation risk escalation in biodegradable resin supply triggering premium pricing power for qualified compounders.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Purification | REACH compliance investment secures margin position against EU regulatory tightening. |
| Embedded Engineering Service Contracts | Technical support bundling locks in multi-year dairy cooperative relationships. |
| Bio-Based Resin Qualification Partnerships | Early compounder alliances capture premium positioning before supply scales. |
| Retrofit Filling Line Integration | Custom mechanical adaptation expertise creates captive demand in Germany. |
| Direct Procurement Channel Displacement | Distributor bypass enables volume pricing capture and technical service monetization. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and filling equipment manufacturer disclosures. Primary interviews engaged closure manufacturing executives, dairy cooperative procurement directors, beverage brand packaging engineers, and bio-based resin compounder technical leads. Secondary validation drew from FDA food-contact substance registrations, EU ECHA migration limit documentation, China GB standards for food packaging materials, and SEC filings from integrated packaging systems houses. Bottom-up demand modeling from filling line installation rates and top-down market sizing from resin consumption patterns were triangulated against each other.
Forecast inputs considered product type segmentation across plastic, snap-on, screw, aluminum, and flip-top formats; material tiers spanning polyethylene, polypropylene, biodegradable resin, and metal alloys; and application splits between milk and dairy, beverage, edible oils, and chemical segments. CAGRs were derived from regression analysis of historical filling equipment deployment rates correlated with closure consumption intensity. Industry-specific inputs included EU Single-Use Plastics Directive implementation timelines and German packaging ordinance fee structure evolution.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese molders or accelerated bio-resin supply scaling by petrochemical majors would shift outcomes. Quarterly review of REACH migration limit enforcement actions, dairy cooperative retrofit project backlogs, and biodegradable resin compounder funding rounds is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Overcaps Market
Caps and Closures
Hinged Dual Flap Caps Market
Caps and Closures
Bag Closures Market
Caps and Closures
Metal Closures Market
Caps and Closures
Case Closures and Sealers Market
Caps and Closures
US Caps and Closure Market
Caps and Closures
Drum Plugs Market
Caps and Closures
Polypropylene Screw Caps Market
Caps and Closures
Pressure Sensitive Wads Market
Caps and Closures
Pharmaceutical Caps and Closures Market
Caps and Closures
Child Resistant Pipette Closures Market
Caps and Closures
Aerosol Caps Market
Caps and Closures
Disc Top Caps Market
Caps and Closures
Lined Lug Caps Market
Caps and Closures
End Cap Market
Caps and Closures
Reverse Cap Bottles Market