
 PET Dome Lids Market | 2026-2036
PET Dome Lids Market Size, Share, and Industry Trends Forecast 2026-2036
PET Dome Lids Market Analytics
Market Context
EU Single-Use Plastics Directive enforcement is repositioning the cost-of-entry calculus for European converters, forcing investments in certified recycled content streams and expanded producer responsibility schemes. Berry Global Inc. leverages vertical integration across resin compounding and thermoforming to control feedstock quality for dome-lid output. Dart Container Corporation anchors North American manufacturing scale with multi-plant distribution networks serving quick-service chains. Amcor differentiates through R&D intensity in thin-wall PET engineering, reducing gram weight per lid while maintaining stack strength.
Technical Definition and Segment Structure
PET dome lids are thermoformed or injection-molded polyethylene terephthalate closures, typically 0.25–0.60 mm in wall thickness, engineered with peripheral stacking lugs and venting channels to maintain beverage topping integrity during transport. These components serve primarily as transparent, tamper-evident covers for cold beverages, frozen desserts, and prepared salads where product visibility drives consumer selection. Recyclable PET and post-consumer recycled PET together dominate material demand, with the latter capturing margin pools as brand owners commit to recycled content targets. Food packaging and beverage packaging applications lead volume, while insulated variants represent the fastest-growing product type as specialty coffee and smoothie chains expand cold-drink menus.
Regulatory Frame and Outlook
US FDA maintains food-contact clearance standards for virgin and recycled PET, while EPA guidelines on sustainable materials management shape state-level procurement preferences for recycled content. EFSA and EU REACH compliance requirements filter market access for non-European suppliers, particularly on additive migration limits and recycling process certification. Stakeholders must monitor evolving extended producer responsibility frameworks across multiple jurisdictions, as these programs will determine which material grades and distribution channels retain cost competitiveness.
Market Dynamics
EU Single-Use Plastics Directive enforcement is restructuring material economics for European converters, mandating certified recycled content thresholds that redirect capital toward post-consumer rPET purification and compounding infrastructure.
Growth Catalysts
- Quick-service beverage format expansion:Cold-brew and smoothie menu proliferation across North American chains is generating pull for stackable, vented dome closures that maintain topping integrity during delivery.
- REACH-compliant rPET certification:ECHA registration pathways for food-contact recycled polymers are unlocking margin pools as brand owners commit to binding recycled content targets.
- German bakery packaging standards:Deli and prepared-food retail formats in Germany favor rigid PET clarity over PP or PS alternatives, concentrating specification demand in this substrate.
Market Restraints
- Flake supply concentration:Post-consumer PET bottle collection infrastructure clusters in Western European and select US municipal systems, creating feedstock access asymmetries for converters in peripheral markets.
- Food-contact additive migration limits:EFSA and FDA clearance timelines for novel antioxidant and processing aid packages extend qualification cycles, delaying formulation pivots.
- Competing fiber applications:Textile and carpet fiber markets bid for identical rPET flake grades, compressing availability for food-packaging thermoformers during demand spikes.
Strategic Opportunities
- Insulated lid variants:Double-wall PET structures with trapped-air channels address specialty coffee and frozen-dessert chains seeking condensation control without foam substitution.
- Extended producer responsibility frameworks:Emerging EPR schemes in multiple US states and Canadian provinces create preferential access for converters with in-house recycling and closed-loop collection infrastructure.
- Digital print personalization:Direct-to-object inkjet on thermoformed lids enables limited-run promotional campaigns for beverage brands, opening short-order production economics previously uneconomical at injection-molding scale.
Industry Challenges
- Thermoforming tool complexity:Precision vent-channel and stacking-lug geometries demand multi-cavity aluminum molds with 12-16 week lead times, constraining rapid product iteration.
- Recycling process certification backlog:Third-party audit capacity for EFSA and FDA food-contact recycling certifications lags application volume, delaying market access for novel mechanical and chemical recycling technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PET Dome Lids Market |
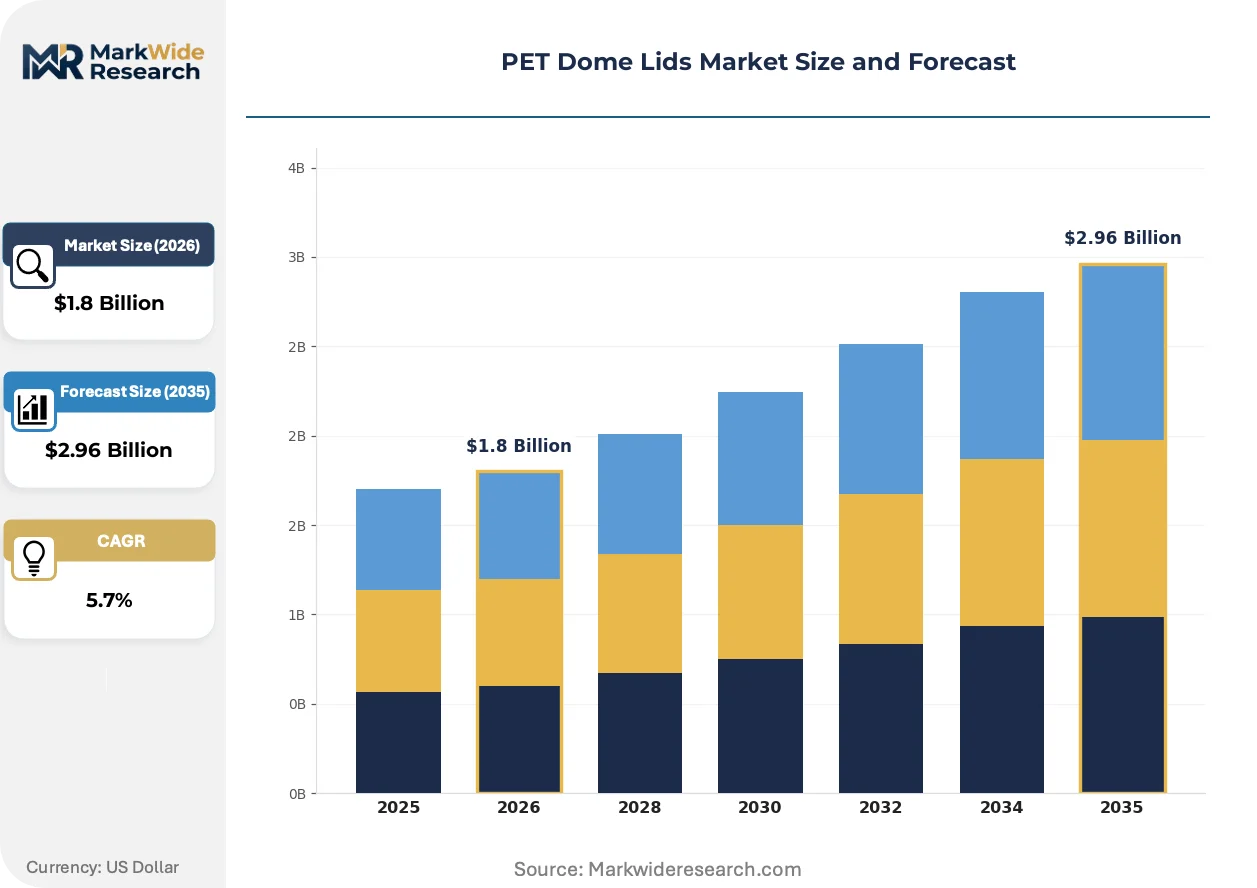
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Custom, Insulated, Disposable Material: Recyclable PET, Biodegradable PET, Post-Consumer Recycled PET, Transparent PET Application: Food Packaging, Beverage Packaging, Bakery Products, Salad Containers Distribution Channel: Online Retail, Wholesale, Supermarkets, Specialty Stores |
| Companies Covered | Berry Global Inc., Dart Container Corporation, Georgia-Pacific LLC, Amcor, Sabert Corporation, Tair Chu Enterprise, Pactiv, EcoPack Limited, MPM Marketing Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PET Dome Lids Market Evolving Landscape
Material science and regulatory compliance are converging to redefine performance specifications for transparent food-service closures, with sustainability mandates now dictating engineering priorities alongside traditional cost and functional metrics.
Thin-wall PET engineering is absorbing gram-weight reduction targets without sacrificing stack strength or snap-fit integrity. Quick-service chains and co-packing operations are adopting sub-0.35 mm wall specifications for standard cold-beverage lids. This compression is absorbing resin volume per thousand units and redirecting converter R&D toward structural ribbing and material distribution algorithms.
REACH authorization requirements for legacy plasticizers and stabilizers are accelerating additive package reformulation across European supply chains. Compounders must qualify replacement chemistries through ECHA's SVHC screening protocols before commercial deployment. Thermoformers serving German and French food retail are absorbing these compliance costs through specification premiums that brand owners increasingly accept as table stakes.
Direct-store-delivery beverage operators are consolidating procurement around single-source lid specifications that interchange across cup diameters and menu categories. This standardization is compressing SKU proliferation and favoring converters with modular thermoforming platforms capable of rapid die changeovers. The pattern is most visible in US quick-service franchise systems where corporate supply agreements override regional sourcing preferences.
PET Dome Lids Market Segmentation
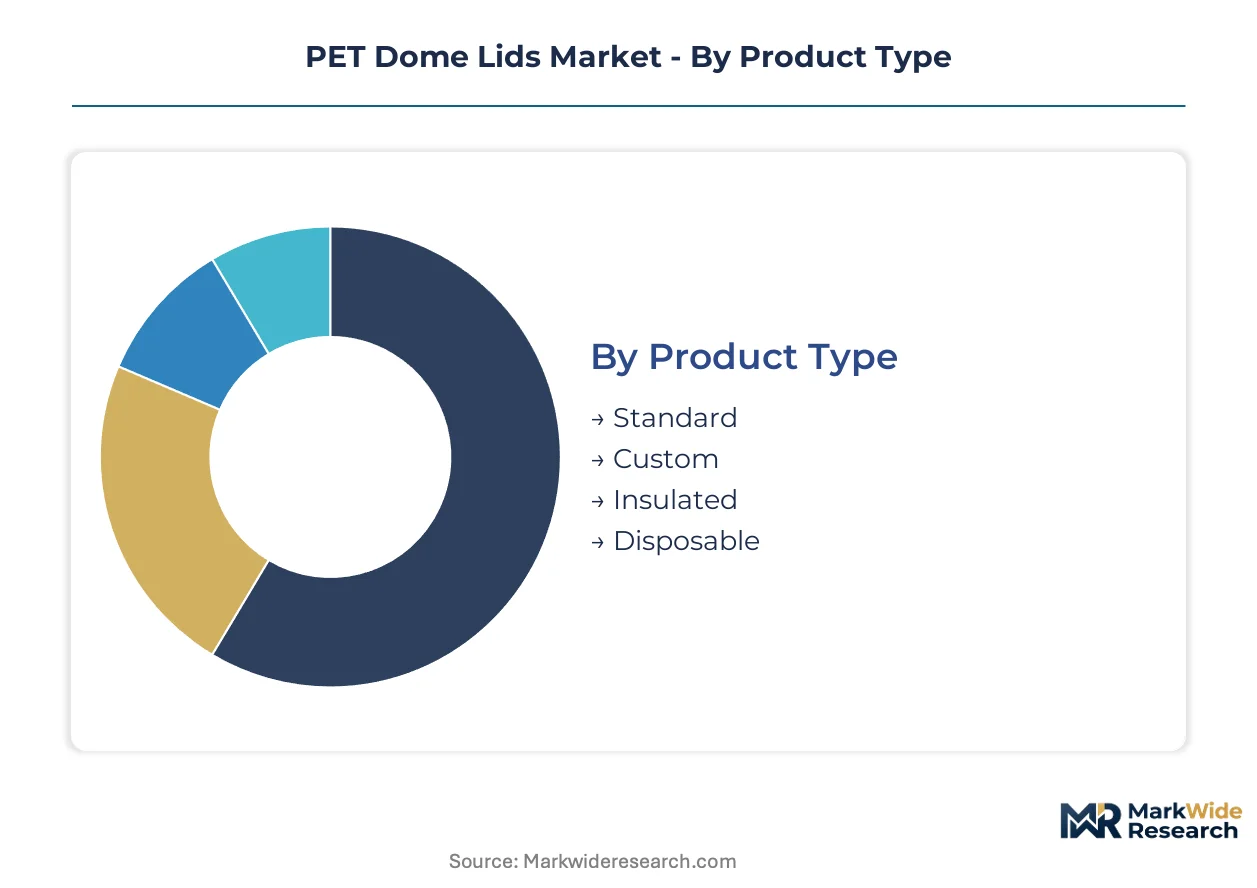
PET dome lid procurement decisions hinge on material certification tiers and application-specific performance thresholds. Converters must align segment selection with FDA or EFSA food-contact clearances and brand owner recycled content commitments.
Product Type:
FDA food-contact certification requirements vary sharply across product tiers, with insulated variants demanding extended thermal stability testing beyond standard cold-beverage specifications.
- Standard:Single-wall thermoformed lids with 0.25–0.35 mm wall thickness dominate quick-service beverage procurement. Chains in the United States specify these for cold-drink formats where cost-per-unit drives vendor selection and stacking lugs must survive automated cup-dispensing systems.
- Insulated:Double-wall structures with trapped-air channels address condensation control for specialty coffee and frozen-dessert applications. Demand concentrates in Canadian and US Pacific Northwest markets where extended transport times and humidity exposure challenge single-wall performance.
- Custom:Proprietary vent-channel geometries and embossed branding for limited promotional runs.
- Disposable:Lowest-unit-cost specifications for event catering and institutional foodservice.
Standard sits at the top of the volume ranking, with Insulated climbing the fastest.
Material:
Cost tiers separate virgin feedstock from certified recycled streams, with post-consumer rPET commanding specification premiums tied to EFSA Novel Food and FDA Letter of No Objection timelines.
- Recyclable PET:Virgin resin with established FDA and EFSA food-contact clearances remains the default for high-speed thermoforming operations. US quick-service chains specify this grade where supply contract stability outweighs sustainability messaging priorities.
- Post-Consumer Recycled PET:EFSA-certified rPET flake from European bottle-to-bottle recycling infrastructure is capturing margin pools as brand owners commit to binding recycled content targets. German retail and French foodservice specifications now mandate minimum thresholds.
- Biodegradable PET:Additive-modified formulations targeting industrial composting certifications.
- Transparent PET:Optical-grade resin for premium deli and bakery visibility requirements.
Recyclable PET retains the highest shipment volumes, while Post-Consumer Recycled PET shows the steepest expansion trajectory.
Application:
Customer type determines structural requirements, with beverage formats prioritizing venting and stackability while food applications demand broader diameter ranges and tamper-evident features.
- Beverage Packaging:Vented dome lids with peripheral stacking lugs serve cold-brew, smoothie, and carbonated drink formats. North American quick-service chains drive specification consolidation around interchangeable diameters to simplify inventory management across franchise systems.
- Food Packaging:Prepared salad and deli container closures require wider sealing surfaces and snap-fit integrity across temperature fluctuations. German supermarket chains specify rigid PET clarity for grab-and-go sections where product visibility influences purchase decisions.
- Bakery Products:Shallow-profile domes for pastry visibility and structural protection.
- Salad Containers:Deep-drawn configurations with condensation management for leafy greens.
Beverage Packaging leads in unit volume terms, with Food Packaging expanding most quickly.
Distribution Channel:
Supply concentration differs by channel, with wholesale and direct-store-delivery networks favoring long-term contract structures while online retail enables spot purchasing for smaller operators.
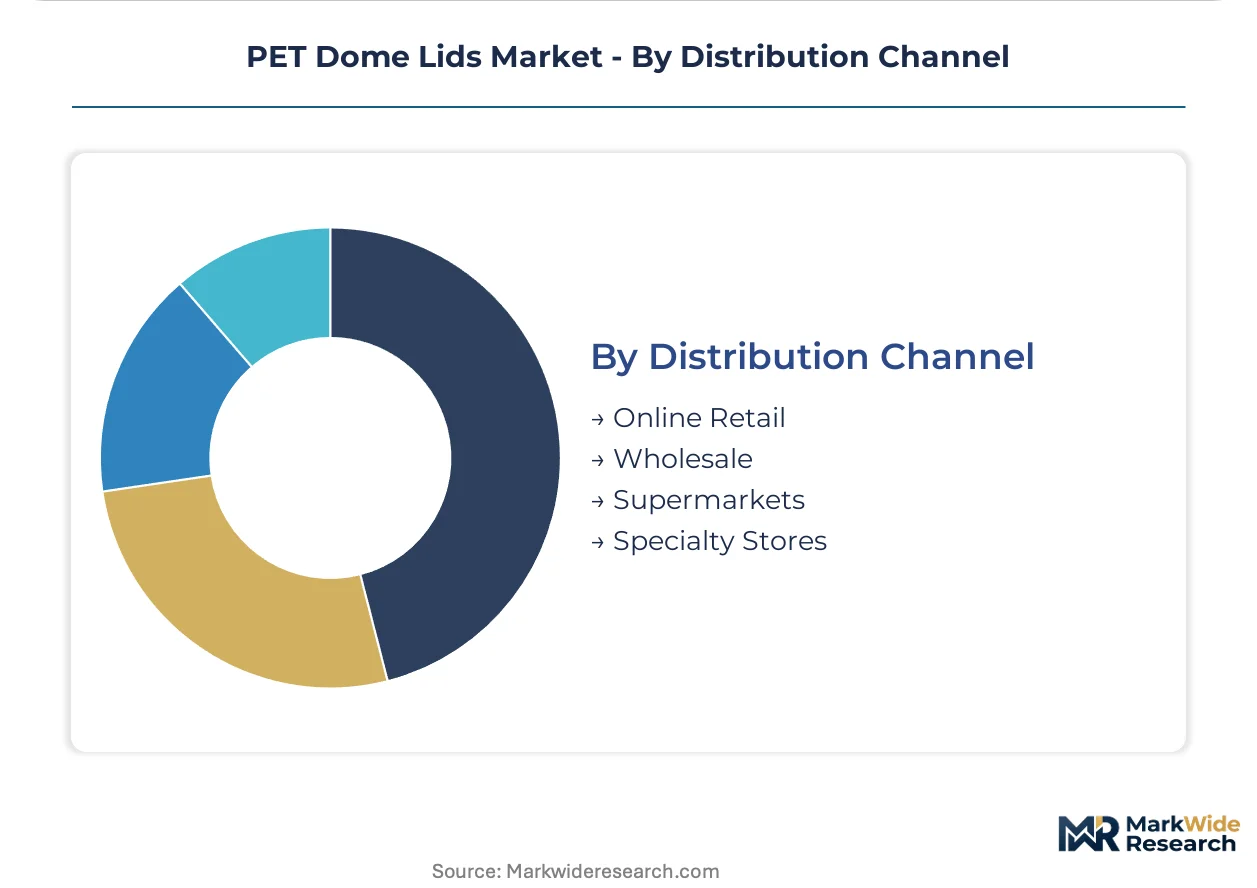
- Wholesale:Pallet-scale procurement through broadline foodservice distributors anchors volume for North American converter operations. Contracts specify annual volume commitments with price adjustment clauses tied to resin index movements.
- Supermarkets:Private-label deli and bakery specifications concentrate demand in Western European retail systems. German and French chains source through approved vendor lists with EFSA compliance documentation requirements.
- Online Retail:E-commerce platforms serving small caterers and independent cafes.
- Specialty Stores:Boutique packaging suppliers for premium and artisan food producers.
Wholesale dominates current shipment values, with Supermarkets gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thermoformed PET closures originated in North American quick-service foodservice operations during the 1970s, with the format spreading to Western Europe as cold-beverage retail formats expanded. Demand geography now tracks regulatory stringency and foodservice density rather than manufacturing cost alone.
United States
Quick-service franchise systems in the United States specify interchangeable dome-lid diameters to simplify inventory across thousands of locations. FDA food-contact clearance standards for virgin and recycled PET shape converter qualification timelines. Chicago and Dallas-Fort Worth anchor thermoforming operations serving national distribution networks.
Germany
German supermarket deli and bakery specifications mandate rigid PET clarity for grab-and-go visibility, concentrating demand in this substrate over PP or PS alternatives. EFSA compliance requirements for post-consumer recycled content filter market access for non-European suppliers. The Rhine-Ruhr corridor hosts compounding and thermoforming clusters serving French and Benelux retail systems.
China
Domestic cold-beverage chains and bubble-tea formats generate pull for stackable vented closures in tier-one cities. SAMR food-contact regulations and GB standards govern additive migration limits for imported resin systems. The Yangtze River Delta concentrates injection-molding and thermoforming capacity serving both domestic and export foodservice markets.
Japan
Convenience store chains and specialty coffee operators demand thin-wall PET engineering with precise stack-fit tolerances. METI circular economy guidelines and JIS standards shape recycled content adoption timelines. The Kanto region around Tokyo anchors precision thermoforming operations for premium beverage packaging.
Canada
Extended transport distances and humidity exposure in coastal markets drive specification for insulated double-wall lid variants. Health Canada food-contact regulations align with FDA standards while provincial extended producer responsibility frameworks emerge. Ontario and Quebec host thermoforming operations integrated with US distribution networks.
PET Dome Lids Market Competitive Landscape
The competitive structure tilts toward integrated resin-to-form converters with captive supply chains and multi-plant distribution networks. Tier-one players combine vertical resin compounding with high-cavity thermoforming tooling, while mid-scale specialists compete on rapid die changeover and short-run promotional formats. Strategic moves concentrate on certified recycled content infrastructure, thin-wall engineering R&D, and direct-store-delivery contract consolidation.
Among North American integrated packaging conglomerates, Berry Global Inc. and Dart Container Corporation exemplify the scale-driven archetype with multi-plant manufacturing footprints. Amcor represents the global diversified packaging tier with cross-material engineering capabilities. These three occupy positions where backward integration into resin compounding and control over feedstock quality separate premium-tier procurement from commodity competition.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Dart Container Corporation |
| Georgia-Pacific LLC |
| Amcor |
| Sabert Corporation |
| Tair Chu Enterprise |
| Pactiv |
| EcoPack Limited |
| MPM Marketing Services |
| Others |
Value Network & Pricing Analysis
Quick-service franchise procurement consolidation in North America anchors pricing power with converters offering multi-plant distribution and long-term resin hedging. This buyer concentration rewards scale players while compressing margins for regional specialists competing on spot-market resin exposure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EFSA-certified rPET specifications from virgin resin and uncertified recycled grades. Price differentiation hinges on food-contact certification tier and volume scale, with annual contract commitments commanding resin-index-linked adjustments. Cost compression in standard-grade virgin PET is intensifying because of flake supply competition from textile fiber markets. Independent cafes and small caterers exhibit highest price sensitivity, while German retail chains absorb specification premiums for certified recycled content as compliance table stakes.
Supply Chain Analysis
Skilled thermoforming technician availability constrains capacity expansion in the US Midwest and Germany's Rhine-Ruhr corridor, where precision mold maintenance and multi-cavity tool changeover expertise concentrates. Supply draws from rPET purification infrastructure in Germany, virgin resin production in the US Gulf Coast, and compounding operations in Belgium. Feedstock vulnerability centers on post-consumer bottle collection concentration in Western European municipal systems. Distribution runs through broadline foodservice wholesalers with pallet-scale annual commitments and price-adjustment clauses tied to resin indices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where sustainability compliance and thin-wall engineering separate premium converters from commodity competition. Specification demand from EFSA-mandated recycled content thresholds is pulling procurement toward certified supply chains with captive rPET infrastructure.
For Market Incumbents: Cement defensive positioning through backward integration into rPET compounding and purification assets in Germany or Belgium, insulating margin pools from flake supply competition with textile fiber markets. Prioritize multi-cavity thermoforming platform investments with rapid die changeover capability to capture direct-store-delivery contract consolidation across North American quick-service franchise systems. For New Entrants and Emerging Players: E-commerce platforms serving independent cafes and small caterers offer the most penetrable route for bypassing entrenched broadline distributor relationships. Target short-run promotional lid formats with direct-to-object digital print capability, exploiting modular thermoforming economics that injection-molding scale cannot match. Lead with REACH-compliant additive package certification to unlock German and French foodservice specifications. For Investors and Strategic Acquirers: Packaging conglomerates with cross-material engineering capabilities are the most active acquirer in this space, seeking bolt-on thermoforming specialists with EFSA-certified recycling infrastructure. Five-to-ten-year viability favors converters with captive rPET supply and thin-wall R&D pipelines. Watch for EPR framework adoption velocity across US states and Canadian provinces as inflection signal for closed-loop collection economics.| Strategic Initiative | Industry Significance |
|---|---|
| rPET Purification Infrastructure Investment | EFSA certification timelines for post-consumer flake unlock German retail procurement at specification premiums. |
| Thin-Wall Engineering R&D Program | Sub-0.35 mm lid specifications reduce resin volume per thousand units while maintaining automated dispensing compatibility. |
| Direct-Store-Delivery Contract Consolidation | Single-source lid specifications interchangeable across cup diameters compress SKU proliferation for franchise systems. |
| Digital Print Personalization Capability | Direct-to-object inkjet on thermoformed lids enables limited-run promotional campaigns previously uneconomical at scale. |
| Extended Producer Responsibility Participation | Closed-loop collection infrastructure in emerging US state and Canadian provincial schemes secures preferential market access. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with thermoforming plant managers, procurement leads at quick-service chains, rPET compounding technical directors, and foodservice distribution channel partners with secondary validation. Secondary sources included FDA food-contact clearance databases, EFSA Novel Food submission records, SEC filings from integrated packaging conglomerates, and trade data from resin industry associations. Bottom-up unit volume estimates from converter capacity utilization triangulated against top-down demand segmentation from end-use procurement patterns.
Historical reference periods anchored the projection horizon to pre-pandemic baseline volumes and post-directive regulatory implementation trajectories. The analytical framework modeled demand across material certification tiers, product type specifications, application categories, and distribution channel structures. CAGRs derived from regression analysis of resin price elasticity, recycled content adoption curves, and quick-service format expansion rates. Forecast inputs incorporated EPR framework adoption timelines and thin-wall engineering penetration assumptions.
The model assumes a particular technology adoption path; alternative pathways for chemical recycling scale-up would alter the outlook for mechanical rPET availability and pricing. Forecasts reflect assumptions about EFSA certification backlog resolution and flake supply competition intensity. Material deviation in EPR implementation velocity or REACH additive authorization timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Crown Closures Market
Caps and Closures
Fez Caps Market
Caps and Closures
Molded Fiber End Caps Market
Caps and Closures
Molded Fiber Pulp Cap Market
Caps and Closures
Bi-Injected Snap Hinge Closure Market
Caps and Closures
Spigot End Cap Market
Caps and Closures
Global Aluminum Caps for Packaging Market
Caps and Closures
United Arab Emirates Plastic Caps and Closures Market
Caps and Closures
France Plastic Caps and Closures Market
Caps and Closures
Crown Caps Market
Caps and Closures
Saudi Arabia Plastic Caps and Closures Market
Caps and Closures
Latin America Metal Caps and Closures Market
Caps and Closures
Linerless Closures Market
Caps and Closures
China Plastic Caps and Closures Market
Caps and Closures
Egypt Plastic Caps and Closures Market
Caps and Closures
Aerosol Valves Market