
 Global Aluminum Caps for Packaging Market | 2026-2036
Global Aluminum Caps for Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aluminum Caps for Packaging Market Analysis
Multi-source procurement among beverage brand owners is decoupling from legacy single-supplier arrangements across the aluminum closure value chain. Crown Holdings Inc. leverages integrated metal-forming capabilities across multiple continents to sustain volume leadership in standard screw caps. Guala Closures S.p.A anchors premium spirits demand through specialized tamper-evident designs. Silgan Holdings Inc. competes on manufacturing scale across North American and European packaging markets.
Aluminum caps for packaging are threaded or press-fit closures formed from aluminum alloy sheet, typically 0.20 to 0.35 millimeters thick, with internal liners of pulp-board, tinplate, or polymer to ensure seal integrity against gas and liquid migration. Their primary purpose is to preserve contents, enable controlled dispensing, and provide tamper evidence across bottled goods. Screw caps occupy the largest volume share as wine and spirits producers abandon natural cork, while tamper-evident variants capture expanding pharmaceutical compliance requirements. Flip top caps lead personal care applications where single-handed dispensing governs consumer preference.
FDA food-contact regulations, EU REACH substance restrictions, and EFSA migration limits collectively determine liner chemistry and alloy composition permissible for beverage and pharmaceutical contact. These frameworks raise reformulation costs for suppliers serving multiple jurisdictions but also lock in qualified incumbents against unproven entrants. Stakeholders must monitor evolving extended producer responsibility schemes and deposit-return mandates that could reshape aluminum recovery economics and closure lightweighting targets.
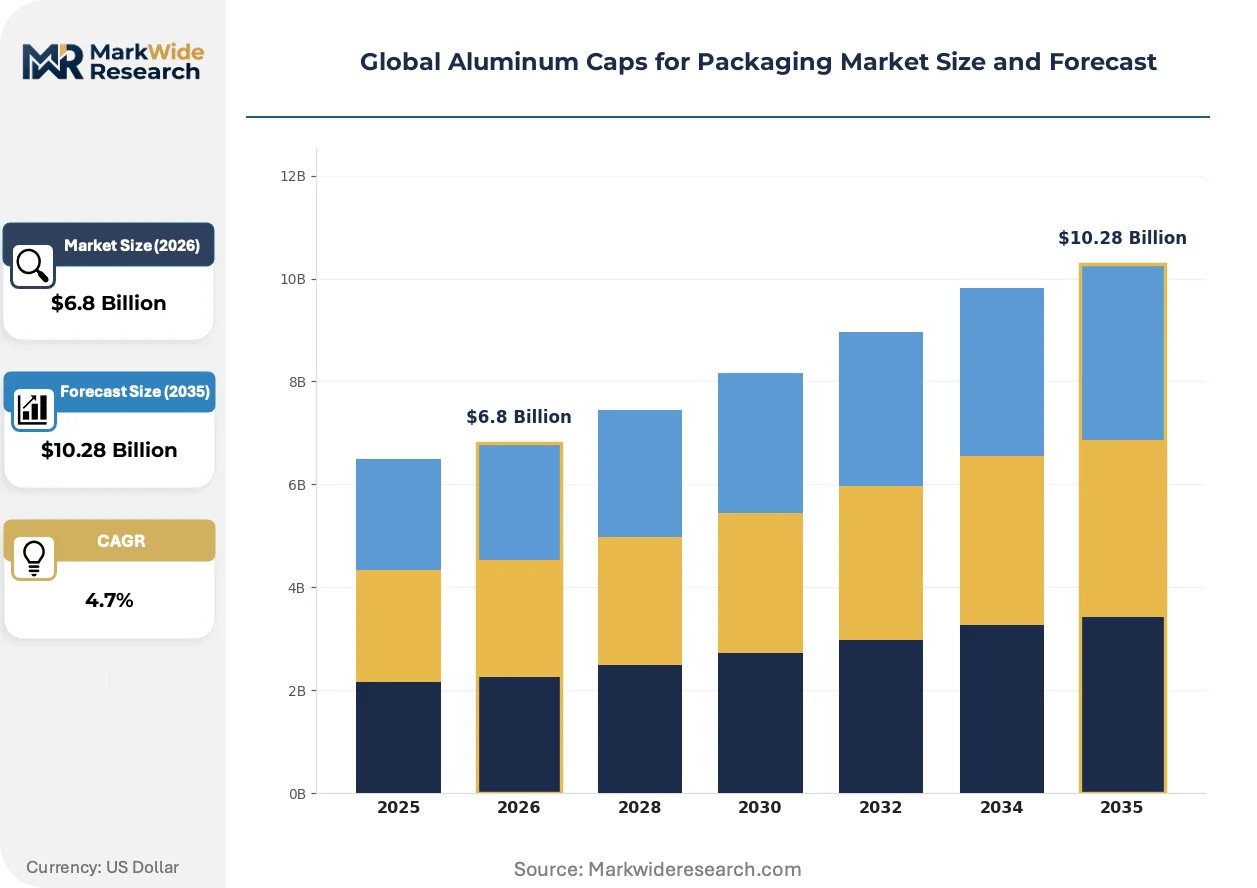
Market Dynamics
Beverage brand owners are decoupling from legacy single-supplier arrangements, fragmenting procurement across aluminum closure converters while EU REACH substance restrictions and the EU Green Deal mandate mono-material recyclability. This structural shift is compressing supplier margins and rewarding qualified incumbents with multi-jurisdictional compliance capabilities.
Growth Catalysts
- Wine and spirits abandonment of natural cork:Screw caps now dominate premium still wine closures, with bottlers citing consistency and TCA elimination as decisive factors. German distillers anchor specialized tamper-evident procurement.
- EU Green Deal circular economy mandates:The framework pushes converters toward aluminum-polymer separation elimination, accelerating mono-material liner development. Qualified suppliers capture locked-in procurement from compliant brand owners.
- Pharmaceutical compliance requirements:Tamper-evident aluminum variants satisfy FDA food-contact regulations and EFSA migration limits for oral solid dose packaging. Regulatory qualification timelines protect incumbent market position.
Market Restraints
- Aluminum alloy sheet price volatility:Input costs for 0.20-0.35 millimeter stock fluctuate with LME pricing and energy surcharges, squeezing converter margins without pass-through mechanisms.
- Specialized liner chemistry concentration:Pulp-board, tinplate, and polymer liner supply clusters in Western European chemical processing hubs, creating geographic dependency risk.
- Extended producer responsibility schemes:Germany's Verpackungsgesetz and similar frameworks impose fee structures that disadvantage smaller converters lacking scale for compliance infrastructure.
Strategic Opportunities
- Indian beverage packaging formalization:FSSAI enforcement and organized retail expansion create first-mover advantage for aluminum closure converters establishing local forming operations.
- Deposit-return mandate proliferation:EU member state implementations of DRS for beverage containers incentivize closure lightweighting and alloy optimization to maximize recovery economics.
- Flip-top personal care convergence:Single-handed dispensing demand in hair care and body wash segments opens aluminum substitution for incumbent plastic pump formats.
Industry Challenges
- Multi-jurisdictional liner reformulation:FDA food-contact regulations, EU REACH substance restrictions, and EFSA migration limits require parallel qualification tracks, extending new product introduction timelines.
- Legacy cork-to-screw line conversion:Wine bottlers face capital intensity for capping equipment replacement and consumer education investments in premium positioning markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aluminum Caps for Packaging Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spout Caps, Flip Top Caps, Screw Caps, Tamper Evident Caps End User: Beverage Industry, Pharmaceutical Sector, Food Packaging, Personal Care Application: Drink Bottles, Medicine Containers, Food Jars, Cosmetic Tubes Distribution Channel: Retail, Wholesale, Online Sales, Direct Distribution |
| Companies Covered | Guala Closures S.p.A, Alutop, Crown Holdings Inc., Pelliconi & C. SpA, Nippon Closures Co. Ltd., Silgan Holdings Inc., Herti JSC, Bericap GmbH & Co. KG, Amcor plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aluminum Caps for Packaging Market Emerging Trajectories
Aluminum closure technology is bifurcating between commodity scale and premium specialization, with regulatory chemistry constraints and end-use performance requirements driving divergent R&D investment patterns across converter portfolios.
Micro-embossed aluminum sheet forming is expanding into premium spirits and wine segments where tactile differentiation commands shelf-price premiums. French and Italian bottlers are adopting these variants fastest, displacing printed plastic shrink capsules. The technology is expanding into authentication applications through integrated holographic elements that compress counterfeiting vulnerability.
EU REACH substance restrictions are tightening liner polymer approvals, forcing converters to eliminate certain plasticizers and stabilizers from pulp-board laminates. Industrial consequence includes accelerated qualification of tinplate and aluminum-to-aluminum sealing interfaces. Wine and spirits producers in Germany, France, and Italy face the steepest reformulation timelines as existing stock depletes.
Multi-source procurement patterns are fragmenting buyer-supplier relationships that historically ran on decade-long sole-source contracts. Beverage brand owners now qualify three to five converters per closure specification, compressing switching costs and intensifying price competition. This behavior is most visible among North American craft distillers and mid-tier wine cooperatives seeking supply security after pandemic disruption.
Global Aluminum Caps for Packaging Market Segmentation
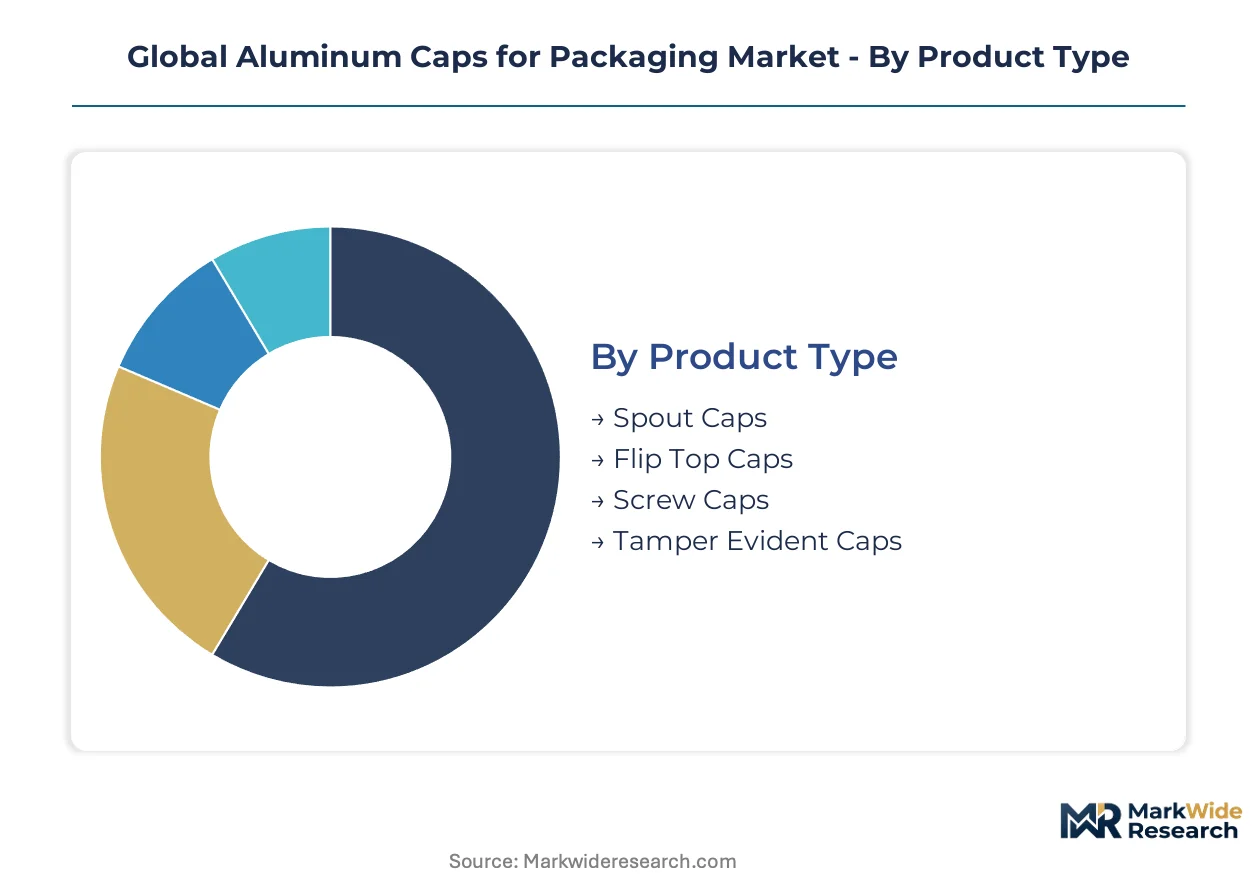
Aluminum closure procurement fragments across four dimensions, each imposing distinct regulatory burdens and technical specifications. Converters must maintain parallel qualification tracks across FDA food-contact, EU REACH, and EFSA frameworks to serve multi-jurisdictional buyers.
Product Type:
FDA food-contact regulations govern liner chemistry for beverage-facing variants, while EU REACH substance restrictions drive mono-material redesign across all formats. Tamper-evident designs face the steepest pharmaceutical compliance timelines.
- Screw Caps:Threaded closures formed from 0.20-0.35 millimeter aluminum alloy sheet with pulp-board or polymer liners. Wine and spirits bottlers in Germany and France drive volume as TCA elimination accelerates cork displacement. EFSA migration limits constrain liner reformulation cycles.
- Tamper Evident Caps:Break-ring or shrink-band integrated designs with specialized forming for evidence integrity. Pharmaceutical oral solid dose packaging in the US and EU anchors demand, with FDA qualification timelines protecting incumbent suppliers. EU Green Deal recyclability mandates are forcing aluminum-to-aluminum seal interface development.
- Flip Top Caps:Hinged single-handed dispensing closures with living-hinge aluminum forming. Personal care applications in North American and European markets favor convenience-driven substitution for plastic pumps.
- Spout Caps:Controlled-pour designs with internal flow restrictors for viscous liquids. Food packaging and industrial chemical segments specify these for precision dosing requirements.
Screw caps sit at the top of the volume ranking, with tamper evident caps climbing the fastest.
End User:
Cost tier stratification separates premium spirits procurement from commodity beverage contracts, with pharmaceutical qualification premiums commanding three-to-five-year supplier lock-ins.
- Beverage Industry:Wine, spirits, and non-alcoholic bottlers represent the dominant demand pool. German premium distillers anchor specialized tamper-evident procurement, while mid-tier wine cooperatives fragment sourcing across three to five qualified converters.
- Pharmaceutical Sector:Oral solid dose and liquid packaging with FDA food-contact and EMA compliance requirements. Regulatory qualification timelines extend new product introduction cycles and protect incumbent market position.
- Food Packaging:Preserves, sauces, and condiment containers with seal integrity against gas migration. EU REACH substance restrictions on liner polymers are accelerating tinplate laminate adoption.
- Personal Care:Hair care, body wash, and cosmetic dispensing with single-handed operation preferences. Flip-top aluminum formats are displacing incumbent plastic pumps in premium positioning segments.
Beverage industry procurement commands the largest contract values, with pharmaceutical sector pricing expanding most quickly.
Application:
Volume concentration tracks end-use scale, with drink bottles driving alloy throughput and medicine containers capturing margin through compliance premiums.
- Drink Bottles:Wine, spirits, water, and carbonated beverage containers with gas-tight seal requirements. Screw caps dominate still wine, while crown corks retain carbonated share. Deposit-return mandates in EU member states are incentivizing lightweighting.
- Medicine Containers:Pharmaceutical bottles and jars with tamper-evidence and child-resistance specifications. FDA and EMA frameworks determine liner chemistry and closure torque standards.
- Food Jars:Preserves, pickles, and condiment packaging with vacuum seal integrity. Pulp-board liner concentration in Western European chemical hubs creates geographic supply risk.
- Cosmetic Tubes:Personal care dispensing with aluminum flip-top or screw closure integration. Premium positioning in French and Italian markets favors micro-embossed tactile differentiation.
Drink bottles generate the highest unit volumes, with medicine containers yielding the steepest margin expansion trajectory.
Distribution Channel:
Customer type determines channel mix, with multinational beverage brand owners consolidating direct distribution and regional converters relying on wholesale intermediaries.
- Direct Distribution:Converter-to-bottler relationships for high-volume beverage and pharmaceutical contracts. Multi-source procurement patterns are fragmenting historically sole-source arrangements.
- Wholesale:Distributor intermediaries serving mid-tier converters and regional brand owners. Extended producer responsibility scheme compliance costs are squeezing smaller players.
- Retail:Spot procurement and aftermarket replacement for specialty and craft segments. North American craft distillers favor this channel for supply security.
- Online Sales:E-commerce platforms for small-batch and specialized closure procurement. Indian beverage packaging formalization is expanding this channel as FSSAI enforcement tightens.
Direct distribution captures the largest contract value, with online sales gaining share fastest among emerging market entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping aluminum closure manufacturing footprints as converters relocate forming operations toward jurisdictions with streamlined compliance pathways and favorable energy pricing. Cost-of-compliance gaps between REACH-regulated Europe and emerging Asian enforcement regimes are accelerating capacity migration decisions.
Germany
Premium spirits and wine bottlers in Baden-Württemberg and Bavaria anchor specialized tamper-evident procurement. The Verpackungsgesetz extended producer responsibility framework imposes fee structures that disadvantage smaller converters lacking compliance infrastructure. Stuttgart-area metal-forming clusters concentrate mono-material liner development for EU Green Deal recyclability mandates.
United States
FDA food-contact qualification timelines protect incumbent suppliers serving pharmaceutical oral solid dose packaging in New Jersey and Pennsylvania corridors. Beverage brand owners fragment procurement across three to five qualified converters after pandemic supply disruption. California wine cooperatives drive screw cap adoption as TCA elimination accelerates cork displacement.
China
Dual carbon goals and GB standards alignment are pressuring domestic converters toward energy-efficient forming technologies. Yangtze River Delta beverage packaging clusters absorb technology transfer from European joint ventures. Shanghai-area chemical processing hubs concentrate pulp-board liner supply for regional closure manufacturers.
India
FSSAI enforcement and organized retail expansion create first-mover advantage for converters establishing local forming operations. Maharashtra and Gujarat beverage bottlers formalize procurement as aluminum closures replace plastic alternatives. Mumbai-Pune industrial corridors attract capital for screw cap capacity serving domestic wine and spirits growth.
France
Bordeaux and Champagne wine producers drive micro-embossed aluminum adoption for tactile shelf differentiation. ANSM pharmaceutical regulations align with EMA frameworks for oral solid dose packaging closures. Lyon-area chemical processing maintains liner polymer supply concentration despite REACH-driven reformulation pressures.
Global Aluminum Caps for Packaging Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty authentication and mono-material recyclability niches. The vendor base stratifies across three tiers: integrated metal-forming multinationals with multi-continental footprint, regional specialists capturing premium spirits and pharmaceutical compliance premiums, and commodity converters competing on cycle time and tooling flexibility. Dominant competitive moves include backward integration into aluminum alloy sheet supply and strategic partnerships with liner chemistry developers to accelerate REACH-compliant reformulation.
Within the integrated-forming tier, Crown Holdings Inc. and Silgan Holdings Inc. exemplify scale-driven positioning across North American and European beverage packaging markets. Guala Closures S.p.A occupies the premium-specialist archetype, anchoring tamper-evident demand from Italian and French spirits producers. Among Asia-Pacific fabricators, Nippon Closures Co. Ltd. represents the regional compliance-qualified incumbent serving multi-jurisdictional pharmaceutical buyers.
| Leading Market Players |
|---|
| Guala Closures S.p.A |
| Alutop |
| Crown Holdings Inc. |
| Pelliconi & C. SpA |
| Nippon Closures Co. Ltd. |
| Silgan Holdings Inc. |
| Herti JSC |
| Bericap GmbH & Co. KG |
| Amcor plc |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists in Baden-Württemberg and Bavaria anchor premium-tier pricing discipline through captive liner-chemistry capabilities, while private-equity-rolled-up commodity converters compete on cycle-time flexibility across standard screw-cap contracts. This ownership fragmentation concentrates margin capture among REACH-qualified incumbents while compressing returns for undifferentiated volume players serving fragmented beverage procurement.
Pricing Analysis
Distributor margins absorb the steepest compression as beverage brand owners fragment procurement across three to five qualified converters per specification. Three-tier pricing structure across premium, standard, and economy levels separates tamper-evident pharmaceutical closures from commodity wine screw caps and undifferentiated food-packaging formats. Cost compression in standard-tier contracts is intensifying because multi-source procurement patterns eliminated sole-source loyalty premiums. Mid-tier wine cooperatives exhibit the highest price sensitivity, while German premium distillers accept certification-grade premiums for EU Green Deal-compliant mono-material designs.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Crown Holdings and Silgan across North American and European beverage markets, while wholesale intermediaries serve regional converters lacking compliance infrastructure. Raw material supply draws from aluminum alloy sheet producers in Germany, China, and the United States, with pulp-board liner chemistry clustering in Western European chemical processing hubs. Single-source vulnerability concentrates in tinplate laminate supply from Lyon-area specialty coaters. Distribution runs through converter-to-bottler direct relationships for pharmaceutical and premium spirits contracts, with spot retail channels capturing North American craft distiller demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories favor converters capturing premium-tier positioning through EU Green Deal-compliant mono-material development, while standard-tier players face relentless cycle-time competition. Liner-chemistry captive production emerges as the decisive cost-down driver separating profitable from marginal market positions.
For Market Incumbents: Acquire specialized liner-chemistry development capabilities to defend margin position against REACH-driven reformulation pressures. Backward integration into aluminum alloy sheet supply secures volume leverage against LME price volatility. Lock in three-to-five-year pharmaceutical qualification contracts before regulatory timelines extend further. Capacity addition in Maharashtra and Gujarat captures Indian beverage formalization upside. For New Entrants and Emerging Players: Boutique authentication specialists command premium positioning through micro-embossed and holographic closure integration for French and Italian spirits producers. White-space concentration sits with flip-top aluminum substitution for plastic pumps in North American personal care segments. FSSAI enforcement windows in Indian organized retail create first-mover formation advantages for local screw-cap capacity. Channel partnership with Mumbai-Pune industrial corridor distributors accelerates market access without direct converter infrastructure. For Investors and Strategic Acquirers: Valuations sit cheapest among commodity converters lacking REACH qualification and mono-material R&D pipelines. Long-term viability frames around five-to-ten-year regulatory compliance moats rather than volume scale alone. Acquisition target archetype: regional specialists with pharmaceutical FDA/EMA dual qualification and underutilized forming capacity. Watch EU member state deposit-return mandate implementation velocity as the inflection signal for lightweighting investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Liner Chemistry | Captive polymer and tinplate laminate production accelerates REACH-compliant reformulation cycles for German spirits contracts. |
| Mono-Material Seal Interface Development | Aluminum-to-aluminum sealing eliminates polymer separation costs under EU Green Deal circular economy mandates. |
| Micro-Embossed Forming Capacity Expansion | Tactile differentiation commands shelf-price premiums from Bordeaux and Champagne wine producers displacing plastic capsules. |
| Pharmaceutical Dual Qualification Investment | FDA and EMA parallel tracks protect incumbent positioning against three-to-five-year regulatory lock-in timelines. |
| Maharashtra-Gujarat Local Forming Operations | FSSAI enforcement and organized retail expansion create first-mover supply security in Indian beverage formalization. |
Methodological Framework
Direct dialogue with converter operations managers, liner-chemistry R&D directors, beverage brand-owner procurement leads, and pharmaceutical packaging compliance officers grounded qualitative assessment. Secondary validation drew from EU REACH substance restriction filings, FDA food-contact regulation updates, EFSA migration limit publications, and aluminum industry trade association capacity surveys. Bottom-up triangulation across converter shipment data and top-down reconciliation against beverage bottling volume statistics ensured cross-verified demand estimation.
Segment-level value and volume trajectories emerged from integrated modeling across product type, end-user industry, application format, and distribution channel dimensions. CAGRs derived from alloy throughput elasticity to beverage production indices, pharmaceutical packaging growth coefficients, and regulatory compliance premium capture rates. Liner chemistry reformulation timelines and deposit-return mandate implementation schedules fed scenario-weighted probability distributions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal enforcement velocity, LME aluminum price volatility, and extended producer responsibility fee structure evolution. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Lined Lug Caps Market
Caps and Closures
North America Plastic Caps and Closures Market
Caps and Closures
PCR Closures Market
Caps and Closures
T-Top Closures Market
Caps and Closures
Crown Caps Market
Caps and Closures
Cap Seals Market
Caps and Closures
North America Metal Caps and Closures Market
Caps and Closures
Twist-Off Metal Caps Market
Caps and Closures
Plastic Caps and Closure Market
Caps and Closures
Screw Caps and Closure Market
Caps and Closures
Japan Plastic Caps and Closures Market
Caps and Closures
Gable Top Cap and Closures Market
Caps and Closures
Germany Plastic Caps and Closures Market
Caps and Closures
Canada Plastic Caps and Closures Market
Caps and Closures
Spigot End Cap Market
Caps and Closures
Heat Induction Cap Liner Market