
 Japan Plastic Caps and Closures Market | 2026-2036
Japan Plastic Caps and Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Plastic Caps and Closures Market Insights
Beverage packaging is consolidating its position as the dominant end-use vertical for plastic caps and closures in Japan. Toyo Seikan Group Holdings Ltd leverages its integrated container and closure manufacturing network to anchor supply relationships with major Japanese beverage brands. Nippon Closures Co. Ltd specializes in precision-molded screw and sports cap formats for pharmaceutical and cosmetic applications. Amcor Group GmbH competes through advanced barrier closure technologies that extend shelf stability for sensitive food products.
Japan plastic caps and closures are threaded or snap-fit dispensing and sealing devices molded from thermoplastic resins, typically featuring tamper-evident bands, linerless seals, or flow-control orifices engineered to specific neck-finish standards. Polypropylene dominates material selection due to its chemical resistance, hinge flexibility in flip-top designs, and compatibility with hot-fill processes. Screw caps occupy the largest volume share across beverage and food packaging channels, while flip-top caps represent the fastest-growing format driven by on-the-go consumption patterns in cosmetics and personal care. Direct sales channels sustain higher margin pools by bypassing distributor markups for large-volume pharmaceutical and food-industry contracts.
METI enforces container and packaging recycling obligations under the Act on Promotion of Resource Circulation, compelling manufacturers to incorporate post-consumer resin and design for mono-material recyclability. JIS standards govern dimensional tolerances and seal integrity, while PMDA regulations mandate child-resistant and senior-friendly closure performance for over-the-counter and prescription pharmaceutical applications. Stakeholders must monitor evolving EPR fee structures and bioplastic certification pathways as these frameworks determine material qualification and competitive access across Japan's tightly regulated packaging value chain.
Market Dynamics
METI's Resource Circulation Strategy is forcing Japanese converters to redesign closures for mono-material recyclability while maintaining seal integrity against oxygen and carbon dioxide ingress. This regulatory pressure intersects with demographic-driven demand for single-serve beverage formats, creating simultaneous pulls on material selection and dimensional precision.
Growth Catalysts
- Container and packaging recycling obligations:METI mandates under the Act on Promotion of Resource Circulation compel brand owners to specify post-consumer resin content, qualifying suppliers with verified PCR sourcing capabilities for premium contract tiers.
- Hot-fill compatible polypropylene grades:Advances in nucleated PP resins enable 85°C filling temperatures without dimensional distortion, opening tea and isotonic beverage segments previously reserved for glass or metal.
- Kanto industrial corridor concentration:Proximity to Tokyo and Kanagawa prefectures' beverage bottling clusters reduces logistics costs for just-in-time closure delivery, reinforcing regional supplier lock-in.
Market Restraints
- Propylene feedstock volatility:Naphtha-derived monomer costs fluctuate with regional refinery utilization, compressing margin predictability for injection molders operating on six-month supply contracts.
- Bioplastic performance gaps:Polylactic acid and bio-based polyethylene exhibit inferior hinge fatigue and barrier properties versus fossil PP, limiting substitution in carbonated and long-shelf-life applications.
- Neck finish standard fragmentation:JIS, PCO, and proprietary 38mm sport-cap specifications require mold inventory duplication, raising working capital requirements for multi-format suppliers.
Strategic Opportunities
- Chubu and Kansai regional expansion:Aichi and Osaka prefectures host underdeveloped pharmaceutical and cosmetic closure demand relative to Kanto, offering whitespace for precision-molding specialists.
- Pharmaceutical child-resistant closure mandates:PMDA regulations for over-the-counter analgesics and prescription medications create certified-supplier premiums unavailable to commodity beverage closure producers.
- Direct-to-bottler digital procurement platforms:B2B marketplace integration enables smaller molders to bypass traditional distributor networks and capture pharmaceutical contract margins previously inaccessible at their scale.
Industry Challenges
- Bioplastic certification timeline compression:Japan Organic Recycling Association verification and METI green purchasing qualification require twelve-to-eighteen-month documentation cycles, delaying commercialization of novel resin formulations.
- Multi-cavity mold reconfiguration costs:Transitioning from 32-cavity to 64-cavity production for high-volume beverage contracts demands capital outlays that strain mid-tier processors with limited balance sheet capacity.
- PCR resin quality inconsistency:Post-consumer polypropylene exhibits melt flow index variation that disrupts automated capping line torque consistency, requiring real-time process adjustment capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Plastic Caps and Closures Market |
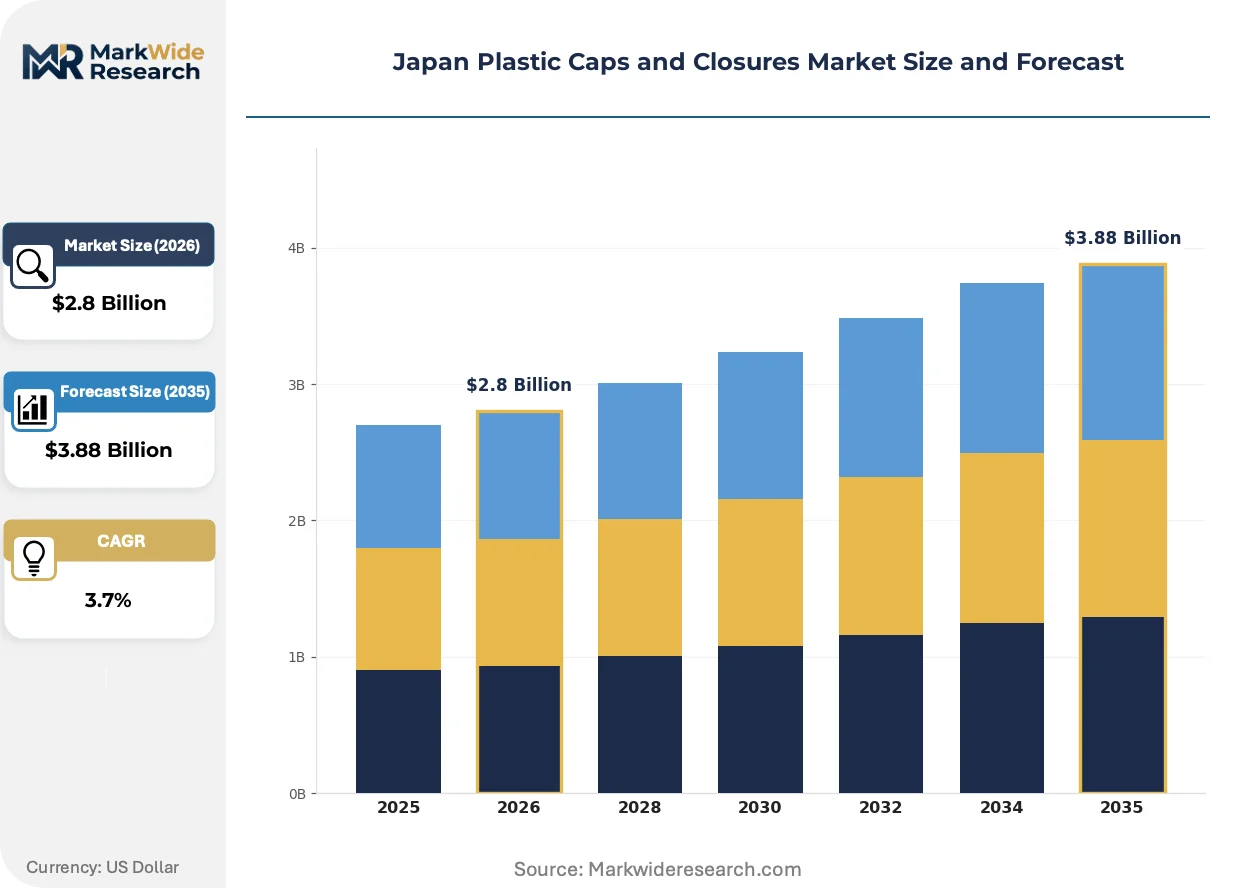
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $3.88 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screw Caps, Sports Caps, Flip-Top Caps, Crown Caps Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Polystyrene End User: Beverage Industry, Pharmaceuticals, Cosmetics, Food Packaging Distribution Channel: Online Sales, Retail Outlets, Direct Sales, Distributors |
| Companies Covered | Nippon Closures Co. Ltd, Toyo Seikan Group Holdings Ltd, Amcor Group GmbH, Aptar Group Inc., Tetra Laval International S.A., Nihon Yamamura Glass Co. Ltd, Mikasa Industry Co. Ltd, Takex Co. Ltd, Sonoco Products Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Plastic Caps and Closures Market Trends and Innovations
Japanese closure manufacturers are integrating digital thread technologies with material science advances to satisfy simultaneous demands for circularity compliance and functional performance. Three developments are restructuring competitive capability requirements.
Mono-material polyethylene closures with integrated tamper-evident bands are absorbing share from multi-component PP/PE constructions as METI's recyclability guidelines harden. Beverage brand owners in Tokyo and Yokohama are specifying these designs for 500ml PET bottle lines, compressing demand for separate liner insertion equipment and reducing converter capital intensity.
Japan's Act on Promotion of Resource Circulation now requires annual reporting of plastic usage and recycling rates across packaging supply chains. Closure manufacturers must document post-consumer resin percentages and design-for-recycling scores, with non-compliant suppliers facing exclusion from prefectural government procurement and major retailer private-label contracts.
Pharmaceutical buyers are consolidating supplier relationships around certified child-resistant and senior-friendly closure specialists capable of simultaneous PMDA compliance and JIS dimensional tolerance verification. This concentration displaces fragmented sourcing across multiple commodity molders, favoring integrated design-to-manufacture providers in Osaka and Nagoya pharmaceutical corridors.
Japan Plastic Caps and Closures Market Segmentation
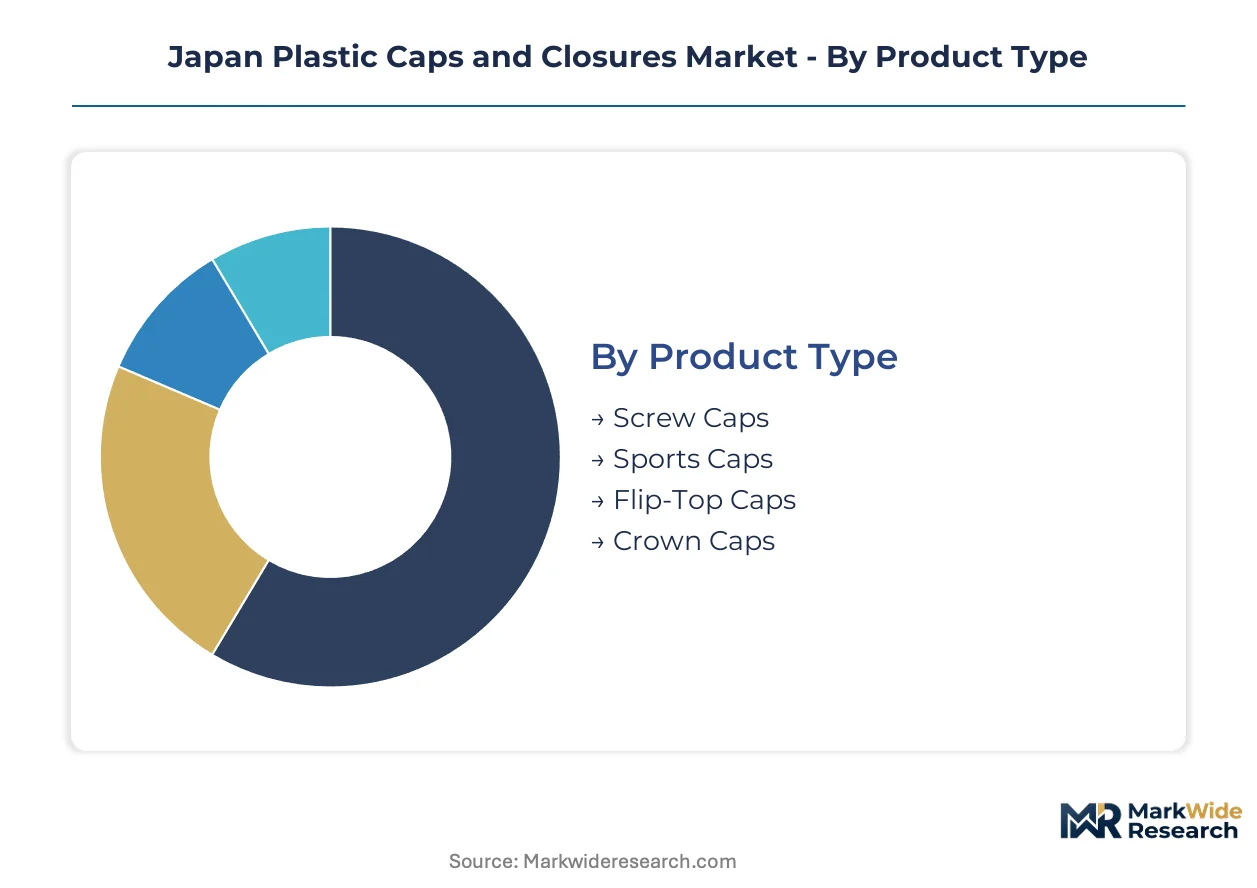
Segmentation in Japan's plastic caps and closures market reveals how regulatory pressure from METI and demographic shifts create divergent technical requirements across product categories. Understanding these divisions exposes where capital deployment and certification investments yield sustainable competitive position.
Product Type:
Screw caps dominate volume flows through precision thread engineering that satisfies JIS dimensional tolerances for carbonated beverage sealing.
- Screw Caps:Polypropylene construction with standardized PCO neck finishes anchors supply contracts with Tokyo and Kanagawa bottling clusters. Demand concentrates in 500ml PET tea and isotonic lines where hot-fill compatibility at 85°C eliminates glass substitution.
- Sports Caps:Flow-control orifices with silicone valve inserts target single-serve consumption patterns among Japan's aging demographic seeking convenience without spillage. Chubu pharmaceutical corridors are absorbing specialized dispensing formats for unit-dose liquid medications.
- Flip-Top Caps:Living hinge designs in nucleated PP grades serve cosmetic and personal care applications across Osaka prefecture.
- Crown Caps:Metal-liner composite construction retains niche position in craft beverage segments.
Mature deployment sits with screw caps. Newer deployment is concentrated in sports caps.
Material:
Resin selection determines recyclability scoring under METI's Resource Circulation Strategy and directly shapes converter qualification for prefectural procurement.
- Polypropylene:Chemical resistance and hinge fatigue performance make this the default for flip-top and sports cap formats. Kanto beverage bottlers specify homopolymer grades for carbonated applications where CO2 barrier requirements exceed polyethylene capabilities.
- Polyethylene:Mono-material HDPE closures with integrated tamper-evident bands are displacing multi-component constructions as METI guidelines harden. Direct sales channels to major food packagers in Yokohama specify these designs for simplified recycling streams.
- Polyvinyl Chloride:Shrink-sleeve compatibility maintains residual demand in specialty pharmaceutical blister packaging.
- Polystyrene:Clarity requirements in cosmetic sampling applications sustain limited volume.
Established qualification pathways favor polypropylene. Emerging substitution pressure targets polyethylene.
End User:
End-use verticals impose distinct certification burdens, with PMDA pharmaceutical mandates creating supplier premiums unavailable in commodity beverage channels.
- Beverage Industry:Carbonated soft drink and ready-to-drink tea bottlers in Tokyo prefecture drive screw cap volume through just-in-time delivery requirements. METI recycling obligations now mandate post-consumer resin documentation for all suppliers to major retail private-label programs.
- Pharmaceuticals:Child-resistant and senior-friendly closure certification under PMDA regulations concentrates sourcing among Nagoya and Osaka specialists capable of simultaneous torque compliance and JIS verification. Unit-dose liquid formats are expanding fastest among aging-population medication adherence packaging.
- Cosmetics:Flip-top and pump closures for premium skincare lines concentrate in Kansai manufacturing corridors.
- Food Packaging:Barrier closure specifications for sensitive condiments and sauces sustain regional molder relationships.
Volume concentration remains with beverage applications. Margin expansion concentrates in pharmaceuticals.
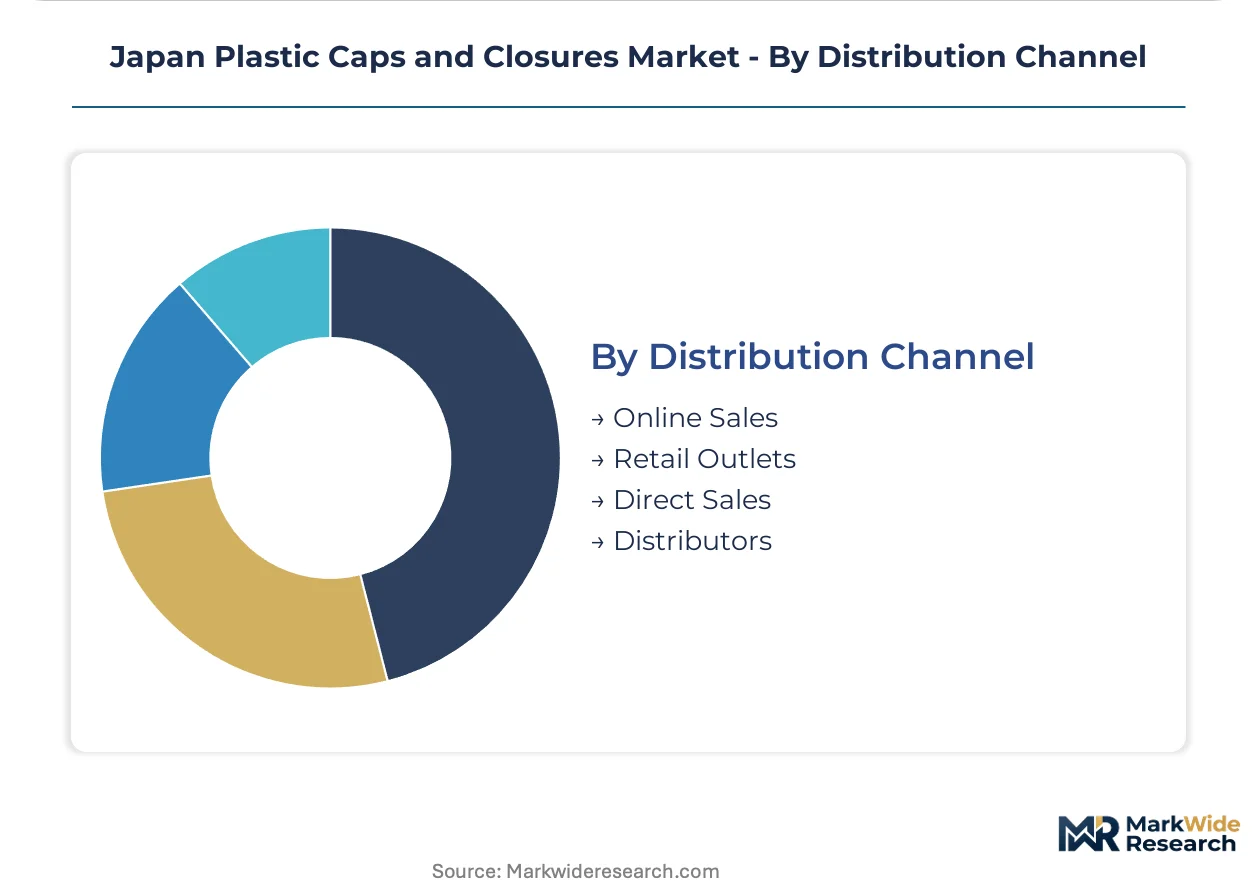
Distribution Channel:
Channel selection determines working capital intensity and margin capture, with direct relationships rewarding scale and certification investment.
- Direct Sales:Large-volume pharmaceutical and food-industry contracts bypass distributor markups, sustaining higher margin pools for converters with verified PCR sourcing and PMDA certification. Tokyo-headquartered beverage multinationals negotiate annual frame contracts with integrated closure-container suppliers.
- Distributors:Regional logistics networks serve mid-tier cosmetic and specialty food packagers lacking procurement scale for direct manufacturer relationships. Inventory duplication across JIS, PCO, and proprietary 38mm specifications raises working capital requirements.
- Online Sales:B2B marketplace platforms enable smaller molders to access pharmaceutical contract tiers previously gated by distributor relationships.
- Retail Outlets:Aftermarket and replacement closure sales for consumer storage applications.
Direct sales anchor premium positioning. Digital procurement platforms are gaining fastest traction among mid-tier suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kanto's special economic zones and industrial infrastructure subsidies have concentrated plastic closure manufacturing within Tokyo and Kanagawa prefectures, creating a demand gravity well that absorbs over half of domestic production capacity.
Kanto/Tokyo
Beverage bottling clusters in Tokyo and Yokohama drive screw cap consumption through just-in-time delivery contracts with major retail private-label programs. METI's Resource Circulation Strategy mandates post-consumer resin documentation for all suppliers to these channels. Chiba and Saitama prefectures host precision molders serving pharmaceutical corridors with PMDA-certified child-resistant closure production.
Kansai/Osaka
Cosmetic and personal care manufacturers in Osaka prefecture absorb flip-top and pump closure volumes for premium skincare lines. The region's pharmaceutical packaging sector concentrates child-resistant and senior-friendly closure demand under evolving PMDA regulations. Kyoto and Hyogo prefectures maintain specialty food packaging relationships requiring barrier closure specifications for sensitive condiments.
Chubu/Nagoya
Automotive and industrial chemical packaging sustains regional demand for chemical-resistant polypropylene closures. Aichi prefecture's pharmaceutical manufacturing corridors present whitespace opportunity for precision-molding specialists seeking PMDA certification. Gifu and Shizuoka prefectures support regional distribution networks serving mid-tier cosmetic packagers.
Kyushu
Fukuoka's emerging food processing sector generates demand for mono-material polyethylene closures compliant with METI recyclability guidelines. The region's underdeveloped pharmaceutical closure infrastructure offers entry points for certified suppliers from Kanto and Kansai. Saga and Nagasaki prefectures maintain residual beverage bottling capacity with legacy screw cap specifications.
Tohoku
Sendai's regional logistics hub serves aftermarket closure distribution for consumer storage applications. The area's limited manufacturing base relies on Kanto suppliers for pharmaceutical and cosmetic packaging needs. Iwate and Miyagi prefectures concentrate agricultural food processing with basic barrier closure requirements.
Japan Plastic Caps and Closures Market Competitive Landscape
Top-tier vendors anchor integrated container-closure manufacturing networks, while mid-tier specialists compete on PMDA certification and mono-material recyclability compliance. Market structure reflects regional supplier lock-in around Kanto beverage bottling clusters, with pharmaceutical channels rewarding certified specialists. Three archetypes dominate: integrated packaging conglomerates, precision-molding specialists, and barrier technology providers. Competitive moves center on backward integration into resin sourcing and digital procurement platform development.
Within the integrated packaging tier, Toyo Seikan Group Holdings Ltd exemplifies the container-closure convergence model, while Nippon Closures Co. Ltd occupies a position among precision-molding specialists serving pharmaceutical and cosmetic verticals. Amcor Group GmbH represents the barrier technology archetype competing through shelf-stability extension capabilities. These three companies anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Nippon Closures Co. Ltd |
| Toyo Seikan Group Holdings Ltd |
| Amcor Group GmbH |
| Aptar Group Inc. |
| Tetra Laval International S.A. |
| Nihon Yamamura Glass Co. Ltd |
| Mikasa Industry Co. Ltd |
| Takex Co. Ltd |
| Sonoco Products Company |
| Others |
Pricing and Supply Chain Analysis
METI's post-consumer resin mandates are compelling brand owners to qualify suppliers with verified PCR documentation, forcing molders to absorb certification costs while Kanto beverage bottlers consolidate procurement around integrated container-closure providers. This specification tightening concentrates pricing power among certified incumbents and raises barriers for mid-tier competitors lacking balance sheet depth for twelve-to-eighteen-month qualification cycles.
Pricing Analysis
Spot inventory discounts of fifteen-to-twenty percent below contract rates attract smaller cosmetic packagers in Osaka and Nagoya seeking to minimize working capital exposure. Three-tier pricing structure across premium, standard, and economy levels separates PMDA-certified pharmaceutical specialists from commodity beverage suppliers and undifferentiated regional molders. Pricing pressure stems from propylene feedstock volatility tied to regional naphtha cracking economics, compressing margin predictability for injection molders locked into six-month supply agreements. Beverage bottlers in Tokyo prefecture exhibit highest price sensitivity due to just-in-time delivery requirements and volume scale, while pharmaceutical buyers prioritize torque compliance and child-resistant certification over unit cost.
Supply Chain Analysis
Polypropylene resin supply rests on Japanese petrochemical producers in Chiba and Kanagawa prefectures, with supplemental volumes drawn from South Korean and Singaporean refiners to hedge against domestic capacity constraints. Nucleated PP grades for hot-fill applications, silicone valve inserts for sports caps, and precision mold tooling constitute critical input dependencies. Single-source vulnerability concentrates around specialty resin formulations qualified for PMDA pharmaceutical applications, where alternative sourcing requires protracted re-qualification. Distribution runs through direct annual frame contracts with Tokyo-headquartered beverage multinationals, supplemented by regional logistics networks serving mid-tier cosmetic and specialty food packagers lacking procurement scale for manufacturer-direct relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
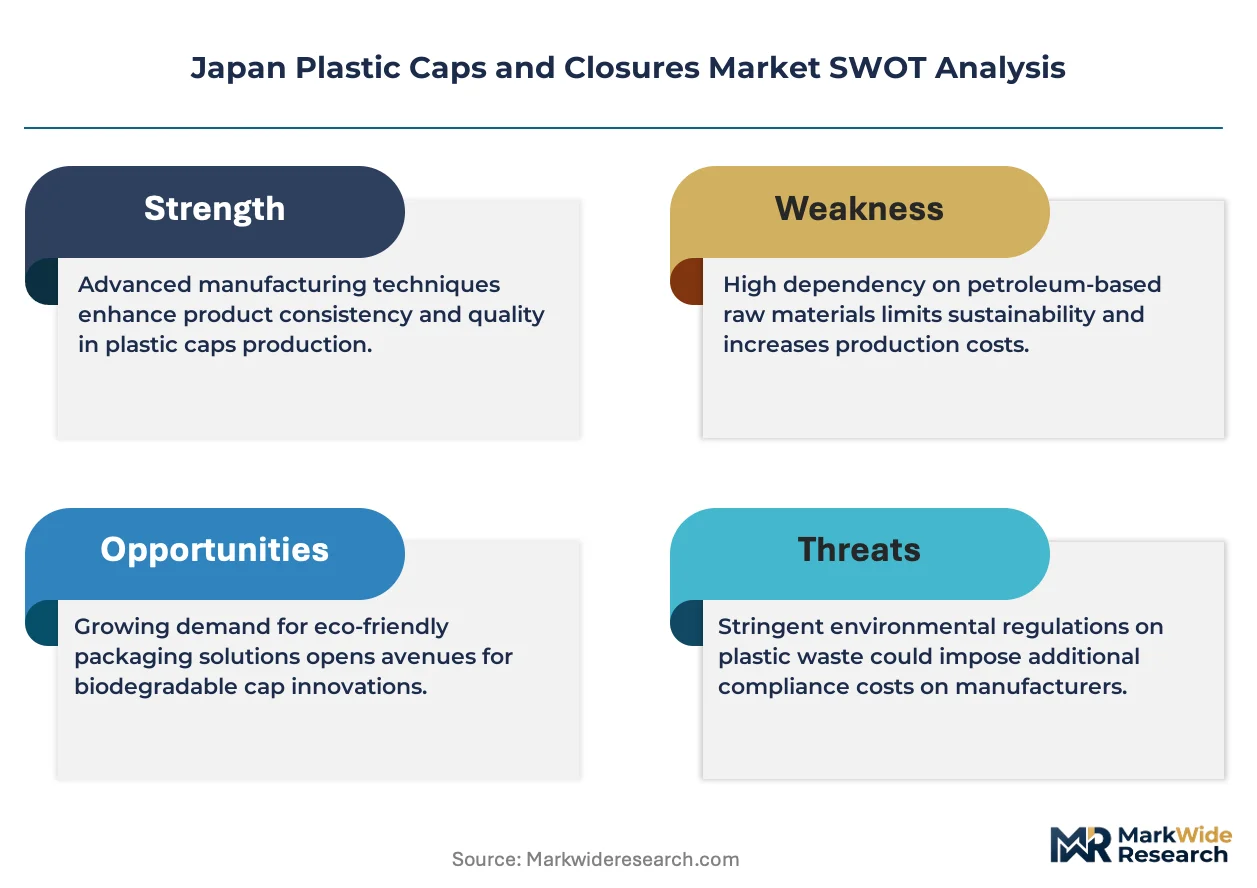
Japan's plastic caps and closures market is consolidating around certified specialists capable of simultaneous METI recyclability compliance and PMDA pharmaceutical qualification, with METI's documentation requirements forcing weaker players toward exit or acquisition.
For Market Incumbents: Anchor Kanto beverage relationships through backward integration into post-consumer resin sourcing, securing verified PCR supply chains that qualify for premium contract tiers under METI's Resource Circulation Strategy. Expand PMDA certification scope into senior-friendly closure designs for Tokyo and Nagoya pharmaceutical corridors, creating supplier premiums unavailable to commodity molders lacking torque compliance expertise. For New Entrants and Emerging Players: Enter via Chubu pharmaceutical corridors in Aichi prefecture, where precision-molding demand for unit-dose liquid medication closures outpaces certified supplier capacity. Target digital procurement platforms to bypass legacy distributor networks and capture pharmaceutical contract margins previously gated by relationship depth, while building JIS dimensional tolerance capabilities to qualify for Osaka cosmetic packaging relationships. For Investors and Strategic Acquirers: The window for entry favors mid-tier molders with latent PMDA certification capacity and established Kanto logistics infrastructure, positioned for rollup into integrated packaging networks. Acquisition targets should demonstrate mono-material design capabilities aligned with METI recyclability trajectories. Watch bioplastic certification timeline compression as the inflection signal determining which resin technology pathways achieve commercial scale.| Strategic Initiative | Industry Significance |
|---|---|
| PCR Supply Chain Integration | Verified post-consumer resin sourcing qualifies suppliers for METI-mandated prefectural procurement contracts. |
| PMDA Certification Expansion | Child-resistant and senior-friendly closure capabilities unlock pharmaceutical premiums in Nagoya and Osaka corridors. |
| Digital Procurement Platform Development | B2B marketplace integration enables mid-tier molders to bypass distributor markups and access pharmaceutical tiers. |
| Mono-Material Design Transition | Integrated tamper-evident PE closures satisfy METI recyclability guidelines while reducing converter capital intensity. |
| Chubu Regional Capacity Addition | Aichi prefecture pharmaceutical manufacturing corridors present whitespace for precision-molding specialists seeking certification. |
Research Methodology
Multi-period observation of METI regulatory filing patterns, PMDA certification timelines, and Kanto beverage bottler procurement contracts anchored the trend analysis, supplemented by interviews with injection molding plant managers, pharmaceutical packaging engineers, and resin procurement leads at downstream OEMs. Secondary validation drew from METI Resource Circulation Strategy documentation, JIS dimensional tolerance standards, PMDA pharmaceutical packaging guidelines, and customs data tracking polypropylene resin import flows. Bottom-up capacity assessments across Tokyo, Kanagawa, Osaka, and Aichi prefectures were triangulated against top-down demand estimates from beverage, pharmaceutical, and cosmetic end-use verticals.
Segment-weighting approaches applied differential growth assumptions across screw caps, sports caps, and flip-top formats, with material-grade stratification between polypropylene and polyethylene constructions, and end-use splits across beverage, pharmaceutical, cosmetic, and food packaging channels. CAGRs were derived from elasticity-adjusted demand modeling incorporating demographic consumption shifts and regulatory compliance cost pass-through. Forecast inputs included nucleated PP resin availability for hot-fill applications, multi-cavity mold reconfiguration cycles, and PCR quality consistency parameters affecting automated capping line performance.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated bioplastic substitution timelines or propylene feedstock disruption scenarios. Model assumptions reflect documented METI enforcement trajectories and PMDA regulatory evolution pathways. A small set of triggers—bioplastic certification timeline compression, EPR fee structure revisions, and Kanto logistics cost shocks—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Lug Caps Market
Caps and Closures
Global Die Cut Lids Market
Caps and Closures
Middle East and Africa Plastic Caps and Closures Market
Caps and Closures
Metal Caps and Closures Market
Caps and Closures
Steel Ring Pull Caps Market
Caps and Closures
Laminated Tube Closure Market
Caps and Closures
North America Metal Caps and Closures Market
Caps and Closures
Reverse Cap Bottles Market
Caps and Closures
Child Resistant Pipette Closures Market
Caps and Closures
Plunger Stopper Market
Caps and Closures
Nordic Plastic Caps and Closures Market
Caps and Closures
Fixed Length Seals Market
Caps and Closures
Screw Closure Market
Caps and Closures
Flip Top Caps and Closures Market
Caps and Closures
Beverage Caps and Closures Market
Caps and Closures
Plastic Sifter Caps Market