
 Bag Closures Market | 2026-2036
Bag Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Bag Closures Market Analysis
The divergence between premium and commodity tiers is shifting as food brands demand tamper-evident closures while discount retailers accept basic twist-tie formats. Kwik Lok Corporation leverages its global manufacturing footprint to serve both tiers. Schutte Bagclosures B.V. specializes in paper-based alternatives for European bakery chains. Bedford Industries, Inc. anchors North American demand through its bread-bag tie dominance.
Bag closures are mechanical or adhesive fastening devices, typically measuring 2–15 cm in length, designed to seal flexible packaging against moisture, contamination, and spillage during storage and transit. Their primary commercial purpose is extending shelf life while enabling repeated consumer access. Plastic zip-lock formats retain the largest volume share across food packaging applications, though biodegradable materials represent the fastest-expanding margin pool as converters respond to retailer sustainability mandates. Heat-seal closures dominate medical supplies where sterility validation is mandatory, while adhesive strips compete aggressively in e-commerce shipping for cost-sensitive apparel and accessory merchants.
FDA food-contact regulations govern closure composition for US packaged goods, while EU REACH and F-Gas Regulation restrict certain polymer chemistries and propellants used in manufacturing. These frameworks compel material substitution investments and reshape supplier qualification criteria for multinational food brands. Stakeholders must monitor evolving extended producer responsibility schemes and biodegradability certification requirements as gatekeepers for retail shelf access.
Market Dynamics
Supermarket private-label standardization is compressing supplier margins while simultaneously elevating performance specifications for resealability and tamper evidence.
Growth Catalysts
- EU F-Gas Regulation:The phase-down of hydrofluorocarbon propellants in closure manufacturing accelerates investment in biodegradable polymer alternatives across European flexible packaging converters.
- Fresh produce packaging:Retail chains mandate resealable formats for cut vegetables and berries, driving volume demand for zip-lock mechanisms with moisture-barrier properties.
- Heat-seal validation:Medical device sterilization requirements expand adoption of hermetic closure systems in pharmaceutical supply chains.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene and polyethylene resin price swings compress converter margins and destabilize annual contract pricing.
- Biodegradability certification bottlenecks:Competing standards from TÜV Austria, BPI, and DIN CERTCO create qualification delays and regional market fragmentation.
- Adhesive strip substitution:Pressure-sensitive tape formats capture e-commerce apparel shipping volumes through lower unit economics.
Strategic Opportunities
- India organized retail expansion:Modern trade penetration in tier-2 cities creates first-mover positioning for standardized closure suppliers to domestic snack brands.
- Extended producer responsibility schemes:France's AGEC Law and similar frameworks in Italy and Spain mandate recyclable packaging, favoring mono-material closure designs.
- Smart packaging convergence:Integration of RFID tags with mechanical closures enables track-and-trace functionality for high-value pharmaceutical and luxury goods.
Industry Challenges
- Biopolymer processing expertise:PLA and PHA formulations require extrusion parameter recalibration that existing workforce competencies do not cover.
- Legacy equipment retrofit costs:Converting thermoforming lines for compostable materials demands capital outlays that mid-tier converters struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bag Closures Market |
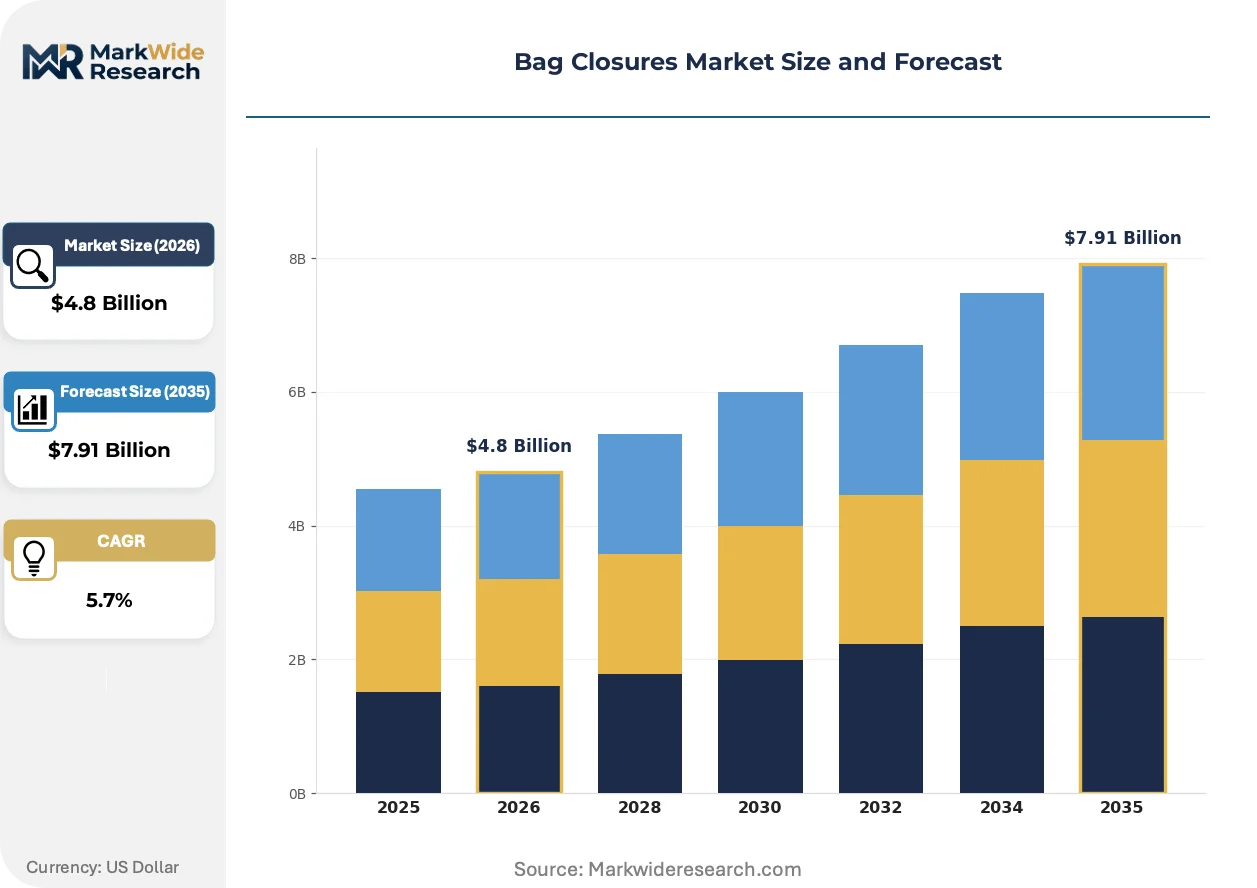
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Closure Type: Zip Lock, Heat Seal, Tie, Adhesive Material: Plastic, Paper, Metal, Biodegradable Application: Food Packaging, Medical Supplies, Retail Products, Waste Management End User: Food Industry, Healthcare, Retail, E-Commerce |
| Companies Covered | Plas-Ties, Co., International Plastics Inc., Kwik Lok Corporation, Inno Bag Closure, ITW Envopak Limited, Schutte Bagclosures B.V., Multipack B.V.B.A., Detmold Group, Bedford Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bag Closures Market Emerging Trajectories
Material science breakthroughs and regulatory compliance automation are redefining how closure manufacturers compete on speed-to-certification and sustainability credentials.
Mono-material polypropylene closures is unifying recyclability with mechanical performance in European bakery and snack applications. German and Dutch retail chains specify these formats for their private-label bread lines. The technology is unifying previously separate supply chains for body and closure into single-stream recovery systems.
REACH substance restriction updates are forcing reformulation of plasticizers and slip agents used in zip-lock manufacturing. ECHA's 2024 candidate list expansion affects phthalate alternatives previously considered safe replacements. Medical and food-contact segments in the EU are accelerating migration testing protocols to maintain market access.
Direct-to-retailer specification contracts are displacing traditional distributor-mediated procurement in North American supermarket chains. Category managers now mandate closure performance benchmarks as part of packaging RFPs rather than delegating to converter discretion. This pattern concentrates most visibly in US fresh produce and bakery verticals where shelf-life guarantees carry penalty clauses.
Bag Closures Market Segmentation
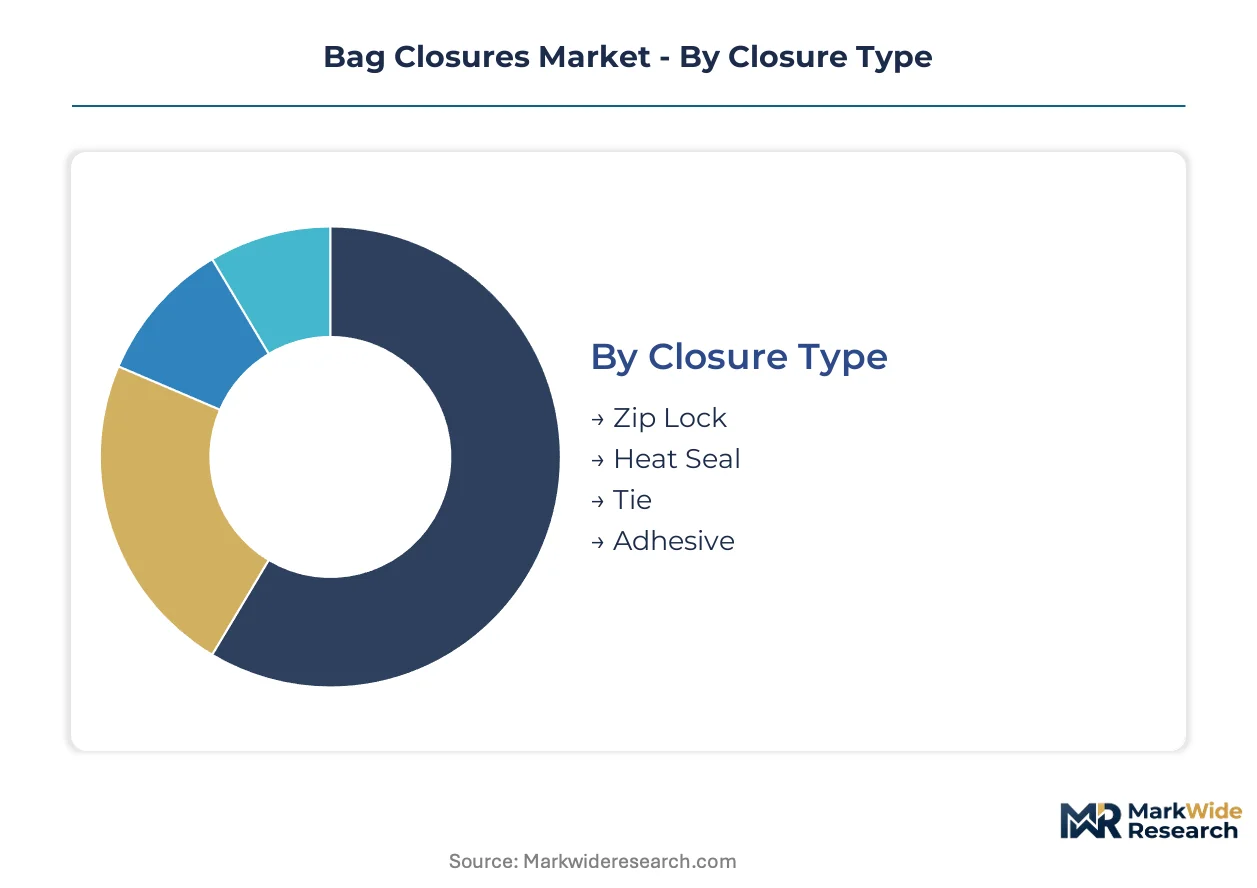
Closure specifications vary dramatically across end-use environments, from moisture-barrier zip-lock mechanisms in fresh produce to sterile heat-seal validation in pharmaceutical supply chains. Material selection and fastening technology determine regulatory compliance pathways and equipment investment requirements.
Closure Type:
Capital intensity clusters around heat-seal and zip-lock formats where precision extrusion and thermoforming equipment dominate facility layouts.
- Zip Lock:Interlocking polymer tracks create resealable barriers through mechanical engagement. Fresh produce packaging in German and Dutch supermarket chains standardizes these formats for cut vegetables and berries requiring repeated consumer access.
- Heat Seal:Hermetic fusion of polymer layers through controlled temperature and pressure delivers validated sterility. Medical device packaging in FDA-regulated US pharmaceutical supply chains mandates this format for terminal sterilization.
- Tie:Twist-wire or plastic clip mechanisms secure bread bags and bulk commodity packaging at minimal unit cost. Bedford Industries anchors North American demand through automated application systems.
- Adhesive:Pressure-sensitive strips compete aggressively in e-commerce apparel shipping where cost-sensitive merchants prioritize throughput over resealability.
Most installed capacity flows through zip-lock formats. Expansion is steepest in heat-seal systems driven by pharmaceutical sterilization mandates.
Material:
Feedstock selection determines processing equipment compatibility and end-of-life recovery pathways.
- Plastic:Polypropylene and polyethylene formulations retain dominant volume share across food packaging. Petrochemical resin price volatility compresses converter margins and destabilizes annual contract structures.
- Biodegradable:PLA and PHA polymers represent the fastest-expanding margin pool as European converters respond to retailer sustainability mandates under France's AGEC Law and similar extended producer responsibility frameworks.
- Paper:Fiber-based alternatives serve European bakery chains seeking mono-material recyclability. Schutte Bagclosures specializes in these formats for Dutch and German retail private-label programs.
- Metal:Twist-tie wires and clip mechanisms anchor cost-efficient bread bag sealing. Limited growth trajectory reflects substitution pressure from plastic alternatives.
Plastic retains the deepest installed base. Biodegradable materials are climbing the fastest as regulatory deadlines approach.
Application:
Performance specifications diverge sharply between shelf-life extension and sterility maintenance.
- Food Packaging:Moisture-barrier and tamper-evident properties dominate supermarket procurement specifications. Resealable formats concentrate in fresh produce and bakery verticals.
- Medical Supplies:Hermetic validation and sterility assurance drive closure selection. FDA and EMA frameworks mandate exhaustive migration testing protocols.
- Retail Products:Brand differentiation through tactile closure quality supports premium positioning in specialty goods.
- Waste Management:Heavy-duty sealing for containment and odor control serves industrial and municipal collection systems.
Food packaging commands the largest equipment footprint. Medical supplies are gaining share fastest through sterilization validation requirements.
End User:
Procurement authority is shifting from converter discretion to direct retailer specification.
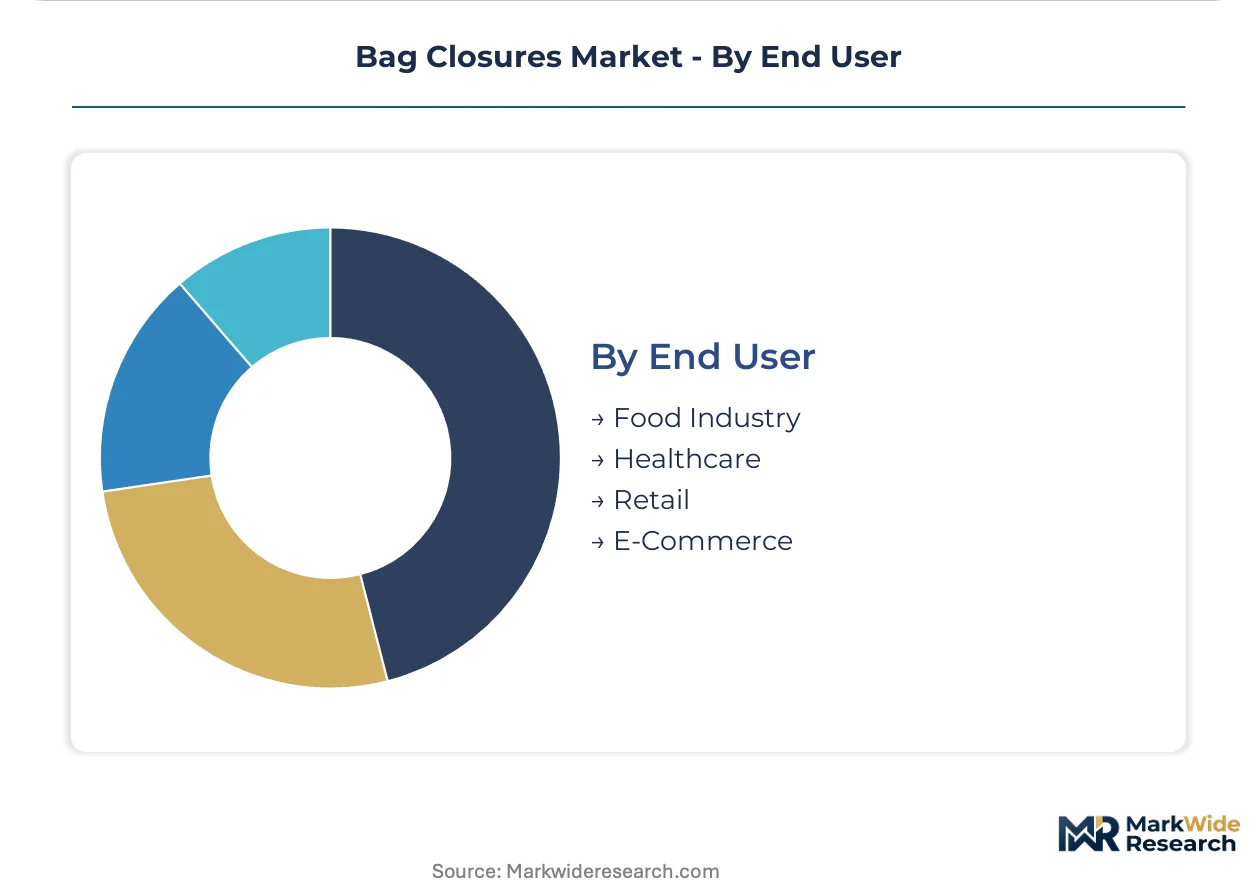
- Food Industry:Bakery and snack manufacturers standardize zip-lock and tie formats through supermarket private-label programs. Category managers now mandate closure performance benchmarks in packaging RFPs.
- Healthcare:Pharmaceutical and medical device manufacturers require heat-seal validation and batch traceability. EMA substance restriction updates accelerate reformulation of plasticizers and slip agents.
- Retail:Supermarket chains compress supplier margins while elevating resealability and tamper-evidence specifications.
- E-Commerce:Apparel and accessory merchants prioritize adhesive strip economics over mechanical closure durability.
Food industry demand represents the deepest capacity utilization. Healthcare procurement is expanding most quickly through regulatory compliance investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled polymer extrusion technicians cluster in Germany's Ruhr Valley and the Netherlands' Brabant region, anchoring European closure manufacturing expertise. Tooling engineers concentrate in China's Yangtze River Delta and Japan's Nagoya industrial corridor. These talent pools shape regional competitive positioning.
Germany
Supermarket private-label bread lines standardize zip-lock formats, driving converter demand. The F-Gas Regulation accelerates biodegradable polymer substitution in flexible packaging. North Rhine-Westphalia hosts specialized extrusion facilities serving Dutch and Belgian retail chains.
United States
Fresh produce packaging mandates from Kroger and Albertsons elevate resealability specifications. FDA food-contact regulations govern closure composition for interstate commerce. Minneapolis-St. Paul anchors automated tie-application system manufacturing for North American bakery networks.
China
E-commerce apparel shipping volumes prioritize adhesive strip economics over mechanical durability. GB standards and SAMR oversight shape domestic packaging safety frameworks. The Pearl River Delta concentrates injection molding capacity for export-oriented zip-lock production.
Netherlands
Bakery chains demand mono-material paper-based alternatives for recyclability compliance. Extended producer responsibility schemes under EU Green Deal timelines pressure material substitution. Eindhoven-Brabant corridor hosts converter R&D facilities specializing in fiber-based closure formats.
India
Organized retail expansion in tier-2 cities creates first-mover positioning for standardized closure suppliers. FSSAI packaging regulations establish food-contact safety benchmarks for domestic brands. Maharashtra's Pune-Nashik industrial belt attracts thermoforming equipment investments from multinational converters.
Bag Closures Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across tiered supplier categories. The vendor base separates between integrated resin-to-closure manufacturers and specialized fastening-component fabricators. Three archetypes dominate: multinational converters with global manufacturing footprints, regional specialists in biodegradable materials, and commodity-scale tie-application equipment suppliers. Consolidation pressure intensifies through supermarket procurement centralization and private-label specification mandates.
Among North American fabricators, Bedford Industries anchors cost-efficient bread-bag tie supply through automated application dominance. Kwik Lok Corporation exemplifies multinational scale with diversified geographic manufacturing presence. Schutte Bagclosures occupies the European specialist tier, representing paper-based alternative development for sustainability-driven retail chains. These three anchors illustrate the competitive spectrum from commodity standardization through premium material innovation.
| Leading Market Players |
|---|
| Plas-Ties, Co. |
| International Plastics Inc. |
| Kwik Lok Corporation |
| Inno Bag Closure |
| ITW Envopak Limited |
| Schutte Bagclosures B.V. |
| Multipack B.V.B.A. |
| Detmold Group |
| Bedford Industries, Inc. |
| Others |
Supply Flow & Price Mechanics
Polypropylene resin volatility cascades through converter pricing tiers as German extrusion facilities pass feedstock swings to European bakery chains while North American tie-application equipment suppliers absorb margin compression through automated throughput gains.
Pricing Analysis
Bundled application-equipment contracts separate from unbundled closure-only supply, with three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on tamper-evidence certification grade and volume scale commitments. Pricing pressure stems from supermarket private-label standardization compressing supplier margins. Discount retailers exhibit highest price sensitivity, while pharmaceutical sterilization validation commands premium tolerance.
Supply Chain Analysis
Skilled polymer extrusion technician scarcity in Germany's Ruhr Valley and the Netherlands' Brabant region constrains European capacity expansion. Manufacturing concentrates in Germany, China, and the United States. Raw material sourcing draws from Saudi Arabian polypropylene, US polyethylene, and Chinese injection-molding equipment. Single-source vulnerability around German precision tooling creates chokepoint exposure. Distribution runs through converter-direct contracts displacing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bag closures market reads as a late-cycle quality story where supermarket mandates for resealability and tamper evidence elevate specification premiums above commodity tier erosion.
For Market Incumbents: Acquire biopolymer processing expertise through targeted talent recruitment in PLA and PHA formulation chemistry. Consolidate position by retrofitting legacy thermoforming lines for compostable materials before mid-tier competitors secure financing. Certification investment in TÜV Austria and BPI standards anchors shelf-access guarantees against regulatory deadline acceleration.
For New Entrants and Emerging Players: Direct-to-retailer specification channels bypass entrenched distributor relationships in North American supermarket chains. White-space concentrates in India's tier-2 organized retail expansion and European mono-material paper-based alternatives for bakery chains. Specialty fastener design for RFID-integrated smart packaging unlocks pharmaceutical track-and-trace procurement.
For Investors and Strategic Acquirers: Consolidation pressure builds where supermarket procurement centralization eliminates sub-scale converter viability. Five-to-ten year viability favors regional specialists with biodegradable material certification depth over commodity-scale resin processors. Watch France's AGEC Law enforcement intensity and similar extended producer responsibility scheme adoptions as inflection signals for mono-material design preference acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Biopolymer Extrusion Capacity Addition | PLA and PHA processing lines in Germany's Ruhr Valley capture F-Gas Regulation-driven substitution demand. |
| Mono-Material Closure Design Investment | Single-stream polypropylene formats align with France's AGEC Law recyclability mandates. |
| RFID Integration Partnership | Smart packaging convergence enables pharmaceutical track-and-trace functionality for high-value goods. |
| Direct-to-Retailer Specification Channel | Bypassing distributor networks captures Kroger and Albertsons fresh produce packaging RFPs. |
| Indian Organized Retail First-Mover Positioning | Tier-2 city penetration captures domestic snack brand standardization before multinational converter entry. |
Methodological Framework
Coverage spans Germany, the United States, China, the Netherlands, and India, with primary inputs from each. Conversations with packaging converter plant managers, supermarket category buyers, pharmaceutical procurement directors, and flexible packaging R&D heads combined with secondary validation from FDA food-contact guidance documents, ECHA REACH substance restriction updates, EU F-Gas Regulation implementation reports, and customs trade flow data. Bottom-up facility capacity assessments and top-down demand modeling triangulate volume estimates.
Granularity-level modeling disaggregates closure type, material composition, application vertical, and end-user procurement authority across the projection horizon. Segmentation dimensions include zip-lock versus heat-seal versus tie versus adhesive formats, plastic versus biodegradable versus paper versus metal substrates, and food packaging versus medical supplies versus retail products versus waste management end-uses. CAGRs derive from installed equipment capacity trajectories and regulatory compliance deadline alignment. Industry-specific inputs encompass supermarket private-label standardization timelines and pharmaceutical sterilization validation protocol adoption curves.
The model assumes a particular technology adoption path; alternative pathways for biopolymer processing equipment deployment would alter the outlook. Forecasts reflect assumptions around F-Gas Regulation phase-down adherence and extended producer responsibility scheme enforcement intensity. Material deviation in regulatory deadline acceleration or petrochemical feedstock price regime shifts warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Brazil Plastic Caps and Closures Market
Caps and Closures
PCR Closures Market
Caps and Closures
Spray Caps Market
Caps and Closures
Handheld Induction Cap Sealers Market
Caps and Closures
Spigot End Cap Market
Caps and Closures
Bi-Injected Snap Hinge Closure Market
Caps and Closures
Spain Plastic Cap and Closure Market
Caps and Closures
PET Dome Lids Market
Caps and Closures
Brush and Dauber Caps Market
Caps and Closures
Twist Caps Market
Caps and Closures
Screw Caps and Closure Market
Caps and Closures
Egypt Plastic Caps and Closures Market
Caps and Closures
Twist Dispensing Closures Market
Caps and Closures
Cork Stoppers Market
Caps and Closures
Dropper Caps Market
Caps and Closures
Reverse Cap Bottles Market