
 China Plastic Caps and Closures Market | 2026-2036
China Plastic Caps and Closures Market Size, Share, and Industry Trends Forecast 2026-2036
China Plastic Caps and Closures Market Outlook
A capital-intensity divergence between automated multi-cavity mold operators and manual-assembly workshops is unwinding competitive stability across China's plastic closure sector. Shantou Jinlei Plastic Industrial leverages vertical integration from resin compounding through finished cap dispatch to sustain margin control in southern China's export-oriented belt. Zhuhai Zhongfu Enterprise anchors its position through dedicated beverage-sector capacity, while Crown Asia Pacific Holdings competes via technical service partnerships with multinational bottlers requiring global specification compliance.
Plastic caps and closures are injection-molded or compression-molded thermoplastic components designed to seal containers against leakage, contamination, and tampering, typically specified by thread geometry, torque-release profile, and sealing-land compression set. Polypropylene dominates material selection for hot-fill and carbonated applications due to its stress-crack resistance and density advantages over polyethylene. Screw caps occupy the largest volume position across beverage and pharmaceutical applications, whereas child-resistant closures represent the fastest-expanding closure-type category as pharmaceutical packaging lines automate compliance with GB standards for senior-friendly yet secure dispensing. Flip top caps concentrate margin pools in personal care, where brand-custom color matching and metallized finishes command specification premiums from multinational cosmetics firms.
SAMR enforces food-contact material compliance through GB 4806 series standards, while MEE oversight of plastic pollution action plans shapes recycled-content mandates and extended-producer-responsibility timelines for packaging converters. NMPA pharmaceutical packaging regulations dictate child-resistant and senior-use effectiveness testing protocols that filter market access for closure suppliers without certified laboratory partnerships. Stakeholders must monitor how provincial-level dual-carbon implementation timelines alter resin sourcing economics and whether GB standard revisions on recycled plastics in food contact will force reformulation investments ahead of enforcement windows.
Market Dynamics
China's dual carbon goals are compressing resin sourcing economics and forcing converters toward lighter-weight polypropylene designs across Guangdong and Zhejiang beverage packaging corridors.
Growth Catalysts
- GB 4806 food-contact compliance:SAMR enforcement of stricter material specifications is pulling pharmaceutical and beverage buyers toward certified suppliers with laboratory partnerships.
- Hot-fill beverage expansion:Polypropylene stress-crack resistance specifications are expanding throughput requirements for tamper-evident formats in Yangtze River Delta manufacturing clusters.
- Child-resistant automation:NMPA effectiveness testing protocols are accelerating line upgrades at pharmaceutical packaging facilities seeking senior-friendly yet secure dispensing solutions.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracking economics and coal-to-olefins capacity swings create margin pressure for non-integrated molders without captive resin supply.
- Mold-making cluster concentration:Yangtze River Delta tooling dependence concentrates supply risk when coastal logistics face weather or policy disruptions.
- Recycled-content technical ceiling:GB standards currently limit post-consumer polypropylene in direct food contact, constraining circular economy positioning against European competitors.
Strategic Opportunities
- Western China manufacturing relocation:Sichuan and Chongqing provinces offer lower energy costs and inland port access for converters serving Central Asian export routes.
- Cosmetics metallized finishes:Brand-custom color matching capabilities command specification premiums from multinational personal care firms seeking differentiation at shelf.
- Extended producer responsibility timelines:MEE plastic pollution action plans will create first-mover advantages for converters with verified recycling partnerships ahead of enforcement windows.
Industry Challenges
- Multi-cavity automation talent scarcity:Mold flow simulation and hot-runner maintenance skills lag demand as manual-assembly workshops attempt capability upgrades.
- Dual-carbon compliance capex burden:Energy-efficient electric presses and renewable power purchase agreements strain balance sheets of mid-tier operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Plastic Caps and Closures Market |
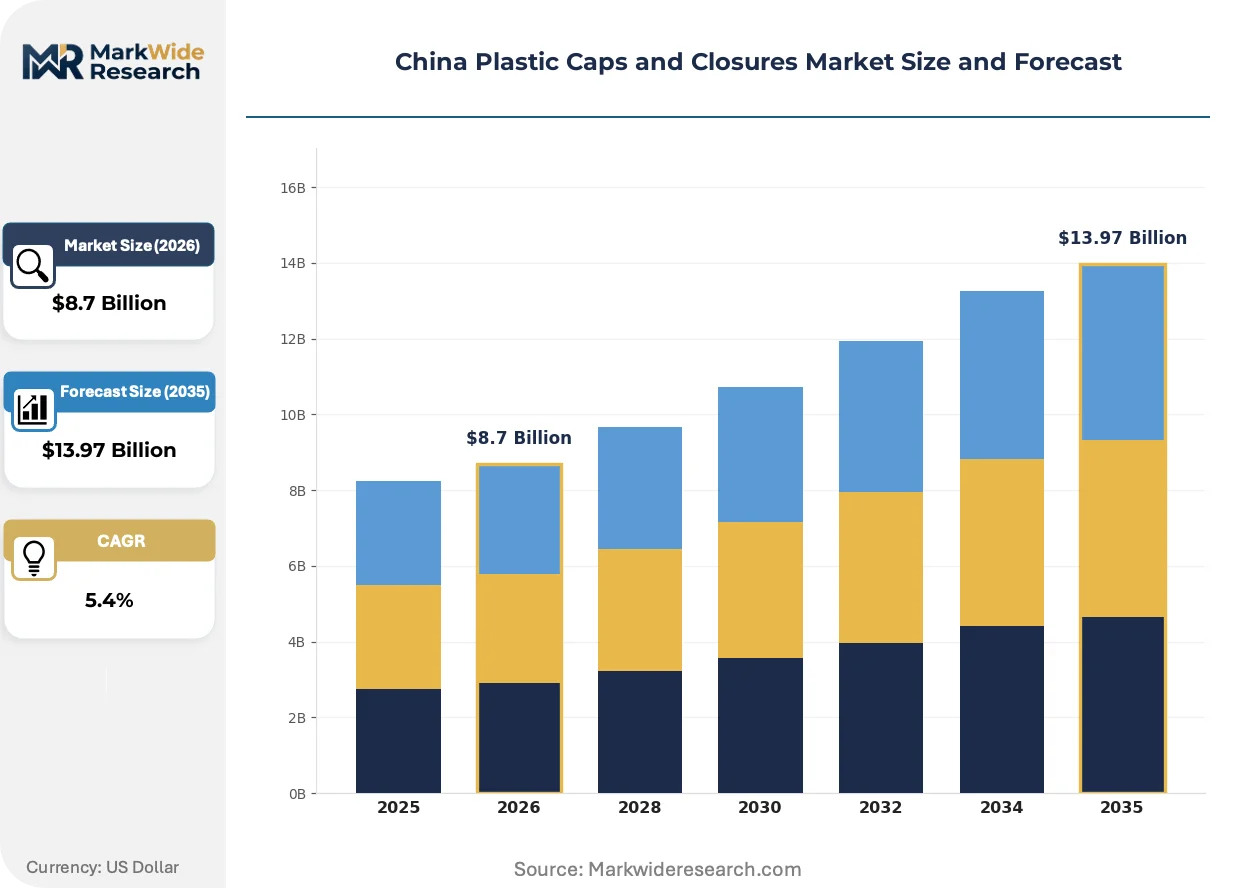
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flip Top Caps, Screw Caps, Snap-On Caps, Spouts Material: Polyethylene, Polypropylene, PVC, ABS Application: Beverage Packaging, Personal Care, Household Products, Pharmaceutical Closure Type: Plug Closures, Tamper Evident Closures, Child Resistant Closures, Twist-Off Closures |
| Companies Covered | Shantou Jinlei Plastic Industrial Co., Ltd., Shangdong Haishengyu Plastic Industry Co. Ltd., Zhuhai Zhongfu Enterprise, Ningbo Kinpack Commodity Co. Ltd, Taizhou Huangyan Baitong Plastic Co. Ltd, Jiangsu Changjiang Lids, Guangzhou Cheers Packing Co., Ltd., Crown Asia Pacific Holdings Ltd., Hicap Closures Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Plastic Caps and Closures Market Strategic Shifts
Material lightweighting and regulatory tightening are converging to reshape specification standards across China's beverage and pharmaceutical closure sectors.
Compression-molded polypropylene is fragmenting traditional injection-molding dominance in carbonated beverage applications. Coca-Cola and Pepsi bottlers in Zhejiang province are specifying compression-molded lightweight designs for 1881 PCO neck finishes. The technology is fragmenting equipment investment patterns as converters choose between retrofitting existing injection assets or committing to dedicated compression lines.
MEE oversight of plastic pollution action plans is tightening recycled-content mandates and extended-producer-responsibility timelines for packaging converters. Industrial consequence includes forced reformulation investments and third-party recycling partnership requirements. Pharmaceutical and food-contact segments are most affected, with suppliers accelerating laboratory certification for post-industrial regrind acceptance protocols.
Direct mill relationships are displacing distributor intermediaries among large FMCG buyers seeking lot-traceability and carbon-footprint documentation. Multinational cosmetics firms and beverage bottlers now require resin-grade certificates and mold-cavity identification codes. This pattern is most visible in Guangdong province, where export-oriented manufacturers face European retailer compliance audits.
China Plastic Caps and Closures Market Segmentation
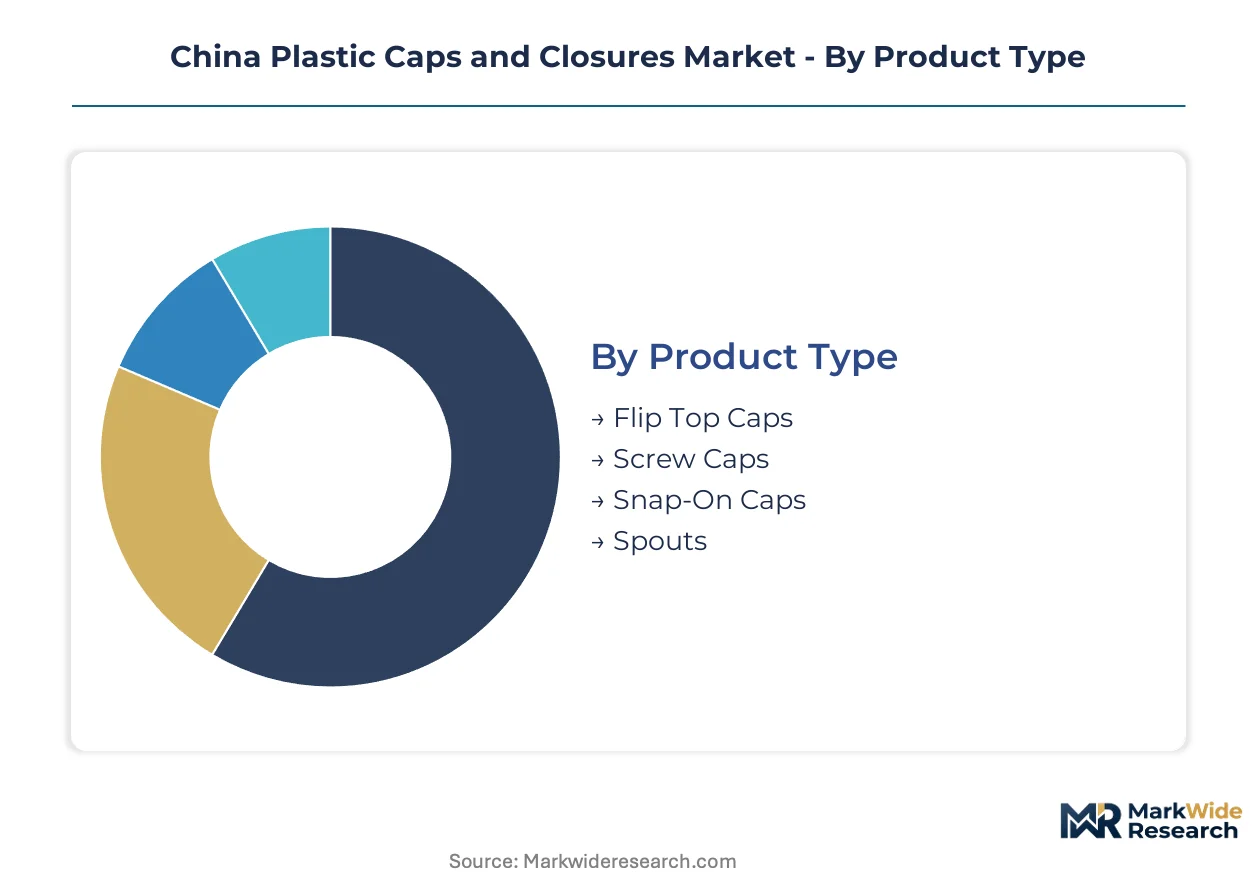
Segmentation in China's plastic caps and closures market reflects divergent technical specifications across regulatory regimes. SAMR food-contact enforcement and NMPA pharmaceutical standards create non-overlapping certification requirements that reshape supplier capabilities by product category.
Product Type:
Regulatory differentiation separates thread-dependent designs from snap-fit formats under GB 4806 torque-release testing protocols.
- Screw Caps:Threaded thermoplastic components with specified torque-release profiles seal carbonated and hot-fill beverage containers. Guangdong bottlers specify 1881 PCO neck finishes for tamper-evident compliance, driving compression-molded lightweight polypropylene adoption.
- Flip Top Caps:Hinged single-piece designs with living-hinge flexure specifications dominate personal care dispensing. Multinational cosmetics firms in the Yangtze River Delta mandate brand-custom color matching and metallized finishes, commanding specification premiums.
- Snap-On Caps:Interference-fit closures without threads serve household product containers where resealability is secondary to cost minimization.
- Spouts:Directional-flow attachments concentrate in liquid detergent and cooking oil packaging lines.
Screw caps handle the majority of throughput; flip top caps are expanding most quickly on share.
Material:
Cost tier stratification aligns resin selection with application thermal and chemical stress requirements.
- Polypropylene:Semi-crystalline thermoplastic with stress-crack resistance and density advantages serves hot-fill and carbonated beverage applications. Zhejiang province converters favor homopolymer grades for 1881 PCO lightweight designs under dual-carbon material reduction mandates.
- Polyethylene:Lower-density option with broader chemical compatibility supplies household and personal care segments where thermal loading is moderate.
- PVC:Rigid formulation with barrier properties persists in specific pharmaceutical blister pack lidding applications.
- ABS:Engineering polymer with surface finish quality supports premium cosmetic closures requiring metallized coating adhesion.
Polypropylene commands the dominant volume position; ABS is climbing the fastest as cosmetics brands upgrade packaging aesthetics.
Application:
Customer type concentration creates divergent procurement patterns between multinational FMCG and domestic manufacturers.
- Beverage Packaging:Carbonated soft drink and bottled water lines across Guangdong and Zhejiang provinces drive tamper-evident screw cap specifications with throughput requirements exceeding 120,000 units per hour.
- Pharmaceutical:Oral solid dose and liquid packaging lines automate NMPA-compliant child-resistant and senior-friendly dispensing systems.
- Personal Care:Shampoo and conditioner bottles specify flip top caps with brand-differentiated actuation forces and color consistency.
- Household Products:Detergent and cleaner containers prioritize cost-optimized snap-on or spout closures with minimal reseal cycles.
Beverage packaging absorbs the largest resin tonnage; pharmaceutical is gaining share fastest on automation investment.
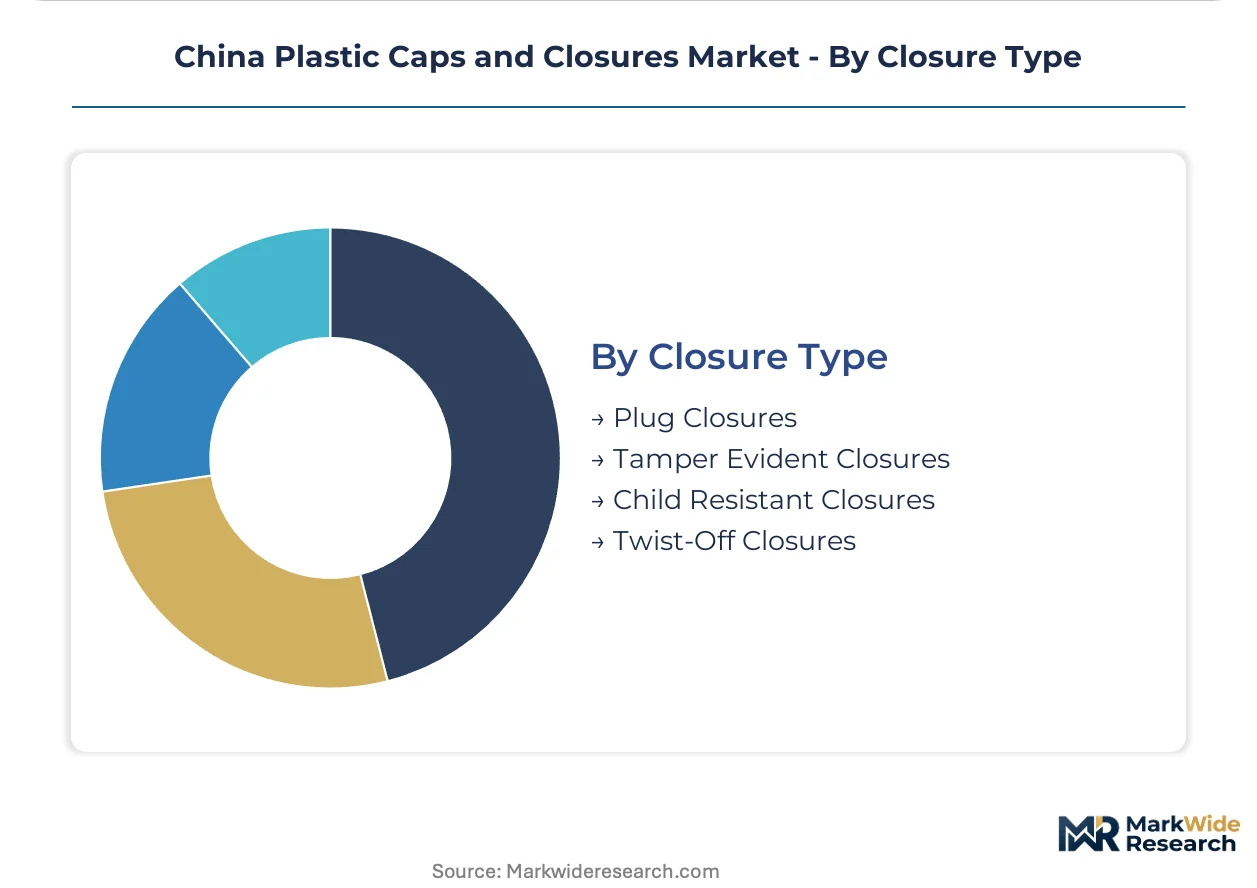
Closure Type:
Supply concentration in Yangtze River Delta mold-making clusters favors converters with certified laboratory partnerships for effectiveness testing.
- Tamper Evident Closures:Break-band or shrink-sleeve integrated designs provide visible post-manufacture intrusion indication. SAMR GB 4806 enforcement pulls beverage buyers toward certified suppliers with lot-traceability documentation.
- Child Resistant Closures:Dual-action or push-and-turn mechanisms meeting NMPA effectiveness protocols filter market access for pharmaceutical suppliers without testing laboratory partnerships.
- Twist-Off Closures:Metal-lug-compatible plastic designs serve preserved food segments with vacuum-seal integrity requirements.
- Plug Closures:Simple interference-fit stoppers concentrate in non-regulated industrial and sample vial applications.
Tamper evident closures process the highest unit volumes; child resistant closures show the steepest expansion trajectory on pharmaceutical line upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong province commands specification premiums from export-oriented beverage bottlers, while Zhejiang converters absorb margin compression from propylene feedstock volatility. This pricing-power asymmetry reshapes investment flows across China's plastic closure manufacturing belt.
Yangtze River Delta
Shanghai and Jiangsu province anchor pharmaceutical and cosmetics packaging demand, with NMPA effectiveness testing protocols filtering supplier access. SAMR GB 4806 enforcement pulls buyers toward certified laboratories in Suzhou and Ningbo mold-making clusters, where multi-cavity automation talent scarcity constrains throughput expansion.
Pearl River Delta
Guangdong's beverage bottlers specify tamper-evident 1881 PCO neck finishes for carbonated soft drink lines exceeding 120,000 units per hour. MEE plastic pollution action plans tighten recycled-content mandates for export manufacturers facing European retailer compliance audits in Shenzhen and Dongguan industrial zones.
Shandong Peninsula
Qingdao and Yantai serve northern China's household product and preserved food segments with twist-off closure specifications. Provincial dual-carbon implementation timelines alter resin sourcing economics for converters without captive naphtha-cracking supply, compressing margins for mid-tier operators.
Sichuan-Chongqing
Chengdu and Chongqing offer lower energy costs and inland port access for converters targeting Central Asian export routes. Western relocation strategies accelerate as coastal logistics face weather disruptions and Yangtze River Delta tooling dependence concentrates supply risk.
Zhejiang Province
Hangzhou and Ningbo concentrate hot-fill beverage expansion with polypropylene stress-crack resistance specifications. Compression-molded lightweight designs fragment equipment investment patterns as converters choose between retrofitting injection assets or committing to dedicated compression lines.
China Plastic Caps and Closures Market Competitive Environment
Concentration sits with vertically integrated resin compounders and dedicated beverage-sector specialists across southern and eastern China. The market structure fragments between automated multi-cavity mold operators and manual-assembly workshops attempting capability upgrades. Three archetypes dominate: captive resin suppliers with backward integration into compounding, export-oriented fabricators with metallized finish capabilities, and multinational technical service partners. Capacity expansion and laboratory certification partnerships represent the dominant competitive moves as GB standard enforcement tightens.
Within the vertically integrated tier, Shantou Jinlei Plastic Industrial Co., Ltd. exemplifies margin control through captive resin supply from compounding through finished cap dispatch. Zhuhai Zhongfu Enterprise occupies a position among beverage-sector specialists with dedicated capacity for carbonated and hot-fill applications. Crown Asia Pacific Holdings Ltd. represents the technical service archetype, anchoring partnerships with multinational bottlers requiring global specification compliance and lot-traceability documentation.
| Leading Market Players |
|---|
| Shantou Jinlei Plastic Industrial Co., Ltd. |
| Shangdong Haishengyu Plastic Industry Co. Ltd. |
| Zhuhai Zhongfu Enterprise |
| Ningbo Kinpack Commodity Co. Ltd |
| Taizhou Huangyan Baitong Plastic Co. Ltd |
| Jiangsu Changjiang Lids |
| Guangzhou Cheers Packing Co., Ltd. |
| Crown Asia Pacific Holdings Ltd. |
| Hicap Closures Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Long-term resin offtake agreements between Yangtze River Delta molders and Sinopec or PetroChina refineries lock in polypropylene supply access while capping feedstock price volatility exposure for converters serving GB 4806-certified beverage packaging lines. These contracts bind annual volume commitments to naphtha-cracking economics, creating divergent margin profiles between integrated compounders and spot-market-dependent workshops across Guangdong and Zhejiang provinces.
Pricing Analysis
Configured-to-order pricing for metallized cosmetic closures commands spreads of 40-60% above standard injection-molded beverage caps, with brand-custom color matching and lot-traceability documentation driving premium capture. Three-tier pricing structure across premium, standard, and economy levels separates NMPA-certified pharmaceutical suppliers from uncertified competitors and manual-assembly workshops. Cost compression in standard-grade polypropylene screw caps is intensifying because propylene feedstock volatility and dual-carbon compliance capex burdens squeeze mid-tier operators without captive resin supply. Domestic FMCG manufacturers exhibit highest price sensitivity, while multinational cosmetics firms and pharmaceutical buyers prioritize certification grade over unit cost.
Supply Chain Analysis
Just-in-time resin delivery dominates beverage packaging corridors, though strategic polypropylene stockpiling accelerates among converters anticipating MEE enforcement windows for recycled-content mandates. Geographic supply concentration centers on China, South Korea, and Singapore, with homopolymer grades from Korean refiners serving premium hot-fill specifications. Raw material dependencies rest on naphtha-derived propylene, imported catalyst systems for polymerization, and precision mold steel from Japanese suppliers. Single-source vulnerability concentrates in Yangtze River Delta mold-making clusters, where coastal logistics disruptions propagate through lead-time compression. Distribution feeds from converter direct dispatch to branded FMCG filling lines, bypassing distributor intermediaries for lot-traceability compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's plastic caps and closures sector faces high-growth disruption as compression-molded lightweight designs fragment equipment investment patterns and MEE plastic pollution action plans force reformulation timelines ahead of GB standard revisions.
For Market Incumbents: Shield margin positions by accelerating captive resin compounding capacity in southern China and securing NMPA laboratory partnerships before effectiveness testing protocols tighten pharmaceutical market access. Dual-carbon compliance capex burdens threaten mid-tier operators without renewable power purchase agreements or energy-efficient electric press fleets. For New Entrants and Emerging Players: Anchor in Sichuan-Chongqing manufacturing relocation corridors, where lower energy costs and inland port access create white-space opportunities for converters serving Central Asian export routes. Western China's underpenetrated pharmaceutical packaging automation segment offers penetrable entry points for child-resistant closure specialists with certified testing capabilities. For Investors and Strategic Acquirers: Dedicated beverage-sector specialists with compression-molded lightweight capabilities and 1881 PCO neck finish specifications represent priority acquisition targets as Zhejiang bottlers retrofit injection assets. Long-term viability hinges on verified recycling partnerships ahead of extended producer responsibility enforcement. Watch for provincial dual-carbon implementation timeline acceleration as inflection indicator for resin sourcing economics disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polypropylene supply insulates margin control against naphtha-cracking volatility in Guangdong export belt. |
| NMPA Laboratory Certification Partnership | Certified effectiveness testing protocols filter market access for pharmaceutical child-resistant closure suppliers. |
| Compression-Molding Line Investment | Dedicated lightweight equipment captures Zhejiang bottler specifications for 1881 PCO carbonated beverage formats. |
| Western China Manufacturing Relocation | Sichuan-Chongqing energy cost advantages and inland port access target Central Asian export route demand. |
| Verified Recycling Partnership Development | Third-party post-industrial regrind acceptance protocols position converters ahead of MEE extended producer responsibility enforcement. |
Study Parameters
Cross-validation between primary interviews with mold-making engineers, procurement leads at multinational beverage bottlers, pharmaceutical packaging line managers, and SAMR regulatory consultants anchors the qualitative findings against secondary validation from customs trade data, GB standards documentation, NMPA filing records, and provincial dual-carbon implementation notices. Bottom-up resin consumption estimates triangulate against top-down packaging machinery installation data across the analysis window.
Sensitivity analysis around propylene feedstock price bands and enforcement timeline scenarios shapes the analytical framework across product type, material grade, application sector, and closure format segmentation dimensions. CAGRs derive from modeled unit volume trajectories adjusted for line automation rates and lightweighting penetration curves, with pharmaceutical automation investment and beverage throughput expansion as key forecast inputs throughout the projection horizon.
Material uncertainties — SAMR GB 4806 revision timing, MEE recycled-content mandate enforcement windows, and naphtha-cracking capacity swings — sit outside the modeled envelope. Forecasts reflect assumptions about laboratory certification partnership formation rates and compression-molding equipment adoption curves. Revision becomes warranted when provincial dual-carbon implementation timeline acceleration crosses thresholds that alter resin sourcing economics for non-integrated converters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Molded Fiber Pulp Cap Market
Caps and Closures
Ribbed Closures Market
Caps and Closures
Crown Caps Market
Caps and Closures
Brush Caps Market
Caps and Closures
Foam Cap Liners Market
Caps and Closures
Middle East and Africa Plastic Caps and Closures Market
Caps and Closures
Plastic Caps and Closure Market
Caps and Closures
Brazil Plastic Caps and Closures Market
Caps and Closures
Latin America Metal Caps and Closures Market
Caps and Closures
Tear-Tab Lids Market
Caps and Closures
Germany Plastic Caps and Closures Market
Caps and Closures
Low Profile Compact System Closures Market
Caps and Closures
Indonesia Plastic Caps and Closures Market
Caps and Closures
Heat Shrink Bands Market
Caps and Closures
Hinged Dual Flap Caps Market
Caps and Closures
Latin America Plastic Caps and Closure Market