
 Lug Caps Market | 2026-2036
Lug Caps Market Size, Share, and Industry Trends Forecast 2026-2036
Lug Caps Market Foresight
Pharmaceutical-grade tamper evidence is reorganizing competitive priorities across the lug caps landscape. Aptar Group Inc. leverages its R&D intensity to dominate high-barrier closure portfolios for regulated drug packaging. Silgan Holdings Inc. anchors North American supply through backward integration into resin compounding and metal forming. Guala Closures Group specializes in premium spirits applications where anti-counterfeiting features command sustained margin premiums.
Lug caps are threaded closures with interrupted helical segments (typically three or four lugs) that engage corresponding bayonet-style threads on container necks, requiring only a quarter-turn for secure sealing; they are injection-molded from polypropylene or compression-molded from tinplate and aluminum to achieve precise torque specifications and hermetic integrity. Plastic lug closures lead volume due to cost scalability in beverage and food applications, while metal variants retain structural importance in carbonated soft drinks and retort-processed goods where thermal stability and pressure resistance are critical. The aftermarket provider channel is expanding fastest as e-commerce parts platforms reduce minimum order quantities and compress lead times for replacement closure sourcing.
FDA 21 CFR regulations govern lug cap materials in direct food contact, while EU REACH and F-Gas Regulation constrain fluoropolymer liner chemistries and propellant-based sealing technologies. ISO 9001 and ISO 15378 certification requirements are tightening market access for suppliers serving pharmaceutical OEMs. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to absorb compliance costs or pass them through tiered supplier contracts.
Market Dynamics
Beverage packaging lines are converting to tamper-evident lug closures at scale, driven by EU Single-Use Plastics Directive mandates and downstream brand owner liability concerns. Material transitions toward recyclable and bio-based alternatives are compressing incumbent resin supply chains while creating qualification bottlenecks for converters.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandatory recyclability targets are forcing beverage brand owners to specify mono-material polypropylene lug closures, accelerating contract migrations away from multi-layer barrier designs.
- Pharmaceutical serialization mandates:Track-and-trace regulations in regulated drug markets are expanding demand for tamper-evident lug closures with integrated RFID or QR authentication features.
- German precision manufacturing clusters:Concentrated tooling expertise around Stuttgart and Nuremberg enables rapid prototyping of high-tolerance lug geometries for premium export markets.
Market Restraints
- Polypropylene resin price volatility:Feedstock exposure to propylene monomer fluctuations compresses converter margins and complicates long-term contract pricing.
- Fluoropolymer liner constraints:EU F-Gas Regulation and REACH restrictions on perfluorinated chemistries are eliminating conventional barrier solutions for carbonated applications.
- Aluminum tariff exposure:Trade policy uncertainty around Section 232 and retaliatory duties disrupts metal lug cap cost structures for North American beverage canners.
Strategic Opportunities
- Bio-based polypropylene scale-up:Mass balance-certified resins from Neste and SABIC supply chains offer brand owners compliance pathways under EU Green Deal circular economy targets.
- E-commerce aftermarket platforms:Digital parts marketplaces are reducing minimum order quantities and compressing lead times for replacement closure sourcing in craft beverage segments.
- India PLI scheme for packaging:Domestic manufacturing incentives are attracting closure system investments to serve subcontinent beverage growth with localized supply.
Industry Challenges
- ISO 15378 certification timelines:Pharmaceutical OEM qualification cycles for GMP-compliant closure manufacturing extend 18-24 months, freezing out mid-tier converters.
- Legacy injection mold retrofit costs:Converting existing tooling for thin-wall recyclable designs requires capital outlays that strain privately held regional suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lug Caps Market |
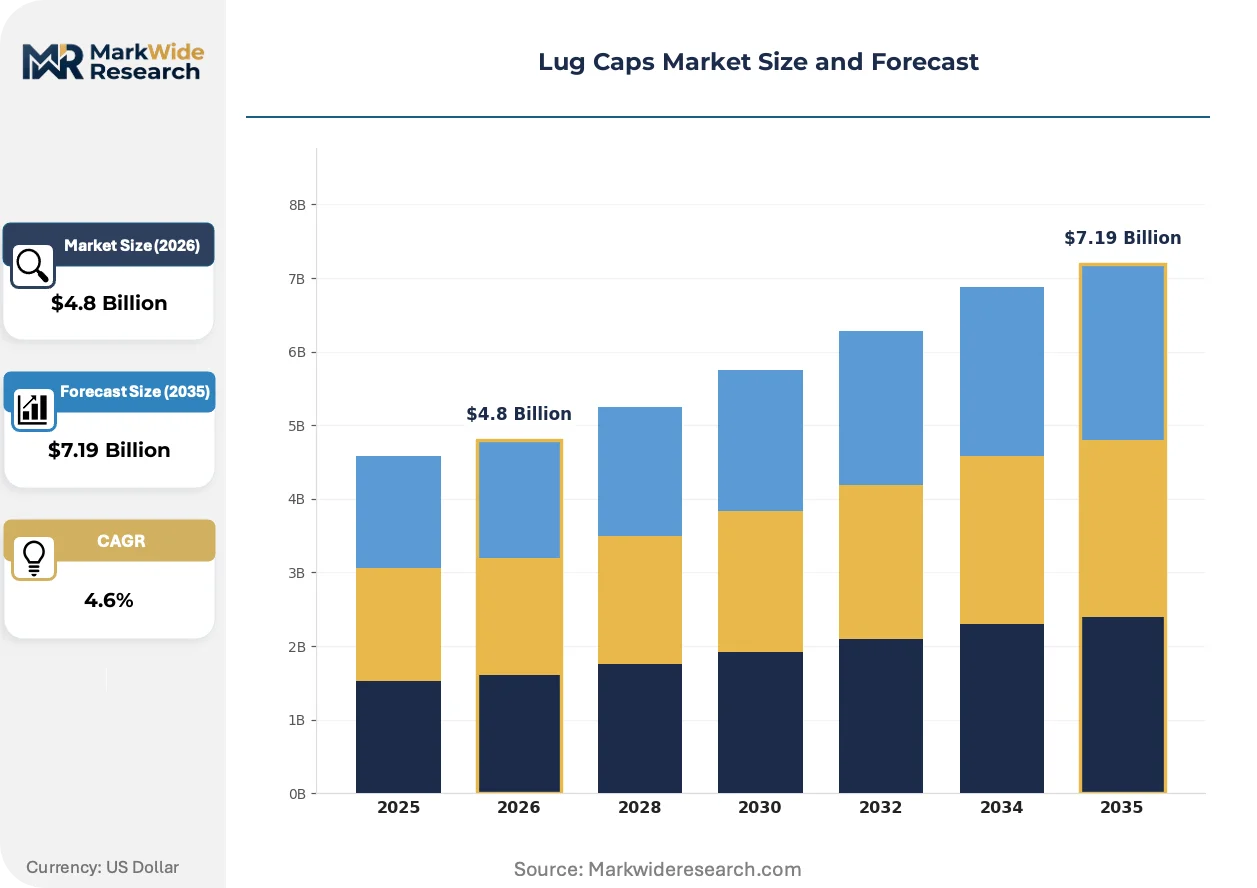
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Metal, Rubber, Composites Application: Automotive, Aerospace, Industrial Equipment, Heavy Machinery End User: Manufacturers, Distributors, OEMs, Aftermarket Providers Distribution Channel: Online Retail, Wholesale, Direct Sales, Others |
| Companies Covered | Aptar Group Inc., Ball Corporation, Silgan Holdings Inc., Guala Closures Group, Global Closure Systems, Amcor Ltd, Berry Global, Inc., BERICAP GmbH & Co. KG, Crown Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lug Caps Market Shifts & Advancements
Material science breakthroughs and regulatory compliance architectures are restructuring competitive advantage in lug closure systems. Digital integration and supply chain transparency requirements are elevating specification complexity beyond commodity manufacturing capabilities.
Mono-material polypropylene designs with engineered venting channels are supplanting multi-component barrier closures in carbonated soft drink applications. Major beverage brand owners in Germany and the United States are mandating these conversions by 2027 to meet recyclability certifications. The shift is compressing demand for ethylene vinyl alcohol coextrusion liners and fluoropolymer seals while expanding specification work for resin rheology optimization.
EU F-Gas Regulation amendments are constraining propellant-based sealing technologies and perfluorinated liner chemistries for food contact applications. Closure converters serving European carbonated beverage markets are accelerating qualification of mechanical venting alternatives and plasma-treated surface barriers. Metal lug cap suppliers with in-house polymer compounding capabilities are capturing specification authority previously held by liner material specialists.
Brand owner sustainability scorecards are compressing supplier qualification cycles and unbundling after-sales technical service from volume contracts. Procurement teams at multinational beverage corporations are consolidating closure sourcing through approved vendor lists with embedded carbon accounting. German and French retail chains are driving this pattern fastest, requiring cradle-to-gate lifecycle data for shelf placement decisions.
Lug Caps Market Segmentation
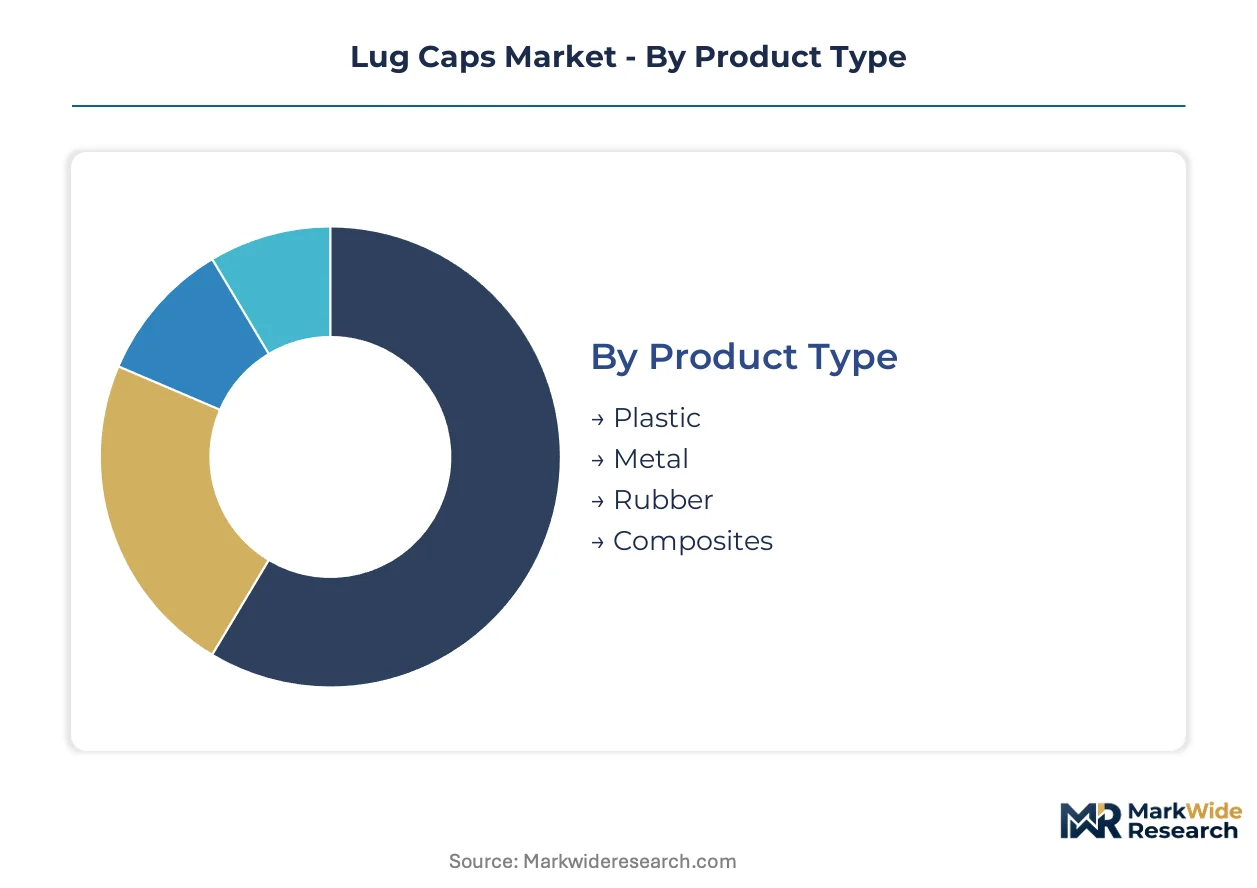
Lug caps serve divergent functional requirements across beverage containment, pharmaceutical sealing, and industrial fluid systems. Segmentation reveals where material science investments concentrate and which substitution vectors threaten incumbent technologies.
Product Type:
Polypropylene faces the most acute substitution pressure from bio-based alternatives under EU Green Deal compliance mandates, while metal formats confront aluminum tariff volatility and fluoropolymer liner restrictions.
- Plastic:Injection-molded polypropylene dominates beverage and food applications through cost scalability and mono-material recyclability. German precision tooling clusters around Stuttgart supply high-tolerance venting geometries for carbonated soft drink brand owners.
- Metal:Compression-molded tinplate and aluminum deliver thermal stability for retort-processed goods and pressure resistance in carbonated applications. EU F-Gas Regulation constraints on perfluorinated liners are forcing mechanical venting redesigns by converters with in-house polymer compounding.
- Rubber:Elastomeric sealing elements provide compression-set recovery for pharmaceutical vial closures requiring hermetic integrity validation.
- Composites:Hybrid material structures combine structural rigidity with barrier performance for specialty chemical containment.
Plastic lug closures anchor the volume base while bio-based polypropylene variants gain share at the steepest rate.
Application:
Cost tier stratification separates commodity beverage sealing from precision-engineered pharmaceutical and aerospace specifications.
- Automotive:Fluid system closures for coolant and brake reservoirs require chemical resistance to glycol ethers and synthetic hydrocarbons. Tier 1 suppliers in Germany specify torque-consistent lug geometries for assembly line automation.
- Aerospace:FAA-compliant pressure vessel sealing demands traceable material certifications and failure-mode documentation. Lightweight aluminum lug caps with redundant locking features serve hydraulic system redundancy requirements.
- Industrial Equipment:Process machinery lubrication systems use standardized thread forms for maintenance interchangeability.
- Heavy Machinery:Mining and construction equipment sealing faces abrasive contamination and extreme temperature cycling.
Automotive applications generate the highest unit volumes while aerospace specifications command the steepest margin premiums.
End User:
Customer type determines procurement sophistication — OEMs impose qualification cycles that freeze out mid-tier converters, while aftermarket channels compress lead times through digital platforms.
- Manufacturers:Captive closure production for integrated beverage bottling operations. Coca-Cola Europacific Partners and similar operators specify mono-material designs for EPR compliance.
- Distributors:Inventory-holding intermediaries serving fragmented craft beverage and regional food processors with consolidated SKU portfolios.
- OEMs:Pharmaceutical packaging line builders require ISO 15378 certification and 18-24 month qualification timelines for GMP-compliant supply.
- Aftermarket Providers:E-commerce parts platforms reduce minimum order quantities for replacement closure sourcing in craft brewing segments.
Aftermarket providers are expanding most quickly as digital procurement penetrates long-tail demand, while OEMs concentrate purchasing power through approved vendor lists.
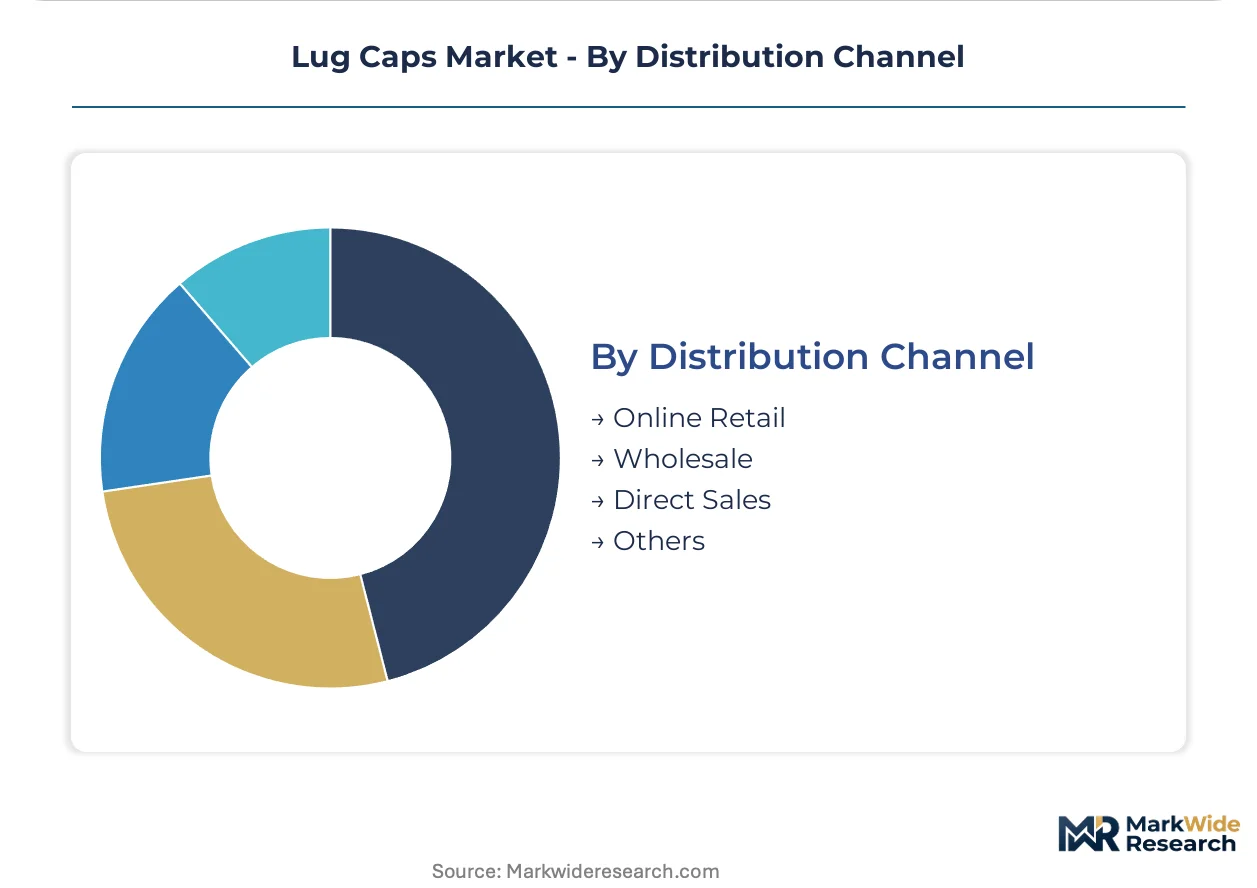
Distribution Channel:
Volume scale separates direct contract manufacturing from fragmented retail access, with online channels capturing specification authority previously held by field sales organizations.
- Online Retail:Digital marketplaces enable small-batch closure sourcing with compressed lead times. Amazon Business and specialty packaging platforms serve craft beverage startups.
- Wholesale:Distributor networks aggregate demand from regional converters and private-label brand owners.
- Direct Sales:Technical field organizations manage multinational beverage corporation contracts with embedded carbon accounting requirements.
- Others:Agent-mediated procurement for emerging market entry where regulatory navigation requires local expertise.
Direct sales retains the largest contract value concentration while online retail climbs the fastest as e-commerce penetrates B2B packaging procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision tooling clusters around Stuttgart and Nuremberg dominate high-tolerance lug cap manufacturing for premium export markets. Closure converters concentrate in industrial corridors with integrated resin compounding and beverage bottling infrastructure. Regulatory fragmentation across major economies forces multi-site qualification strategies for multinational suppliers.
Germany
Beverage brand owners in the Rhine-Main and Stuttgart regions mandate mono-material polypropylene closures for EU Green Deal compliance. The F-Gas Regulation eliminates perfluorinated liner chemistries, accelerating mechanical venting redesigns. Precision engineering clusters around Nuremberg supply rapid prototyping capabilities for carbonated soft drink applications.
United States
Craft beverage startups and regional canners drive aftermarket demand through digital procurement platforms. FDA 21 CFR governs direct food contact materials while Section 232 aluminum tariffs disrupt metal lug cap cost structures. Midwest injection molding corridors serve Coca-Cola Europacific Partners and similar integrated bottling operations.
China
Domestic beverage growth and packaging localization attract closure system investments under dual carbon goals. MIIT standards and GB regulations constrain imported resin specifications for food contact applications. Yangtze River Delta manufacturing hubs scale thin-wall recyclable designs for carbonated soft drink exports.
India
The PLI scheme for packaging incentivizes domestic manufacturing to serve subcontinent beverage expansion. FSSAI regulations govern food contact closures while state-level industrial policies attract converter investments. Maharashtra and Gujarat host emerging precision tooling capabilities for pharmaceutical-grade tamper-evident specifications.
Japan
Pharmaceutical serialization mandates expand demand for RFID-integrated lug closures in regulated drug markets. METI circular economy targets pressure brand owners toward mass balance-certified bio-based polypropylene. Kanto region packaging line builders require ISO 15378 certification with 18-24 month qualification timelines.
Lug Caps Market Competitive Landscape
Concentration sits with diversified packaging conglomerates and specialized closure engineers. Tier 1 suppliers anchor multinational beverage contracts through backward integration into resin compounding and metal forming. Three archetypes dominate: precision-engineered specialists serving pharmaceutical and premium spirits segments; scale-driven converters optimizing commodity beverage volumes; and integrated packaging conglomerates offering captive closure supply to affiliated bottling operations. Competitive moves center on portfolio diversification into tamper-evident authentication features and geographic expansion through India PLI scheme manufacturing.
Among diversified packaging conglomerates, Aptar Group Inc., Silgan Holdings Inc., and BERICAP GmbH & Co. KG exemplify contrasting strategic positions. Aptar represents the R&D-intensive archetype targeting pharmaceutical-grade barrier portfolios. Silgan occupies a position anchored in North American supply chain integration. BERICAP sits within the European precision-engineering tradition serving carbonated beverage brand owners with mono-material recyclable designs.
| Leading Market Players |
|---|
| Aptar Group Inc. |
| Ball Corporation |
| Silgan Holdings Inc. |
| Guala Closures Group |
| Global Closure Systems |
| Amcor Ltd |
| Berry Global, Inc. |
| BERICAP GmbH & Co. KG |
| Crown Holdings Inc. |
| Others |
Supply & Pricing Matrix
Injection molding capacity utilization above 85 percent in German precision tooling clusters concentrates pricing power among converters with mono-material polypropylene qualification. Scale economies in Stuttgart and Nuremberg corridors establish price floors that regional suppliers cannot match without capital-intensive mold retrofits.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure by eliminating conventional fluoropolymer liner chemistries and forcing mechanical venting redesign investments. Three-tier pricing structure across pharmaceutical-grade, beverage premium, and commodity economy levels separates ISO 15378-certified supply from standard food-grade and generic aftermarket tiers. Cost compression in commodity polypropylene closures is intensifying because propylene monomer volatility compresses converter margins. Craft beverage startups exhibit highest price sensitivity through digital procurement platforms, while pharmaceutical OEMs prioritize certification compliance over unit cost.
Supply Chain Analysis
Inventory lead times for precision-engineered lug geometries stretch 12-16 weeks due to concentrated tooling fabrication in German manufacturing clusters. Supply draws from Germany, China, and India as dominant production geographies, with resin compounding tethered to propylene feedstock markets in the Middle East and North America. Raw material dependencies center on polypropylene resin, aluminum coil stock, and tinplate substrates. Single-source vulnerability in fluoropolymer liner alternatives creates qualification bottlenecks for carbonated beverage converters. Distribution runs through direct technical sales for multinational contracts and e-commerce platforms for fragmented aftermarket demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Beverage brand owner consolidation through approved vendor lists with embedded carbon accounting has shifted procurement leverage toward buyers with volume concentration. Multinational corporations now unbundle technical service from volume contracts, compressing supplier margins.
For Market Incumbents: Secure backward integration into mass balance-certified bio-based polypropylene resin compounding to defend margin position against Neste and SABIC supply chain entrants. Anchor certification investments in ISO 15378 pharmaceutical compliance to freeze out mid-tier converters facing 18-24 month qualification timelines. Prioritize rapid prototyping capabilities in Stuttgart-Nuremberg corridors to maintain specification authority over mono-material recyclable designs. For New Entrants and Emerging Players: Anchor in India PLI scheme manufacturing incentives to serve subcontinent beverage expansion with localized supply and avoid EU F-Gas Regulation compliance costs. Target craft beverage aftermarket segments through digital parts platforms where minimum order quantity compression reduces incumbent scale advantages. Pursue pharmaceutical serialization mandate opportunities in Japan and European markets with RFID-integrated tamper-evident specifications. For Investors and Strategic Acquirers: Precision tooling specialists with pharmaceutical-grade GMP capabilities represent the most defensible acquisition archetype as ISO 15378 certification timelines create moats around high-margin segments. Long-term viability hinges on exposure to bio-based material transitions and circular economy compliance rather than commodity volume scale. Monitor EU extended producer responsibility framework implementation as the inflection signal for contract migration toward mass balance-certified supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Resin Compounding | Mass balance certification from Neste supply chains secures EU Green Deal compliance pathways for beverage contracts. |
| ISO 15378 Pharmaceutical Certification Investment | GMP-compliant manufacturing qualification freezes out mid-tier converters and commands premium pricing in regulated drug packaging. |
| Mechanical Venting Redesign for F-Gas Compliance | Plasma-treated surface barriers replace perfluorinated liners for carbonated applications under EU REACH constraints. |
| India PLI Scheme Manufacturing Localization | Domestic production incentives attract closure system investments to serve subcontinent beverage growth with tariff-advantaged supply. |
| E-Commerce Aftermarket Platform Integration | Digital procurement penetration reduces minimum order quantities and compresses lead times for craft beverage replacement sourcing. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with beverage packaging line engineers, pharmaceutical OEM procurement managers, closure converter plant managers, and aftermarket platform operators. Secondary validation drew from EU F-Gas Regulation filings, FDA 21 CFR food contact guidance, SEC 10-K disclosures by diversified packaging conglomerates, and customs trade data for polypropylene resin and aluminum coil imports. Bottom-up volume estimates from application-level demand curves were triangulated against top-down market size assessments from industry association aggregates.
Across the analysis window, the forecasting framework modeled segmentation dimensions including material type, end-use application, customer procurement archetype, and regional regulatory cluster. CAGRs were derived from regression-weighted historical trajectory analysis with forward adjustment for policy-driven inflection points. Industry-specific inputs incorporated propylene monomer price elasticity coefficients and pharmaceutical serialization mandate implementation schedules.
Decision-makers should treat outputs as directional under assumptions of sustained EU Single-Use Plastics Directive enforcement and stable aluminum tariff regimes; material deviation in either would warrant model refresh. Specific risks include accelerated fluoropolymer liner bans, polypropylene feedstock supply disruptions, and pharmaceutical OEM consolidation beyond historical patterns. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Flip Top Caps and Closures Market
Caps and Closures
Plastic Tamper Evident Closures Market
Caps and Closures
Plunger Stopper Market
Caps and Closures
Cap Liner Market
Caps and Closures
Ring Pull Caps Market
Caps and Closures
Brazil Plastic Caps and Closures Market
Caps and Closures
Plastic Caps and Closure Market
Caps and Closures
Foam Cap Liners Market
Caps and Closures
Twist Caps Market
Caps and Closures
Cone Lined Caps Market
Caps and Closures
Brush and Dauber Caps Market
Caps and Closures
PCR Closures Market
Caps and Closures
North America Plastic Caps and Closures Market
Caps and Closures
South Africa Plastic Caps and Closures Market
Caps and Closures
Aerosol Valves Market
Caps and Closures
Low Profile Compact System Closures Market