
 Nordic Plastic Caps and Closures Market | 2026-2036
Nordic Plastic Caps and Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Nordic Plastic Caps and Closures Market Insights
Aftermarket technical service revenue is narrowing as Nordic converters push total-cost-of-ownership contracts upstream. Berry Global Inc. leverages its European thermoforming footprint to supply dairy processors across southern Sweden. Bericap Holding GmbH anchors high-volume beverage closure production through its German-Nordic logistics corridor. Amcor Group GmbH differentiates via pharmaceutical-grade child-resistant formats for Danish and Finnish drug manufacturers.
Plastic caps and closures are injection- or compression-molded sealing devices, typically manufactured from polyethylene, polypropylene, or PET with thread geometries precision-engineered to ISO 8317 or DIN standards, designed to preserve contents, enable controlled dispensing, and confirm tamper evidence. Screw caps occupy the dominant volume position across Nordic food and beverage bottling due to reseal reliability and line-speed compatibility. Dispensing caps represent the fastest-growing product type as personal care and household chemical brands in Norway and Finland adopt pump-and-flip integrated formats. Polypropylene leads closure material selection for hot-fill and retort applications in the region's preserved food sector.
EU REACH and the Single-Use Plastics Directive shape material compliance timelines, while national extended producer responsibility frameworks in Sweden and Denmark mandate recycled content thresholds that redirect procurement toward rPP-certified suppliers. ECHA substance restrictions on intentional microplastics additives are forcing reformulation of certain PVC closure compounds ahead of sunset dates. Stakeholders must monitor pending EU Packaging and Packaging Waste Regulation revisions to assess whether tethered-cap mandates or deposit-system expansions alter mold-investment priorities.
Market Dynamics
The EU Single-Use Plastics Directive is compressing virgin polymer demand across Nordic beverage packaging lines while simultaneously forcing mold-retooling cycles for tethered-cap compliance. This regulatory pressure is redistributing competitive advantage toward converters with certified recycled-content supply chains.
Growth Catalysts
- rPP-certified supply chains:Sweden's extended producer responsibility framework mandates recycled content thresholds that redirect dairy processor procurement toward post-consumer polypropylene suppliers.
- Hot-fill compatibility:Polypropylene closures are capturing share in Finland's preserved food sector due to retort stability and steam-sterilization resistance.
- Dispensing format adoption:Norwegian personal care brands are integrating pump-and-flip closures that command premium positioning in household chemical segments.
Market Restraints
- Feedstock volatility:Virgin polypropylene pricing fluctuates with propylene monomer supply disruptions from North Sea petrochemical complexes.
- Recycled resin scarcity:Food-grade rPP availability concentrates among German and Benelux reprocessors, creating Nordic supply bottlenecks.
- ECHA microplastic restrictions:Intentional additive bans in PVC closure compounds are forcing Danish manufacturers into accelerated reformulation cycles.
Strategic Opportunities
- Icelandic beverage export corridor:Bottled water and premium soft drink producers are expanding closure demand through North Atlantic shipping routes to North American specialty retailers.
- Pharmaceutical child-resistant formats:Danish and Finnish drug manufacturers are sourcing ISO 8317-certified closures for OTC and prescription packaging lines.
- Tethered-cap mandate preparation:Pending EU Packaging and Packaging Waste Regulation revisions are incentivizing mold investments for integrated hinge designs ahead of compliance deadlines.
Industry Challenges
- Recycled-content certification timelines:Third-party rPP verification for food-contact applications extends procurement lead times by 8-14 weeks.
- Multi-cavity mold complexity:Tethered-cap geometries require synchronized hot-runner systems that strain technical staffing at Swedish and Norwegian converter facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nordic Plastic Caps and Closures Market |
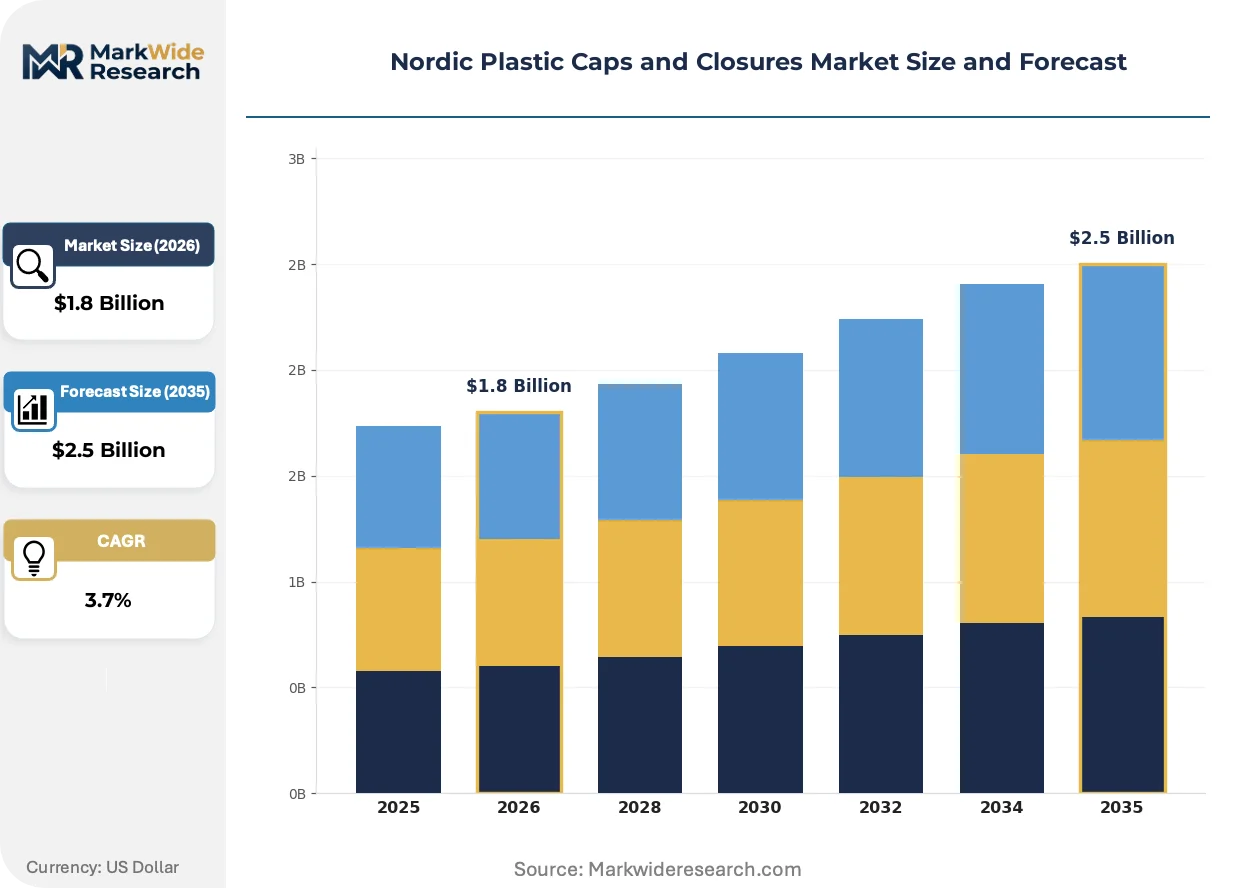
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screw Caps, Snap-On Caps, Dispensing Caps, Valved Caps Closure Material: Polyethylene, Polypropylene, PET, PVC End User Industry: Food & Beverage, Pharmaceuticals, Cosmetics, Household Products Shape: Round, Square, Oval, Custom |
| Companies Covered | Berry Global Inc., Bericap Holding GmbH, Amcor Group GmbH, Modulpac AB, Tetra Pak International SV, Carmo A/S, Fin-Korkki Oy, Robinson PLC, Tetra Pak International BV, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nordic Plastic Caps and Closures Market Trends and Innovations
Lightweighting and material substitution are converging with regulatory compliance mandates to reshape Nordic closure specifications. The competitive frontier is shifting from unit cost minimization toward total-cost-of-ownership optimization across the packaging value chain.
Compression-molded polypropylene closures are rendering obsolete heavier injection-molded equivalents in Sweden's high-speed dairy bottling lines. Arla Foods and smaller regional processors are adopting 1.2-gram standard finishes that maintain torque performance while reducing resin consumption. This transition is compressing demand for legacy high-density polyethylene screw caps in refrigerated milk applications.
REACH substance restrictions on intentional microplastics are forcing PVC compound reformulation across Danish pharmaceutical and industrial chemical packaging. ECHA sunset dates for certain plasticizer additives are accelerating migration toward polypropylene and polyethylene terephthalate alternatives. Finnish converters serving household chemical segments are qualifying halogen-free closure materials ahead of enforcement windows.
Total-cost-of-ownership contracting is displacing transactional spot purchasing among Norwegian beverage bottlers. Procurement teams are bundling closure supply with technical service and line-integration support, compressing aftermarket revenue pools for standalone service providers. This shift is most visible in Oslo and Bergen metropolitan bottling corridors where converter-distributor relationships are consolidating.
Nordic Plastic Caps and Closures Market Segmentation
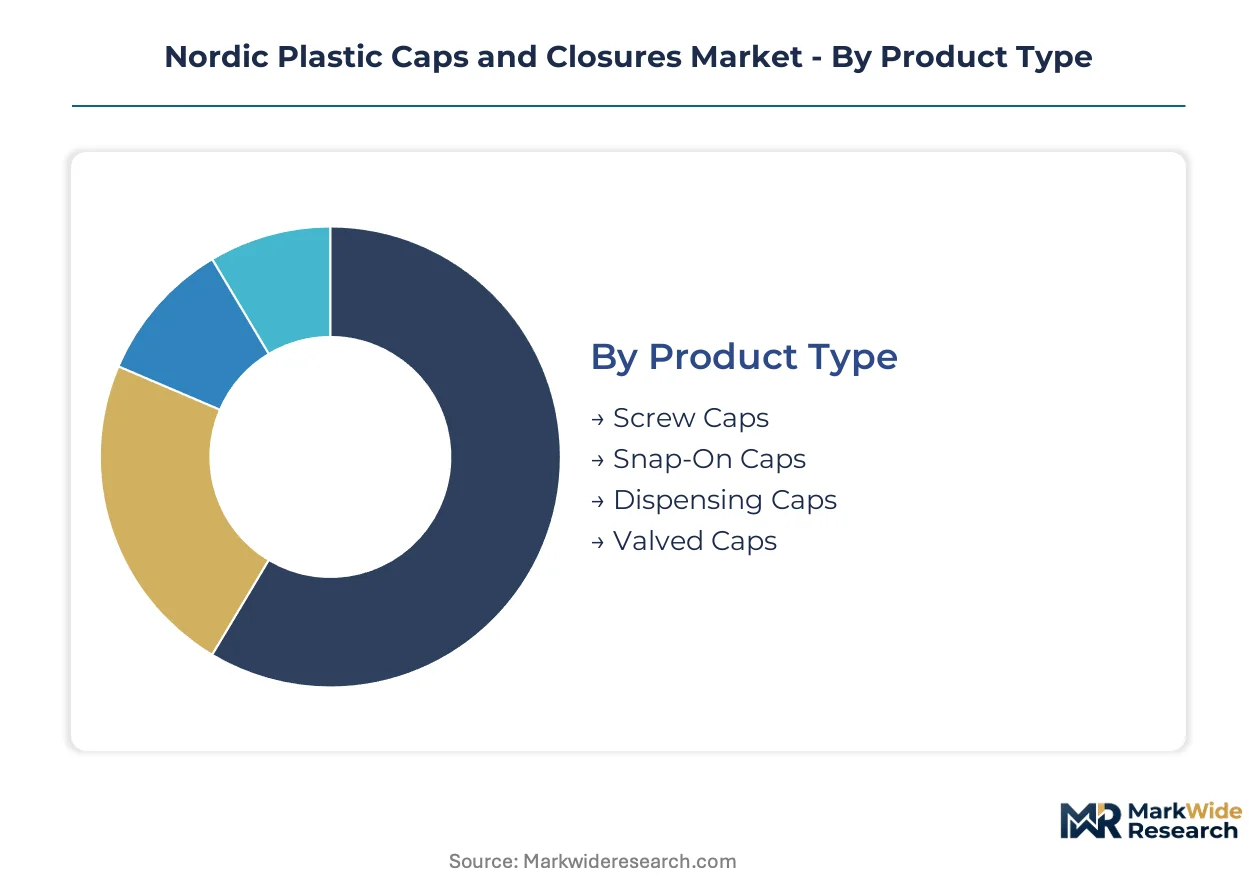
Nordic closure procurement patterns diverge sharply by application rigor—dairy bottlers prioritize reseal torque reliability while pharmaceutical packagers demand child-resistant certification. Segmentation discipline reveals where converter technical capabilities align with end-use compliance burdens.
Product Type:
Closure geometries span resealable convenience, single-use security, and controlled dispensing across Nordic packaging lines.
- Screw Caps:Threaded polypropylene or polyethylene designs engineered to DIN 168 GL standards deliver repeatable torque performance for carbonated beverage and dairy applications. Sweden's high-speed bottling corridors favor these formats for line efficiency and consumer reseal reliability. Established volume favors screw caps; emerging adoption favors dispensing caps.
- Snap-On Caps:Press-fit polyethylene closures with integral tamper-evident rings secure single-serve dairy and juice portions. Finnish dairy processors specify these for portion-controlled fermented milk products where reseal is unnecessary.
- Dispensing Caps:Integrated pump-and-flip mechanisms command premium positioning in Norwegian personal care and household chemical segments. Pump actuator compatibility with viscous formulations drives specification for shampoo and cleaning concentrate bottles. This segment is climbing the fastest as brand owners differentiate through user experience.
- Valved Caps:Silicone membrane or slit-valve designs enable controlled product release for inverted packaging formats. Danish food manufacturers deploy these for condiment and sauce dispensing where drip control determines shelf appeal.
Standard threaded formats dominate unit economics; value-added dispensing mechanisms capture margin expansion.
Closure Material:
Material selection trades thermal stability, chemical resistance, and recycled-content compliance against mold-cycle efficiency.
- Polyethylene:Low-density and high-density grades provide cost-efficient sealing for ambient-temperature beverages and dry food containers. Norwegian bottled water producers favor LDPE for lightweight screw-cap finishes that reduce resin consumption per thousand units.
- Polypropylene:Homopolymer and copolymer formulations deliver hot-fill compatibility and retort stability for preserved food applications. Finland's steam-sterilization packaging lines specify PP closures for shelf-stable ready meals where dimensional integrity under thermal stress is non-negotiable. Established volume favors polypropylene; emerging adoption favors certified recycled polyethylene.
- PET:Injection-molded or compression-molded polyester closures align with bottle-to-bottle recycling streams for premium beverage positioning. Swedish spring water brands specify clear PET caps to maintain visual continuity with container aesthetics.
- PVC:Phthalate-plasticized compounds persist in industrial chemical packaging despite REACH-driven reformulation pressure. Danish converters are qualifying halogen-free alternatives ahead of ECHA sunset dates for intentional microplastic additives.
Polypropylene anchors thermal-performance applications; polyethylene retains cost-sensitive volume.
End User Industry:
Industry-specific compliance frameworks dictate closure certification requirements and procurement lead times.
- Food & Beverage:Dairy, bottled water, and preserved food applications generate the dominant demand share across Nordic converter output. Sweden's Arla Foods and regional dairy cooperatives specify torque-tested closures for extended shelf-life milk and fermented products. Established volume favors food and beverage; emerging adoption favors pharmaceutical-grade formats.
- Pharmaceuticals:ISO 8317-certified child-resistant and senior-friendly designs serve Danish and Finnish OTC and prescription drug packaging. Tamper-evident band integrity and push-and-turn mechanism reliability determine supplier qualification timelines.
- Cosmetics:Premium dispensing pumps and airless closure systems support Norwegian and Swedish skincare brand positioning. Aesthetic surface finish and actuator ergonomics drive specification for high-margin personal care segments.
- Household Products:Chemical-resistant polyethylene and polypropylene closures secure bleach, detergent, and cleaning concentrate containers. Finnish converters emphasize venting features for chlorine-releasing formulations where pressure buildup risks container deformation.
Food safety mandates govern volume procurement; pharmaceutical compliance creates supplier stickiness.
Shape:
Geometry selection balances mold complexity, label adhesion, and retail shelf differentiation.
- Round:Radially symmetric designs dominate high-speed capping equipment compatibility across Nordic bottling lines. Standard 28mm and 38mm finishes align with international filling machinery specifications.
- Square:Flat-sided geometries maximize label real estate for brand communication on premium beverage and cosmetic containers. Danish specialty food producers specify these for artisan positioning in retail environments.
- Oval:Elongated profiles accommodate ergonomic grip surfaces and directional pouring control. Norwegian household chemical brands adopt oval closures for heavy-container handling convenience.
- Custom:Proprietary geometries with integrated handles, tethered hinges, or brand-embossed surfaces support differentiation strategies. Tethered-cap mandate preparation is accelerating mold investment in integrated hinge designs across Swedish converter facilities.
Standard round formats optimize line speed; custom geometries command tooling premiums for brand distinction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sweden consumes closures differently than its Nordic neighbors, with dairy processors driving rPP-certified procurement under extended producer responsibility mandates, while pharmaceutical packagers in Denmark and Finland prioritize ISO 8317-certified child-resistant formats over cost minimization.
Sweden
Arla Foods and regional dairy cooperatives anchor closure demand through high-speed bottling corridors in Skåne and Västra Götaland. The country's extended producer responsibility framework mandates recycled content thresholds that redirect procurement toward post-consumer polypropylene suppliers. Göteborg-based converter facilities are retooling for tethered-cap compliance ahead of EU Packaging and Packaging Waste Regulation revisions.
Denmark
Pharmaceutical manufacturers in the Copenhagen-Roskilde corridor drive ISO 8317-certified child-resistant closure demand for OTC and prescription drug packaging. ECHA restrictions on intentional microplastics in PVC compounds are forcing accelerated reformulation cycles among local converters. The Kalundborg industrial cluster hosts halogen-free material qualification programs ahead of sunset dates.
Finland
Preserved food packagers specify polypropylene closures for steam-sterilization packaging lines producing shelf-stable ready meals. Finnish EPR frameworks align with Swedish thresholds, creating cross-border procurement coordination for rPP-certified supply. The Helsinki-Tampere logistics corridor concentrates converter technical service capabilities for hot-fill compatibility testing.
Norway
Personal care brands in Oslo and Bergen metropolitan areas integrate pump-and-flip dispensing closures for premium household chemical positioning. Total-cost-of-ownership contracting is displacing transactional spot purchasing among beverage bottlers. Stavanger-based converters are bundling closure supply with line-integration support to capture consolidated distributor relationships.
Iceland
Bottled water and premium soft drink producers are expanding closure demand through North Atlantic shipping routes to North American specialty retailers. The island's limited domestic converter base sources standard finishes through Danish and Swedish supply corridors. Reykjavík-area beverage packagers are qualifying lightweight 1.2-gram polypropylene finishes for export-grade positioning.
Nordic Plastic Caps and Closures Market Competitive Landscape
Capability concentration sits with specialized converters holding pharmaceutical-grade certification and tethered-cap mold expertise; scale advantage sits with pan-European suppliers leveraging German-Nordic logistics corridors for high-volume dairy and beverage contracts. The market exhibits tiered competition between multinational packaging conglomerates and regional specialists. Three archetypes dominate: rPP-certified supply chain operators, pharmaceutical compliance specialists, and integrated dispensing mechanism designers. Competitive moves center on mold-retooling investments for tethered-cap compliance and backward integration into recycled resin sourcing.
Among Germany-based closure manufacturers, Bericap Holding GmbH anchors high-volume beverage production through its logistics corridor into Nordic markets. Berry Global Inc., a US-incorporated packaging conglomerate, exemplifies the scale-driven archetype through its European thermoforming footprint serving southern Swedish dairy processors. Amcor Group GmbH, an Austrian-registered packaging group, represents the pharmaceutical compliance tier through its positioning for Danish and Finnish drug manufacturers.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Bericap Holding GmbH |
| Amcor Group GmbH |
| Modulpac AB |
| Tetra Pak International SV |
| Carmo A/S |
| Fin-Korkki Oy |
| Robinson PLC |
| Tetra Pak International BV |
| Others |
Pricing and Supply Chain Analysis
Göteborg's converter corridor anchors Nordic polypropylene closure capacity, with mold-retooling investments for tethered-cap compliance concentrating technical talent and compressing spot-market pricing power among non-integrated distributors. This supply-side density enables long-term offtake negotiations that lock in rPP-certified volumes ahead of ECHA enforcement windows, while spot purchasers absorb resin volatility from North Sea petrochemical disruptions.
Pricing Analysis
Long-term offtake contracts dominate procurement between Swedish dairy processors and German-Benelux reprocessors, compressing spot-market liquidity for rPP-certified grades. Price differentiation rests on food-contact certification tier and volume scale, with Arla Foods-scale buyers commanding 15-20% discounts against regional cooperatives. Pricing pressure stems from recycled resin scarcity extending procurement lead times, forcing smaller Norwegian bottlers into premium spot positions. Pharmaceutical packagers in Denmark exhibit lowest price sensitivity due to ISO 8317 compliance mandates.
Supply Chain Analysis
Contract manufacturing concentrates among Swedish and German converter facilities holding tethered-cap mold expertise, with Berry Global and Bericap anchoring high-volume beverage corridors through integrated logistics networks. Raw material dependencies center on propylene monomer from North Sea crackers, post-consumer polypropylene flake from German reprocessors, and hot-runner system components from Italian mold-makers. Single-source vulnerability concentrates in food-grade rPP certification, where third-party verification bottlenecks strain procurement timelines. Distribution runs through converter-direct relationships with dairy processors, bypassing traditional distributor markups in Skåne and Västra Götaland bottling clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service bundling represents the fastest-expanding revenue layer, as Norwegian beverage bottlers disaggregate aftermarket support from hardware procurement and pay premium retainers for line-integration expertise. This service-attach dynamic outpaces unit volume growth across the projection horizon.
For Market Incumbents: Insulate margin position through captive rPP sourcing agreements with German reprocessors ahead of Swedish EPR threshold escalations. Prioritize tethered-cap mold investments in Göteborg facilities to preempt EU Packaging and Packaging Waste Regulation compliance deadlines. Lock in five-year technical service contracts with Arla Foods-scale dairy processors to displace standalone service providers from bottling corridors. For New Entrants and Emerging Players: Establish a beachhead in Icelandic beverage export packaging, where limited domestic converter capacity and North Atlantic shipping growth create procurement gaps for lightweight polypropylene finishes. Target Reykjavík-area bottled water producers with 1.2-gram standard finishes qualified for North American retail shelf requirements. Lead with line-speed optimization consulting to differentiate against established Nordic suppliers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance consolidation play because tethered-cap mandates and ECHA microplastic restrictions are systematically raising technical barriers for sub-scale converters. Acquisition targets cluster around Swedish and Danish specialists holding ISO 8317 pharmaceutical certification and integrated hinge mold expertise. Monitor Swedish government announcements on EPR threshold revisions as the primary inflection signal for rPP procurement urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Tethered-Cap Mold Investment | Göteborg converters retool synchronized hot-runner systems ahead of EU Packaging and Packaging Waste Regulation enforcement. |
| Backward Integration into rPP Sourcing | Swedish dairy processors secure post-consumer polypropylene supply chains under extended producer responsibility mandates. |
| Pharmaceutical Certification Expansion | Danish converters pursue ISO 8317 accreditation to serve Copenhagen-Roskilde drug manufacturing clusters. |
| Technical Service Bundling | Norwegian bottlers consolidate closure procurement with line-integration support, compressing standalone aftermarket revenue pools. |
| Icelandic Export Corridor Qualification | Lightweight polypropylene finishes gain North American retail positioning through Reykjavík-based beverage packagers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with converter plant managers, dairy procurement leads at Arla Foods and regional cooperatives, pharmaceutical packaging engineers in Denmark, and technical service directors at Nordic distribution channels. Secondary validation drew from EU REACH substance restriction filings, Swedish EPA extended producer responsibility reports, ECHA microplastic additive sunset date documentation, and customs trade data on polypropylene resin flows. Bottom-up volume estimates from individual converter capacities were triangulated against top-down demand projections from end-use industry consumption patterns.
Calibration across the analysis window employed a segmented growth model disaggregating by closure type, material grade, end-use industry rigor, and national regulatory framework. CAGRs were derived from regression analysis of historical procurement volumes against EPR implementation timelines and tethered-cap adoption curves. Key forecast inputs included Swedish dairy bottling line expansion schedules, Finnish preserved food sterilization capacity additions, and Norwegian personal care dispensing format penetration rates.
Sensitivities concentrate around EU Packaging and Packaging Waste Regulation revision timing, North Sea propylene supply disruptions, and food-grade rPP certification bottleneck duration. Forecasts embed assumptions on regulatory enforcement consistency and recycled resin quality stabilization that could shift materially. Quarterly review of Swedish government EPR announcements, ECHA substance restriction updates, and German reprocessor capacity utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Overcaps Market
Caps and Closures
Flat Valve Caps and Closures Market
Caps and Closures
Global Die Cut Lids Market
Caps and Closures
United States Plastic Caps and Closure Market
Caps and Closures
Laminated Tube Closure Market
Caps and Closures
Sterile Lids Market
Caps and Closures
Spain Plastic Cap and Closure Market
Caps and Closures
Plastic Tamper Evident Closures Market
Caps and Closures
Bar Top Corks Market
Caps and Closures
United Kingdom Plastic Caps and Closures Market
Caps and Closures
Brush and Dauber Caps Market
Caps and Closures
Colombia Plastic Caps and Closures Market
Caps and Closures
T-Top Closures Market
Caps and Closures
Brazil Plastic Caps and Closures Market
Caps and Closures
Screw Closure Market
Caps and Closures
Cap Liner Market