
 Box Latch Market | 2026-2036
Box Latch Market Size, Share, and Industry Trends Forecast 2026-2036
Box Latch Market Outlook
E-commerce fulfillment operators is rotating procurement priority toward tamper-evident and quick-release closure systems for returnable transport packaging. Southco leverages captive engineering resources to dominate specification-grade paddle latch designs for server racks and industrial enclosures. Dirak anchors European demand through deep distribution partnerships with German automotive logistics providers. Eberhard Manufacturing sustains North American market presence via specialized zinc alloy hasps engineered for heavy-duty transportation applications.
A box latch is a mechanical fastening device, typically fabricated from stamped steel, die-cast zinc alloy, or injection-molded polymers, designed to secure hinged panels, doors, or container lids through cam-action, sliding bolt, or spring-loaded hook mechanisms. Stainless steel slide latches command premium positioning in food processing and pharmaceutical cleanroom environments where corrosion resistance and washdown compatibility are mandatory. Plastic variants represent the fastest-expanding material segment, driven by lightweighting mandates in consumer electronics packaging and cost-sensitive furniture assembly. Zinc alloy hasps retain volume leadership in industrial equipment applications where shear strength and padlock compatibility outweigh material cost considerations.
REACH substance restrictions and RoHS hazardous substance limits in Europe constrain cadmium and hexavalent chromium plating processes, forcing suppliers to certify alternative surface finishes for zinc alloy components. The EPA's evolving sustainable packaging guidelines and California SB 54 extended producer responsibility framework pressure brand owners to specify recyclable or reusable closure hardware. Stakeholders must monitor regulatory divergence between EU chemical compliance and emerging U.S. state-level packaging mandates when configuring regional product portfolios and qualifying supplier networks.
Market Dynamics
Automotive parts distribution networks are consolidating specification-grade latch procurement around German logistics corridors, compressing supplier qualification timelines and forcing zinc alloy component manufacturers to certify REACH-compliant surface finishes ahead of competing geographies.
Growth Catalysts
- E-commerce fulfillment automation:Tamper-evident closure systems are becoming mandatory in North American distribution centers handling high-value consumer electronics returns. Warehouse operators specify quick-release paddle latches compatible with robotic handling equipment.
- REACH substance restrictions:ECHA's cadmium and hexavalent chromium plating bans are accelerating supplier migration to trivalent chromium and zinc-nickel alternatives for European automotive container applications.
- Stainless steel corrosion resistance:Food processing and pharmaceutical cleanroom environments in Switzerland and Denmark specify 316-grade slide latches capable of withstanding caustic washdown protocols without degradation.
Market Restraints
- Zinc alloy input cost volatility:London Metal Exchange zinc price fluctuations compress margin buffers for die-cast hasp manufacturers serving heavy-duty transportation equipment builders.
- German supplier concentration:Specification-grade automotive latch qualification pathways concentrate among three established logistics hardware distributors, creating barrier-to-entry friction for qualified alternative suppliers.
- Polymer shear strength limitations:Injection-molded nylon and polypropylene variants lack the mechanical load-bearing capacity required for industrial equipment enclosures subject to vibration and impact stress.
Strategic Opportunities
- Indian pharmaceutical cold chain:CDSCO temperature-controlled logistics mandates are creating specification demand for corrosion-resistant latches on insulated shipping containers serving vaccine distribution networks.
- California extended producer responsibility:SB 54 packaging recyclability requirements pressure brand owners to specify reusable metal closure hardware rather than single-use plastic alternatives in consumer goods shipping.
- RFID-integrated latch convergence:Combining mechanical fastening with embedded tracking electronics enables real-time container security monitoring for high-value aerospace component logistics.
Industry Challenges
- Surface finish certification timelines:ECHA REACH SVHC testing protocols and EPA sustainable packaging guideline alignment require 18-24 month qualification cycles for new zinc alloy plating chemistries.
- Legacy equipment retrofit compatibility:Automotive logistics providers maintain mixed fleets of returnable containers spanning 15-year service lives, forcing latch suppliers to maintain backward-compatible mounting patterns.
- Die-cast tooling capex intensity:Zinc alloy hasp production requires hardened steel molds costing $150,000-$400,000 per cavity configuration, constraining product line expansion for mid-cap manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Box Latch Market |
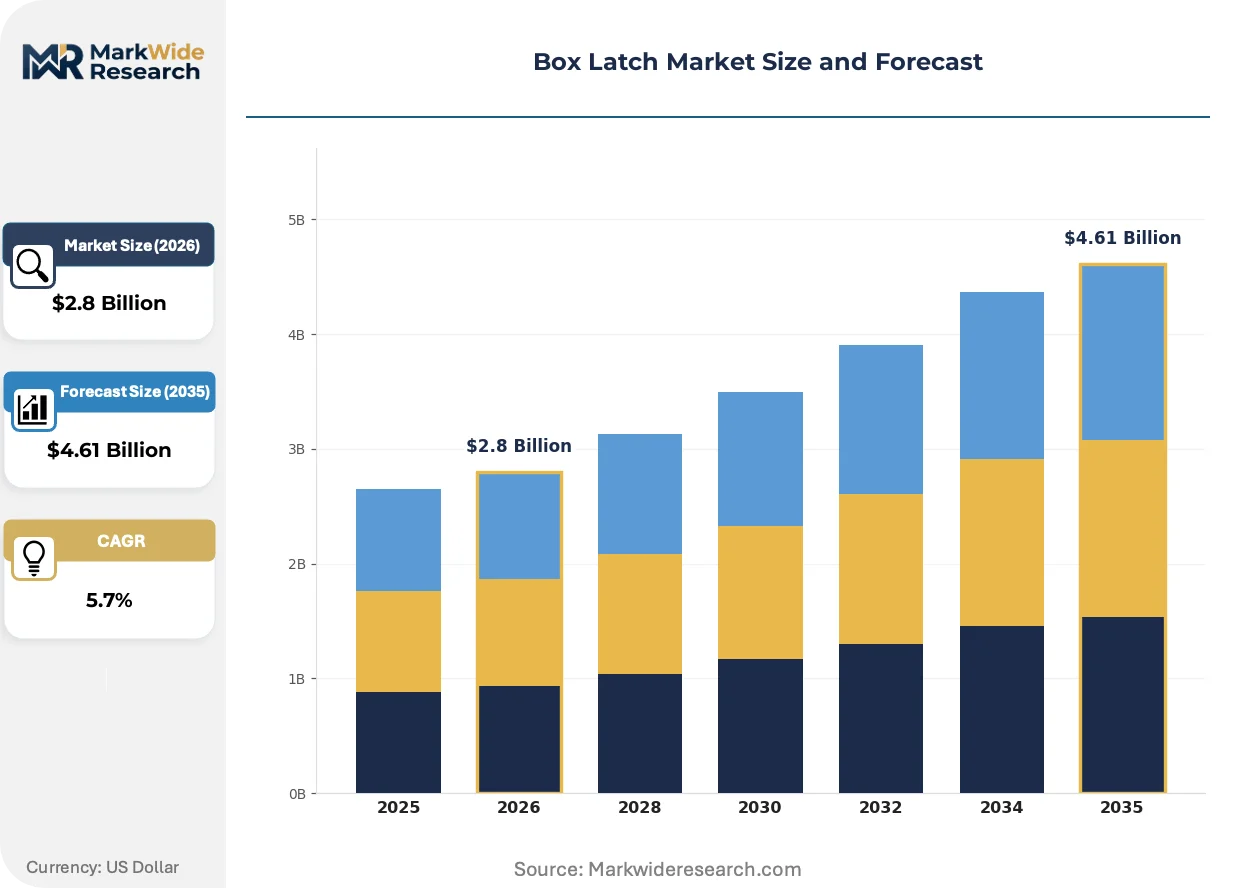
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Slide Latch, Hasps, Simple Hook, Paddle Latch Material: Plastic, Stainless Steel, Zinc Alloy, Aluminum Application: Furniture, Industrial Equipment, Packaging, Storage Solutions End User: Manufacturers, Retailers, Contractors, Consumers |
| Companies Covered | Southco, Dirak, Camlock Systems, Eberhard Manufacturing, Peter Allen & Associates, Rocket Mechanism, JJR Lockets, Almetax, Chengxun Hardware, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Box Latch Market Strategic Shifts
Mechanical fastening architectures are converging with electronic sensing and lightweight material science, compressing the traditional trade-off between security verification and rapid access in container closure design.
Spring-loaded hook mechanisms fabricated from glass-reinforced polyamide are displacing metal counterparts in consumer electronics packaging. Smartphone and laptop manufacturers specify these polymer latches to achieve 30-40% weight reduction in retail shipping containers. The technology is miniaturizing cam-action geometries previously requiring stamped steel construction, enabling sub-5mm profile closures for tablet and wearable device boxes.
EPA sustainable packaging guidelines and California SB 54 extended producer responsibility frameworks are mandating recyclable or reusable closure hardware for brand-owner shipping containers. These regulations force zinc alloy and stainless steel latch specifications over thermoplastic alternatives in premium consumer goods logistics. Food processing and pharmaceutical cleanroom operators in the United States are responding by consolidating procurement around 304 and 316-grade stainless steel slide latches certified for washdown compatibility.
Automotive logistics providers in Germany are unbundling after-sales latch replacement from original container procurement contracts. Tier-1 suppliers now negotiate separate multi-year service agreements for wear-part refresh cycles on returnable packaging fleets. This behavioral shift concentrates spare parts demand among authorized distributors with reverse logistics capabilities, compressing spot-market opportunities for independent hardware vendors serving the aftermarket.
Box Latch Market Segmentation
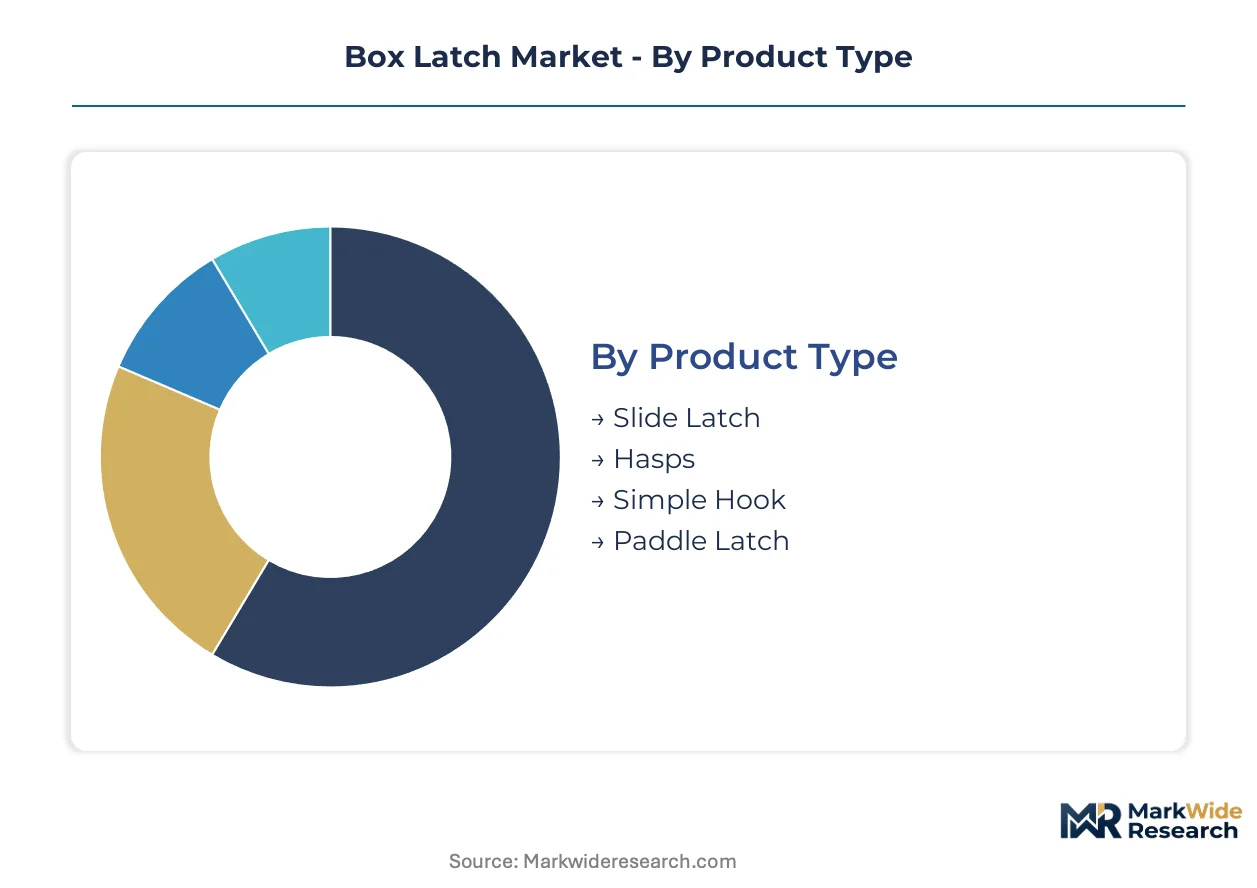
Segmentation in the box latch market reveals distinct performance envelopes across material chemistry and mechanical architecture. Procurement decisions increasingly hinge on regulatory compliance trajectories and automation compatibility rather than unit cost alone.
Product Type:
Substitution pressure from adhesive closures and magnetic fastening systems weighs heaviest on simple mechanical designs lacking tamper-evidence or quick-release functionality.
- Slide Latch:Linear bolt mechanisms fabricated from stamped steel or extruded aluminum enable single-handed operation in high-frequency access environments. Pharmaceutical cleanroom operators in Switzerland and Denmark specify 316-grade stainless variants for caustic washdown compatibility.
- Hasps:Staple-and-loop configurations accommodate padlock security in heavy-duty transportation and outdoor storage applications. Zinc alloy die-castings dominate automotive logistics fleets serving German distribution corridors, though REACH-compliant surface finish certification extends supplier qualification timelines.
- Simple Hook:Spring-loaded wire forms offer lowest unit cost for furniture and consumer goods packaging. Polymer overmolding variants address lightweighting mandates in electronics retail shipping.
- Paddle Latch:Cam-action mechanisms with integrated grip surfaces enable robotic handling in automated fulfillment centers. E-commerce operators specify these for returnable transport packaging requiring rapid cycle times.
Hasps retain volume leadership in industrial procurement; paddle latches hold the steepest expansion curve as warehouse automation penetrates North American fulfillment networks.
Material:
Cost tier stratification separates specification-grade metals from commodity plastics, with mid-range aluminum occupying an intermediate position threatened by polymer performance advances.
- Stainless Steel:Austenitic grades 304 and 316 deliver corrosion resistance mandatory for food processing equipment and pharmaceutical containment. FDA washdown protocols and EPA sustainable packaging guidelines reinforce metal specifications over thermoplastic alternatives in regulated industries.
- Zinc Alloy:Die-cast ZAMAK compositions achieve complex geometries with shear strength exceeding polymer alternatives. ECHA REACH restrictions on cadmium and hexavalent chromium plating force migration to trivalent chromium and zinc-nickel finishes for European automotive container applications.
- Plastic:Glass-reinforced polyamide and polypropylene compounds enable 30-40% weight reduction in consumer electronics packaging. Shear strength limitations constrain adoption in vibration-prone industrial equipment enclosures.
- Aluminum:Extruded and stamped profiles balance corrosion resistance with moderate cost for marine and outdoor storage applications. Anodized finishes satisfy aesthetic requirements in architectural furniture.
Zinc alloy retains volume leadership across heavy-duty transportation and automotive logistics; plastic compounds are gaining share fastest in consumer electronics and lightweight furniture assembly.
Application:
Volume concentration in automotive parts distribution creates margin pressure on packaging segment suppliers, while industrial equipment commands specification-grade pricing premiums.
- Industrial Equipment:Enclosure latches for electrical panels, HVAC units, and machinery guards require vibration resistance and padlock compatibility. German automotive logistics providers specify die-cast hasps with REACH-certified finishes for returnable container fleets.
- Packaging:E-commerce fulfillment centers drive demand for tamper-evident quick-release mechanisms compatible with robotic handling. California SB 54 extended producer responsibility mandates pressure brand owners toward reusable metal closure hardware.
- Furniture:Cam-action and magnetic latches prioritize aesthetic integration and silent operation over mechanical load-bearing. Assembly-kit manufacturers favor stamped steel and polymer variants for cost-sensitive flat-pack distribution.
- Storage Solutions:Outdoor and warehouse shelving systems specify corrosion-resistant slide latches for security doors and access panels. Stainless steel variants penetrate food service and cold chain applications.
Industrial equipment commands the highest specification-grade pricing; packaging applications demonstrate the most rapid procurement-volume expansion as e-commerce fulfillment automation accelerates.
End User:
Procurement authority concentration among large-scale manufacturers and retailers fragments demand visibility for contractors and individual consumers.
- Manufacturers:Original equipment builders specify latches during product design phases, locking in multi-year supply agreements. Automotive tier-1 suppliers in Germany consolidate procurement through authorized distributors with reverse logistics capabilities.
- Retailers:E-commerce and big-box operators specify closure hardware for private-label returnable transport packaging. Quick-release paddle latches dominate automated fulfillment center requirements.
- Contractors:Installation and maintenance providers purchase through wholesale distribution for replacement and retrofit applications. Mixed-fleet container ages force backward-compatible mounting pattern requirements.
- Consumers:DIY and household purchases concentrate in simple hook and light-duty slide latch categories through retail hardware channels. Price sensitivity limits specification-grade metal adoption.
Manufacturers retain volume leadership through design-phase specification authority; retailers demonstrate the steepest procurement expansion curve as e-commerce fulfillment infrastructure scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports specification-grade zinc alloy hasps to automotive logistics networks across Europe and North America, while China manufactures stamped steel slide latches for consumer electronics packaging destined for US and European retail channels.
Germany
Automotive parts distribution drives demand for REACH-compliant die-cast hasps on returnable transport containers. ECHA substance restrictions on cadmium plating force migration to trivalent chromium finishes. The Stuttgart-Munich industrial corridor concentrates procurement authority among tier-1 suppliers negotiating multi-year service agreements for wear-part refresh cycles.
United States
E-commerce fulfillment automation accelerates specification of quick-release paddle latches compatible with robotic handling equipment. EPA sustainable packaging guidelines and California SB 54 extended producer responsibility pressure brand owners toward reusable metal closure hardware. Distribution centers in the Inland Empire and Dallas-Fort Worth metroplex consolidate procurement of tamper-evident systems for high-value consumer electronics returns.
China
Consumer electronics packaging exports drive stamped steel and polymer latch production for smartphone and laptop manufacturers. MIIT lightweighting mandates and GB standards for transport packaging shape material specifications. The Yangtze River Delta manufacturing cluster supplies glass-reinforced polyamide spring hooks achieving 30-40% weight reduction in retail shipping containers.
Switzerland
Pharmaceutical cleanroom operators specify 316-grade stainless steel slide latches for caustic washdown compatibility. Swissmedic containment protocols and FDA-aligned export requirements reinforce metal specifications over thermoplastic alternatives. Basel and Zurich pharmaceutical hubs consolidate procurement around corrosion-resistant fastening systems for vaccine distribution packaging.
India
CDSCO temperature-controlled logistics mandates create specification demand for corrosion-resistant latches on insulated shipping containers. The country's national pharmaceutical regulator enforces cold chain integrity standards for vaccine distribution networks. Mumbai and Hyderabad pharmaceutical clusters drive adoption of stainless steel closure hardware serving export-oriented biologics manufacturers.
Box Latch Market Competitive Environment
Player mix skews toward specification-grade metal fabricators serving automotive and industrial equipment verticals, with mid-cap polymer specialists capturing share in consumer electronics packaging. The competitive structure fragments across three tiers: multinational engineering houses with captive R&D, regional zinc alloy die-casters with deep automotive qualifications, and commodity stampers competing on unit cost. Dominant competitive moves include geographic expansion through authorized distribution partnerships and portfolio diversification into RFID-integrated smart fastening systems.
Among the named participants, Southco and Dirak occupy positions within the premium engineering tier, while Eberhard Manufacturing anchors North American heavy-duty transportation applications. Southco exemplifies the multinational archetype leveraging specification-grade design authority, Dirak represents European automotive logistics concentration through distribution partnerships, and Eberhard Manufacturing illustrates specialized zinc alloy hasp production for vibration-prone industrial environments. These three names serve as reference points for understanding how competitive positioning stratifies across material chemistry, regulatory certification depth, and end-use vertical access.
| Leading Market Players |
|---|
| Southco |
| Dirak |
| Camlock Systems |
| Eberhard Manufacturing |
| Peter Allen & Associates |
| Rocket Mechanism |
| JJR Lockets |
| Almetax |
| Chengxun Hardware |
| Others |
Value Chain & Pricing Dynamics
Multi-year service agreements for wear-part refresh cycles lock in both supply access and price visibility for German automotive logistics providers negotiating with authorized distributors. These contracts compress spot-market opportunities while anchoring zinc alloy hasp procurement around REACH-certified surface finishes.
Pricing Analysis
Specification-grade stainless steel slide latches command substantial premiums over stamped steel alternatives due to 316-grade corrosion resistance and FDA washdown certification. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical cleanroom specifications from furniture assembly commodities. Cost compression in zinc alloy die-castings intensifies because London Metal Exchange price volatility erodes margin buffers for heavy-duty transportation equipment builders. Retailers and e-commerce operators demonstrate highest price sensitivity, while pharmaceutical and food processing manufacturers prioritize certification compliance over unit cost.
Supply Chain Analysis
Inbound logistics costs from Yangtze River Delta manufacturing clusters to North American distribution centers hinge on container availability across Pacific trade lanes. Die-cast zinc alloy hasp production concentrates in Germany, China, and the United States, drawing from ZAMAK ingot, hardened steel tooling, and trivalent chromium plating chemistries. Single-source vulnerability persists for REACH-certified surface finish suppliers serving European automotive container applications. Distribution runs through authorized distributors with reverse logistics capabilities rather than spot-market hardware vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RFID-integrated latch convergence with embedded tracking electronics is reshaping competitive positioning as real-time container security monitoring becomes mandatory for high-value aerospace component logistics.
For Market Incumbents: Secure backward integration into trivalent chromium and zinc-nickel plating chemistries to insulate margin structures from ECHA REACH SVHC certification delays. Anchor capacity expansion in the Stuttgart-Munich corridor to defend against emerging polymer specialists threatening specification-grade metal dominance in consumer electronics packaging. For New Entrants and Emerging Players: Differentiate on RFID-integrated smart fastening systems targeting Indian pharmaceutical cold chain applications where CDSCO temperature-controlled logistics mandates create specification demand. Penetrate the California SB 54 compliance segment through reusable metal closure hardware positioned against single-use plastic alternatives in consumer goods shipping. For Investors and Strategic Acquirers: Regional zinc alloy die-casters with deep automotive qualifications and existing REACH certification pathways offer the most attractive acquisition profile for portfolio exposure to specification-grade logistics hardware. Monitor ECHA substance restriction expansion timelines as the critical inflection signal for plating chemistry migration capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| RFID Integration Development | Combines mechanical fastening with embedded tracking electronics for aerospace component logistics. |
| REACH Certification Investment | Accelerates supplier migration to trivalent chromium finishes ahead of ECHA plating bans. |
| Backward Integration into Plating | Captures margin from surface finish chemistries critical for German automotive container applications. |
| Authorized Distribution Partnership | Concentrates spare parts demand among reverse logistics-capable channel partners in European corridors. |
| Polymer Lightweighting R&D | Develops glass-reinforced polyamide spring hooks for 30-40% weight reduction in electronics packaging. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from industrial equipment manufacturers, ECHA substance restriction databases, and automotive logistics procurement disclosures. Interviews with plant engineers, OEM procurement teams, aftermarket service heads, and distribution channel partners inform demand-side validation. Bottom-up volume modeling triangulates against top-down value estimates derived from production capacity disclosures.
Segmentation dimensions modeled include material chemistry, mechanical architecture, application vertical, and end-user procurement authority across the analysis window. CAGRs derive from regression analysis of historical procurement volumes against e-commerce fulfillment automation penetration rates and regulatory compliance timeline acceleration. Forecast inputs incorporate REACH SVHC testing protocol durations and EPA sustainable packaging guideline adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained e-commerce infrastructure investment or accelerated regulatory divergence between EU chemical compliance and U.S. state-level packaging mandates would require recalibration. Forecasts reflect assumptions regarding zinc price volatility stability and die-cast tooling capex availability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
PCR Closures Market
Caps and Closures
Molded Fiber End Caps Market
Caps and Closures
Gable Top Cap and Closures Market
Caps and Closures
Foam End Caps Market
Caps and Closures
IBC Caps Market
Caps and Closures
Mexico Plastic Caps and Closures Market
Caps and Closures
Metal Caps and Closures Market
Caps and Closures
Thailand Plastic Caps and Closures Market
Caps and Closures
Vented Caps Market
Caps and Closures
Global Die Cut Lids Market
Caps and Closures
North America Plastic Caps and Closures Market
Caps and Closures
Lug Caps Market
Caps and Closures
Plastic Sifter Caps Market
Caps and Closures
Poland Plastic Caps and Closures Market
Caps and Closures
Continuous Thread Metal Cap Market
Caps and Closures
Sport Caps and Closures Market