
 Flexible Lid Stock Packaging Market | 2026-2036
Flexible Lid Stock Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Lid Stock Packaging Market Analysis
The capital-intensity divergence between integrated film extruders and converters without metallization capacity is collapsing as barrier coextrusion technology commoditizes. Amcor plc leverages captive resin compounding and global toll manufacturing networks to sustain margin structures smaller competitors cannot match. Sonoco Products Company anchors its position through rigid-flexible hybrid platforms that bundle lidding with thermoformed trays. Mondi PLC differentiates via fiber-based barrier substrates that navigate emerging single-use plastic restrictions across European retail channels.
Flexible lid stock packaging denotes thin-gauge multilayer webs, typically 25–150 micron total caliper, engineered with sealant coextrusions, aluminum oxide or ethylene vinyl alcohol barrier layers, and printable skin films for hermetic closure of trays, cups, and formed containers. The primary industrial purpose centers on gas and moisture barrier protection for perishable goods, enabling extended shelf stability without refrigeration dependency. Composite structures currently lead volume due to their tunable oxygen transmission rates and puncture resistance, though aluminum faces structural decline as brand owners prioritize source-reduced and recyclable alternatives. Pouch-based packaging formats represent the fastest-growing packaging type segment, driven by pet food retort applications and pharmaceutical unit-dose compliance packs where flat lidding films replace three-dimensional rigid closures.
FDA compliance for indirect food contact substances under 21 CFR 177.1390 governs sealant layer migration limits in US markets, while REACH and the EU Packaging and Packaging Waste Regulation shape material composition and extended producer responsibility obligations across European supply chains. EFSA evaluations of mineral oil saturated hydrocarbons in recycled paperboard are accelerating migration toward virgin polymer and certified compostable sealant alternatives. Stakeholders must monitor evolving state-level extended producer responsibility legislation in the US and pending EU harmonized recyclability performance grades that will determine which multilayer constructions retain market access.
Market Dynamics
Barrier coextrusion commoditization is collapsing the historical margin premium between integrated film extruders and toll-dependent converters, forcing asset-light competitors toward specialty sealant formulation or exit.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Recyclability mandates for multi-layer structures are accelerating R&D investment in mono-material compatible sealant webs across European dairy processors.
- Peelable seal film retrofitting:German food processors are converting thermoforming lines to accommodate easy-open lidding, creating pull-through demand for compatible web substrates.
- Retort pouch expansion:Pet food manufacturers are substituting flat lidding films for rigid closures in high-barrier applications, extending addressable volume for aluminum oxide barrier suppliers.
Market Restraints
- Ethylene vinyl alcohol resin concentration:Supply tightness in Asian EVOH polymer capacity creates input cost volatility for oxygen barrier film producers without captive resin compounding.
- Aluminum decline structural drag:Brand owner sustainability commitments are compressing foil-laminate volumes faster than replacement barrier technologies can achieve equivalent transmission rates.
- REACH compliance friction:Extended producer responsibility obligations for mineral oil saturated hydrocarbons in recycled substrates are disqualifying post-consumer feedstock from food-contact applications.
Strategic Opportunities
- Pharmaceutical unit-dose compliance packs:Flat lidding films are penetrating child-resistant senior-friendly blister formats previously dominated by push-through foil, creating premium pricing headroom.
- Fiber-based barrier substrates:Mondi's cellulose-derived platforms demonstrate regulatory navigation of single-use plastic restrictions across European retail channels without sacrificing hermetic performance.
- Extended producer responsibility tailwinds:Pending EU harmonized recyclability performance grades will disqualify non-compliant multilayer constructions, clearing market access for certified compostable sealant innovators.
Industry Challenges
- Migration testing capability scarcity:FDA 21 CFR 177.1390 compliance for indirect food contact substances requires specialized analytical infrastructure that mid-scale converters lack in-house.
- Thermoforming line reconfiguration capex:Peelable seal film adoption demands precision heat-sealing retrofits that strain capital allocation for small-batch dairy processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Lid Stock Packaging Market |
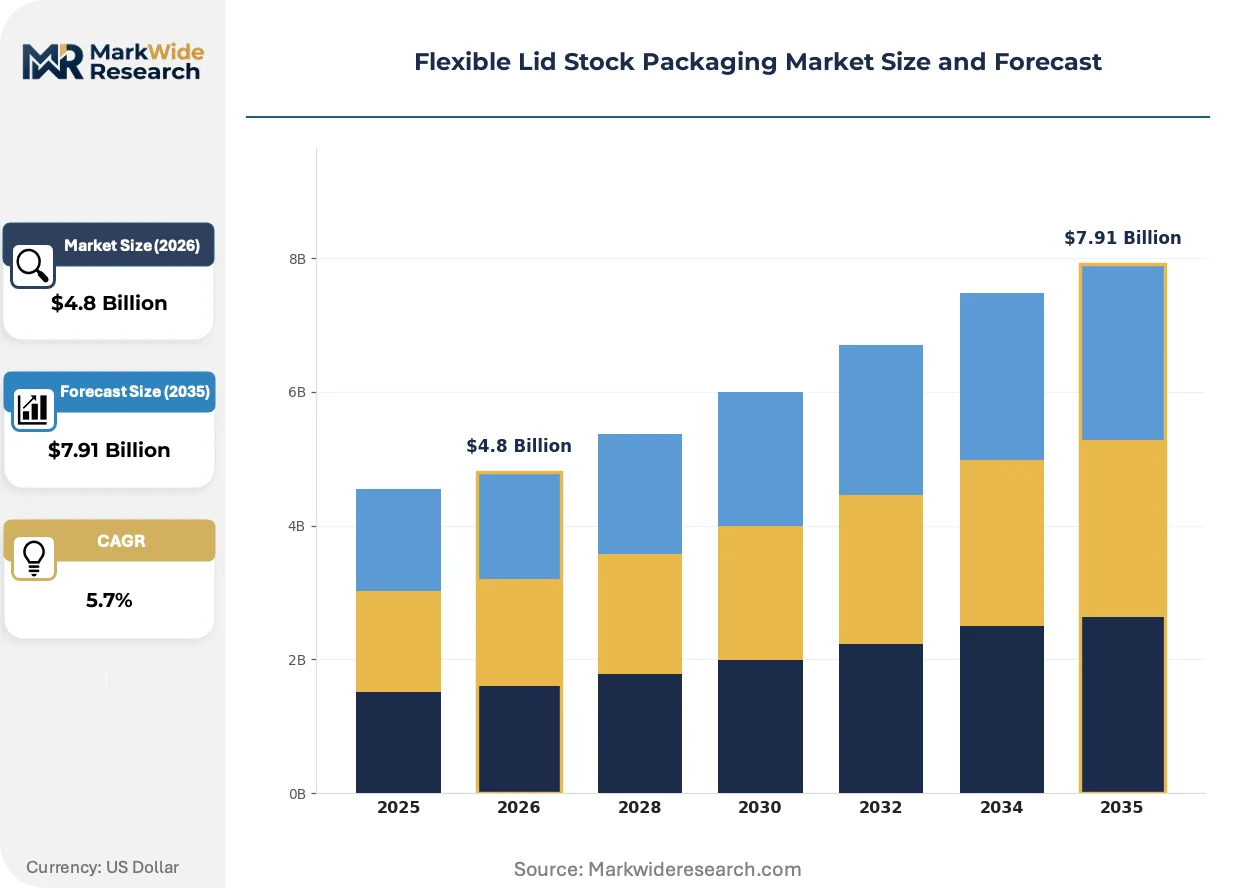
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Plastic, Paper, Composite End User: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Packaging Type: Trays, Clamshells, Pouches, Sealed Containers Application: Food Preservation, Shelf-life Extension, Moisture Control, Contamination Prevention |
| Companies Covered | Berry Global Inc., Sonoco Products Company, Amcor plc, Schur Flexibles Holding GesmbH, TC Transcontinental, Sealed Air Corporation, Constantia Flexibles, International Plastics Inc., Mondi PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Lid Stock Packaging Market Emerging Trajectories
Active barrier technology deployment is splitting the market between commodity oxygen scavengers and premium moisture-responsive systems, with adoption pace varying sharply by end-use shelf-life requirements.
Aluminum oxide vapor deposition is bifurcating the transparent barrier segment from metallized polyethylene terephthalate legacy supply. Pharmaceutical blister pack converters in Switzerland and Germany are specifying AlOx-coated polyethylene for unit-dose compliance applications where metal detection compatibility matters. This split is compressing metallizer tolling volumes while expanding captive sputtering capacity announcements from integrated film producers.
REACH Article 33 substance of very high concern disclosure requirements are forcing downstream brand owners to audit full polymer supply chains for per- and polyfluoroalkyl substances. Dairy and ready-to-eat meal producers are now requiring fluorine-free sealant certifications from lidding film suppliers as a procurement gate. German retailers are responding fastest, with Rewe and Edeka chains imposing 2025 deadlines for PFAS-free packaging across private-label portfolios.
Specification consolidation among multinational food processors is compressing supplier diversity in European procurement. Nestlé and Unilever packaging engineering teams are reducing qualified film vendors from twelve to four per region, prioritizing those with global toll manufacturing networks and harmonized migration testing protocols. This concentration is most visible in Germany, where centralized purchasing decisions at Düsseldorf and Hamburg headquarters now govern plant-level film selection across dairy, confectionery, and prepared meal divisions.
Flexible Lid Stock Packaging Market Segmentation
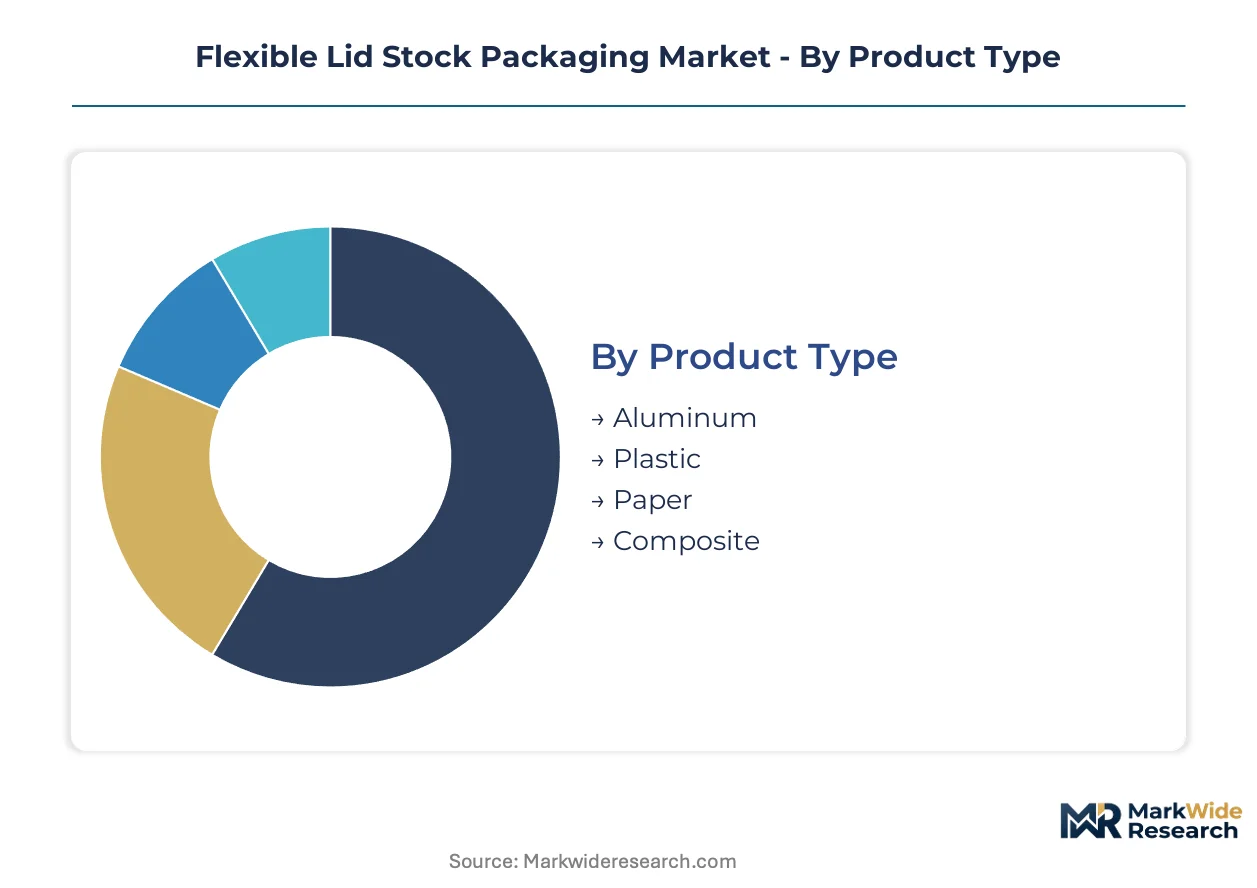
Segmentation in flexible lid stock packaging reveals how material science investments, regulatory compliance burdens, and end-use shelf-life requirements fragment procurement priorities across converter tiers. Understanding these divisions exposes where specification consolidation and margin compression intersect.
Product Type:
Margin pools concentrate in barrier-layer formulations where oxygen transmission rate precision commands pricing premiums from pharmaceutical and retort food processors.
- Aluminum:Foil-laminate structures deliver sub-0.01 cc/m²/day oxygen transmission rates essential for pharmaceutical blister packs and long-shelf-life dairy. German retailers are accelerating phase-out timelines under private-label sustainability mandates, compressing volume faster than oxide-barrier replacements can scale.
- Composite:Multilayer coextrusions combining ethylene vinyl alcohol with polyethylene sealants dominate European dairy retrofitting, where peelable seal compatibility drives specification. Thermoforming line conversions in Bavaria and North Rhine-Westphalia are pulling through demand for 80-120 micron total caliper webs with tuned heat-seal initiation temperatures.
- Plastic:Mono-material polyethylene and polypropylene constructions navigate EU Packaging and Packaging Waste Regulation recyclability thresholds, though barrier performance trade-offs limit penetration to short-shelf-life applications.
- Paper:Fiber-based barrier substrates from integrated pulp-film producers address single-use plastic restrictions in French and Italian retail channels, with mineral oil saturated hydrocarbon compliance emerging as a procurement gate.
The dominant share belongs to Composite, while Aluminum is ceding ground fastest under sustainability-driven specification changes.
End User:
Application-specific migration testing requirements and batch traceability demands create divergent qualification timelines across customer categories.
- Food & Beverage:Dairy processors and ready-to-eat meal manufacturers in Germany represent the core volume pull, with centralized procurement at Düsseldorf and Hamburg headquarters consolidating supplier panels from twelve to four qualified vendors per region.
- Pharmaceuticals:Unit-dose compliance packs and child-resistant senior-friendly blister formats are substituting flat lidding films for push-through foil, with Swiss and German converters specifying aluminum oxide-coated polyethylene for metal detection compatibility.
- Cosmetics:Premium skincare and fragrance brands prioritize hermetic seal integrity for volatile organic compound retention, though volume concentration remains fragmented across niche European converters.
- Electronics:Static-dissipative and moisture-barrier requirements for semiconductor shipping trays represent a specialty niche with extended qualification cycles and captive supply relationships.
Food & Beverage commands the installed base, though Pharmaceuticals is expanding most quickly as compliance-pack regulations tighten.
Packaging Type:
Equipment retrofitting costs and line speed compatibility determine adoption velocity across format categories.
- Pouches:Flat lidding films for retort pet food applications and pharmaceutical unit-dose packs are displacing rigid closures, with aluminum oxide barrier suppliers capturing expanded addressable volume.
- Trays:Thermoformed container lidding dominates European dairy, where peelable seal film retrofits demand precision heat-sealing equipment upgrades that strain capital allocation for small-batch processors.
- Sealed Containers:Hermetic closure systems for prepared meals and medical devices require matched sealant-web pairs with validated peel-strength consistency.
- Clamshells:Rigid-flexible hybrid formats bundle lidding with formed trays, anchoring volume for integrated converters with captive thermoforming capacity.
Trays retain the largest installed equipment base, while Pouches are climbing the fastest as retort applications multiply.
Application:
Performance specification stringency and regulatory scrutiny intensity vary sharply across functional use cases.
- Shelf-life Extension:Oxygen scavenger integration and ethylene vinyl alcohol barrier layers enable ambient distribution of perishables, with EFSA evaluations of mineral oil saturated hydrocarbons accelerating migration toward virgin polymer sealants.
- Moisture Control:Desiccant-embedded lidding and aluminum oxide vapor deposition protect moisture-sensitive pharmaceuticals and electronics, with active barrier technology deployment splitting between commodity scavengers and premium responsive systems.
- Food Preservation:Modified atmosphere packaging compatibility requires sealant webs with CO₂ and O₂ permeability tuning for meat and cheese applications.
- Contamination Prevention:Hermetic integrity standards for sterile medical devices and aseptic food processing demand validated seal-strength protocols and batch-level traceability.
Shelf-life Extension holds the dominant specification complexity, while Moisture Control is gaining share fastest as pharmaceutical unit-dose formats expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany exhibit the lowest price elasticity as sustainability mandates override cost considerations, while processors in emerging markets remain highly sensitive to resin input volatility. This demand-elasticity contrast shapes regional investment patterns and supplier qualification timelines.
Germany
Dairy processors in Bavaria and North Rhine-Westphalia are retrofitting thermoforming lines for peelable seal films, creating concentrated demand for 80-120 micron coextruded webs. The EU Packaging and Packaging Waste Regulation's recyclability mandates are disqualifying multi-layer aluminum laminates from private-label portfolios. Rewe and Edeka headquarters in Düsseldorf and Hamburg have imposed 2025 deadlines for PFAS-free packaging across their supply chains.
United States
Pet food manufacturers are expanding retort pouch capacity, substituting flat lidding films for rigid closures in high-barrier applications. FDA compliance under 21 CFR 177.1390 governs sealant layer migration limits, requiring specialized analytical infrastructure that mid-scale converters struggle to maintain. Migration testing capability scarcity concentrates procurement among integrated film producers with captive laboratory networks.
Switzerland
Pharmaceutical blister pack converters are specifying aluminum oxide-coated polyethylene for unit-dose compliance applications where metal detection compatibility matters. Swissmedic regulations for child-resistant senior-friendly formats are accelerating substitution of push-through foil with flat lidding films. Basel-area packaging engineering clusters are validating seal-strength protocols for sterile medical device applications.
France
Fiber-based barrier substrates are penetrating retail channels as single-use plastic restrictions tighten across French supermarkets. EFSA evaluations of mineral oil saturated hydrocarbons in recycled paperboard are accelerating migration toward virgin polymer sealants. Industrial clusters around Lyon and Paris are piloting certified compostable sealant alternatives for short-shelf-life dairy.
China
Domestic dairy processors are importing European peelable seal technology to upgrade aging thermoforming infrastructure. GB standards for food contact materials are evolving toward harmonization with EU migration limits, though enforcement remains fragmented. Yangtze River Delta converters are building captive sputtering capacity to reduce dependence on metallized polyethylene terephthalate imports.
Flexible Lid Stock Packaging Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated film extruders commanding premium pricing for barrier precision while toll-dependent converters compete on volume flexibility. The market structure concentrates among multinational packaging conglomerates with global manufacturing footprints, though mid-scale regional specialists retain niche positions in pharmaceutical compliance formats. Three archetypes dominate: integrated resin compounders with captive metallization, rigid-flexible hybrid platform providers, and fiber-based barrier substrate innovators. Competitive moves center on strategic partnerships for toll manufacturing networks and portfolio diversification into mono-material recyclable constructions.
Among integrated packaging conglomerates, Amcor plc, Mondi PLC, and Sonoco Products Company exemplify distinct strategic positioning within the market structure. Amcor represents the integrated resin compounder archetype with global toll manufacturing networks. Mondi occupies a position within fiber-based barrier substrate innovation, navigating regulatory restrictions on single-use plastics. Sonoco anchors the rigid-flexible hybrid platform segment, bundling lidding with thermoformed tray solutions. These three companies collectively illustrate how scale, material science capability, and format integration define competitive positioning in a market where barrier coextrusion technology is commoditizing.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Sonoco Products Company |
| Amcor plc |
| Schur Flexibles Holding GesmbH |
| TC Transcontinental |
| Sealed Air Corporation |
| Constantia Flexibles |
| International Plastics Inc. |
| Mondi PLC |
| Others |
Supply Flow & Price Mechanics
Aluminum oxide barrier substitution for metallized polyethylene terephthalate is simultaneously shifting sputtering capacity geography toward German and Swiss converter clusters and compressing legacy tolling margins. This displacement dynamic concentrates pricing power among integrated film producers with captive resin compounding while fragmenting procurement leverage for asset-light converters dependent on spot metallization services.
Pricing Analysis
After-sales revenue from technical service contracts and migration testing support drives lifetime value for integrated film producers. Three-tier pricing structure across premium barrier precision, standard coextrusion, and economy mono-material tiers separates pharmaceutical qualification-grade webs from dairy retrofit volumes. Cost compression in standard-tier peelable seal films is intensifying because EVOH resin supply tightness in Asian markets feeds input volatility. Mid-scale converters without captive laboratory networks exhibit highest price sensitivity, while German dairy processors under sustainability mandates show lowest elasticity.
Supply Chain Analysis
Strategic stockpiling of ethylene vinyl alcohol resin dominates inventory strategy among European barrier film producers facing Asian polymer supply tightness. Manufacturing gravity centers on Germany, Switzerland, and China, with German converters retrofitting thermoforming lines and Chinese Yangtze River Delta facilities building captive sputtering capacity. Raw material dependencies draw from EVOH polymer, aluminum oxide deposition targets, and virgin polymer sealants. Single-source vulnerability in Asian EVOH resin concentration creates structural risk. Distribution runs through converter-direct relationships with multinational food processors and pharmaceutical OEMs, bypassing traditional distributor tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flexible lid stock packaging is approaching a platform-economics inflection where specification consolidation by Nestlé and Unilever creates interoperability standards that favor global toll manufacturing networks over regional specialists.
For Market Incumbents: Shield barrier-layer margin pools by deepening backward integration into EVOH resin compounding and expanding captive sputtering capacity in Germany and Switzerland. Specification consolidation by multinational food processors threatens smaller competitors, while REACH Article 33 PFAS disclosure requirements demand fluorine-free sealant certification investment as a procurement gate. For New Entrants and Emerging Players: Anchor in pharmaceutical unit-dose compliance packs where metal-detection-compatible aluminum oxide barrier films command premium pricing and qualification timelines deter incumbent retaliation. Swiss and German blister pack converters represent the most penetrable customer segment, with go-to-market traction coming through specialized migration testing partnerships that address FDA 21 CFR 177.1390 compliance scarcity. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-scale converters lacking metallization capacity and facing barrier coextrusion commoditization. Long-term viability over a multi-year horizon rests on mono-material recyclable construction pipelines and EU harmonized recyclability certification positioning. Watch for EU Packaging and Packaging Waste Regulation enforcement thresholds as the inflection signal that clears market access for certified compostable sealant innovators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EVOH Resin Compounding | Captive polymer supply insulates margin structures from Asian supply tightness and input cost volatility. |
| Captive Sputtering Capacity Expansion | Aluminum oxide vapor deposition control captures transparent barrier demand from pharmaceutical blister pack converters. |
| Fluorine-Free Sealant Certification | REACH Article 33 compliance opens procurement access to Rewe and Edeka private-label portfolios. |
| Migration Testing Laboratory Investment | FDA 21 CFR 177.1390 analytical capability concentrates procurement relationships among mid-scale converters. |
| Mono-Material Recyclable Construction Pipeline | EU Packaging and Packaging Waste Regulation alignment secures market access under pending harmonized performance grades. |
Methodological Framework
Initial hypotheses were tested against primary input from film extrusion plant managers, dairy procurement leads, pharmaceutical packaging engineers, and barrier technology R&D directors and refined through secondary validation. Trade data from European plastics associations, FDA 21 CFR submission records, EFSA scientific opinions, and SEC filings from integrated packaging conglomerates anchored quantitative baselines. Bottom-up volume triangulation across converter capacity utilization and top-down value estimation from resin input cost models were reconciled to produce segment outputs.
Variance decomposition across material type, end-use application, packaging format, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from segmented growth rate reconciliation across the projection horizon, with EVOH resin supply elasticity, thermoforming line retrofit adoption curves, and EU regulatory enforcement intensity serving as industry-specific forecast inputs.
Material uncertainties — EVOH polymer supply disruptions, EU recyclability performance grade finalization, and PFAS regulatory scope expansion — sit outside the modeled envelope. Forecasts reflect assumptions about barrier technology substitution velocity and specification consolidation pace. Revision becomes warranted when EU harmonized recyclability thresholds or FDA migration limit enforcement crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Flexible Paper for Food & Beverages Packaging Market
Flexible Packaging
North America Flexible Plastic Packaging Market
Flexible Packaging
Thailand Flexible Plastic Packaging Market
Flexible Packaging
Mexico Flexible Plastic Packaging Market
Flexible Packaging
Egypt Flexible Plastic Packaging Market
Flexible Packaging
Europe Flexible Plastic Packaging Market
Flexible Packaging
Nigeria Flexible Packaging Market
Flexible Packaging
Indonesia Flexible Packaging Market
Flexible Packaging
China Flexible Packaging Market
Flexible Packaging
Brazil Flexible Plastic Packaging Market
Flexible Packaging
Italy Flexible Plastic Packaging Market
Flexible Packaging
France Flexible Plastic Packaging Market
Flexible Packaging
GCC Shrink Sleeves Market
Flexible Packaging
Saudi Arabia Flexible Packaging Market
Flexible Packaging
Global Flexible Packaging Market
Flexible Packaging
Mexico Flexible Packaging Market